
 Global Biodegradable Films Market | 2026-2036
Global Biodegradable Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biodegradable Films Market Foresight
The capital-intensity divergence between integrated resin producers and downstream converters is unwinding competitive stability across the biodegradable films sector. BASF SE leverages its backward integration into polylactic acid feedstocks to sustain margin control across European supply chains. Novamont S.p.A. anchors its position through proprietary Mater-Bi starch blend technology that dominates Italian agricultural applications. Futamura Chemical Co., Ltd. competes primarily in cellulose film segments where its manufacturing scale in Japan creates defensible cost positions.
Biodegradable films are polymeric sheet materials engineered to decompose through microbial action into carbon dioxide, water, and biomass under composting conditions, typically achieving complete breakdown within 180 days in industrial aerobic facilities. These films function as protective barriers with controlled oxygen and moisture permeability, replacing conventional petroleum-derived plastics in applications requiring end-of-life environmental compatibility. Polylactic acid films lead value generation due to their optical clarity and heat-seal performance in food packaging, while starch blends capture fastest volume expansion driven by cost competitiveness in agricultural mulch. Cellulose films retain niche premium positioning in medical packaging where sterilization compatibility and breathability command higher unit economics.
The EU Packaging and Packaging Waste Regulation, FDA food contact substance notifications, and India's BIS compostability standards collectively reshape product certification requirements and market access conditions across major demand centers. REACH compliance in Europe and emerging state-level extended producer responsibility laws in the United States are forcing reformulation investments and supply chain documentation upgrades. Stakeholders must monitor regulatory divergence between industrial composting certification pathways and home-compostable label claims to avoid stranded inventory in markets with incompatible waste infrastructure standards.
Market Dynamics
The EU Packaging and Packaging Waste Regulation's extended producer responsibility mandates are forcing packaging converters across Germany, France, and Italy to abandon conventional polyethylene inventories and rebuild supply chains around certified compostable alternatives.
Growth Catalysts
- REACH compliance deadlines:European chemical safety requirements are accelerating reformulation investments by film converters seeking to retain market access across German and French retail channels.
- Starch blend cost competitiveness:Agricultural mulch buyers in India are switching from conventional plastic under BIS compostability standards and Plastic Waste Management Amendment enforcement.
- Cellulose film sterilization compatibility:Medical packaging manufacturers in Japan favor cellulose substrates for breathability and autoclave performance in surgical kit applications.
Market Restraints
- Polylactic acid feedstock volatility:Corn and sugarcane price swings in Brazilian and Thai agricultural markets transmit directly to PLA resin costs, compressing converter margins.
- Industrial composting infrastructure gaps:Home-compostable label claims face rejection in markets lacking aerobic digestion facilities, stranding inventory in US states without municipal composting programs.
- Polyethylene price anchoring:Conventional plastic remains the reference price floor in food wrap segments, limiting biodegradable premium capture in cost-sensitive retail chains.
Strategic Opportunities
- Indian agricultural mulch penetration:State-level plastic bans in Maharashtra and Karnataka are creating first-mover advantages for starch-based film suppliers with BIS certification.
- Home-compostable certification divergence:Early alignment with emerging home-compostable standards in France and Italy opens premium positioning ahead of harmonized EU definitions.
- Cellulose-barrier hybrid films:Convergence of regenerated cellulose with bio-based barrier coatings targets modified-atmosphere meat packaging in Japanese and South Korean retail.
Industry Challenges
- Compostability certification timelines:Industrial facility testing under EN 13432 and ASTM D6400 protocols extends product launch cycles by 8-14 months for new formulations.
- Legacy extrusion equipment retrofitting:Conventional blown-film lines require screw and die modifications to process hygroscopic PLA and starch blends without thermal degradation.
- Cross-border documentation complexity:Divergent waste infrastructure standards between German industrial composting and Italian home-composting claims force SKU fragmentation and inventory risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biodegradable Films Market |
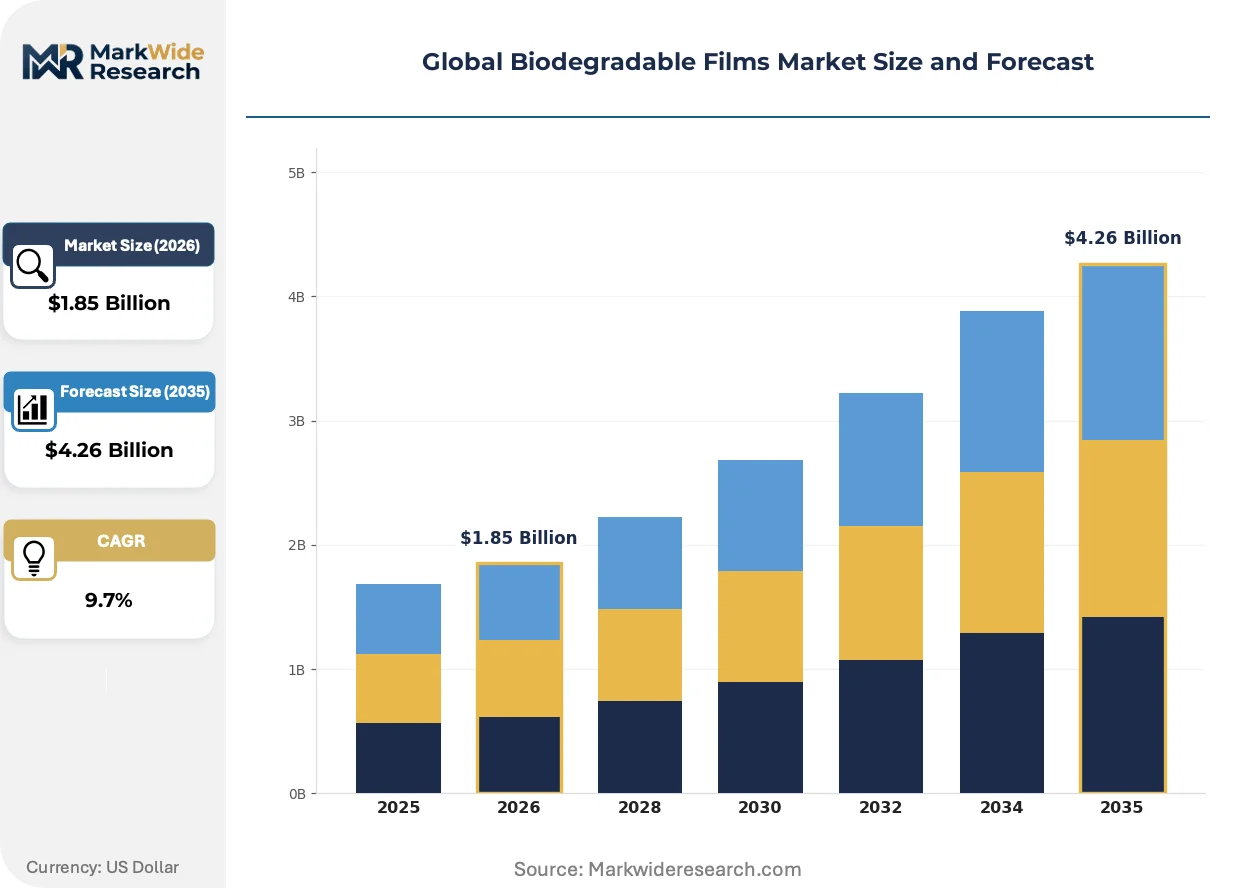
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.26 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polylactic Acid, Polyhydroxyalkanoates, Starch Blends, Cellulose Films, Biopolyester Application: Food Packaging, Agriculture Mulch, Medical Packaging, Textile Covers, Electronic Protection End User: Packaging Manufacturers, Agricultural Enterprises, Medical Device Producers, Textile Fabricators, Electronics Suppliers Form: Flat Films, Cast Films, Blown Films, Co-extruded Films, Laminated Films |
| Companies Covered | BASF SE, Futamura Chemical Co., Ltd., Novamont S.p.A., NatureWorks LLC, Taghleef Industries, BioBag International AS, Cortec Corporation, Kingfa Sci & Tech Co., Ltd., Walki Group Oy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biodegradable Films Market Shifts & Advancements
Active reformulation across barrier chemistry and certification pathways is splitting the market between industrial-compostable and home-compostable performance tiers, with diverging technical specifications reshaping R&D allocation.
Multilayer coextrusion technology is bifurcating the high-performance segment. PLA-PBAT blends with bio-based tie layers now deliver oxygen transmission rates below 1 cc/m²/day for cheese and fresh pasta packaging. German retail chains are specifying these constructions for private-label lines. The technology is bifurcating converter capabilities between commodity starch processors and precision barrier specialists.
REACH substance restrictions on persistent organic pollutants are forcing elimination of certain conventional additives in European film production. ECHA's candidate list updates are triggering supply chain audits for plasticizers and slip agents. Agricultural mulch segments in Italy face the tightest substitution timelines as Mater-Bi formulations already exclude restricted chemistries.
Retail procurement specifications now mandate third-party compostability certification ahead of price negotiation in German and French supermarket chains. Volume tenders from Carrefour and REWE Group require EN 13432 or OK Compost INDUSTRIAL labels as table stakes. This certification-driven gatekeeping is most visible in fresh produce packaging, where uncertified films face automatic disqualification regardless of unit cost.
Global Biodegradable Films Market Segmentation
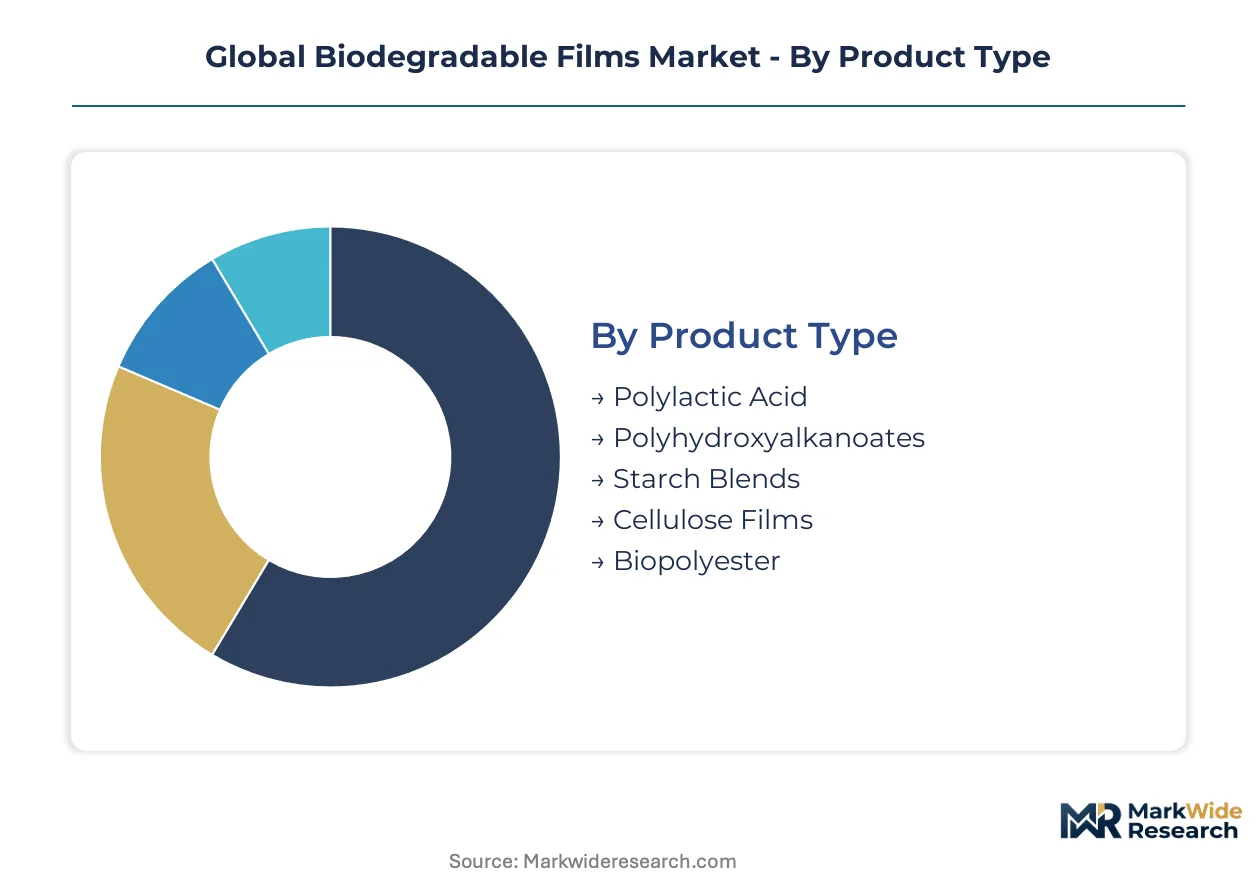
Segmentation in biodegradable films reveals how regulatory certification requirements, processing technologies, and end-use performance specifications create distinct competitive arenas with divergent margin structures and capital requirements.
Product Type:
REACH substance restrictions and divergent compostability certification pathways are fragmenting competitive positioning across resin chemistries, with industrial-compostable and home-compostable tiers commanding different technical specifications and pricing power.
- Polylactic Acid:Derived from fermented corn or sugarcane starch, PLA delivers optical clarity and heat-seal performance comparable to conventional plastics. Demand concentrates in German and French retail food packaging where Carrefour and REWE Group mandate EN 13432 certification as procurement table stakes.
- Starch Blends:Mater-Bi and similar formulations combine thermoplastic starch with biodegradable polyesters to reduce material costs versus pure PLA. Agricultural mulch buyers in Maharashtra and Karnataka under India's BIS compostability standards are switching from conventional plastic as state-level bans take effect.
- Cellulose Films:Regenerated cellulose from wood pulp offers breathability and autoclave sterilization compatibility. Japanese medical packaging manufacturers specify these substrates for surgical kit applications where moisture vapor transmission rates are critical.
- Polyhydroxyalkanoates:Bacterial fermentation polymers with marine biodegradability credentials. Niche adoption in coastal aquaculture packaging where industrial composting infrastructure is absent.
- Biopolyester:Includes PBAT and PBS variants engineered for flexibility and toughness. Blended with PLA in multilayer constructions to balance barrier performance with processability.
Starch blends handle the majority of throughput; cellulose films are gaining share fastest in premium medical applications.
Application:
Cost tier differentiation separates commodity volume plays from precision barrier segments, with food packaging commanding scale economies and medical packaging extracting premium unit economics through sterilization compatibility requirements.
- Food Packaging:Modified-atmosphere applications for cheese, fresh pasta, and produce require oxygen transmission rates below 1 cc/m²/day. German private-label retail chains specify multilayer PLA-PBAT constructions with bio-based tie layers.
- Agriculture Mulch:Soil-biodegradable films eliminate retrieval labor costs while suppressing weeds and regulating soil temperature. Indian enforcement of Plastic Waste Management Amendment rules is accelerating displacement of conventional polyethylene in Maharashtra and Karnataka.
- Medical Packaging:Sterilization-grade breathability and autoclave resistance command premium positioning. Japanese surgical kit manufacturers favor cellulose substrates for compliance with METI guidance on single-use plastic reduction.
- Textile Covers:Breathable protective films for garment shipping and retail display. Limited penetration due to cost sensitivity in fast fashion supply chains.
- Electronic Protection:Anti-static biodegradable films for component shipping. Emerging segment constrained by ESD performance requirements and limited composting infrastructure near electronics manufacturing clusters.
Food packaging dominates current volume; agriculture mulch is expanding most quickly on policy-driven replacement cycles.
End User:
Customer type determines procurement sophistication, with retail-facing packaging manufacturers facing mandatory third-party certification requirements that agricultural enterprises have only begun to encounter under emerging state-level enforcement.
- Packaging Manufacturers:Film converters supplying German and French supermarket chains must maintain EN 13432 or OK Compost INDUSTRIAL labels to qualify for volume tenders. Certification documentation now precedes price negotiation in Carrefour and REWE Group procurement.
- Agricultural Enterprises:Farm operators and agricultural cooperatives in India select starch-based mulch based on BIS compostability certification and state-level plastic ban compliance. First-mover suppliers with established certification capture switching demand in Maharashtra and Karnataka.
- Medical Device Producers:Japanese surgical kit assemblers specify cellulose films for autoclave compatibility and moisture vapor transmission control. Regulatory alignment with METI sustainability guidelines shapes material selection.
- Textile Fabricators:Apparel brands with public sustainability commitments pilot biodegradable garment bags. Procurement volumes remain constrained by cost premiums versus conventional polypropylene.
- Electronics Suppliers:Component manufacturers evaluate biodegradable alternatives for shipping protection. Adoption limited by anti-static performance gaps and absence of composting infrastructure near manufacturing clusters.
Packaging manufacturers represent the most demanding certification environment; agricultural enterprises are the fastest-growing customer category on policy enforcement timelines.
Form:
Processing technology maturity separates established blown-film converters from precision coextrusion specialists, with legacy equipment retrofitting requirements creating capability gaps that reshape competitive entry barriers.
- Blown Films:Conventional extrusion process for commodity packaging films. German and Italian converters retrofit hygroscopic PLA and starch blend processing capability through screw and die modifications.
- Co-extruded Films:Multilayer constructions combining PLA, PBAT, and bio-based tie layers deliver sub-1 cc/m²/day oxygen barriers. Precision barrier specialists in Germany supply private-label cheese and fresh pasta packaging for retail chains.
- Cast Films:Chill-roll casting produces optical-grade clarity for high-visibility retail packaging. Limited adoption due to PLA's thermal sensitivity and brittleness challenges.
- Flat Films:Calendar or extrusion-processed sheets for laminating and bag-making applications. Commodity positioning with limited differentiation.
- Laminated Films:Adhesive or thermal lamination of biodegradable substrates with barrier coatings. Targets modified-atmosphere meat packaging in Japanese and South Korean retail where cellulose-barrier hybrids command premium positioning.
Blown films handle the majority of current throughput; co-extruded films are climbing the fastest on barrier performance requirements in premium food packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters command premium pricing for EN 13432-certified films while Indian suppliers compete on volume under BIS standards, creating a transcontinental pricing-power asymmetry that shapes procurement patterns across both regions.
Germany
REWE Group and Carrefour volume tenders mandate third-party compostability certification as procurement table stakes. The national packaging ordinance enforces extended producer responsibility for single-use plastics. Film converters in the Rhine-Ruhr industrial cluster retrofit legacy extrusion lines to process hygroscopic PLA formulations.
France
Retail chains specify multilayer PLA-PBAT constructions for private-label cheese and fresh pasta packaging. ECHA substance restrictions under REACH trigger supply chain audits for plasticizers and slip agents. Precision barrier specialists around Lyon supply modified-atmosphere packaging to supermarket distribution networks.
India
Maharashtra and Karnataka state-level plastic bans accelerate displacement of conventional polyethylene mulch. The Plastic Waste Management Amendment rules enforce BIS compostability standards for agricultural films. Starch blend suppliers capture first-mover advantages among farm operators switching from conventional plastic.
Japan
Surgical kit manufacturers specify cellulose substrates for autoclave sterilization compatibility. METI guidance on single-use plastic reduction shapes material selection in medical packaging. Manufacturing scale in the Nagoya industrial corridor creates defensible cost positions in regenerated cellulose segments.
Italy
Agricultural mulch segments face tightest substitution timelines as Mater-Bi formulations exclude restricted chemistries. The EU Packaging and Packaging Waste Regulation forces converters to abandon conventional polyethylene inventories. Processing capabilities concentrate in the Po Valley among commodity starch processors and precision barrier specialists.
Global Biodegradable Films Market Competitive Landscape
Concentration sits with integrated resin producers and proprietary technology holders who control margin structures across European supply chains. The vendor base splits between backward-integrated chemical conglomerates, starch blend specialists, and cellulose film manufacturers. Strategic moves center on certification pre-positioning ahead of regulatory enforcement and equipment retrofitting to process hygroscopic biopolymer formulations.
Among European chemical conglomerates, BASF SE anchors positions through captive polylactic acid feedstock production. Novamont S.p.A. occupies a distinctive tier through proprietary starch blend technology. Futamura Chemical Co., Ltd. exemplifies scale-driven specialization in cellulose film segments where manufacturing concentration in Japan supports premium positioning.
| Leading Market Players |
|---|
| BASF SE |
| Futamura Chemical Co., Ltd. |
| Novamont S.p.A. |
| NatureWorks LLC |
| Taghleef Industries |
| BioBag International AS |
| Cortec Corporation |
| Kingfa Sci & Tech Co., Ltd. |
| Walki Group Oy |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for polylactic acid feedstocks concentrate pricing power with backward-integrated resin producers in Germany and Thailand, while converters without captive corn or sugarcane sourcing absorb margin volatility from agricultural commodity swings. This lead-time asymmetry splits the market between price-makers with upstream control and price-takers facing reformulation cost spikes under REACH compliance deadlines.
Pricing Analysis
Customization-premium spreads of 15-25% separate standard starch blend mulch films from multilayer PLA-PBAT barrier constructions engineered for modified-atmosphere cheese packaging. Pricing stratifies across premium, standard, and economy tiers where EN 13432 certification grade and volume scale drive differentiation. Cost compression in commodity starch segments intensifies as Indian state-level plastic bans accelerate supplier entry, while medical-grade cellulose films command pricing resilience through sterilization compatibility requirements that limit buyer price sensitivity.
Supply Chain Analysis
Inventory concentration in German and Italian extrusion hubs creates 8-14 month certification bottlenecks as EN 13432 testing protocols delay new formulation launches. Supply draws from corn and sugarcane agricultural markets in Brazil and Thailand, PLA resin production in Germany and the United States, and cellulose pulp processing in Japan. Single-source vulnerability sits with lactic acid fermentation capacity concentrated among three integrated producers. Distribution runs through converter-direct relationships with REWE Group and Carrefour procurement teams, bypassing traditional chemical distribution channels for certified film volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as conventional polyethylene price floors and home-compostable certification divergence threaten to strand industrial-compostable inventory in markets with incompatible waste infrastructure.
For Market Incumbents: Fortify backward integration into polylactic acid feedstocks or secure long-term offtake agreements with Brazilian and Thai agricultural suppliers to buffer margin compression from corn price volatility. Deepen certification pre-positioning under emerging French and Italian home-compostable standards ahead of harmonized EU definitions, locking in premium positioning before regulatory convergence erodes differentiation. For New Entrants and Emerging Players: Differentiate on BIS-certified starch blend formulations targeting Maharashtra and Karnataka agricultural mulch buyers as state-level plastic bans displace conventional polyethylene. Capture first-mover advantages through direct farm cooperative relationships bypassing established distributor networks, with technical service bundled to address soil-biodegradability performance concerns in tropical conditions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multilayer coextrusion capability as precision barrier specifications demand equipment investments beyond commodity blown-film retrofitting. Target acquisition candidates with installed coextrusion capacity and established EN 13432 certification documentation serving German retail private-label accounts. Watch for inflection when home-compostable standard harmonization triggers inventory write-downs among industrial-compostable specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstocks | BASF SE's captive lactic acid production insulates margin control from Brazilian corn price swings. |
| Certification Pre-Positioning | Early EN 13432 and OK Compost INDUSTRIAL alignment secures REWE Group and Carrefour procurement qualification. |
| Equipment Retrofitting for Hygroscopic Polymers | Rhine-Ruhr converters modify screw and die configurations to process PLA without thermal degradation. |
| Regional Capacity Expansion | Nagoya industrial corridor cellulose scale supports Futamura's defensible cost positions in medical packaging. |
| Long-Term Agricultural Supply Agreements | NatureWorks LLC's Thai sugarcane sourcing anchors resin cost stability for downstream converter contracts. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with film converter plant managers, Carrefour and REWE Group procurement leads, and Novamont R&D directors; and secondary validation through BIS compostability standard filings, ECHA REACH substance restriction updates, and SEC 10-K disclosures from integrated resin producers. Bottom-up volume modeling across resin chemistry, application, and form segments triangulated against top-down spending estimates from packaging manufacturer procurement surveys.
Across the projection horizon, analytical frameworks modeled demand segmentation by product type, application, end user, and form with regional regulatory cluster overlays. CAGRs derived from polynomial trend fitting to historical volume data, adjusted for policy enforcement timelines in Maharashtra, Karnataka, and EU member states. Industry-specific forecast inputs incorporated corn and sugarcane futures curves, industrial composting facility buildout pipelines, and retail chain sustainability procurement mandate announcements.
Material uncertainties — regulatory divergence between industrial and home-compostable certification pathways, feedstock price volatility in Brazilian agricultural markets, and legacy extrusion equipment retrofitting delays — sit outside the modeled envelope. Forecasts reflect assumptions regarding BIS enforcement consistency and EU Packaging and Packaging Waste Regulation implementation timelines. Revision becomes warranted when home-compostable standard harmonization crosses thresholds triggering inventory reclassification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Biodegradable Packing Peanuts Market
Biodegradable Packaging
Asia-Pacific Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Biodegradable Packaging Materials Market
Biodegradable Packaging
Biofoam Packaging Market
Biodegradable Packaging
Biodegradable Water Bottles Market
Biodegradable Packaging
Europe Biodegradable Plastic Packaging Market
Biodegradable Packaging
Biodegradable Plastic Packaging Market
Biodegradable Packaging
Biodegradable Food Packaging Market
Biodegradable Packaging
North America Biodegradable Film Market
Biodegradable Packaging
Bioplastic Packaging Bag Market
Biodegradable Packaging
Biopolymer Packaging Market
Biodegradable Packaging
Europe Biodegradable Film Market
Biodegradable Packaging
Biodegradable Packaging Market
Biodegradable Packaging
Starch-Based Bioplastics Packaging Market
Biodegradable Packaging
North America Biodegradable Paper and Plastic Packaging Market