
 India Biodegradable Tableware & Packaging Products Market | 2026-2036
India Biodegradable Tableware & Packaging Products Market Size, Share, and Industry Trends Forecast 2026-2036
India Biodegradable Tableware & Packaging Products Market Insights
Single-source reliance on imported PLA resin is decoupling as domestic bagasse and starch-based supply chains mature. Pakka Limited leverages captive sugarcane fiber processing to anchor its position in South India. Thooshan competes through artisanal areca-leaf plate networks in Kerala and Tamil Nadu. Pappco Greenware specializes in molded fiber technology for temperature-resistant containers.
India biodegradable tableware and packaging products encompass compostable serveware manufactured from plant-derived polymers, agricultural residues, or microbial bioplastics, typically degrading under industrial composting conditions within 90 to 180 days. These products function as direct replacements for conventional petroleum-based disposables in food contact applications where thermal stability and grease resistance are critical. Compostable plates and containers dominate volume due to institutional catering procurement scale, while PLA-based cups command margin premiums in cold-beverage retail channels. Bagasse material feeds occupy the fastest expansion trajectory as sugar mill byproduct utilization aligns with circular economy mandates. Starch-based formulations sustain relevance in price-sensitive segments where moisture barriers remain secondary to cost.
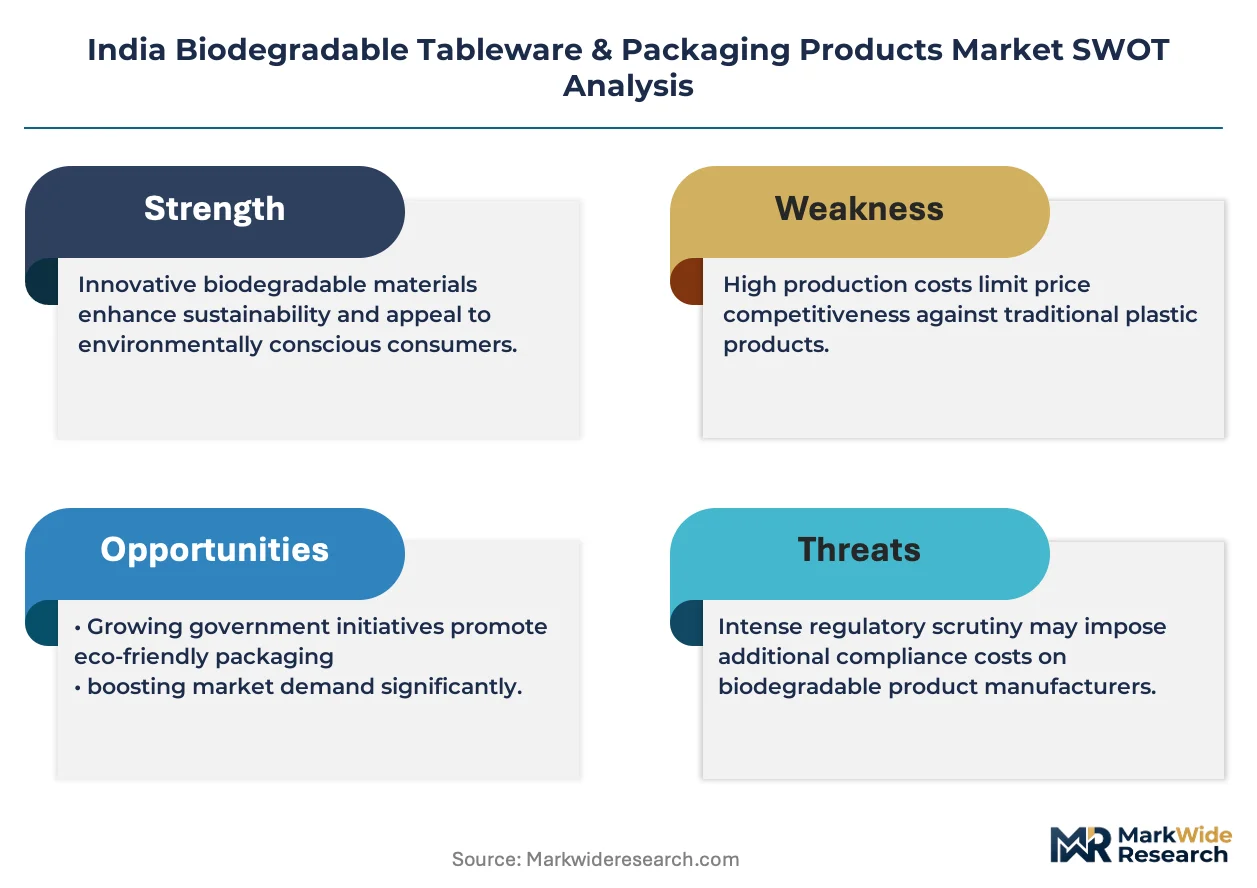
BIS compostability certification under IS/ISO 17088, FSSAI food-contact safety clearances, and state-level plastic ban enforcement under PWM Rules collectively determine market access and procurement eligibility. The CEA's renewable energy credits for biomass processing units indirectly lower feedstock conversion costs for domestic manufacturers. Stakeholders must monitor evolving EPR liability frameworks and state-level ban granularity to anticipate demand inflection points.
Market Dynamics
Bagasse feedstock localization is compressing import dependency for PLA resin while Maharashtra and Karnataka foodservice chains accelerate compliance-driven procurement timelines under state-level plastic bans.
Growth Catalysts
- Plastic Waste Management Rules enforcement:State-level bans on single-use plastics in Maharashtra, Karnataka, and Delhi NCR mandate biodegradable alternatives for institutional catering and quick-service restaurants.
- Bagasse supply chain maturation:Sugar mill byproduct utilization creates captive fiber streams for molded fiber tableware, reducing raw material cost volatility for domestic manufacturers.
- FSSAI food-contact safety clearances:Standardized approval pathways enable faster product launches for compostable serveware targeting temperature-resistant container applications.
Market Restraints
- Industrial composting infrastructure gaps:Limited municipal composting facility coverage in Tier-2 and Tier-3 cities restricts end-of-life disposal pathways for certified biodegradable products.
- Imported PLA resin price volatility:Single-source reliance on international polylactic acid suppliers exposes converters to currency fluctuation and shipping cost shocks.
- Conventional plastic price undercutting:Virgin polypropylene and polystyrene disposables maintain cost advantages in price-sensitive street food and informal catering segments.
Strategic Opportunities
- CEA renewable energy credits:Biomass processing units qualify for tariff incentives that lower bagasse conversion energy costs for South India manufacturers.
- Areca-leaf artisanal networks:Kerala and Tamil Nadu cottage industries offer decommoditized plate production for premium hospitality and wedding catering segments.
- EPR liability framework expansion:Extended producer responsibility mandates for plastic packaging create substitution pull for compostable alternatives in e-commerce and retail channels.
Industry Challenges
- BIS IS/ISO 17088 certification timelines:Testing backlog at accredited laboratories delays product launches by four to six months for new market entrants.
- Moisture barrier formulation expertise:Limited domestic technical talent for starch-based grease-resistant coatings constrains product performance in hot-oil food applications.
- Supply chain reconfiguration friction:Legacy petroleum-based disposable distributors resist margin compression from lower-volume biodegradable product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Biodegradable Tableware & Packaging Products Market |
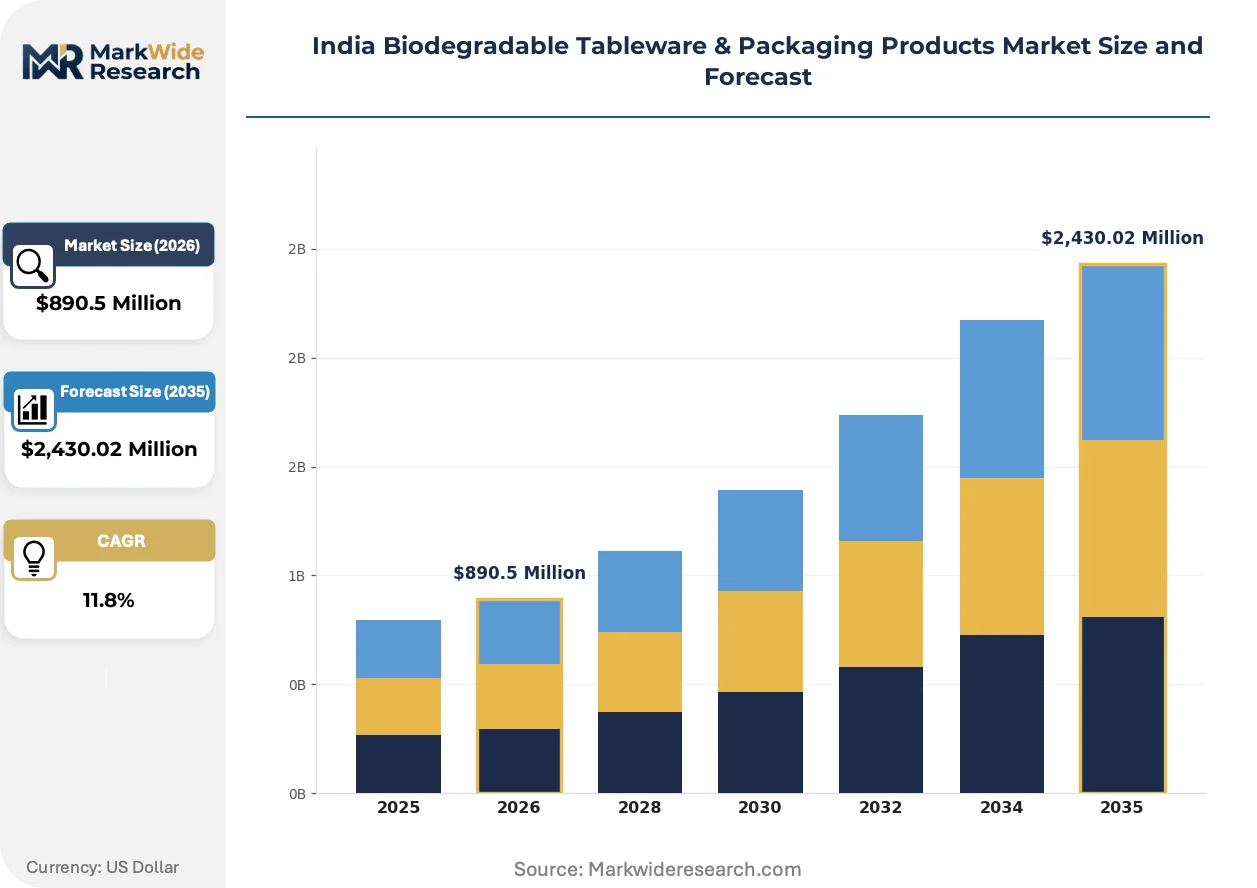
| Market Size in 2026 | $890.5 Million |
| Market Size in 2035 | $2,430.02 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compostable Plates, Compostable Cups, Cutlery, Containers Material: PLA, Starch-based Material, Bagasse, Palm Leaf End User: Restaurants, Catering Services, Retail Outlets, Event Organizers Distribution Channel: Online Retail, Wholesale Distributors, Supermarkets, Specialty Stores |
| Companies Covered | Pakka Limited, Thooshan, Pappco Greenware, Tamul Plates Marketing Private Limited, Earthsoul Bio Products LLP, Ecoware, Varsya Eco, Qudrat, Thricore, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Biodegradable Tableware & Packaging Products Market Trends and Innovations
Material science convergence with agricultural residue processing is rewriting cost-performance tradeoffs for heat-resistant serveware. Three developments merit attention.
Molded fiber technology is absorbing thermal stability requirements previously served by foam and plastic containers. Quick-service chains in Mumbai and Bangalore are piloting bagasse-based clamshells for hot-oil fried foods at scale. The shift is compressing price premiums for temperature-resistant biodegradable alternatives.
FSSAI has tightened food-contact migration limits for biodegradable polymers, accelerating reformulation investments among domestic converters. Manufacturers must now demonstrate heavy metal and additive compliance beyond base compostability certification. Cold-beverage retail channels face the steepest retesting burden.
Institutional procurement contracts are consolidating vendor bases around certified suppliers with verified composting partnerships. Large catering operators in Delhi NCR now mandate BIS certification plus end-of-life collection proof as table stakes. This behavior is fragmenting the long-tail of uncertified regional producers.
India Biodegradable Tableware & Packaging Products Market Segmentation
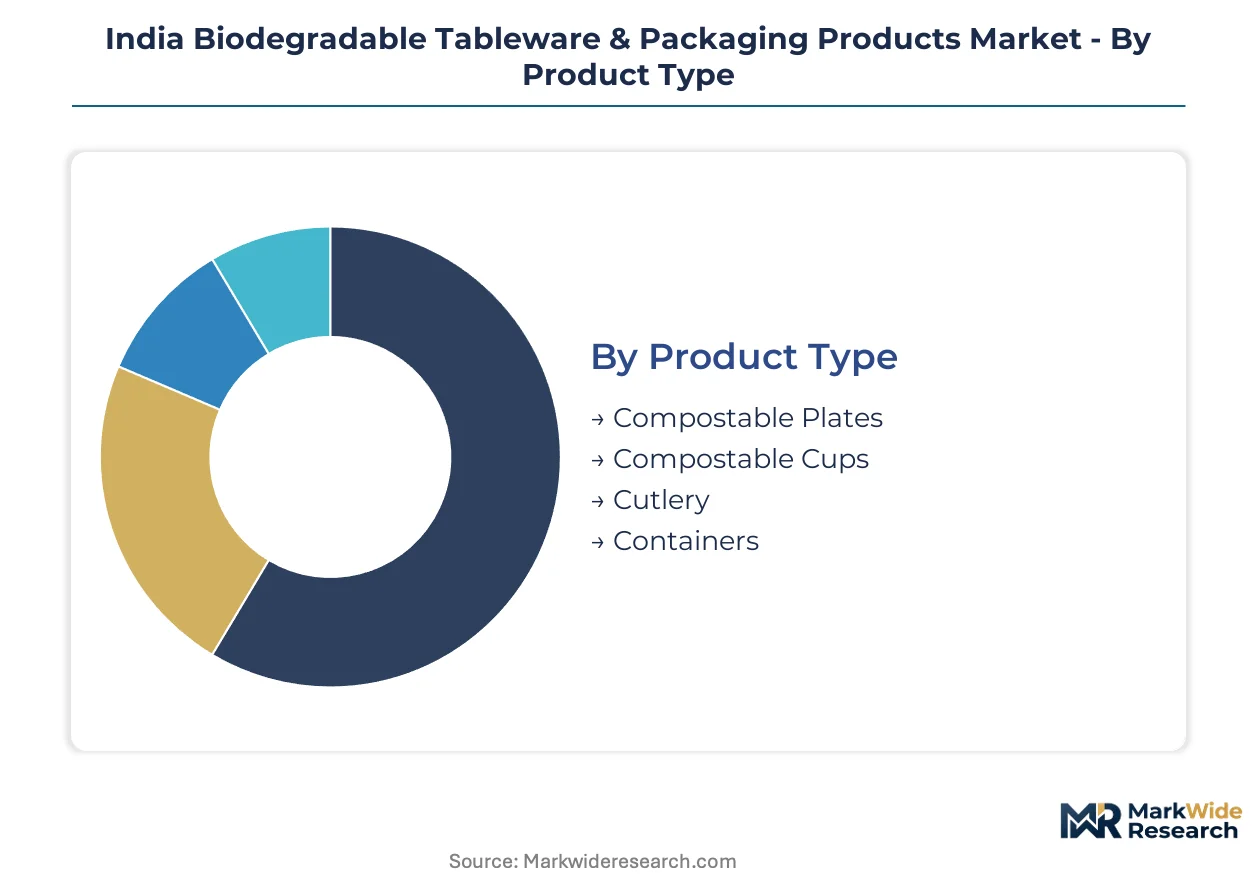
Segmentation in the India biodegradable tableware market reveals distinct procurement patterns across institutional buyers and price-sensitive street vendors. Material composition and certification status drive vendor selection more than brand recognition in this compliance-driven environment.
Product Type:
Restaurants prioritize thermal performance and grease resistance when selecting compostable serveware for their specific menu applications.
- Compostable Plates:Molded fiber and bagasse-based flatware dominate institutional catering contracts across Maharashtra and Karnataka. Quick-service chains in Mumbai mandate BIS-certified plates for compliance with state-level plastic bans.
- Compostable Cups:PLA-lined cold-beverage containers command premium positioning in Bangalore retail channels where FSSAI migration limits have tightened formulation requirements.
- Cutlery:Starch-based spoons and forks serve price-sensitive street food segments in Delhi NCR where cost parity with plastic remains critical.
- Containers:Clamshell and hinged-lid designs target takeaway packaging for cloud kitchens and food delivery aggregators.
Compostable plates lead on scale; compostable cups lead on momentum.
Material:
Feedstock localization determines margin sustainability for converters facing volatile resin import costs.
- Bagasse:Sugarcane fiber processing leverages captive supply from South India sugar mills, creating cost advantages for molded fiber manufacturers. CEA renewable energy credits further reduce conversion energy costs for biomass processing units.
- Starch-based Material:Domestic corn and tapioca feedstocks sustain relevance in moisture-tolerant applications where price sensitivity outweighs performance requirements.
- PLA:Imported polylactic acid resin exposes converters to currency fluctuation and shipping cost volatility despite superior clarity for cold-beverage cups.
- Palm Leaf:Kerala and Tamil Nadu cottage industries harvest areca sheaths for artisanal plate production serving premium wedding catering segments.
Bagasse dominates volume economics; palm leaf commands premium positioning.
End User:
Procurement scale and compliance urgency separate institutional buyers from fragmented informal channels.
- Restaurants:Quick-service chains across Mumbai, Bangalore, and Delhi NCR drive standardized SKU demand with mandated BIS certification requirements.
- Catering Services:Institutional operators consolidate vendor bases around suppliers with verified composting partnerships and end-of-life collection proof.
- Retail Outlets:Cold-beverage kiosks and convenience stores prioritize PLA cups with food-contact safety clearances for grab-and-go consumption.
- Event Organizers:Temporary hospitality procurement favors areca-leaf disposables for premium positioning at weddings and corporate gatherings in South India.
Catering services anchor procurement volume; restaurants drive standardization.
Distribution Channel:
Channel selection reflects buyer scale and certification verification requirements.
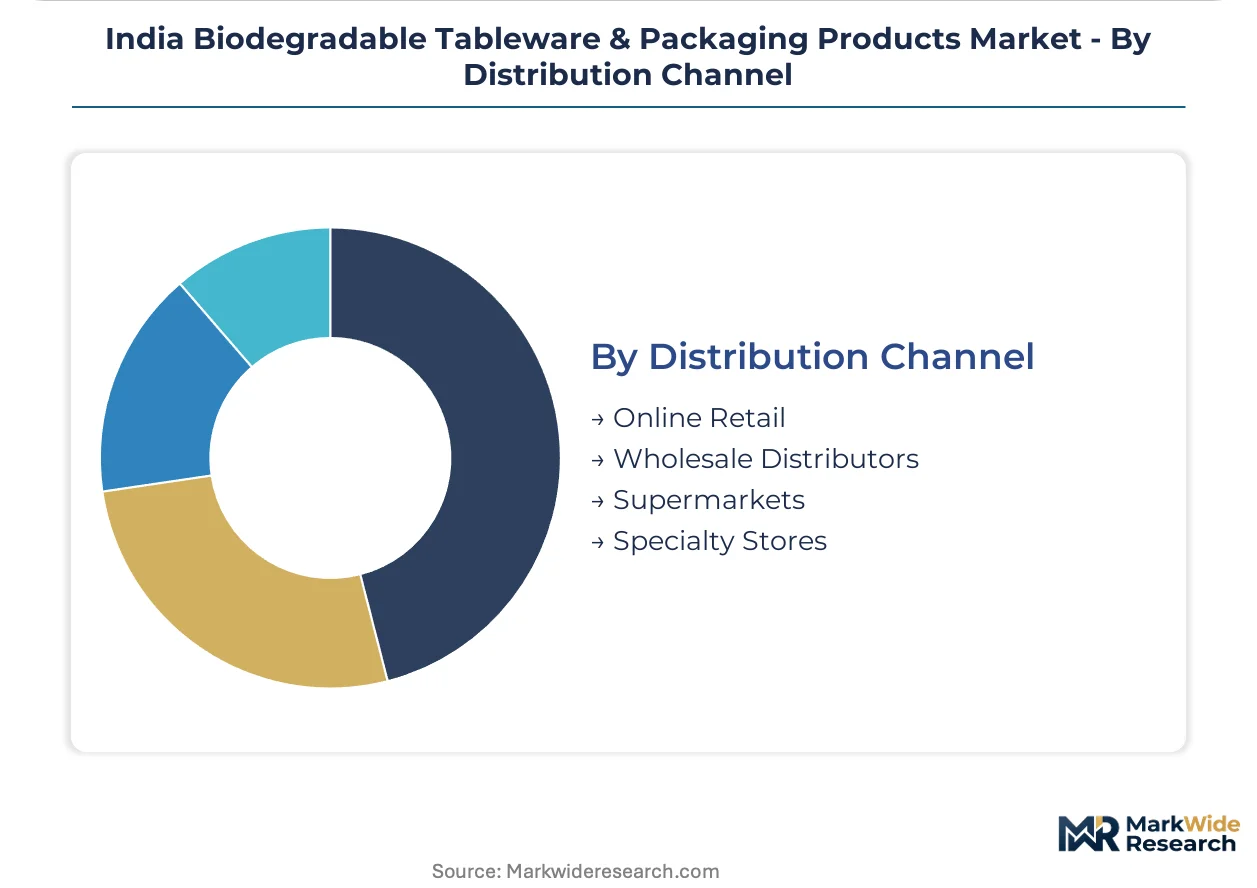
- Wholesale Distributors:Legacy petroleum-based disposable distributors in Tier-2 cities resist margin compression from lower-volume biodegradable lines despite growing compliance pressure.
- Online Retail:E-commerce platforms enable direct procurement for small restaurants and cloud kitchens seeking transparent certification documentation and flexible order quantities.
- Supermarkets:Organized retail chains stock certified consumer packs for household entertaining and small office catering in metropolitan markets.
- Specialty Stores:Eco-focused retailers in Bangalore and Pune curate premium areca-leaf and palm-leaf selections for environmentally conscious consumers.
Wholesale distributors retain volume leadership; online retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's sugar belt anchors India's biodegradable tableware production capacity, with Mumbai's foodservice chains driving compliance-led procurement at scale. State-level plastic bans across western and southern India are redrawing manufacturing footprints toward feedstock-rich hinterlands.
Maharashtra
Quick-service chains in Mumbai and Pune mandate BIS-certified bagasse serveware under the state's comprehensive plastic ban enforcement. The Maharashtra Pollution Control Board coordinates with municipal corporations to inspect foodservice compliance, accelerating vendor consolidation around certified suppliers. Kolhapur and Solapur sugar mills supply captive fiber streams to molded fiber converters operating within 150-kilometer radiuses.
Karnataka
Bangalore's cloud kitchen density generates concentrated demand for clamshell containers and hinged-lid takeaway packaging. The Karnataka State Pollution Control Board mandates biodegradable alternatives for institutional catering contracts exceeding fifty thousand rupees in value. Mandya and Mysuru districts host sugar mill byproduct processing clusters that feed Bangalore's packaging converters.
Tamil Nadu
Chennai's wedding catering industry sustains artisanal areca-leaf plate networks across Tirunelveli and Madurai districts. The Tamil Nadu Plastic Pollution Free Tamil Nadu Mission enforces retailer-level compliance for disposable serveware in coastal tourism zones. Coimbatore's engineering base supports tooling fabrication for molded fiber pressing equipment serving regional converters.
Kerala
Thiruvananthapuram and Kochi hospitality sectors source premium palm-leaf disposables for high-end event catering and resort operations. The Kerala State Pollution Control Board operates India's most stringent single-use plastic prohibition, covering manufacture, stock, and distribution. Kasaragod and Kannur districts harvest areca sheaths through women's self-help group networks supplying export-grade plate specifications.
Delhi NCR
Institutional caterers across Delhi, Gurgaon, and Noida consolidate procurement around suppliers with verified composting partnerships and end-of-life collection infrastructure. The Delhi Pollution Control Committee enforces plastic ban penalties through food safety inspections at quick-service restaurant chains. Ghaziabad and Faridabad host warehousing and distribution hubs serving NCR's fragmented retail channel.
India Biodegradable Tableware & Packaging Products Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue artisanal premium positioning and regional feedstock captive supply. The vendor base stratifies across three maturity levels: integrated sugar mill affiliates with captive fiber access, independent molded fiber specialists with FSSAI clearances, and cottage industry networks serving ceremonial catering segments. Strategic archetypes include feedstock-backward integrators, certification-first standard suppliers, and decommoditized craft producers. Competitive intensity centers on BIS certification speed and municipal composting partnership verification.
Among South India-based integrated producers, Pakka Limited anchors the bagasse processing tier through captive sugarcane fiber operations. Thooshan exemplifies the artisanal network archetype, occupying a position within Kerala and Tamil Nadu cottage industry supply chains. Pappco Greenware sits within the molded fiber technology tier, representing temperature-resistant container specialization for quick-service restaurant procurement. These three entities collectively illustrate the geographic and capability segmentation defining vendor selection criteria across institutional and premium hospitality channels.
| Leading Market Players |
|---|
| Pakka Limited |
| Thooshan |
| Pappco Greenware |
| Tamul Plates Marketing Private Limited |
| Earthsoul Bio Products LLP |
| Ecoware |
| Varsya Eco |
| Qudrat |
| Thricore |
| Others |
Pricing and Supply Chain Analysis
Mumbai quick-service chains mandating BIS-certified bagasse serveware under Maharashtra's plastic ban are compressing procurement timelines and forcing supply-side reconfiguration toward captive fiber sources, which in turn anchors price premiums around certification speed rather than raw material cost alone.
Pricing Analysis
Imported PLA resin cost pass-through volatility exposes converters to margin compression when currency fluctuation strikes, while domestic bagasse feedstock localization creates pricing insulation for South India manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates FSSAI-cleared temperature-resistant containers from uncertified commodity plates. Pricing pressure stems from conventional polypropylene undercutting in street food segments where BIS compliance remains unenforced. Institutional catering services exhibit lowest price sensitivity; Delhi NCR cloud kitchens face highest cost pressure.
Supply Chain Analysis
BIS compostability certification timelines and state-level plastic ban enforcement are reshaping sourcing toward domestic bagasse processing clusters in Maharashtra, Karnataka, and Tamil Nadu. Raw material dependencies center on sugar mill fiber streams, corn and tapioca starch feedstocks, and imported polylactic acid resin. Single-source vulnerability to international PLA suppliers creates exposure when shipping costs spike. Distribution runs through legacy wholesale networks in Tier-2 cities and accelerating e-commerce platforms serving cloud kitchens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates around feedstock-backward integrators capturing CEA renewable energy credits and premium-tier areca-leaf positioning where artisanal scarcity commands pricing power.
For Market Incumbents: Extend captive sugarcane fiber processing capacity within 150-kilometer radiuses of Kolhapur and Solapur sugar mills to defend against emerging molded fiber specialists. Accelerate BIS IS/ISO 17088 certification pipeline investments to compress four-to-six month testing delays that cede procurement share to faster rivals. For New Entrants and Emerging Players: Cloud kitchen aggregators in Bangalore represent the most penetrable channel partner type for clamshell container specialists seeking volume scale without legacy distributor margin compression. Target Kerala and Tamil Nadu women's self-help group networks for areca-leaf plate supply partnerships that unlock premium wedding catering positioning. Pursue direct-to-kitchen e-commerce routes with transparent certification documentation to bypass wholesale distributor resistance. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated sugar mill affiliates combining captive fiber access with CEA renewable energy credit monetization. Five-to-ten year viability favors feedstock-backward integrators over PLA-dependent converters exposed to import volatility. Monitor municipal composting facility coverage expansion in Tier-2 cities as inflection signal for end-of-life collection infrastructure maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Fiber Supply | Sugar mill byproduct utilization under CEA credits lowers conversion energy costs for Maharashtra manufacturers. |
| BIS Certification Fast-Track Investment | Compressed testing timelines at accredited laboratories accelerate product launches before state ban enforcement deadlines. |
| Municipal Composting Partnership Verification | Institutional catering contracts in Delhi NCR now mandate end-of-life collection proof as vendor selection criterion. |
| Areca-Leaf Artisanal Network Expansion | Kerala women's self-help groups supply export-grade specifications for premium hospitality and wedding catering segments. |
| E-Commerce Direct Procurement Channel | Online platforms enable small restaurant and cloud kitchen access to transparent certification documentation. |
Research Methodology
Direct dialogue with molded fiber plant managers, sugar mill procurement leads, FSSAI regulatory affairs officers, cloud kitchen operations heads, and institutional catering contract managers combined with secondary validation against BIS certification databases, state pollution control board enforcement records, sugar industry association reports, and customs trade data for PLA resin imports. Bottom-up and top-down triangulation cross-validated regional production capacity estimates against end-user procurement scale.
Bottom-up modeling aggregated segment-level volume and value outputs across product type, material composition, end-user category, and distribution channel dimensions over the projection horizon. Top-down analysis cross-checked aggregate market trajectories against sugar mill byproduct availability and state-level plastic ban implementation timelines. CAGRs were derived from normalized growth rate convergence across the two analytical approaches, with specific inputs including CEA renewable energy credit utilization rates and FSSAI food-contact safety clearance issuance velocity.
Revisions become necessary when municipal composting infrastructure deployment accelerates beyond baseline assumptions, when PLA resin import tariffs or currency fluctuation exceeds modeled bands, or when state-level plastic ban enforcement granularity shifts procurement eligibility criteria. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Oxo-Biodegradable Plastic Packaging Market
Biodegradable Packaging
North America Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Global Bioplastic Multi-Layer Films Market
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Bioplastic Packaging Market
Biodegradable Packaging
Starch-Based Bioplastics Packaging Market
Biodegradable Packaging
Biodegradable Cups Market
Biodegradable Packaging
Bioplastic Packaging Bag Market
Biodegradable Packaging
Bioadhesives for Packaging Market
Biodegradable Packaging
Biodegradable Cutlery Market
Biodegradable Packaging
Europe Biodegradable Film Market
Biodegradable Packaging
Biopolymer Packaging Market
Biodegradable Packaging
Biodegradable Lids Market
Biodegradable Packaging
Global Biodegradable Films Market
Biodegradable Packaging
Global Biodegradable Tableware Market
Biodegradable Packaging
Asia-Pacific Biodegradable Film Market