
 Global Biodegradable Tableware Market | 2026-2036
Global Biodegradable Tableware Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biodegradable Tableware Market Analysis
Catering services and food delivery platforms are redrawing procurement priorities across the biodegradable tableware landscape. Huhtamäki Oyj leverages its European manufacturing footprint to supply bagasse-based products at scale. Vegware Ltd specializes in compostable foodservice packaging with certified closed-loop collection systems. Dart Container Corporation competes through its integrated fiber molding operations across multiple North American facilities.
Biodegradable tableware comprises disposable serving items engineered from plant-derived polymers, agricultural residues, or microbially processed starches, typically designed to decompose under industrial composting conditions within 90 to 180 days. These products serve the foodservice industry's need for hygienic, single-use serviceware that aligns with waste diversion mandates and corporate sustainability commitments. PLA formulations currently occupy the premium tier due to their clarity and heat resistance, while bagasse dominates in cost-sensitive quick-service applications where structural rigidity matters more than transparency. Bamboo-based cutlery extends the fastest among product forms as consumers reject plastic utensils in dine-in and takeaway settings.
The EU Green Deal and F-Gas Regulation indirectly shape material selection by pressuring petrochemical feedstocks, while FDA food-contact substance notifications govern PLA and starch-based formulations in the United States. India's BIS certification requirements for compostable plastics and China's GB standards for biodegradable products create divergent compliance pathways that fragment supplier strategies. Stakeholders must monitor how municipal composting capacity expansions in specific cities determine which material certifications translate into actual end-of-life value rather than greenwashing liability.
Market Dynamics
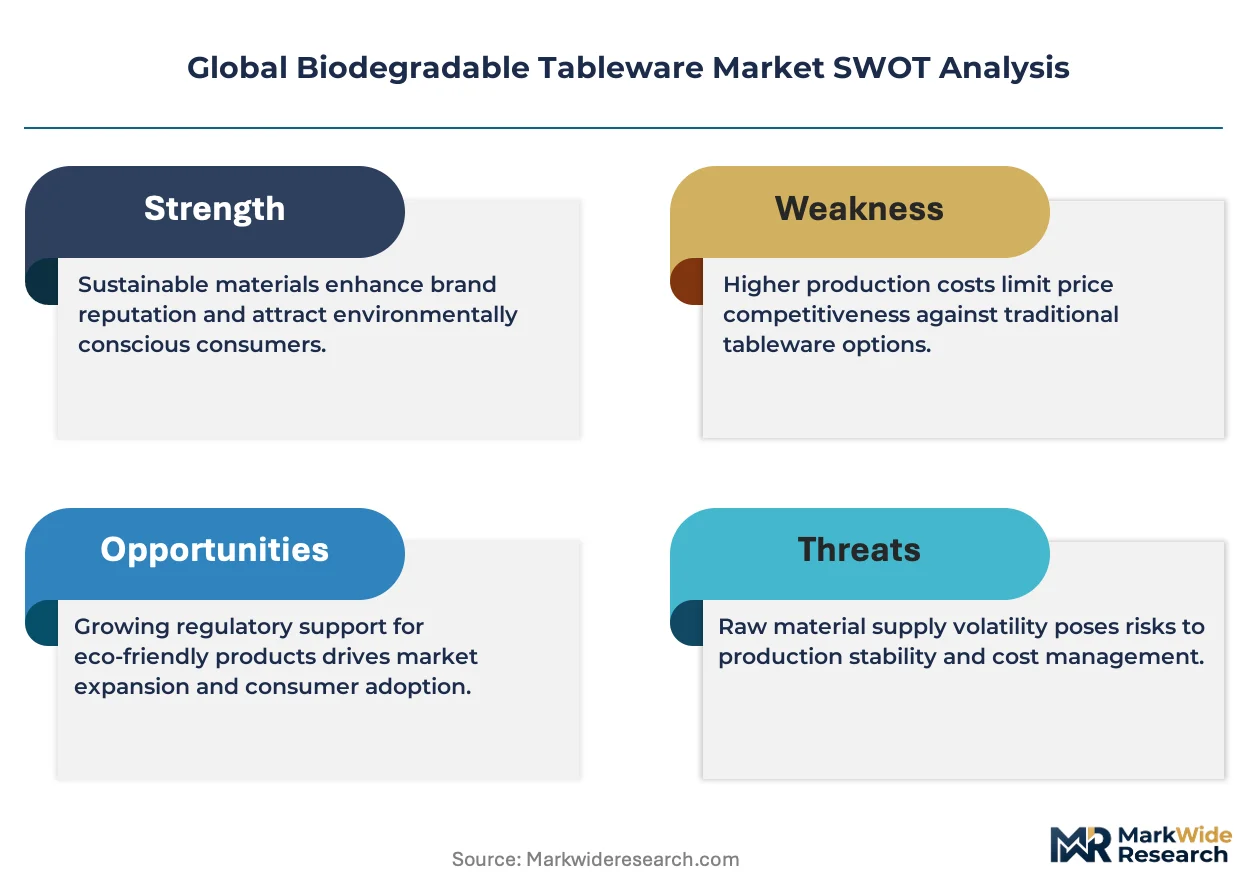
Municipal composting infrastructure gaps force suppliers to certify products for multiple degradation pathways simultaneously, raising compliance costs while fragmenting addressable markets by city-level waste management capabilities.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandates phase-out of conventional plastic serviceware across member states, redirecting institutional procurement budgets toward certified compostable alternatives in foodservice operations.
- Quick-service restaurant chains:Corporate sustainability commitments with public-facing targets are embedding bagasse and PLA specifications into multi-year supply agreements.
- Bagasse fiber molding:Advances in pulp processing technology are lowering unit costs for rigid containers, matching polystyrene price points in high-volume catering applications.
Market Restraints
- Industrial composting access:Only 185 US municipalities operate facilities accepting certified compostable packaging, limiting end-of-life value realization for PLA and bagasse products.
- Feedstock price volatility:Corn starch and sugarcane bagasse costs fluctuate with agricultural commodity cycles, compressing margins for manufacturers lacking long-term supply contracts.
- Home composting incompatibility:Most certified products require industrial conditions above 55°C, creating consumer confusion and contamination in residential organics streams.
Strategic Opportunities
- India's BIS certification pathway:Early compliance with compostable plastics standards positions suppliers for rapid penetration as urban municipal corporations expand waste segregation infrastructure.
- Marine-degradable formulations:Convergence of enzymatic degradation research with anaerobic digestion systems opens coastal tourism and seafood processing segments currently unserved by industrial-compostable-only products.
- Direct-to-foodservice platforms:Digital procurement channels are disintermediating traditional distribution, enabling smaller manufacturers to capture institutional accounts with customized SKU configurations.
Industry Challenges
- Certification timeline compression:Multiple overlapping standards from BPI, TÜV Austria, and DIN CERTCO require 12-18 month validation cycles, delaying product launches and freezing R&D roadmaps.
- Composting facility integration:Suppliers must coordinate with municipal waste operators to establish accepted material lists, creating account-by-account sales complexity without guaranteed volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biodegradable Tableware Market |
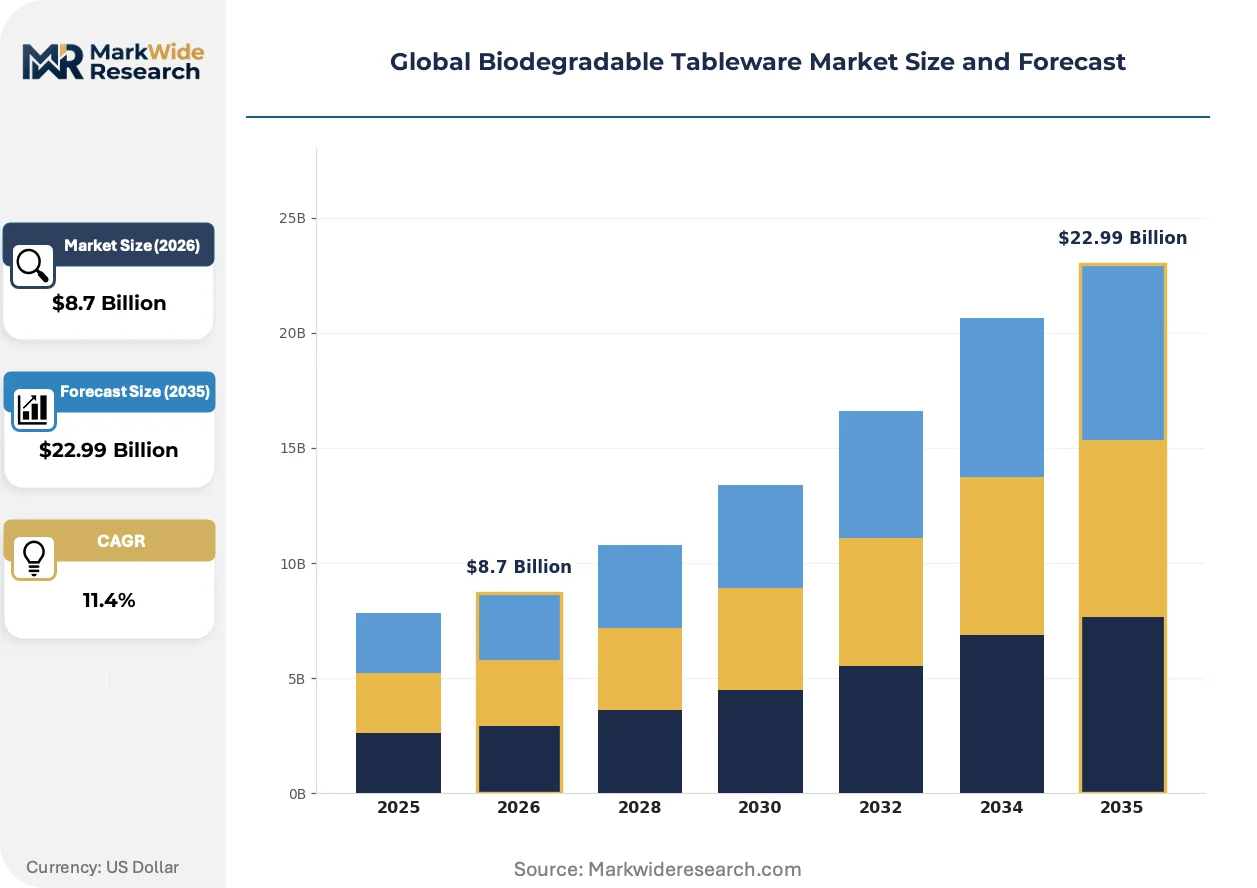
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PLA, Bagasse, Bamboo, Starch Product Form: Plates, Bowls, Cutlery, Cups End User: Restaurants, Catering Services, Food Delivery, Retail Distribution Channel: Online, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Huhtamäki Oyj, Dart Container Corporation, Vegware Ltd, Pactiv Evergreen Inc., BioPak, Novolex, Genpak, LLC, Eco-Products, PacknWood, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biodegradable Tableware Market Emerging Trajectories
Material science advances and waste policy implementation are diverging across geographies, creating parallel innovation tracks for industrial-compostable and home-degradable product lines serving distinct municipal infrastructure environments.
Barrier coating technology is fragmenting as multiple approaches compete for dominance in moisture-resistant paperboard applications. Water-based dispersions, PLA lamination, and bio-wax formulations each claim distinct performance-cost positions. Quick-service chains in Germany and the Netherlands are piloting all three variants simultaneously, forcing suppliers to maintain redundant production lines rather than standardizing on single-technology platforms.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating oil-resistant fluorochemical coatings from food-contact materials. European manufacturers are retrofitting coating lines to handle bio-based alternatives ahead of 2025 enforcement deadlines. PLA-laminated paperboard is capturing premium takeaway container demand in France and Italy as brands preempt regulatory liability.
Corporate buyers are consolidating supplier relationships around vertically integrated manufacturers capable of certifying closed-loop collection systems. Food delivery platforms in California and New York are mandating vendor participation in post-consumer composting programs as contract prerequisites. This behavioral shift favors larger producers with established logistics partnerships over specialty manufacturers lacking collection infrastructure.
Global Biodegradable Tableware Market Segmentation
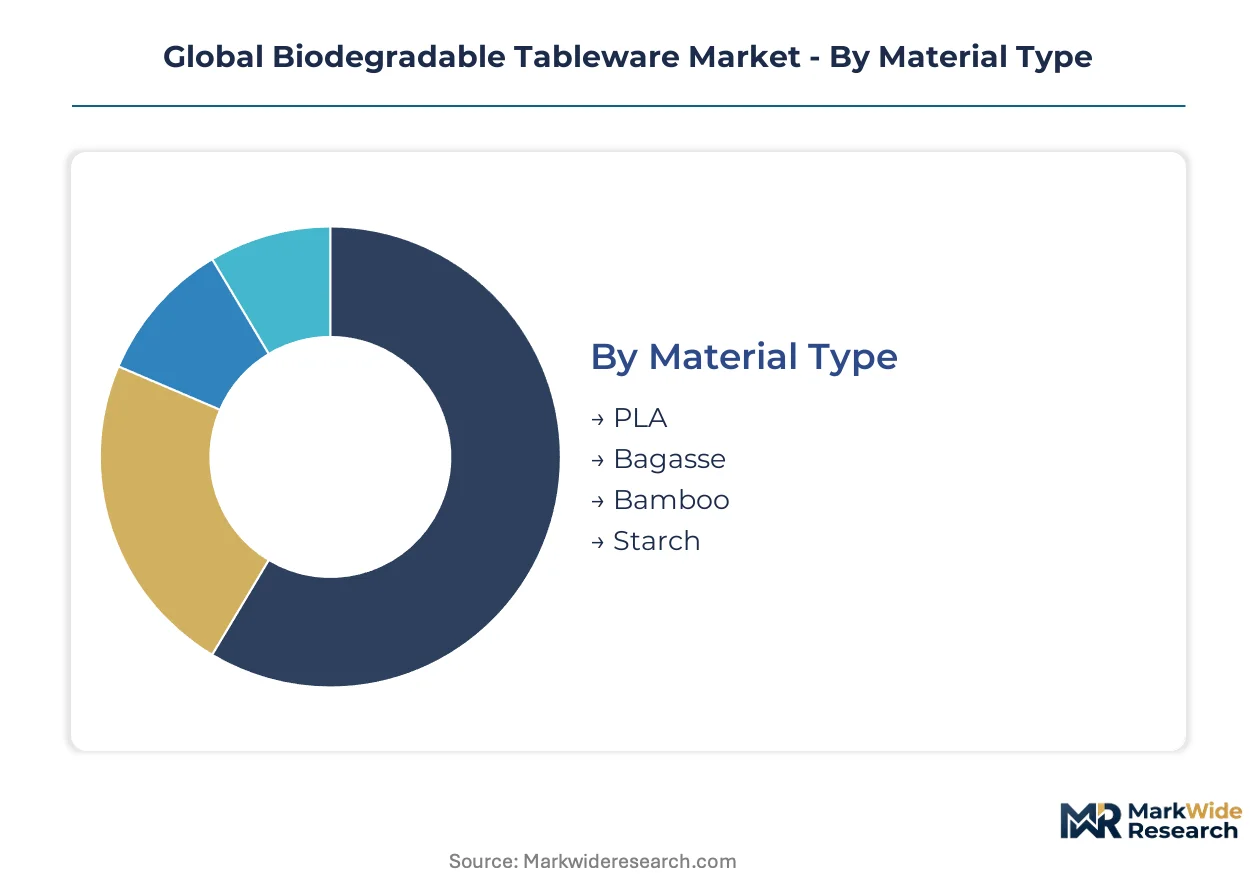
Segmentation in biodegradable tableware reveals how material properties, end-use requirements, and channel economics create distinct competitive arenas. Suppliers must align formulation choices with composting infrastructure availability and procurement specifications across foodservice verticals.
Material Type:
Domestic production of bagasse and starch concentrates in agricultural processing regions with captive fiber supply, while PLA and bamboo derivatives flow through export-oriented manufacturing hubs serving premium markets in Germany, France, and California.
- PLA:Polylactic acid formulations deliver optical clarity and heat resistance up to 110°C through corn starch polymerization. Demand clusters in California and German quick-service chains where municipal composting infrastructure validates premium positioning against conventional plastics.
- Bagasse:Sugarcane fiber pulp molded under high pressure creates rigid containers with natural grease resistance. Volume concentrates in Indian and Brazilian foodservice procurement where cost parity with polystyrene drives institutional adoption.
- Bamboo:Mechanically processed grass fibers yield dense cutlery with superior tensile strength for heavy-duty applications.
- Starch:Thermoplastic formulations from potato and corn sources biodegrade rapidly in industrial conditions but lack structural rigidity for hot-fill applications.
Bagasse holds the largest share; momentum sits with bamboo as dine-in establishments reject plastic utensils.
Product Form:
Form selection tracks heat exposure requirements and liquid containment needs, with hot-food applications commanding stricter material specifications and certification burdens than ambient-service items.
- Plates:Flat-bottomed dishware dominates catering and institutional procurement through standardized sizing and stackability. German municipal composting programs accept bagasse plates at scale, while French regulations mandate PLA lamination for oil-heavy cuisines.
- Cutlery:Fork, knife, and spoon sets face the steepest performance expectations for flexural strength and edge retention. California's statewide plastic utensil restrictions are redirecting quick-service procurement toward bamboo and reinforced starch alternatives.
- Bowls:Deep-drawn containers with rolled rims serve soup and grain-based meals where liquid resistance determines material selection.
- Cups:Tapered vessels for hot and cold beverages require barrier coatings to prevent moisture wicking in paperboard substrates.
Plates command the greatest procurement volume; bowls are climbing fastest as grain-bowl concepts expand across urban foodservice.
End User:
Customer scale and sustainability visibility determine specification stringency, with publicly traded chains facing stricter disclosure requirements than independent operators.
- Restaurants:Dine-in and takeaway establishments balance cost controls with brand-aligned material choices. India's quick-service sector is embedding BIS-certified compostables into supply agreements ahead of municipal waste segregation mandates in Mumbai and Delhi.
- Food Delivery:Platform economics favor lightweight, stackable packaging that minimizes delivery fees and thermal loss. California and New York delivery aggregators are mandating vendor participation in post-consumer composting programs as contract prerequisites.
- Catering Services:Event-based procurement prioritizes disposability and volume pricing for single-use serviceware at scale.
- Retail:Consumer-direct sales through grocery channels emphasize home-composting claims despite industrial certification realities.
Restaurants absorb the greatest material volume; food delivery is gaining share fastest as platform consolidation concentrates procurement power.
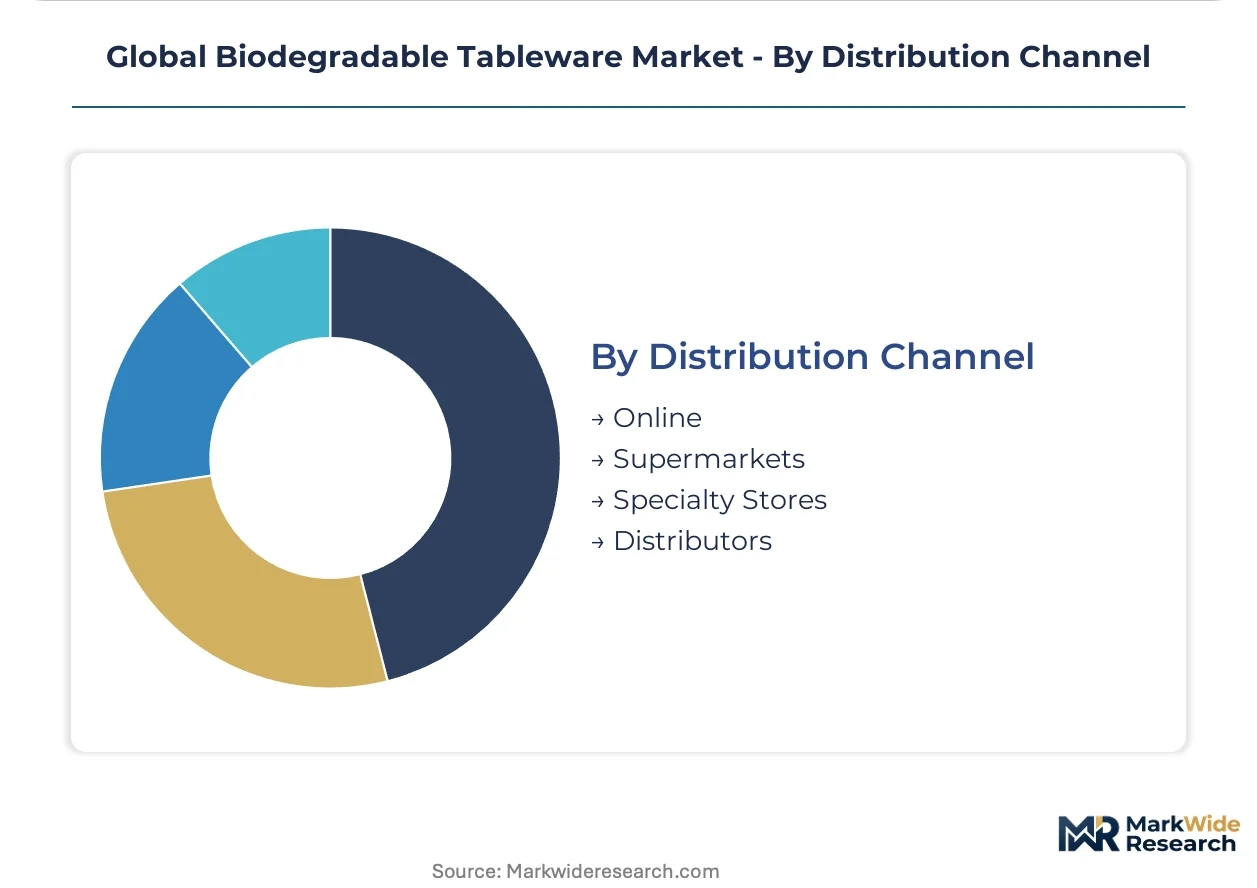
Distribution Channel:
Channel structure determines margin capture and customer relationship depth, with direct digital sales disintermediating traditional wholesale relationships in mid-market accounts.
- Distributors:Broadline foodservice wholesalers maintain SKU breadth and logistics integration for multi-unit chains. German and Dutch distributors are consolidating supplier relationships around vertically integrated manufacturers with closed-loop collection capabilities.
- Online:Digital procurement platforms enable smaller manufacturers to bypass traditional wholesale markups and customize configurations for institutional buyers. California-based foodservice procurement startups are disintermediating legacy distribution for independent restaurants.
- Supermarkets:Mass retail channels serve consumer-direct and small-business procurement with standardized pack sizes.
- Specialty Stores:Eco-focused retailers emphasize certification transparency and premium positioning for environmentally motivated purchasers.
Distributors retain the largest share; online channels are expanding most quickly as procurement digitization accelerates post-pandemic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers dominate export flows into European and North American foodservice procurement channels, while domestic demand clusters in agricultural processing regions with captive bagasse supply.
Germany
Municipal composting infrastructure in Bavaria and North Rhine-Westphalia validates premium PLA positioning for quick-service chains. The EU Single-Use Plastics Directive mandates phase-out timelines that redirect institutional procurement budgets. Berlin-Brandenburg clusters host vertically integrated distributors coordinating closed-loop collection systems with food delivery platforms.
United States
California and New York procurement mandates concentrate demand for certified compostable serviceware among delivery aggregators. FDA food-contact substance notifications govern PLA formulations entering interstate commerce. The Pacific Northwest hosts pilot programs testing marine-degradable alternatives for coastal tourism applications.
India
Quick-service restaurant expansion in Mumbai and Delhi drives BIS-certified compostable specifications into supply agreements. The Plastic Waste Management Rules mandate extended producer responsibility frameworks for foodservice packaging. Gujarat and Maharashtra industrial corridors concentrate bagasse molding operations near sugarcane processing facilities.
France
REACH restrictions on perfluoroalkyl substances eliminate fluorochemical coatings from takeaway containers ahead of enforcement deadlines. The EU Green Deal pressures petrochemical feedstock alternatives in food-contact materials. Île-de-France quick-service chains pilot PLA-laminated paperboard for oil-heavy cuisine applications.
Brazil
Sugarcane bagasse supply from São Paulo state processing facilities supports cost-competitive rigid container production for institutional catering. National solid waste policies incentivize compostable alternatives in federal procurement. The Southeast region concentrates fiber molding operations serving domestic foodservice and export markets.
Global Biodegradable Tableware Market Vendor Landscape
Listed leaders compete with private specialists across certification capabilities and collection infrastructure. The vendor base organizes around three tiers: multinational packaging conglomerates with European manufacturing footprints, mid-scale specialists with closed-loop collection systems, and regional fabricators serving cost-sensitive institutional accounts. Two strategic archetypes dominate competitive positioning: vertically integrated manufacturers controlling pulp processing through finished goods distribution, and technology licensors enabling regional producers to meet certification standards. M&A activity concentrates on coating technology assets and municipal composting logistics partnerships.
Within the multinational tier, Huhtamäki Oyj exemplifies European manufacturing scale, while Dart Container Corporation anchors North American fiber molding capacity. Among specialists with certified collection systems, Vegware Ltd occupies a position linking product certification to post-consumer composting program participation. These three entities represent distinct strategic postures: geographic manufacturing footprint, integrated operations, and closed-loop service integration.
| Leading Market Players |
|---|
| Huhtamäki Oyj |
| Dart Container Corporation |
| Vegware Ltd |
| Pactiv Evergreen Inc. |
| BioPak |
| Novolex |
| Genpak, LLC |
| Eco-Products |
| PacknWood |
| Others |
Supply Flow & Price Mechanics
Bagasse displacement of polystyrene in Indian and Brazilian quick-service procurement simultaneously redraws supply geography toward sugarcane processing corridors and compresses pricing economics for rigid container manufacturers lacking captive fiber access.
Pricing Analysis
The current-generation PLA-to-bagasse pricing gap spans roughly three performance tiers, with heat-resistant polylactic acid formulations commanding premium positioning in German and California municipal composting zones while bagasse pulp molding matches legacy polystyrene unit economics in cost-sensitive institutional catering. Price differentiation separates BPI-certified premium grades from uncertified economy alternatives, with FDA food-contact notification status adding further tier separation. Pricing pressure stems from corn starch feedstock volatility squeezing PLA margins, while bagasse producers face compression from sugarcane commodity cycles. Quick-service chains in India and Brazil exhibit the highest price sensitivity, whereas California delivery platforms prioritize certification compliance over unit cost.
Supply Chain Analysis
China and India anchor global biodegradable tableware manufacturing, with Chinese export hubs serving European and North American foodservice procurement while Indian domestic production concentrates near Gujarat and Maharashtra sugarcane processing facilities. Raw material flows draw from corn starch in the US Midwest, bagasse pulp from São Paulo state mills, and bamboo fiber from Sichuan province processors. Supply chain risk centers on single-source vulnerability for PLA resin production concentrated among limited polymerization facilities. Distribution runs through broadline foodservice wholesalers in developed markets, with digital procurement platforms disintermediating traditional channels for mid-scale independent restaurants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among California and New York food delivery platforms, with procurement consolidation forcing suppliers into post-consumer composting program participation as mandatory contract terms.
For Market Incumbents: Fortify closed-loop collection infrastructure ahead of platform consolidation mandates, embedding logistics partnerships that lock out smaller competitors lacking municipal waste operator relationships. Capacity expansion in Bavaria and North Rhine-Westphalia secures German quick-service supply agreements under EU Single-Use Plastics Directive timelines. Certification investment across BPI, TÜV Austria, and DIN CERTCO pathways defends against margin pressure from regional fabricators with narrower compliance scope. For New Entrants and Emerging Players: Post-consumer composting logistics gaps in mid-sized US municipalities offer white-space entry where incumbents under-serve account-by-account coordination complexity. India's BIS certification pathway remains penetrable ahead of Mumbai and Delhi waste segregation infrastructure buildout. Direct digital sales to independent restaurants bypass broadline distributor markups and enable customized SKU configurations for ethnic cuisine operators with specialized container requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed coating technology specialists holding enzymatic degradation IP for marine-degradable formulations. Long-term viability frames around municipal composting capacity expansion trajectories determining which material certifications translate to realized end-of-life value versus stranded greenwashing liability. Watch coastal tourism regulatory momentum in the Pacific Northwest as inflection signal for marine-degradable product line viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bagasse Pulp Processing | Captive fiber supply from São Paulo mills secures cost parity against polystyrene in Brazilian institutional catering. |
| BIS Certification Pre-Compliance Investment | Early alignment with India's compostable plastics standards positions suppliers for Mumbai and Delhi municipal procurement waves. |
| Closed-Loop Collection System Partnerships | Logistics integration with Berlin-Brandenburg waste operators meets California platform mandates for post-consumer composting participation. |
| Marine-Degradable Formulation R&D | Enzymatic degradation advances open coastal tourism segments unserved by industrial-compostable-only certification pathways. |
| Digital Procurement Platform Launch | Direct channels disintermediate broadline foodservice wholesalers for independent restaurant accounts with customized configuration needs. |
Methodological Framework
Cross-validation between primary interviews with foodservice procurement directors, municipal waste management operators, and coating technology R&D leads anchors the qualitative findings against secondary validation through EU Single-Use Plastics Directive implementation filings, FDA food-contact substance notification databases, and BIS compostable plastics certification records. Bottom-up demand modeling from quick-service chain procurement specifications triangulates with top-down supply assessment of bagasse pulp capacity and PLA resin production economics.
Sensitivity analysis across the projection horizon tests material substitution rates, municipal composting infrastructure buildout timing, and feedstock price volatility assumptions. Segmentation dimensions modeled include material type, product form, end-user vertical, and distribution channel, with regional regulatory cluster differentiation for EU, US, and Indian compliance pathways. CAGRs derive from installed base penetration curves and replacement cycle dynamics, incorporating food delivery platform procurement consolidation as volume concentration input.
Material uncertainties — municipal composting facility commissioning delays, REACH enforcement timeline shifts, and agricultural commodity price spikes — sit outside the modeled envelope. Forecasts reflect assumptions about certification standard harmonization and waste segregation infrastructure investment flows. Recalibration cycles align with material shifts in EU Green Deal implementation intensity and coastal state marine-degradable regulatory momentum.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Europe Biodegradable Cups Market
Biodegradable Packaging
Clear Bioplastics Packaging Market
Biodegradable Packaging
India Biodegradable Tableware & Packaging Products Market
Biodegradable Packaging
Bioplastic Packaging Bag Market
Biodegradable Packaging
Asia-Pacific Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Starch-Based Bioplastics Packaging Market
Biodegradable Packaging
Biodegradable Lids Market
Biodegradable Packaging
Biodegradable Packing Peanuts Market
Biodegradable Packaging
Biodegradable Plastic Bags and Sacks Market
Biodegradable Packaging
Biodegradable Cutlery Market
Biodegradable Packaging
Biopolymer Packaging Market
Biodegradable Packaging
Biodegradable Packaging Materials Market
Biodegradable Packaging
Bioplastic Packaging Market
Biodegradable Packaging
Biodegradable Water Bottles Market
Biodegradable Packaging
Bioadhesives for Packaging Market