
 Biodegradable Packaging Products Market | 2026-2036
Biodegradable Packaging Products Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Packaging Products Market Insights
The food industry is pivoting toward plant-based containers and compostable wrapping solutions as restaurant chains and grocery retailers face plastic reduction mandates. Mondi Group leverages its integrated paper and bioplastic operations to supply major European food brands with certified compostable packaging. Amcor plc sustains R&D intensity in barrier-coated biodegradable films that extend shelf life without petroleum-based layers. NatureWorks LLC anchors North American supply of Ingeo polylactic acid resins for thermoformed food trays and cold-drink cups.
Biodegradable packaging products are materials engineered to decompose through microbial action under composting conditions, typically within 90 to 180 days in industrial facilities, with specifications covering disintegration rate, heavy metal limits, and ecotoxicity per EN 13432 and ASTM D6400 standards. Their primary commercial purpose is to contain, protect, and present goods while eliminating persistent plastic waste accumulation in landfills and marine environments. Paper-based formats dominate current volume owing to mature recycling infrastructure and lower unit cost, yet bioplastics represent the fastest-expanding category as polylactic acid and polyhydroxyalkanoate production scales reduce resin premiums. Plant-based materials command margin concentration in premium personal care and organic food segments where consumers pay packaging differentiation.
The EU Green Deal and REACH frameworks mandate compostability certification for packaging placed on European markets, while the FDA governs food-contact safety for biodegradable materials in the United States. Extended producer responsibility laws in Germany and France now assign end-of-life collection costs directly to brand owners, accelerating demand for certified biodegradable alternatives. Stakeholders must monitor evolving industrial composting capacity gaps between material certification and actual regional processing infrastructure.
Market Dynamics
Extended producer responsibility laws across Europe are restructuring cost allocation in the biodegradable packaging value chain, forcing brand owners to internalize end-of-life collection expenses and redesign procurement specifications around certified compostability.
Growth Catalysts
- EU Green Deal mandates:The framework's single-use plastic restrictions compel food retailers and quick-service chains to replace petroleum-based containers with certified compostable alternatives, creating guaranteed offtake for converters.
- Polylactic acid resin scaling:NatureWorks and TotalEnergies Corbion are expanding fermentation capacity for Ingeo PLA, narrowing the cost gap with conventional polymers and enabling broader thermoformed tray adoption.
- German packaging converters:Extended producer responsibility compliance deadlines in 2025 are accelerating investment in barrier-coated paper and bioplastic lines to serve domestic food brands.
Market Restraints
- Industrial composting infrastructure gaps:Certification under EN 13432 outpaces actual regional processing capacity, creating stranded material risk in markets lacking anaerobic digestion or composting facilities.
- Polyhydroxyalkanoate feedstock volatility:Agricultural sugar and vegetable oil price swings transmit directly to PHA resin costs, compressing margins for specialty film producers.
- Conventional plastic substitution:Mechanical recycling advances for polypropylene and PET reduce the waste-management advantage of biodegradable alternatives in non-food contact applications.
Strategic Opportunities
- France's anti-waste law AGEC:Mandatory compostability for fast-food packaging by 2025 creates a concentrated demand window for certified suppliers with existing EU regulatory dossiers.
- Home-compostable certification:TÜV Austria's OK Compost HOME standard opens premium positioning for garden waste streams, differentiating from industrial-only competitors in personal care and premium food segments.
- E-commerce protective packaging:Cold-chain bioplastic loose fill and molded pulp corner protectors represent underpenetrated substitution territory as Amazon and Zalando implement plastic reduction pledges.
Industry Challenges
- EN 13432 testing timelines:Full certification requires 180-day disintegration validation plus ecotoxicity screening, stretching product development cycles and delaying commercial launches.
- Barrier coating integration:Combining oxygen and moisture resistance with compostable substrates demands co-extrusion expertise scarce among traditional paper converters.
- Composting facility contamination:Mislabeled conventional plastics entering industrial streams degrade output quality, prompting operators to reject certified materials absent clear provenance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Packaging Products Market |
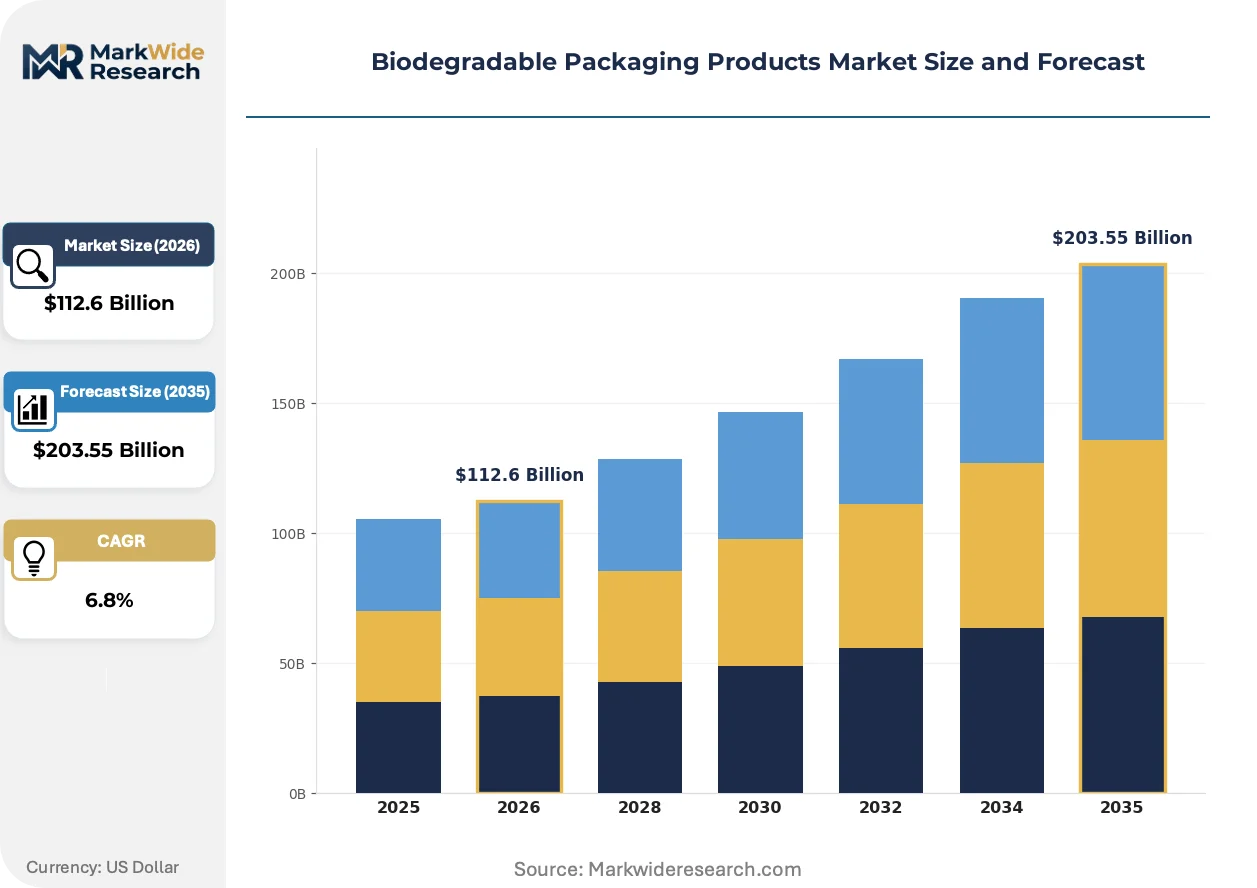
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $203.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioplastics, Paper, Plant-Based Materials, Mushroom Packaging End User: Food Industry, Consumer Electronics, Personal Care, Agricultural Sector Application: Packaging Materials, Bags, Containers, Wrapping Solutions Distribution Channel: Online Retail, Supermarkets, Wholesalers, Direct Sales |
| Companies Covered | Mondi Group, Amcor plc, Tetra Pak International SA, Smurfit Westrock, DS Smith, NatureWorks LLC, BASF SE, International Paper Company, Novamont S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Packaging Products Market Trends and Innovations
Barrier-coated paper substrates are absorbing functional roles once reserved for multilayer plastics, while regulatory certification requirements tighten material specifications and procurement departments rewrite supplier scorecards around compostability verification.
Cellulose nanofiber reinforcement is absorbing structural load-bearing functions in molded pulp trays and clamshells, enabling thinner walls without compromising stack strength. European dairy and ready-meal brands are piloting these formulations for refrigerated distribution. The technology is absorbing premium positioning in temperature-sensitive applications where conventional paperboard fails.
REACH framework amendments are tightening heavy metal limits in biodegradable packaging additives, forcing reformulation of colorants and slip agents used in bioplastic films. Compounders serving the European market are rebuilding supply chains around bio-based pigment systems. Food-contact notification dossiers now require expanded migration testing for novel biodegradable barrier layers.
Centralized procurement teams at grocery retailers are consolidating supplier lists around vertically integrated converters with in-house compostability certification capabilities. Regional distributors and merchant resin traders are losing shelf space as direct mill relationships become the preferred contracting mode. Germany's REWE and EDEKA chains exemplify this concentration, mandating third-party OK Compost verification for all private-label packaging tenders.
Biodegradable Packaging Products Market Segmentation
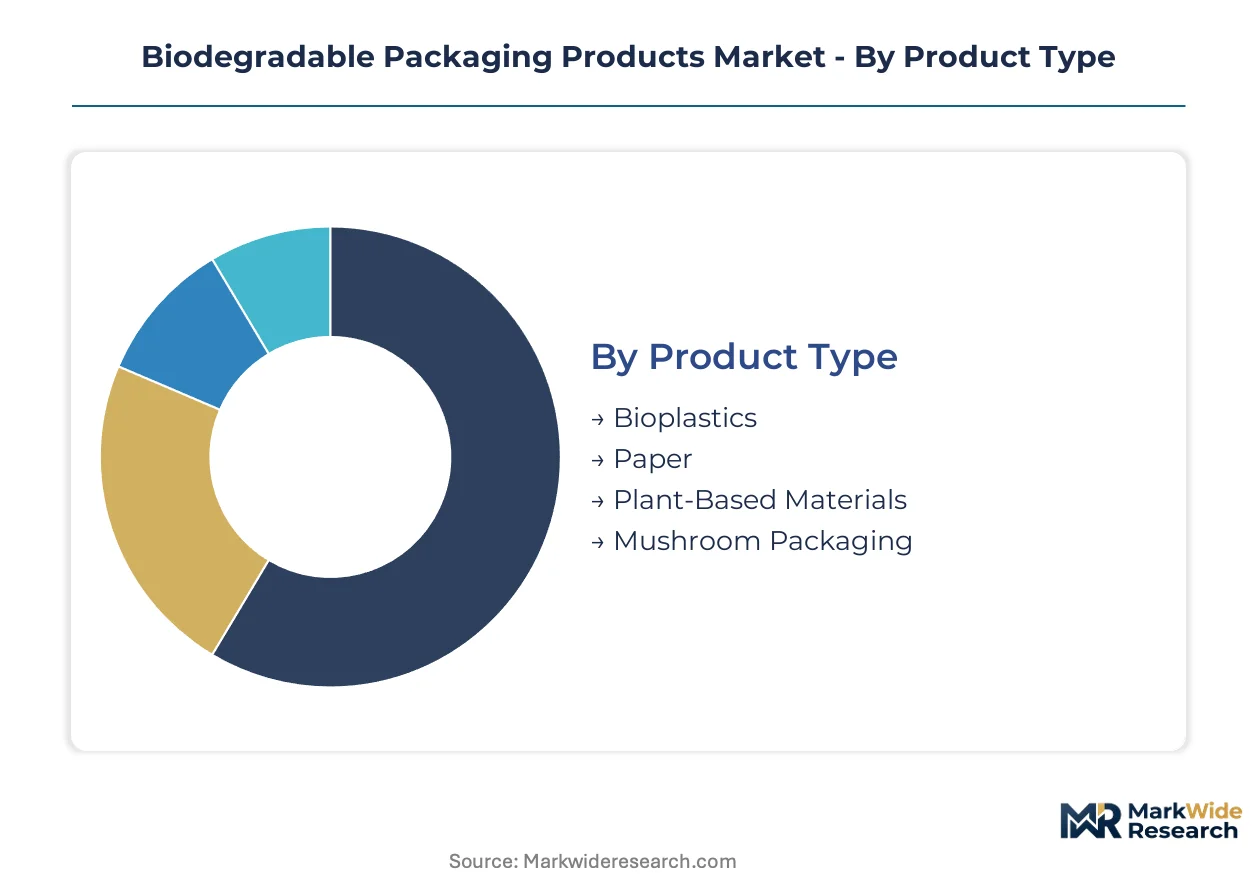
Segmentation in biodegradable packaging reveals where technical performance requirements diverge from cost-driven commodity substitution. Procurement teams at major food retailers and electronics manufacturers source from entirely different supplier pools based on barrier specifications and certification standards.
Product Type:
Standalone biodegradable materials dominate high-visibility consumer applications, while embedded bioplastic layers serve functional barrier roles within multilayer structures.
- Bioplastics:Polylactic acid and polyhydroxyalkanoate resins deliver thermoformability and heat-seal performance for food trays and flexible films. Demand concentrates in Germany's extended producer responsibility compliance window, where converters must certify compostability under EN 13432 to serve REWE and EDEKA private-label programs.
- Paper:Kraft and molded pulp substrates leverage existing recycling infrastructure while meeting home-compostable standards through TÜV Austria OK Compost HOME certification. European dairy brands pilot cellulose nanofiber-reinforced formulations for refrigerated distribution, absorbing structural load without petroleum-based barriers.
- Plant-Based Materials:Agricultural residue fibers and starch blends serve molded pulp protective packaging for e-commerce loose fill.
- Mushroom Packaging:Mycelium-bound agricultural waste creates custom-molded corner protectors and cushioning for consumer electronics shipments.
Paper leads volumes today; bioplastics are gaining share fastest.
End User:
Regulatory pressure intensity varies sharply across end-use verticals, with food-contact mandates driving certification investment far ahead of industrial applications.
- Food Industry:Quick-service chains and grocery retailers face mandatory compostability under France's AGEC law and EU Green Deal single-use plastic restrictions. Cold-chain bioplastic loose fill and barrier-coated containers absorb the bulk of converter capacity expansion.
- Personal Care:Premium organic brands command packaging differentiation through home-compostable certification, opening garden waste stream positioning unavailable to industrial-only competitors.
- Consumer Electronics:Molded pulp and mushroom packaging substitute expanded polystyrene in protective applications as Amazon and Zalando implement plastic reduction pledges.
- Agricultural Sector:Mulch films and crop protection sheets utilize soil-biodegradable formulations certified to regional agricultural standards.
Food industry procurement dominates absolute spend; personal care shows the steepest expansion trajectory.
Application:
Functional requirements stratify applications between primary containment demanding barrier performance and secondary protection prioritizing cost and disintegration speed.
- Packaging Materials:Flexible films and rigid containers requiring oxygen and moisture resistance drive co-extrusion investment among integrated paper and bioplastic converters.
- Containers:Thermoformed trays and clamshells for ready meals and fresh produce absorb polylactic acid resin scaling from NatureWorks and TotalEnergies Corbion fermentation capacity expansion.
- Bags:Carry-out and produce bags face mandatory thickness and compostability specifications under municipal ordinances in France and Germany.
- Wrapping Solutions:Stretch film and waxed paper alternatives serve butcher counters and bakery operations with lower barrier demands.
Containers anchor current revenue; flexible packaging materials climb the fastest.
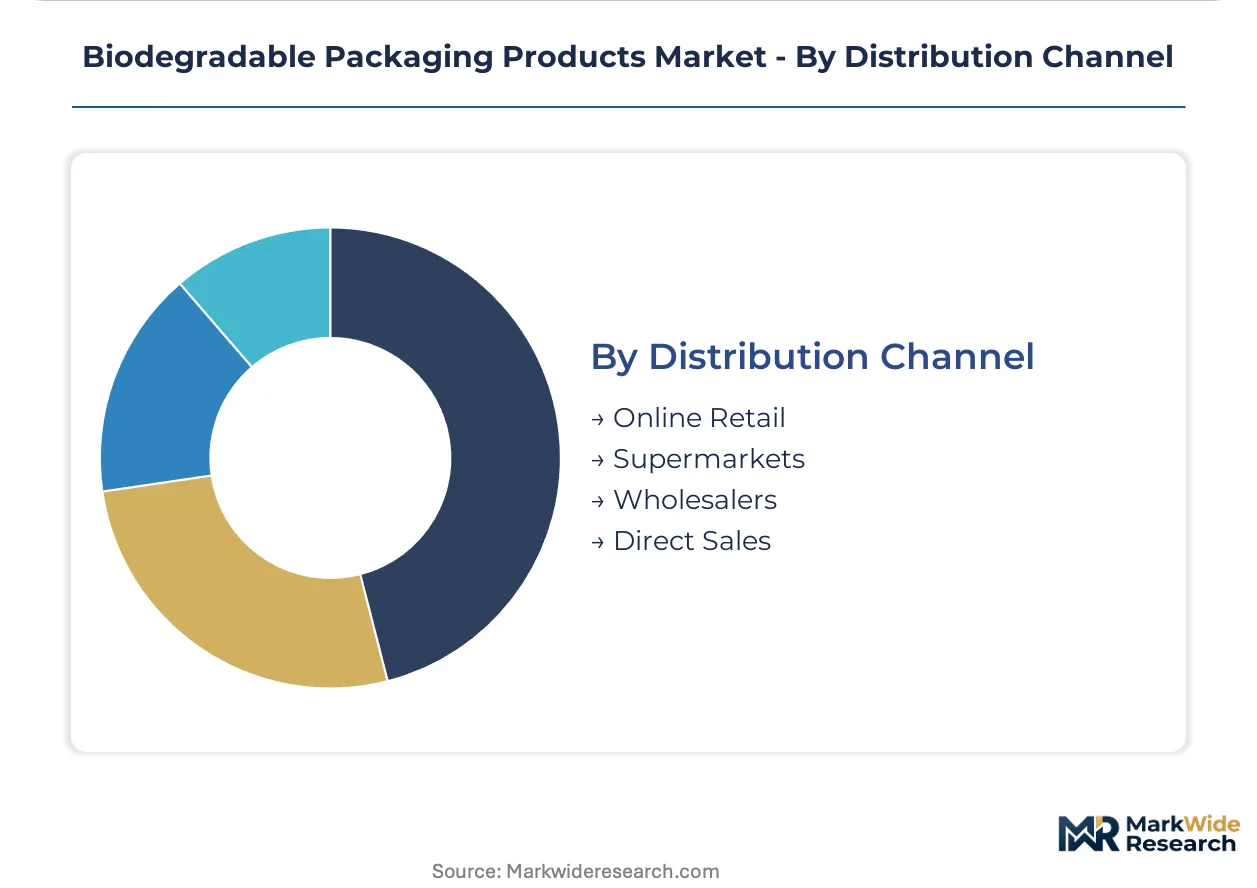
Distribution Channel:
Channel selection reflects order scale and certification verification requirements, with centralized procurement consolidating around direct mill relationships.
- Direct Sales:Vertically integrated converters with in-house compostability certification capabilities capture grocery retailer consolidation as REWE and EDEKA mandate third-party OK Compost verification for private-label tenders.
- Supermarkets:Private-label packaging procurement teams rewrite supplier scorecards around compostability verification, displacing regional distributors.
- Wholesalers:Merchant resin traders lose shelf space as brand owners internalize end-of-life collection costs under extended producer responsibility laws.
- Online Retail:E-commerce protective packaging demand for cold-chain bioplastic loose fill serves smaller volume buyers lacking direct converter access.
Direct sales command the largest contract values; online retail channels show the fastest growth rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as converters migrate toward jurisdictions with mature composting infrastructure and streamlined certification pathways. The EU Green Deal's cost-of-compliance gradient concentrates investment in Germany, France, and Benelux, while North American capacity clusters around resin production sites.
Germany
Extended producer responsibility deadlines in 2025 are accelerating converter investment in barrier-coated paper and bioplastic lines. The country's packaging ordinance mandates full cost internalization for end-of-life collection. Hamburg and North Rhine-Westphalia host the densest concentration of certified thermoforming operations serving REWE and EDEKA private-label programs.
France
AGEC law mandates compostable fast-food packaging by 2025, creating a concentrated demand window for certified suppliers. The anti-waste framework assigns collection infrastructure costs directly to brand owners. Île-de-France and Auvergne-Rhône-Alpes anchor converter capacity expansion for quick-service chain supply.
United States
FDA food-contact safety requirements govern biodegradable material approval timelines, with fermentation capacity expansion concentrated in the Midwest. NatureWorks anchors domestic Ingeo PLA resin supply from Nebraska operations. California municipal ordinances on single-use plastics drive coastal demand for certified alternatives.
Italy
Novamont's Novara operations anchor European starch-based bioplastic supply, with Lombardy hosting integrated compounder-converter clusters. The country's national packaging consortium enforces separate collection targets for compostable fractions. Emilia-Romagna's food processing corridor generates concentrated demand for thermoformed tray applications.
Netherlands
Randstad logistics infrastructure supports cross-border distribution of certified packaging into German and Belgian retail channels. The country's waste management operators maintain among Europe's highest industrial composting capacity per capita. Brabant's chemical cluster hosts pilot facilities for next-generation barrier coating development.
Biodegradable Packaging Products Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated paper-bioplastic converters commanding grocery retailer procurement consolidation. The vendor base stratifies into three tiers: multinational packaging conglomerates with captive resin supply, regional specialists with certification depth, and merchant compounders supplying formulation services. Strategic moves center on backward integration into fermentation capacity and geographic licensing of compostability certification dossiers.
Among integrated packaging conglomerates, Mondi Group exemplifies the vertically integrated archetype with paper and bioplastic operations spanning certification capabilities. Amcor plc occupies a position among barrier technology specialists, while NatureWorks LLC anchors the upstream resin tier as a dedicated polylactic acid producer. These three represent distinct competitive positioning vectors: substrate integration, functional coating expertise, and feedstock control.
| Leading Market Players |
|---|
| Mondi Group |
| Amcor plc |
| Tetra Pak International SA |
| Smurfit Westrock |
| DS Smith |
| NatureWorks LLC |
| BASF SE |
| International Paper Company |
| Novamont S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between industrial-compostable and home-compostable tiers splits both pricing power and supply chain configuration across the biodegradable packaging value chain. Buyers qualifying for France's AGEC mandates pay premiums for EN 13432-certified materials, while garden-waste stream positioning under TÜV Austria's OK Compost HOME standard commands separate margin pools from commodity paper converters.
Pricing Analysis
Distributor margin compression runs through merchant resin channels as REWE and EDEKA procurement teams consolidate around direct mill relationships. Three-tier pricing structure across premium certified, standard industrial-grade, and economy paper-based tiers reflects the certification ladder under EU Green Deal compliance windows. Price differentiation hinges on barrier coating performance and compostability verification depth. Cost compression in bioplastic resin tiers is intensifying because NatureWorks and TotalEnergies Corbion fermentation capacity expansion narrows the gap with conventional polymers. Quick-service chains show least price sensitivity for certified fast-food packaging, while agricultural mulch film buyers remain most cost-conscious.
Supply Chain Analysis
Dual-sourcing requirements from German grocery retailers mandate multi-supplier qualification for both polylactic acid resins and barrier-coated paper substrates. Geographic supply concentration centers on Germany, France, and Italy, with Novamont's Novara compounder cluster and Hamburg thermoforming operations anchoring European capacity. Raw material dependencies draw from agricultural sugar feedstocks for PLA fermentation, cellulose pulp for paper substrates, and vegetable oil streams for polyhydroxyalkanoate production. Single-source vulnerability persists in specialized barrier coating chemistries where co-extrusion expertise concentrates among integrated paper-bioplastic converters. Distribution runs through direct sales channels for large-format grocery tenders, with online retail serving smaller volume e-commerce protective packaging buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable packaging operates as a late-cycle quality story where procurement departments reward certified compostability over cost minimization. The demand-shift toward premium barrier-coated paper specifications for refrigerated ready-meals validates this premium positioning.
For Market Incumbents: Cement certification depth as the primary defensive moat by acquiring in-house compostability testing capabilities before EN 13432 timelines lengthen product development cycles. Add barrier coating capacity in North Rhine-Westphalia to capture REWE and EDEKA private-label consolidation. Mechanical recycling advances for polypropylene threaten the waste-management advantage of biodegradable alternatives in non-food segments, demanding tighter food-contact specialization. For New Entrants and Emerging Players: Enter via home-compostable certification gaps in personal care premium segments where TÜV Austria's OK Compost HOME standard remains underpenetrated. Target e-commerce protective packaging white space for cold-chain bioplastic loose fill as Amazon and Zalando plastic reduction pledges create guaranteed offtake. Lead with garden waste stream positioning unavailable to industrial-only competitors, leveraging direct-to-brand sales bypassing consolidated grocery procurement. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists holding captive compostability certification dossiers and vertical integration into fermentation feedstocks. Long-term viability over the coming decade hinges on industrial composting infrastructure buildout keeping pace with material certification expansion. Watch composting facility contamination rates as the inflection indicator—mislabeled conventional plastics degrading output quality could trigger operator rejection of certified materials absent provenance documentation, stranding premium-tier suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | NatureWorks and TotalEnergies Corbion expansion narrows PLA resin premiums against conventional polymers. |
| Compostability Certification Acquisition | In-house EN 13432 and OK Compost verification capabilities displace regional distributors from REWE and EDEKA tenders. |
| Barrier Coating Technology Licensing | Oxygen and moisture resistance co-extrusion expertise transfers to traditional paper converters facing skill gaps. |
| Geographic Licensing of Certification Dossiers | EU regulatory dossier portability accelerates market entry for converters in France's AGEC compliance window. |
| Home-Compostable Product Line Extension | TÜV Austria OK Compost HOME certification opens garden waste stream positioning in premium personal care segments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with packaging converter operations directors, grocery retailer procurement leads, composting facility managers, and bioplastic resin compounders with secondary validation. Customs trade data, EU ECHA regulatory filings, SEC 10-K disclosures from listed packaging conglomerates, and industrial composting capacity databases anchored the data foundation. Bottom-up capacity buildouts by fermentation plant and top-down demand projections by end-use vertical were triangulated for consistency.
Historical reference periods anchored the projection horizon to observed certification adoption curves and extended producer responsibility implementation timelines across European jurisdictions. Segmentation dimensions modeled include product type tier, end-use industry vertical, application functional requirement, and distribution channel structure. CAGRs were derived from fitted adoption curves incorporating regulatory mandate enforcement intensity and resin production capacity expansion schedules. Forecast inputs incorporated industrial composting facility commissioning rates and barrier coating technology yield improvements.
Inputs from converter operations directors and grocery procurement leads were available through the study window; gaps in real-time industrial composting throughput data introduce uncertainty bands around material adoption assumptions. Forecasts reflect documented assumptions regarding EN 13432 certification timeline adherence and fermentation capacity expansion schedules. Deviation in composting facility contamination rejection rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Biodegradable Water Bottles Market
Biodegradable Packaging
Oxo-Biodegradable Plastic Packaging Market
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Biodegradable Packaging Market
Biodegradable Packaging
Botanical Packaging Market
Biodegradable Packaging
Starch-Based Bioplastics Packaging Market
Biodegradable Packaging
Europe Biodegradable Plastic Packaging Market
Biodegradable Packaging
Biodegradable Plastic Bags and Sacks Market
Biodegradable Packaging
Europe Biodegradable Cups Market
Biodegradable Packaging
Global Bioplastic Multi-Layer Films Market
Biodegradable Packaging
Biodegradable Plastic Packaging Market
Biodegradable Packaging
Biodegradable Cups Market
Biodegradable Packaging
Biodegradable Packaging Materials Market
Biodegradable Packaging
Biodegradable Packing Peanuts Market
Biodegradable Packaging
Biopolymer Packaging Market