
 GCC Disposables (Single-Use) Packaging Market | 2026-2036
GCC Disposables (Single-Use) Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Disposables (Single-Use) Packaging Market Foresight
The GCC disposables packaging sector is pivoting between premium eco-certified tiers and commodity plastic lines as procurement teams split budgets across sustainability targets and cost floors. Hotpack Packaging LLC leverages integrated manufacturing across UAE and Saudi facilities to sustain volume leadership in food service disposables. Al Bayader International anchors its position through specialized paper-based product lines targeting hospitality procurement channels in Dubai and Abu Dhabi.
GCC disposables (single-use) packaging comprises engineered containers, serviceware, and utensils manufactured from plastic resins, paper substrates, biodegradable polymers, or expanded foam, typically designed for one consumer interaction before disposal. Specifications include heat resistance thresholds, moisture barrier ratings, and food-contact compliance certifications that govern safe usage across hot and cold applications. Plastic material segments dominate current volume flows while biodegradable alternatives capture accelerating interest from institutional buyers. Food service application channels lead absolute consumption, though healthcare end users generate higher per-unit margins through sterilization-grade requirements.
Saudi Standards, Metrology and Quality Organization (SASO) technical regulations and UAE Ministry of Climate Change and Environment circulars on single-use plastics are reshaping product compliance thresholds across Gulf markets. The Emirates Authority for Standardization and Metrology (ESMA) food contact material protocols further constrain import access for uncertified suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and bioplastics certification pathways to secure long-term positioning.
Market Dynamics
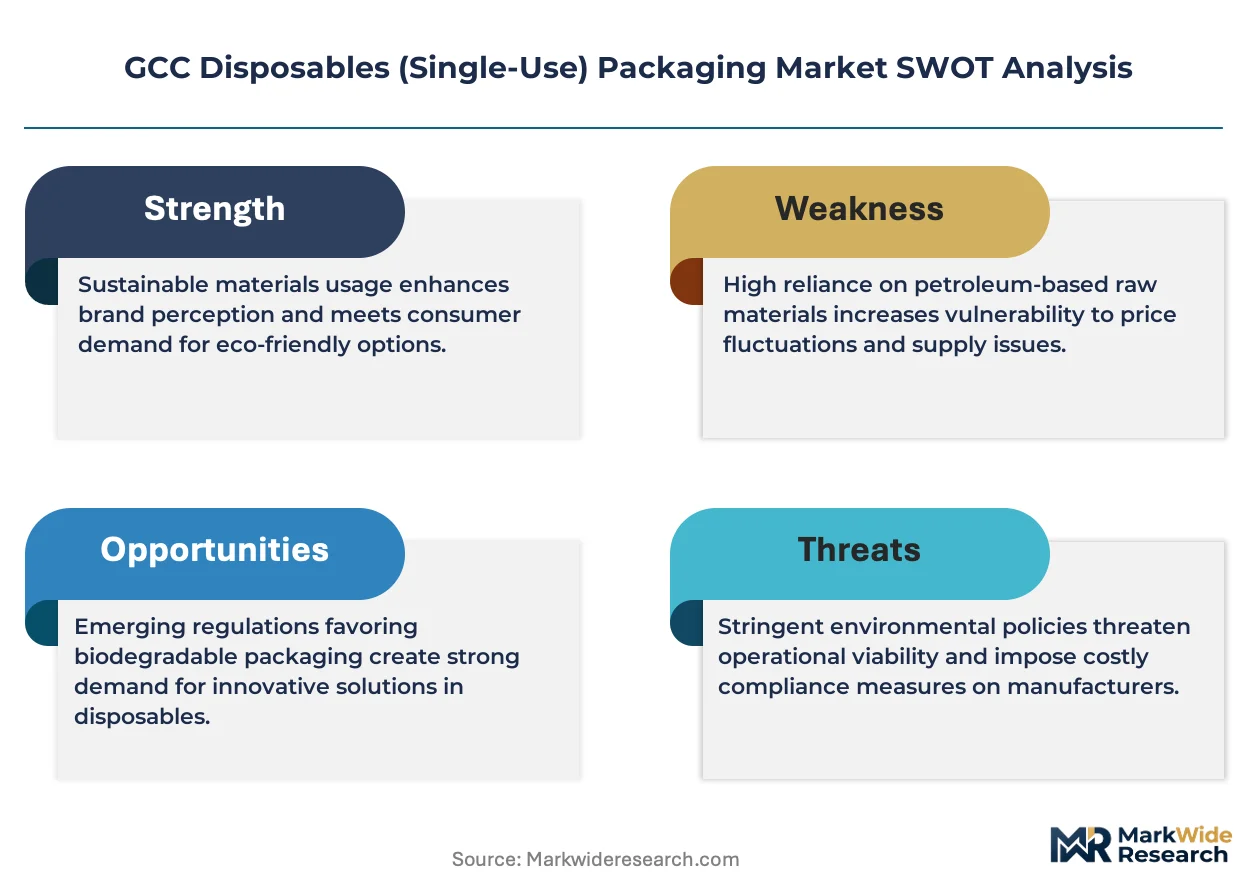
Saudi Vision 2030 sustainability mandates and UAE single-use plastic restrictions are compressing procurement timelines as food service operators scramble to certify biodegradable alternatives before compliance deadlines.
Growth Catalysts
- SASO Technical Regulations:Saudi Standards, Metrology and Quality Organization mandates on food-contact materials are forcing rapid material transitions toward certified biodegradable substrates in Riyadh and Jeddah food service corridors.
- QSR Channel Expansion:Quick-service restaurant chains across Saudi Arabia are doubling down on compostable packaging procurement to align with corporate sustainability commitments and avoid regulatory penalties.
- Biodegradable Polymer Innovation:PLA and bagasse-based formulations are achieving cost parity with conventional plastics at scale, accelerating adoption in UAE hospitality procurement channels.
Market Restraints
- Feedstock Cost Volatility:Sugarcane bagasse and corn-starch PLA prices fluctuate with agricultural commodity cycles, squeezing margin stability for converters dependent on bio-based inputs.
- Import Concentration Risk:Raw biopolymer resin supply concentrates among Southeast Asian producers, exposing GCC converters to shipping cost spikes and currency exposure.
- Performance Trade-offs:Current biodegradable alternatives exhibit inferior heat resistance above 85°C and shorter shelf stability, limiting penetration in hot-fill and long-distribution applications.
Strategic Opportunities
- Kuwait and Bahrain Penetration:These markets lag Saudi Arabia and UAE in regulatory stringency, creating first-mover windows for certified suppliers to establish procurement relationships before mandates arrive.
- Healthcare Sterilization-Grade Segment:Hospitals and clinics in Dubai and Abu Dhabi generate premium-margin demand for single-use sterile packaging with biodegradability credentials.
- Extended Producer Responsibility Frameworks:Emerging take-back and recycling obligations across Gulf states will reward vertically integrated players with captive collection infrastructure.
Industry Challenges
- ESMA Certification Timelines:Emirates Authority for Standardization and Metrology food-contact approval processes stretch 8-14 months, delaying product launches and freezing working capital.
- Bioplastics Composting Infrastructure Gap:Industrial composting facilities remain scarce across the GCC, undermining end-of-life claims and creating greenwashing liability exposure for brand owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Disposables (Single-Use) Packaging Market |
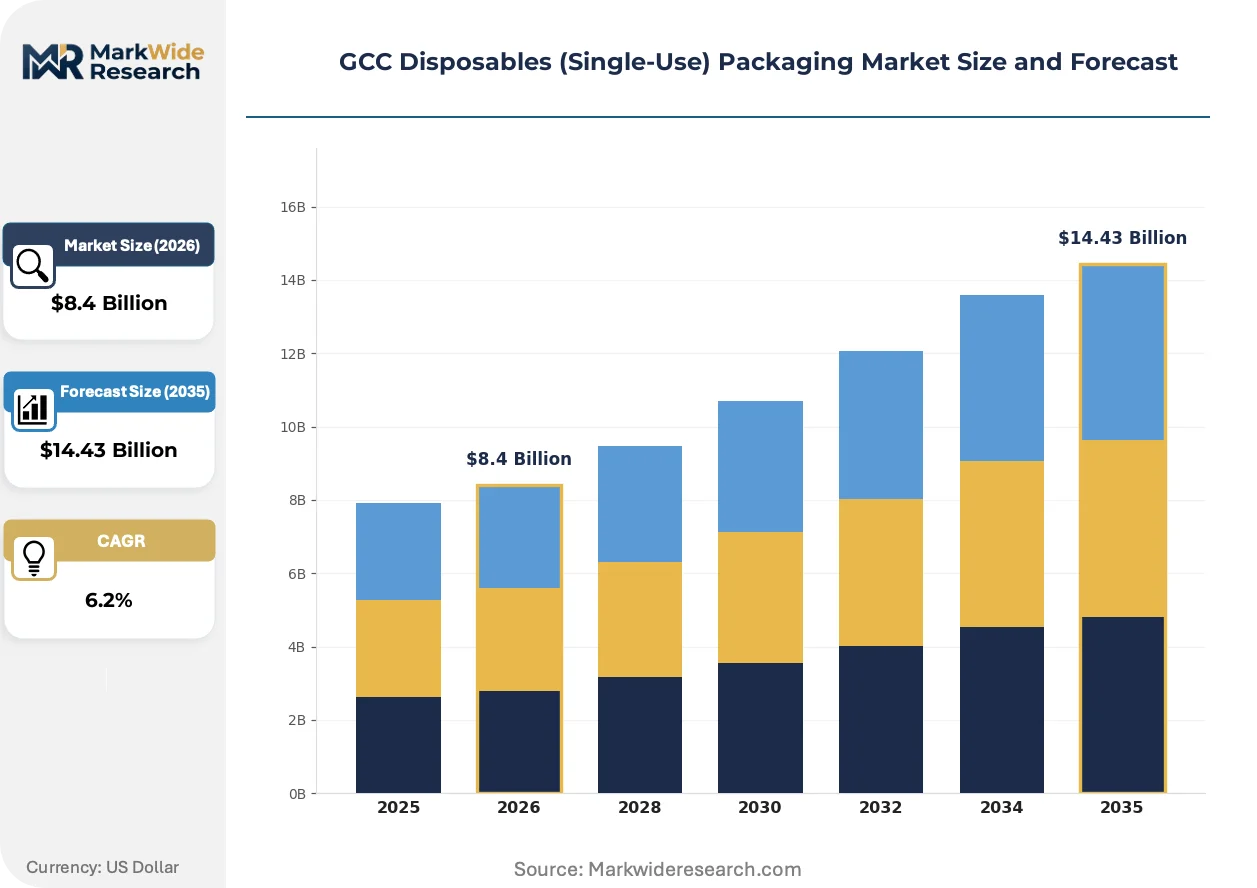
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Cups, Cutlery, Straws Material: Plastic, Paper, Biodegradable, Foam Application: Food Service, Retail, Healthcare, Events End User: Restaurants, Caterers, Hospitals, Retailers |
| Companies Covered | Precision Plastic Products Co (LLC), Panache International FZ LLC, Jebel Pack LLC, Al Bayader International, Gulf East Paper & Plastic Industries LLC, Detpak - Detmold Group, Freshpack LLC, Hotpack Packaging LLC, Falcon Pack, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Disposables (Single-Use) Packaging Market Shifts & Advancements
Material science breakthroughs and compliance-driven procurement are converging to restructure competitive advantage around certification depth rather than commodity scale alone.
Barrier-coated molded fiber technology is expanding into hot-food container applications previously dominated by expanded polystyrene. UAE-based catering operators are piloting these containers for delivery and event channels at accelerating volumes. This shift is compressing demand for fossil-based foam while creating specification battles between water-based and PLA-laminated fiber variants.
UAE Ministry of Climate Change and Environment circulars on single-use plastics are triggering supply chain requalification waves across Dubai and Abu Dhabi hospitality networks. Food service distributors must now document biodegradability certification for entire SKU portfolios to retain hotel and restaurant contracts. Smaller importers lacking ESMA documentation are losing shelf access to integrated regional manufacturers.
Centralized procurement consolidation is reshaping buyer-supplier relationships as Saudi and UAE food service groups aggregate purchasing across franchise networks. Procurement teams are replacing fragmented local supplier relationships with direct mill contracts tied to volume commitments and sustainability scorecards. This concentration is most visible in Riyadh-based QSR chains and Dubai hotel group purchasing organizations.
GCC Disposables (Single-Use) Packaging Market Segmentation
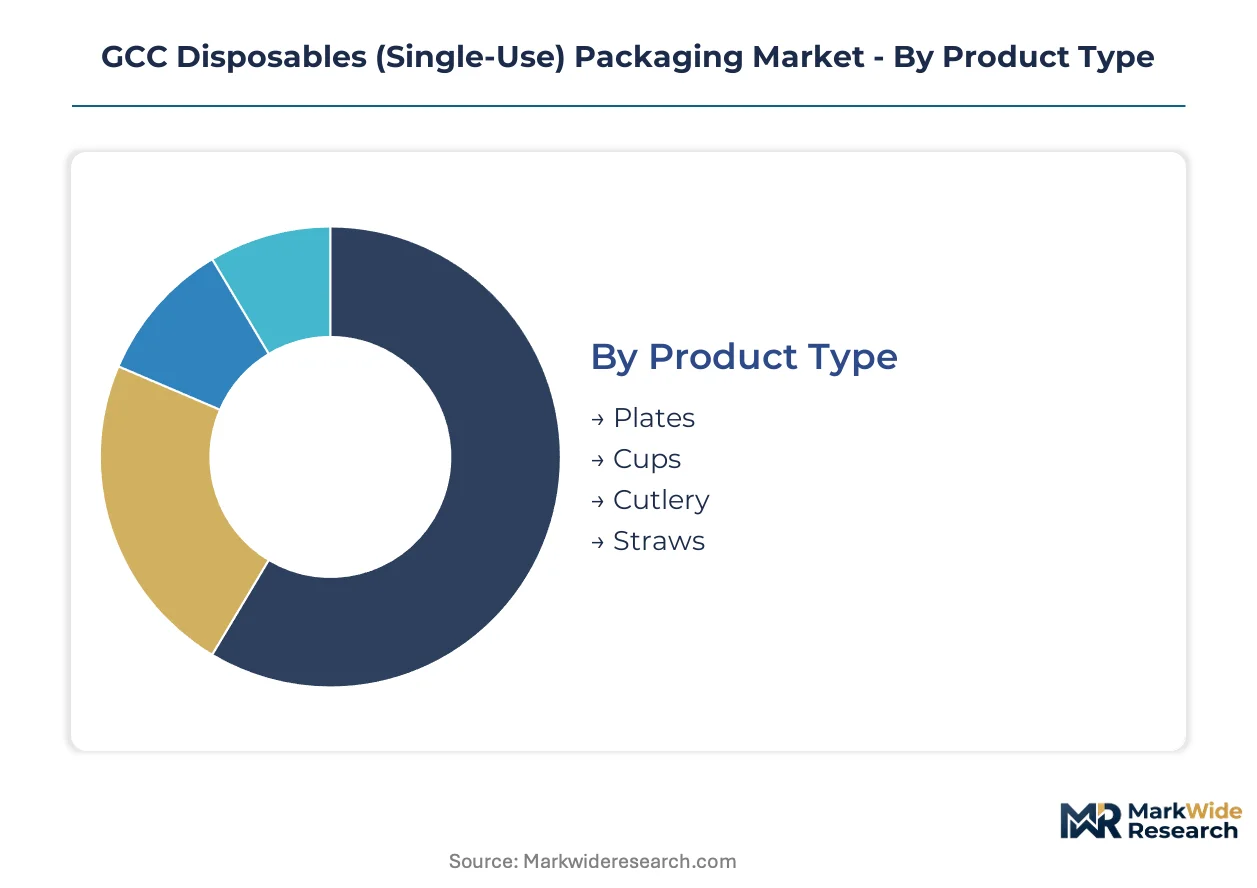
Certification requirements fragment procurement specifications across the GCC disposables sector, with ESMA food-contact protocols and SASO biodegradability mandates creating divergent compliance burdens by product category and material substrate.
Product Type:
ESMA certification timelines stretch longest for liquid-contact formats, while rigid food-contact items face accelerated SASO technical regulation deadlines in Saudi Arabia.
- Plates:Rigid substrates dominate current procurement volumes across Riyadh and Jeddah food service corridors. QSR chains in Saudi Arabia are consolidating purchasing around compostable molded fiber specifications to meet corporate sustainability commitments ahead of regulatory deadlines.
- Cups:Liquid-contact applications require the most extensive ESMA approval documentation, with heat-resistant biodegradable polymer formulations gaining traction in UAE hospitality channels despite 8-14 month certification timelines.
- Cutlery:Polystyrene alternatives face immediate displacement pressure from CPLA and bagasse options across Dubai catering networks.
- Straws:Paper and PLA variants have captured majority procurement share in UAE hotel group purchasing organizations following single-use plastic circulars.
Plates sit at the top of the volume ranking, with cups climbing the fastest as hot-beverage delivery channels expand across Saudi and UAE urban centers.
Material:
Cost tier stratification separates premium-certified biodegradable lines from commodity plastic volumes, with procurement teams splitting budgets across sustainability targets and margin floors.
- Plastic:Polypropylene and PET formulations retain dominant share in price-sensitive institutional procurement, though regulatory compression is narrowing viable applications to non-food-contact and cold-fill uses.
- Paper:Barrier-coated molded fiber technology is displacing expanded polystyrene in hot-food containers across UAE catering pilots, with water-based coating variants competing against PLA-laminated alternatives on cost and performance specifications.
- Biodegradable:PLA and bagasse-based substrates are achieving procurement scale in Dubai and Abu Dhabi hospitality networks, though industrial composting infrastructure gaps undermine end-of-life claims.
- Foam:Expanded polystyrene faces accelerating regulatory phase-out across Saudi Arabia and UAE markets, with remaining demand concentrating in cost-driven event catering and informal food service channels.
Plastic maintains volume leadership, though biodegradable materials are gaining share fastest as certification-compliant alternatives reach cost parity at procurement scale.
Application:
Application-specific performance requirements dictate material selection, with heat resistance and moisture barrier specifications varying sharply across end-use environments.
- Food Service:Quick-service restaurants and full-service dining operations across Saudi Arabia's Riyadh-Jeddah corridor generate the largest absolute demand, with procurement teams prioritizing heat-resistant biodegradable alternatives for hot-fill applications.
- Retail:Supermarket and convenience store channels in UAE are requalifying entire SKU portfolios around documented biodegradability certification to retain shelf access under distributor sustainability mandates.
- Healthcare:Hospitals and clinics in Dubai and Abu Dhabi generate premium-margin demand for sterilization-grade single-use packaging, with biodegradability credentials emerging as a secondary procurement criterion.
- Events:Large-scale catering and exhibition procurement in UAE concentrates volume during seasonal peaks, with compostable specifications increasingly mandatory for government-contracted events.
Food Service anchors absolute consumption, with Healthcare expanding most quickly on a value basis as sterilization-grade requirements command pricing premiums.
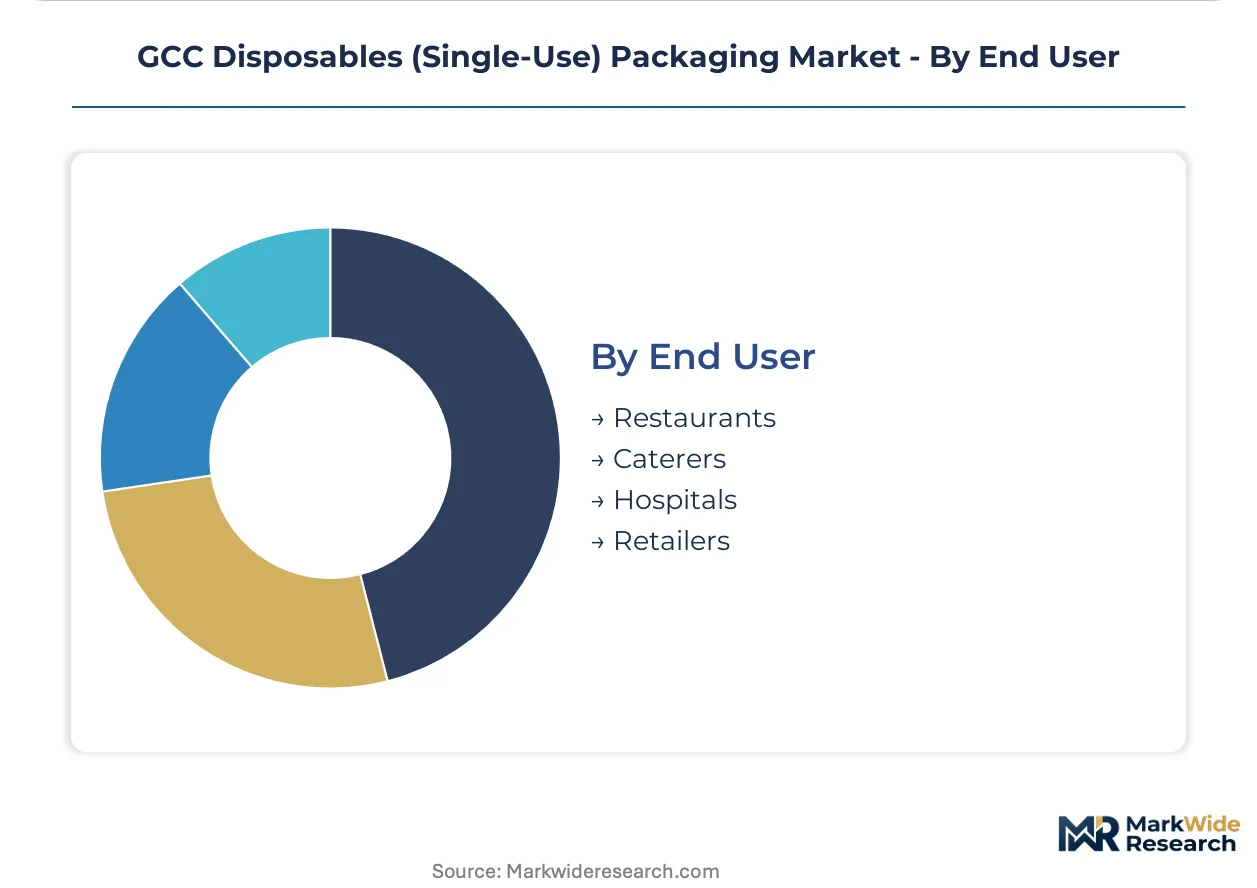
End User:
Customer type determines procurement sophistication, with centralized purchasing organizations imposing sustainability scorecards that fragmented independent operators cannot match.
- Restaurants:Chain QSR operators across Saudi Arabia are replacing fragmented local supplier relationships with direct mill contracts tied to volume commitments and certification documentation.
- Caterers:Event and institutional catering operators in Dubai are piloting barrier-coated molded fiber containers at accelerating volumes, compressing demand for fossil-based foam in delivery and banquet applications.
- Hospitals:Dubai and Abu Dhabi medical facilities require ESMA-compliant food-contact materials alongside sterilization protocols, creating dual certification burdens that favor established regional manufacturers over import-dependent distributors.
- Retailers:Hypermarket and supermarket procurement teams in UAE are consolidating supplier relationships around integrated manufacturers capable of documenting full-chain biodegradability certification.
Restaurants lead procurement volume, with hospitals following the steepest margin trajectory as sterilization-grade specifications compound certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging engineers and sustainability compliance officers cluster in Riyadh and Dubai, anchoring the GCC's technical workforce for single-use packaging transitions. These talent concentrations sit at the intersection of SASO regulatory mandates and corporate procurement deadlines.
Saudi Arabia
QSR procurement teams in Riyadh and Jeddah are consolidating purchasing around compostable molded fiber specifications ahead of SASO technical regulation deadlines. The Saudi Vision 2030 sustainability framework mandates rapid material transitions across food service corridors. Riyadh-based QSR chains are replacing fragmented local supplier relationships with direct mill contracts tied to volume commitments and certification documentation.
United Arab Emirates
Dubai and Abu Dhabi hospitality networks are requalifying entire SKU portfolios around ESMA food-contact documentation to retain hotel and restaurant contracts. The UAE Ministry of Climate Change and Environment single-use plastic circulars trigger supply chain requalification waves across distributor networks. Dubai-based catering operators are piloting barrier-coated molded fiber containers at accelerating volumes, compressing demand for fossil-based foam in delivery channels.
Kuwait
Food service distributors in Kuwait City are establishing early procurement relationships with certified biodegradable suppliers ahead of anticipated regulatory mandates. The country's national environmental regulator is drafting circulars modeled on UAE and Saudi precedents. Kuwait City-based institutional catering operators generate seasonal volume peaks for compostable event packaging.
Bahrain
Manama-based hospitality procurement teams are sourcing certified alternatives through UAE and Saudi distributor channels while local compliance frameworks mature. The national standards body is aligning technical regulations with Gulf Cooperation Council harmonization initiatives. Manama's food service corridor concentrates demand for price-sensitive biodegradable alternatives in QSR and casual dining segments.
Qatar
Doha-based event catering operators and hotel groups are mandating compostable specifications for government-contracted events and international exhibition procurement. The national climate and environment ministry is implementing extended producer responsibility consultations. Doha's hospitality procurement organizations aggregate purchasing across franchise networks with sustainability scorecards.
GCC Disposables (Single-Use) Packaging Market Competitive Landscape
Top-tier vendors anchor integrated manufacturing positions across UAE and Saudi facilities, while mid-tier converters and import-dependent distributors compete on certification speed and regional logistics reach. The vendor base stratifies across three archetypes: integrated regional manufacturers with captive production, specialized paper-based converters targeting hospitality channels, and biopolymer-focused innovators scaling PLA and bagasse formulations. Capacity expansion and strategic partnerships dominate competitive moves as players race to secure ESMA and SASO certifications before compliance deadlines.
Among UAE-based integrated manufacturers, Hotpack Packaging LLC and Al Bayader International occupy positions exemplifying scale-driven and specialization-driven archetypes respectively. Hotpack Packaging LLC represents the integrated manufacturing model with facilities spanning UAE and Saudi Arabia. Al Bayader International exemplifies the paper-based specialization approach targeting hospitality procurement channels. Gulf East Paper & Plastic Industries LLC sits within the diversified converter tier, balancing plastic and fiber substrate capabilities.
| Leading Market Players |
|---|
| Precision Plastic Products Co (LLC) |
| Panache International FZ LLC |
| Jebel Pack LLC |
| Al Bayader International |
| Gulf East Paper & Plastic Industries LLC |
| Detpak - Detmold Group |
| Freshpack LLC |
| Hotpack Packaging LLC |
| Falcon Pack |
| Others |
Supply & Pricing Matrix
Centralized procurement organizations across Saudi and UAE food service networks concentrate purchasing power into direct mill contracts, compressing margins for distributors and rewarding integrated manufacturers with captive certification documentation.
Pricing Analysis
Certification-bundled pricing separates ESMA-compliant biodegradable lines from uncertified commodity imports. Price differentiation hinges on biodegradability certification tier and volume scale commitments, with Riyadh-based QSR chains commanding steepest discounts through consolidated direct contracts. Pricing pressure stems from feedstock cost volatility in agricultural commodity-linked PLA and bagasse inputs. Independent catering operators exhibit highest price sensitivity, while Dubai hospital procurement teams absorb premiums for sterilization-grade specifications.
Supply Chain Analysis
Raw biopolymer resin supply draws from Thailand, Malaysia, and Indonesia, exposing GCC converters to shipping cost spikes and currency exposure. Key inputs include sugarcane bagasse, corn-starch PLA, and barrier-coated molded fiber substrates. Single-source vulnerability concentrates in Southeast Asian biopolymer producers, with limited qualified alternatives for ESMA-compliant food-contact grades. Distribution runs through integrated regional manufacturers with captive UAE and Saudi production facilities, while import-dependent distributors lose shelf access to certified competitors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kuwait and Bahrain lag Saudi Arabia and UAE in regulatory stringency, creating procurement windows where certified suppliers can establish relationships ahead of mandate-driven cost premiums.
For Market Incumbents: Lock in Riyadh and Jeddah QSR procurement relationships through multi-year direct contracts tied to SASO certification maintenance and volume commitments. Deepen backward integration into biopolymer compounding capabilities to reduce exposure to Southeast Asian resin price volatility. Prioritize captive industrial composting infrastructure investments to defend end-of-life claims against greenwashing liability exposure. For New Entrants and Emerging Players: SASO technical regulations in Saudi Arabia open a window for certified biodegradable suppliers to displace fragmented local distributors before compliance deadlines harden. Target Kuwait City institutional catering operators ahead of anticipated regulatory circulars modeled on UAE precedents. Enter through hospitality procurement channels in Manama via UAE distributor partnerships while local certification frameworks mature. For Investors and Strategic Acquirers: Integrated packaging conglomerates are the most active acquirer in this space, seeking ESMA-certified production assets to consolidate procurement relationships across Dubai and Abu Dhabi hospitality networks. Long-term viability centers on vertical control over certification pathways and composting infrastructure rather than commodity scale alone. Watch for industrial composting facility permitting announcements across Gulf states as inflection indicators for end-of-life claim defensibility.| Strategic Initiative | Industry Significance |
|---|---|
| ESMA Certification Investment | 8-14 month approval timelines freeze working capital for uncertified competitors. |
| Backward Integration into Biopolymer Compounding | Captive resin production insulates margins from Southeast Asian agricultural commodity cycles. |
| Industrial Composting Infrastructure Buildout | End-of-life facility ownership defends biodegradability claims against greenwashing exposure. |
| Direct Mill Contract Consolidation | Riyadh-based QSR chains replace fragmented distributors with volume-tied sustainability scorecards. |
| Kuwait and Bahrain First-Mover Expansion | Anticipated regulatory harmonization creates procurement windows before mandate-driven cost premiums arrive. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with packaging procurement managers at Saudi and UAE food service groups, sustainability compliance officers at hospitality operators, and technical directors at integrated manufacturers with secondary validation through SASO technical regulation filings, ESMA food-contact material protocols, UAE Ministry of Climate Change and Environment circulars, and customs trade data on biopolymer resin imports. Bottom-up SKU-level volume builds triangulated against top-down sector expenditure estimates.
Segment-weighting across product type, material substrate, application channel, and end-user archetype anchored the analytical framework throughout the forecast period. CAGRs derived from regression against regulatory deadline schedules and procurement contract renewal cycles. Industry-specific inputs included biodegradability certification penetration rates and industrial composting facility development pipelines across Gulf states.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated SASO mandate implementation or sustained agricultural commodity price spikes. Forecasts reflect assumptions on regulatory harmonization timelines and certification capacity constraints. A small set of triggers warrants ongoing watch: ESMA approval backlog clearance rates, Southeast Asian biopolymer export quota adjustments, and Gulf state extended producer responsibility framework announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Global Anti-Static Films Market
Packaging Materials
Transit Packaging Market
Packaging Materials
Insulated Thermal Box Liners Market
Packaging Materials
Packaging Materials Market
Packaging Materials
Global Adherence Packaging Market
Packaging Materials
Brazil Packaging Market
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
Global Packaging Foams Market
Packaging Materials
Flow Wraps Market
Packaging Materials
Sun Control Films Market
Packaging Materials
Disposable Egg Trays Market
Packaging Materials
Hygiene Packaging Market
Packaging Materials
Paint Packaging Market
Packaging Materials
Cutterbox Films Market
Packaging Materials
Insulated Box Liner Market
Packaging Materials
PET Packaging Market