
 Wheat Straw Cutlery Market | 2026-2036
Wheat Straw Cutlery Market Size, Share, and Industry Trends Forecast 2026-2036
Wheat Straw Cutlery Market Analytics
Multi-source agricultural fiber procurement is pivoting toward vertically integrated supply chains as wheat straw prices fluctuate with grain harvest cycles. Biotrem leverages captive straw supply from Polish cooperative farms to stabilize input costs. Eco-Products sustains North American market presence through direct contracts with Kansas and Nebraska wheat belt processors. Manglam Industries anchors South Asian production with dedicated molding facilities in Punjab's grain-processing corridor.
Wheat straw cutlery consists of thermoformed or injection-molded utensils manufactured from pulverized wheat stalk fibers combined with plant-based binders, typically withstands temperatures between 100°C and 120°C, and serves as a compostable alternative to petroleum-based disposable tableware in foodservice operations. The product-type dimension shows forks and spoons commanding volume leadership due to universal meal-service applicability, while knives remain technically challenging because fiber-composite edge retention struggles against dense foods. Application segmentation reveals foodservice and catering as the mature revenue core, whereas events and household channels are expanding fastest as retail distribution penetrates consumer pantry stockpiles.
The EU's Single-Use Plastics Directive and REACH compliance frameworks mandate compostability certifications for fiber-based utensils entering European foodservice supply chains, directly shaping product formulation standards and market access requirements. The US FDA regulates food-contact substances under 21 CFR, while the USDA BioPreferred program confers federal purchasing preference on certified biobased cutlery. China's SAMR enforces GB standards for disposable tableware safety, including heavy-metal limits in agricultural-fiber composites. Stakeholders must monitor evolving compostability certification reciprocity between European EN 13432 and US ASTM D6400 standards to avoid market fragmentation that would complicate cross-border product strategies.
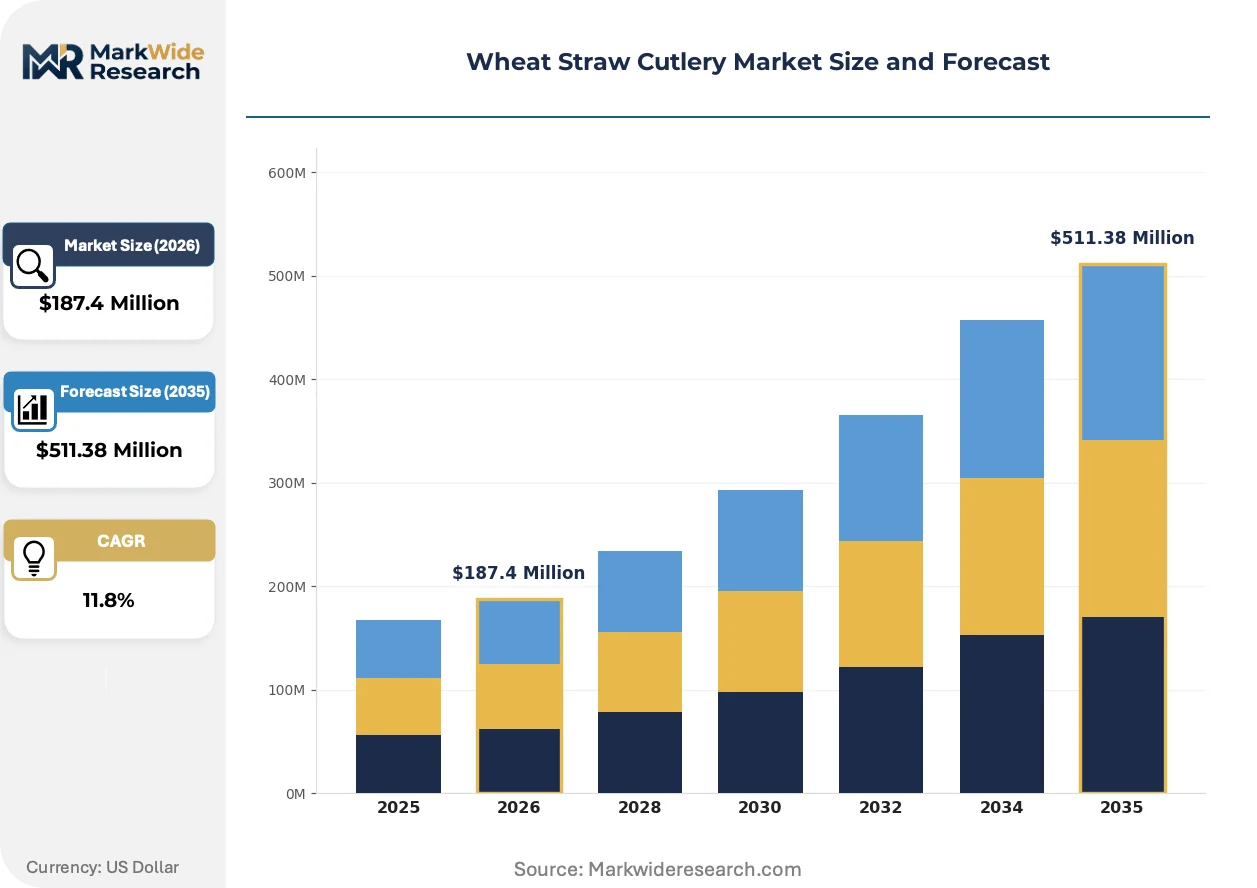
Market Dynamics
The wheat straw cutlery market pivots on regulatory bans against petroleum-based disposables, with the EU Single-Use Plastics Directive and similar mandates across multiple jurisdictions forcing foodservice operators toward fiber-molded alternatives. This structural pressure compresses substitution timelines and concentrates procurement authority among large-scale buyers.
Growth Catalysts
- EU Single-Use Plastics Directive:The ban on conventional plastic cutlery creates immediate compliance demand across European foodservice, with municipal composting infrastructure in Germany and France processing agricultural-fiber tableware at industrial scale.
- Quick-service restaurant procurement:North American QSR chains are replacing petroleum-based utensils with fiber-molded alternatives, driving volume commitments that stabilize manufacturing capacity utilization.
- Composting infrastructure maturation:Industrial composting facilities in the Netherlands and Belgium now accept wheat straw cutlery, closing the waste-loop and validating product claims for institutional buyers.
Market Restraints
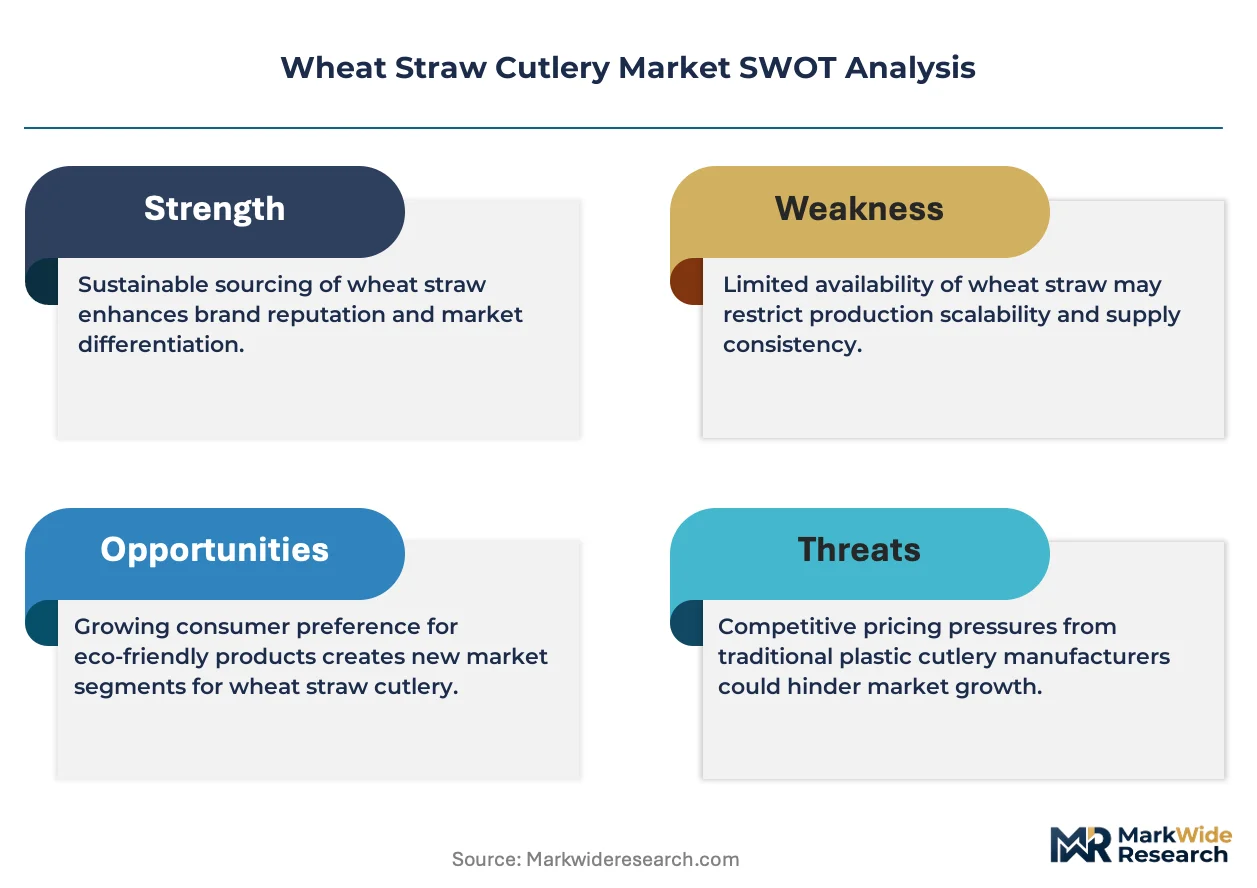
- Grain harvest price volatility:Wheat straw input costs fluctuate with annual grain yields, squeezing margin predictability for molders lacking cooperative farm contracts or captive supply arrangements.
- Fiber-composite edge retention limits:Knives manufactured from wheat straw struggle against dense foods, restricting application scope and forcing continued reliance on alternative materials for cutting implements.
- Certification reciprocity gaps:Non-alignment between European EN 13432 and US ASTM D6400 compostability standards fragments product strategies and raises compliance costs for cross-border suppliers.
Strategic Opportunities
- Events and household channels:Retail distribution penetration into consumer pantry stockpiles is expanding fastest as sustainability messaging reaches end-users directly through e-commerce platforms.
- USDA BioPreferred program:Federal purchasing preference for certified biobased cutlery opens institutional procurement pathways, including military and school nutrition programs.
- Thermoforming-injection molding convergence:Hybrid manufacturing processes combining thermoforming efficiency with injection-molding precision are enabling thinner-walled, lower-cost utensil production.
Industry Challenges
- Compostability certification timelines:Laboratory testing and documentation for EN 13432 or ASTM D6400 approval extends 12-18 months, delaying market entry and tying up working capital.
- Supply chain reconfiguration friction:Foodservice distributors must re-slot warehouse layouts and retrain procurement staff to handle compostable product categories with distinct handling requirements and shorter shelf lives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheat Straw Cutlery Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $511.38 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forks, Spoons, Knives, Plates Application: Foodservice, Catering, Events, Household End User: Restaurants, Cafes, Catering Services, Households Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Biotrem, Eco-Products, Vegware, Manglam Industries, Shantou Europe Pack Plastic Co., Ltd., Wenzhou Puqiao Arts and Crafts, Hubei Wheat-Straw Environmental Technology, GreenGood USA, BioGreenChoice, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheat Straw Cutlery Market Evolving Landscape
Material science advances and regulatory harmonization efforts are compressing product development cycles while expanding the performance envelope of agricultural-fiber tableware. Three developments are restructuring competitive positioning.
Advanced plant-based binders are absorbing moisture-resistance limitations that previously restricted wheat straw cutlery to dry-food applications. Quick-service chains in Scandinavia are deploying these reformulated utensils for hot soup service. The technology is absorbing market share from polylactic acid alternatives by matching temperature tolerance at lower unit cost.
REACH compliance frameworks are tightening heavy-metal thresholds in agricultural-fiber composites, forcing reformulation of colorants and process additives. European molders are investing in X-ray fluorescence screening equipment to verify incoming raw material batches. The cutlery segment faces the steepest compliance burden due to direct food-contact classification and children's meal service exposure.
Foodservice procurement teams are consolidating supplier rosters around vertically integrated manufacturers with documented farm-to-facility traceability. Kansas and Nebraska wheat belt processors are capturing volume leadership through direct straw sourcing contracts. The shift is most visible in North American institutional catering, where sustainability scorecards now weight supply chain transparency above unit price.
Wheat Straw Cutlery Market Segmentation
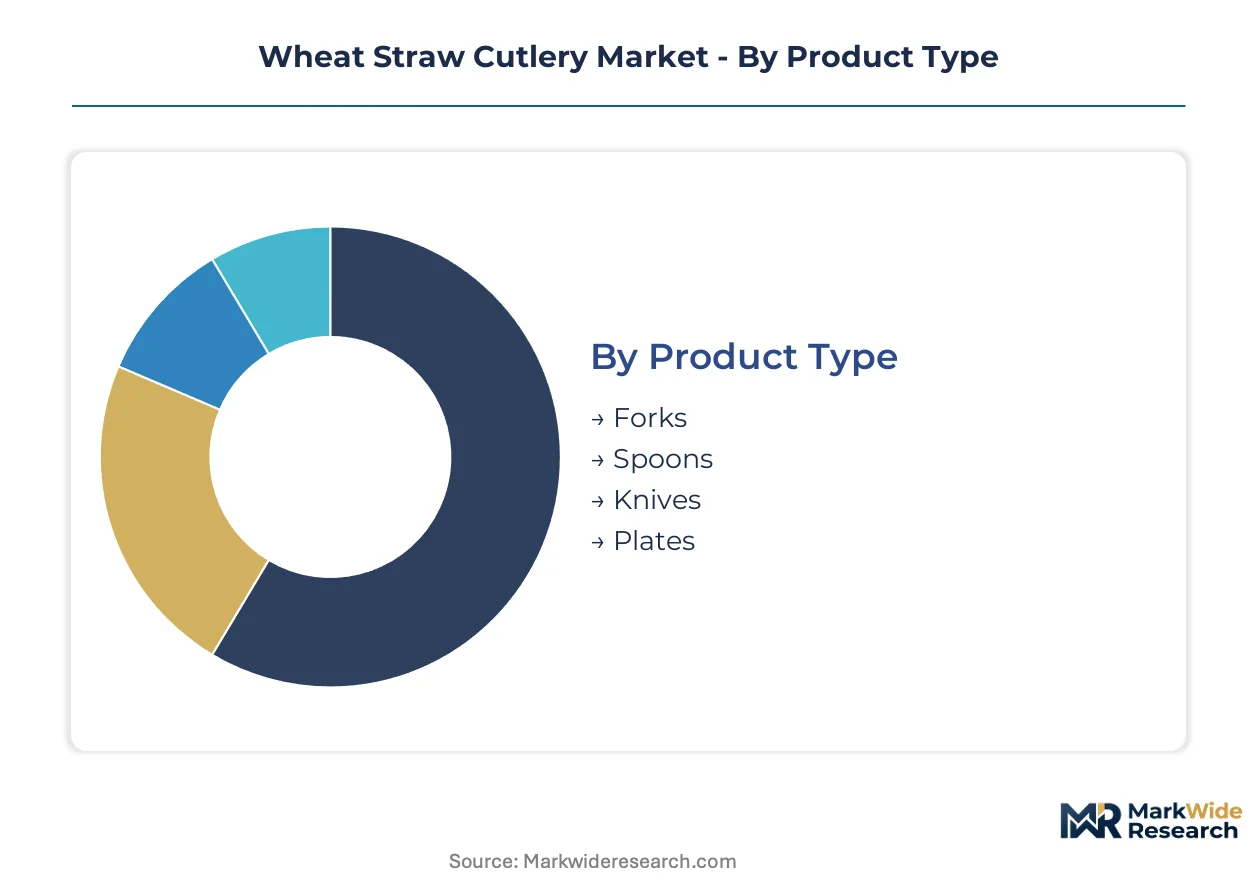
Wheat straw cutlery manufacturers configure product portfolios around thermal performance thresholds and compostability certification tiers. Segmentation decisions determine mold tooling investments, binder formulation costs, and which foodservice channels validate product claims.
Product Type:
Thermal tolerance and structural integrity specifications define the manufacturing approach across utensil geometries.
- Forks:Tines formed through thermoforming or injection-molding withstand temperatures between 100°C and 120°C. Quick-service restaurants across North America deploy these for hot meal service, with procurement teams prioritizing EN 13432 or ASTM D6400 certification alignment.
- Spoons:Bowl-depth geometry requires higher binder ratios to prevent liquid absorption during soup service. Scandinavian foodservice chains are absorbing advanced plant-based binder formulations for extended moisture resistance.
- Knives:Fiber-composite edge retention struggles against dense foods, restricting application scope.
- Plates:Larger surface area demands thicker wall sections and longer cooling cycles in production.
Forks lead on scale; knives lag on technical feasibility.
Application:
Channel maturity determines pricing power and certification documentation requirements.
- Foodservice:Institutional procurement teams consolidate supplier rosters around vertically integrated manufacturers with farm-to-facility traceability. Kansas and Nebraska wheat belt processors capture volume leadership through direct straw sourcing contracts.
- Catering:Event-based demand concentrates in Germany, where municipal composting infrastructure processes agricultural-fiber tableware at industrial scale.
- Events:Retail distribution penetration into consumer pantry stockpiles is expanding most quickly as sustainability messaging reaches end-users directly through e-commerce platforms.
- Household:Shorter purchase cycles and price sensitivity dominate this emerging channel.
Foodservice anchors revenue stability; events climb the fastest.
End User:
Operational scale dictates order batch sizes and logistics configuration.
- Restaurants:High-volume quick-service chains drive thermoforming-injection molding convergence for thinner-walled, lower-cost production.
- Cafes:Smaller footprint operations prioritize compact packaging and minimal storage requirements.
- Catering Services:Seasonal demand spikes require flexible manufacturing capacity and rapid fulfillment windows.
- Households:Individual consumers respond to USDA BioPreferred labeling and retail shelf placement.
Restaurants dominate procurement volume; households gain share fastest.
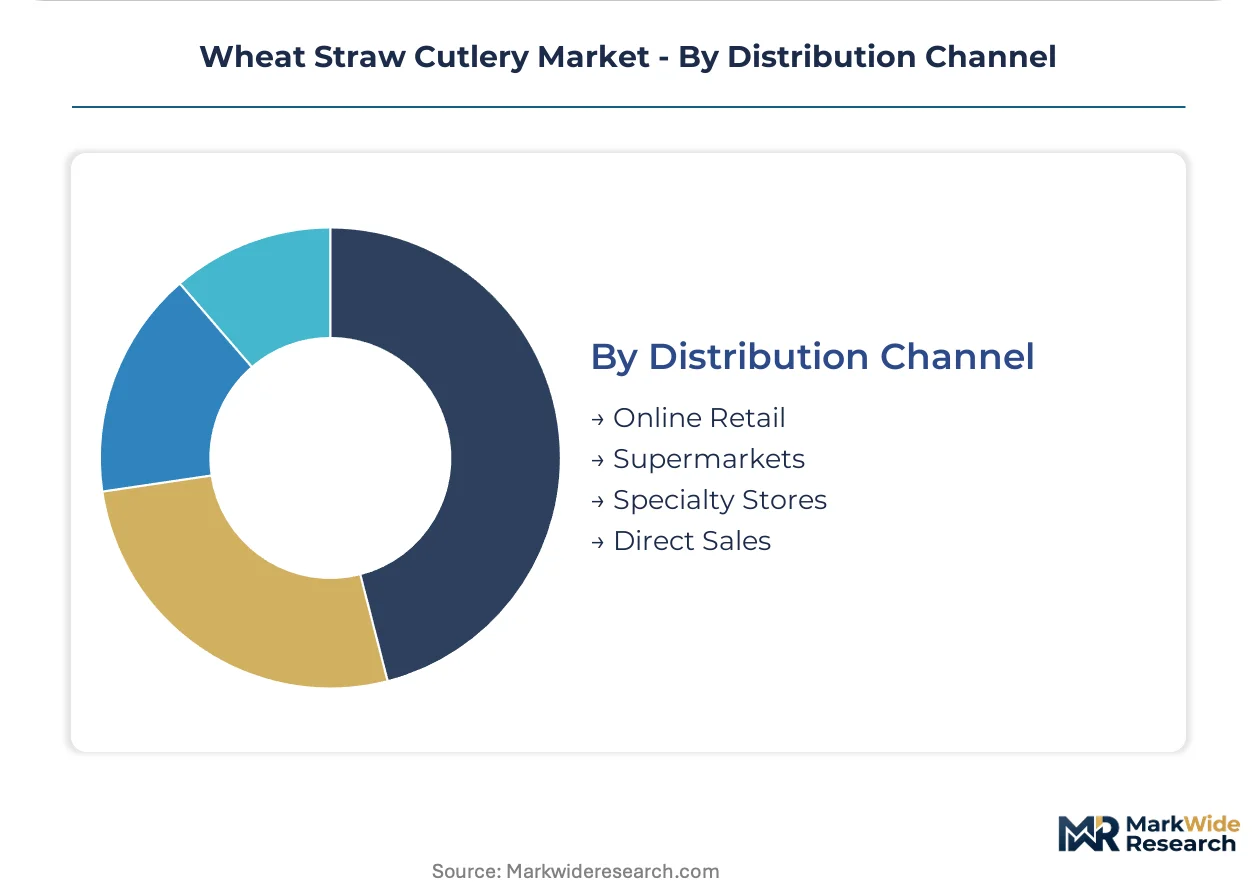
Distribution Channel:
Channel economics reflect handling requirements and shelf-life constraints distinct from petroleum-based alternatives.
- Online Retail:Direct-to-consumer platforms enable sustainability storytelling and subscription replenishment models.
- Supermarkets:Mass retail placement requires pallet-level logistics and competitive unit pricing against conventional disposables.
- Specialty Stores:Eco-focused retailers emphasize compostability certification documentation and supply chain transparency.
- Direct Sales:Foodservice distributors re-slot warehouse layouts and retrain procurement staff for compostable product categories with distinct handling requirements.
Direct sales command institutional commitment; online retail scales fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production arbitrage is redirecting manufacturing toward jurisdictions with lower compliance-documentation burdens while demand concentrates where single-use plastic bans are enforced most stringently. Wheat straw cutlery flows across this regulatory gradient, with European buyers absorbing premium-certified volumes and Asian fabricators capturing scale-driven orders.
Germany
Municipal composting infrastructure in Bavaria and North Rhine-Westphalia processes agricultural-fiber tableware at industrial scale, anchoring European demand. The country's national packaging regulator enforces extended producer responsibility schemes that mandate compostability documentation for foodservice disposables. Stuttgart-based procurement consortia coordinate bulk purchases for institutional catering networks across the southwestern manufacturing belt.
United States
Quick-service restaurant chains across the Great Plains drive thermoforming capacity utilization through direct straw-sourcing contracts with Kansas and Nebraska wheat belt processors. The USDA BioPreferred program confers federal purchasing preference on certified biobased cutlery, opening military and school nutrition procurement pathways. Chicago-area foodservice distributors are reconfiguring warehouse layouts to handle compostable product categories with distinct shelf-life requirements.
China
Shandong Peninsula and Yangtze River Delta manufacturing clusters supply export-oriented volumes to European and North American buyers seeking cost-competitive alternatives. The State Administration for Market Regulation enforces GB standards for disposable tableware safety, including heavy-metal limits in agricultural-fiber composites. Wenzhou-based fabricators are consolidating molding capacity to capture economies of scale in injection-molded utensil production.
Poland
Cooperative farm networks in the central grain belt provide captive straw supply to molders serving EU compliance markets. REACH frameworks administered by the European Chemicals Agency tighten heavy-metal thresholds in agricultural-fiber composites, forcing reformulation investments. Warsaw-area logistics hubs coordinate cross-border distribution into German and French foodservice supply chains.
India
Punjab's grain-processing corridor hosts dedicated molding facilities targeting domestic foodservice and export markets. The Food Safety and Standards Authority of India regulates food-contact materials under evolving standards for agricultural-fiber composites. Mumbai-based catering operators are piloting wheat straw cutlery for event-service contracts amid rising sustainability scrutiny from multinational corporate clients.
Wheat Straw Cutlery Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent bio-composite applications and regional certification arbitrage. The vendor base stratifies between vertically integrated agricultural processors and specialized molding operations dependent on spot-market straw procurement. Three archetypes dominate: cooperative-linked fabricators with captive fiber supply, contract manufacturers serving private-label foodservice brands, and diversified bioplastics houses cross-selling polylactic acid alternatives. Competitive dynamics center on backward integration into straw collection networks and rapid certification documentation for EN 13432 or ASTM D6400 compliance.
Among European specialists, Biotrem exemplifies the cooperative-linked archetype through its positioning within Polish agricultural supply structures. Eco-Products occupies a parallel position in North American procurement channels, anchoring volume relationships with Great Plains wheat processors. Manglam Industries represents the South Asian fabrication tier, sitting within Punjab's grain-processing corridor with proximity to raw material flows. These three entities illustrate how geographic embedding in agricultural supply zones determines cost structure and certification responsiveness.
| Leading Market Players |
|---|
| Biotrem |
| Eco-Products |
| Vegware |
| Manglam Industries |
| Shantou Europe Pack Plastic Co., Ltd. |
| Wenzhou Puqiao Arts and Crafts |
| Hubei Wheat-Straw Environmental Technology |
| GreenGood USA |
| BioGreenChoice |
| Others |
Value Network & Pricing Analysis
Molding technician clusters in Shandong and Wenzhou compress labor-cost spreads between premium EN 13432-certified cutlery and standard-grade alternatives, widening pricing-tier differentiation as European compliance documentation adds fixed overhead.
Pricing Analysis
Distributor margin absorption compresses retail markups for wheat straw cutlery, forcing manufacturers to price through direct foodservice contracts. Three-tier pricing structure across premium, standard, and economy levels separates ASTM D6400-certified volumes from uncertified commodity grades. Pricing pressure stems from grain harvest volatility squeezing straw input costs. Quick-service chains exhibit lowest price sensitivity due to sustainability procurement mandates; household retail channels show highest elasticity.
Supply Chain Analysis
Container freight rate volatility from Yangtze River Delta ports to Rotterdam and Hamburg disrupts landed-cost predictability for export-oriented molders. Supply concentrates in China, Poland, and India, with raw material flows drawing from Kansas-Nebraska wheat belts, Polish cooperative farms, and Punjab grain corridors. Binder formulations and compostability certification documentation constitute critical input dependencies. Single-source vulnerability runs through European EN 13432 testing laboratories. Distribution runs through foodservice distributors reconfiguring warehouse layouts for compostable product handling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wheat straw cutlery has shifted to a late-cycle quality story as procurement teams weight farm-to-facility traceability above unit price, favoring vertically integrated molders with documented cooperative farm contracts.
For Market Incumbents: Deploy captive straw supply arrangements to lock input cost predictability against grain harvest volatility. Biotrem's Polish cooperative farm model anchors margin stability. Invest in X-ray fluorescence screening equipment to preempt REACH heavy-metal threshold tightening. Consolidate supplier rosters around molders with dual EN 13432 and ASTM D6400 certification to capture cross-border procurement contracts.
For New Entrants and Emerging Players: The EU Single-Use Plastics Directive in Germany and France opens a window for regional certification specialists lacking legacy petroleum-plastic infrastructure. Target events and household channels where retail distribution penetration expands fastest through e-commerce sustainability messaging. Pursue USDA BioPreferred program registration to access federal institutional procurement pathways including military and school nutrition programs.
For Investors and Strategic Acquirers: Foodservice distributors are the most active acquirer in this space, seeking backward integration into compostable product categories with distinct handling requirements. Acquisition targets center on cooperative-linked molders with captive fiber supply and documented farm-to-facility traceability. The signal to monitor is EN 13432-ASTM D6400 certification reciprocity negotiations, which would eliminate cross-border product strategy fragmentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Straw Collection Networks | Captive supply from Kansas and Nebraska wheat belts stabilizes input cost volatility against grain harvest cycles. |
| Dual Certification Investment | Simultaneous EN 13432 and ASTM D6400 approval eliminates market fragmentation for cross-border suppliers. |
| Thermoforming-Injection Molding Convergence | Hybrid processes enable thinner-walled, lower-cost utensil production for high-volume quick-service restaurant procurement. |
| Events Channel Expansion | Retail distribution into consumer pantry stockpiles through e-commerce platforms captures fastest-growing demand segment. |
| X-ray Fluorescence Screening Deployment | Incoming raw material verification preempts REACH heavy-metal threshold compliance failures in European markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with foodservice procurement directors, composting facility operators, agricultural cooperative managers, and regulatory compliance officers with secondary validation against customs trade data, FDA food-contact substance filings, USDA BioPreferred program records, and EN 13432 certification registries. Bottom-up straw supply estimates and top-down foodservice disposable demand projections were triangulated to anchor volume figures.
Historical reference periods spanning pre-regulatory-ban and post-directive implementation phases anchored the forecast window across the analysis window. Segmentation dimensions modeled include product type, application channel, compostability certification tier, and regional regulatory cluster. CAGRs were derived from installed manufacturing capacity utilization trends and procurement commitment trajectories. Forecast inputs incorporated municipal composting infrastructure buildout timelines and quick-service restaurant sustainability pledge conversion rates.
Revisions become necessary when grain harvest failures, certification standard reciprocity breakdowns, or binder formulation breakthroughs materialize. Forecasts reflect documented assumptions about regulatory enforcement continuity and composting facility acceptance rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Asia-Pacific Eco-Friendly Packaging Market
Sustainable Packaging
Global Disappearing Packaging Market
Sustainable Packaging
Green Packaging Market
Sustainable Packaging
Middle East and Africa Eco-Friendly Packaging Market
Sustainable Packaging
Areca Plates Market
Sustainable Packaging
Plant Based Packaging Market
Sustainable Packaging
Japan Green Packaging Market
Sustainable Packaging
Eco-Friendly Straw Market
Sustainable Packaging
Bagasse Bowls Market
Sustainable Packaging
Sustainable Plastic Packaging Market
Sustainable Packaging
North America Eco-Friendly Packaging Market
Sustainable Packaging
Compostable Tableware Market
Sustainable Packaging
Compostable Food Trays Market
Sustainable Packaging
Eco Friendly Bottles Market
Sustainable Packaging
Zero Waste Packaging Market
Sustainable Packaging
Asia-Pacific Sustainable Packaging Market