
 Biodegradable Food Packaging Market | 2026-2036
Biodegradable Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Food Packaging Market Analysis
European biopolymer producers are pivoting capacity toward food-grade PLA and PHA resins as brand owners face compliance deadlines. BASF SE leverages its polymer science heritage to anchor technical credibility in certified compostable formulations. Huhtamaki Oyj sustains geographic dominance through its Nordic manufacturing footprint and direct supply relationships with pan-European quick-service restaurants. Novamont S.p.A. specializes in starch-based Mater-Bi compounds, occupying a defensible niche in flexible film applications where mechanical performance requirements are less severe.
Biodegradable food packaging encompasses containers, wrapping materials, trays, and bags engineered to decompose through microbial action under composting conditions, typically requiring ASTM D6400 or EN 13432 certification for disintegration within 180 days in industrial facilities. PLA and cellulose materials dominate current commercial volumes, though PHA formulations are gaining traction for their superior marine biodegradability profile and broader temperature stability. Paper-based segments lead in absolute tonnage across retail and food service channels, while seaweed and mushroom-derived substrates represent the fastest-growing innovation tier, attracting pilot-scale investment from e-commerce fulfillment operators seeking differentiated unboxing experiences. Margin pools concentrate in customized container solutions for catering and prepared meal delivery, where printability and grease resistance command price premiums over commodity bag and wrap formats.
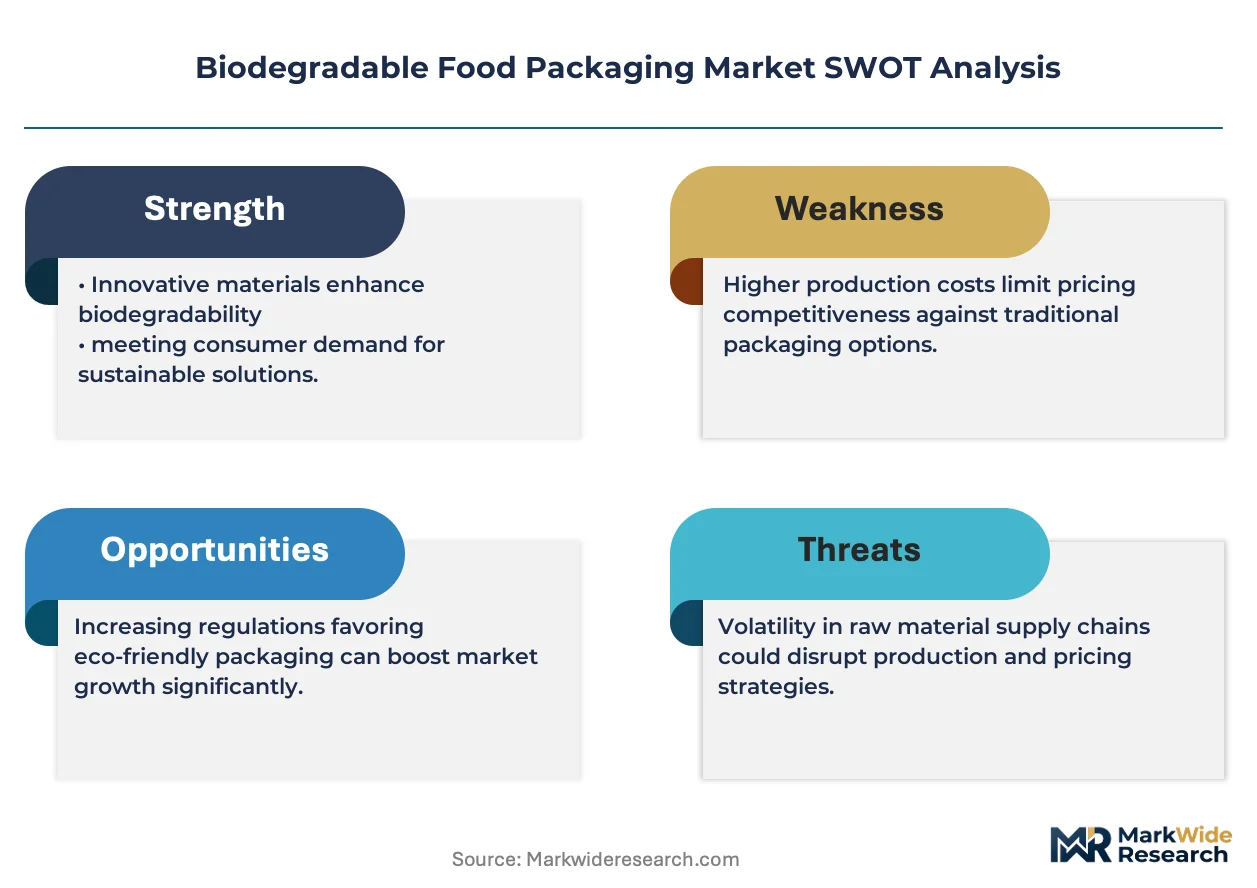
The EU F-Gas Regulation and REACH chemical restrictions shape material substitution pathways, while FDA food-contact notification requirements govern US market entry for novel biopolymer coatings. EFSA safety assessments for recycled content in food-contact applications create additional compliance layers for cellulose-based packaging sourced from post-consumer fiber streams. Stakeholders must monitor the divergence between industrial composting certification standards and actual regional processing capacity, as infrastructure gaps in key consumption clusters threaten to undermine the environmental value proposition that drives purchasing decisions.
Market Dynamics
The EU Single-Use Plastics Directive is compressing compliance timelines for brand owners, forcing immediate material substitution decisions across fresh produce retail and quick-service restaurant supply chains before certification deadlines crystallize.
Growth Catalysts
- Industrial Composting Infrastructure:Germany's centralized anaerobic digestion and composting network enables volume deployment of PLA trays and cellulose films that require controlled temperature and humidity conditions unavailable in home composting environments.
- REACH Chemical Restrictions:ECHA's tightening substance authorization lists accelerate substitution of conventional plasticizers and coatings in food-contact applications, opening formulation windows for bio-based alternatives.
- Quick-Service Restaurant Chains:Pan-European QSR procurement mandates for certified compostable packaging in takeaway applications create predictable demand baselines for tray and container manufacturers.
Market Restraints
- Lactic Acid Feedstock Volatility:PLA resin costs fluctuate with corn and sugar beet commodity markets, compressing margin stability for converters operating on fixed-price annual contracts with food brand customers.
- Industrial Composting Access Gaps:Collection and processing infrastructure remains concentrated in Northern European markets, leaving Southern and Eastern European consumption clusters without viable end-of-life pathways for certified compostable packaging.
- Temperature Performance Limitations:PLA's glass transition threshold near 60°C restricts hot-fill and microwave applications, ceding share to conventional polypropylene in ready-meal and soup packaging segments.
Strategic Opportunities
- Seaweed-Based Substrates:Marine-derived films from brown algae cultivation bypass agricultural land-use constraints and offer inherent biodegradability in marine environments where PLA persists.
- E-Commerce Fulfillment Differentiation:Direct-to-consumer meal kit operators deploy mushroom mycelium cushioning and edible coatings as unboxing experience differentiators that generate social media engagement.
- EU Green Deal Funding Windows:Horizon Europe and Innovation Fund financing for circular bioeconomy projects subsidize pilot-scale PHA fermentation capacity expansion.
Industry Challenges
- ASTM D6400 and EN 13432 Certification Timelines:Third-party laboratory testing for industrial compostability certification extends 12-18 months, delaying product launches and locking out smaller converters without dedicated compliance staff.
- Food-Contact Notification Complexity:EFSA safety assessments for novel biopolymer coatings and recycled cellulose fiber streams require extensive migration testing that strains R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Food Packaging Market |
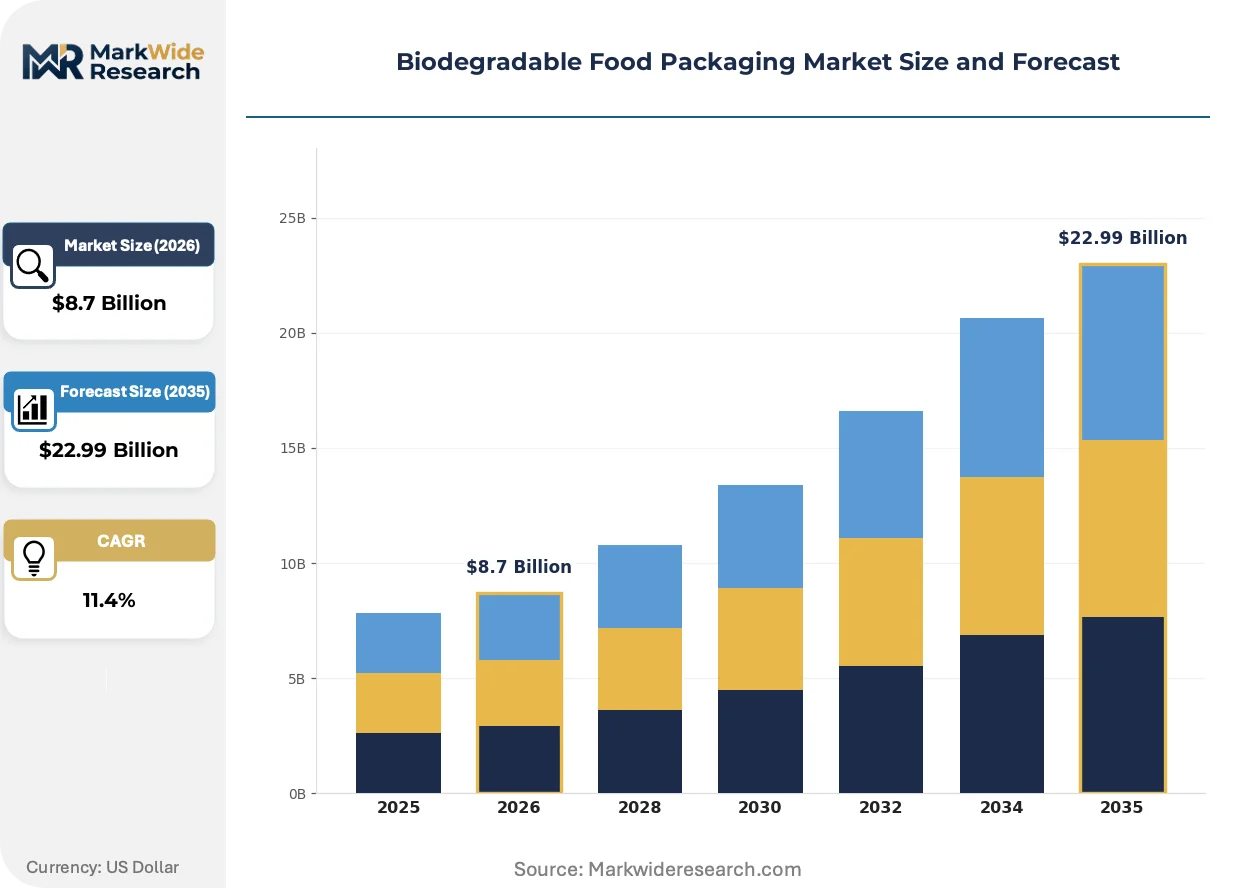
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioplastics, Paper, Mushroom, Seaweed Material: PLA, PHA, Starch-Based, Cellulose End User: Food Service, Retail, E-commerce, Catering Application: Containers, Wrapping, Trays, Bags |
| Companies Covered | Novamont S.p.A., BASF SE, Huhtamaki Oyj, Smurfit Kappa Group, Amcor plc, Mondi Group, Tetra Pak International SA, Sealed Air Corporation, International Paper Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Food Packaging Market Emerging Trajectories
Material science breakthroughs and enforcement tightening on single-use plastics are converging to reshape competitive positioning in food-contact applications, with performance gaps between bio-based and conventional polymers narrowing faster than projected.
Active barrier coatings derived from chitosan and lignin derivatives are electrifying shelf-life extension for fresh produce packaging, enabling breathable films that match ethylene scavenging performance of synthetic alternatives. German and Dutch supermarket chains are piloting these formats for berry and leafy green applications at scale. The technology is compressing the historical trade-off between compostability and functional performance that has constrained adoption in high-respiration produce categories.
REACH authorization procedures for persistent organic pollutants and phthalate plasticizers are tightening material substitution pathways for food-contact films, with ECHA's 2024-2025 restriction roadmap targeting specific polymer additives used in conventional flexible packaging. Converters serving ready-meal and dairy segments face reformulation mandates that favor bio-based plasticizers and slip agents. The regulatory pressure is most acute in France and Belgium, where national implementation exceeds minimum EU harmonization requirements.
Brand-owner sustainability scorecards now weight end-of-life verification more heavily than recycled content claims, with procurement teams demanding proof of industrial composting access within 50 kilometers of primary consumption points. This behavioral shift favors regional converters with established relationships to municipal waste operators over distant low-cost suppliers. The Netherlands and Denmark exhibit the most pronounced procurement pattern evolution, with centralized purchasing consortia consolidating volumes around certified compostable specifications.
Biodegradable Food Packaging Market Segmentation
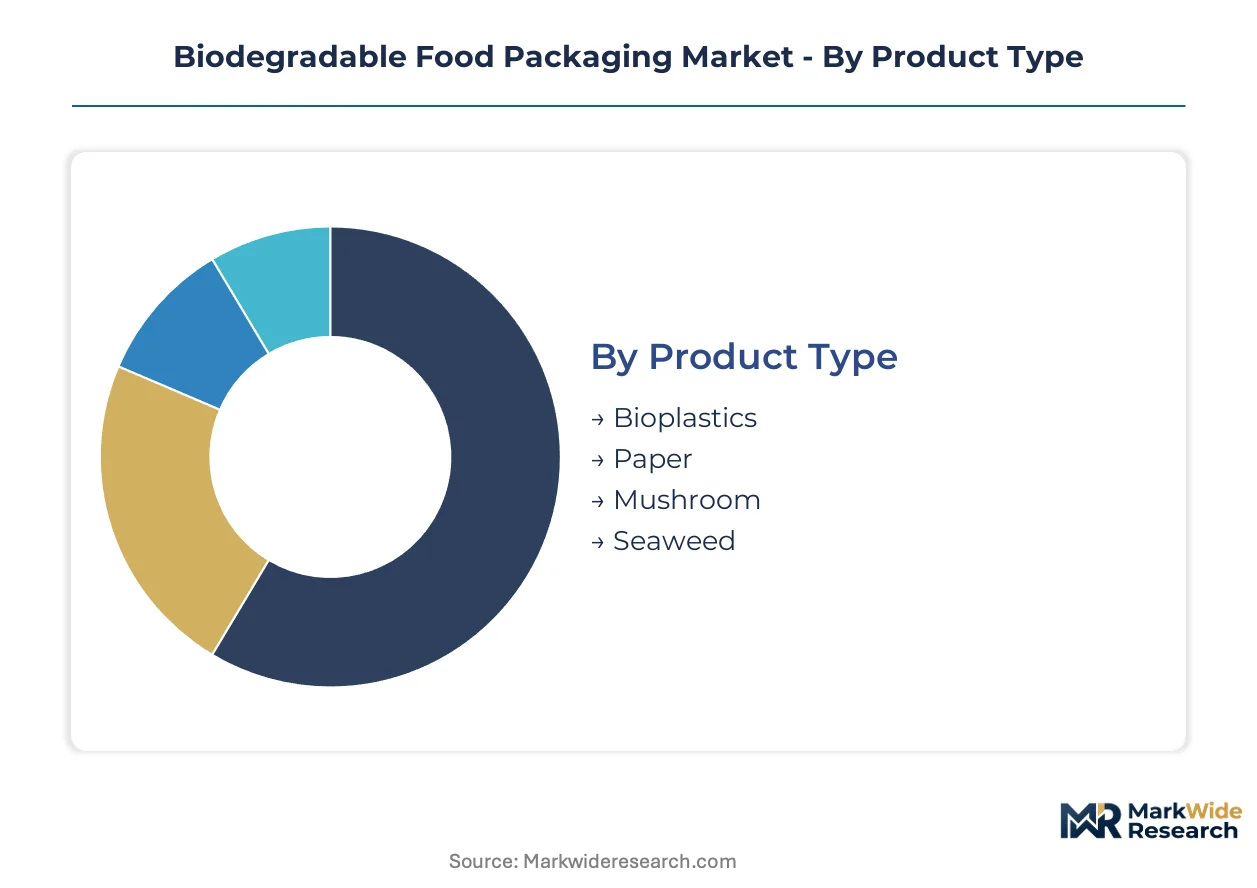
Segmentation in biodegradable food packaging reveals how certification requirements, performance specifications, and end-of-life infrastructure shape material selection across customer categories. Understanding these divides enables suppliers to align formulation investments with addressable demand pools.
Product Type:
ASTM D6400 and EN 13432 certification timelines vary substantially across product categories, with films requiring more extensive migration testing than rigid formats and novel substrates facing extended EFSA safety assessments.
- Bioplastics:PLA and PHA resins dominate tonnage in thermoformed trays and cutlery, with German quick-service restaurant chains specifying certified compostable grades for takeaway containers. REACH chemical restrictions on conventional plasticizers accelerate substitution toward bio-based alternatives in flexible film applications.
- Paper:Cellulose-based formats lead absolute volume across retail grocery and food service channels, leveraging existing recycling infrastructure while meeting grease-resistance requirements through bio-based coatings. EFSA assessments for post-consumer fiber content in food-contact applications create compliance complexity for recycled-content claims.
- Mushroom:Mycelium-derived cushioning targets e-commerce meal kit fulfillment as an unboxing differentiator, bypassing agricultural land-use constraints through controlled cultivation on agricultural waste substrates.
- Seaweed:Marine-derived films from brown algae cultivation offer inherent biodegradability in ocean environments where PLA persists, attracting pilot investment from coastal European markets with marine plastic pollution mandates.
Paper sits at the top of the volume ranking, with seaweed climbing the fastest.
Material:
Cost tiers stratify sharply across resin categories, with fermentation-based PHA commanding premium pricing over corn-derived PLA and starch compounds occupying the economy tier for less demanding applications.
- PLA:Thermoplastic polyester from lactic acid polymerization dominates tray and rigid container production, though its 60°C glass transition temperature restricts hot-fill applications. German industrial composting infrastructure supports volume deployment where controlled temperature and humidity conditions are guaranteed.
- PHA:Microbial polyester production delivers superior marine biodegradability and broader temperature stability than PLA, with EU Green Deal funding windows subsidizing fermentation capacity expansion for food-contact grades.
- Starch-Based:Mater-Bi compounds occupy flexible film niches where mechanical performance requirements are less severe, competing on cost against conventional polyethylene in produce bag applications.
- Cellulose:Regenerated wood pulp substrates leverage existing paper industry infrastructure, with active barrier coatings from chitosan and lignin derivatives enabling shelf-life extension for high-respiration produce.
PLA holds the largest installed base, with PHA gaining share fastest.
End User:
Procurement sophistication varies dramatically across customer types, with pan-European quick-service restaurant chains imposing standardized compostable specifications while fragmented food service operators prioritize unit economics over certification compliance.
- Food Service:Takeaway and fast-casual operators drive container and cutlery demand, with centralized purchasing consortia in the Netherlands and Denmark consolidating volumes around certified compostable mandates.
- Retail:Supermarket chains pilot active barrier films for berry and leafy green applications, with Dutch and German banners leading adoption of breathable compostable formats.
- E-commerce:Direct-to-consumer meal kit operators deploy mushroom mycelium cushioning and edible coatings as social media engagement tools, prioritizing unboxing experience over cost minimization.
- Catering:Event and institutional food service demands customized printability and grease resistance, commanding price premiums over commodity formats through specification differentiation.
Food Service anchors current volumes, with E-commerce expanding most quickly.
Application:
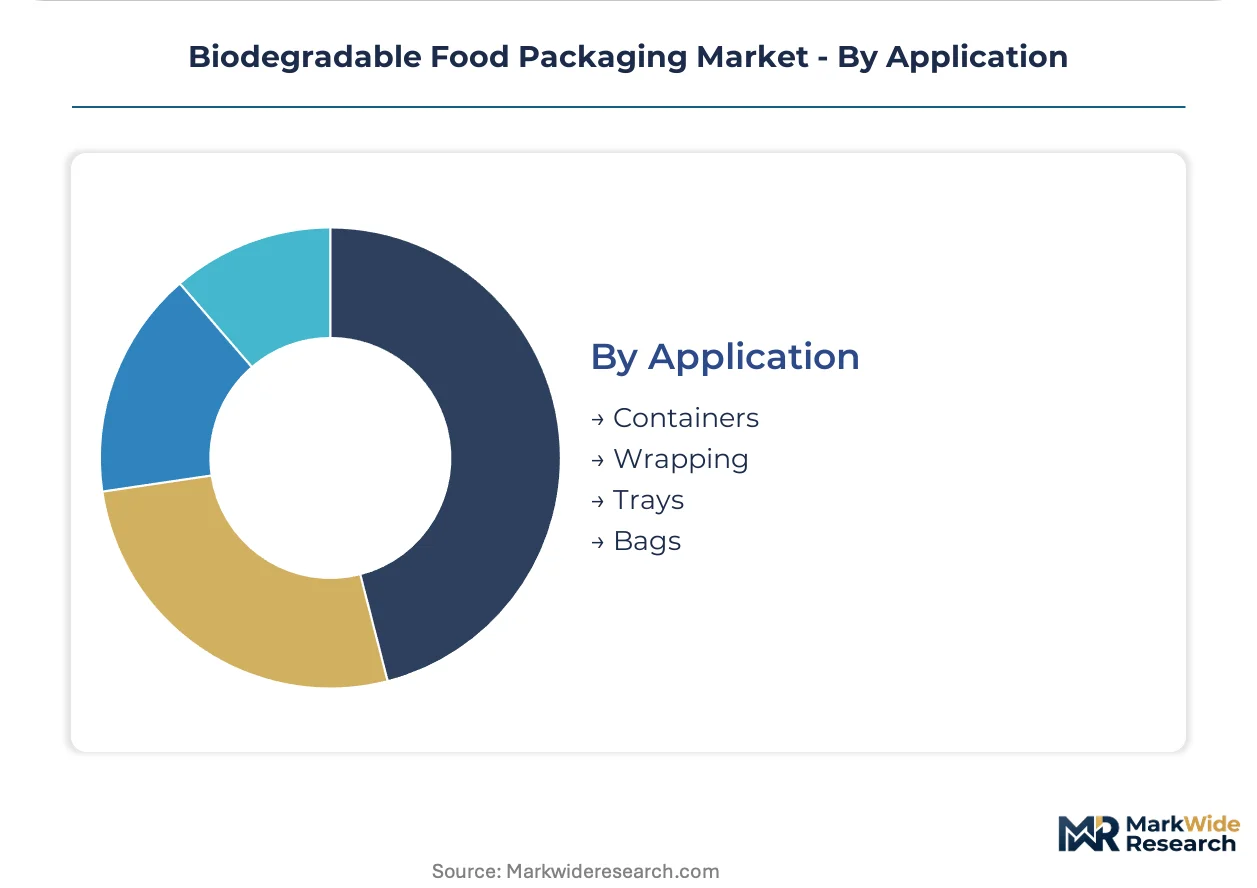
Margin pools concentrate in formats requiring functional performance beyond basic containment, with grease resistance, printability, and temperature stability driving specification premiums.
- Containers:Thermoformed PLA and molded fiber formats serve ready-meal and soup applications, though temperature limitations cede hot-fill share to conventional polypropylene.
- Wrapping:Flexible films for sandwich and bakery applications face reformulation pressure from REACH restrictions on phthalate plasticizers, favoring bio-based slip agents.
- Trays:Produce retail chains across Western Europe accelerate compostable tray adoption, with centralized industrial composting infrastructure in Germany enabling volume deployment.
- Bags:Carryout and produce bag applications represent the most price-sensitive segment, with starch-based compounds competing against recycled polyethylene where composting access is limited.
Trays lead in value concentration, with containers showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate capacity toward jurisdictions with established industrial composting infrastructure and harmonized certification frameworks, compressing cost-of-compliance gaps between Northern and Southern European markets.
Germany
Centralized anaerobic digestion networks in Bavaria and North Rhine-Westphalia enable volume deployment of PLA trays and cellulose films. The country's packaging ordinance implements stricter sorting requirements than baseline EU mandates. Berlin-Brandenburg clusters host pilot-scale PHA fermentation facilities subsidized through EU Green Deal windows.
France
Quick-service restaurant procurement mandates drive container demand across Paris-Île-de-France and Lyon-Auvergne-Rhône-Alpes corridors. ANSM enforces national implementation of REACH restrictions that exceed minimum EU harmonization thresholds. Provençal agricultural cooperatives pilot seaweed-based films for regional produce distribution.
Netherlands
Randstad purchasing consortia consolidate food service volumes around certified compostable specifications. The country's extended producer responsibility framework mandates higher recycling targets for packaging waste. Rotterdam port logistics clusters support import processing of bio-based resin feedstocks.
Italy
Fresh produce retail chains in Lombardy and Emilia-Romagna accelerate adoption of breathable compostable films for berry applications. EFSA safety assessments for recycled cellulose content create compliance complexity for converters sourcing post-consumer fiber. Novara-based starch compound specialists supply Mater-Bi formulations to flexible film processors.
United Kingdom
London-Southeast food service operators face post-Brexit divergence from EU compostability certification standards. The Environment Agency's packaging waste regulations create separate compliance pathways for industrial compostable claims. Midlands manufacturing clusters adapt thermoforming capacity to serve both domestic and residual EU export demand.
Biodegradable Food Packaging Market Vendor Landscape
European producers anchor the formulation tier through polymer science heritage and established certification relationships; Asian converters hold cost-driven volume positions in commodity bag and wrap formats. Market structure tilts toward consolidated leadership in resin supply alongside fragmented competition among downstream converters. Three archetypes dominate: integrated chemical conglomerates with captive biopolymer capacity, specialized packaging converters with direct QSR supply relationships, and niche substrate innovators in marine-derived materials. Capacity expansion and strategic partnerships represent the dominant competitive vectors as players secure feedstock access and composting infrastructure alliances.
Within the integrated chemical tier, BASF SE and Novamont S.p.A. exemplify divergent strategic postures—BASF anchoring technical credibility through polymer science heritage while Novamont occupies a defensible niche in starch-based flexible film applications. Huhtamaki Oyj represents the packaging converter archetype, sustaining geographic proximity advantages through Nordic manufacturing footprints and direct procurement relationships with pan-European food service operators. These three entities illustrate how competitive positioning stratifies across formulation expertise, manufacturing scale, and customer access dimensions rather than converging on a single winning model.
| Leading Market Players |
|---|
| Novamont S.p.A. |
| BASF SE |
| Huhtamaki Oyj |
| Smurfit Kappa Group |
| Amcor plc |
| Mondi Group |
| Tetra Pak International SA |
| Sealed Air Corporation |
| International Paper Company |
| Others |
Supply Flow & Price Mechanics
Pan-European quick-service restaurant chains concentrate procurement volumes for certified compostable packaging, compressing supplier margins through centralized purchasing consortia while rewarding converters with dedicated composting infrastructure partnerships.
Pricing Analysis
Retailer markup layers dominate the channel-margin structure, with Dutch and German supermarket banners capturing differential value from active barrier film formats. Pricing stratifies across premium certified grades, standard industrial compostable tiers, and economy starch-based compounds. Cost compression in the economy tier intensifies because agricultural feedstock volatility transmits directly to PLA resin contracts. Food service operators exhibit the highest price sensitivity, while e-commerce meal kit brands prioritize unboxing differentiation over unit economics.
Supply Chain Analysis
Certification gating through ASTM D6400 and EN 13432 timelines restricts supplier qualification, elongating onboarding cycles for novel biopolymer converters. Manufacturing concentrates in Germany, Italy, and the Netherlands, with Bavarian anaerobic digestion networks and Novara starch compounding facilities anchoring regional supply. Raw material dependencies on corn-derived lactic acid, wood pulp cellulose, and agricultural waste substrates for mycelium cultivation create feedstock risk. Single-source vulnerability persists for marine-derived seaweed substrates cultivated in limited coastal zones. Distribution runs through pan-European logistics clusters at Rotterdam and Hamburg port facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biodegradable food packaging market compounds steadily as regulatory enforcement timelines for single-use plastics substitution create predictable demand baselines across food service and retail channels.
For Market Incumbents: Anticipate margin compression from Asian converters entering commodity bag segments by securing backward integration into lactic acid fermentation capacity and expanding PHA pilot facilities in Berlin-Brandenburg clusters. Reinforce certification relationships with EFSA and municipal composting operators to maintain technical credibility barriers against emerging substrate innovators. For New Entrants and Emerging Players: The gap between premium PHA pricing and economy starch-based tiers offers white-space positioning for mid-market PLA converters serving quick-service restaurant chains with regional composting access. Target Southern European markets where industrial composting infrastructure gaps have delayed incumbent penetration. Pursue direct supply relationships with coastal supermarket banners piloting seaweed-based films for produce applications. For Investors and Strategic Acquirers: Packaging conglomerates with food service channel control represent the most active acquirer category in this space, seeking formulation expertise to complement existing manufacturing footprints. Five-to-ten-year viability hinges on divergence between certification standard adoption and actual regional processing capacity expansion. Monitor municipal composting infrastructure investment announcements in Italy and Spain as inflection indicators for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | ASTM D6400 and EN 13432 accreditation unlocks QSR procurement mandates in Germany and the Netherlands. |
| Feedstock Backward Integration | In-house lactic acid production insulates PLA converters from corn commodity volatility. |
| Composting Infrastructure Partnership | Alliances with Bavarian anaerobic digestion operators secure end-of-life pathway guarantees for brand customers. |
| Active Barrier Coating Development | Chitosan and lignin derivative formulations capture shelf-life extension premiums from Dutch berry retailers. |
| Marine Substrate Scale-Up | Brown algae cultivation expansion addresses PLA's marine persistence limitations for coastal European markets. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biopolymer R&D directors, QSR procurement leads, municipal waste operators, and flexible film converters with secondary validation against EFSA safety assessments, EU Green Deal funding disclosures, and customs trade data for bio-based resin imports. Bottom-up volume estimates from individual facility capacities and top-down demand modeling from end-use consumption patterns were cross-referenced for triangulation.
Segment-weighting approaches distributed value across product type, material chemistry, end-user category, and application format dimensions. CAGRs were derived from fitted growth curves calibrated to regulatory deadline impacts and infrastructure deployment timelines. Forecast inputs incorporated industrial composting facility capacity expansion schedules and REACH restriction roadmap implementation phases.
Caveats apply where EFSA novel food-contact assessments or municipal composting access gaps could materially shift the outlook. A model refresh is warranted upon material change in EU Single-Use Plastics Directive enforcement intensity or PHA fermentation capacity commissioning announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Global Bioplastic Multi-Layer Films Market
Biodegradable Packaging
Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Compostable Shrink Wrap Market
Biodegradable Packaging
Biodegradable Plastic Packaging Market
Biodegradable Packaging
Biodegradable Packaging Products Market
Biodegradable Packaging
Biofoam Packaging Market
Biodegradable Packaging
Biodegradable Plastic Bags and Sacks Market
Biodegradable Packaging
India Biodegradable Tableware & Packaging Products Market
Biodegradable Packaging
Global Biodegradable Films Market
Biodegradable Packaging
Biodegradable Cups Market
Biodegradable Packaging
Biodegradable Packing Peanuts Market
Biodegradable Packaging
Europe Biodegradable Cups Market
Biodegradable Packaging
Biopolymer Packaging Market
Biodegradable Packaging
North America Biodegradable Film Market
Biodegradable Packaging
Asia-Pacific Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Middle East and Africa Biodegradable Film Market