
 Automatic Thermoforming Vacuum Machine Market | 2026-2036
Automatic Thermoforming Vacuum Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Thermoforming Vacuum Machine Market Outlook
Remote diagnostics and predictive maintenance subscriptions is realigning how automatic thermoforming vacuum machine vendors capture lifetime value. Multivac leverages its global service network to anchor recurring revenue streams alongside hardware sales. Kiefel Technologies specializes in medical-grade thermoforming systems that sustain premium positioning through validated process control.
An automatic thermoforming vacuum machine heats thermoplastic sheet material—typically PET, PVC, or polystyrene—to a pliable forming temperature, then applies vacuum pressure to draw the material over a mold cavity, producing rigid trays, blisters, or clamshells with wall thicknesses ranging from 0.2 to 2.0 millimeters for protective packaging and sterile barrier applications. Continuous roll-fed systems dominate high-volume food packaging lines where throughput exceeds 120 cycles per minute, while batch configurations retain structural margin pools in medical device cleanroom environments requiring lot traceability and validated changeover protocols. Plug assist technology variants are displacing basic vacuum-only architectures in electronics anti-static tray applications where dimensional repeatability below 0.1 millimeter prevents component damage.
Germany's KBA enforces machinery safety standards under the Machinery Directive that constrain pneumatic heating system designs, while FDA 21 CFR Part 820 quality system regulations for medical device packaging compel validated installation qualification and operational qualification documentation from thermoforming equipment suppliers. China's GB standards for food contact materials, administered by SAMR, restrict PVC migration limits in direct-food applications and redirect material preferences toward PET and aluminum laminate structures. Stakeholders must monitor how heating technology electrification intersects with evolving energy efficiency certification schemes to determine capital allocation between hybrid and fully electric platform development.
Market Dynamics
Electric heating retrofits are compressing pneumatic system margins as EU F-Gas Regulation phase-downs force capital reallocation across European installed bases, while Bavaria's packaging machinery cluster and Guangdong's consumer goods corridor concentrate demand-pull signals.
Growth Catalysts
- EU F-Gas Regulation phase-down:Germany's KBA enforces machinery safety standards that accelerate electric heating adoption over pneumatic systems in food packaging lines.
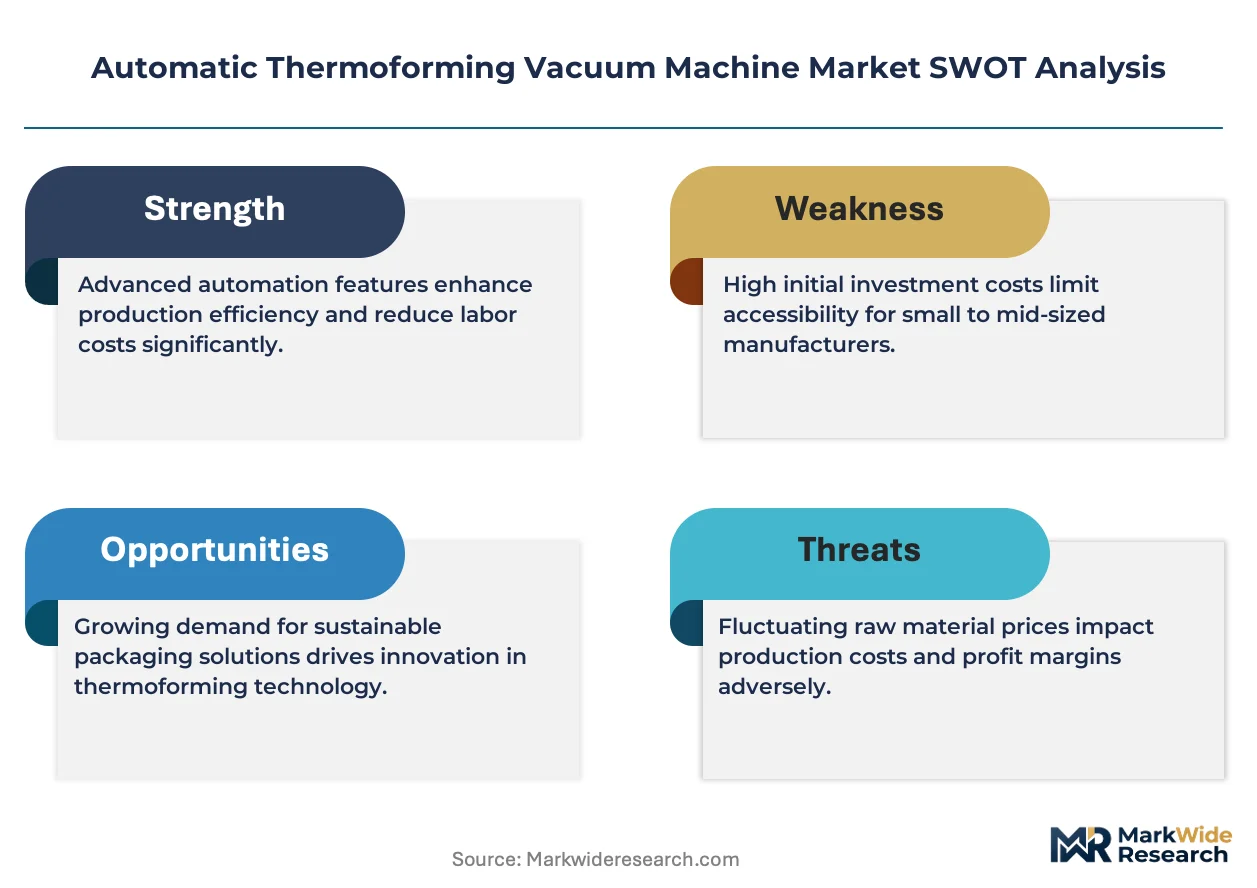
- Chilled ready-meal segments:Food packaging manufacturers in Germany and China are expanding thermoformed tray capacity to capture shelf-life extension demand.
- Plug assist technology:Electronics anti-static tray applications require dimensional repeatability below 0.1 millimeter, displacing basic vacuum-only architectures.
Market Restraints
- Aluminum laminate material costs:China's GB standards restrict PVC migration limits, redirecting preferences toward PET and aluminum laminate structures with volatile input pricing.
- Cleanroom validation timelines:FDA 21 CFR Part 820 quality system regulations for medical device packaging compel validated IQ/OQ documentation that extends sales cycles.
- Batch configuration capex intensity:Medical device cleanroom environments requiring lot traceability sustain premium equipment costs that constrain mid-tier buyer entry.
Strategic Opportunities
- Remote diagnostics subscriptions:Predictive maintenance revenue streams realign vendor lifetime value capture beyond hardware sales in established European bases.
- Medical-grade validated process control:Sterile barrier applications sustain premium positioning through equipment-software integration in North American hospital supply chains.
- Guangdong consumer goods corridor:Underpenetrated mid-tier food processors present retrofit demand for continuous roll-fed systems above 120 cycles per minute.
Industry Challenges
- Electrification skill gaps:Hybrid and fully electric platform development requires thermal engineering expertise scarce in legacy pneumatic service networks.
- Legacy system integration friction:Validated changeover protocols in medical cleanrooms complicate retrofit timelines when interfacing with existing track-and-trace infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Thermoforming Vacuum Machine Market |
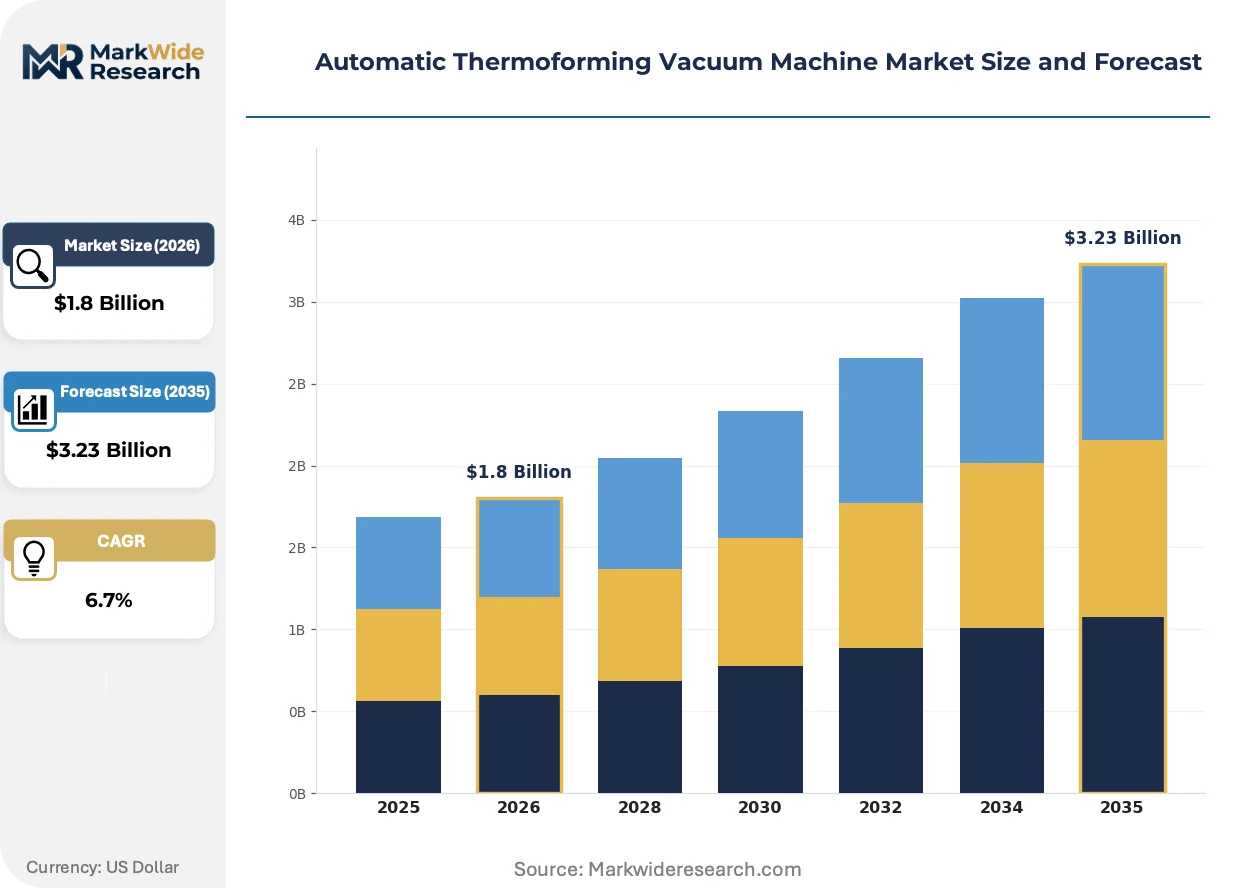
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous, Batch, Plug Assist, Roll-Fed Material: Plastic, Aluminum, PVC, PET End User: Food Packaging, Medical Devices, Consumer Goods, Electronics Technology: Heating, Electrical, Pneumatic, Hybrid |
| Companies Covered | Gabler Thermoform, GEA, Multivac, ULMA Packaging, Weber Maschinenbau, Illig Maschinenbau, TZ Machinery, Brown Machine Group, Kiefel Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Thermoforming Vacuum Machine Market Strategic Shifts
Heating technology electrification is intersecting with predictive service models to reconfigure how value flows between equipment vendors and packaging converters across food and medical end-uses.
Electric heating elements with zone-controlled temperature profiling are absorbing thermal management functions previously handled by compressed air systems. Medical device packaging lines in FDA-regulated environments are adopting these systems fastest, with sterile barrier manufacturers prioritizing process validation documentation over cycle speed. This absorption is compressing pneumatic component supplier margins while elevating electrical engineering content in vendor R&D budgets.
The EU F-Gas Regulation mandates progressive hydrofluorocarbon phase-downs that eliminate high-global-warming-potential refrigerants from industrial heating applications. Machinery OEMs in Germany must redesign thermal systems to comply with KBA-enforced Machinery Directive safety standards concurrent with refrigerant transitions. Food packaging manufacturers in Bavaria are responding by accelerating capital plans for fully electric platforms ahead of regulatory deadlines.
Converters are unbundling after-sales service from equipment purchase contracts, subscribing to remote diagnostics rather than accepting bundled maintenance terms. Medical device packaging cleanrooms in North America are driving this shift, with validated uptime guarantees replacing transactional spare parts procurement. Guangdong's consumer goods manufacturers are replicating the model, pressuring local distributors to deploy predictive analytics capabilities or lose multi-year service agreements.
Automatic Thermoforming Vacuum Machine Market Segmentation
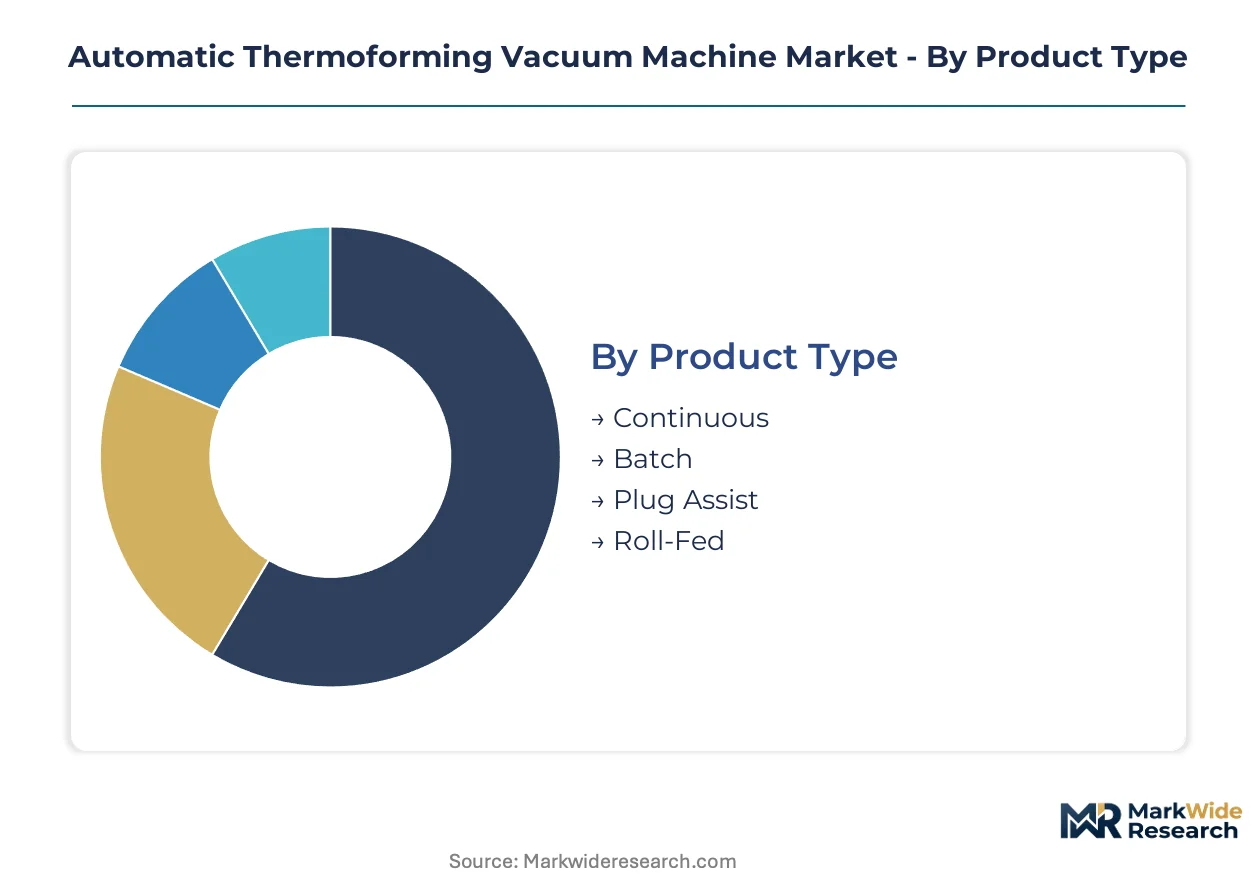
Segmentation in automatic thermoforming vacuum machines reveals how buyer priorities diverge between throughput-maximizing food processors and validation-driven medical device manufacturers. Equipment specifications, material compatibility, and regulatory compliance requirements create distinct procurement pathways that vendors must navigate separately.
Product Type:
Buyers choose between continuous and batch architectures based on lot traceability requirements versus cycle speed economics.
- Continuous:Roll-fed systems sustain cycle rates exceeding 120 per minute for high-volume food packaging lines. Demand concentrates in Germany's chilled ready-meal segment where shelf-life extension drives capital expansion.
- Batch:Validated changeover protocols support medical device cleanrooms requiring lot traceability. Bavaria's sterile barrier manufacturers absorb premium equipment costs to maintain FDA 21 CFR Part 820 compliance.
- Plug Assist:Delivers dimensional repeatability below 0.1 millimeter for electronics anti-static trays. Guangdong's consumer goods corridor drives displacement of basic vacuum-only architectures.
- Roll-Fed:Integrates material feeding with forming stations for uninterrupted production. China's food packaging manufacturers favor this configuration for PET tray expansion.
Volume sits with Continuous systems; growth tilts toward Plug Assist as electronics precision requirements harden.
Material:
Material selection tracks regulatory migration limits and end-use performance specifications across food contact and sterile barrier applications.
- Plastic:Polystyrene and polypropylene dominate cost-sensitive consumer goods packaging. China's SAMR-administered GB standards redirect preferences away from restricted compositions.
- Aluminum:Laminate structures absorb thermal management functions in retort-ready meal applications. Volatile input pricing constrains mid-tier processor adoption.
- PVC:Migration limit restrictions under China's GB standards compress direct-food application share. Medical device blister packs retain limited sterile barrier use.
- PET:Barrier properties and recyclability sustain premium positioning in European food packaging. Germany's packaging machinery cluster drives electric-heated PET line retrofits.
Procurement weight rests with PET; aluminum laminate climbs fastest as retort meal segments expand.
End User:
End-use segmentation separates regulated medical environments from speed-driven food and electronics applications.
- Food Packaging:Chilled ready-meal manufacturers in Germany and China expand thermoformed tray capacity. EU F-Gas Regulation phase-downs accelerate electric heating adoption over pneumatic systems.
- Medical Devices:Sterile barrier manufacturers require validated IQ/OQ documentation per FDA 21 CFR Part 820. North American hospital supply chains sustain premium equipment-software integration demand.
- Consumer Goods:Guangdong's manufacturing corridor presents underpenetrated mid-tier retrofit opportunity. Predictive maintenance subscriptions realign vendor lifetime value capture.
- Electronics:Anti-static tray applications demand plug assist precision below 0.1 millimeter. Component damage prevention justifies technology upgrade premiums.
Food Packaging absorbs installed base volume; Medical Devices delivers margin expansion through validation services.
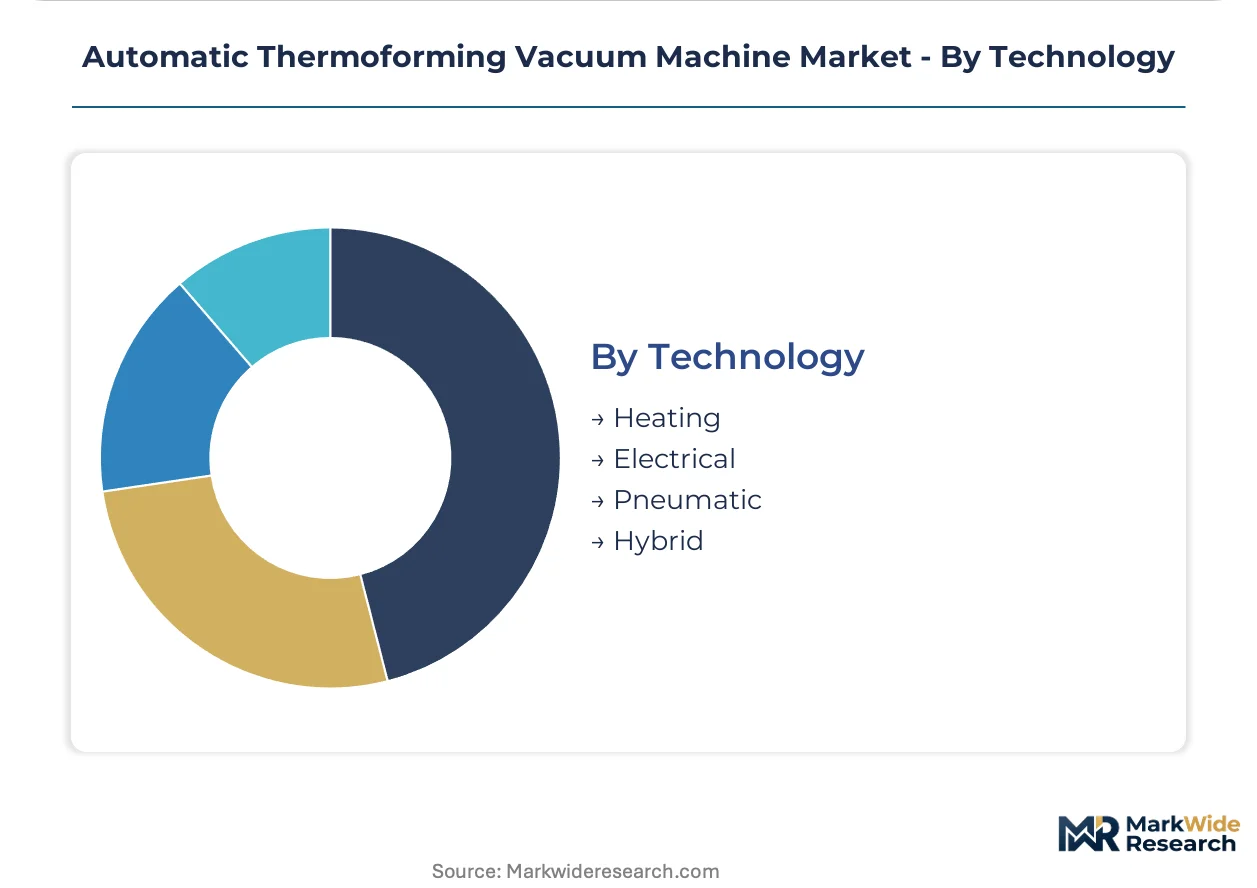
Technology:
Technology architecture determines energy efficiency compliance pathways and service network retraining requirements.
- Heating:Zone-controlled temperature profiling absorbs thermal management from compressed air systems. Medical device packaging lines in FDA-regulated environments adopt these systems fastest.
- Electrical:Fully electric platforms align with EU F-Gas Regulation hydrofluorocarbon phase-down mandates. Germany's KBA-enforced Machinery Directive safety standards constrain design alternatives.
- Pneumatic:Legacy installed base faces margin compression as refrigerant transitions force capital reallocation. Service network electrification skill gaps complicate maintenance revenue retention.
- Hybrid:Bridges thermal engineering expertise scarcity in legacy pneumatic service networks. Bavaria's packaging machinery cluster evaluates intermediate retrofit pathways.
Electrical systems capture regulatory-driven replacement; Hybrid configurations serve transition-bound installed bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures the majority of high-precision thermoforming equipment while China absorbs the largest share of installed capacity expansion. This production-consumption divide shapes capital flows and technology transfer patterns across the forecast window.
Germany
Bavaria's packaging machinery cluster drives chilled ready-meal tray capacity expansion for export markets. The KBA enforces Machinery Directive safety standards that accelerate electric heating retrofits over legacy pneumatic systems. Stuttgart-based fabricators concentrate medical-grade system development for sterile barrier applications.
China
Guangdong's consumer goods manufacturing corridor generates demand-pull signals for continuous roll-fed systems above 120 cycles per minute. SAMR-administered GB standards restrict PVC migration limits in direct-food applications, redirecting material preferences toward PET structures. Shanghai processors are expanding thermoformed tray capacity to serve domestic chilled ready-meal segments.
United States
FDA 21 CFR Part 820 quality system regulations compel validated IQ/OQ documentation from equipment suppliers serving medical device packaging lines. Midwest food processors drive demand for shelf-life extension packaging in frozen and refrigerated segments. California's electronics manufacturers require plug assist precision below 0.1 millimeter for anti-static tray applications.
Japan
METI energy efficiency certification schemes intersect with heating technology electrification to determine capital allocation between hybrid and fully electric platforms. Osaka-based packaging converters prioritize process validation documentation over cycle speed in pharmaceutical blister pack applications. Chubu region machinery builders supply precision forming systems to domestic electronics component manufacturers.
Italy
Emilia-Romagna's food packaging machinery district specializes in mid-tier continuous systems for European export markets. CE marking requirements under EU F-Gas Regulation phase-downs force refrigerant transitions in thermal system designs. Lombardy processors are retrofitting pneumatic heating lines with zone-controlled electric elements to maintain access to German buyer networks.
Automatic Thermoforming Vacuum Machine Market Competitive Environment
Top-tier vendors anchor premium positioning through validated process control and service network scale, while mid-tier fabricators compete on retrofit cost efficiency and regional proximity. The vendor base stratifies across three tiers: multinational systems integrators with global service footprints, regional specialists concentrating on specific end-use verticals, and emerging Asian manufacturers capturing mid-volume food packaging demand. Two dominant competitive moves are reshaping positioning: predictive maintenance subscription unbundling from hardware sales, and electric heating platform development to capture EU regulatory-driven replacement cycles.
Among Germany-based machinery builders, Multivac GmbH and Illig Maschinenbau GmbH & Co. KG exemplify the premium-tier archetype through equipment-software integration capabilities. Kiefel Technologies GmbH occupies a position within the medical-grade specialization vector. Brown Machine Group represents North American scale-driven fabrication, while TZ Machinery Co., Ltd. anchors the Asia-Pacific cost-optimized tier. These named entities illustrate how competitive positioning fragments across technology sophistication, regulatory compliance depth, and geographic service density rather than converging on a single performance dimension.
| Leading Market Players |
|---|
| Gabler Thermoform |
| GEA |
| Multivac |
| ULMA Packaging |
| Weber Maschinenbau |
| Illig Maschinenbau |
| TZ Machinery |
| Brown Machine Group |
| Kiefel Technologies |
| Others |
Value Chain & Pricing Dynamics
Chilled ready-meal manufacturers in Germany and Guangdong's consumer goods corridor concentrate procurement volume, anchoring contract-based long-term equipment offtake as the dominant pricing model for automatic thermoforming vacuum machines.
Pricing Analysis
Margin tightening in mid-tier continuous systems traces to aluminum laminate material cost volatility and electric heating retrofit premiums. Three-tier pricing structure across premium validated medical-grade, standard food packaging, and economy retrofit configurations separates buyers by certification level and after-sales service bundling. Cost-down pressure on pneumatic legacy lines accelerates because EU F-Gas Regulation phase-downs compress residual value. Mid-tier food processors in China exhibit highest price sensitivity; sterile barrier manufacturers in North America absorb premium positioning through equipment-software integration.
Supply Chain Analysis
Refurbishment flows from Bavaria's packaging machinery cluster and Stuttgart-based fabricators extend equipment lifecycle, feeding secondary market channels in Eastern European food processing. Component manufacturing draws from Germany, China, and Japan for precision forming stations, zone-controlled heating elements, and vacuum pump assemblies. Single-source vulnerability concentrates in high-grade aluminum laminate supply for retort-ready applications. Distribution runs through OEM-direct sales for medical-grade systems and regional distributor networks for mid-tier food packaging lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automatic thermoforming vacuum machine vendors face consolidation pressure as electric heating electrification eliminates pneumatic service network viability, forcing weaker players toward acquisition or exit.
For Market Incumbents: Anchor recurring revenue through predictive maintenance subscription unbundling from hardware sales, defending against emerging Asian cost-optimized manufacturers capturing Guangdong mid-tier retrofit demand. Deepen vertical integration into zone-controlled heating element production to secure margin pools compressed by aluminum laminate input volatility. For New Entrants and Emerging Players: Direct-to-converter digital sales channels bypass established distributor networks in underpenetrated Eastern European food processing markets. Target batch configuration medical device packaging lines in North America where FDA 21 CFR Part 820 validation documentation requirements sustain premium entry barriers against commodity competition. For Investors and Strategic Acquirers: The window for entry favors electric heating platform specialists with validated process control software stacks. Long-term viability hinges on service network density in EU-regulated environments. Monitor EU F-Gas Regulation enforcement acceleration as inflection signal for pneumatic asset write-down velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Heating Platform Development | Captures EU F-Gas Regulation-driven replacement cycles in Bavaria's packaging cluster. |
| Predictive Maintenance Subscription Launch | Realigns vendor lifetime value capture beyond transactional hardware sales in established bases. |
| Medical-Grade Validation Documentation Investment | Sustains premium positioning through FDA 21 CFR Part 820 compliance depth. |
| Guangdong Distribution Channel Expansion | Accesses underpenetrated mid-tier food processor retrofit demand above 120 cycles per minute. |
| Heating Element Backward Integration | Secures margin control over zone-controlled thermal systems displacing pneumatic architectures. |
Study Parameters
Independent corroboration across packaging machinery OEMs, food processing plant engineers, and medical device sterile barrier manufacturers underwrites the qualitative findings in this study. Primary interviews with maintenance directors at chilled ready-meal manufacturers, biomedical engineers at hospital supply chains, and aftermarket service heads at regional distributors combined with secondary validation from SEC filings, customs equipment import records, and EU F-Gas Regulation implementation databases. Bottom-up equipment shipment analysis and top-down packaging machinery market sizing triangulate volume estimates.
Rate-of-change decomposition across product type, material compatibility, end-use vertical, and heating technology architecture structures the forecast framework. Segmentation dimensions modeled include continuous versus batch configuration, food packaging versus medical device end-use, and electric versus pneumatic versus hybrid heating systems. CAGRs derive from installed base replacement velocity analysis and regulatory deadline alignment. Industry-specific inputs incorporate EU F-Gas Regulation phase-down schedules and FDA validation timeline benchmarks.
The model holds under steady regulatory enforcement timelines and aluminum laminate supply continuity; deviation in EU F-Gas acceleration or medical device packaging demand contraction would shift replacement cycle assumptions. Forecasts reflect documented base conditions with acknowledged sensitivity to electrification skill gap resolution rates. Practitioners should monitor KBA machinery safety standard updates and SAMR GB standard enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Sliding Injection Molding Machine Market
Packaging Machinery
Automatic Paper Cutter Market
Packaging Machinery
Vertical Strapping Machines Market
Packaging Machinery
Heavy Duty Band Sealer Machine Market
Packaging Machinery
Wraparound Case Packers Market
Packaging Machinery
Global Film Coating Machine Market
Packaging Machinery
Soap Stamping Machine Market
Packaging Machinery
Packaging Conveyors Market
Packaging Machinery
Sack Filling Machine Market
Packaging Machinery
Automatic Liquid Filling Machines Market
Packaging Machinery
Die Cutting Machine Market
Packaging Machinery
Candy Wrapping Machine Market
Packaging Machinery
Slitter Rewinder Machines Market
Packaging Machinery
Bottle Filling Machine Market
Packaging Machinery
Face Mask Machines Market
Packaging Machinery
Confectionery Packaging Machine Market