
 Biodegradable Plastic Packaging Market | 2026-2036
Biodegradable Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Plastic Packaging Market Analysis
Polylactic acid is recalibrating cost structures across rigid and flexible formats as it displaces fossil-derived alternatives in food-contact applications. BASF SE leverages its polymer science heritage to anchor supply security for brand owners transitioning from conventional resins. Danimer Scientific specializes in fermentation-based PHA production, competing on marine biodegradability credentials that standard PLA cannot match. NatureWorks dominates North American feedstock access through its Blair, Nebraska facility, sustaining geographic cost advantages for domestic converters.
Biodegradable plastic packaging comprises films, containers, bags, and pouches engineered from PLA, PHA, starch-based, or cellulose feedstocks to decompose under industrial composting or soil conditions within defined timeframes. These materials typically require controlled temperature, moisture, and microbial activity to achieve mineralization, with PLA demanding sustained heat above fifty-five degrees Celsius for effective breakdown. PLA films occupy the largest volume share given mature extrusion infrastructure and favorable clarity properties for fresh produce display. PHA containers represent the fastest-expanding category as marine-degradable certification opens food-service channels previously closed to home-compostable alternatives. Starch-based bags retain cost leadership in agricultural film, though margin pools concentrate in medical packaging where sterility validation commands premium pricing.
The EU Green Deal and REACH frameworks mandate compostability certification for packaging waste streams, while the FDA regulates food-contact notifications for novel biodegradable polymers entering US commerce. Japan's METI has established JIS standards for biomass plastics that influence procurement specifications across Asian supply chains. Stakeholders must monitor evolving definitions of industrial versus home compostability, as divergent national standards threaten to fragment product compliance and limit cross-border material flows.
Market Dynamics
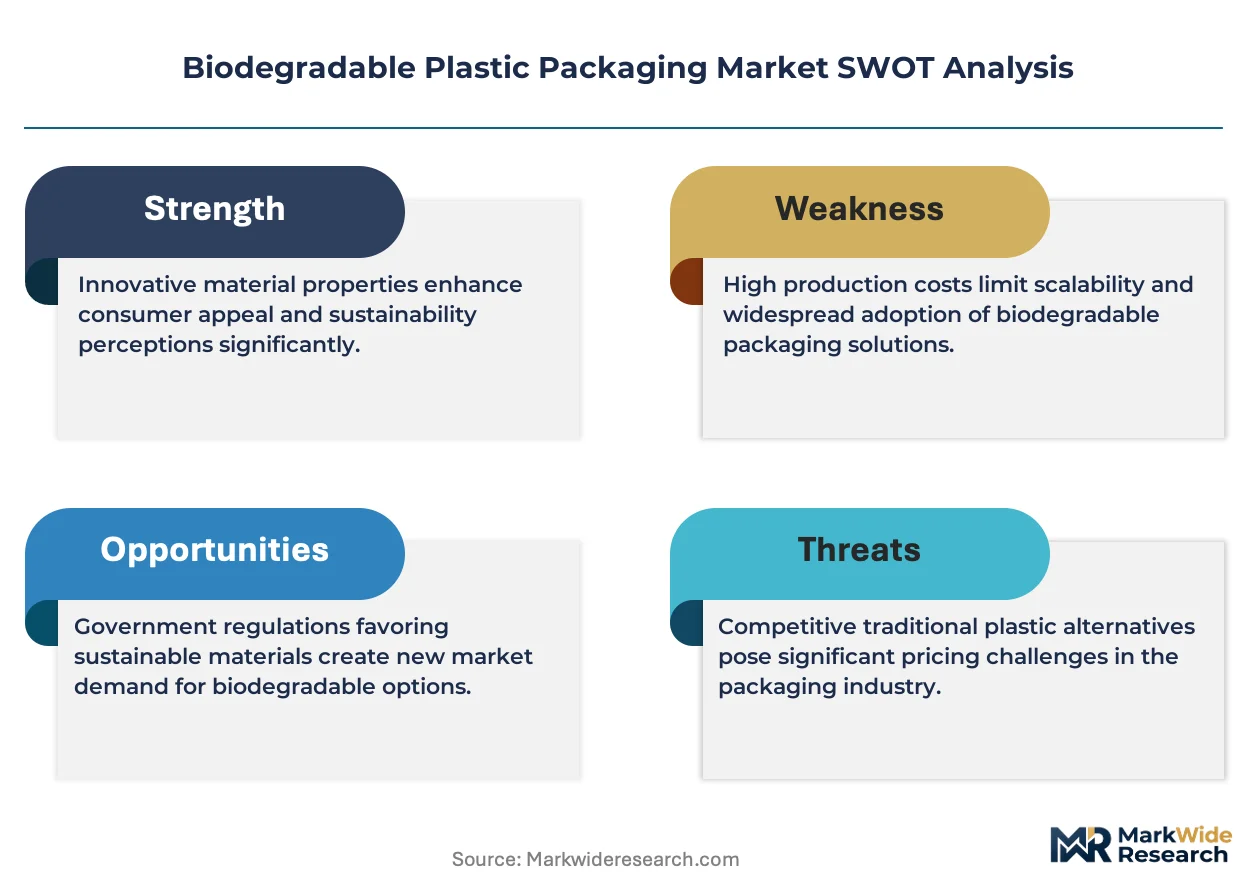
The EU Green Deal is forcing a wholesale reconfiguration of material specifications across food-contact packaging, compelling converters to abandon fossil-derived films before 2030 mandates take full effect. This regulatory compression is redrawing competitive advantage toward suppliers with certified composting infrastructure and verified feedstock traceability.
Growth Catalysts
- EU single-use plastic directives:France and Germany have accelerated compliance timelines for food-service disposables, pulling forward demand for certified compostable alternatives.
- Starch-based film technology:Agricultural mulch applications are expanding as soil-degradable formulations eliminate retrieval costs for farming operations.
- Marine biodegradability certification:Coastal municipalities in Japan are mandating PHA-based food containers for beachside vendors under METI procurement guidelines.
Market Restraints
- Industrial composting infrastructure gaps:Limited facility coverage in the United States forces reliance on anaerobic digestion, which fails to mineralize PLA effectively.
- Feedstock price volatility:Corn and sugarcane input costs fluctuate with agricultural commodity cycles, compressing margins for PLA producers.
- Performance limitations in high-moisture environments:Starch-based films exhibit accelerated degradation in refrigerated supply chains, restricting fresh protein applications.
Strategic Opportunities
- Underpenetrated medical packaging:Sterile barrier applications for surgical kits remain dominated by conventional plastics, creating white space for validated PHA alternatives.
- Direct-to-retailer distribution:E-commerce fulfillment centers are sourcing custom mailer films with home-compostable certification, bypassing traditional converter channels.
- Japan's biomass plastic procurement incentives:METI's JIS-compliant purchasing mandates are opening institutional food-service contracts previously locked by petroleum-based supply agreements.
Industry Challenges
- Industrial composting certification timelines:ASTM D6400 and EN 13432 validation requires 180-day testing cycles that delay product launches.
- Extrusion equipment reconfiguration:Legacy blown-film lines require screw and die modifications to process PLA without thermal degradation.
- Cross-border standard fragmentation:Divergent definitions of home versus industrial compostability between Germany and the Netherlands complicate pan-European product strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Plastic Packaging Market |
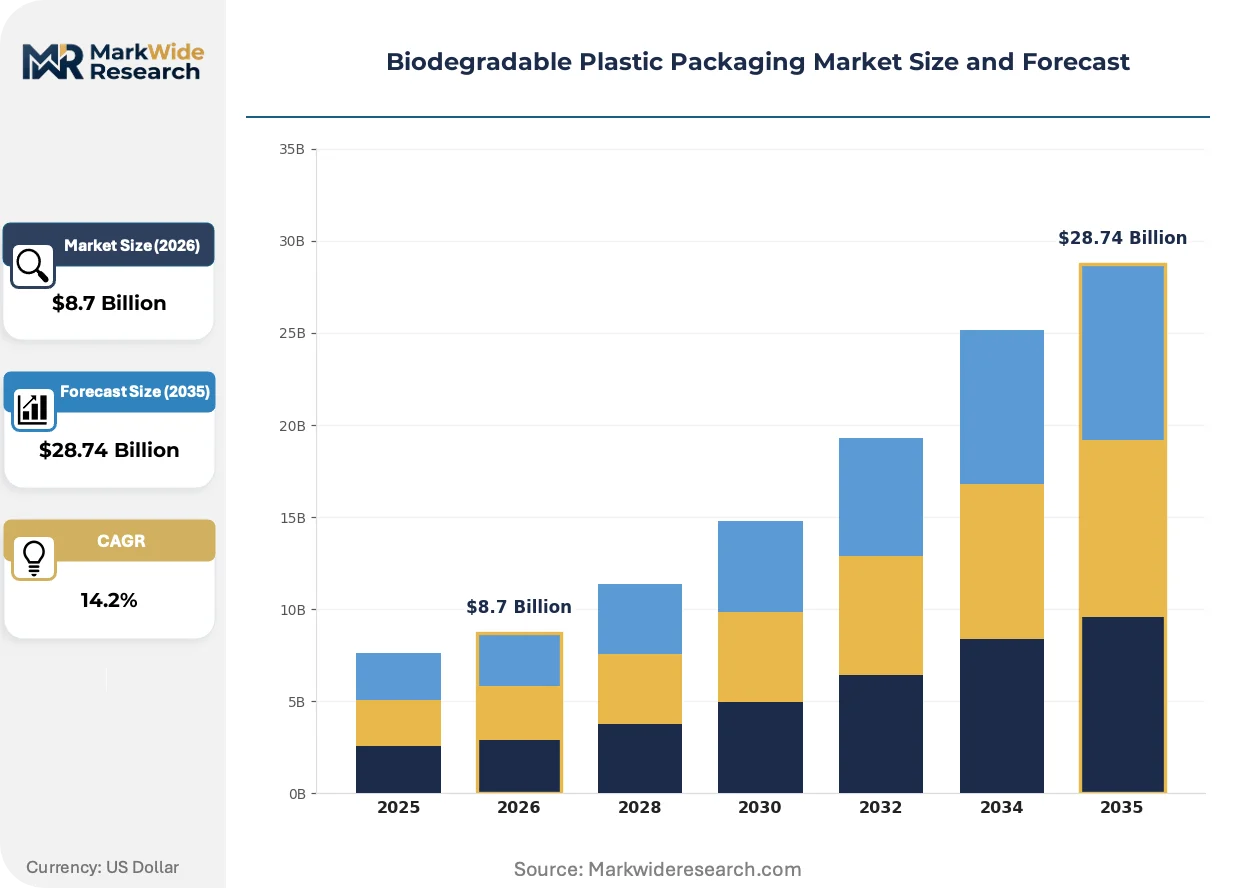
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PLA, PHA, Starch-Based, Cellulose Product Type: Films, Containers, Bags, Pouches Application: Food Packaging, Medical Packaging, Retail Packaging, Agricultural Film End User: Food & Beverage, Healthcare, Retail, Agriculture |
| Companies Covered | NatureWorks, BASF SE, Huhtamäki, Pactiv Evergreen, Danimer Scientific, BioPak, Novamont, Stora Enso, Vegware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Plastic Packaging Market Emerging Trajectories
Active barrier coatings are redefining shelf-life performance for biodegradable formats, narrowing the functional gap with multilayer petroleum-based structures. These advances are unlocking premium food segments previously inaccessible to compostable alternatives.
PHA copolymer formulations are integrating active antimicrobial layers for fresh protein packaging, extending refrigerated shelf life to fourteen days. Major retail chains in Germany are piloting these structures for private-label meat programs. The technology is integrating high-barrier performance with end-of-life compostability, collapsing the traditional trade-off between protection and sustainability.
REACH framework amendments are tightening notification requirements for novel biodegradable additives entering European commerce. ECHA's expanded substance evaluation is extending compliance timelines by eight to twelve months for non-registered polymer variants. Food-contact applications face the steepest documentation burdens, with brand owners demanding pre-certified material streams to avoid regulatory delays.
Buyer concentration among national retail banners is compressing supplier qualification cycles from twenty-four months to twelve. Procurement teams at French hypermarket chains are bundling biodegradable packaging mandates with volume commitments, locking in multi-year supply agreements. This pattern is most pronounced in fresh produce categories, where private-label expansion is driving specification consolidation toward certified compostable films.
Biodegradable Plastic Packaging Market Segmentation
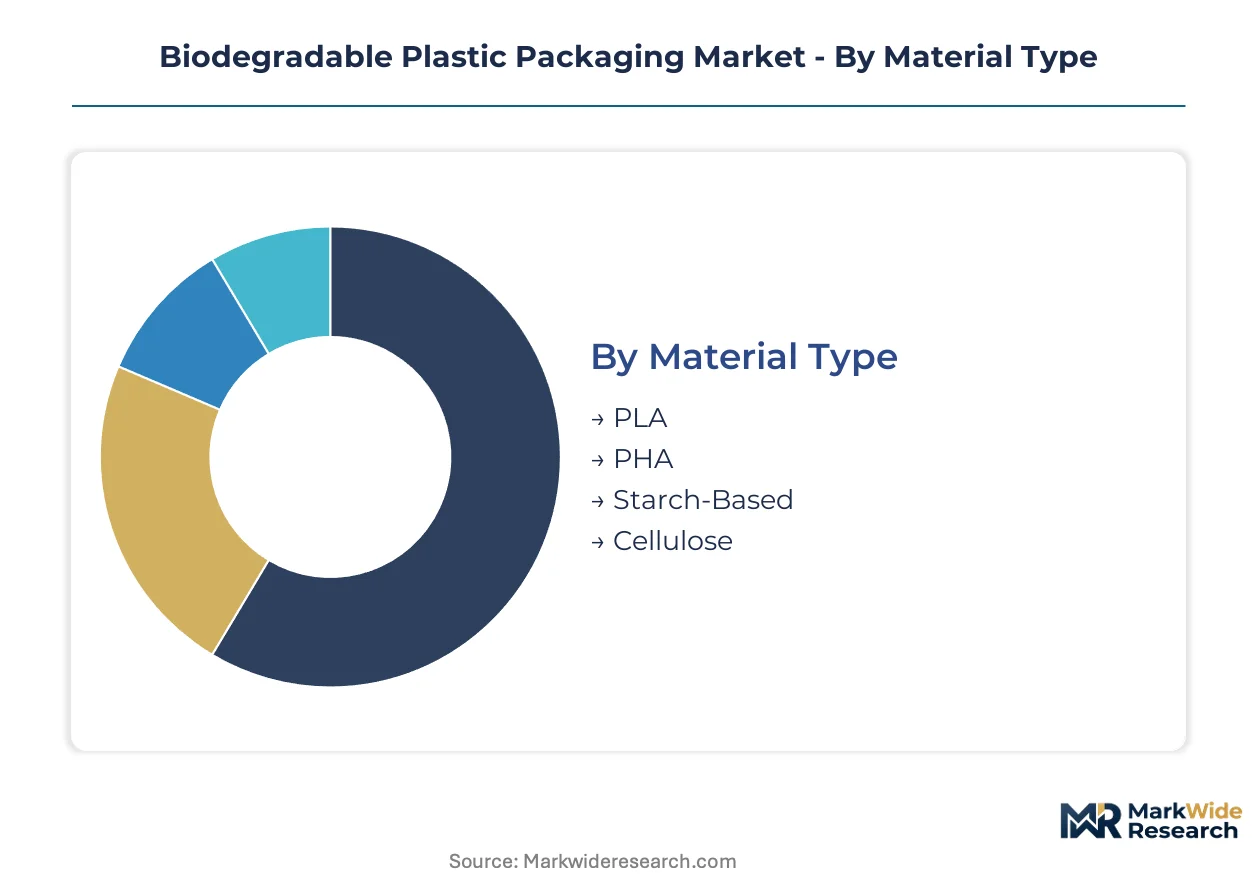
Biodegradable plastic packaging defies uniform treatment across applications. Material selection, product geometry, and end-use sterilization requirements create sharply divergent specification clusters that suppliers must navigate simultaneously.
Material Type:
Supply concentration for fermentation-derived polymers has consolidated around three dominant feedstock pathways, each with distinct geographic anchoring and certification profiles.
- PLA:Corn and sugarcane-derived polylactic acid dominates rigid thermoforming and clear film applications through mature extrusion infrastructure. Demand concentrates in German fresh produce retail where EN 13432 certification is mandatory for private-label packaging programs.
- PHA:Microbial fermentation produces marine-biodegradable polyhydroxyalkanoates that mineralize in ambient soil and aquatic environments without industrial composting heat. Japanese coastal municipalities under METI procurement guidelines are mandating PHA food containers for beachside institutional vendors.
- Starch-Based:Thermoplastic starch compounds from potato and maize feedstocks offer cost leadership in agricultural mulch films. French farming cooperatives are eliminating retrieval labor through soil-degradable formulations.
- Cellulose:Regenerated wood pulp films and molded fiber structures serve premium cosmetic and electronics packaging where tactile differentiation commands specification priority.
Today's leader: PLA. Tomorrow's challenger: PHA.
Product Type:
Manufacturing asset intensity varies dramatically across format categories, with blown film lines requiring the lowest capital barrier to entry and injection molding demanding the highest tooling investment.
- Films:Blown and cast PLA films occupy the largest volume position given retrofitted extrusion infrastructure across European converters. German retail chains specify these for fresh produce display windows where optical clarity drives purchase conversion.
- Containers:Thermoformed and injection-molded rigid formats are climbing fastest as marine-biodegradable PHA grades unlock food-service channels previously restricted to petroleum-based polypropylene. Japanese convenience store chains are piloting PHA bento boxes under METI biomass plastic procurement mandates.
- Bags:Starch-based formulations dominate agricultural carry and soil-degradable mulch applications where mechanical performance requirements are modest and cost sensitivity is acute.
- Pouches:Stand-up and flat pouch structures integrate multilayer barrier coatings for dry food and supplement applications, with French hypermarket private-label programs driving specification consolidation.
Films command current volume leadership. Containers are gaining share fastest in premium food-service segments.
Application:
Regulatory compliance intensity fragments the application landscape, with food-contact notifications imposing steeper documentation burdens than agricultural or retail formats.
- Food Packaging:Fresh produce, protein, and prepared meal applications drive the steepest specification escalation as EU single-use plastic directives force converters toward certified compostable alternatives before 2030 mandates.
- Medical Packaging:Sterile barrier applications for surgical kits and pharmaceutical blisters remain underpenetrated by biodegradable alternatives due to FDA validation timelines and gamma sterilization compatibility requirements.
- Retail Packaging:E-commerce mailers and point-of-sale bags are shifting toward home-compostable certification as direct-to-consumer brands bypass traditional converter channels.
- Agricultural Film:Soil-degradable mulch and greenhouse films eliminate retrieval costs for farming operations, with French and Dutch agricultural cooperatives specifying starch-based formulations.
Food packaging anchors revenue concentration. Medical packaging offers the steepest expansion trajectory for validated barrier technologies.
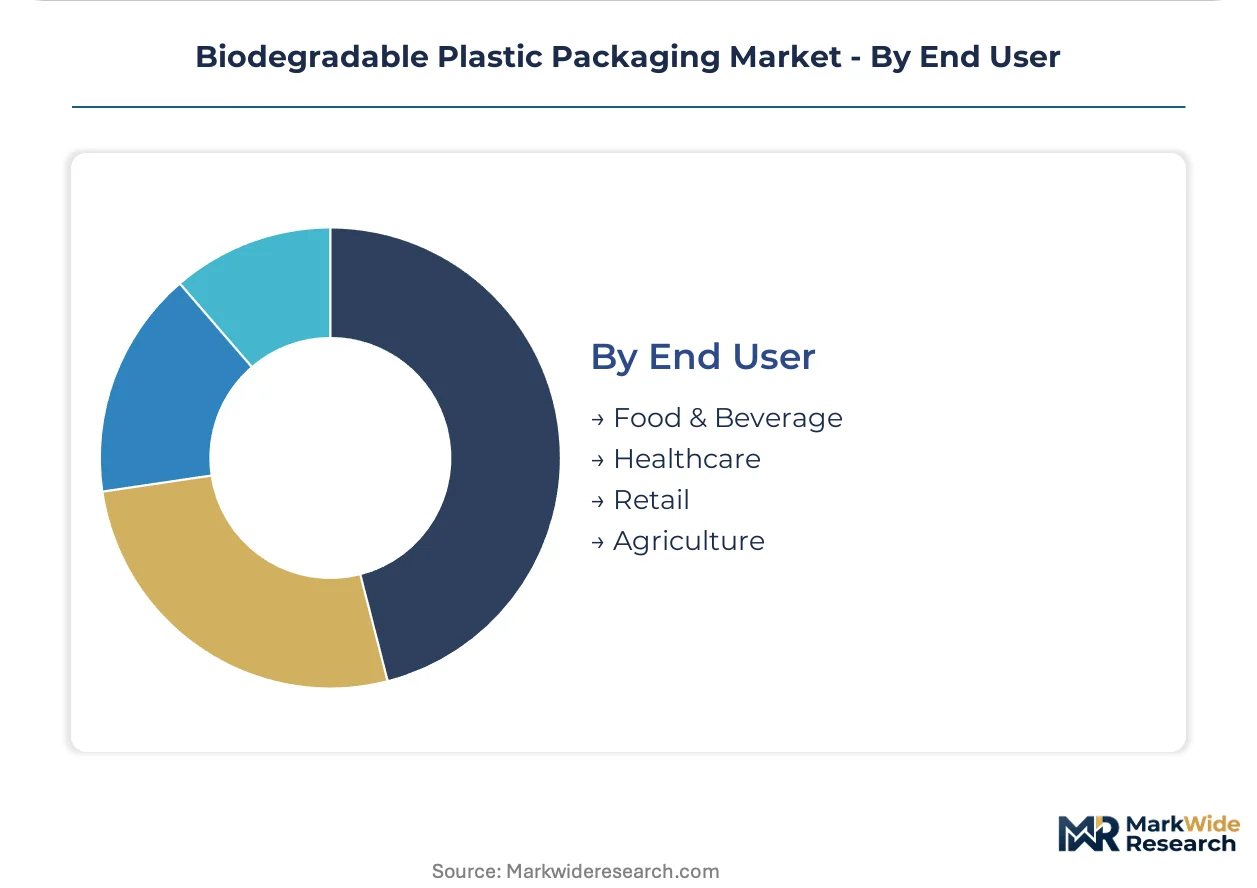
End User:
Procurement sophistication diverges sharply across customer categories, with healthcare and food-service buyers demanding pre-certified material streams while agricultural purchasers prioritize unit economics.
- Food & Beverage:National retail banners and quick-service chains are compressing supplier qualification cycles through bundled volume commitments tied to compostable packaging mandates.
- Healthcare:Hospital systems and pharmaceutical manufacturers face the steepest regulatory documentation burdens, with FDA food-contact notifications and sterilization validation creating multi-year barriers to entry.
- Retail:E-commerce fulfillment centers and national hypermarket chains are consolidating specifications toward certified compostable films, with French procurement teams driving the fastest consolidation timelines.
- Agriculture:Farming cooperatives and greenhouse operators prioritize soil-degradable formulations that eliminate seasonal retrieval labor, with Dutch horticultural clusters specifying starch-based mulch films.
Food and beverage buyers dominate current procurement volume. Healthcare represents the most defensible margin pool for compliant suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr and Rhine-Main corridors anchor European converter capacity for certified compostable films. Regulatory compression across multiple jurisdictions is fragmenting compliance requirements while concentrating procurement power among national retail banners.
Germany
Fresh produce retail chains and private-label expansion drive specification consolidation toward EN 13432-certified films. The EU Green Deal mandates accelerate compliance timelines for food-service disposables through 2030. The Rhine-Ruhr industrial cluster hosts blown-film extrusion assets retrofitted for PLA processing, serving pan-European distribution networks.
France
Hypermarket procurement teams compress supplier qualification cycles through bundled volume commitments tied to compostable mandates. REACH framework amendments tighten notification requirements for novel biodegradable additives entering French commerce. The Paris Basin agricultural belt specifies soil-degradable starch-based mulch films through farming cooperative procurement programs.
Netherlands
Dutch horticultural clusters drive demand for greenhouse films and soil-degradable agricultural applications. The country's national packaging waste framework mandates compostability certification for institutional food-service channels. Rotterdam-Antwerp port logistics facilitate feedstock import flows for fermentation-derived polymer production.
United States
Limited industrial composting infrastructure forces reliance on anaerobic digestion pathways that fail to mineralize PLA effectively. FDA food-contact notification requirements impose multi-year validation timelines for novel biodegradable polymers entering commerce. The Blair, Nebraska feedstock facility anchors North American PLA supply security for domestic converters.
Japan
Coastal municipalities mandate marine-biodegradable PHA food containers for beachside institutional vendors under METI procurement guidelines. JIS standards for biomass plastics influence procurement specifications across Asian supply chains. The Kanto corridor convenience store chains pilot PHA bento boxes for prepared meal applications.
Biodegradable Plastic Packaging Market Vendor Landscape
Global majors compete with regional champions across certification infrastructure and feedstock access. The vendor base stratifies between polymer science conglomerates with integrated resin production and specialized converters focused on single-format extrusion. Three archetypes dominate: fermentation-based biopolymer specialists, petrochemical incumbents pivoting toward bio-based portfolios, and regional packaging converters with retrofitted film lines. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines compress.
Among fermentation-derived biopolymer specialists, Danimer Scientific exemplifies marine-biodegradable PHA production, while NatureWorks occupies a position anchoring North American feedstock access. BASF SE represents the petrochemical incumbent archetype with polymer science heritage extending toward compostable resin supply security. These three entities illustrate the competitive tension between specialized biopolymer pathways and integrated material science platforms.
| Leading Market Players |
|---|
| NatureWorks |
| BASF SE |
| Huhtamäki |
| Pactiv Evergreen |
| Danimer Scientific |
| BioPak |
| Novamont |
| Stora Enso |
| Vegware |
| Others |
Supply Flow & Price Mechanics
Polymer engineering talent clusters in Germany's Rhine-Ruhr corridor anchor cost differentials between premium-certified and economy-grade biodegradable packaging tiers. Labor scarcity for fermentation-process specialists in Nebraska and Thailand widens spreads between PLA and PHA resin pricing.
Pricing Analysis
Input-cost pass-through from corn and sugarcane agricultural cycles dominates PLA resin pricing, with starch-based compounds tracking potato and maize commodity indices. Three-tier pricing structure across premium, standard, and economy levels separates marine-biodegradable PHA from home-compostable PLA from agricultural starch films. Cost compression in standard-grade PLA is intensifying because European converters are retrofitting extrusion lines at scale. Agricultural cooperatives exhibit the highest price sensitivity, while pharmaceutical manufacturers accept premiums for sterile barrier validation.
Supply Chain Analysis
Feedstock supply rests on corn cultivation in the United States Midwest, sugarcane harvesting in Thailand, and potato processing in the Netherlands. Lactic acid fermentation capacity, PHA microbial production, and cellulose pulp regeneration constitute the critical processing nodes. Single-source vulnerability concentrates in Thai sugarcane supply during monsoon disruption seasons. Distribution runs through converter networks in Germany and Japan serving retail banner procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's 2030 single-use plastic mandates compound regulatory demand for certified compostable alternatives across food-contact applications. This regulatory compression rewards early certification investment and penalizes lagging converter transitions.
For Market Incumbents: To counter feedstock price volatility from agricultural commodity cycles, secure long-term offtake agreements with Nebraska and Thai corn suppliers. Anchor certification infrastructure through EN 13432 and ASTM D6400 pre-validation to compress buyer qualification timelines from twenty-four months toward twelve.
For New Entrants and Emerging Players: Marine-biodegradable PHA technology for Japanese coastal municipal procurement offers the most penetrable wedge against established PLA incumbents. Target medical packaging sterile barrier applications where FDA validation timelines have deterred incumbent expansion. Lead with direct-to-retailer e-commerce mailer channels bypassing traditional converter relationships.
For Investors and Strategic Acquirers: National retail banners and quick-service chains are the most active acquirers in this space, consolidating supplier bases through bundled volume commitments. Five-to-ten-year viability hinges on composting infrastructure buildout pace rather than resin production capacity alone. Watch METI procurement guideline expansion beyond coastal municipalities into Japan's institutional food-service channels as the key demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Cultivation | Corn supply agreements in Nebraska and Thailand secure margin stability against agricultural commodity volatility. |
| Marine-Biodegradable Certification Investment | ASTM D6691 and OECD 306 validation unlocks Japanese coastal municipal procurement under METI guidelines. |
| Medical Packaging Sterile Barrier Development | FDA 510(k) pathways for gamma-sterilizable PHA formats access premium-margin surgical kit applications. |
| Direct-to-Retailer Distribution Channel | Home-compostable mailer films bypass converter markups for e-commerce fulfillment center procurement teams. |
| Industrial Composting Infrastructure Partnership | Facility co-location with German and Dutch waste management operators closes end-of-life certification loops. |
Methodological Framework
Bottom-up food packaging and medical device modeling reconciled against top-down resin production and converter capacity tracking forms the analytical core. Primary interviews with polymer plant managers, retail procurement leads, agricultural cooperative buyers, and regulatory affairs directors combined with secondary validation from FDA food-contact notifications, ECHA REACH substance evaluations, EN 13432 certification registries, and METI biomass plastic procurement disclosures.
Input-output matrices map fermentation feedstock flows through extrusion, thermoforming, and injection molding asset bases across the projection horizon. Segmentation dimensions include material type, product format, application compliance intensity, and regional regulatory cluster. CAGRs derive from elasticity-calibrated demand curves against capacity expansion timelines. Forecast inputs incorporate EU Green Deal mandate acceleration scenarios and Japanese JIS standard adoption curves.
The model holds under stable agricultural commodity conditions and certification timeline continuity; deviation in industrial composting infrastructure buildout pace or REACH framework amendment frequency would shift volume trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Oxo Biodegradable Bags Market
Biodegradable Packaging
Global Biodegradable Tableware Market
Biodegradable Packaging
India Biodegradable Tableware & Packaging Products Market
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Oxo-Biodegradable Plastic Packaging Market
Biodegradable Packaging
Bioadhesives for Packaging Market
Biodegradable Packaging
Bioplastic Packaging Market
Biodegradable Packaging
Biodegradable Lids Market
Biodegradable Packaging
Europe Biodegradable Film Market
Biodegradable Packaging
Biodegradable Lidding Films Market
Biodegradable Packaging
Europe Biodegradable Cups Market
Biodegradable Packaging
Asia-Pacific Biodegradable Film Market
Biodegradable Packaging
Clear Bioplastics Packaging Market
Biodegradable Packaging
Biopolymer Packaging Market
Biodegradable Packaging
Biodegradable Cutlery Market
Biodegradable Packaging
Biodegradable Meal Trays Market