
 Botanical Packaging Market | 2026-2036
Botanical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Botanical Packaging Market Outlook
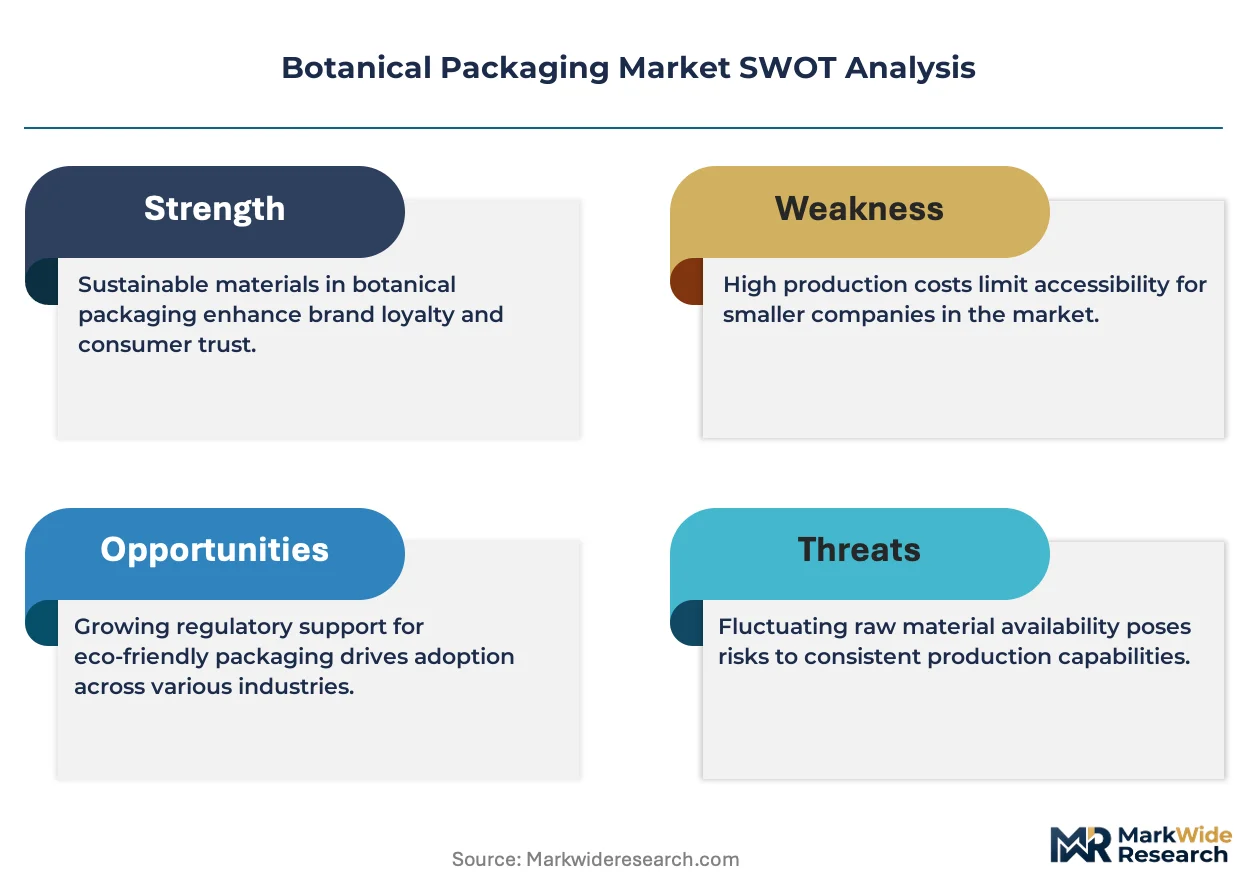
The EU Packaging and Packaging Waste Regulation is restructuring procurement criteria across European botanical product supply chains. Botanical PaperWorks leverages seed-embedded paper technology to anchor premium cosmetic gifting segments. Eco Marketing Solutions sustains channel control through direct-to-brand design partnerships. Searo competes with seaweed-derived films that occupy the marine-biodegradable niche.
Botanical packaging denotes plant-derived or plant-themed primary and secondary packaging systems engineered from cellulose fibers, polysaccharide films, or lignocellulosic substrates with specified compostability windows and aesthetic surface finishes. These systems serve commercial functions of brand differentiation, shelf-life extension, and end-of-life environmental compliance for consumer goods. Bioplastic packaging leads value contribution due to performance parity with conventional polymers in moisture barrier applications. Paper packaging dominates unit volume across Food & Beverage end use where grease resistance and printability requirements align with fiber substrate capabilities. Hemp-based materials represent the fastest-expanding material segment as fiber processing yields improve and regulatory THC thresholds clarify.
FDA food contact substance notifications govern cellulose-based packaging entering US distribution, while EFSA evaluates novel biopolymer migration limits under EU framework 1935/2004. REACH registration requirements for bamboo-derived additives constrain European material sourcing flexibility. Stakeholders must monitor evolving compostability certification divergence between BPI and OK Compost standards to avoid market access fragmentation.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing substitution timelines across botanical packaging supply chains, forcing material transitions ahead of cost parity with conventional substrates.
Growth Catalysts
- Compostability Mandates:The EU PPWR mandates compostable secondary packaging for certified organic cosmetic lines in France and Germany, creating immediate procurement pull from premium beauty brands.
- Fiber Processing Yields:Improved hemp fiber decortication technology is lowering unit material costs and clarifying regulatory THC thresholds for cross-border trade.
- Rhine-Ruhr Cluster Concentration:Germany's packaging manufacturing corridor concentrates converter capacity, enabling rapid scale-up of cellulose-based formats for food and beverage clients.
Market Restraints
- REACH Registration Barriers:Bamboo-derived additive registration under ECHA requirements constrains European sourcing flexibility and extends qualification timelines for new suppliers.
- Moisture Barrier Performance Gap:Polysaccharide films exhibit inferior oxygen and water vapor transmission rates versus conventional polymers in extended shelf-life applications.
- Certification Divergence:Misalignment between BPI and OK Compost standards fragments market access and forces redundant testing expenditures for multi-jurisdictional brands.
Strategic Opportunities
- Marine-Biodegradable Films:Seaweed-derived packaging formats address coastal pollution concerns and open gifting segments in Nordic markets with stringent marine discharge regulations.
- Seed-Embedded Paper:Embedded germination technology differentiates premium cosmetic gifting and creates post-use engagement loops for direct-to-consumer beauty brands.
- Direct-to-Brand Design Partnerships:Bypassing traditional distributor channels captures margin and locks in specification control for specialized botanical substrate converters.
Industry Challenges
- Composting Infrastructure Mismatch:Industrial composting facility availability lags material certification expansion, creating end-of-life execution gaps in mid-sized metropolitan markets.
- Food Contact Notification Timelines:FDA cellulose-based packaging reviews average 18-24 months, delaying US market entry for novel biopolymer formulations.
- Legacy Equipment Retrofit Costs:Converting existing paperboard lines for hemp fiber processing requires capital-intensive drying and calendering modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Botanical Packaging Market |
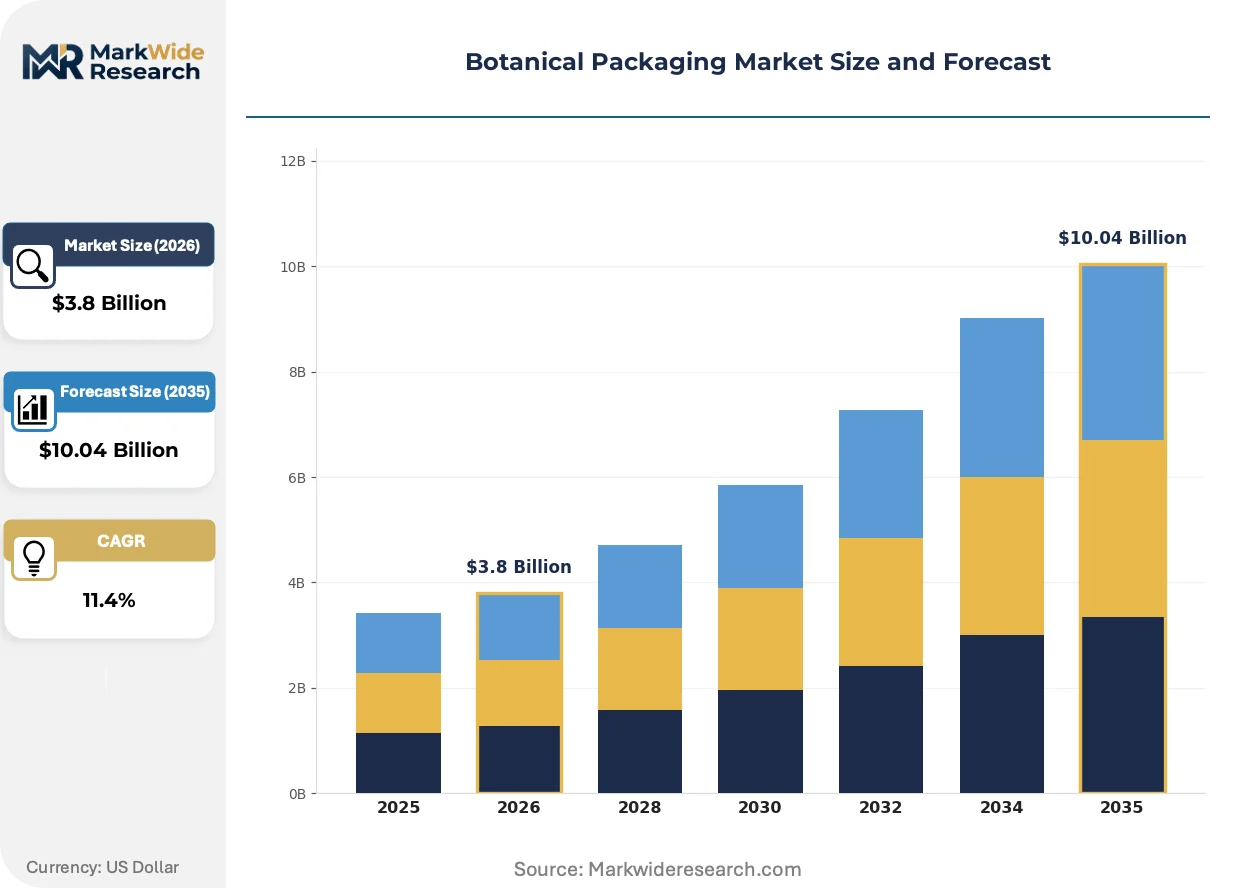
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Glass, Paper, Bioplastic, Aluminum End Use: Cosmetics, Food & Beverage, Pharmaceuticals, Home Care Material: Bamboo, Recycled Paper, Corn Starch, Hemp Design Style: Minimalist, Rustic, Vintage, Modern |
| Companies Covered | Botanical PaperWorks, The Mend, Eco Marketing Solutions, Earthly Goods, inc., Searo, FlexSea, Evoware, Greenfield, Bloomin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Botanical Packaging Market Strategic Shifts
Material science advances are collapsing the performance gap between plant-derived substrates and petrochemical alternatives, while regulatory pressure accelerates commercial deployment timelines.
Hemp fiber processing technology is converging with traditional paperboard manufacturing infrastructure. German packaging converters in the Rhine-Ruhr corridor are retrofitting de-inking and refining systems to handle higher-lignin hemp pulp without fiber damage. Cosmetic and food brands with certified organic lines are adopting these substrates at premium price points, compressing the timeline for cost parity with wood-pulp alternatives.
REACH registration requirements for novel biopolymer additives are tightening material qualification pathways across European supply chains. ECHA's expanded data requirements for bamboo-derived substances are extending pre-market approval timelines and favoring incumbent cellulose suppliers with existing dossiers. Premium cosmetic brands are responding by consolidating supplier bases around REACH-registered fiber sources, reducing formulation experimentation.
Beauty sector procurement patterns are fragmenting toward specialized design partnerships. Direct-to-brand relationships are displacing traditional packaging distributor channels for botanical substrate sourcing, particularly in France and Germany where organic certification mandates require traceability documentation. This channel shift concentrates volume with converters offering in-house design and compostability certification support.
Botanical Packaging Market Segmentation
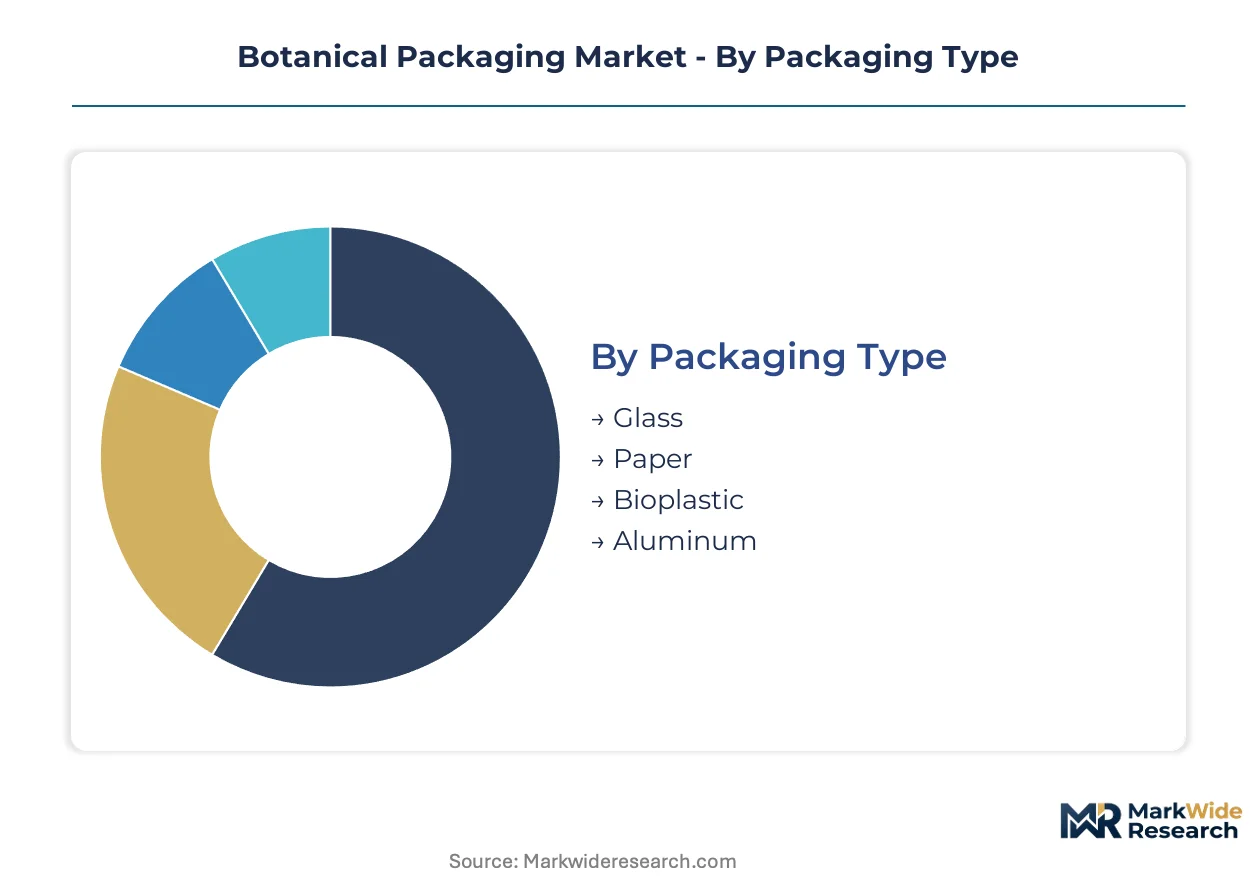
Botanical packaging procurement varies sharply by substrate performance requirements and end-use regulatory exposure. Material selection directly determines compostability certification pathways and brand positioning in premium organic segments.
Packaging Type:
Buyers differentiate primarily by moisture barrier specifications and shelf-life extension needs.
- Bioplastic:Polylactide and starch-based polymers achieve functional parity with conventional plastics in oxygen barrier applications. Premium cosmetic brands in France mandate certified compostable formats for organic product lines under EU PPWR timelines.
- Paper:Cellulose fiber substrates dominate food service applications where grease resistance and printability converge. Germany's Rhine-Ruhr packaging corridor concentrates converter capacity for rapid scale-up of fiber-based formats.
- Glass:Silica-based containers preserve volatile botanical compounds in pharmaceutical and high-end cosmetic applications.
- Aluminum:Lightweight metal formats serve extended shelf-life requirements where total barrier protection outweighs compostability priorities.
Paper leads volumes today; bioplastic is gaining share fastest.
End Use:
Regulatory intensity and certification documentation requirements separate procurement patterns across verticals.
- Cosmetics:Organic certification mandates in France and Germany drive compostable secondary packaging specifications. EFSA migration limit evaluations under framework 1935/2004 govern cellulose-based primary packaging for EU distribution.
- Food & Beverage:FDA food contact substance notifications govern cellulose packaging entering US distribution, with reviews averaging 18-24 months for novel biopolymer formulations.
- Pharmaceuticals:Child-resistant and tamper-evident requirements constrain material substitution timelines for botanical-derived substrates.
- Home Care:Concentrated chemical compatibility testing limits adoption of polysaccharide films in detergent and cleaning product applications.
Food & Beverage generates the highest unit volumes; Cosmetics shows the steepest expansion trajectory.
Material:
Processing yield improvements and cross-border regulatory clarity determine sourcing economics.
- Hemp:Decortication technology advances are lowering fiber processing costs while THC threshold clarifications ease cross-border trade. REACH registration requirements constrain bamboo alternatives, favoring hemp for European converter qualification.
- Bamboo:Rapid-growth grass fibers offer aesthetic differentiation in premium gifting segments. ECHA expanded data requirements for bamboo-derived additives extend pre-market approval timelines versus incumbent cellulose suppliers.
- Recycled Paper:Post-consumer fiber streams provide cost-competitive substrates with established composting infrastructure compatibility.
- Corn Starch:Polysaccharide films derived from maize feedstocks occupy the marine-biodegradable niche in Nordic coastal markets.
Recycled Paper anchors current supply; Hemp is climbing the fastest.
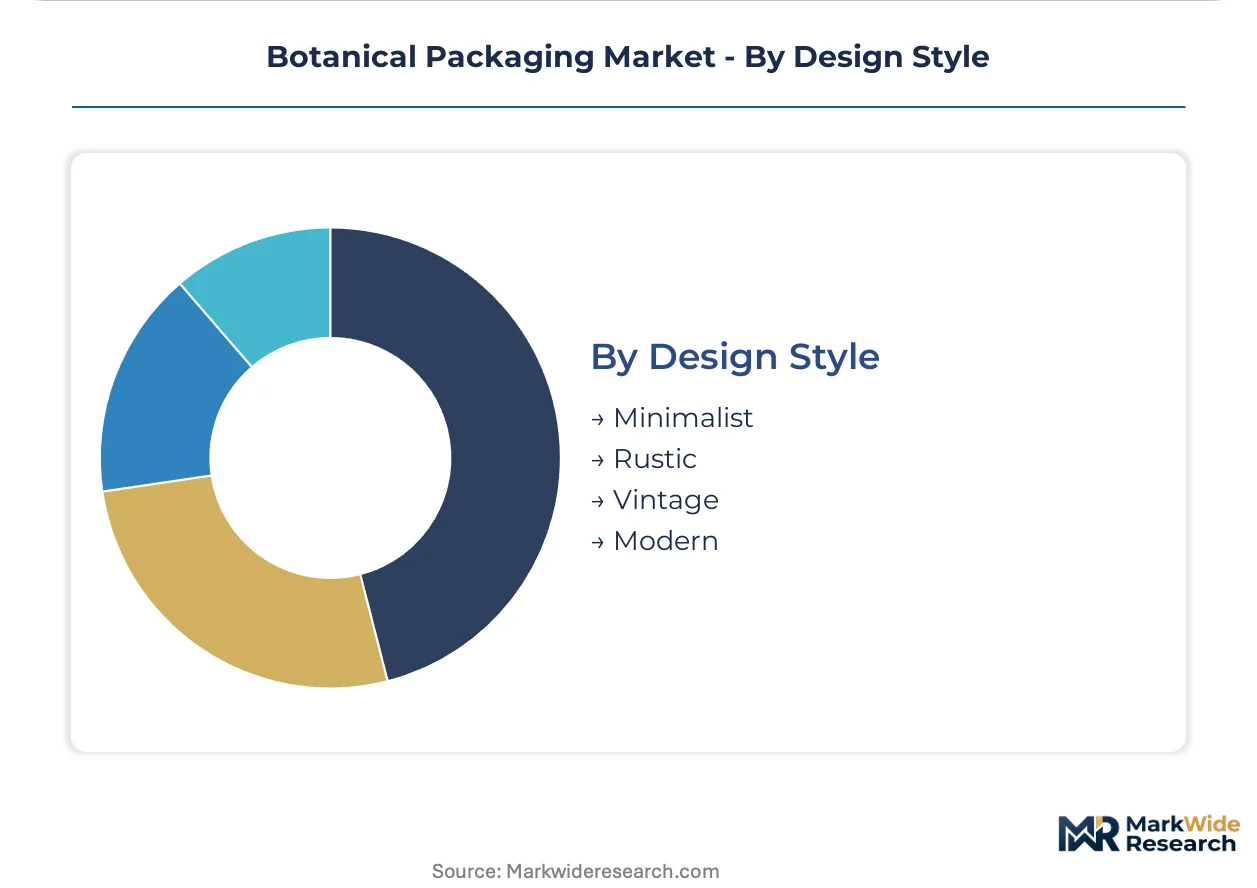
Design Style:
Brand positioning tier and direct-to-consumer engagement goals drive aesthetic specification.
- Minimalist:Reduced ink coverage and unbleached fiber exposure signal sustainability credentials to premium organic buyers. Seed-embedded paper technology creates post-use engagement loops for direct-to-consumer beauty brands.
- Rustic:Visible fiber texture and earth-tone palettes target artisanal food and small-batch cosmetic positioning.
- Vintage:Ornate typography and patina finishes serve heritage brand repositioning in European apothecary-inspired segments.
- Modern:Clean geometry and metallic accents balance botanical substrate origins with contemporary luxury aesthetics.
Minimalist dominates premium procurement; Modern is expanding most quickly in mass-market conversions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Botanical packaging manufacturing first achieved industrial scale in Germany's Rhine-Ruhr corridor during the early 2000s, when hemp fiber processing converged with established paperboard infrastructure. This historical foundation continues to shape procurement patterns and regulatory alignment across major demand centers.
Germany
Premium cosmetic brands headquartered in Hamburg and Düsseldorf now mandate compostable secondary packaging for certified organic product lines. The EU Packaging and Packaging Waste Regulation compresses substitution timelines, forcing material transitions ahead of full cost parity. The Rhine-Ruhr packaging cluster concentrates converter capacity, enabling rapid scale-up of cellulose-based formats for food and beverage clients.
France
Paris-based beauty houses drive specification pull for seed-embedded paper technology in premium cosmetic gifting segments. ANSM cosmetic packaging guidelines intersect with EFSA migration limit evaluations under framework 1935/2004 for primary packaging. The Île-de-France region hosts design-forward converters specializing in direct-to-brand partnerships with traceability documentation.
United States
California and New York cosmetic brands pursue compostable formats for direct-to-consumer sustainability positioning. FDA food contact substance notifications govern cellulose-based packaging entering distribution, with reviews averaging 18-24 months for novel biopolymer formulations. The Pacific Northwest houses early-stage hemp fiber processors building regional supply chains.
United Kingdom
London-headquartered apothecary-inspired brands adopt vintage-design botanical substrates for heritage repositioning. The UK Environment Agency enforces packaging waste recovery targets that accelerate certified compostable adoption. Midlands-based converters retrofit equipment for higher-lignin hemp pulp processing without fiber damage.
Netherlands
Amsterdam sustainable packaging startups pilot marine-biodegradable seaweed films for Nordic market export. The Dutch National Institute for Public Health and the Environment monitors biopolymer migration in food contact applications. The Randstad logistics hub enables just-in-time delivery to German and French cosmetic manufacturers.
Botanical Packaging Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and design partnership capabilities. The vendor base spans seed-embedded paper specialists, seaweed film innovators, and hemp fiber converters with varying REACH registration status. Three archetypes dominate: certified compostability aggregators, marine-biodegradable niche developers, and direct-to-brand design studios. Consolidation pressure is accelerating through strategic partnerships and capacity expansion in the Rhine-Ruhr corridor.
Within the certified compostability tier, Botanical PaperWorks and Bloomin exemplify seed-embedded paper technology developers targeting premium cosmetic gifting. Searo occupies a position among marine-biodegradable specialists leveraging seaweed-derived films for coastal pollution-sensitive markets. These three entities represent divergent substrate strategies—terrestrial fiber germination, marine polysaccharide extraction, and industrial compostability certification—each anchoring distinct procurement channels.
| Leading Market Players |
|---|
| Botanical PaperWorks |
| The Mend |
| Eco Marketing Solutions |
| Earthly Goods, inc. |
| Searo |
| FlexSea |
| Evoware |
| Greenfield |
| Bloomin |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between BPI-verified compostable formats and uncertified fiber alternatives manifests in both margin structures and raw material sourcing configurations. Premium cosmetic brands in France and Germany absorb 40-60% unit cost premiums for REACH-registered hemp substrates, while food service buyers in the Rhine-Ruhr corridor prioritize cost-competitive recycled paper with established industrial composting compatibility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts, with BPI certification and EFSA migration compliance anchoring the top tier. Price differentiation hinges on compostability certification depth and hemp fiber content ratios. Cost compression in standard-tier recycled paper is intensifying because German converters are retrofitting de-inking systems for higher-throughput post-consumer fiber processing. Food & Beverage procurement teams exhibit highest price sensitivity due to thin category margins, while organic cosmetic brand managers demonstrate lowest sensitivity when traceability documentation ensures EU PPWR compliance.
Supply Chain Analysis
Single-source vulnerability sits with German hemp fiber decortication capacity concentrated in Lower Saxony processing facilities. Raw material flows draw from French hemp cultivars, Dutch seaweed harvesting cooperatives, and Belgian recycled paper collection networks. Tariff exposure on bamboo-derived additives imported from Asian suppliers constrains formulation flexibility for REACH-registered converters. Distribution runs through direct-to-brand design partnerships displacing traditional packaging distributors, particularly for premium cosmetic clients requiring traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in botanical packaging rests on hemp fiber processing yield improvements collapsing cost premiums versus wood-pulp alternatives, alongside premium-tier adoption acceleration from EU PPWR mandates.
For Market Incumbents: To counter REACH registration barriers favoring established cellulose suppliers, incumbent converters should deepen backward integration into hemp cultivation partnerships in Lower Saxony and Rhineland-Palatinate while accelerating BPI-OK Compost dual certification investments to preempt market access fragmentation. For New Entrants and Emerging Players: Marine-biodegradable film technology offers the most penetrable wedge for specialized entrants, with Amsterdam-based pilot facilities demonstrating scalable seaweed-derived formats for Nordic coastal markets. White-space targets include pharmaceutical secondary packaging where child-resistant requirements have slowed botanical substrate adoption, and UK apothecary-inspired heritage brands seeking vintage-design fiber substrates. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap converters possessing dual REACH registration and in-house design capabilities. Long-term viability over the next decade favors entities integrating hemp fiber processing with direct-to-brand channel control. The signal to watch is FDA food contact notification approval timelines for novel biopolymer formulations, which would unlock US market expansion for European substrate innovators.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Investment | ECHA dossier completion locks in European supplier qualification ahead of bamboo additive restrictions. |
| Hemp Fiber Processing Scale-Up | Rhine-Ruhr corridor retrofitting captures cost parity with wood-pulp alternatives for organic cosmetic lines. |
| Dual Certification Program | BPI-OK Compost alignment eliminates redundant testing expenditures for multi-jurisdictional brand clients. |
| Direct-to-Brand Design Partnership | Channel bypass captures margin and locks specification control for specialized botanical substrate converters. |
| Marine-Biodegradable Film Development | Seaweed-derived formats address Nordic coastal discharge regulations and premium gifting differentiation. |
Study Parameters
Coverage spans Germany, France, the United States, the United Kingdom, and the Netherlands, with primary inputs from each market triangulated against secondary validation. Packaging converter operations directors, cosmetic brand sustainability officers, ECHA regulatory affairs consultants, and industrial composting facility managers provided structured interviews. Secondary sources included EU Packaging and Packaging Waste Regulation implementation guidance, EFSA migration limit evaluations under framework 1935/2004, FDA food contact substance notification databases, and Rhine-Ruhr packaging cluster trade association capacity surveys. Bottom-up volume modeling and top-down value reconciliation ensured cross-validation.
Granularity-level modeling disaggregated demand across packaging type, end-use vertical, material substrate, and design style dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs incorporated hemp fiber decortication yield improvement curves, REACH registration timeline distributions for novel biopolymer additives, and EU PPWR compliance deadline phasing across member states.
The model holds under sustained EU regulatory enforcement and stable hemp cultivation acreage; deviation in FDA food contact notification approval accelerations or industrial composting infrastructure buildout delays would shift volume trajectories. Forecasts reflect documented assumptions regarding certification standard convergence and fiber processing technology maturation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Bioplastic Packaging Market
Biodegradable Packaging
Europe Biodegradable Film Market
Biodegradable Packaging
Europe Biodegradable Cups Market
Biodegradable Packaging
Biofoam Packaging Market
Biodegradable Packaging
Biodegradable Water Bottles Market
Biodegradable Packaging
Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Biodegradable Plastic Packaging Market
Biodegradable Packaging
India Biodegradable Tableware & Packaging Products Market
Biodegradable Packaging
Biodegradable Packaging Market
Biodegradable Packaging
Biodegradable Plastic Bags and Sacks Market
Biodegradable Packaging
Biodegradable Cutlery Market
Biodegradable Packaging
North America Biodegradable Film Market
Biodegradable Packaging
Bioadhesives for Packaging Market
Biodegradable Packaging
Biodegradable Lids Market
Biodegradable Packaging
Bioplastic Packaging Bag Market
Biodegradable Packaging
Biodegradable Lidding Films Market