
 Biodegradable Lidding Films Market | 2026-2036
Biodegradable Lidding Films Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Lidding Films Market Outlook
Direct procurement between film converters and ready-meal packers is narrowing as sustainability audits become mandatory upstream. Amcor Plc leverages its integrated resin-to-film platform to secure multi-year supply agreements with European dairy processors. Mondi Group anchors its position through captive kraft-paper and biopolymer operations in Central Europe. UFlex Ltd competes on cost-engineered PLA formulations tailored to Indian and Southeast Asian humidity conditions.
Biodegradable lidding films are heat-sealable barrier layers engineered from polylactic acid, polyhydroxyalkanoates, or cellulose derivatives, typically spanning 20 to 80 micrometers with oxygen transmission rates below 1 cc per square meter per day to preserve shelf-stable and chilled contents. Their primary commercial purpose is to replace multilayer petroleum-based lidding in modified-atmosphere and vacuum-sealed trays while maintaining peelability and printability. PLA dominates current volume owing to mature resin supply chains and FDA food-contact clearance, though PHA grades command premium positioning where marine biodegradability certifications apply. Food packaging absorbs the majority of film output, with medical packaging emerging as a margin-rich segment demanding lot-level traceability and ethylene oxide sterilization compatibility.
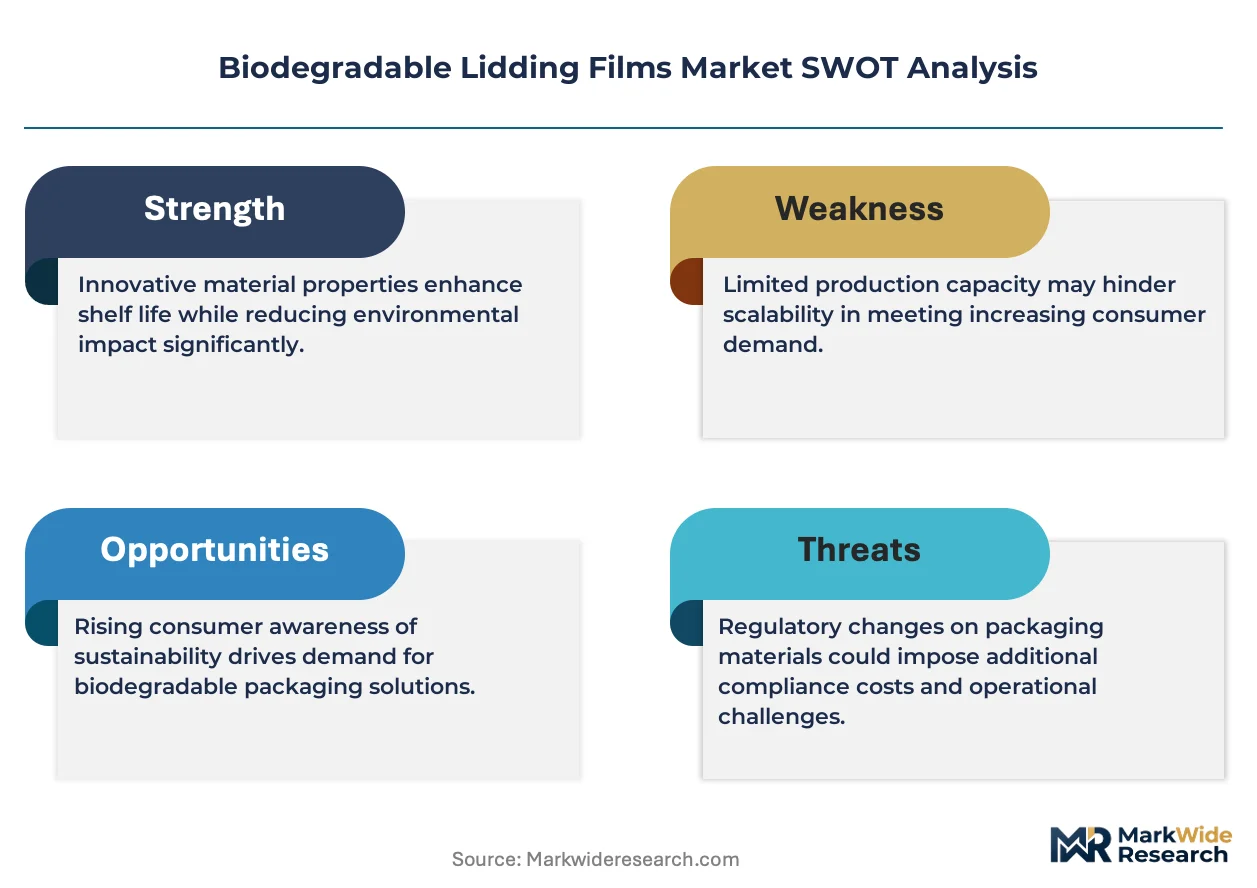
The EU F-Gas Regulation and REACH chemical restrictions compel converters to validate biopolymer feedstocks through ECHA-registered safety dossiers, while FDA bio-based content guidelines shape US market access protocols for compostable claims. Germany's national packaging law, implementing extended producer responsibility fees calibrated to recyclability scores, redirects investment toward certified home-compostable film structures. Stakeholders must monitor evolving home-composting infrastructure gaps, as industrial composting dominance in most regions threatens to cap consumer-facing brand value unless collection systems scale proportionally with material supply.

Market Dynamics
EU Single-Use Plastics Directive enforcement is compressing substitution timelines for petroleum-based lidding across food retail, forcing converters to requalify entire product lines before mandated phase-out deadlines.
Growth Catalysts
- REACH chemical dossiers:ECHA-registered biopolymer safety validation accelerates regulatory clearance for PLA and PHA film grades entering European food-contact applications.
- Fresh food packaging trays:Supermarket private-label mandates for compostable ready-meal packaging drive volume commitments from German and French retail chains.
- Marine biodegradability certifications:PHA-based lidding commands premium positioning in coastal markets where TÜV OK biodegradable marine standards apply.
Market Restraints
- Industrial lactic acid supply:Corn feedstock price volatility and fermentation capacity constraints in Thailand and China create input cost instability for PLA resin.
- Home-composting infrastructure gaps:Collection system underdevelopment in most EU member states caps consumer-facing brand value despite certified film availability.
- Multilayer barrier performance:Oxygen transmission rates above 0.5 cc per square meter per day limit shelf-life extension for high-fat dairy applications.
Strategic Opportunities
- Medical packaging segment:Ethylene oxide sterilization-compatible biopolymer films offer margin expansion through lot-level traceability requirements.
- Indian humidity-engineered formulations:Cost-optimized PLA grades adapted to monsoon climate conditions unlock Southeast Asian processed food export packaging.
- Extended producer responsibility fees:Germany's national packaging law recyclability scoring redirects investment toward certified home-compostable structures.
Industry Challenges
- ECHA dossier compilation timelines:Biopolymer feedstock registration delays extend product qualification cycles by 18-24 months for new resin entrants.
- Heat-seal layer integration:Biodegradable sealant compatibility with existing tray thermoforming equipment requires line-speed recalibration and technician retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Lidding Films Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PHA, Starch-Based, Cellulose End Use Industry: Food Packaging, Medical Packaging, Consumer Goods, Pharmaceutical Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors Thickness: Thin, Medium, Thick, Ultra-Thin |
| Companies Covered | Amcor Plc, Mondi Group, UFlex Ltd, Berry Global, Sealed Air Corporation, Huhtamaki, Quantum Packaging, Rockwell Solutions, Source One Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Lidding Films Market Strategic Shifts
Active barrier coating technologies and resin-alloy formulations are compressing performance gaps between biopolymer and conventional multilayer films, reshaping converter R&D priorities.
Multilayer coextrusion with bio-based ethylene vinyl alcohol is collapsing the barrier-performance differential that previously restricted biodegradable lidding to short-shelf-life applications. European dairy processors now specify these structures for 21-day chilled distribution. The technology is collapsing premium pricing power for petroleum-based high-barrier alternatives.
F-Gas Regulation phase-down mandates compel converters to eliminate fluorinated barrier chemistries from lidding specifications. Industrial consequence includes accelerated validation of cellulose-derived coatings and plasma-deposited silicon oxide layers. Modified-atmosphere meat packaging in Italy and Spain faces the most acute reformulation pressure.
Retailer sustainability audit integration into supplier scorecards compresses qualification cycles for film converters. Direct procurement relationships between ready-meal packers and resin producers displace distributor intermediaries in Northern European supply chains. Germany's supermarket consolidation amplifies this pattern most visibly.
Biodegradable Lidding Films Market Segmentation

Biodegradable lidding films serve divergent performance requirements across food preservation, medical sterilization, and consumer convenience applications. Material selection, thickness engineering, and channel strategy each determine unit economics and regulatory compliance pathways for converters.
Product Type:
Use-case spectrum spans oxygen-sensitive dairy applications requiring sub-1 cc transmission rates through marine-degradable coastal packaging where TÜV OK certification commands premium positioning.
- PLA:Polylactic acid formulations leverage mature fermentation supply chains from Thailand and China to deliver FDA-cleared food-contact films at scale. German supermarket private-label mandates concentrate demand for 20-40 micrometer grades in ready-meal trays.
- PHA:Polyhydroxyalkanoates achieve marine biodegradability certification where coastal jurisdictions enforce TÜV standards. Italian and Spanish meat packers specify these grades for modified-atmosphere applications facing F-Gas Regulation phase-down pressure.
- Starch-Based:Cost-engineered blends target Indian and Southeast Asian humidity conditions through moisture-resistant alloy formulations.
- Cellulose:Derived from wood pulp, these films replace fluorinated barrier chemistries in plasma-deposited silicon oxide coating applications.
The dominant share belongs to PLA, while PHA is closing the gap fastest through marine certification premiums.
End Use Industry:
Application maturity varies sharply by sterilization compatibility requirements and shelf-life extension demands.
- Food Packaging:Fresh food packaging trays absorb majority volume as retailers phase out petroleum-based alternatives. EU Single-Use Plastics Directive enforcement compresses substitution timelines across member states.
- Medical Packaging:Ethylene oxide sterilization-compatible biopolymer films command margin premiums through lot-level traceability requirements. European dairy processors now specify multilayer coextrusion structures for 21-day chilled distribution.
- Consumer Goods:Peelability and printability specifications drive material selection for convenience-oriented applications.
- Pharmaceutical:Barrier performance requirements limit penetration where oxygen transmission rates above 0.5 cc per square meter per day restrict adoption.
Food packaging holds the volume base, with medical packaging expanding most quickly through sterilization-grade qualification.
Distribution Channel:
Channel structure reflects sustainability audit integration into procurement workflows.
- Online Retail:E-commerce platforms aggregate specialty film orders from small-batch food processors seeking certified compostable packaging.
- Supermarkets:Direct procurement relationships displace distributor intermediaries as German retail consolidation amplifies private-label mandate enforcement.
- Specialty Stores:Technical film specifications for medical and pharmaceutical applications route through converter-direct channels.
- Distributors:Traditional intermediaries retain position in fragmented Southern European markets where audit integration lags Northern European patterns.
Supermarkets command the procurement volume, while online retail is gaining share fastest through small-batch aggregation.
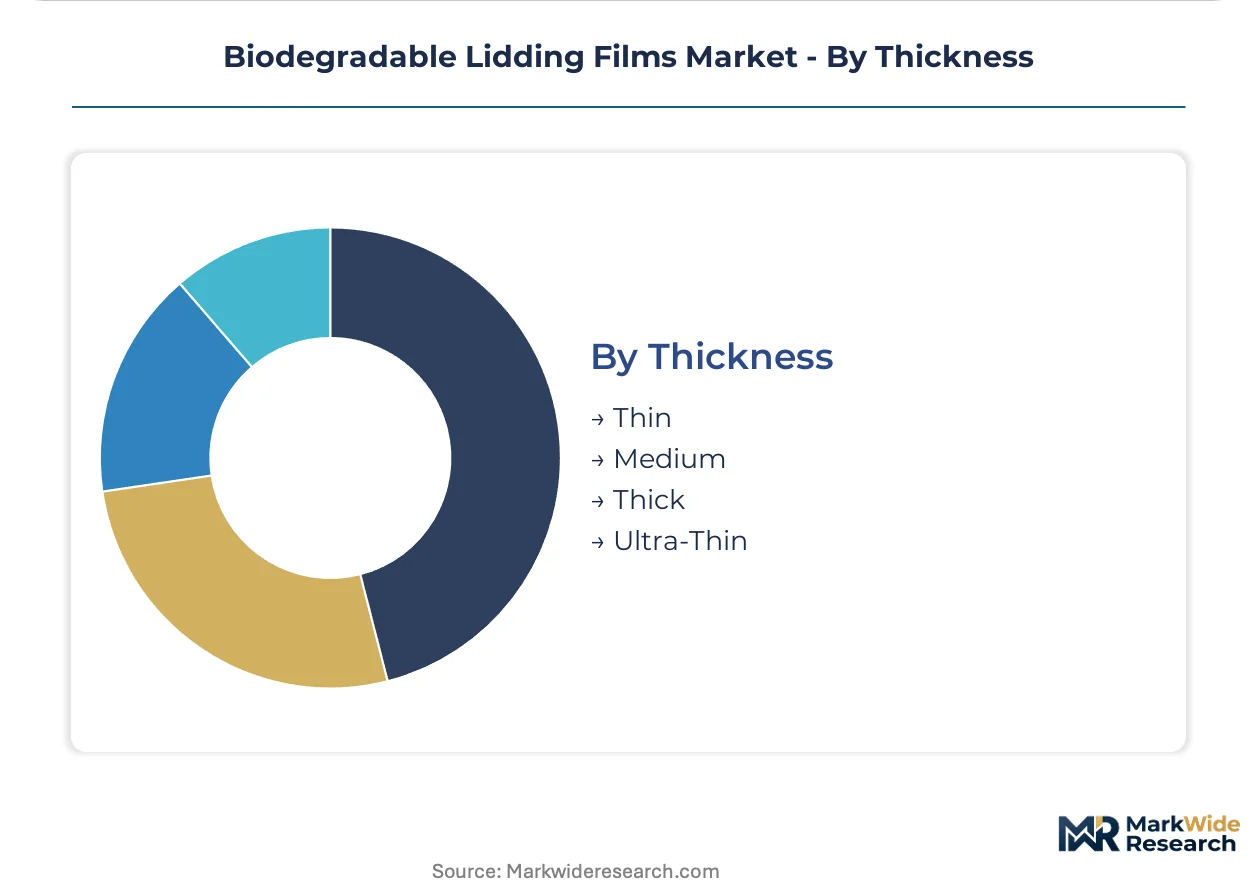
Thickness:
Thickness engineering balances barrier performance against compostability certification and thermoforming equipment compatibility.
- Thin:20-35 micrometer grades serve short-shelf-life fresh produce where oxygen transmission tolerance permits cost minimization.
- Medium:35-55 micrometer structures dominate ready-meal applications requiring 14-day distribution windows.
- Thick:55-80 micrometer films address high-fat dairy barrier requirements where multilayer coextrusion with bio-based ethylene vinyl alcohol extends shelf life to 21 days.
- Ultra-Thin:Sub-20 micrometer experimental grades target pharmaceutical blister pack substitution where heat-seal layer integration challenges persist.
Medium thickness captures the installed base, with thick grades climbing the fastest through extended shelf-life specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA-registered safety dossiers for biopolymer feedstocks anchor European regulatory clearance timelines, while FDA bio-based content guidelines shape parallel pathways in North America. Demand concentrates where extended producer responsibility fees and supermarket private-label mandates intersect.
Germany
Supermarket chains have mandated compostable packaging for private-label ready meals, compressing substitution timelines for petroleum-based alternatives. The national packaging law calibrates extended producer responsibility fees to recyclability scores, redirecting investment toward certified home-compostable film structures. The Rhine-Ruhr industrial corridor hosts converter operations supplying dairy processors with multilayer coextrusion structures.
United States
FDA bio-based content guidelines shape market access protocols for compostable claims, particularly for PLA grades entering food-contact applications. The absence of federal extended producer responsibility frameworks creates state-level fragmentation, with California and New York advancing divergent certification requirements. Midwest corn-belt proximity supports fermentation supply chains for lactic acid feedstock production.
China
Dual carbon goals and MEE enforcement priorities accelerate industrial composting infrastructure deployment, though home-composting collection systems remain underdeveloped outside tier-one cities. GB standards for biodegradable plastics create domestic certification pathways distinct from EU TÜV or US BPI marks. Yangtze River Delta chemical clusters concentrate PLA resin fermentation capacity.
India
FSSAI packaging safety notifications and DGFT import restrictions on single-use plastics create regulatory pressure for domestic biopolymer film adoption. PLI scheme incentives for specialty chemicals support backward integration into lactic acid production. Mumbai-Pune and Ahmedabad industrial corridors host cost-engineered formulation operations adapted to monsoon humidity conditions.
Thailand
Corn feedstock availability and fermentation infrastructure position the country as a PLA resin export hub serving European and Japanese converters. BOI investment promotion privileges for bioplastics manufacturing attract film converter joint ventures. Eastern Economic Corridor industrial estates concentrate integrated resin-to-film operations.
Biodegradable Lidding Films Market Competitive Environment
Integrated resin-to-film platforms and specialized converter operations split the market between upstream-controlled supply chains and flexibility-focused service models. Three strategic archetypes dominate: multinational packaging conglomerates with captive biopolymer supply, regional converters with humidity-engineered formulation capabilities, and niche specialists in sterilization-grade medical films. Competitive moves center on multi-year supply agreement capture and sustainability audit integration into procurement workflows.
Among multinational packaging conglomerates, Amcor Plc and Mondi Group exemplify integrated platform strategies. Amcor leverages resin-to-film integration to anchor European dairy processor relationships, while Mondi Group's captive kraft-paper and biopolymer operations in Central Europe support barrier film coextrusion. UFlex Ltd occupies a position among cost-optimized regional specialists, with formulation capabilities adapted to Indian and Southeast Asian climate conditions.
| Leading Market Players |
|---|
| Amcor Plc |
| Mondi Group |
| UFlex Ltd |
| Berry Global |
| Sealed Air Corporation |
| Huhtamaki |
| Quantum Packaging |
| Rockwell Solutions |
| Source One Packaging |
| Others |
Value Chain & Pricing Dynamics
Fermentation capacity underutilization in Thailand's Eastern Economic Corridor is compressing PLA resin spot pricing and forcing converters toward long-term offtake contracts to lock margin visibility. This utilization dynamic simultaneously rewards integrated resin-to-film platforms with procurement leverage while squeezing standalone converters dependent on merchant resin markets.
Pricing Analysis
European converters command 15-25% premia over Southeast Asian delivered prices for identical PLA film specifications, reflecting ECHA registration costs and logistics exposure. Pricing stratifies across marine-certified PHA grades, industrial-compostable PLA structures, and uncertified starch blends based on certification tier and volume scale. Cost compression in standard PLA grades is intensifying because Thai fermentation capacity additions outpace German converter demand growth. Small-batch food processors exhibit highest price sensitivity, while medical packaging buyers prioritize sterilization compatibility over unit economics.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for PLA resin procurement. Production gravity centers on Thailand, China, and Germany for resin fermentation and film conversion respectively. Raw material dependencies span corn feedstock for lactic acid, fermentation-derived PHA biomass, and cellulose pulp for barrier coatings. Distribution runs through direct procurement channels displacing traditional distributor networks as supermarket sustainability audits mandate supply chain transparency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through ECHA-registered biopolymer dossiers creates defensive moats that compound with each qualification cycle, extending incumbent advantage through 18-24 month registration timelines that new resin entrants cannot circumvent.
For Market Incumbents: Entrench position through captive lactic acid fermentation capacity in Thailand's Eastern Economic Corridor, securing backward integration into corn feedstock supply. Accelerate multilayer coextrusion R&D to collapse barrier-performance differentials with petroleum-based alternatives before F-Gas Regulation phase-down deadlines eliminate fluorinated chemistry options. Prioritize ECHA dossier maintenance investments over price competition to exploit registration-delay advantages against emerging Asian resin suppliers. For New Entrants and Emerging Players: Establish a beachhead in Indian humidity-engineered formulations where monsoon-adapted PLA alloys face limited incumbent competition. Target Southeast Asian processed food export packaging segments where cost-optimized starch-PLA blends satisfy FSSAI compliance without premium certification requirements. Pursue joint venture structures with Thai BOI-privileged fermentation operators to bypass capital-intensive greenfield resin construction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated resin-to-film platforms serving European dairy processors under multi-year supply agreements. Long-term viability hinges on exposure to medical packaging sterilization-grade qualifications where lot-level traceability requirements sustain margin premiums. Monitor ECHA registration approval velocity as the critical inflection signal for resin entrant competitive threat assessment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactic Acid Fermentation | Captive Thai corn-belt supply secures margin control against merchant resin volatility. |
| Marine Biodegradability Certification Investment | TÜV OK certification unlocks premium positioning in Italian and Spanish coastal meat packaging. |
| Multilayer Coextrusion Capacity Expansion | Bio-based ethylene vinyl alcohol integration extends shelf-life specifications for German dairy processors. |
| Direct Procurement Channel Development | Supermarket sustainability audit integration displaces distributor intermediaries in Northern European supply chains. |
| Humidity-Engineered Formulation R&D | Monsoon-adapted PLA alloys penetrate Indian and Southeast Asian export packaging segments. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from packaging conglomerates, and ECHA registration databases. Film converter executives, biopolymer procurement leads at European dairy processors, and regulatory affairs directors at resin fermentation operators provided operational validation. Technical R&D directors and sustainability audit managers at German supermarket chains supplied demand-side perspective. Bottom-up volume modeling triangulated against top-down value estimates derived from trade flow analysis.
Forecast inputs include material-grade segmentation across PLA, PHA, starch-based, and cellulose film types; thickness-tier engineering specifications; and end-use industry penetration rates for food, medical, consumer goods, and pharmaceutical applications. Channel structure evolution from distributor-mediated to direct procurement was modeled explicitly. CAGRs were derived from regression analysis of historical substitution patterns against regulatory deadline enforcement intensity, cross-referenced with fermentation capacity expansion announcements.
Stress conditions across corn feedstock price volatility, ECHA registration timeline delays, and home-composting infrastructure deployment gaps were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Single-Use Plastics Directive enforcement consistency and F-Gas Regulation phase-down adherence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Clear Bioplastics Packaging Market
Biodegradable Packaging
Compostable Shrink Wrap Market
Biodegradable Packaging
Europe Biodegradable Plastic Packaging Market
Biodegradable Packaging
Bioadhesives for Packaging Market
Biodegradable Packaging
Oxo Biodegradable Bags Market
Biodegradable Packaging
Biodegradable Packaging Materials Market
Biodegradable Packaging
Biodegradable Cups Market
Biodegradable Packaging
Biodegradable Packaging Market
Biodegradable Packaging
Biodegradable Plastic Packaging Market
Biodegradable Packaging
Biodegradable Water Bottles Market
Biodegradable Packaging
Global Bioplastic Multi-Layer Films Market
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
North America Biodegradable Film Market
Biodegradable Packaging
Biodegradable Lids Market
Biodegradable Packaging
Biodegradable Food Packaging Market