
 Compostable Shrink Wrap Market | 2026-2036
Compostable Shrink Wrap Market Size, Share, and Industry Trends Forecast 2026-2036
Compostable Shrink Wrap Market Analytics
Food packaging procurement is consolidating around compostable shrink wrap as major retailers enforce sustainability mandates across supplier networks. BASF SE leverages its polymer science depth to anchor European supply of certified compostable films. NatureWorks LLC specializes in PLA-based formulations that compete on clarity and seal strength with conventional polyethylene. Mondi Group controls integrated paper-polymer capacity that sustains cost positions in industrial-grade segments.
Compostable shrink wrap denotes a flexible packaging film engineered from bio-based polymers, cellulose derivatives, or coated paper substrates that disintegrate under industrial or home composting conditions within specified temperature and humidity parameters, typically serving to unitize, protect, and display consumer products through heat-shrink application. Polymer-based grades dominate current volume owing to compatibility with existing shrink-tunnel equipment, while cellulose variants capture premium positioning in food-grade applications where optical clarity and grease resistance command margin pools. Biofilm segments represent the fastest-expanding structural category as material scientists improve barrier properties against moisture and oxygen transmission.
The European Chemicals Agency enforces REACH compliance for bio-based additives, while the U.S. FDA regulates food-contact substances under 21 CFR, and ASTM D6400 certification governs industrial compostability claims in North America; these frameworks collectively elevate technical barriers that filter out uncertified suppliers and redirect procurement toward validated film sources. Stakeholders must monitor evolving home-composting standards and anaerobic digestion compatibility as municipalities expand organic waste collection programs.
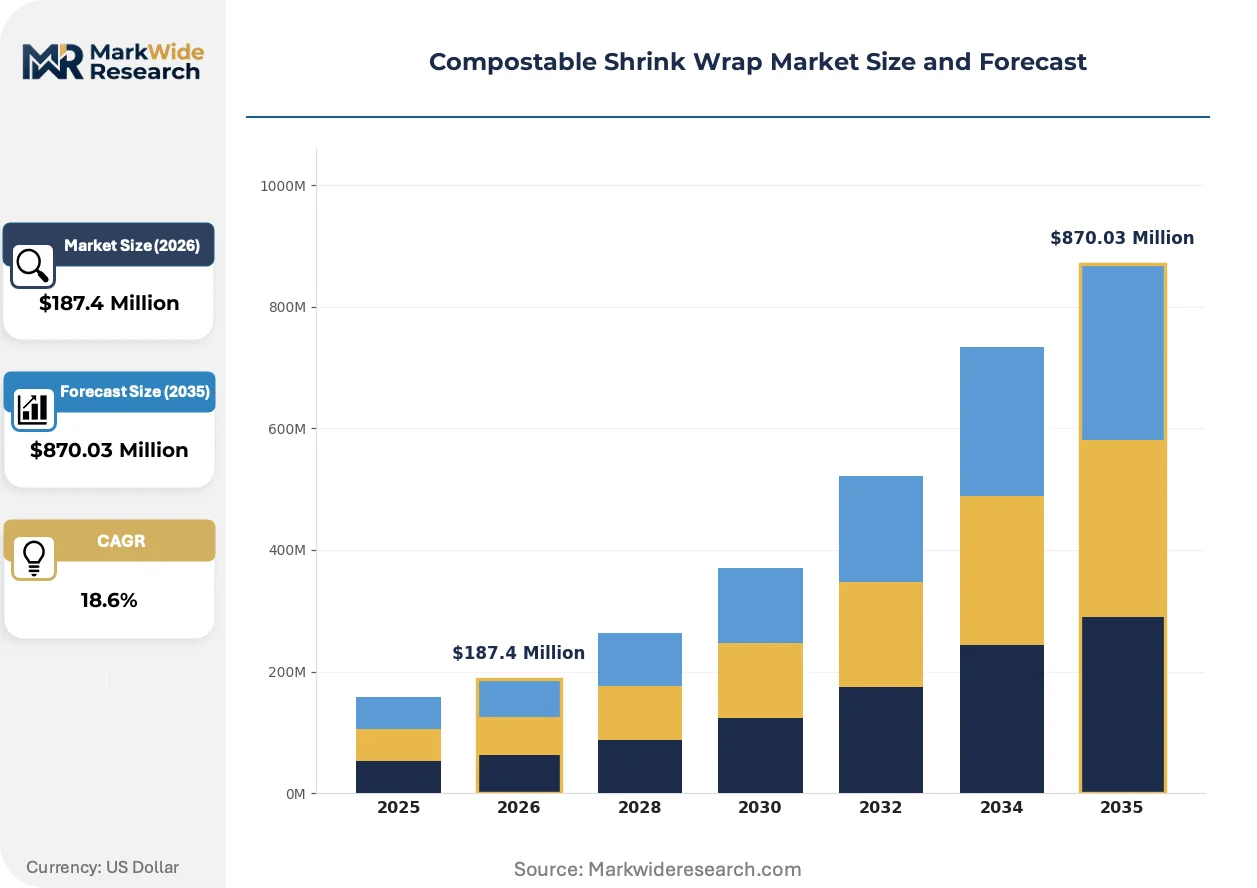
Market Dynamics
Industrial composting infrastructure expansion is concentrating demand validation in specific municipalities, forcing film suppliers to align certification tiers with localized waste-processing capabilities rather than pursuing universal compostability claims.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightening material standards for single-use plastics are redirecting supermarket procurement toward certified compostable alternatives. Food retailers now mandate supplier compliance with industrial compostability protocols.
- PLA barrier enhancement:Material scientists have improved moisture and oxygen transmission resistance in polylactic acid formulations. This technical advance allows compostable films to protect perishable goods through extended supply chains.
- German industrial composting density:The country's mature organic waste collection network supports premium film uptake by guaranteeing end-of-life processing. Meal-kit services leverage this infrastructure to market fully compostable packaging.
Market Restraints
- Caprolactam price volatility:Bio-based polyamide feedstocks track petrochemical derivatives, exposing compostable film margins to input cost swings. Producers lack hedging instruments for specialty bio-monomers.
- Home-composting standard fragmentation:Absence of unified ASTM or ISO protocols for domestic decomposition creates labeling confusion. Retailers hesitate to stock films carrying incompatible certification marks.
- Shrink-tunnel equipment retrofit costs:Converting polyethylene-optimized heat tunnels for PLA or cellulose films requires temperature-control modifications. Small converters delay adoption pending equipment amortization cycles.
Strategic Opportunities
- Anaerobic digestion compatibility:Municipal organic waste programs in the Netherlands and Belgium are expanding biogas extraction capacity. Film formulations compatible with both composting and digestion pathways capture dual-endpoint premiums.
- Pharmaceutical unit-dose packaging:Blister packs and shrink-wrapped medical devices present untapped demand for certified compostable barriers. Regulatory scrutiny of healthcare plastic waste accelerates pilot programs.
- Direct-to-farm supply contracts:Produce distributors bypass converter intermediaries by sourcing certified films straight from polymer compounders. This channel compression captures margin and ensures chain-of-custody documentation.
Industry Challenges
- ASTM D6400 certification timelines:Third-party validation of industrial compostability requires 180-day laboratory decomposition testing. Product development cycles stretch 14-18 months, delaying market entry against conventional films.
- Polymer science talent scarcity:Formulation chemists with expertise in both bio-based materials and heat-shrink processing command premium compensation. Training programs at technical universities have not scaled to meet demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compostable Shrink Wrap Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-Based, Paper, Cellulose, Biofilm Application: Food Packaging, Consumer Goods, Electronics, Retail Branding End User: Manufacturers, Retailers, Distributors, E-Commerce Material Grade: Industrial Grade, Food Grade, Eco-Friendly, Recyclable |
| Companies Covered | BASF SE, Amcor, International Paper Company, Mondi Group, Smurfit Kappa Group, Kingfa Science & Technology, NatureWorks LLC, Sealed Air, Tetra Pak International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compostable Shrink Wrap Market Evolving Landscape
Material science breakthroughs are compressing the performance gap between bio-based films and petroleum-derived alternatives, while regulatory frameworks accelerate end-of-life accountability across packaging value chains.
Multilayer coextrusion technology is converging with nanocellulose reinforcement to produce compostable shrink films with oxygen transmission rates below 1 cc/m²/day. Premium meat and cheese packagers in France and Italy have adopted these structures for modified-atmosphere applications. The convergence is displacing conventional EVOH barrier layers in shelf-life-sensitive segments.
REACH compliance enforcement by the European Chemicals Agency now mandates full disclosure of bio-based additive migration profiles. Compounders must submit extensive safety data for plasticizers and slip agents derived from renewable feedstocks. Food-contact film producers serving EU markets have restructured supply chains to exclude non-registered additives, elevating formulation costs but filtering out uncertified competitors.
Supermarket private-label consolidation is compressing supplier bases toward vertically integrated film producers with in-house certification capabilities. German and Austrian retail chains now require single-source accountability for compostability claims, displacing fragmented converter networks. This concentration favors compounders with captive polymerization and blown-film extrusion assets.
Compostable Shrink Wrap Market Segmentation
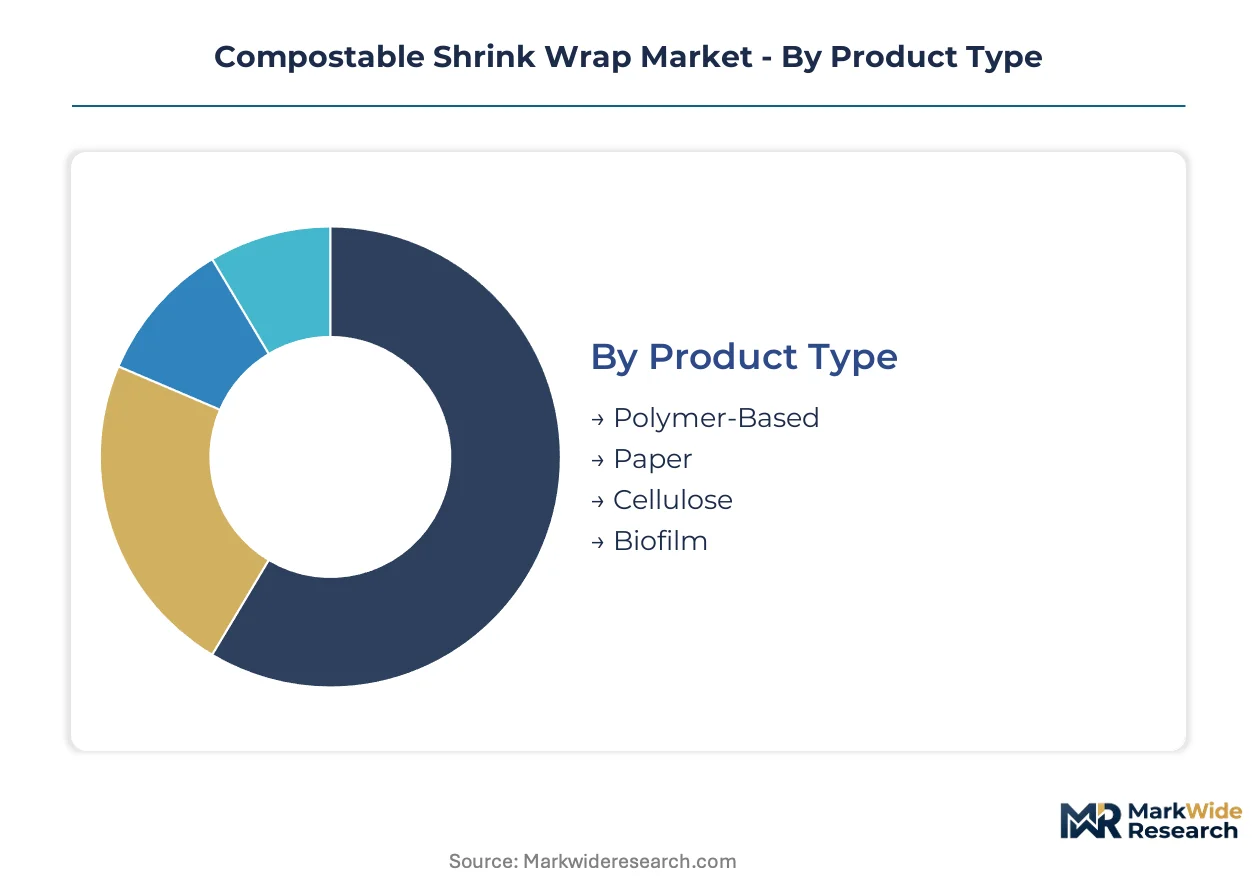
Compostable shrink wrap markets fragment across material chemistry, end-use performance requirements, and certification tiers. Procurement teams select film grades based on composting infrastructure availability, equipment compatibility, and regulatory compliance obligations rather than unit cost alone.
Product Type:
Material composition determines shrink-tunnel compatibility, barrier performance, and end-of-life processing pathways.
- Polymer-Based:PLA and bio-polyamide formulations dominate current volumes through direct substitution for conventional polyethylene in existing heat-tunnel equipment. German supermarket chains and meal-kit services concentrate procurement here due to mature industrial composting infrastructure.
- Biofilm:Advanced multilayer structures incorporating nanocellulose reinforcement achieve oxygen transmission rates below 1 cc/m²/day. French and Italian meat packagers adopt these for modified-atmosphere applications where shelf-life extension commands premium positioning.
- Cellulose:Regenerated cellulose films serve premium food-grade segments demanding optical clarity and grease resistance.
- Paper:Coated paper substrates target industrial bundling applications where moisture barrier demands remain modest.
Polymer-based grades lead volumes today; biofilm is gaining share fastest.
Application:
Performance specifications vary sharply by product protection requirements and display priorities.
- Food Packaging:Modified-atmosphere and fresh produce applications demand precise oxygen and moisture barriers. EU Packaging and Packaging Waste Regulation mandates are redirecting supermarket procurement toward certified compostable alternatives with full chain-of-custody documentation.
- Consumer Goods:Unitization and retail display functions prioritize clarity and printability over extended barrier performance.
- Electronics:Anti-static and moisture protection requirements have slowed compostable adoption pending material science advances.
- Retail Branding:Printed shrink sleeves for private-label differentiation emphasize graphic reproduction quality and scuff resistance.
Food packaging commands the dominant revenue pool; retail branding applications are expanding most quickly as sustainability claims drive private-label differentiation.
End User:
Procurement scale and technical capability determine whether buyers source through converters or direct from compounders.
- Retailers:German and Austrian supermarket chains now mandate single-source accountability for compostability claims, consolidating supplier bases toward vertically integrated film producers with in-house certification capabilities.
- Manufacturers:Produce distributors increasingly bypass converter intermediaries by sourcing certified films straight from polymer compounders to capture margin and ensure documentation integrity.
- Distributors:Intermediate stocking roles are compressing as direct supply contracts proliferate.
- E-Commerce:Fulfillment operations prioritize unitization efficiency and damage reduction over compostability certification.
Retailers drive specification standards; manufacturers are capturing procurement volume fastest through direct supply arrangements.
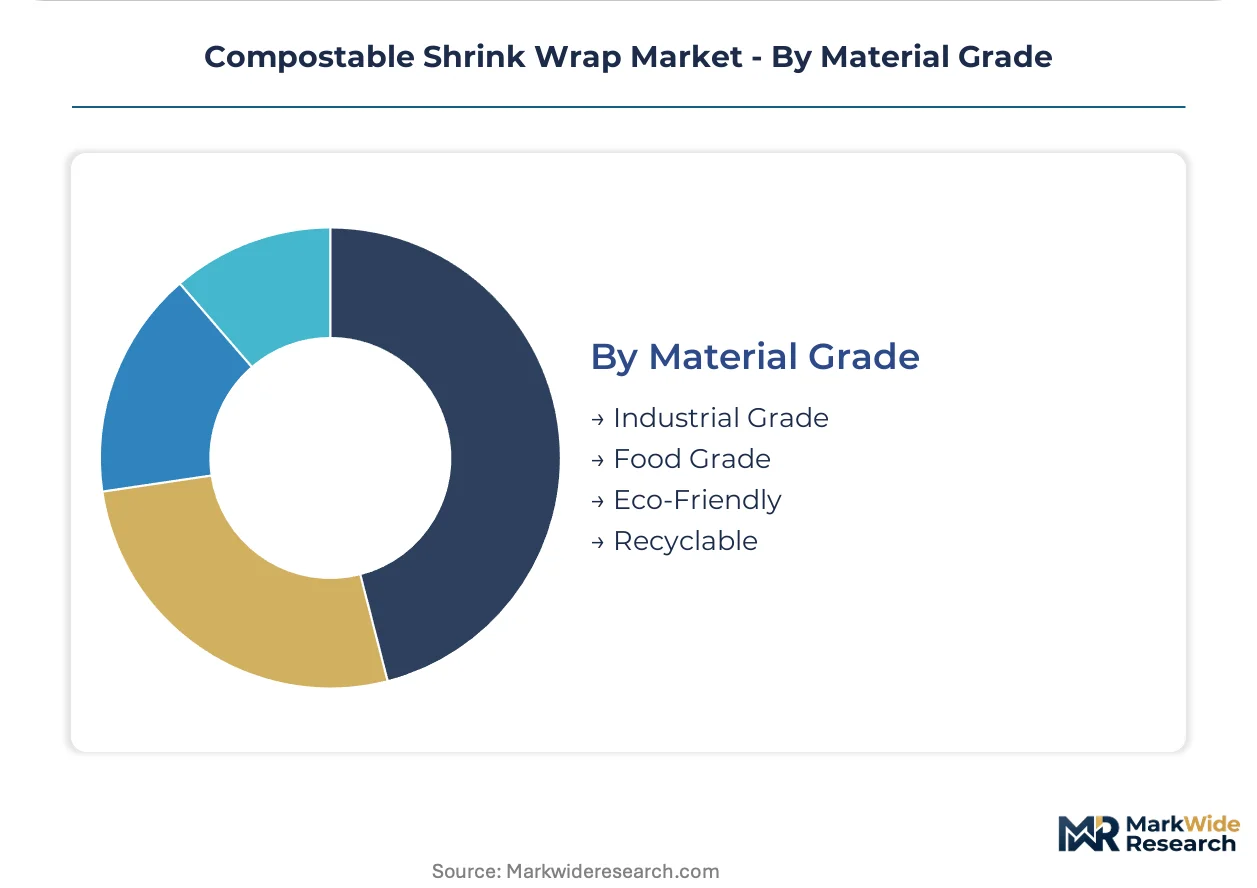
Material Grade:
Certification tier and intended contact level determine formulation complexity and validation burden.
- Food Grade:REACH-compliant additives and full migration profile disclosure are mandatory for EU market access. ECHA enforcement has restructured supply chains to exclude non-registered plasticizers and slip agents, elevating formulation costs.
- Industrial Grade:Bundling and palletization applications tolerate broader additive portfolios where food contact is absent.
- Eco-Friendly:Home-composting claims face standard fragmentation across jurisdictions, creating labeling uncertainty that restrains retailer stocking decisions.
- Recyclable:Designs compatible with both industrial composting and anaerobic digestion capture dual-endpoint premiums in Netherlands and Belgium municipal waste programs.
Food grade dominates premium positioning; recyclable grades are climbing the fastest as municipalities expand organic waste collection infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium film volumes through mature composting infrastructure, while the United States lags in unified home-composting standards despite substantial food packaging demand. This divergence shapes supplier certification strategies across both markets. Industrial composting density and regulatory stringency determine regional competitive positioning.
Germany
Meal-kit services and supermarket chains anchor demand through mandated supplier compliance with industrial compostability protocols. The country's national packaging regulator enforces strict verification under EU Packaging and Packaging Waste Regulation amendments. The Rhine-Ruhr industrial corridor concentrates blown-film extrusion capacity serving pan-European retail networks.
United States
Food retailers and produce distributors drive procurement consolidation around ASTM D6400 certified alternatives. FDA food-contact substance regulations under 21 CFR elevate technical barriers for bio-based additive formulations. California's organic waste collection mandates in the Bay Area and Central Valley create localized demand validation zones.
France
Premium meat and cheese packagers adopt multilayer biofilm structures for modified-atmosphere applications demanding extended shelf life. ECHA REACH compliance enforcement mandates full additive migration profile disclosure for EU market access. The Lyon-Grenoble polymer science cluster advances nanocellulose reinforcement research for barrier enhancement.
Netherlands
Municipal organic waste programs expanding biogas extraction capacity create dual-endpoint demand for anaerobic digestion compatible films. The country's environmental agency coordinates with Belgian regulators on cross-border composting standard harmonization. The Rotterdam-Antwerp port complex facilitates bio-polymer import and distribution logistics.
Italy
Private-label retail branding applications accelerate as sustainability claims drive supermarket differentiation strategies. National composting consortiums certify industrial facilities under evolving EU harmonized standards. The Emilia-Romagna packaging belt integrates film conversion with fresh produce logistics for export markets.
Compostable Shrink Wrap Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification tiers and material chemistries. The supplier base concentrates around compounders with captive polymerization assets and in-house validation capabilities. Three archetypes dominate: vertically integrated polymer producers controlling raw material through finished film, specialized bio-based formulation houses, and integrated paper-polymer converters leveraging fiber supply chains. Competitive moves center on certification pre-emption and direct supply contract capture with retail consolidators.
Within the polymer science tier, BASF SE anchors European supply of certified compostable films through its Ludwigshafen-based operations. NatureWorks LLC exemplifies the bio-based specialist archetype with PLA formulation expertise. Mondi Group occupies a position bridging paper and polymer integration for industrial-grade segments. These three entities represent distinct strategic postures: petrochemical diversification into bio-feedstocks, renewable feedstock pure-play focus, and fiber-based packaging convergence.
| Leading Market Players |
|---|
| BASF SE |
| Amcor |
| International Paper Company |
| Mondi Group |
| Smurfit Kappa Group |
| Kingfa Science & Technology |
| NatureWorks LLC |
| Sealed Air |
| Tetra Pak International |
| Others |
Value Network & Pricing Analysis
Caprolactam price volatility cascades through bio-polyamide feedstock tiers, compressing margins for compounders lacking long-term monomer contracts and forcing three-tier pricing stratification across premium certified, standard industrial, and economy unverified film grades.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for ASTM D6400 certified films, while unvalidated Asian imports pressure mid-tier positioning. Certification grade and volume scale drive price differentiation, with food-contact REACH compliance commanding substantial premiums over industrial bundling grades. Cost compression in standard tiers intensifies as supermarket private-label consolidation squeezes converter margins. Small regional converters exhibit highest price sensitivity; multinational meal-kit services absorb premium positioning with documented chain-of-custody requirements.
Supply Chain Analysis
Freight cost differentials between Rotterdam-Antwerp port entry and inland European conversion centers favor compounders with captive polymerization near industrial composting clusters. Supply concentrates in Germany, the Netherlands, and France, drawing from corn-derived PLA feedstocks, cellulose pulp, and bio-polyamide resins. Single-source vulnerability runs through lactic acid fermentation capacity concentrated with NatureWorks LLC and select European biorefiners. Distribution runs through vertically integrated film producers with in-house certification capabilities, displacing fragmented converter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as EU Packaging and Packaging Waste Regulation amendments tighten single-use plastic restrictions, embedding compostable alternatives into supermarket procurement mandates.
For Market Incumbents: Acquire anaerobic digestion compatible formulation IP to capture dual-endpoint premiums in Netherlands and Belgium municipal waste programs. BASF SE and Mondi Group should extend backward integration into lactic acid fermentation to secure bio-monomer supply against caprolactam volatility. Certification investment in home-composting standards hedges against regulatory fragmentation. For New Entrants and Emerging Players: Launch via direct-to-farm supply contracts with produce distributors bypassing converter intermediaries. Pharmaceutical unit-dose packaging presents the most penetrable white-space, with blister pack and medical device applications untapped by current biofilm suppliers. Target anaerobic digestion compatibility as the primary go-to-market angle for Benelux market entry. For Investors and Strategic Acquirers: Asymmetric upside sits with bio-based formulation houses possessing captive nanocellulose reinforcement capabilities and in-house REACH validation infrastructure. Five-to-ten year viability hinges on polymer science talent pipelines scaling at technical universities. Monitor ECHA enforcement intensity on bio-based additive migration profiles as the inflection signal for supply chain restructuring velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactic Acid Fermentation | Captive bio-monomer supply insulates margins from petrochemical derivative volatility. |
| Anaerobic Digestion Compatibility Certification | Dual-endpoint validation captures premiums in Netherlands and Belgium biogas programs. |
| Direct-to-Farm Supply Contract Capture | Channel compression with produce distributors secures margin and documentation integrity. |
| Nanocellulose Reinforcement R&D Investment | Oxygen transmission below 1 cc/m²/day displaces EVOH barriers in modified-atmosphere meat packaging. |
| Home-Composting Standard Pre-emption | Early certification hedges against ASTM/ISO protocol fragmentation across jurisdictions. |
Research Methodology
Bottom-up food packaging procurement modeling reconciled against top-down polymer compounding capacity tracking forms the analytical core. Primary interviews with blown-film extrusion plant managers, supermarket category buyers, meal-kit supply chain directors, and ECHA regulatory affairs specialists combined with secondary validation from EU Packaging and Packaging Waste Regulation amendment texts, ASTM D6400 certification databases, and customs trade data on bio-polyamide resin flows.
Input-output matrices map PLA and bio-polyamide resin availability through conversion capacity to end-use demand across food packaging, consumer goods, and retail branding segments. Segmentation dimensions include material chemistry tier, certification grade, composting infrastructure compatibility, and regional regulatory cluster. CAGRs derive from penetration rate modeling against industrial composting facility expansion trajectories, with sensitivity analysis on caprolactam price corridors and REACH compliance cost pass-through assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under home-composting standard fragmentation or accelerated anaerobic digestion infrastructure deployment. Forecasts reflect documented assumptions on EU regulatory enforcement timelines and bio-monomer supply expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Biodegradable Packaging Materials Market
Biodegradable Packaging
Biodegradable Lidding Films Market
Biodegradable Packaging
India Biodegradable Tableware & Packaging Products Market
Biodegradable Packaging
Clear Bioplastics Packaging Market
Biodegradable Packaging
Biodegradable Packaging Products Market
Biodegradable Packaging
Biodegradable Water Bottles Market
Biodegradable Packaging
Global Biodegradable Tableware Market
Biodegradable Packaging
Biopolymer Packaging Market
Biodegradable Packaging
Biodegradable Plastic Packaging Market
Biodegradable Packaging
North America Biodegradable Film Market
Biodegradable Packaging
Biodegradable Packing Peanuts Market
Biodegradable Packaging
Biodegradable Food Packaging Market
Biodegradable Packaging
Europe Biodegradable Cups Market
Biodegradable Packaging
Biofoam Packaging Market
Biodegradable Packaging
Bioplastic Packaging Bag Market
Biodegradable Packaging
Botanical Packaging Market