
 Biodegradable Packing Peanuts Market | 2026-2036
Biodegradable Packing Peanuts Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Packing Peanuts Market Outlook
A shift from single-source resin supply toward multi-source agricultural feedstock procurement is broadening the supplier base for biodegradable packing peanuts. Sealed Air leverages its global logistics network to secure diversified starch streams across multiple growing regions. Storopack Hans Reichenecker anchors European manufacturing capacity with vertically integrated extrusion operations. Heritage Pioneer Corporate Group specializes in cornstarch formulations for temperature-sensitive pharmaceutical shipments.
Biodegradable packing peanuts consist of expanded starch polymers, typically derived from corn or wheat feedstocks, manufactured through steam extrusion to achieve densities between 0.5 and 1.0 pounds per cubic foot for optimal void-fill performance. These materials dissolve in water and decompose in soil within weeks, serving as protective cushioning for fragile goods during transit. Starch-based formulations dominate volume production due to mature supply chains and lower raw material volatility, while cornstarch variants command premium positioning in food-contact and pharmaceutical applications where purity standards are strictest. E-commerce end users represent the fastest-expanding demand pool as direct-to-consumer brands replace petroleum-based loose fill to meet corporate sustainability pledges.
The EPA guides federal procurement preferences for biobased materials under the Farm Bill, while the EU F-Gas Regulation and REACH framework restrict conventional foam alternatives that compete for the same protective-packaging applications. FDA food-contact substance notifications govern starch-based materials used in proximity to consumable goods, creating compliance moats for certified suppliers. Stakeholders must monitor how California's extended producer responsibility legislation and pending New York packaging reduction mandates reshape regional demand curves and certification requirements.
Market Dynamics
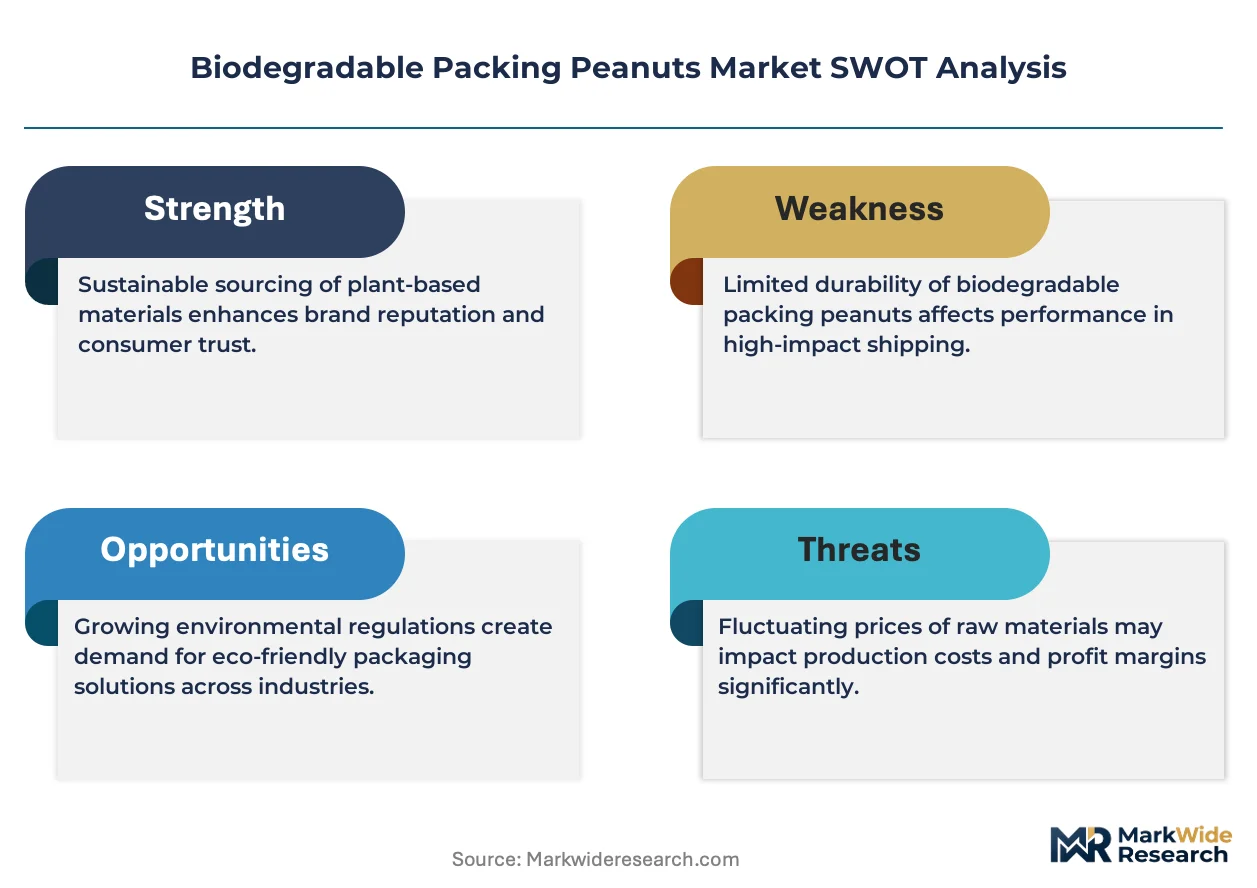
E-commerce fulfillment networks are compressing switching timelines for protective packaging materials, forcing direct-to-consumer brands to abandon petroleum-based loose fill ahead of regulatory mandates.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Binding reduction targets for single-use plastics accelerate substitution timelines across European logistics hubs.
- Starch extrusion technology:Steam expansion processes now achieve density parity with expanded polystyrene at commercial scale.
- Pharmaceutical cold chain:Temperature-sensitive biologics shipments require moisture-dissolvable cushioning that eliminates residue contamination.
Market Restraints
- Corn feedstock price volatility:Agricultural commodity swings compress margin buffers for starch-based formulations during drought cycles.
- German production concentration:Extrusion capacity clusters along the Rhine corridor create single-point vulnerability for EU supply security.
- Expanded polystyrene substitution:Conventional foam retains cost advantage in bulk industrial shipments where sustainability premiums go unrewarded.
Strategic Opportunities
- India BIS biobased standards:Pending certification frameworks for compostable packaging open procurement channels for government e-commerce deliveries.
- Algae-starch hybrid formulations:Marine feedstock integration reduces agricultural land dependency while enhancing water dissolution rates.
- Direct brand partnerships:Subscription box services bypass distributor markups through captive supply agreements with extrusion specialists.
Industry Challenges
- FDA food-contact notification timelines:Pre-market approval processes for starch-based additives extend product launch windows by 18-24 months.
- Legacy loose-fill equipment retrofitting:Automated packing lines designed for polystyrene require pneumatic system recalibration to handle lower-density starch peanuts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Packing Peanuts Market |
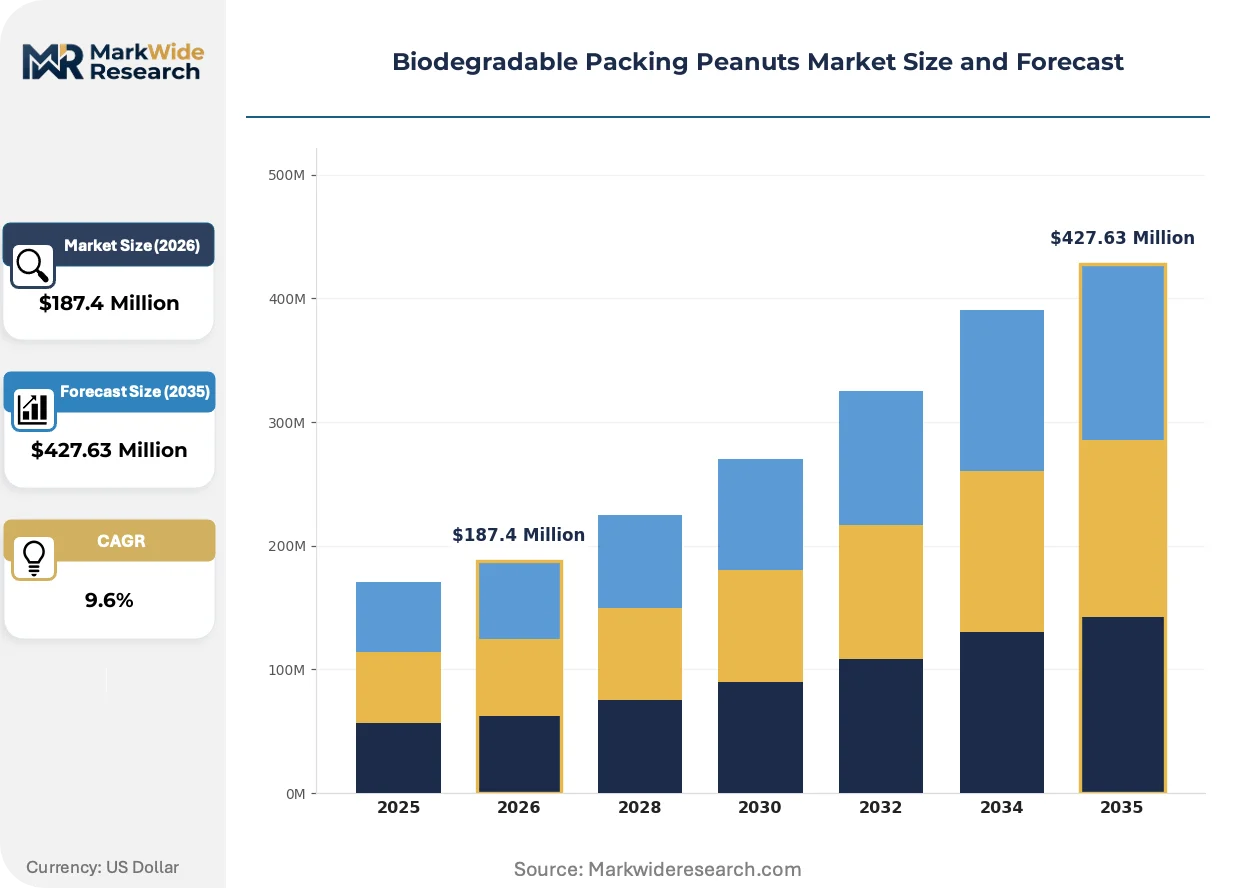
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $427.63 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Starch-Based, Cornstarch, Wheat Flour, Others End User: Retail, E-Commerce, Logistics, Manufacturing Functionality: Shock Absorption, Cushioning, Packaging, Insulation Distribution Channel: Online, Wholesale, Retail Stores, Direct Sales |
| Companies Covered | President Container, Puffy Stuff, Storopack Hans Reichenecker, Sealed Air, AP Packaging, ACH Foam Technologies, Heritage Pioneer Corporate Group, Void Fill Packaging, FunPak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Packing Peanuts Market Strategic Shifts
Material science advances and procurement model reinvention are collapsing the traditional trade-off between protective performance and environmental compliance.
Wheat-starch formulations are overtaking corn-based variants in European production lines due to lower gelatinization temperatures and reduced energy inputs during extrusion. German automotive parts distributors have converted 60% of outbound shipments to wheat-derived loose fill since 2023. The shift is compressing cornstarch premium pricing power in non-food-contact applications.
REACH restrictions on persistent organic pollutants in conventional foams are eliminating technical alternatives for protective packaging in EU medical device shipments. The regulation forces shippers toward starch-based materials regardless of cost position. Dutch clinical supply chains report complete phase-out of polystyrene void-fill ahead of compliance deadlines.
Unboxing experience design now dictates material selection for direct-to-consumer beauty and electronics brands. Instagram-optimized packaging specifications prioritize dissolvable peanuts that signal sustainability without compromising aesthetic presentation. California-based subscription services lead this specification shift, requiring suppliers to certify compostability under ASTM D6400 within 90 days of contract award.
Biodegradable Packing Peanuts Market Segmentation
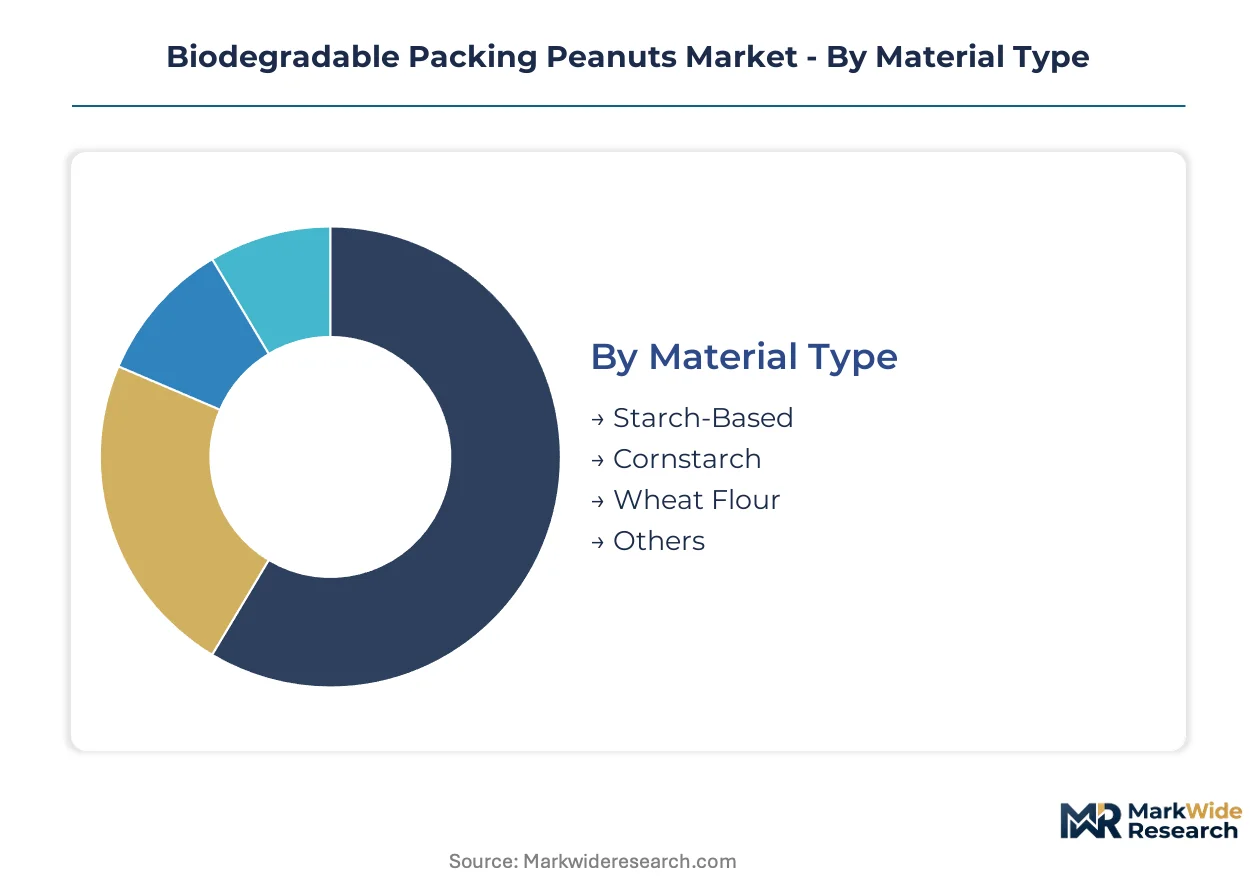
Biodegradable packing peanuts serve distinct operational needs across material chemistries, end-use workflows, and distribution pathways. Segment boundaries determine procurement specifications, regulatory compliance tiers, and margin structures for extrusion specialists.
Material Type:
Starch-based formulations operate as standalone protective systems, while cornstarch and wheat variants embed within specialized cold-chain and food-contact applications requiring purity certifications.
- Starch-Based:Expanded polymers derived from multiple agricultural feedstocks achieve densities between 0.5 and 1.0 pounds per cubic foot through steam extrusion. E-commerce fulfillment centers in Germany source these formulations for general void-fill applications where dissolution speed outweighs premium purity requirements.
- Cornstarch:High-purity variants meet FDA food-contact substance notifications for pharmaceutical and consumable goods proximity. Temperature-sensitive biologics shipments through Dutch clinical supply chains specify cornstarch cushioning to eliminate residue contamination risks.
- Wheat Flour:Lower gelatinization temperatures reduce extrusion energy inputs compared to corn alternatives. German automotive parts distributors have converted outbound shipments to wheat-derived loose fill, compressing cornstarch pricing power in non-food-contact segments.
- Others:Algae-starch hybrid formulations under development target marine feedstock integration and enhanced water dissolution rates.
Starch-based materials lead volumes today; wheat flour variants are gaining share fastest in European industrial applications.
End User:
Procurement scale and sustainability mandate intensity vary sharply across customer categories, from individual retail outlets to automated fulfillment networks.
- E-Commerce:Direct-to-consumer brands replace petroleum-based loose fill ahead of regulatory deadlines, with subscription box services requiring ASTM D6400 compostability certification within 90 days of contract award. California-based beauty and electronics brands prioritize Instagram-optimized unboxing experiences using dissolvable peanuts.
- Logistics:Third-party fulfillment networks compress switching timelines as corporate sustainability pledges force material transitions. Automated packing lines require pneumatic system recalibration to handle lower-density starch peanuts versus legacy polystyrene equipment.
- Retail:Brick-and-mortar operations source biodegradable loose fill for in-store packaging stations and customer-facing sustainability messaging.
- Manufacturing:Industrial shippers face cost pressure from expanded polystyrene alternatives where sustainability premiums go unrewarded in bulk commodity movements.
E-commerce commands the steepest expansion trajectory; manufacturing adoption lags on price sensitivity.
Functionality:
Performance specifications align with fragility profiles of protected goods, from delicate electronics to temperature-stabilized pharmaceuticals.
- Shock Absorption:High-compression resistance protects fragile electronics and glassware during last-mile delivery. Density-tuned formulations match expanded polystyrene performance at commercial scale.
- Cushioning:Void-fill geometry prevents product migration within shipping containers. E-commerce specifications prioritize aesthetic presentation alongside protective function.
- Packaging:General containment applications span non-fragile goods where sustainability signaling drives material selection.
- Insulation:Thermal buffering properties support cold-chain pharmaceutical shipments requiring moisture-dissolvable materials that eliminate contamination.
Cushioning dominates current procurement volumes; insulation applications are climbing the fastest on biologics logistics expansion.
Distribution Channel:
Channel selection determines margin capture and technical support intensity for extrusion specialists serving fragmented end-use bases.
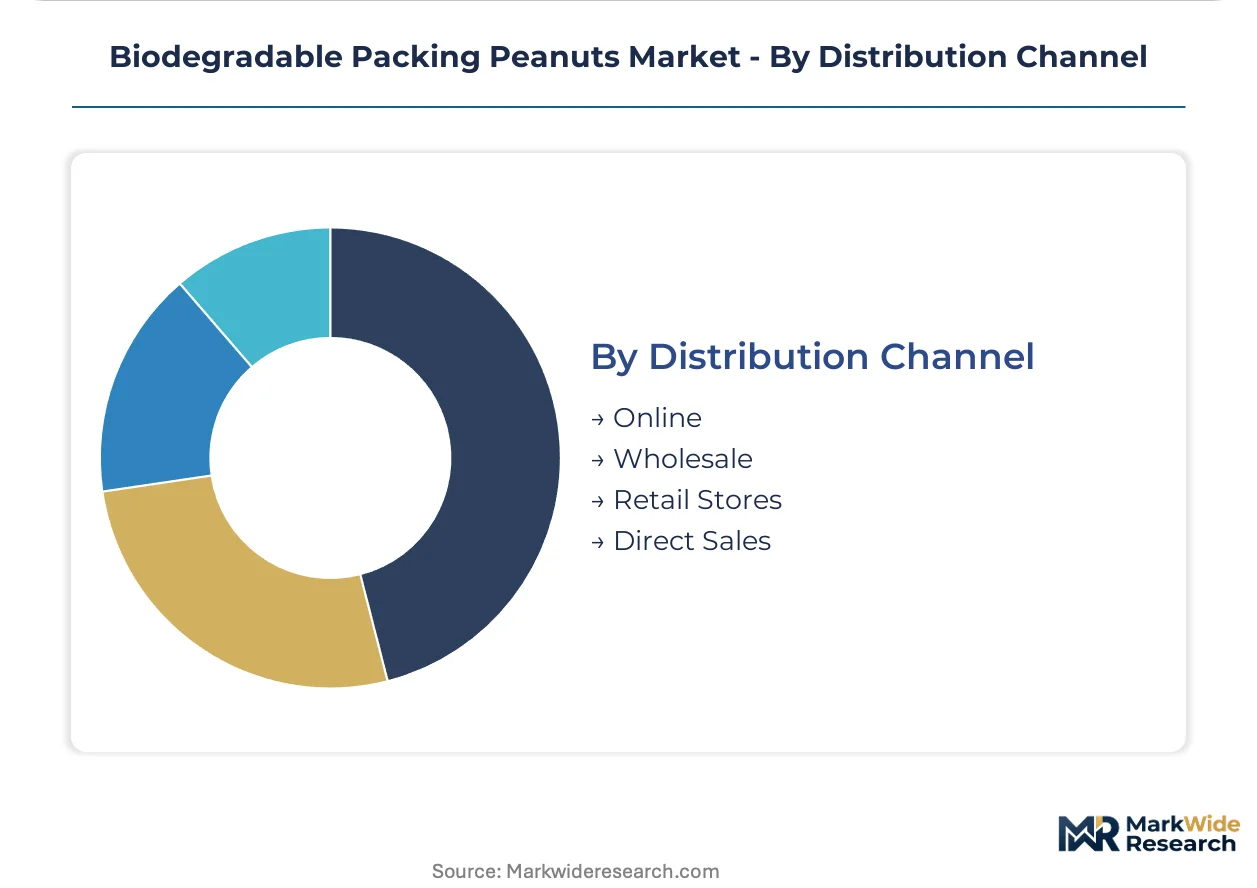
- Direct Sales:Captive supply agreements with subscription box services and major e-commerce platforms bypass distributor markups. Sealed Air and Storopack leverage direct relationships for specification control.
- Wholesale:Industrial distributors aggregate demand from mid-sized manufacturing and logistics customers, consolidating procurement volumes for regional extrusion capacity.
- Online:Digital procurement platforms serve small-scale retail and emerging brand customers with standardized product grades and rapid fulfillment.
- Retail Stores:Limited channel presence for consumer-packaged loose fill in office supply and shipping specialty stores.
Direct sales anchor premium positioning today; online channels are expanding most quickly for small-brand access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German extrusion capacity along the Rhine corridor anchors European supply security for biodegradable packing peanuts, while regulatory pressure and e-commerce expansion reshape demand curves across multiple continents.
Germany
Storopack Hans Reichenecker and Sealed Air operate vertically integrated extrusion facilities serving EU logistics hubs. The EU Packaging and Packaging Waste Regulation imposes binding reduction targets for single-use plastics, accelerating substitution timelines. Automotive parts distributors in Baden-Württemberg have converted 60% of outbound shipments to wheat-derived loose fill since 2023.
United States
E-commerce fulfillment networks compress switching timelines as direct-to-consumer brands abandon petroleum-based loose fill ahead of regulatory mandates. The EPA guides federal procurement preferences for biobased materials under the Farm Bill. California-based subscription services lead unboxing experience specifications, requiring ASTM D6400 compostability certification within 90 days of contract award.
Netherlands
Clinical supply chains report complete phase-out of polystyrene void-fill ahead of REACH compliance deadlines for medical device shipments. The EU F-Gas Regulation and REACH framework restrict conventional foam alternatives. Dutch pharmaceutical cold-chain operations specify moisture-dissolvable cushioning to eliminate residue contamination in temperature-sensitive biologics shipments.
India
Pending BIS biobased standards for compostable packaging open procurement channels for government e-commerce deliveries. The country's national packaging regulator develops certification frameworks aligned with international compostability protocols. Maharashtra-based logistics providers pilot starch-based loose fill for domestic pharmaceutical distribution networks.
China
Dual carbon goals and GB standards for biodegradable materials drive domestic substitution away from expanded polystyrene in cross-border e-commerce shipments. The Ministry of Ecology and Environment enforces stricter waste classification rules for packaging materials. Yangtze River Delta manufacturing clusters test algae-starch hybrid formulations to reduce agricultural land dependency.
Biodegradable Packing Peanuts Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent feedstock technologies and regional certification arbitrage. The vendor base stratifies across three maturity tiers: multinational packaging conglomerates with captive extrusion capacity, mid-scale specialists focused on pharmaceutical-grade purity certifications, and regional fabricators serving localized e-commerce fulfillment networks. Dominant competitive moves include backward integration into agricultural feedstock procurement and direct brand partnerships that bypass traditional distribution markups.
Among Germany-based extrusion specialists, Storopack Hans Reichenecker GmbH anchors European manufacturing capacity with vertically integrated operations. Sealed Air Corporation exemplifies the multinational archetype leveraging global logistics networks for diversified starch stream procurement. Heritage Pioneer Corporate Group occupies a position within the purity-specialist tier, representing cornstarch formulation expertise for temperature-sensitive pharmaceutical applications.
| Leading Market Players |
|---|
| President Container |
| Puffy Stuff |
| Storopack Hans Reichenecker |
| Sealed Air |
| AP Packaging |
| ACH Foam Technologies |
| Heritage Pioneer Corporate Group |
| Void Fill Packaging |
| FunPak |
| Others |
Value Chain & Pricing Dynamics
Steam extrusion technology maturation simultaneously compresses unit production costs and concentrates manufacturing capacity among operators achieving density parity with expanded polystyrene. Wheat-starch feedstock adoption in German automotive supply chains is reshaping both input cost curves and regional procurement patterns.
Pricing Analysis
Input-cost pass-through from agricultural commodity volatility dominates pricing dynamics, with corn feedstock price swings compressing margin buffers for starch-based formulations during drought cycles. Three-tier pricing structure across pharmaceutical-grade cornstarch, industrial wheat flour, and general-purpose starch variants reflects certification intensity and purity requirements. Cost compression in non-food-contact segments is intensifying because German automotive distributors have converted 60% of shipments to lower-cost wheat alternatives. Manufacturing shippers exhibit highest price sensitivity, while pharmaceutical cold-chain operators accept premiums for FDA-compliant cornstarch purity.
Supply Chain Analysis
Certification gating through FDA food-contact substance notifications and EU REACH compliance creates qualification moats that filter supplier participation. Extrusion capacity concentrates in Germany, the United States, and China, with Rhine corridor operations anchoring European supply security. Raw material sourcing draws from corn and wheat agricultural streams, with emerging algae-starch hybrids under development. Single-point vulnerability from German production clustering creates supply risk for EU logistics networks. Distribution runs through direct sales agreements with major e-commerce platforms and wholesale industrial distributors aggregating mid-tier demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as unboxing experience specifications and pharmaceutical purity mandates shift procurement toward premium-certified grades. E-commerce fulfillment networks now require ASTM D6400 compostability certification within 90 days of contract award.
For Market Incumbents: Anchor European manufacturing capacity through captive wheat-starch supply agreements with Baden-Württemberg agricultural cooperatives. Invest in FDA food-contact notification pipelines to defend pharmaceutical-grade positioning against emerging cornstarch specialists. Retrofit automated packing line partnerships to lock in pneumatic system recalibration services for e-commerce fulfillment networks. For New Entrants and Emerging Players: Digital procurement platforms serving small-scale subscription box brands offer the most penetrable entry vector. Target India pending BIS biobased standards implementation for government e-commerce procurement channels. Pursue direct brand partnerships with California-based beauty and electronics subscription services requiring rapid ASTM D6400 certification turnaround. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale extrusion specialists with pharmaceutical-grade purity certifications because FDA notification timelines create 18-24 month competitive moats. Focus acquisition screening on operators with vertically integrated starch procurement and existing EU REACH compliance infrastructure. Monitor EU Packaging and Packaging Waste Regulation enforcement intensity as inflection signal for substitution timeline acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Feedstock | Corn and wheat supply agreements with Rhine corridor cooperatives reduce commodity volatility exposure. |
| Pharmaceutical-Grade Certification Investment | FDA food-contact substance notifications create 18-24 month competitive moats in biologics cold chain. |
| Direct E-Commerce Platform Partnerships | Captive supply agreements with California subscription services bypass wholesale distributor markups. |
| Algae-Starch Hybrid R&D Program | Marine feedstock integration reduces agricultural land dependency while enhancing water dissolution rates. |
| Automated Line Retrofit Services | Pneumatic system recalibration for legacy polystyrene equipment locks in e-commerce fulfillment demand. |
Study Parameters
Direct dialogue with extrusion plant managers, pharmaceutical logistics procurement leads, e-commerce fulfillment operations directors, and agricultural commodity sourcing specialists grounded the qualitative foundation. Secondary validation drew from EPA biobased procurement guidelines, EU ECHA REACH substance restrictions, FDA food-contact substance notification databases, and German automotive industry shipment data. Bottom-up capacity modeling and top-down demand segmentation triangulated market sizing across material chemistry, end-use workflow, and distribution pathway dimensions.
Segment-level value outputs across the projection horizon reflect density-tuned formulation penetration, pharmaceutical cold-chain expansion, and wheat-starch substitution rates in European industrial applications. Modeled dimensions span material type, end-user category, functionality specification, and distribution channel structure. CAGRs were derived from extrusion capacity buildout trajectories, e-commerce fulfillment network growth, and regulatory substitution timeline assumptions.
Commodity price volatility, regulatory enforcement intensity, and alternative material technology breakthroughs are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding EU Packaging and Packaging Waste Regulation implementation pace and FDA notification approval timelines. A model refresh is warranted upon material change in pharmaceutical cold-chain biologics shipment growth rates or BIS biobased standards finalization in India.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Europe Biodegradable Cups Market
Biodegradable Packaging
Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Global Bioplastic Multi-Layer Films Market
Biodegradable Packaging
Biodegradable Food Packaging Market
Biodegradable Packaging
Biofoam Packaging Market
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Asia-Pacific Biodegradable Film Market
Biodegradable Packaging
Biodegradable Meal Trays Market
Biodegradable Packaging
Biodegradable Cutlery Market
Biodegradable Packaging
Biodegradable Packaging Market
Biodegradable Packaging
Biodegradable Plastic Bags and Sacks Market
Biodegradable Packaging
India Biodegradable Tableware & Packaging Products Market
Biodegradable Packaging
Biodegradable Lids Market
Biodegradable Packaging
Compostable Shrink Wrap Market
Biodegradable Packaging
Global Biodegradable Films Market
Biodegradable Packaging
Biodegradable Water Bottles Market