
 Middle East and Africa Biodegradable Film Market | 2026-2036
Middle East and Africa Biodegradable Film Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Biodegradable Film Market Foresight
The EU Green Deal's extraterritorial supply chain standards is pivoting export-oriented packaging producers across North Africa toward certified compostable substrates. BASF SE leverages its Ludwigshafen polymer research network to supply PLA masterbatch formulations to Egyptian converters. Taghleef Industries Group anchors regional flexible packaging capacity through its Dubai manufacturing hub, while BioBag International specializes in home-compostable bag structures for South African retail chains.
Biodegradable film denotes polymeric sheet materials engineered to undergo microbial decomposition into carbon dioxide, water, and biomass under specified composting conditions, typically achieving complete disintegration within 180 days in industrial aerobic environments. These films function primarily as temporary protective or containment layers that eliminate persistent plastic accumulation in agricultural soils, marine ecosystems, and landfill sites. Starch-based formulations dominate volume production due to feedstock proximity from Sub-Saharan maize processing, whereas PLA commands premium positioning in food-contact applications requiring clarity and heat resistance. Agricultural films represent the fastest-expanding application segment as drip-irrigation and greenhouse operators in Israel and Morocco substitute conventional polyethylene mulch with soil-biodegradable alternatives.
South Africa's National Regulator for Compulsory Specifications enforces biodegradability testing protocols aligned with ISO 17088, while the Saudi Standards, Metrology and Quality Organization (SASO) implements technical regulations for single-use plastic alternatives in the Kingdom. Egypt's Environmental Affairs Agency is developing compostability certification requirements for imported film products. Stakeholders must monitor harmonization gaps between national standards and EU REACH compliance to avoid customs detention and secure preferential trade access.
Market Dynamics
South Africa's extended producer responsibility regulations and Egypt's emerging compostability certification requirements are compressing procurement timelines and forcing converters to pre-qualify suppliers against ISO 17088 protocols before contract award.
Growth Catalysts
- EU Green Deal extraterritoriality:Export-oriented packaging producers across North Africa are pivoting toward certified compostable substrates to maintain preferential trade access to European markets.
- Arid-climate agricultural innovation:Drip-irrigation and greenhouse operators in Israel and Morocco are substituting conventional polyethylene mulch with soil-biodegradable alternatives at accelerating rates.
- Starch feedstock proximity:Sub-Saharan maize processing clusters provide regional converters with cost-advantaged raw material access for volume biodegradable film production.
Market Restraints
- PLA resin import dependency:Regional converters rely on European and Asian polymer suppliers, exposing margins to freight cost volatility and currency fluctuation.
- Industrial composting infrastructure gaps:Limited aerobic digestion capacity in secondary Gulf Cooperation Council cities restricts end-of-life assurance for certified compostable packaging.
- Conventional polyethylene price anchoring:Fossil-based film alternatives maintain 40-60% cost advantages in bulk agricultural applications, slowing substitution in price-sensitive segments.
Strategic Opportunities
- Saudi Arabian retail channel expansion:SASO technical regulations for single-use plastic alternatives are creating mandated demand windows for home-compostable bag structures in supermarket chains.
- Soil-degradable mulch film standardization:Harmonization between national standards and EU REACH compliance protocols would unlock customs clearance efficiencies for Egyptian and Moroccan exporters.
- Greenhouse agriculture technology convergence:Integration of biodegradable mulch films with precision irrigation systems is creating bundled solution opportunities for Israeli agritech providers.
Industry Challenges
- Compostability certification timeline compression:Egyptian converters face 12-18 month validation cycles for imported film products under developing Environmental Affairs Agency protocols.
- Technical talent scarcity in polymer formulation:Regional masterbatch development capabilities concentrate in South African and UAE technical centers, creating recruitment bottlenecks for scaling operations.
- Legacy polyethylene equipment retrofit costs:Existing blown film lines require screw and die modifications to process starch-based formulations at commercial yields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Biodegradable Film Market |
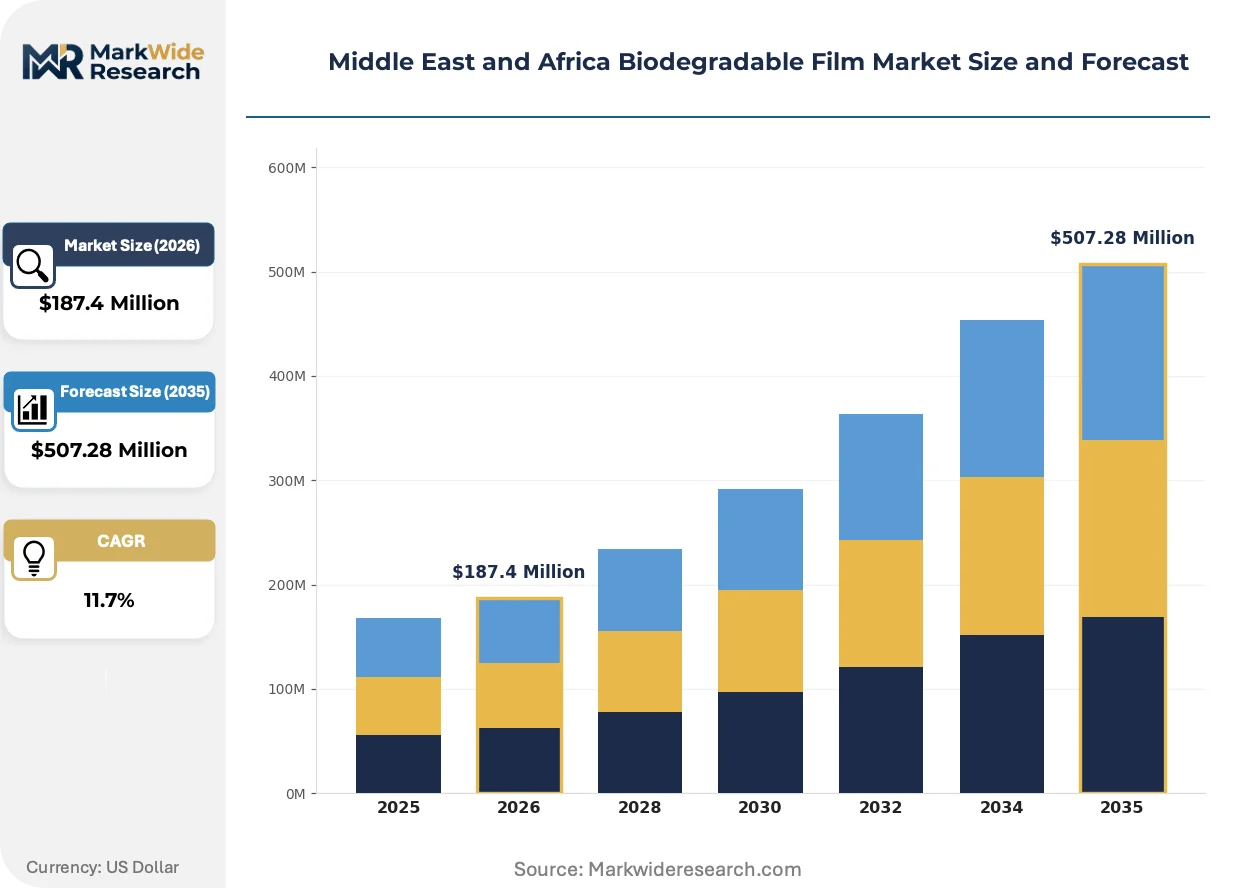
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
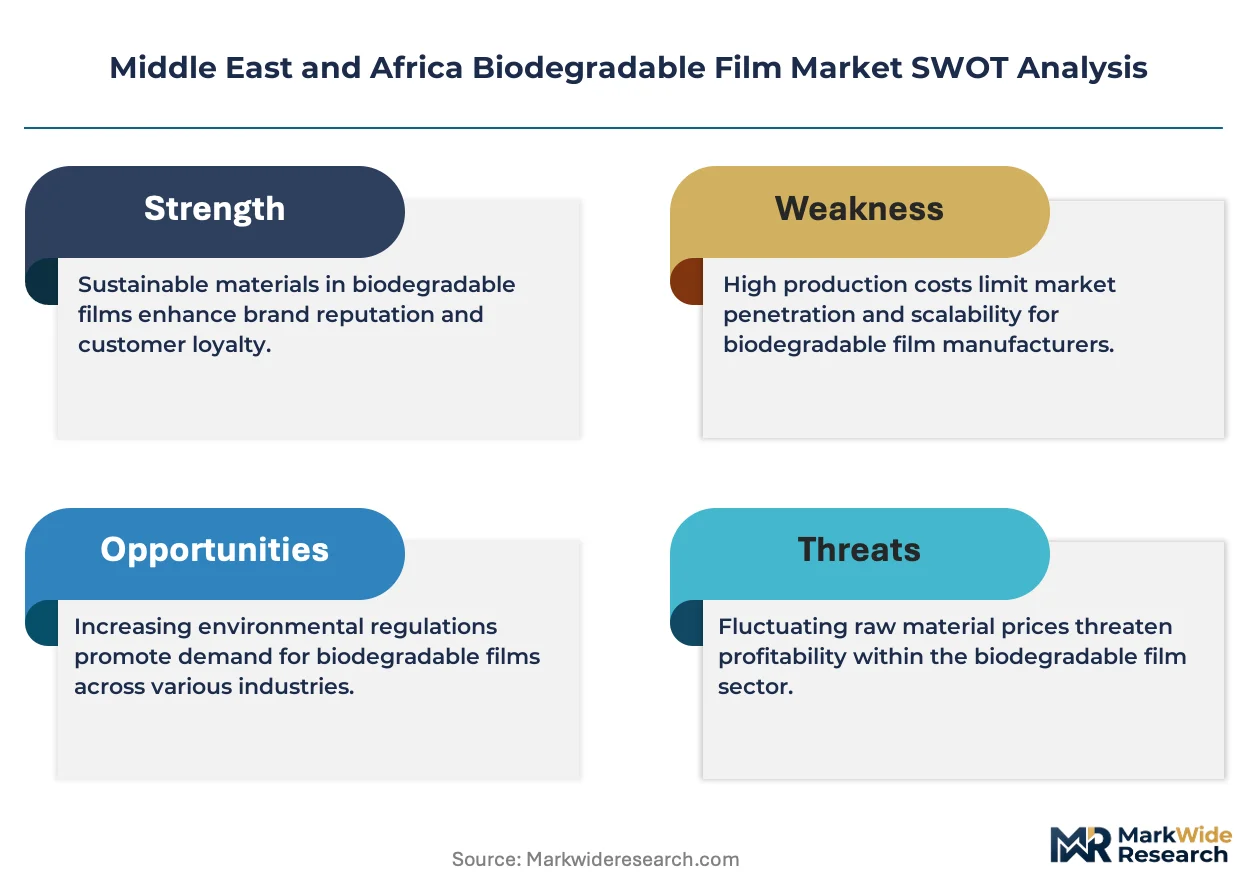
| Segmentation | Type: Starch-Based, Cellulose-Based, PLA, PHA Application: Agricultural Films, Packaging Films, Food Service, Waste Management End User: Food Industry, Agriculture, Consumer Goods, Retail Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | BASF SE, Taghleef Industries Group, Clondalkin Group, BioBag International, Plastchim-T, TIPA Ltd, Cortec Corporation, Kingfa Technology, Futamura, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Biodegradable Film Market Shifts & Advancements
Material science advances and regulatory harmonization efforts are converging to reshape competitive positioning across the biodegradable film value chain. Three developments merit particular attention.
Multilayer coextrusion technology incorporating PLA outer skins with starch-based core layers is absorbing premium food-contact volume previously captured by conventional laminated structures. Israeli dairy and fresh produce packagers are adopting these formulations for thermoformed trays and lidding films, compressing the clarity and heat-resistance gap that historically protected fossil-based alternatives in refrigerated supply chains.
SASO technical regulations for single-use plastic alternatives are mandating biodegradability testing protocols across Saudi Arabian retail and foodservice distribution. The industrial consequence is a supplier pre-qualification surge, with converters demanding third-party certification documentation before contract execution. Food-contact flexible packaging represents the most affected category, with domestic and regional suppliers accelerating ISO 17088 alignment investments.
Retail procurement committees in South African supermarket chains are embedding compostability certification into supplier scorecards alongside price and logistics performance metrics. This behavioral shift is displacing conventional tender-based sourcing with multi-year partnership frameworks that lock in volume commitments for certified film suppliers. The change is most visible in Cape Town and Johannesburg metropolitan distribution networks serving premium consumer segments.
Middle East and Africa Biodegradable Film Market Segmentation
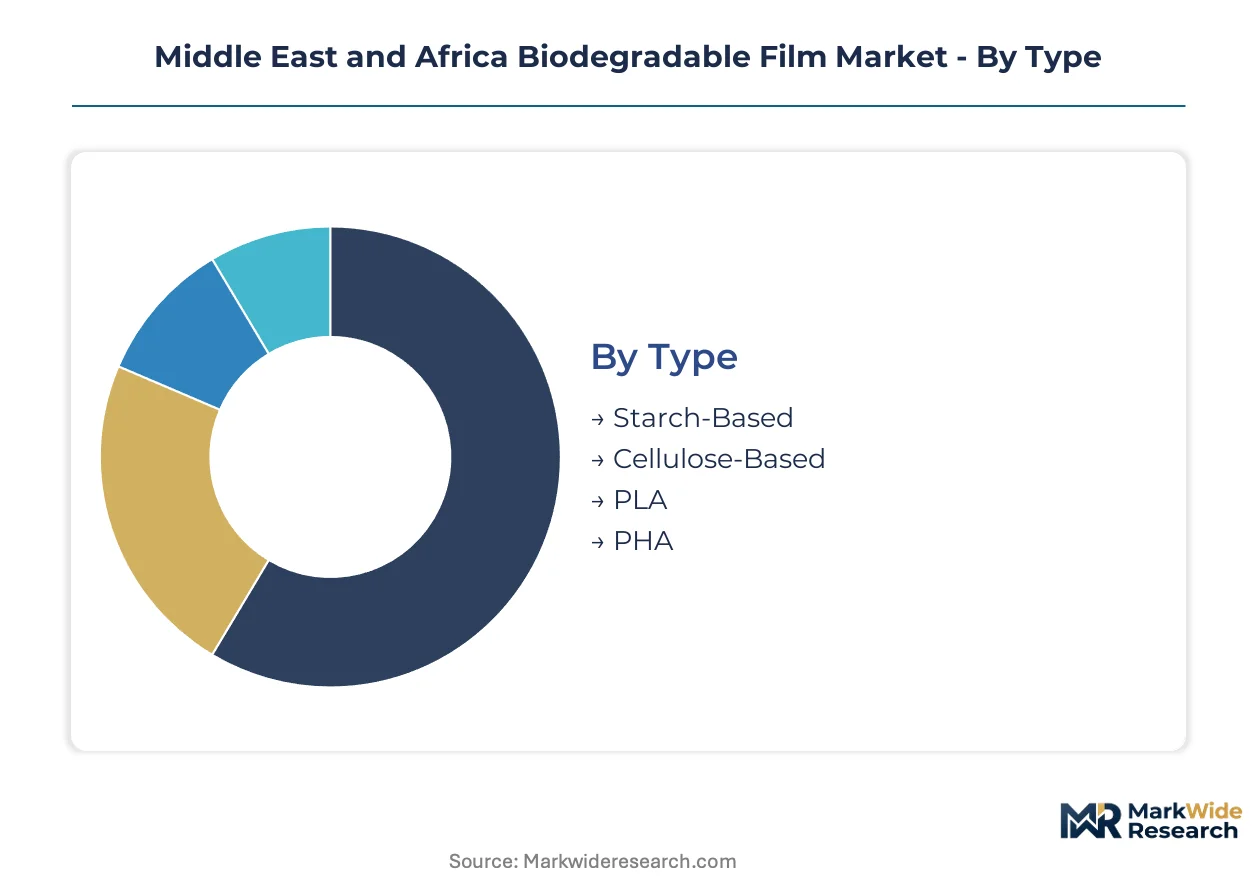
Segmentation reveals how feedstock economics, regulatory pressure, and end-use performance requirements split demand across material types and customer channels. Understanding these divides exposes where procurement budgets concentrate and where substitution timelines compress.
Type:
Volume production gravitates toward starch-based formulations, while premium positioning clusters around PLA clarity and heat-resistance specifications.
- Starch-Based:Formulations derive from Sub-Saharan maize processing residues, delivering cost-advantaged feedstock proximity for regional converters. Egyptian and South African agricultural film producers prioritize these grades for soil-degradable mulch applications where optical clarity is secondary to decomposition speed.
- PLA:Polylactic acid films command premium positioning through superior transparency and heat-seal integrity required in Israeli dairy and fresh produce thermoformed trays. Import dependency on European and Asian resin suppliers exposes margins to freight volatility and currency fluctuation.
- Cellulose-Based:Regenerated cellulose films serve niche pharmaceutical and luxury food-contact applications demanding grease resistance without synthetic polymer content.
- PHA:Polyhydroxyalkanoate formulations remain development-stage in regional production, constrained by fermentation scale-up costs and limited local bioreactor capacity.
Today's leader: Starch-Based. Tomorrow's challenger: PLA.
Application:
Arid-climate farming constraints and retail regulatory mandates are reshaping deployment priorities across use cases.
- Agricultural Films:Soil-biodegradable mulch films dominate Israeli and Moroccan drip-irrigation and greenhouse operations, displacing conventional polyethylene in applications where tillage labor costs exceed film premiums. SASO technical regulations and South African extended producer responsibility frameworks are accelerating specification shifts.
- Packaging Films:Multilayer coextrusion incorporating PLA outer skins with starch cores is absorbing premium food-contact volume in refrigerated supply chains. Cape Town and Johannesburg supermarket procurement committees now embed compostability certification into supplier scorecards.
- Food Service:Single-use alternatives face demand compression where industrial composting infrastructure gaps in secondary Gulf Cooperation Council cities restrict end-of-life assurance.
- Waste Management:Collection bags for organic waste streams represent emerging volume as Egyptian composting facility investments mature.
Agricultural Films currently absorb the largest procurement budgets. Packaging Films are climbing the fastest as retail certification requirements tighten.
End User:
Customer sophistication and compliance exposure determine specification stringency and contract duration.
- Food Industry:Israeli dairy and fresh produce packagers demand ISO 17088-certified films with documented industrial composting pathway assurance, compressing supplier qualification timelines to 12-18 months.
- Agriculture:Moroccan and Israeli greenhouse operators prioritize soil-degradable mulch performance under arid UV exposure and mechanical tillage stress, tolerating higher per-hectare film costs against labor savings.
- Consumer Goods:Premium personal care and household product brands in South African metropolitan distribution networks specify home-compostable structures for brand differentiation.
- Retail:Saudi Arabian supermarket chains are mandating biodegradability testing documentation under SASO technical regulations, displacing conventional tender-based sourcing with multi-year partnership frameworks.
Food Industry specifications set the technical ceiling. Retail procurement is forcing the fastest standardization.
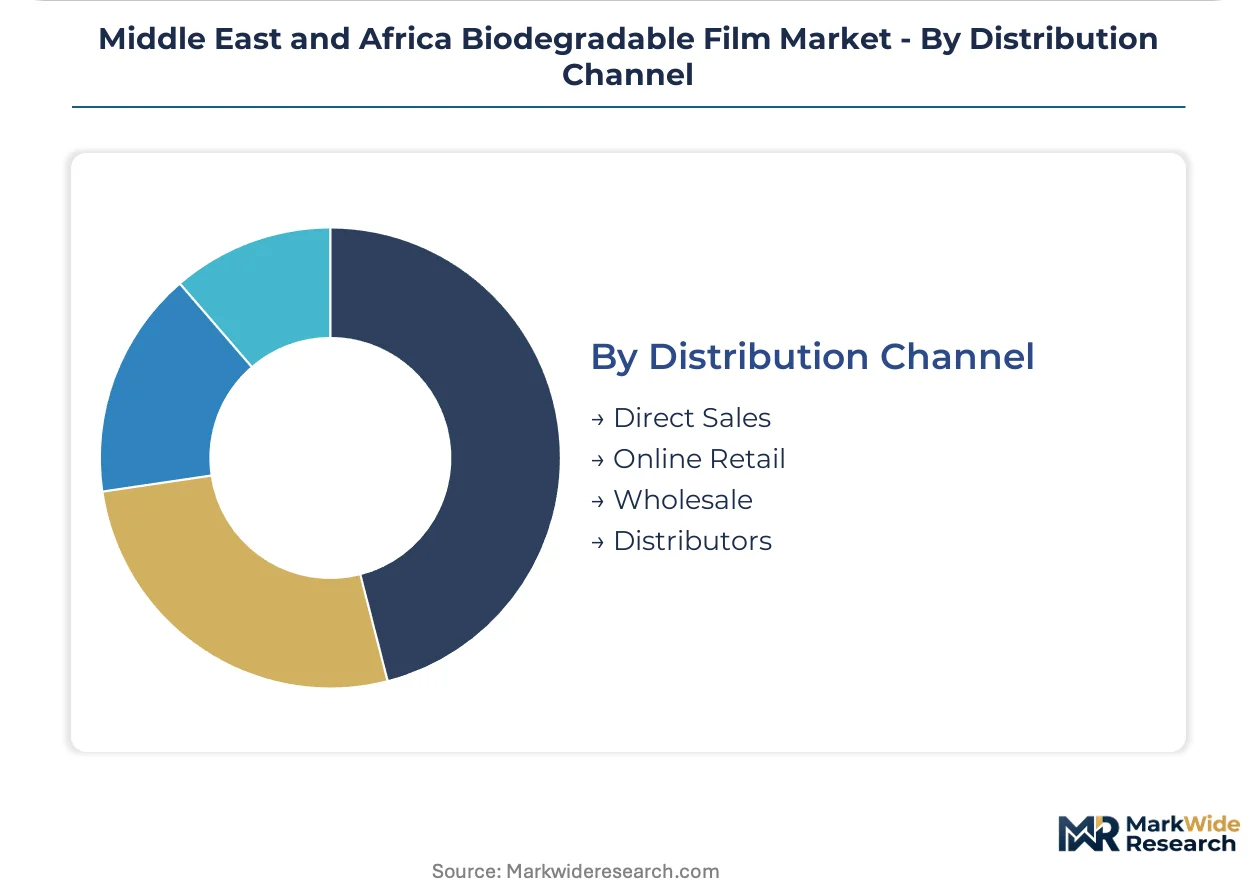
Distribution Channel:
Channel selection tracks order scale, technical service requirements, and geographic concentration of demand.
- Direct Sales:Large-volume agricultural film contracts in Israel and Morocco run through converter-direct relationships requiring field technical support for mulch laying equipment compatibility.
- Distributors:Regional packaging film distribution networks in Dubai and Johannesburg warehouse certified inventory for rapid replenishment of South African and Gulf Cooperation Council converter operations.
- Wholesale:Bulk starch-based formulations move through commodity wholesale channels serving price-sensitive agricultural segments in Egypt and Sub-Saharan markets.
- Online Retail:Specialty home-compostable bag structures for South African retail chains and consumer segments utilize digital procurement for specification transparency and certification documentation access.
Direct Sales currently lock in the largest contract values. Distributor relationships are gaining share fastest as certification pre-qualification burdens concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial biodegradable film production first scaled in European polymer research centers during the early 2000s, with technology transfer reaching Middle Eastern and African converters through Egyptian and South African packaging clusters by 2010. Regional demand now fragments across agricultural, food-contact, and retail regulatory mandates.
Saudi Arabia
SASO technical regulations for single-use plastic alternatives are mandating biodegradability testing protocols across retail and foodservice distribution. Riyadh-based supermarket chains now require third-party certification documentation before contract execution. The Eastern Province industrial corridor hosts converter operations supplying certified films to domestic retail networks.
South Africa
The National Regulator for Compulsory Specifications enforces ISO 17088-aligned testing protocols that compress procurement timelines for imported film products. Cape Town and Johannesburg metropolitan distribution networks now embed compostability certification into supplier scorecards. Extended producer responsibility regulations are reshaping procurement criteria across retail chains.
Egypt
The Environmental Affairs Agency is developing compostability certification requirements that impose 12-18 month validation cycles on imported film products. Cairo and Alexandria converter clusters are pivoting toward certified compostable substrates to maintain preferential EU market access. Agricultural film demand concentrates in Nile Delta greenhouse operations.
Israel
Drip-irrigation and greenhouse operators are substituting conventional polyethylene mulch with soil-biodegradable alternatives at accelerating rates. The national standards institute maintains alignment with EU REACH compliance protocols for export-oriented packagers. Tel Aviv and Haifa technical centers drive agritech integration of biodegradable films with precision irrigation systems.
Morocco
Agadir and Marrakesh greenhouse clusters prioritize soil-degradable mulch performance under arid UV exposure and mechanical tillage stress. National regulators are harmonizing standards with EU technical regulations to unlock customs clearance efficiencies for export-oriented producers. Agricultural film procurement tolerates higher per-hectare costs against labor savings in tillage operations.
Middle East and Africa Biodegradable Film Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and resin formulation complexity. The vendor base stratifies between multinational polymer suppliers with captive masterbatch development and regional converters dependent on imported resin formulations. Three archetypes dominate: integrated polymer-to-film manufacturers, specialized compostable packaging converters, and agricultural film distributors with field technical service capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves as players pre-qualify against tightening national certification protocols.
Within the integrated polymer supplier tier, BASF SE and Taghleef Industries Group exemplify divergent geographic anchoring strategies. BASF SE leverages European research network access to supply PLA masterbatch formulations to Egyptian and North African converters. Taghleef Industries Group anchors regional flexible packaging capacity through its Dubai manufacturing hub. BioBag International occupies a position within the specialized compostable packaging tier, focusing on home-compostable bag structures for South African retail distribution networks.
| Leading Market Players |
|---|
| BASF SE |
| Taghleef Industries Group |
| Clondalkin Group |
| BioBag International |
| Plastchim-T |
| TIPA Ltd |
| Cortec Corporation |
| Kingfa Technology |
| Futamura |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap converters across Egypt and Morocco anchor regional supply behavior, leveraging generational relationships with Nile Delta maize processors to secure feedstock cost advantages that discipline pricing for starch-based agricultural films. Their financing patterns—reinvested retained earnings rather than private-equity leverage—insulate margin structures from external capital pressure while limiting aggressive price competition in premium PLA segments.
Pricing Analysis
Three-tier pricing structure across ISO 17088-certified premium, industrial-grade standard, and uncertified economy levels stratifies the market. Certification grade and volume scale drive price differentiation, with South African retail procurement committees embedding compostability documentation into supplier scorecards. Cost compression in standard-grade starch films is intensifying because Egyptian converters face extended validation cycles for imported resin formulations. Agricultural greenhouse operators in Israel and Morocco demonstrate lowest price sensitivity, tolerating per-hectare premiums against labor savings, while bulk commodity buyers in Sub-Saharan wholesale channels exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with European and Asian PLA resin suppliers, exposing regional converters to freight cost volatility and currency fluctuation. Manufacturing concentrates in Germany, China, and Thailand for polylactic acid feedstock, while Sub-Saharan maize processing clusters anchor starch-based formulation supply. Raw material dependencies rest on corn starch derivatives, lactic acid monomers, and multilayer coextrusion equipment. Tariff exposure through EU REACH compliance protocols threatens customs clearance efficiency for Egyptian and Moroccan export-oriented producers. Distribution runs through Dubai and Johannesburg hub warehouses serving Gulf Cooperation Council and South African converter operations with rapid replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where South Africa's extended producer responsibility enforcement compresses procurement timelines against Egypt's 12-18 month certification validation cycles, creating cost-structure divergences for regional converters.
For Market Incumbents: Anchor certification pre-qualification investments against SASO technical regulations in Saudi Arabia and South Africa's National Regulator for Compulsory Specifications protocols. Defensive consolidation should prioritize backward integration into Sub-Saharan maize processing clusters to secure feedstock cost advantages, while capacity addition in Dubai manufacturing hubs protects Gulf Cooperation Council market share against emerging Egyptian converter clusters.
For New Entrants and Emerging Players: SASO technical regulations in Saudi Arabia open a window for home-compostable bag structure specialists targeting mandated retail procurement windows. The most penetrable segment lies in South African metropolitan distribution networks where supermarket chains displace tender-based sourcing with multi-year partnership frameworks. A go-to-market angle through online retail channels enables specification transparency and certification documentation access for specialty bag structures.
For Investors and Strategic Acquirers: Integrated polymer-to-film manufacturers with captive masterbatch development capabilities are the most active acquirer in this space, consolidating regional converter operations to secure ISO 17088 pre-qualified supply positions. Long-term viability hinges on 5-10 year regulatory harmonization trajectories between national standards and EU REACH compliance. Acquisition targets should display agricultural film field technical service capabilities and established relationships with Israeli drip-irrigation operators. The signal to monitor is Egyptian Environmental Affairs Agency protocol finalization timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive maize processing supply secures cost advantages for Egyptian starch-based film producers against import-dependent competitors. |
| ISO 17088 Certification Investment | Pre-qualified supplier status unlocks South African retail chain procurement committees embedding compostability into scorecards. |
| Multilayer Coextrusion Capacity Expansion | PLA outer skin production absorbs Israeli dairy and fresh produce packaging volume from conventional laminated structures. |
| Field Technical Service Network Buildout | Mulch laying equipment compatibility support locks in direct sales contracts with Moroccan and Israeli greenhouse operators. |
| Dubai Hub Distribution Partnership | Regional warehousing enables rapid replenishment of Gulf Cooperation Council converter operations facing SASO mandate deadlines. |
Research Methodology
Bottom-up agricultural film and packaging modeling reconciled against top-down polymer supply tracking forms the analytical core of this study. Primary interviews with plant managers at Egyptian and South African converter facilities, procurement leads at Israeli greenhouse operations, distribution channel partners in Dubai and Johannesburg, and technical R&D directors at polymer suppliers were validated against secondary sources including customs and trade data, SEC filings from multinational resin suppliers, SASO technical regulation documentation, and South African National Regulator for Compulsory Specifications protocols. This approach triangulates demand-side consumption patterns with supply-side capacity and certification alignment.
Historical trendline analysis of biodegradable film adoption rates in arid-climate agriculture and retail regulatory mandate implementation informed projection frameworks. Segmentation dimensions modeled include material type tier, application category, end-user sophistication level, and distribution channel structure across the projection horizon. CAGRs were derived from regression analysis of feedstock cost trajectories, regulatory timeline compression effects, and substitution elasticity against conventional polyethylene pricing. Industry-specific forecast inputs incorporate composting infrastructure investment pipelines and EU Green Deal extraterritorial compliance exposure for North African export-oriented producers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Egyptian Environmental Affairs Agency protocol acceleration or Gulf Cooperation Council industrial composting infrastructure delays. Forecasts reflect documented assumptions regarding regulatory harmonization progress and feedstock cost stability. Specific risk factors that could revise projections include PLA resin import tariff adjustments, currency devaluation in Egyptian and South African markets, and unanticipated delays in ISO 17088 testing facility accreditation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Biodegradable Cups Market
Biodegradable Packaging
Oxo-Biodegradable Plastic Packaging Market
Biodegradable Packaging
Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Oxo Biodegradable Bags Market
Biodegradable Packaging
Global Biodegradable Tableware Market
Biodegradable Packaging
Europe Biodegradable Film Market
Biodegradable Packaging
Biodegradable Water Bottles Market
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Biopolymer Packaging Market
Biodegradable Packaging
Biodegradable Plastic Bags and Sacks Market
Biodegradable Packaging
Bioplastic Packaging Bag Market
Biodegradable Packaging
Bioplastic Packaging Market
Biodegradable Packaging
Botanical Packaging Market
Biodegradable Packaging
Biofoam Packaging Market
Biodegradable Packaging
Biodegradable Packaging Materials Market
Biodegradable Packaging
North America Biodegradable Paper and Plastic Packaging Market