
 Europe Biodegradable Plastic Packaging Market | 2026-2036
Europe Biodegradable Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biodegradable Plastic Packaging Market Foresight
The split between premium certified compostable grades and commodity starch blends is realigning procurement patterns across European converters. BASF SE leverages its upstream control over PBAT polymerization to secure supply agreements with major food brands. Novamont S.p.A. anchors its position through integrated biorefinery operations in Italy, while Tipa-Corp Ltd. specializes in high-barrier flexible films for organic produce distribution.
Europe biodegradable plastic packaging comprises polymer systems engineered to mineralize under industrial composting or soil conditions within defined timeframes, typically requiring ASTM D6400 or EN 13432 certification with controlled disintegration thresholds. These materials function primarily to replace conventional polyethylene and polypropylene in applications where end-of-life collection infrastructure supports organic recycling pathways. PLA and starch-based formulations currently dominate volume flows into foodservice and fresh produce wrapping, where clarity and sealability carry premium value. PHA grades occupy narrower but higher-margin positions in marine-sensitive applications and agricultural mulching, where biodegradation in uncontrolled environments becomes a functional requirement rather than a disposal convenience.
The EU Green Deal, REACH chemical compliance frameworks, and national transpositions of the Single-Use Plastics Directive collectively mandate phased reduction of fossil-based packaging across member states while establishing harmonized compostability labeling. EFSA safety assessments for food-contact biodegradable polymers further condition which materials gain shelf access in regulated retail channels. Stakeholders must track evolving certification interoperability between EN 13432, OK Compost, and emerging soil-biodegradability standards to avoid stranded inventory in fragmented national compliance regimes.
Market Dynamics
Certification fragmentation between EN 13432 and emerging soil-biodegradability standards is forcing converters to dual-qualify inventory, compressing margins while expanding compliance overhead across the European supply base.
Growth Catalysts
- EU Green Deal packaging mandates:The phased reduction of fossil-based single-use plastics under the EU Green Deal is pulling foodservice operators toward certified compostable alternatives ahead of enforcement deadlines.
- Industrial composting infrastructure:Germany's expansion of anaerobic digestion and composting facilities is creating viable end-of-life pathways for PLA and starch-based packaging that lacked collection density five years ago.
- Fresh produce retail consolidation:Centralized buying desks at major European grocery chains are standardizing OK Compost certification requirements, aggregating demand toward qualified suppliers.
Market Restraints
- PBAT feedstock volatility:Butanediol and adipic acid price swings tied to naphtha markets transmit directly to biodegradable film converters, eroding cost parity with conventional polyethylene.
- Italian biopolymer supply concentration:Novamont's integrated biorefinery at Porto Torres controls a disproportionate share of European starch-based resin capacity, creating single-source vulnerability for flexible packaging buyers.
- Home composting performance gaps:Materials certified only for industrial composting fail to mineralize in domestic compost heaps, limiting consumer-facing applications and inviting greenwashing scrutiny.
Strategic Opportunities
- France agricultural film conversion:The French Ministry of Agriculture's subsidy program for soil-biodegradable mulching films is opening volume deployment of PHA grades in vegetable production zones.
- E-commerce protective packaging:Loose-fill and mailer bag demand from fulfillment centers is migrating toward starch-based void fill as brands seek plastic-free unboxing credentials.
- Marine biodegradability certification:TÜV Austria's OK biodegradable MARINE standard is enabling premium positioning for fishing gear and coastal food packaging in North Sea markets.
Industry Challenges
- Composting facility contamination protocols:Operators of industrial composting plants lack spectroscopic sorting equipment to separate certified biodegradable films from conventional plastics, causing rejection of entire organic waste streams.
- Food-contact migration testing backlog:EFSA safety assessments for novel biodegradable polymers face 18-24 month queues, freezing new material introductions in regulated retail channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biodegradable Plastic Packaging Market |
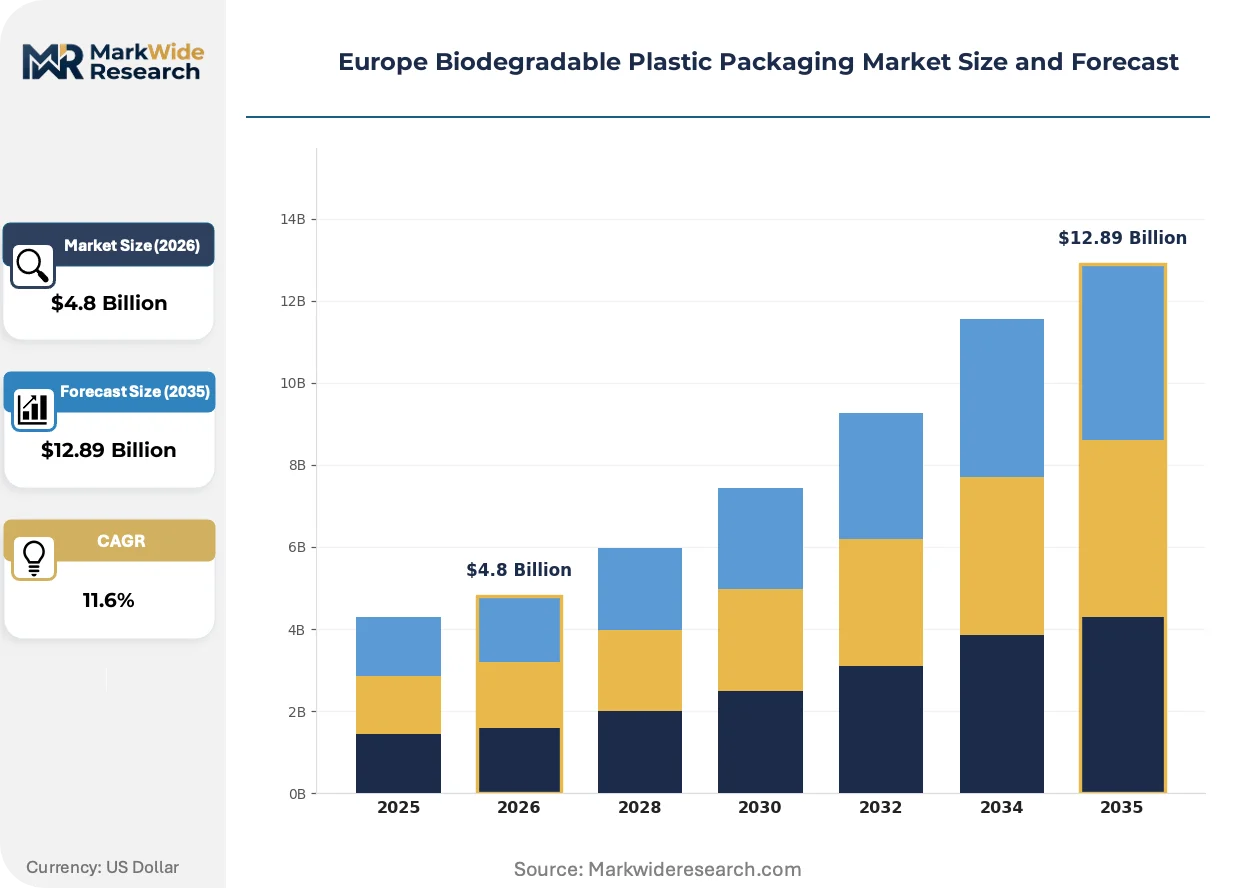
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PBS, PLA, PHA, Starch-based End User: Food Packaging, Consumer Goods, Healthcare, Retail Form: Films, Containers, Bags, Foam Application: Single-use Products, Foodservice, E-commerce, Agricultural Films |
| Companies Covered | Tetra Pak International SA, Amcor plc, Mondi plc, BASF SE, Novamont S.p.A., Huhtamaki Oyj, Sealed Air Corporation, NatureWorks LLC, Tipa-Corp Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biodegradable Plastic Packaging Market Shifts & Advancements
Active barrier coating technologies and enzymatic degradation triggers are compressing the performance gap between biodegradable and conventional plastics in oxygen-sensitive food applications.
Multilayer high-barrier films incorporating bio-based polyamides and vapor-deposited coatings are electrifying shelf-life extension for organic meat and dairy packaging. German discount retailers are piloting these structures in private-label cheese wraps. The technology is compressing the historical trade-off between compostability and moisture vapor transmission rates.
The F-Gas Regulation's phase-down of hydrofluorocarbon blowing agents is accelerating bio-based foam development for protective packaging applications. Extruded PLA foams with supercritical CO2 processing are displacing expanded polystyrene in electronics shipping. French appliance manufacturers are qualifying these materials ahead of 2030 reduction targets.
Centralized sustainability procurement functions at European grocery conglomerates are consolidating supplier qualification around cradle-to-cradle certification. This consolidation is displacing fragmented regional buying patterns that previously tolerated mixed certification portfolios. The Netherlands and Belgium show the fastest transition toward unified OK Compost HOME and INDUSTRIAL dual requirements.
Europe Biodegradable Plastic Packaging Market Segmentation
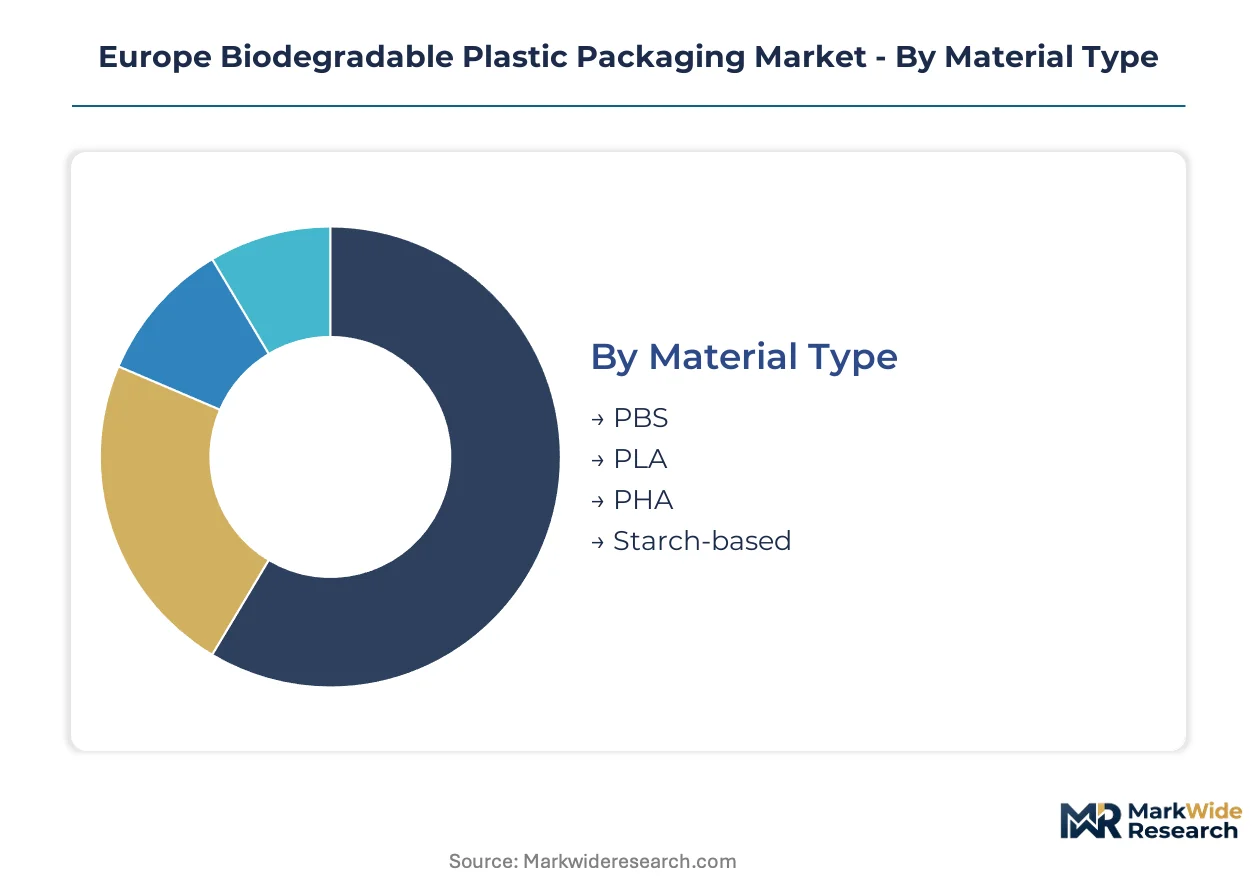
Material chemistry and end-of-life certification requirements split procurement decisions across European converters. Segmentation reveals where industrial composting infrastructure aligns with polymer performance characteristics.
Material Type:
Standalone biodegradable resins compete against embedded formulations within multilayer structures. Integration depth varies by thermal stability and barrier requirements.
- PLA:Polylactic acid delivers high clarity and rigidity for thermoformed trays and cold-fill beverage cups. German discount retailers specify PLA for private-label dairy packaging where industrial composting collection exists. REACH compliance for food-contact additives constrains formulation flexibility.
- Starch-based:Thermoplastic starch blends provide cost-competitive flexible films with moderate moisture sensitivity. French agricultural film buyers favor these grades for mulching applications where soil contact triggers biodegradation. Novamont's Porto Torres biorefinery anchors European supply security.
- PBS:Polybutylene succinate offers superior heat resistance for hot-fill and microwaveable containers. Italian pasta sauce packagers specify PBS lids where PLA would deform.
- PHA:Polyhydroxyalkanoates mineralize in marine and soil environments without industrial composting. North Sea fishing gear manufacturers qualify PHA for gear loss scenarios where uncontrolled biodegradation becomes a functional requirement.
Volume placements concentrate in starch-based grades; the faster expansion belongs to PHA.
End User:
Cost tier stratification separates premium certified applications from commodity substitution plays. Margin structures diverge sharply across buyer sophistication levels.
- Food Packaging:Fresh produce wrapping and protein trays demand high-barrier multilayer films with OK Compost INDUSTRIAL certification. Centralized buying at Dutch grocery conglomerates aggregates specification power toward qualified suppliers. EFSA migration testing queues delay new material introductions.
- Foodservice:Disposable cutlery, cups, and clamshells face EU Single-Use Plastics Directive phase-out deadlines. German QSR chains pre-empt enforcement with PLA alternatives ahead of national transpositions.
- Consumer Goods:Cosmetic and personal care bottles utilize biodegradable polymers for brand differentiation in premium positioning. French beauty brands lead qualification of PBS pump bottles.
- Healthcare:Sterile barrier packaging and disposable medical trays require validated biodegradation timelines compatible with clinical waste streams. Belgian hospital networks pilot starch-based sterilization pouches.
- Retail:Carry bags and merchandise packaging face divergent national plastic bag taxes. Italian retail chains substitute conventional polyethylene with certified compostable alternatives in municipalities with collection infrastructure.
Premium pricing endurance sits with food packaging; healthcare represents the steepest expansion trajectory.
Form:
Application requirements dictate whether films, rigid containers, or foamed structures dominate procurement specifications. Customer type clustering separates industrial buyers from consumer-facing deployments.
- Films:Flexible wrapping and pouch structures constitute the largest volume flow. German industrial packaging corridors specify high-clarity PLA films for organic produce distribution where optical properties carry premium value.
- Containers:Thermoformed trays and injection-molded tubs serve ready-meal and dairy applications. French retailers pilot multilayer PLA-PBS structures for extended shelf-life cheese packaging.
- Bags:Mailers, carry bags, and refuse sacks migrate toward starch-based formulations. E-commerce fulfillment centers in the Netherlands specify biodegradable mailer bags for plastic-free unboxing credentials.
- Foam:Protective packaging and loose-fill void fill displace expanded polystyrene. Supercritical CO2-processed PLA foams from German converters qualify for French electronics shipping ahead of F-Gas Regulation reduction targets.
Films anchor current procurement volumes; foam structures are climbing the fastest.
Application:
Maturity gradients separate established food-contact applications from emerging deployment zones. Supply concentration shapes regional availability.
- Single-use Products:Cutlery, straws, and stirrers face explicit EU Green Deal reduction mandates. Belgian foodservice distributors stock PLA alternatives ahead of enforcement deadlines.
- Foodservice:QSR packaging and catering disposables integrate biodegradable polymers for brand compliance. Italian coffee chains specify compostable lids for espresso cup systems.
- E-commerce:Protective packaging and shipping materials face pressure for plastic-free credentials. German appliance manufacturers qualify bio-based foam corner protectors.
- Agricultural Films:Mulching films and silage wraps demand soil-biodegradability certification beyond EN 13432. French Ministry of Agriculture subsidies accelerate PHA mulching film deployment in vegetable production zones around Nantes and Avignon.
Single-use products dominate current placements; agricultural films are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European biodegradable packaging demand through its dense concentration of food processing, chemical production, and logistics infrastructure that supports closed-loop composting systems.
Germany
Foodservice operators and discount retailers drive procurement of PLA thermoformed trays and cold-fill cups. The EU Green Deal's national transposition deadlines accelerate substitution ahead of enforcement. Bavaria's packaging technology cluster around Munich supplies high-barrier multilayer films to organic dairy processors.
France
Agricultural film buyers in vegetable production zones deploy soil-biodegradable mulching films under Ministry of Agriculture subsidy programs. The F-Gas Regulation's phase-down targets push appliance manufacturers toward bio-based foam protective packaging. The Nantes-Angers corridor concentrates PHA film extrusion capacity for farming cooperatives.
Italy
Integrated biorefinery operations at Porto Torres supply thermoplastic starch blends to flexible packaging converters serving Mediterranean fresh produce exports. REACH compliance frameworks condition food-contact additive approvals for pasta sauce and coffee packaging applications. Lombardy's industrial packaging corridor around Milan qualifies compostable films for premium organic brands.
Netherlands
Centralized sustainability procurement at grocery conglomerates standardizes OK Compost HOME and INDUSTRIAL dual certification requirements. The Randstad logistics hub enables collection density for industrial composting infrastructure that supports PLA scale-up. Rotterdam's port facilities import bio-based resin feedstocks for Benelux distribution.
United Kingdom
Post-Brexit regulatory divergence creates parallel compliance tracks for EN 13432-certified materials entering EU versus domestic markets. EFSA safety assessment backlogs delay novel polymer introductions in regulated retail channels. The Midlands packaging belt around Birmingham supplies starch-based mailer bags to e-commerce fulfillment centers.
Europe Biodegradable Plastic Packaging Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated supply base where integrated resin manufacturers hold upstream pricing power while specialized converters capture application-specific premiums. The vendor base stratifies around three archetypes: petrochemical majors with biopolymer divisions, dedicated bioplastic specialists with captive fermentation or agricultural feedstock operations, and flexible packaging converters layering certification expertise over commodity extrusion. Dominant competitive moves include backward integration into polymerization capacity and exclusive supply agreements with retail chains seeking single-source accountability for compostability claims.
Among integrated chemical producers, BASF SE anchors the petrochemical-major archetype through upstream PBAT polymerization control, while Novamont S.p.A. exemplifies the dedicated bioplastic model with its Porto Torres biorefinery complex. Tipa-Corp Ltd. occupies the specialized converter position, representing high-barrier flexible film expertise for organic produce distribution channels. These three entities collectively illustrate the competitive tension between scale-driven resin supply and application-specific formulation know-how.
| Leading Market Players |
|---|
| Tetra Pak International SA |
| Amcor plc |
| Mondi plc |
| BASF SE |
| Novamont S.p.A. |
| Huhtamaki Oyj |
| Sealed Air Corporation |
| NatureWorks LLC |
| Tipa-Corp Ltd. |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap converters across Italy and Germany anchor European supply discipline through conservative balance-sheet management that resists margin-eroding price wars during feedstock volatility cycles. Their financing patterns tie pricing power directly to certification-holding inventory positions that command premiums from risk-averse retail buyers.
Pricing Analysis
Certification-grade pricing anchors value capture across the European biodegradable packaging market, with EN 13432 and OK Compost INDUSTRIAL tiers commanding substantial premiums over uncertified starch blends. Price differentiation separates premium multilayer barrier films from commodity single-use cutlery grades, while PBAT feedstock volatility tied to naphtha markets transmits directly to converter margins. Cost compression in flexible film segments is intensifying because Italian biopolymer supply concentration limits buyer leverage. Foodservice distributors show highest price sensitivity due to thin operating margins, whereas organic produce retailers absorb premiums for shelf-life-extending barrier properties.
Supply Chain Analysis
Reverse-logistics flows for industrial composting collection create infrastructure-dependent supply constraints that reshape distribution economics across member states. Raw material concentration centers on Italy's Porto Torres biorefinery for thermoplastic starch, Germany's chemical corridor for PBAT polymerization, and Dutch import terminals for PLA resin feedstocks. The supply chain draws from agricultural commodity markets for corn starch and sugarcane-derived lactic acid, creating single-source vulnerability during harvest disruptions. Distribution runs through centralized sustainability procurement functions at Benelux grocery conglomerates that aggregate specification power toward qualified suppliers. Tariff exposure on bio-based resin imports from Asia threatens margin structures for non-integrated converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification fragmentation and capital intensity are forcing consolidation across European biodegradable packaging, eliminating undercapitalized converters unable to dual-qualify inventory for divergent national compliance regimes.
For Market Incumbents: Hedge against Novamont's supply dominance by securing alternative starch-based resin agreements with emerging Portuguese and Spanish biorefinery projects. BASF and other integrated petrochemical majors should accelerate backward integration into fermentation-derived monomers to decouple from fossil feedstock volatility that erodes cost parity with conventional polyethylene. For New Entrants and Emerging Players: The EU Green Deal's national transposition deadlines across Germany and France open a window for certified compostable foodservice alternatives ahead of enforcement. Agricultural film deployment in French vegetable production zones represents the most penetrable white-space segment, with PHA grades qualifying for Ministry of Agriculture subsidies that offset premium pricing. A direct-to-farming-cooperative go-to-market model bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized high-barrier film converters with captive certification expertise in the Netherlands and Belgium, where centralized grocery procurement consolidates demand toward qualified suppliers. Long-term viability over the coming decade hinges on interoperability between emerging soil-biodegradability standards and existing EN 13432 infrastructure. Monitor TÜV Austria's OK biodegradable MARINE certification uptake in North Sea coastal markets as an inflection indicator for premium marine-grade material demand.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | EN 13432 and OK Compost HOME qualification unlocks Dutch grocery conglomerate procurement mandates. |
| Backward Integration into Fermentation | In-house lactic acid production insulates PLA converters from agricultural commodity price swings. |
| Agricultural Film Subsidy Alignment | French Ministry of Agriculture PHA deployment programs accelerate volume adoption in vegetable zones. |
| Industrial Composting Partnership | Exclusive collection agreements with German anaerobic digestion facilities secure end-of-life pathway credibility. |
| Marine Biodegradability Qualification | TÜV Austria OK biodegradable MARINE certification enables premium positioning in North Sea fishing gear markets. |
Research Methodology
Multi-period observation of certification adoption rates, composting infrastructure buildout, and retail procurement specification changes anchored the trend analysis, supplemented by interviews with plant managers at Italian biorefineries, procurement leads at German discount retailers, distribution channel partners in Benelux logistics hubs, and technical R&D directors at flexible film converters. Secondary validation drew from EFSA food-contact safety assessments, EU Green Deal national transposition documents, REACH compliance filings, and customs data on bio-based resin trade flows. Bottom-up volume estimates from converter capacity utilization triangulated against top-down demand projections from grocery sector sustainability reports.
Input-output matrices modeled polymer production capacity against end-use demand across material chemistry grades, certification tiers, application formats, and regional collection infrastructure maturity. The analytical framework projected value trajectories across the analysis window by linking resin price elasticity to substitution thresholds for conventional plastics. Segmentation dimensions included thermal stability requirements, barrier performance specifications, and soil-biodegradability certification status. CAGRs derived from elasticity-adjusted adoption curves that weighted regulatory enforcement timelines against infrastructure readiness.
The model assumes a particular technology adoption path; alternative pathways for enzymatic degradation triggers or vapor-deposited bio-based coatings would alter the outlook for high-barrier food packaging displacement. Forecasts reflect assumptions about EFSA assessment queue durations and industrial composting contamination protocol standardization. Practitioners should monitor French agricultural subsidy program expansion and German anaerobic digestion capacity buildout for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Biodegradable Water Bottles Market
Biodegradable Packaging
India Biodegradable Tableware & Packaging Products Market
Biodegradable Packaging
Asia-Pacific Biodegradable Film Market
Biodegradable Packaging
Compostable Shrink Wrap Market
Biodegradable Packaging
Global Biodegradable Films Market
Biodegradable Packaging
Biodegradable Cups Market
Biodegradable Packaging
Biopolymer Packaging Market
Biodegradable Packaging
Asia-Pacific Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Middle East and Africa Biodegradable Film Market
Biodegradable Packaging
Biodegradable Packaging Market
Biodegradable Packaging
Biofoam Packaging Market
Biodegradable Packaging
Biodegradable Lids Market
Biodegradable Packaging
North America Biodegradable Film Market
Biodegradable Packaging
Europe Biodegradable Film Market
Biodegradable Packaging
Global Biodegradable Tableware Market
Biodegradable Packaging
Starch-Based Bioplastics Packaging Market