
 Clear Bioplastics Packaging Market | 2026-2036
Clear Bioplastics Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Clear Bioplastics Packaging Market Outlook
Food and beverage brands is collapsing into cosmetics and electronics buyers as the fastest-expanding customer archetype for clear bioplastics packaging. Amcor Plc anchors its position through manufacturing scale across European and North American converting facilities. NatureWorks LLC leverages captive PLA resin supply from its Blair, Nebraska biopolymer complex. TotalEnergies Corbion competes on geographic dominance with its Thai lactic acid-to-PLA integration.
Clear bioplastics packaging denotes transparent films, rigid containers, and formed articles manufactured from polylactic acid, polyhydroxyalkanoates, or thermoplastic starch, offering optical clarity above 85% light transmission alongside ASTM D6400 or EN 13432 compostability certification. These materials serve primary industrial functions in shelf-visible food preservation, tamper-evident pharmaceutical blisters, and premium cosmetic display applications. PLA films command the largest current volume share due to mature extrusion infrastructure and cost-competitive feedstock from corn starch fermentation. PHA grades represent the fastest-expanding segment because marine biodegradability certifications unlock single-use foodservice applications previously closed to petrochemical films. Rigid container formats concentrate margin pools where optical clarity requirements exclude paper-based substitutes.
The EPA regulates compostability claims under the Federal Trade Commission's Green Guides in the United States, while the EU Green Deal's Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds across all member states. FDA food contact notifications and EFSA safety assessments determine market access for new biopolymer chemistries in respective jurisdictions. Stakeholders must monitor evolving composting infrastructure gaps between certification standards and actual industrial composting availability.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing demand timelines for petroleum-based films while compostable alternatives scale manufacturing capacity. Retail procurement protocols in Germany and France now mandate optical clarity above 85% light transmission alongside ASTM D6400 or EN 13432 certification, forcing converters to requalify supply chains.
Growth Catalysts
- EU Green Deal mandates:Minimum recycled content thresholds across member states compel food and beverage brands to switch from conventional films to PLA and PHA grades certified under EN 13432.
- Marine biodegradability certification:PHA grades unlock single-use foodservice applications previously closed to petrochemical films, expanding addressable demand in coastal tourism economies.
- German retail procurement protocols:Sustainability scorecards enforced by major grocery chains concentrate volume toward converters with verified compostable film supply.
Market Restraints
- Corn starch feedstock volatility:PLA resin costs fluctuate with agricultural commodity cycles and ethanol policy arbitrage in the US Corn Belt.
- Thai lactic acid supply concentration:Geographic clustering of lactic acid-to-PLA integration creates single-source risk for European converters dependent on Asian feedstock.
- Industrial composting infrastructure gaps:ASTM D6400 certification outpaces actual municipal composting facility availability in most US metropolitan markets.
Strategic Opportunities
- Pharmaceutical blister packaging:Tamper-evident applications with optical clarity requirements exclude paper substitutes, creating premium margin pools for rigid PLA containers.
- Cosmetics display packaging:Premium beauty brands in France and Italy seek shelf-visible formed articles with marine biodegradability credentials for Mediterranean coastal retail.
- US EPA Green Guides alignment:Early compliance with FTC compostability claim enforcement creates first-mover positioning before anticipated federal procurement mandates.
Industry Challenges
- Extrusion technician scarcity:Biopolymer processing requires distinct temperature and moisture control expertise absent from conventional film workforce pipelines.
- Dual certification timelines:Simultaneous FDA food contact notification and EFSA safety assessment processes extend market entry cycles for novel PHA chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clear Bioplastics Packaging Market |
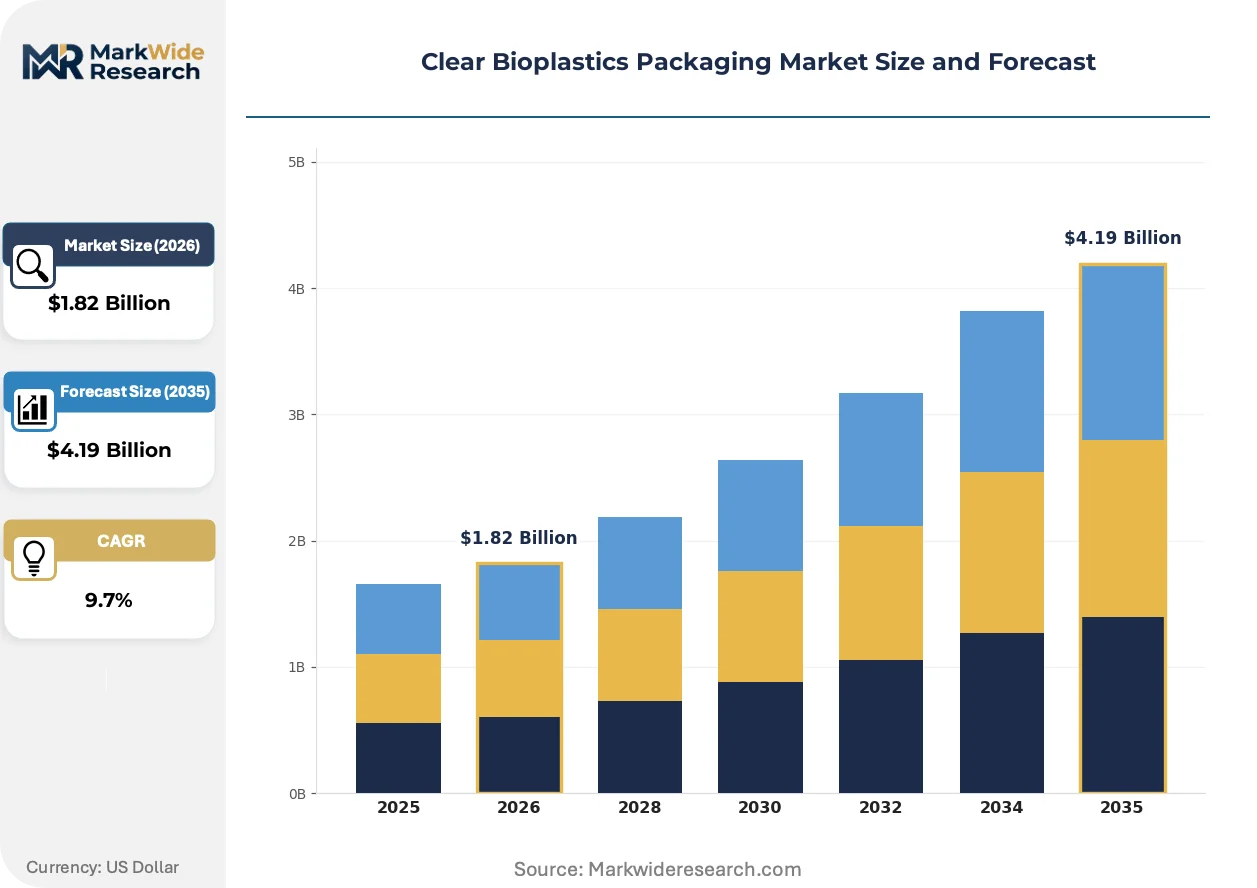
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $4.19 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PHA, PBS, TPS End User: Food & Beverage, Cosmetics, Electronics, Pharmaceuticals Form: Films, Rigid Containers, Trays, Bottles Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | NatureWorks LLC, BASF SE, TotalEnergies Corbion, Novamont S.p.A., Braskem, Danimer Scientific, Amcor Plc, Coveris, Biome Bioplastics Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clear Bioplastics Packaging Market Strategic Shifts
Material science breakthroughs in barrier coating and optical clarity enhancement are compressing performance gaps between bioplastics and petrochemical films. Three developments dominate competitive positioning.
Barrier-coated PLA films are decomposing the technical limitations that previously restricted bioplastic use in moisture-sensitive food applications. Modified atmosphere packaging buyers in fresh produce and ready-to-eat segments are accelerating qualification trials. The technology is decomposing incumbent multilayer petrochemical structures by matching oxygen transmission rates at competitive unit economics.
REACH substance restrictions on persistent organic pollutants are tightening compliance windows for conventional film additives used in food contact applications. Industrial converters face reformulation costs or material substitution decisions by 2026. Rigid container segments serving pharmaceutical and cosmetic end-uses are most affected, with German and French converters advancing biopolymer qualification to preempt regulatory disruption.
Direct-to-brand procurement contracts are consolidating volume away from distributor intermediaries in European markets. Large food and beverage manufacturers now require converter transparency on carbon intensity and feedstock provenance. This pattern is most visible in German retail supply chains, where sustainability scorecards determine supplier tier placement and contract renewal terms.
Clear Bioplastics Packaging Market Segmentation
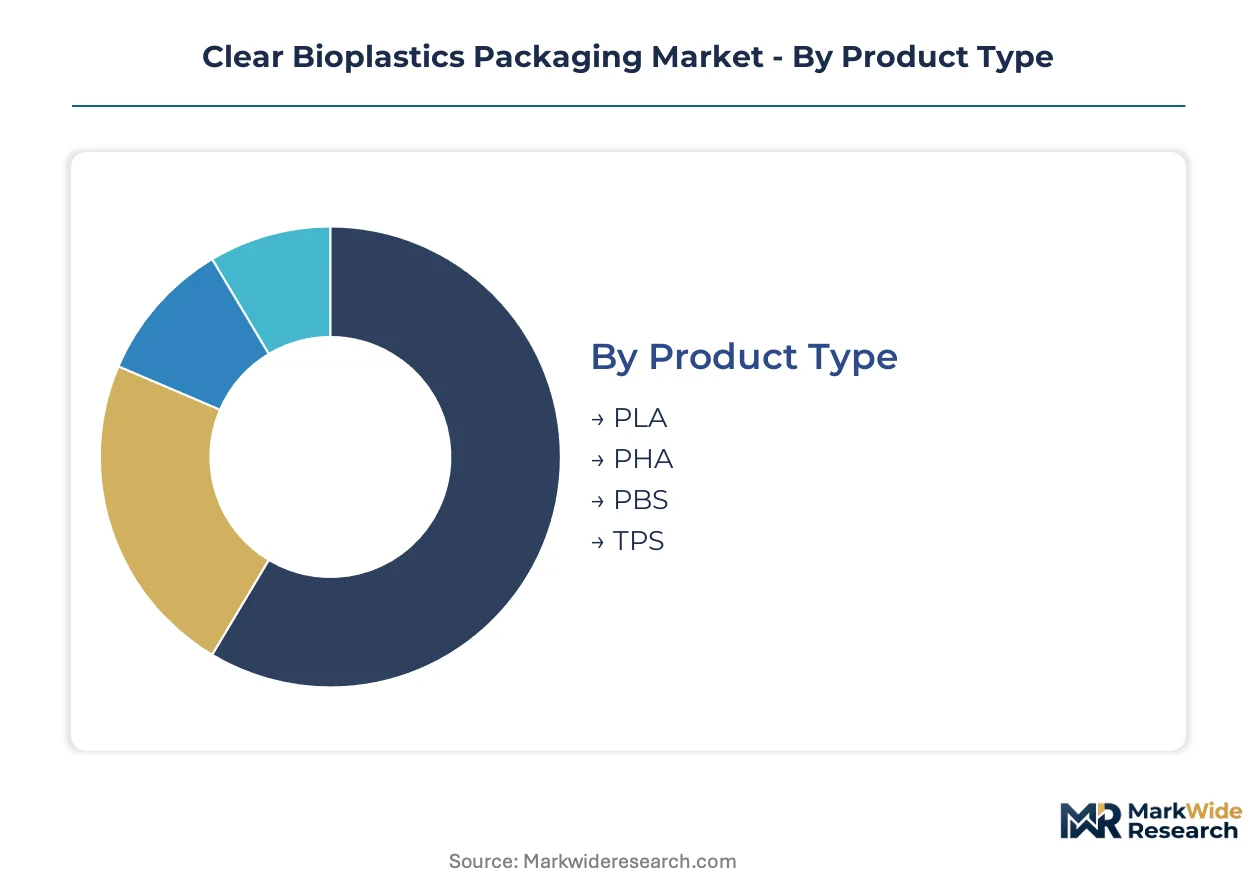
Segmentation in clear bioplastics packaging reveals how material chemistry, end-use specifications, and channel economics create distinct margin pools. Each dimension carries procurement protocols that reshape converter qualification requirements.
Product Type:
Channel mix varies sharply by resin chemistry, with PLA dominating supermarket and direct sales while PHA penetrates specialty coastal retail demanding marine biodegradability credentials.
- PLA:Polylactic acid derived from corn starch fermentation delivers optical clarity above 85% with mature extrusion infrastructure. German retail chains concentrate procurement through direct sales contracts mandating EN 13432 certification and verified carbon intensity scoring.
- PHA:Polyhydroxyalkanoates offer marine biodegradability certifications unattainable by petrochemical films. Demand concentrates in Mediterranean coastal tourism economies where single-use foodservice buyers face tightening disposal regulations.
- PBS:Polybutylene succinate bridges performance gaps between PLA flexibility and PHA marine credentials, finding niche adoption in flexible packaging applications.
- TPS:Thermoplastic starch represents cost-competitive entry grades with lower optical clarity, serving price-sensitive segments through distributor channels.
By volume, PLA leads. By growth pace, PHA is expanding most quickly.
End User:
Application-driven cost tiers separate premium pharmaceutical specifications from commodity foodservice volumes.
- Food & Beverage:Modified atmosphere packaging and fresh produce films require barrier-coated PLA matching oxygen transmission rates of multilayer petrochemical structures. German and French retail procurement protocols enforce sustainability scorecards determining supplier tier placement.
- Cosmetics:Premium beauty brands in France and Italy seek shelf-visible formed articles with marine biodegradability credentials for Mediterranean coastal retail displays.
- Electronics:Anti-static and moisture barrier specifications for component shipping create qualification barriers favoring established converters with FDA food contact notification experience.
- Pharmaceuticals:Tamper-evident blister applications with optical clarity requirements exclude paper substitutes, generating premium margin pools for rigid PLA containers.
Food and beverage commands current volume share. Cosmetics and electronics are climbing the fastest as brand sustainability commitments accelerate.
Form:
Volume concentration tracks customer type, with rigid containers serving institutional pharmaceutical buyers and films penetrating fragmented foodservice operators.
- Films:Flexible PLA and PHA grades serve modified atmosphere packaging and fresh produce wrapping through supermarket and direct sales channels. Barrier coating advances are displacing incumbent multilayer petrochemical structures in moisture-sensitive applications.
- Rigid Containers:Injection-molded and thermoformed articles with optical clarity above 85% serve pharmaceutical blisters and premium cosmetic displays. German converters advance biopolymer qualification to preempt REACH substance restriction deadlines.
- Trays:Thermoformed serving vessels concentrate in foodservice applications with compostability mandates across EU member states.
- Bottles:Blow-molded containers face stretch blow molding equipment retrofit costs limiting converter adoption to large-scale beverage brand contracts.
Films dominate current output. Rigid containers are gaining share fastest as pharmaceutical and cosmetic specifications harden.
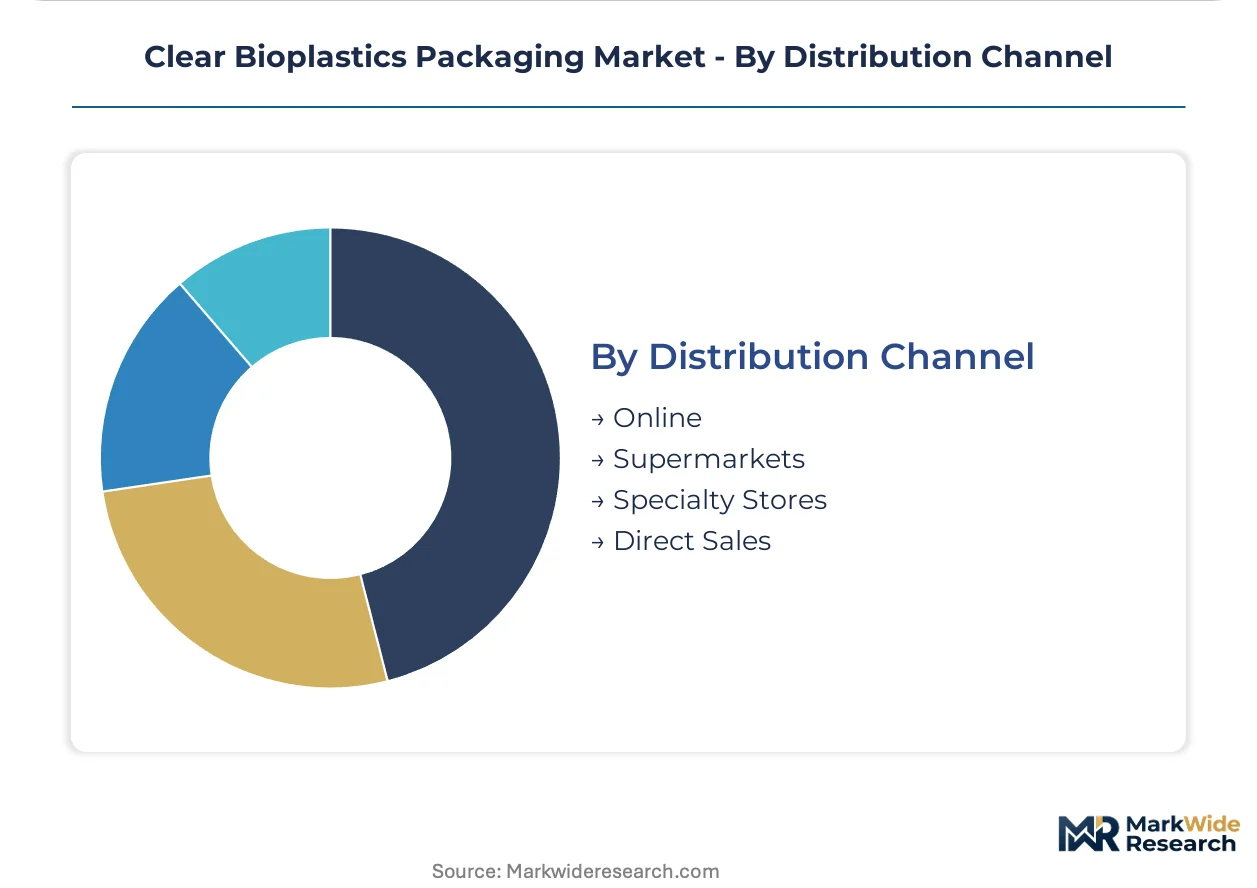
Distribution Channel:
Geography dictates channel structure, with German retail concentration driving direct sales consolidation while fragmented US markets sustain distributor intermediaries.
- Online:E-commerce procurement platforms serve small-batch cosmetic and electronics buyers requiring rapid qualification turnaround and transparent carbon accounting.
- Supermarkets:German grocery chains enforce sustainability scorecards concentrating volume toward converters with verified compostable film supply and EN 13432 certification.
- Specialty Stores:Coastal Mediterranean retailers source marine-biodegradable PHA grades for single-use foodservice, bypassing conventional distributor networks.
- Direct Sales:Large food and beverage manufacturers require converter transparency on feedstock provenance, consolidating volume away from intermediaries in European markets.
Direct sales leads by contract value. Online channels show steepest expansion trajectory as mid-tier brands accelerate sustainability procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's bioplastics transshipment hub underwrites European supply chain dominance, while Thailand's Map Ta Phut industrial corridor anchors Asian lactic acid-to-PLA integration.
Germany
Retail procurement protocols from REWE and EDEKA enforce EN 13432 certification and carbon intensity scoring. The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds across member states. The Rhine-Ruhr converting cluster concentrates biopolymer extrusion capacity where converters preempt REACH substance restriction deadlines.
United States
Corn Belt agricultural infrastructure supplies NatureWorks' Blair, Nebraska biopolymer complex with starch feedstock. The EPA regulates compostability claims under the FTC Green Guides while industrial composting infrastructure gaps persist in most metropolitan markets. The Midwest converting corridor processes PLA resin for food and beverage brand contracts.
Thailand
TotalEnergies Corbion's Map Ta Phut facility integrates lactic acid fermentation through PLA polymerization. The country's Board of Investment incentives attract biopolymer feedstock investments. The Eastern Economic Corridor clusters chemical processing infrastructure serving European converter demand.
France
L'Oréal and LVMH sustainability procurement drives premium cosmetic display packaging demand. The EU Green Deal's packaging mandates accelerate qualification timelines for compostable alternatives. The Lyon-Toulouse industrial axis hosts thermoforming specialists serving Mediterranean coastal retail chains.
Italy
Barilla and Ferrero supply chain requirements concentrate bioplastic film procurement through direct sales contracts. EFSA safety assessments determine market access for novel biopolymer chemistries. The Emilia-Romagna packaging district advances rigid container qualification for pharmaceutical blister applications.
Clear Bioplastics Packaging Market Competitive Environment
Concentration sits with integrated resin producers controlling upstream fermentation assets and downstream converting capacity. The market structure tiered across three archetypes: petrochemical majors diversifying into biopolymers, dedicated bioplastics specialists with captive agricultural feedstock, and packaging converters requalifying supply chains for certified compostable films. Strategic moves center on backward integration into lactic acid production and geographic expansion of compounding facilities to reduce freight exposure.
Among integrated resin producers, NatureWorks LLC and TotalEnergies Corbion exemplify the upstream-control archetype through captive fermentation infrastructure. Amcor Plc occupies a position representing the converter-scale tier with multi-continental extrusion footprint. BASF SE anchors the diversified chemical major segment, leveraging existing polymer compounding networks to distribute bioplastic grades alongside conventional portfolios.
| Leading Market Players |
|---|
| NatureWorks LLC |
| BASF SE |
| TotalEnergies Corbion |
| Novamont S.p.A. |
| Braskem |
| Danimer Scientific |
| Amcor Plc |
| Coveris |
| Biome Bioplastics Ltd |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day lactic acid feedstock lead times from Thai fermentation facilities concentrate pricing power with integrated resin producers while compressing converter margins during agricultural commodity spikes. This inventory exposure forces European and North American converters into long-term offtake contracts or captive starch sourcing to stabilize unit economics.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical blister specifications from commodity foodservice films, with EN 13432 certification grade and optical clarity percentage serving as primary price differentiation drivers. Three-tier pricing stratifies across premium pharmaceutical grades, standard food-contact films, and economy TPS entry levels. Cost compression in standard PLA grades is intensifying because NatureWorks and TotalEnergies Corbion expand fermentation capacity. Foodservice distributors exhibit highest price sensitivity, while cosmetics brands absorb premiums for marine biodegradability credentials.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp container lanes elevates inbound logistics costs for European converters dependent on Asian lactic acid feedstock. Supply concentrates in Thailand, the United States Corn Belt, and the Rhine-Ruhr converting cluster, with corn starch and sugarcane molasses as primary fermentation inputs. Single-source vulnerability from Thai lactic acid-to-PLA integration creates structural risk for European supply security. Distribution runs through direct sales contracts with large food and beverage manufacturers, bypassing distributor intermediaries in concentrated German retail procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clear bioplastics packaging sits in early-cycle expansion as EU Green Deal mandates compress substitution timelines for petroleum-based films, with marine biodegradability certifications unlocking coastal foodservice applications previously closed to incumbents.
For Market Incumbents: Consolidate backward integration into lactic acid fermentation assets to offset Thai feedstock concentration risk. Expand compounding capacity in the Rhine-Ruhr corridor to reduce freight exposure to German retail procurement scorecards. Lock multi-year offtake agreements with REWE and EDEKA before REACH substance restrictions force reformulation costs.
For New Entrants and Emerging Players: Anchor in Mediterranean coastal tourism economies where single-use foodservice buyers face tightening disposal regulations and marine biodegradability certifications command premium positioning. Target cosmetics display packaging for French and Italian premium beauty brands seeking shelf-visible formed articles. Pursue direct-to-brand procurement contracts with transparent carbon accounting as the go-to-market wedge.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds across member states, structurally advantaging compostable alternatives over conventional films. Acquisition targets should cluster around converters with verified EN 13432 certification and established FDA food contact notification pathways. Monitor industrial composting facility buildout rates in US metropolitan markets as the inflection signal for demand realization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactic Acid | Captive fermentation assets insulate NatureWorks and TotalEnergies Corbion from agricultural commodity volatility. |
| Barrier Coating Technology Investment | Modified atmosphere packaging qualification trials displace multilayer petrochemical structures in fresh produce segments. |
| Marine Biodegradability Certification | PHA grades unlock single-use foodservice applications in Mediterranean coastal tourism economies. |
| Rhine-Ruhr Compounding Expansion | Proximity to German retail chains reduces freight exposure and accelerates sustainability scorecard compliance. |
| Direct-to-Brand Procurement Contracts | Transparency on feedstock provenance consolidates volume away from distributor intermediaries in European markets. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with biopolymer extrusion technicians, sustainability procurement leads at German retail chains, FDA regulatory affairs specialists, and lactic acid fermentation plant managers. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, EFSA safety assessment databases, ASTM D6400 certification registries, and SEC disclosures from integrated resin producers. Bottom-up volume modeling triangulated against top-down market sizing across material chemistry, end-use specification, and channel economics.
Across the analysis window, forecasts employed a segmented growth-curve approach with PLA, PHA, PBS, and TPS chemistries modeled separately against end-use adoption rates in food and beverage, cosmetics, electronics, and pharmaceutical applications. CAGRs derived from regression against EU regulatory implementation timelines, German retail procurement protocol adoption curves, and US industrial composting infrastructure buildout assumptions. Feedstock cost sensitivity and barrier coating technology penetration served as key scenario variables.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and stable agricultural commodity pricing; material deviation would warrant model refresh. Forecasts reflect base-case assumptions around certification standard alignment and composting facility availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Asia-Pacific Biodegradable Film Market
Biodegradable Packaging
Europe Biodegradable Plastic Packaging Market
Biodegradable Packaging
Biodegradable Packaging Products Market
Biodegradable Packaging
Asia-Pacific Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Compostable Shrink Wrap Market
Biodegradable Packaging
Middle East and Africa Biodegradable Film Market
Biodegradable Packaging
Biodegradable Cups Market
Biodegradable Packaging
Biodegradable Meal Trays Market
Biodegradable Packaging
Biodegradable Plastic Packaging Market
Biodegradable Packaging
Biopolymer Packaging Market
Biodegradable Packaging
North America Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Biodegradable Cutlery Market
Biodegradable Packaging
Bioplastic Packaging Market
Biodegradable Packaging
Botanical Packaging Market
Biodegradable Packaging
Biodegradable Food Packaging Market
Biodegradable Packaging
Europe Biodegradable Film Market