
 Bioplastic Packaging Market | 2026-2036
Bioplastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Bioplastic Packaging Market Intelligence
The capital-intensity divergence between integrated resin producers and converters is unwinding as fermentation-based PLA capacity requires billion-dollar biorefinery investments that only a few players can fund. NatureWorks LLC leverages its captive corn-sugar feedstock supply in Nebraska to sustain cost parity with fossil-derived plastics. BASF SE anchors European PHA development through its fermentation partnerships, while Novamont S.p.A dominates Italian starch-blend packaging with vertically integrated agricultural sourcing.
Bioplastic packaging comprises polymer materials derived from renewable biomass sources such as corn starch, sugarcane, or cellulose, engineered to meet barrier, tensile, and thermal specifications comparable to conventional polyethylene or polypropylene. These materials serve primarily to reduce fossil-fuel dependency and enable compostable end-of-life pathways for single-use packaging. PLA currently leads product-type volume due to mature fermentation infrastructure and food-contact approvals, while PHA captures margin pools in marine-degradable applications where biodegradation in aquatic environments is specified. Starch-based blends occupy the economy tier of food packaging as drop-in replacements for expanded polystyrene trays.
The EU Green Deal and REACH frameworks restrict petroleum-based single-use packaging across member states, while FDA food-contact notifications govern PLA and PHA migration limits in the United States. The F-Gas Regulation indirectly supports bioplastic adoption by penalizing fluorinated barrier coatings that competing synthetic films require. Stakeholders must monitor composting infrastructure buildout rates against resin capacity announcements to avoid supply-demand mismatches in certified-compostable grades.
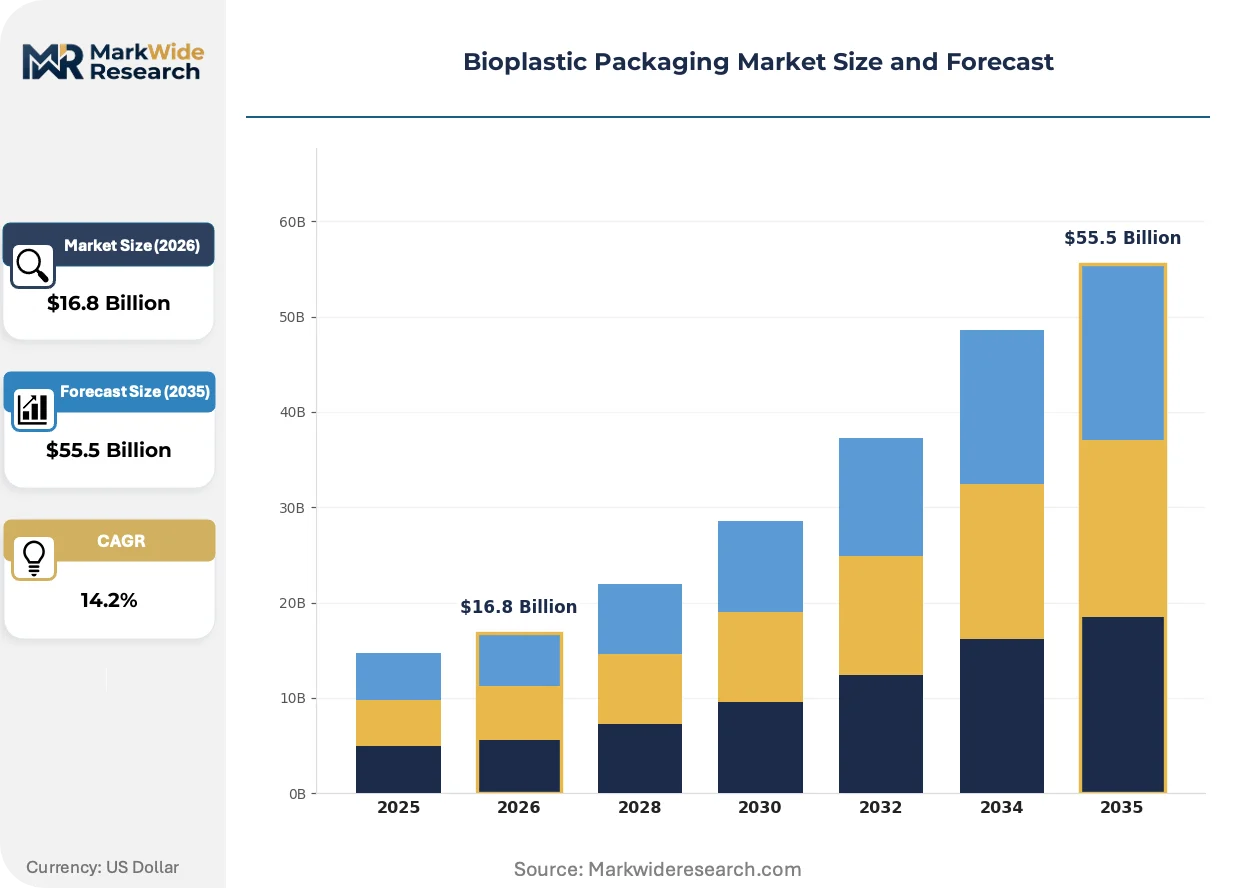
Market Dynamics
The capital barrier separating resin producers from converters is collapsing as fermentation-based biorefineries demand billion-dollar investments that only integrated agribusiness conglomerates can deploy. NatureWorks LLC's captive corn-sugar supply in Nebraska and Novamont S.p.A's agricultural sourcing in Italy exemplify how feedstock control determines competitive viability.
Growth Catalysts
- EU Green Deal packaging mandates:The framework's phase-out of petroleum-based single-use plastics compels brand owners to certify compostable alternatives. Germany's industrial composting infrastructure expansion accelerates adoption timelines.
- Fermentation technology maturation:PLA production yields have reached parity with fossil-derived polymers for barrier applications. Food-contact approvals under FDA and EFSA jurisdictions unlock beverage and fresh-produce segments.
- Marine-degradable specification demand:Coastal municipalities in France and Italy mandate aquatic biodegradation for food-service packaging. PHA formulations capture this specification-driven procurement.
Market Restraints
- Corn-sugar feedstock volatility:PLA resin costs fluctuate with agricultural commodity cycles and ethanol policy arbitrage in the US Midwest.
- Composting infrastructure concentration:Certified industrial composting capacity clusters in Germany, France, and northern Italy, leaving southern and eastern Europe with landfill-dominant end-of-life pathways.
- Barrier performance gaps:Oxygen and moisture transmission rates in starch-based blends exceed specifications for protein and dairy packaging, limiting substitution scope.
Strategic Opportunities
- Underpenetrated Eastern European markets:Poland and Romania lack industrial composting networks but show accelerating retail-chain sustainability commitments. Early-mover resin suppliers can anchor regional hub strategies.
- Pharmaceutical cold-chain packaging:Temperature-stable PLA-PHA copolymers address controlled-room-temperature shipment requirements. EU GDP guidelines create compliance-driven demand.
- Digital product passport integration:The EU's packaging traceability requirements favor blockchain-verified compostability claims. Technology convergence between polymer authentication and supply-chain transparency creates new service revenue pools.
Industry Challenges
- Fermentation engineering talent scarcity:Industrial microbiology and bioprocess optimization skills concentrate in pharmaceutical and biofuel sectors. Packaging resin producers compete for limited specialist pools.
- OK compost INDUSTRIAL certification timelines:TÜV Austria's evaluation protocols require 12-18 months for novel copolymer formulations. Product launch schedules compress against regulatory validation windows.
- Legacy extrusion equipment retrofit costs:Converters face capital outlays for temperature-control modifications when switching from polyolefins to lower-melt-stability bioplastics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioplastic Packaging Market |
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $55.5 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PHA, Starch-based, PBAT Application: Food Packaging, Consumer Goods, Medical, Agriculture End User: Food Industry, Retail Sector, Healthcare Providers, Agriculture Sector Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Amcor plc, NatureWorks LLC, Novamont S.p.A, Sealed Air, BASF SE, Coveris, Constantia Flexibles Group GmbH, Mondi plc, ALPLA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioplastic Packaging Market Strategic Shifts & Innovations
Active barrier coating technologies and anaerobic digestion compatibility are redefining material specifications. Brand owners now specify end-of-life performance before mechanical properties in procurement tenders.
Multilayer PLA-PHA laminates with bio-based moisture barriers are supplanting metallized polyester films in snack and confectionery packaging. Nestlé and Unilever have converted premium product lines in Germany and France. This substitution is compressing demand for aluminum vapor-deposition equipment while expanding co-extrusion line orders.
The EU F-Gas Regulation penalizes fluorinated barrier coatings that conventional synthetic films require. Competing multilayer structures lose cost competitiveness as F-gas quotas tighten. Food-contact notification pathways under EFSA and FDA now prioritize bio-based alternatives in review timelines.
Retail-chain sustainability scorecards now weight compostability certification above recycled content claims. Carrefour and Auchan have restructured produce packaging procurement around TÜV Austria and BPI certifications. This preference shift concentrates volume with suppliers holding pre-certified resin grades, marginalizing converters dependent on spot-market material sourcing.
Bioplastic Packaging Market Segmentation
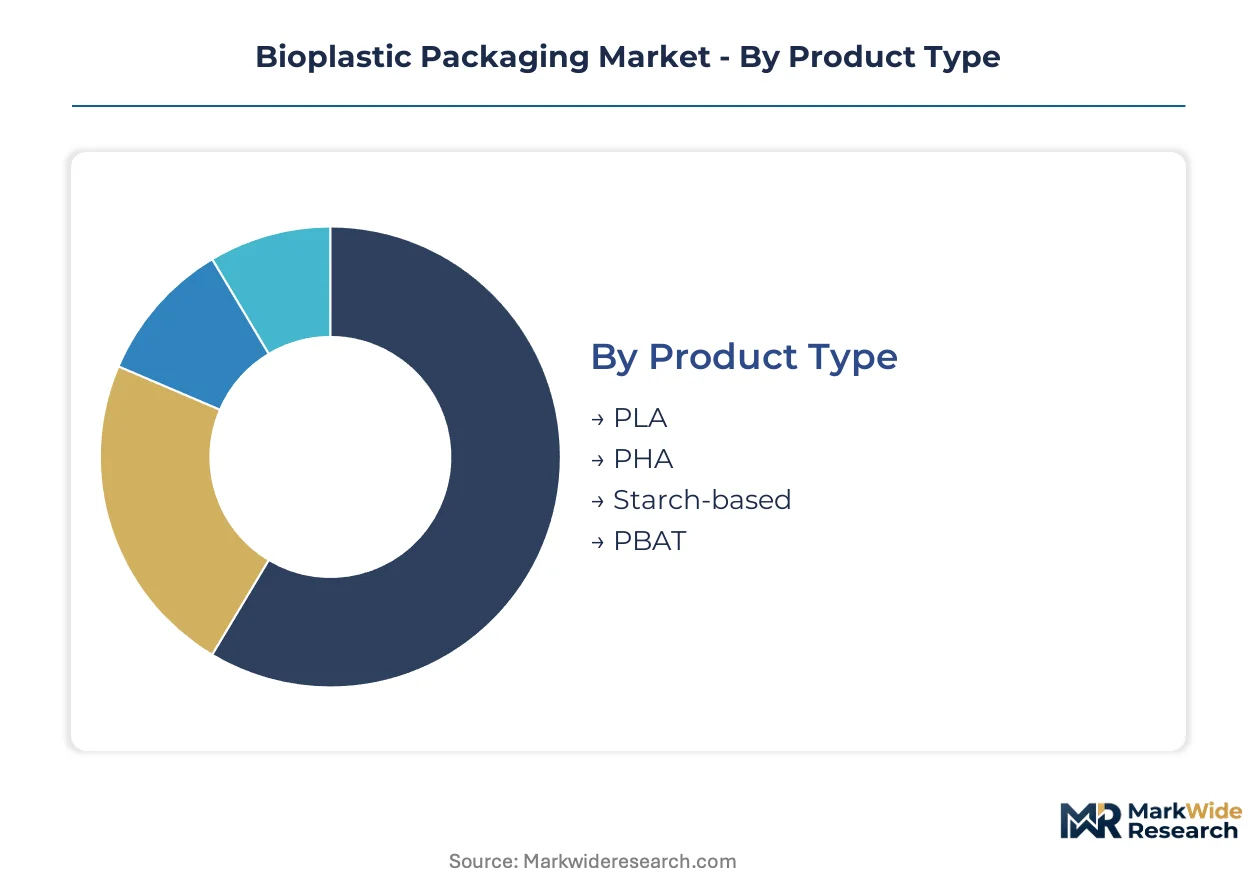
Bioplastic packaging segments diverge sharply in substitution economics against fossil-derived alternatives. Fermentation scale, composting infrastructure access, and end-use performance specifications determine which categories capture volume versus margin pools.
Product Type:
Polylactic acid faces the most intense substitute pressure from conventional polypropylene in barrier-sensitive applications, while marine-degradable grades command specification premiums that insulate pricing.
- PLA:Corn-starch-derived aliphatic polyester with crystallinity tunable for thermoforming or fiber applications. Demand concentrates in German and French fresh-produce packaging where industrial composting infrastructure validates end-of-life claims. FDA and EFSA food-contact approvals unlock beverage segments, though oxygen barrier limitations exclude protein-rich foods.
- PHA:Bacterial fermentation polyesters with intrinsic marine biodegradability. Coastal municipalities in Italy and France mandate aquatic degradation for food-service items, creating procurement specifications that fossil-derived materials cannot meet. Higher production costs limit penetration to premium single-use segments.
- Starch-based:Thermoplastic starch blends with synthetic polymer modifiers for moisture resistance. Drop-in replacement for expanded polystyrene trays in economy-tier food packaging across southern Europe.
- PBAT:Fossil-derived biodegradable copolyester often blended with PLA for flexibility. Compost bag and agricultural mulch film applications dominate Italian and Spanish volume.
PLA retains volume leadership; PHA holds the steepest expansion curve.
Application:
Cost tier stratification separates segments where bioplastics compete on specification versus those driven by compliance mandates alone.
- Food Packaging:Primary demand driver spanning fresh produce, bakery, and ready-meal segments. EU Green Deal single-use plastic phase-outs compel brand switches in Germany, France, and Italy. TÜV Austria OK compost INDUSTRIAL certification now gates retail-chain procurement at Carrefour and Auchan.
- Consumer Goods:Premium cosmetics and personal care packaging where bio-based content supports brand positioning. Lower volume sensitivity to price premiums versus food segments.
- Medical:Sterile barrier applications requiring ethylene oxide or gamma sterilization compatibility. PLA-PHA copolymers address EU GDP cold-chain requirements with temperature stability.
- Agriculture:Mulch films and plant pots where soil biodegradability eliminates retrieval costs. Italian tomato and vine crop systems drive adoption.
Food packaging dominates current volume; medical applications are expanding most quickly.
End User:
Customer-type concentration determines pricing power and certification requirements across the value chain.
- Food Industry:Processors and packers supplying private-label and branded retail. Sustainability scorecards now weight compostability above recycled content, concentrating procurement with pre-certified resin holders.
- Retail Sector:Supermarket chains and food-service operators with direct packaging specification authority. German and French retail consolidation amplifies buyer leverage.
- Healthcare Providers:Hospital systems and pharmaceutical distributors with sterilization and traceability requirements. EU MDR and GDP compliance frameworks govern material selection.
- Agriculture Sector:Grower cooperatives and agricultural input distributors. Price sensitivity limits adoption to mulch film segments with labor-cost offset value.
The food industry commands the largest procurement volume; healthcare providers offer the highest margin tier.
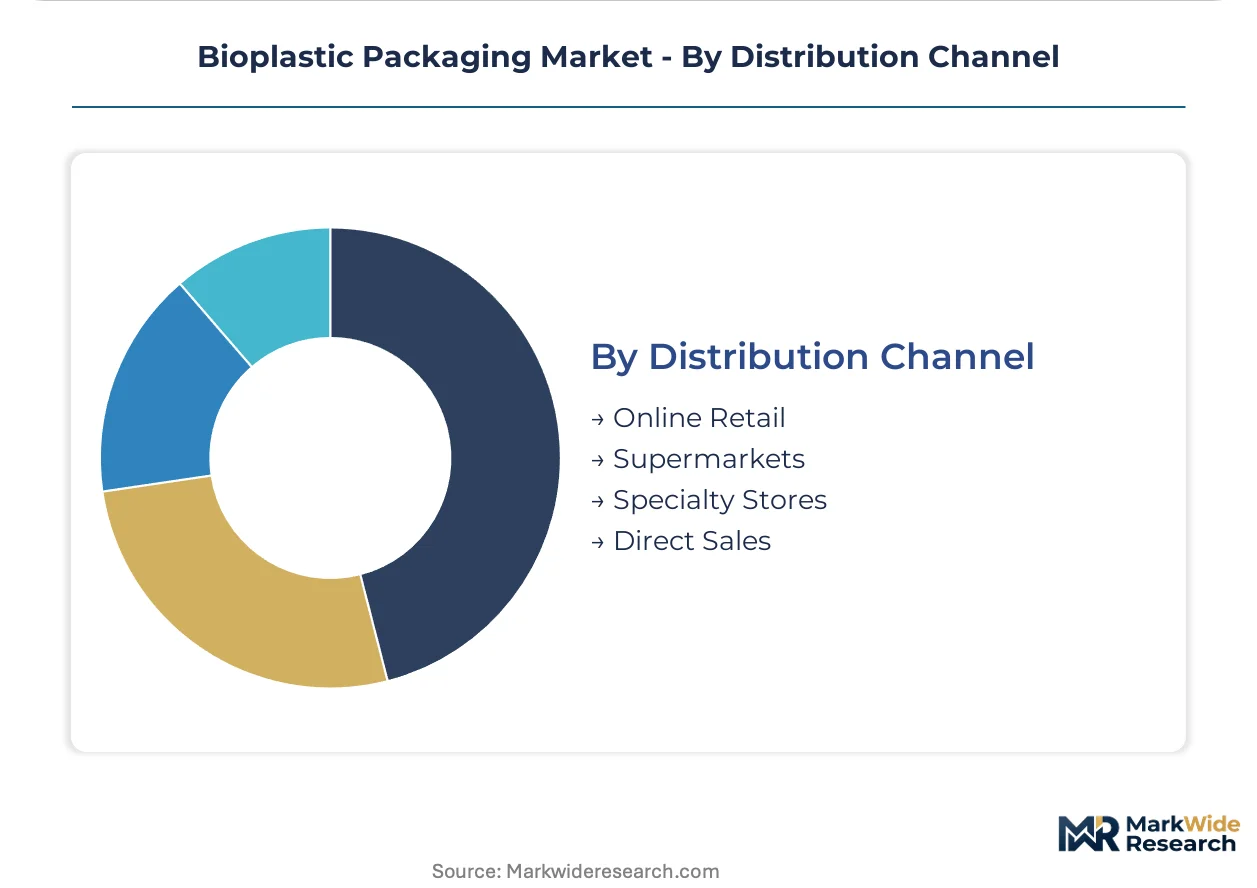
Distribution Channel:
Supply concentration in resin production shapes channel economics and converter access to certified grades.
- Online Retail:E-commerce platforms serving small-to-mid converters with spot resin purchases. Blockchain-verified compostability claims emerging as differentiation tool.
- Supermarkets:Direct procurement relationships between retail chains and integrated resin producers. Volume commitments secure priority allocation during feedstock volatility.
- Specialty Stores:Technical distributors serving niche medical and agricultural segments with formulation support. Regional expertise compensates for limited geographic coverage.
- Direct Sales:Long-term offtake agreements between biorefinery operators and major converters. Captive relationships lock in NatureWorks and Novamont volume.
Direct sales anchor resin producer margins; online retail channels are gaining share fastest among smaller converters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power clusters in Germany and France while Italian converters absorb feedstock volatility through agricultural integration. The EU Green Deal enforces divergent compliance costs across member states with uneven composting infrastructure.
Germany
Industrial composting capacity and retail-chain procurement concentration drive PLA demand. The Packaging Act mandates extended producer responsibility for single-use plastics. The Rhine-Main cluster around Frankfurt anchors resin distribution networks serving Central European converters.
France
Coastal municipality mandates for marine-degradable food service create specification premiums. The AGEC Law anti-waste provisions accelerate petroleum-plastic phase-outs. The Lyon-Grenoble corridor hosts PHA fermentation partnerships linking agricultural cooperatives to packaging converters.
Italy
Vertically integrated starch-blend production leverages Po Valley corn and wheat supply chains. The EU F-Gas Regulation penalizes fluorinated barriers in conventional films. Novara and Bologna industrial districts concentrate thermoforming capacity for fresh-produce trays.
United States
Corn-sugar feedstock abundance in the Midwest sustains cost parity debates with fossil-derived polymers. FDA food-contact notifications govern PLA migration limits for beverage applications. The Nebraska-Iowa corridor anchors captive agricultural supply chains for integrated biorefinery operators.
Poland
Retail-chain sustainability commitments outpace industrial composting infrastructure buildout. The EU Single-Use Plastics Directive drives regulatory compliance pressure without local end-of-life validation. The Łódź-Warsaw manufacturing belt attracts converter investments seeking Eastern European market access.
Bioplastic Packaging Market Key Industry Players
Concentration sits with integrated agribusiness conglomerates that control fermentation feedstock supply. The market structure separates billion-dollar biorefinery operators from equipment-dependent converters. Three archetypes dominate: captive-feedstock resin producers, agricultural-integrated compounders, and specialty multilayer converters. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure composting certification pre-qualification.
Within the captive-feedstock tier, NatureWorks LLC exemplifies Midwest agricultural integration, while Novamont S.p.A occupies the Mediterranean starch-blend position. BASF SE anchors European PHA development through fermentation partnerships. These three represent divergent feedstock strategies—corn-sugar, agricultural starch, and bacterial fermentation—that shape regional supply security.
| Leading Market Players |
|---|
| Amcor plc |
| NatureWorks LLC |
| Novamont S.p.A |
| Sealed Air |
| BASF SE |
| Coveris |
| Constantia Flexibles Group GmbH |
| Mondi plc |
| ALPLA |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between integrated biorefinery operators and major converters lock in both feedstock supply security and price visibility across multi-year procurement cycles. These contracts insulate German and French packaging converters from corn-sugar commodity volatility while anchoring resin producer capacity utilization.
Pricing Analysis
The customization-premium spread separates standard PLA grades from marine-degradable PHA formulations configured to coastal municipality specifications. Three-tier pricing structure across premium, standard, and economy levels reflects TÜV Austria certification tiers, with OK compost INDUSTRIAL validation commanding material premiums. Price differentiation stems from barrier performance grades and composting infrastructure proximity. Cost compression in starch-based blends is intensifying because expanded polystyrene substitution economics tighten converter margins. Food industry procurement teams show highest price sensitivity, while healthcare providers absorb premiums for sterilization-compatible grades.
Supply Chain Analysis
Inventory lead times for certified compostable resins stretch 8-14 weeks as fermentation batch cycles constrain just-in-time availability. Supply concentrates in the United States, Germany, and Italy, with Nebraska corn-sugar processing, Frankfurt Rhine-Main distribution, and Po Valley agricultural starch forming regional anchors. Raw material dependencies include corn starch, sugarcane bagasse, and bacterial fermentation feedstocks. Single-source vulnerability concentrates in NatureWorks LLC's captive Nebraska supply for North American PLA volume. Distribution runs through direct sales agreements with integrated resin producers, supplemented by specialty technical distributors serving medical and agricultural segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates switching costs that lock brand owners into certified supply relationships. Composting infrastructure access and pre-certified resin grades form structural barriers that compound over contract renewal cycles.
For Market Incumbents: Shield market position by accelerating TÜV Austria and BPI certification coverage for novel copolymer formulations before regulatory validation windows compress product launches. Deepen backward integration into agricultural feedstock supply through cooperative partnerships with corn and wheat growers in the Po Valley and US Midwest. Capacity addition in Poland and Romania addresses the emerging threat of Eastern European retail-chain sustainability commitments outpacing local composting infrastructure. For New Entrants and Emerging Players: Certification fast-track through BPI pre-qualification programs unlocks procurement gates at Carrefour and Auchan before established resin producers expand spot-market allocation. White-space targets include Polish and Romanian converter markets where retail-chain sustainability scorecards concentrate demand without local industrial composting validation. Pharmaceutical cold-chain packaging offers the most penetrable segment, with EU GDP compliance requirements creating specification-driven procurement that fossil-derived materials cannot satisfy. Go-to-market positioning should emphasize temperature-stable PLA-PHA copolymer formulations for controlled-room-temperature shipment applications. For Investors and Strategic Acquirers: Agricultural-integrated compounders with captive starch supply and pre-certified resin grades represent the acquisition target archetype most exposed to compounding regulatory tailwinds. Long-term viability framing centers on 5-10 year composting infrastructure buildout rates against resin capacity announcements, with supply-demand mismatches in certified grades creating margin expansion windows. The signal to watch is OK compost INDUSTRIAL certification timeline compression at TÜV Austria, as 12-18 month validation protocols create bottlenecks that pre-certified inventory holders can exploit.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive corn-sugar access in Nebraska insulates NatureWorks from agricultural commodity cycles and ethanol policy arbitrage. |
| Composting Certification Pre-Qualification | TÜV Austria OK compost INDUSTRIAL validation gates retail-chain procurement at Carrefour and concentrates volume with certified resin holders. |
| Regional Hub Strategy in Eastern Europe | Polish and Romanian converter investments capture retail-chain sustainability commitments before local industrial composting infrastructure matures. |
| Multilayer Co-Extrusion Capacity Expansion | PLA-PHA laminates with bio-based moisture barriers displace metallized polyester films in Nestlé and Unilever premium product lines. |
| Digital Product Passport Integration | Blockchain-verified compostability claims align with EU packaging traceability requirements and create service revenue pools beyond resin sales. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with biorefinery operations directors, packaging converter procurement leads, retail-chain sustainability officers, and industrial composting facility managers; and secondary validation through customs and trade data, European Bioplastics association reports, SEC filings from listed packaging converters, and TÜV Austria certification registries. Bottom-up resin capacity buildout estimates triangulated against top-down retail procurement volume commitments across Germany, France, and Italy.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, application segment, end-user category, and distribution channel, with additional dimensioning by composting infrastructure access tier and certification status. CAGRs were derived from regression analysis of historical resin pricing against feedstock cost indices, overlaying regulatory mandate implementation schedules. Industry-specific inputs included fermentation yield improvement curves and industrial composting facility commissioning timelines.
Underlying assumptions cover EU Green Deal packaging mandate adherence timelines and FDA food-contact notification pathway efficiency, with deviation risk concentrated in agricultural commodity price volatility and composting infrastructure buildout delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Biodegradable Packaging Materials Market
Biodegradable Packaging
Clear Bioplastics Packaging Market
Biodegradable Packaging
Global Bioplastic Multi-Layer Films Market
Biodegradable Packaging
Bioadhesives for Packaging Market
Biodegradable Packaging
Middle East and Africa Biodegradable Film Market
Biodegradable Packaging
Europe Biodegradable Cups Market
Biodegradable Packaging
Botanical Packaging Market
Biodegradable Packaging
North America Biodegradable Film Market
Biodegradable Packaging
Biodegradable Packaging Products Market
Biodegradable Packaging
Biodegradable Packaging Market
Biodegradable Packaging
Biodegradable Lids Market
Biodegradable Packaging
Biodegradable Cups Market
Biodegradable Packaging
Global Biodegradable Tableware Market
Biodegradable Packaging
Europe Biodegradable Plastic Packaging Market
Biodegradable Packaging
Oxo-Biodegradable Plastic Packaging Market
Biodegradable Packaging
Compostable Shrink Wrap Market