
 Biodegradable Meal Trays Market | 2026-2036
Biodegradable Meal Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Meal Trays Market Outlook
Airline catering procurement is reorganizing around compostable service ware mandates, pulling biodegradable tray volumes toward aviation-grade specifications. Huhtamaki leverages its molded fiber expertise to anchor European airline contracts. Vegware competes through certified home-compostable coatings that extend product utility across cold-chain meal delivery. Smurfit Kappa dominates corrugated and pressed-fiber formats for institutional catering, sustaining volume leadership through integrated pulp sourcing.
Biodegradable meal trays are rigid food-contact containers engineered from plant-derived polymers such as PLA or lignocellulosic fibers including bagasse and wheat straw, designed to decompose under industrial composting conditions within 90 to 180 days. Their primary commercial purpose is to replace petroleum-based plastic trays in prepared food distribution while satisfying organics-diversion requirements. PLA formulations currently lead material value due to clarity and thermoformability, though bagasse segments are capturing faster growth as pulp-molding equipment scales and unit costs compress. Compartmentalized shapes command premium positioning in airline and healthcare catering, whereas rectangular formats occupy mainstream takeaway and delivery volumes.
The EU Single-Use Plastics Directive and REACH frameworks restrict conventional plastic food service items, compelling converters to certify biodegradability through EN 13432 or OK Compost INDUSTRIAL standards. FDA food-contact substance notifications govern PLA and coating chemistries in the United States, creating dual-compliance burdens for exporters. Stakeholders must monitor evolving composting infrastructure gaps between jurisdictions, as tray biodegradability claims depend on access to industrial composting facilities that remain unevenly distributed.
Market Dynamics
Compostable mandate cascades from EU airline catering procurement are restructuring converter capacity allocation toward aviation-grade fiber molding, compressing lead times for institutional buyers and fragmenting legacy supplier relationships.
Growth Catalysts
- EU Single-Use Plastics Directive:The directive bans conventional plastic food service items across member states, forcing food service operators to source certified compostable alternatives and expanding addressable tray volumes in Germany's QSR sector.
- Bagasse pulp-molding scale-up:Equipment cost compression in lignocellulosic fiber processing is narrowing unit cost gaps with petroleum-based plastics, accelerating substitution in France's airline catering hubs.
- Industrial composting infrastructure expansion:Municipal organics-diversion programs in the Netherlands and Belgium are creating certified end-of-life pathways that validate biodegradability claims and reduce buyer risk.
Market Restraints
- PLA resin price volatility:Corn starch feedstock costs fluctuate with agricultural commodity cycles, compressing converter margins and creating pricing instability for thermoformed tray specifications.
- Industrial composting access gaps:Uneven facility distribution between urban and rural jurisdictions in Italy and Spain limits biodegradability claim validity and constrains market penetration outside metropolitan corridors.
- Extended shelf-life coating limitations:Current water-based barrier chemistries degrade under hot-fill conditions above 85°C, excluding biodegradable trays from soup and hot-beverage applications.
Strategic Opportunities
- Home-compostable certification tier:OK Compost HOME standards unlock residential disposal pathways in the UK and Scandinavia, where curbside organics collection remains underdeveloped and consumer willingness-to-pay premiums persists.
- Cold-chain meal delivery expansion:Refrigerated logistics platforms in the Netherlands are integrating compartmentalized fiber trays for prepared meal subscriptions, creating recurring volume contracts outside traditional food service.
- Healthcare catering pivot:Hospital procurement in France is adopting single-patient compostable service ware to reduce cross-contamination protocols, opening a price-insensitive institutional segment.
Industry Challenges
- EN 13432 certification timeline compression:Testing protocols require 180-day industrial composting validation cycles that delay product launches and tie up working capital in inventory.
- Molded fiber tooling capex intensity:Aviation-grade compartmentalized tray formats require precision aluminum molds costing €150,000-400,000 per cavity, limiting mid-scale converter entry.
- Barrier coating migration compliance:FDA and EFSA food-contact substance notifications for novel bio-based coatings demand toxicological data packages that smaller converters lack resources to assemble.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Meal Trays Market |
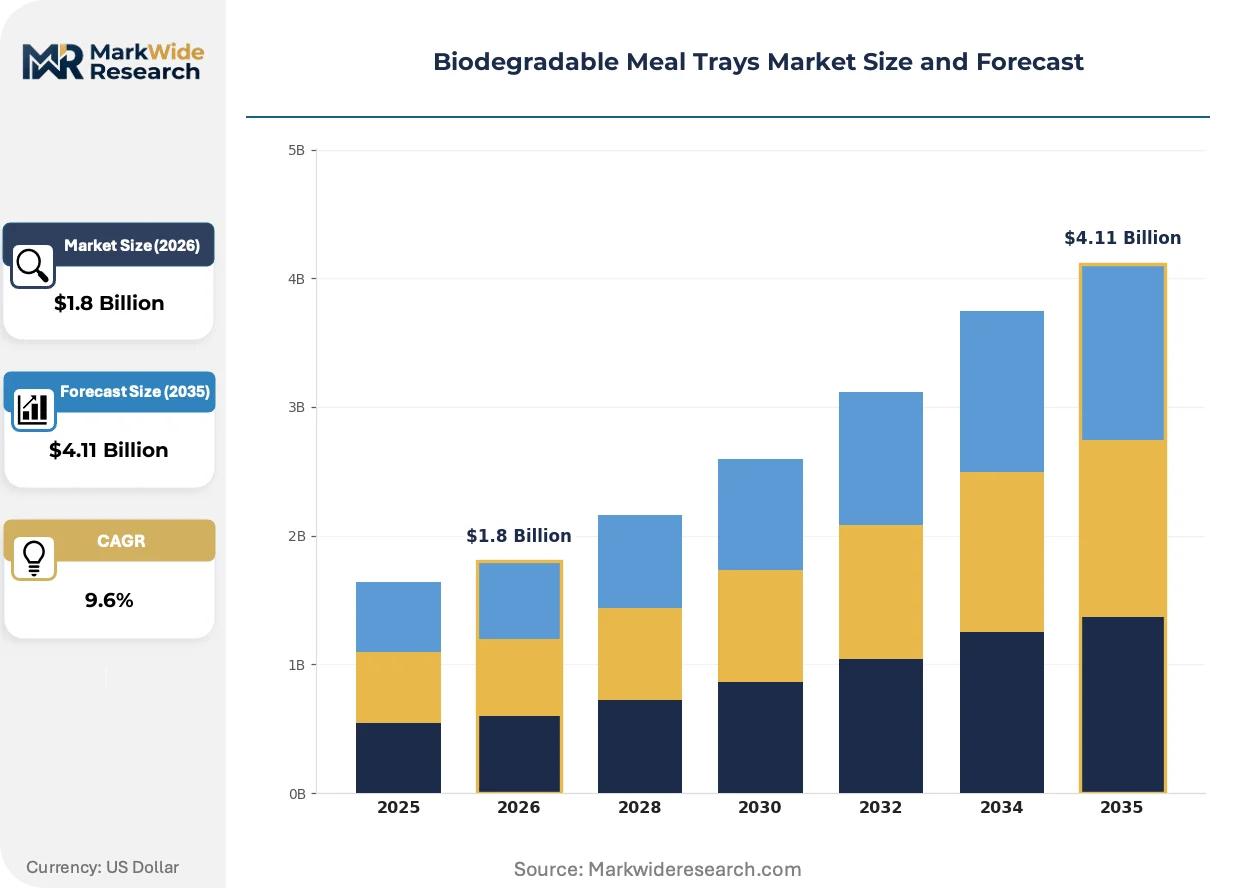
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.11 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PLA, Bagasse, Wheat Straw, Palm Leaf Shape: Rectangular, Round, Compartmentalized, Square End User: Food Service, Catering, Airlines, Restaurants Application: Takeaway, Food Delivery, Event Catering, Meal Prepping |
| Companies Covered | Smurfit Kappa, WestRock, DS Smith, Mondi Group, International Paper, Huhtamaki, BioPak, Vegware, Greenwave, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Meal Trays Market Strategic Shifts
Material science convergence with regulatory compliance engineering is redefining performance thresholds for biodegradable food-contact applications, creating divergence between industrial-compostable and home-compostable product tiers.
Barrier coating technology is fragmenting as multi-layer bio-based formulations replace single-use PLA linings. Airlines in France and Germany are specifying mineral-coated bagasse trays for hot entree service. The shift enables fiber-based products to capture premium catering segments previously reserved for aluminum or plastic.
REACH framework amendments are tightening notification requirements for food-contact substances containing nanoparticles or novel polymers. Converter R&D budgets are reallocating toward full material disclosure documentation. The regulatory burden falls heaviest on PLA compounders seeking EU market access, who must reformulate to exclude restricted additives.
Airline procurement departments are consolidating supplier rosters around vertically integrated fiber converters capable of certifying chain-of-custody from pulp sourcing through composting validation. Lufthansa Group and Air France-KLM procurement teams now mandate OK Compost INDUSTRIAL certification as a baseline qualification. The consolidation trend concentrates volume among three to four European molded fiber specialists and marginalizes smaller tray assemblers lacking in-house coating capabilities.
Biodegradable Meal Trays Market Segmentation
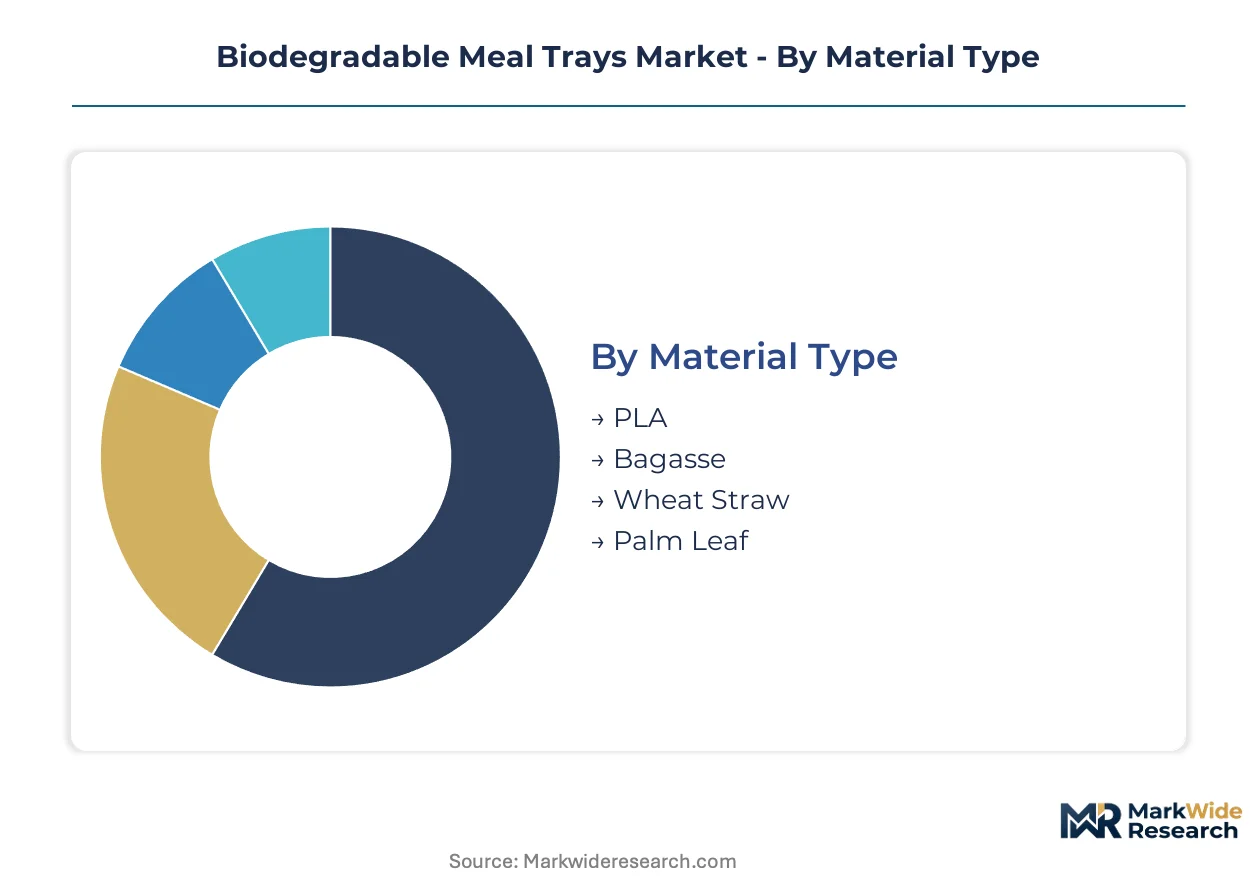
Segmentation in biodegradable meal trays reveals divergent margin structures across material chemistry and end-use specifications. PLA formulations command thermoforming premiums while fiber-based alternatives scale through pulp-molding automation. Shape complexity and certification tiers further stratify pricing power across converter portfolios.
Material Type:
Margin pools concentrate in certified compostable polymers with optical clarity and thermal stability, while fiber-based segments compete on unit cost compression through equipment scale-up.
- PLA:Polylactic acid derived from corn starch offers thermoformability and transparency for cold-chain visibility. Germany's QSR procurement channels favor PLA for premium takeaway formats requiring lid-seal integrity and refrigeration compatibility.
- Bagasse:Sugarcane fiber pulp molded under heat and pressure creates rigid, grease-resistant containers. France's airline catering hubs specify bagasse for hot entree service where mineral-coated barriers replace plastic linings.
- Wheat Straw:Agricultural residue fibers processed through mechanical pulping yield lower-density trays with muted aesthetic profiles. Netherlands institutional buyers source wheat straw for cost-sensitive volume catering.
- Palm Leaf:Areca palm sheaths pressed into natural-curve shapes serve premium event catering with minimal processing. UK outdoor hospitality operators specify palm leaf for visual differentiation in sustainable wedding and festival markets.
PLA holds installed capacity through legacy thermoforming infrastructure. Bagasse is rotating up the share rankings as aviation procurement consolidates around fiber-based specifications.
Shape:
Geometric complexity directly correlates with tooling investment and aviation contract eligibility, separating commodity formats from precision-molded premium tiers.
- Rectangular:Standardized dimensions optimize logistics cube efficiency and automated packing lines. Food delivery platforms in Belgium specify rectangular formats for stackability in insulated courier bags.
- Round:Curved perimeters suit bowl-based cuisine and soup applications where structural rigidity distributes load. Scandinavian meal-prep subscription services rotate round containers for aesthetic presentation in direct-to-consumer channels.
- Compartmentalized:Multi-cavity aluminum molds create segregated sections for protein, starch, and vegetable components. Lufthansa Group catering procurement mandates compartmentalized fiber trays for long-haul economy service.
- Square:Equal edge lengths maximize shelf-space utilization in retail cold cases. Spain's supermarket ready-meal sections specify square formats for display consistency.
Compartmentalized formats absorb the steepest expansion trajectory as airline procurement consolidates supplier rosters. Rectangular configurations maintain volume leadership through delivery platform integration.
End User:
Procurement sophistication varies sharply across institutional buyers, with aviation and healthcare segments demanding chain-of-custody documentation absent in casual dining channels.
- Food Service:Broad-spectrum operators including contract caterers and facility management companies. Netherlands municipal procurement frameworks specify EN 13432 certification for public sector food service contracts.
- Catering:Event and institutional specialists managing volume meal distribution. French hospital procurement is adopting single-patient compostable service ware to reduce cross-contamination protocols.
- Airlines:Aviation catering departments with stringent weight, safety, and disposal pathway requirements. Air France-KLM mandates OK Compost INDUSTRIAL certification as baseline supplier qualification.
- Restaurants:Independent and chain operators balancing cost control with sustainability signaling. Germany's QSR sector leads fiber tray adoption driven by compostable mandates in urban jurisdictions.
Airlines concentrate the highest-margin contract structures. Catering is rotating up the share rankings as healthcare procurement pivots toward single-use compostable protocols.
Application:
Usage context determines barrier performance requirements and temperature exposure limits, excluding certain material formulations from hot-fill or extended-shelf-life scenarios.
- Takeaway:Counter-service formats requiring rapid handoff and consumer disposal guidance. Belgium's municipal organics-diversion programs validate biodegradability claims for takeaway packaging.
- Food Delivery:Courier-mediated transport demanding structural integrity through vibration and temperature fluctuation. Netherlands refrigerated logistics platforms integrate compartmentalized fiber trays for prepared meal subscriptions.
- Event Catering:Large-scale temporary service with visual presentation priorities and mixed waste stream challenges. UK festival operators specify palm leaf and bagasse for home-compostable disposal pathways.
- Meal Prepping:Subscription-based portion control with multi-day refrigeration and microwave reheating requirements. Scandinavian cold-chain meal delivery services specify PLA-lidded formats for clarity and seal performance.
Food Delivery holds installed capacity through platform logistics integration. Event Catering is rotating up the share rankings as outdoor hospitality recovers and sustainability procurement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Netherlands distribution dominance for compostable food service imports, while Rhine corridor rail links position Germany as the continental conversion hub for molded fiber equipment.
Germany
QSR procurement channels favor PLA thermoformed formats requiring refrigeration compatibility and lid-seal integrity. The country's packaging ordinance mandates extended producer responsibility for food service disposables. Munich and Hamburg host converter clusters supplying Lufthansa Group catering contracts with aviation-grade compartmentalized specifications.
France
Airline catering procurement at Air France-KLM hubs drives mineral-coated bagasse specifications for hot entree service. REACH framework amendments tighten notification requirements for food-contact substances containing novel polymers. Toulouse and Lyon concentrate molded fiber specialists certifying chain-of-custody from pulp sourcing through composting validation.
Netherlands
Refrigerated logistics platforms integrate compartmentalized fiber trays for prepared meal subscription services outside traditional food service. Municipal organics-diversion programs in Amsterdam and Rotterdam create certified end-of-life pathways validating biodegradability claims. Eindhoven hosts equipment manufacturers scaling lignocellulosic fiber processing automation.
United Kingdom
Outdoor hospitality operators specify palm leaf and bagasse formats for home-compostable disposal pathways at festival and wedding markets. OK Compost HOME standards unlock residential disposal where curbside organics collection remains underdeveloped. London procurement frameworks drive sustainability signaling among independent restaurant operators.
Belgium
Food delivery platforms specify rectangular formats optimized for stackability in insulated courier bags. Municipal organics-diversion programs validate biodegradability claims for takeaway packaging across Brussels and Antwerp corridors. The country's central geography positions converters for cross-border supply into French and German QSR networks.
Biodegradable Meal Trays Market Competitive Environment
Concentration sits with vertically integrated fiber converters capable of certifying chain-of-custody from pulp sourcing through composting validation. Three strategic archetypes dominate: European molded fiber specialists with aviation-grade tooling capabilities, North American corrugated giants leveraging integrated pulp sourcing, and certified home-compostable coating innovators serving cold-chain delivery platforms. Competitive moves center on precision aluminum mold capacity expansion and OK Compost INDUSTRIAL certification acquisition.
Among European molded fiber specialists, Huhtamaki anchors the aviation-grade segment through molded fiber expertise securing airline contracts. Vegware occupies a position within the home-compostable certification tier, exemplifying coating innovation extending product utility across cold-chain applications. Smurfit Kappa represents the integrated pulp-sourcing archetype, dominating corrugated and pressed-fiber formats for institutional catering volume leadership.
| Leading Market Players |
|---|
| Smurfit Kappa |
| WestRock |
| DS Smith |
| Mondi Group |
| International Paper |
| Huhtamaki |
| BioPak |
| Vegware |
| Greenwave |
| Others |
Value Chain & Pricing Dynamics
Aviation-grade mold capacity utilization above 80% in Germany and France is compressing lead times for institutional buyers while elevating price floors for compartmentalized tray specifications. This scale concentration simultaneously rewards early equipment investors with procurement lock-in from Lufthansa Group and Air France-KLM, and penalizes mid-scale converters facing €150,000-400,000 per-cavity tooling barriers.
Pricing Analysis
Three-tier pricing structure across aviation-certified, industrial-compostable, and economy fiber grades dominates converter quotations. Price differentiation hinges on OK Compost INDUSTRIAL certification status and mineral barrier coating performance tiers. Cost compression in bagasse pulp-molding is intensifying because equipment automation is narrowing unit gaps with petroleum-based alternatives. QSR procurement in Germany exhibits highest price sensitivity, while airline catering contracts demonstrate lowest sensitivity due to sustainability mandate compliance requirements.
Supply Chain Analysis
Strategic stockpiling of bagasse pulp prevails among European converters buffering against Brazilian sugarcane harvest volatility, whereas just-in-time resin delivery characterizes PLA thermoforming operations tethered to NatureWorks and TotalEnergies Corbion production schedules. Geographic supply concentration centers on Germany, France, and the Netherlands for molded fiber equipment and coating chemistry. Raw material dependencies include sugarcane bagasse, corn starch feedstock, and mineral barrier formulations. Single-source vulnerability in precision aluminum mold fabrication constrains capacity expansion. Distribution runs through Rotterdam port infrastructure and Rhine corridor rail links serving continental food service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable meal trays sit in early-cycle expansion as EU Single-Use Plastics Directive enforcement cascades through food service procurement channels, with aviation and healthcare segments still underpenetrated by certified compostable alternatives.
For Market Incumbents: Compound mold capacity advantages in aviation-grade compartmentalized formats before mid-scale competitors secure precision tooling partnerships. Defend supplier roster positions against emerging Asian fiber converters by accelerating OK Compost HOME certification for UK and Scandinavian residential disposal pathways. Prioritize backward integration into bagasse pulp sourcing to buffer Brazilian harvest volatility. For New Entrants and Emerging Players: Differentiate on home-compostable coating chemistry for cold-chain meal delivery platforms where Vegware has established proof points but capacity constraints create fulfillment gaps. Target Netherlands refrigerated logistics subscriptions and UK festival catering as penetrable segments lacking dominant suppliers. Pursue private-label partnerships with meal-prep subscription services seeking sustainability credentials without certification investment. For Investors and Strategic Acquirers: Certified coating specialists with FDA and EFSA food-contact substance notification capabilities represent the most defensible acquisition archetype as REACH amendments tighten nanoparticle disclosure requirements. Long-term viability frames around industrial composting infrastructure buildout pacing in Italy and Spain. Watch municipal organics-diversion program announcements in secondary European cities as inflection indicators for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Aluminum Mold Capacity Expansion | Aviation-grade compartmentalized tooling at €150,000-400,000 per cavity locks in Lufthansa and Air France-KLM contracts. |
| OK Compost INDUSTRIAL Certification Acquisition | EN 13432 validation becomes baseline qualification for EU airline procurement consolidation. |
| Backward Integration into Bagasse Pulp Sourcing | Captive supply from Brazilian sugarcane mills hedges agricultural commodity cycle exposure. |
| Mineral Barrier Coating R&D Investment | Hot-fill performance above 85°C unlocks soup and beverage applications excluded from current specifications. |
| Home-Compostable Product Tier Launch | OK Compost HOME standards capture UK and Scandinavian residential disposal where curbside collection lags. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with airline catering procurement managers, molded fiber converter plant directors, food service sustainability officers, and composting facility operators. Secondary validation drew from EU Single-Use Plastics Directive implementation trackers, EN 13432 certification registries, municipal organics-diversion program disclosures, and SEC filings of publicly traded packaging converters. Bottom-up volume estimates from equipment capacity and pulp consumption data were triangulated against top-down market sizing from food service operator procurement surveys.
Across the analysis window, the forecasting framework modeled biodegradable meal tray demand through material chemistry segmentation, shape complexity tiers, end-user procurement sophistication levels, and application temperature requirements. CAGRs were derived from equipment installation trajectories, pulp-molding automation adoption curves, and regulatory mandate enforcement calendars. Industry-specific inputs included aviation catering contract renewal cycles and healthcare single-patient service ware conversion timelines.
Forecasts assume regulatory continuity in EU REACH and Single-Use Plastics Directive enforcement; material policy shifts would require re-modeling addressable market boundaries. Forecasts reflect assumptions regarding industrial composting facility buildout pacing and bagasse pulp supply elasticity. Revision becomes warranted when PLA resin price volatility or coating migration compliance costs cross thresholds that alter converter margin structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
North America Biodegradable Film Market
Biodegradable Packaging
Biodegradable Packaging Products Market
Biodegradable Packaging
Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Oxo Biodegradable Bags Market
Biodegradable Packaging
Biodegradable Water Bottles Market
Biodegradable Packaging
Biodegradable Packaging Market
Biodegradable Packaging
Compostable Shrink Wrap Market
Biodegradable Packaging
Oxo-Biodegradable Plastic Packaging Market
Biodegradable Packaging
Biodegradable Food Packaging Market
Biodegradable Packaging
Biopolymer Packaging Market
Biodegradable Packaging
Global Biodegradable Films Market
Biodegradable Packaging
Biodegradable Lids Market
Biodegradable Packaging
Middle East and Africa Biodegradable Film Market
Biodegradable Packaging
Clear Bioplastics Packaging Market
Biodegradable Packaging
Botanical Packaging Market
Biodegradable Packaging
Biodegradable Plastic Bags and Sacks Market