
 North America Barium Carbonate Market | 2026-2036
North America Barium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
North America Barium Carbonate Market Intelligence
Modular packaging of barium carbonate in customizable lot sizes and tailored purity grades is shifting procurement patterns among mid-sized ceramics and glass buyers. Solvay leverages its integrated baryte-to-carbonate production network to sustain cost advantages across North American distribution channels. Cimbar Performance Minerals, Inc. anchors its position through direct mine-to-plant supply relationships with domestic glass manufacturers. American Elements differentiates by offering ultra-high-purity specifications for electronics-grade applications.
Barium carbonate is an inorganic salt with the chemical formula BaCO₃, typically manufactured through the soda ash or carbonation process from barite ore, with commercial grades ranging from 98% to 99.9% purity depending on end-use requirements. It functions primarily as a fluxing agent, crystallization modifier, and raw material in the production of barium ferrites, specialty glass, and ceramic dielectrics. Precipitated barium carbonate commands premium positioning in pharmaceutical and electronics applications where particle size distribution and trace metal control determine performance. Powdered barium carbonate dominates volume flows into construction-facing ceramics and standard glass manufacturing, where cost efficiency outweighs precision specifications. Granular barium carbonate occupies a narrowing mid-tier niche in chemicals processing, facing displacement from more handleable precipitated alternatives.
EPA Resource Conservation and Recovery Act provisions govern barium-containing waste streams from carbonate production facilities, while OSHA permissible exposure limits dictate workplace handling protocols across manufacturing and downstream processing sites. Health Canada and PMRA coordinate with EPA on cross-border hazardous substance classifications affecting import-export compliance for Canadian processors. Stakeholders must monitor evolving state-level barium discharge regulations in Texas and Tennessee, where production concentration creates localized compliance exposure that could reshape supplier qualification requirements.
Market Dynamics
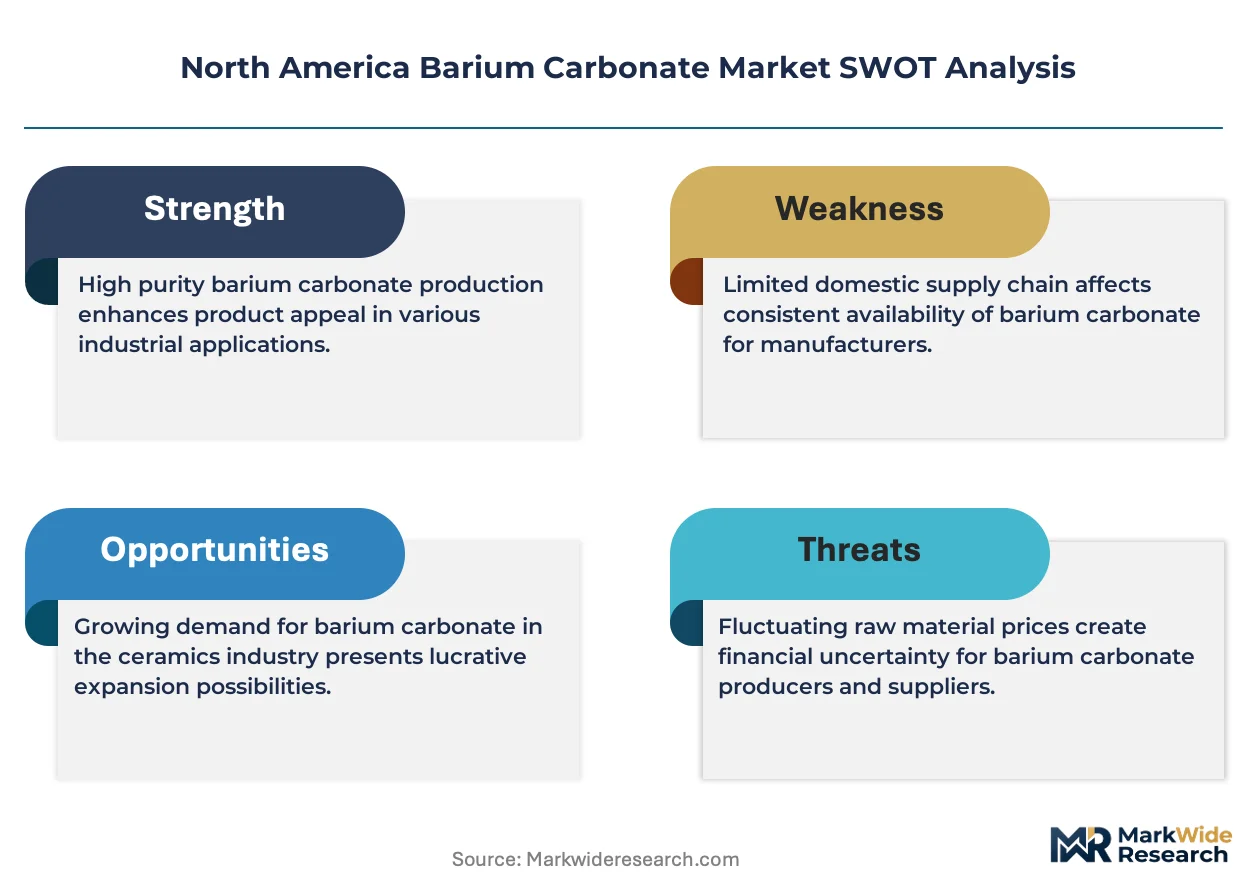
EPA Resource Conservation and Recovery Act enforcement is intensifying purification requirements across the barium carbonate supply chain, forcing processors to retool waste-handling infrastructure and redirect capital toward compliance rather than capacity expansion.
Growth Catalysts
- Specialty ceramics demand:Mexican manufacturers are scaling procurement of high-purity grades for advanced dielectric applications in multilayer ceramic capacitors.
- OSHA workplace exposure limits:Tighter permissible exposure thresholds are accelerating facility upgrades that favor established suppliers with capital reserves.
- Southeastern US industrial clustering:Refractory and glass producers concentrated near baryte processing infrastructure in Tennessee and Texas are consolidating purchase volumes.
Market Restraints
- Baryte ore supply concentration:Domestic barite mining capacity constraints in Nevada and Missouri create input volatility for carbonate converters.
- EPA hazardous waste classification:Stricter RCRA Subtitle C provisions raise disposal costs for precipitation sludge and filter cake residues.
- Substitute fluxing agents:Strontium carbonate and lithium compounds are displacing barium carbonate in certain specialty glass formulations where toxicity concerns dominate.
Strategic Opportunities
- Electronics-grade purification:Ultra-high-purity specifications for barium ferrite magnets in electric vehicle motors represent an underpenetrated specification tier.
- Canadian cross-border processing:Health Canada and PMRA coordination on hazardous substance classifications creates qualification advantages for integrated North American suppliers.
- Modular lot sizing:Customizable packaging formats are opening mid-sized ceramics buyers previously locked out by minimum order thresholds.
Industry Challenges
- Process engineer scarcity:Specialized expertise in barium salt precipitation and crystallization control is concentrating at legacy production sites.
- Legacy equipment retrofit timelines:Converting soda ash process lines to meet tightened EPA air emissions standards requires 18-24 month certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Barium Carbonate Market |
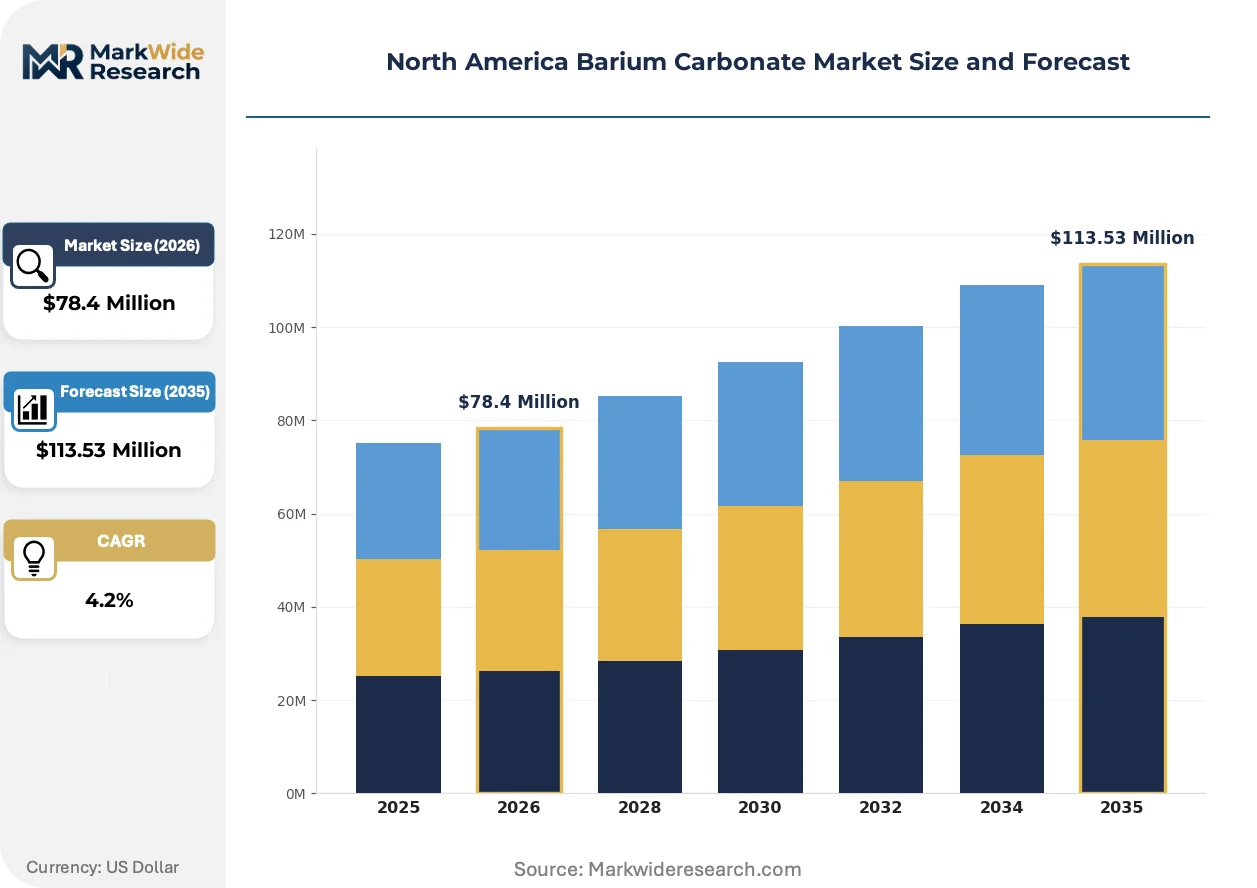
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $113.53 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Precipitated Barium Carbonate, Granular Barium Carbonate, Powdered Barium Carbonate, Others Application: Ceramics, Glass Manufacturing, Pharmaceuticals, Chemicals End User: Construction, Automotive, Electronics, Agriculture Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Chemical Products Corporation, Barium & Chemicals, Inc, Solvay, Ashland, Cimbar Performance Minerals, Inc, Honeywell International Inc., PVS Chemicals, Barox Chemicals, American Elements, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Barium Carbonate Market Strategic Shifts & Innovations
Active transformation in barium carbonate markets centers on purification technology advances, regulatory harmonization pressures, and procurement model restructuring that together reshape competitive access and margin structures.
Precipitated barium carbonate with controlled particle size distribution is expanding into pharmaceutical and electronics applications where trace metal specifications determine qualification. Specialty ceramics manufacturers in Mexico and the southeastern United States are adopting these grades at accelerated pace for multilayer capacitor dielectrics. The technology is expanding into volume segments previously served by standard powdered grades, compressing the addressable market for commodity specifications.
EPA alignment with Health Canada and PMRA on cross-border hazardous substance classifications is creating unified compliance frameworks for North American processors. This harmonization reduces dual-registration burdens for integrated suppliers while raising barriers for single-market operators. Canadian glass and ceramics importers are responding by consolidating supplier relationships with US-based producers holding dual-jurisdiction certifications.
Direct mine-to-plant supply contracts are displacing traditional distributor intermediaries in standard-grade barium carbonate procurement. Domestic glass manufacturers in Tennessee and Texas are negotiating multi-year offtake agreements with Nevada and Missouri barite operators, bypassing merchant chemical distributors. This pattern is most visible in construction-facing ceramics where price transparency and volume predictability outweigh specification flexibility.
North America Barium Carbonate Market Segmentation
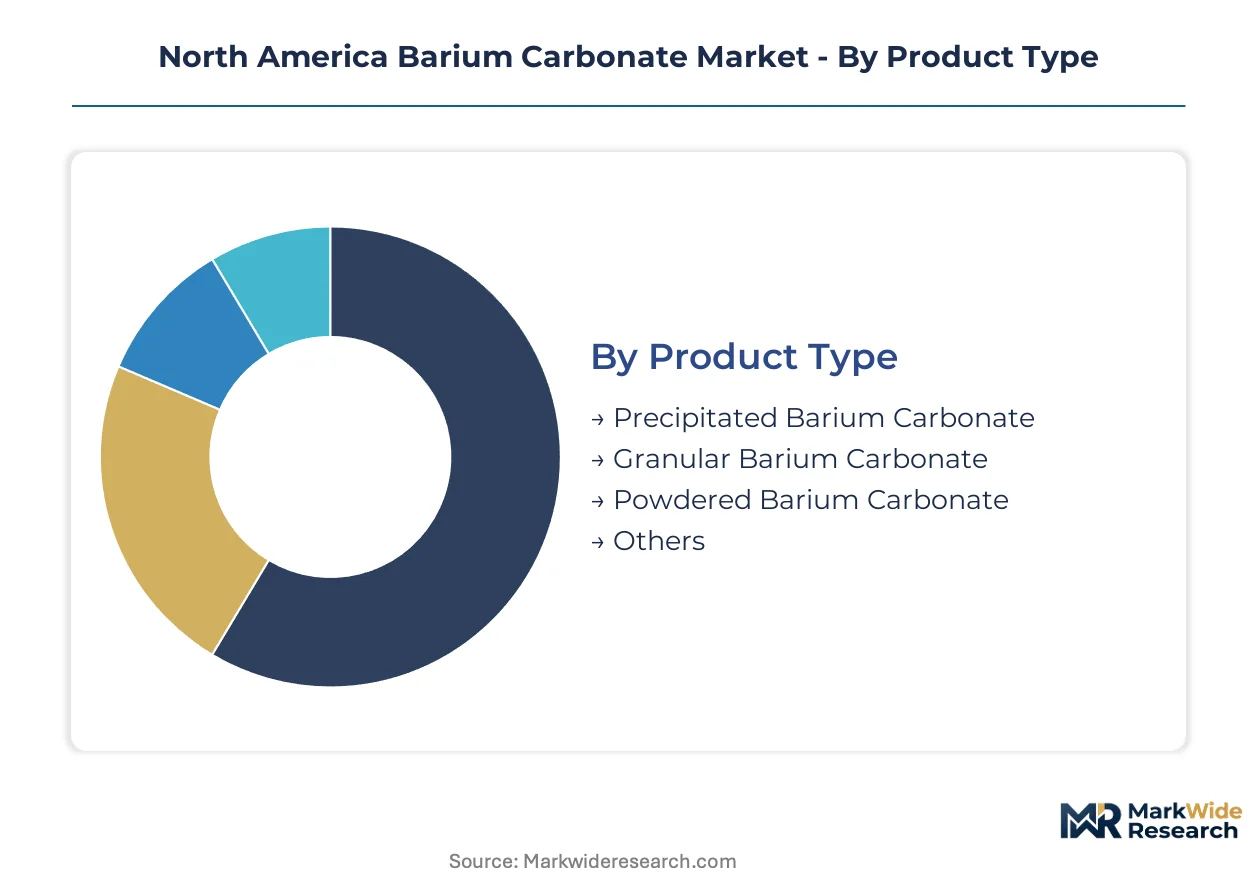
Barium carbonate procurement patterns diver sharply between integrated industrial buyers seeking captive supply arrangements and fragmented end-users dependent on merchant distribution. Specification tiers, application purity requirements, and channel access together determine supplier qualification and pricing realization across North American markets.
Product Type:
Precipitated and powdered grades anchor fundamentally different supply chain configurations — one demanding crystallization expertise, the other scale-driven milling operations.
- Precipitated Barium Carbonate:Manufactured through controlled precipitation from barium sulfide solutions, this grade achieves 99.5%+ purity with tight particle size distribution. Mexican specialty ceramics manufacturers in Tijuana and Guadalajara are scaling procurement for multilayer ceramic capacitor dielectrics where trace strontium and calcium limits determine qualification. EPA wastewater discharge permits for precipitation facilities are tightening, concentrating supply among legacy producers with upgraded environmental infrastructure.
- Powdered Barium Carbonate:Ground and classified material typically ranging 98-99% purity serves as the workhorse flux in construction ceramics and container glass. Tennessee and Texas glass manufacturers cluster near Nevada barite processing infrastructure, consolidating purchase volumes through direct mine-to-plant contracts that bypass traditional chemical distributors.
- Granular Barium Carbonate:Agglomerated form offering reduced dust exposure during handling occupies a narrowing mid-tier niche in chemicals processing.
- Others:Slurry and customized blend formulations address specialized pharmaceutical and laboratory applications requiring liquid delivery systems.
Powdered barium carbonate leads volumes today; precipitated grades are gaining share fastest.
Application:
End-use specifications range from commodity fluxing functions to precision dielectric performance, creating distinct margin pools and technical barriers.
- Ceramics:Barium carbonate functions as a flux and crystallization modifier in tile, sanitaryware, and technical ceramics. Southeastern US refractory producers near Missouri barite deposits are consolidating supplier relationships to secure volume commitments amid domestic mining capacity constraints.
- Glass Manufacturing:Primary application in optical glass, cathode ray tube faceplates, and specialty container formulations where barium improves refractive index and radiation shielding. Strontium carbonate substitution pressure is strongest in this segment where toxicity concerns dominate customer specifications.
- Pharmaceuticals:High-purity grades serve as contrast agent precursors and diagnostic reagents, with Health Canada and FDA dual-registration requirements raising qualification barriers for non-integrated suppliers.
- Chemicals:Feedstock for barium ferrite magnets, barium chloride, and other barium salts faces displacement from more handleable precipitated alternatives in downstream processing.
Glass manufacturing leads volumes today; ceramics applications are expanding most quickly.
End User:
Customer scale and technical sophistication determine whether procurement flows through distributor intermediaries or direct contractual arrangements.
- Construction:Volume buyer of standard-grade powdered barium carbonate for ceramic tile, sanitaryware, and cement additives. Texas and Tennessee construction ceramics clusters negotiate multi-year offtake agreements with Nevada barite operators, compressing distributor margins.
- Electronics:Mexican multilayer ceramic capacitor manufacturers drive demand for ultra-high-purity precipitated grades with controlled particle morphology. OSHA workplace exposure limits and EPA RCRA hazardous waste classifications are accelerating facility upgrades that favor established suppliers with capital reserves.
- Automotive:Barium ferrite magnet applications in electric vehicle motors represent an emerging specification tier requiring electronics-grade purity at automotive volume scale.
- Agriculture:Minor end-use in rodenticide and pesticide formulations faces regulatory pressure from EPA FIFRA re-registration requirements.
Construction leads volumes today; electronics represents the steepest expansion trajectory.
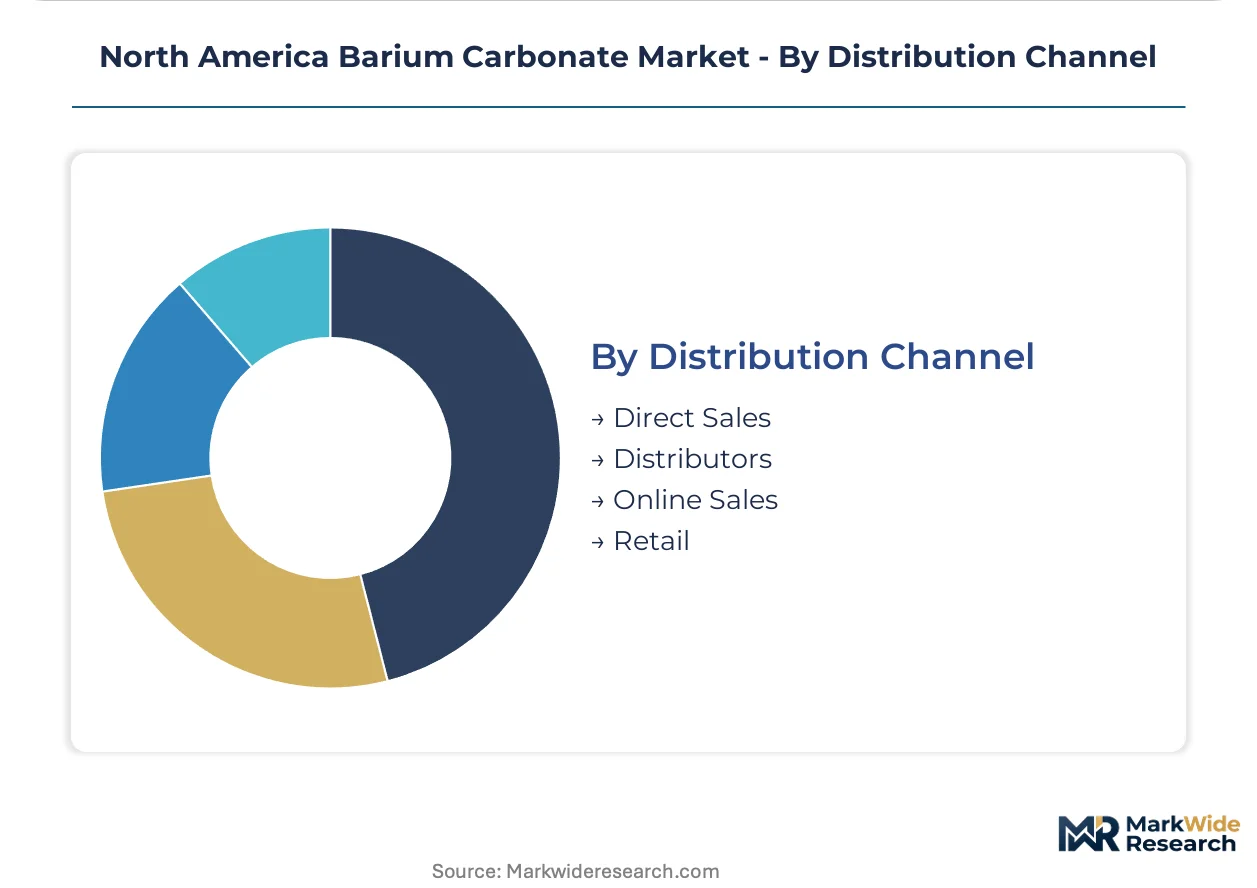
Distribution Channel:
Channel selection reflects customer scale, specification complexity, and geographic proximity to production assets.
- Direct Sales:Integrated producers maintain captive sales forces for large-volume glass and ceramics manufacturers. Solvay leverages its baryte-to-carbonate network to sustain cost advantages across direct North American distribution channels.
- Distributors:Merchant chemical distributors serve mid-sized buyers lacking volume thresholds for direct supplier relationships. Modular lot sizing initiatives are opening ceramics and glass buyers previously locked out by minimum order requirements.
- Online Sales:Digital procurement platforms address small-volume laboratory, research, and specialty chemical buyers requiring rapid fulfillment of standardized grades.
- Retail:Limited presence in agricultural and consumer product applications through farm supply and hardware channels.
Direct sales leads volumes today; online channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barium carbonate production scaled initially in the eastern United States during the mid-20th century, with subsequent capacity expansion following baryte mining development in Nevada and Missouri. The industry now distributes across three national markets with distinct regulatory and demand profiles.
United States
Tennessee and Texas glass manufacturers drive procurement volumes for standard-grade powdered barium carbonate, leveraging proximity to Nevada barite processing infrastructure. EPA Resource Conservation and Recovery Act enforcement intensifies purification requirements, forcing facility upgrades across precipitation operations. Southeastern refractory clusters near Missouri mining deposits are consolidating supplier relationships to secure volume commitments amid domestic ore constraints.
Canada
Cross-border glass and ceramics processors in Ontario and Quebec depend on US-sourced carbonate with dual-jurisdiction certification. Health Canada and PMRA coordinate hazardous substance classifications with EPA, creating unified compliance frameworks that favor integrated North American suppliers. Canadian importers are consolidating relationships with US producers holding dual-registration status to reduce qualification burdens.
Mexico
Tijuana and Guadalajara specialty ceramics manufacturers scale procurement of high-purity precipitated grades for multilayer ceramic capacitor dielectrics. Mexican environmental regulators align with EPA standards on barium waste classification, raising compliance thresholds for domestic processors. Northern border state industrial parks attract electronics-grade carbonate distribution to serve maquiladora capacitor production lines.
North America Barium Carbonate Market Key Industry Players
Premium-margin players sit above commodity-margin players across specification tiers, with ultra-high-purity grades commanding substantial price premiums over standard fluxing formulations. The vendor base organizes into three distinct tiers: integrated baryte-to-carbonate producers with captive mining assets, merchant chemical processors dependent on external ore supply, and specialty distributors serving fragmented laboratory and research buyers. Dominant competitive moves include direct mine-to-plant contract negotiation bypassing traditional distribution channels, and modular lot-sizing initiatives targeting mid-sized ceramics buyers previously excluded by minimum order thresholds.
Within the integrated production tier, Solvay leverages its baryte-to-carbonate network to sustain cost advantages across North American distribution channels. Cimbar Performance Minerals, Inc. anchors its market position through direct supply relationships with domestic glass manufacturers. American Elements occupies a position serving ultra-high-purity specifications for electronics-grade applications where trace metal control determines supplier qualification.
| Leading Market Players |
|---|
| Chemical Products Corporation |
| Barium & Chemicals, Inc |
| Solvay |
| Ashland |
| Cimbar Performance Minerals, Inc |
| Honeywell International Inc. |
| PVS Chemicals |
| Barox Chemicals |
| American Elements |
| Others |
Cost & Logistics Intelligence
Process engineer scarcity in the southeastern United States widens labor-cost spreads between legacy precipitation facilities and commodity grinding operations, translating into premium-mid-economy pricing differentiation across the three main specification tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates electronics-grade precipitated material from construction-facing powdered grades and narrowing granular formulations. Price differentiation hinges on trace metal certification thresholds and volume scale commitments, with Mexican multilayer capacitor manufacturers showing lowest price sensitivity. Cost compression in standard-grade segments is intensifying because Tennessee and Texas glass producers negotiate multi-year offtake agreements directly with Nevada barite operators.
Supply Chain Analysis
Dual-sourcing requirements from EPA-permitted precipitation facilities and Health Canada-registered importers mandate multi-supplier qualification for cross-border processors in Ontario and Quebec. Geographic supply concentration centers on Nevada and Missouri for domestic barite ore, with supplemental feedstock drawing from Mexican northern border state industrial parks. Single-source vulnerability persists around specialized crystallization expertise concentrated at legacy Tennessee production sites. Distribution runs through direct mine-to-plant contracts for volume buyers, with merchant chemical distributors serving fragmented mid-sized ceramics accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by Mexican specialty ceramics manufacturers scaling procurement toward ultra-high-purity precipitated grades for advanced dielectric applications.
For Market Incumbents: Lock in multi-year offtake agreements with Nevada and Missouri barite operators before domestic mining capacity constraints tighten further. Accelerate EPA wastewater discharge permit upgrades at precipitation facilities to outpace compliance timelines that stricter RCRA Subtitle C provisions impose on smaller competitors. For New Entrants and Emerging Players: Enter via electronics-grade purification for barium ferrite magnet applications in electric vehicle motors, an underpenetrated specification tier where automotive volume scale meets electronics-grade purity requirements. Target Canadian cross-border processors in Ontario seeking dual-jurisdiction certified suppliers to reduce Health Canada and PMRA qualification burdens. For Investors and Strategic Acquirers: Valuations sit cheapest among merchant chemical processors dependent on external ore supply yet possessing upgradeable precipitation infrastructure. Long-term viability favors integrated baryte-to-carbonate producers with captive Nevada mining assets and existing EPA environmental infrastructure. The signal to watch is OSHA workplace exposure limit enforcement intensity, which accelerates facility upgrade timelines and concentrates supply among capital-reserved legacy operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barite Mining | Captive Nevada ore supply insulates Solvay and Cimbar from domestic mining capacity constraints and input volatility. |
| Electronics-Grade Purification Investment | Ultra-high-purity precipitation capability qualifies suppliers for Mexican multilayer ceramic capacitor dielectric procurement. |
| EPA Environmental Infrastructure Upgrade | Upgraded wastewater discharge permits create compliance moats against smaller competitors facing 18-24 month certification cycles. |
| Modular Lot Sizing Program | Customizable packaging formats open mid-sized Tennessee and Texas ceramics buyers previously excluded by minimum order thresholds. |
| Dual-Jurisdiction Certification | Health Canada and EPA dual-registration reduces qualification burdens for Canadian glass and ceramics importers consolidating supplier relationships. |
Research Approach
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market combining interviews with plant managers at precipitation facilities, procurement leads at Tennessee and Texas glass manufacturers, distribution channel partners, and technical R&D directors at specialty ceramics producers. Secondary validation draws from EPA RCRA enforcement records, Health Canada PMRA registration databases, SEC 10-K filings from integrated chemical producers, and customs trade data tracking barite ore and carbonate flows across North American borders. Bottom-up volume modeling triangulates against top-down value estimates across product type, application, and end-user segmentation.
Rate-of-change decomposition separates volume growth from price realization across the analysis window, with segmentation modeling across grade tier, end-use industry, packaging format, and regional production hub. CAGRs derive from regression against historical production capacity utilization, regulatory enforcement intensity indices, and substitution elasticity estimates for strontium carbonate in specialty glass formulations. Industry-specific forecast inputs include Mexican maquiladora capacitor production line expansion schedules and Nevada barite mining permit approval timelines.
Inputs from EPA enforcement databases and Health Canada registration systems were available through the study window; gaps in real-time OSHA workplace exposure monitoring data introduce uncertainty bands around facility upgrade cost assumptions. Deviation in EPA RCRA Subtitle C hazardous waste classification stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Cerium Nitride Market
Ceramics
USA and Canada Alumina Market
Ceramics
Titanium Carbide Market
Ceramics
Ceramic Ware Market
Ceramics
Tetra-N-Butyl Titanate Market
Ceramics
Zirconia Ceramics Market
Ceramics
2N High Purity Alumina Market
Ceramics
Heat-Resistant Ceramic Tableware Market
Ceramics
Titanates Market
Ceramics
East Africa Ceramic Tiles Market
Ceramics
Aluminium Nitride Market
Ceramics
Stoneware Market
Ceramics
Cordierite Market
Ceramics
Asia-Pacific Activated Alumina Market
Ceramics
White Fused Alumina Market
Ceramics
Strontium Carbonate Market