
 Zirconia Ceramics Market | 2026-2036
Zirconia Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Zirconia Ceramics Market Analytics
The performance gap between premium yttria-stabilized grades and commodity alumina-toughened alternatives is broadening. Tosoh Corporation leverages captive zircon sand refining to sustain cost discipline across electronic substrate grades. Morgan Advanced Materials anchors European aerospace thermal barrier supply through specialized coating formulations. Kyocera Corporation dominates Japanese dental block exports with tightly controlled powder metallurgy protocols.
Zirconia ceramics denote yttria-stabilized tetragonal zirconia polycrystal (Y-TZP) and related phase-engineered oxide ceramics, typically containing 3-8 mol% yttria and sintered at 1400-1550°C to achieve fracture toughness exceeding 5 MPa·m½ for load-bearing prosthetics and wear components. Dental ceramics leads absolute revenue generation through CAD/CAM millable disc demand, while functional ceramics represents the fastest-expanding margin pool as solid oxide fuel cell electrolyte adoption accelerates. Industrial ceramics occupies a mature volume position in pump seals and valve components where alumina substitution cycles have stabilized.
FDA 510(k) pathways govern US dental implant clearance timelines, while EU MDR recertification pressures force European producers toward enhanced biocompatibility documentation. China's MEE enforces dual carbon compliance on energy-intensive sintering operations, reshaping regional cost structures. Stakeholders must monitor phase-purity certification standards as medical and energy applications diverge in specification stringency.
Market Dynamics
Phase-purity certification divergence between medical and energy applications is fragmenting supplier qualification pathways, forcing manufacturers to maintain parallel production protocols for dental implants versus solid oxide fuel cell electrolytes.
Growth Catalysts
- Solid oxide fuel cell electrolyte demand:Energy sector decarbonization mandates in the European Union and Japan are accelerating Y-TZP membrane procurement for stationary power generation systems.
- China's MEE dual carbon enforcement:Tighter emission standards for ceramic sintering furnaces are consolidating production toward energy-efficient electric kiln operators with captive renewable power.
- CAD/CAM dental block standardization:Open-architecture milling system compatibility is expanding addressable clinic bases beyond proprietary equipment ecosystems.
Market Restraints
- Zircon sand supply concentration:Heavy mineral sand deposits in Australia and South Africa dominate feedstock availability, exposing processors to geopolitical disruption and shipping cost volatility.
- EU MDR recertification burden:Enhanced biocompatibility documentation requirements for dental implants are extending clearance timelines and elevating compliance costs for European producers.
- Alumina-toughened ceramic substitution:Commodity oxide ceramics satisfy cost-sensitive industrial seal and valve applications where fracture toughness requirements fall below 5 MPa·m½.
Strategic Opportunities
- India's dental tourism corridor:Mumbai and Chennai clinic clusters are importing premium Y-TZP blocks for same-day crown fabrication serving Gulf and Southeast Asian patients.
- Japan's precision manufacturing ecosystem:METI industrial technology roadmaps prioritize zirconia bearing and cutting tool development for semiconductor equipment subsystems.
- Additive manufacturing convergence:Binder jet and lithography-based ceramic printing are enabling complex lattice structures for orthopedic scaffolds previously impossible via subtractive machining.
Industry Challenges
- Phase stability engineering talent scarcity:Yttria dopant distribution control and tetragonal phase retention expertise concentrate among senior powder metallurgists approaching retirement in Japanese and German research institutes.
- FDA 510(k) predicate device navigation:Dental implant manufacturers face narrowing equivalence pathways as FDA tightens substantial equivalence standards for new zirconia abutment designs.
- Sintering furnace electrification capex:China's MEE carbon compliance deadlines require gas-fired kiln replacement with electric alternatives costing 2-3x per unit capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zirconia Ceramics Market |
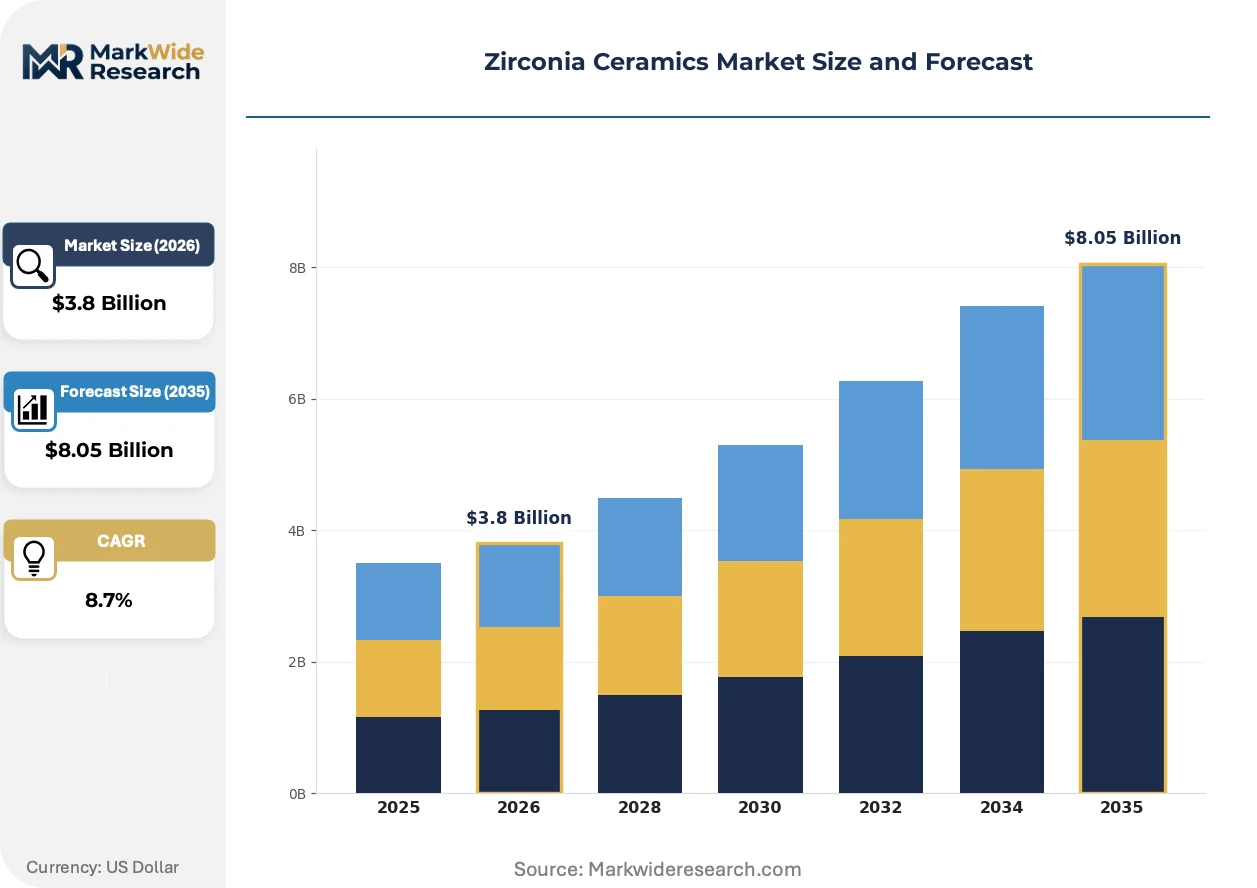
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dental Ceramics, Industrial Ceramics, Structural Ceramics, Functional Ceramics End User: Healthcare, Aerospace, Electronics, Automotive Form: Blocks, Discs, Coatings, Compounds Application: Prosthetics, Insulation, Components, Tools |
| Companies Covered | Morgan Advanced Materials, Tosoh Corporation, CoorsTek, Inc., NGK Spark Plug Co., Ltd., Saint-Gobain Ceramics & Plastics, CeramTec GmbH, Kyocera Corporation, Nishimura Advanced Ceramics Co., Ltd., 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zirconia Ceramics Market Evolving Landscape
Digital workflow integration is compressing the traditional laboratory-to-clinic supply chain for dental prosthetics while simultaneously enabling mass customization in industrial component production.
Additive manufacturing of zirconia ceramics is absorbing investment from orthopedic implant developers seeking patient-specific geometries. German and Swiss medical device manufacturers are piloting lithography-based ceramic printing for acetabular cups and spinal cages. The technology is absorbing market share from five-axis milling centers for complex lattice structures.
China's MEE dual carbon enforcement is reshaping regional competitive positioning. Sintering operations must document renewable electricity procurement or install carbon capture retrofits by 2025. Energy-intensive producers in Shandong and Jiangsu provinces are relocating to western regions with hydroelectric surplus or exiting the market entirely.
Japanese dental clinics are consolidating procurement through integrated practice management platforms. Tokyo and Osaka clinic chains now specify open-architecture CAD/CAM block compatibility, disintermediating proprietary system vendors. This preference shift favors Taiwanese and Korean block suppliers offering ISO 13356 certification without equipment lock-in.
Zirconia Ceramics Market Segmentation
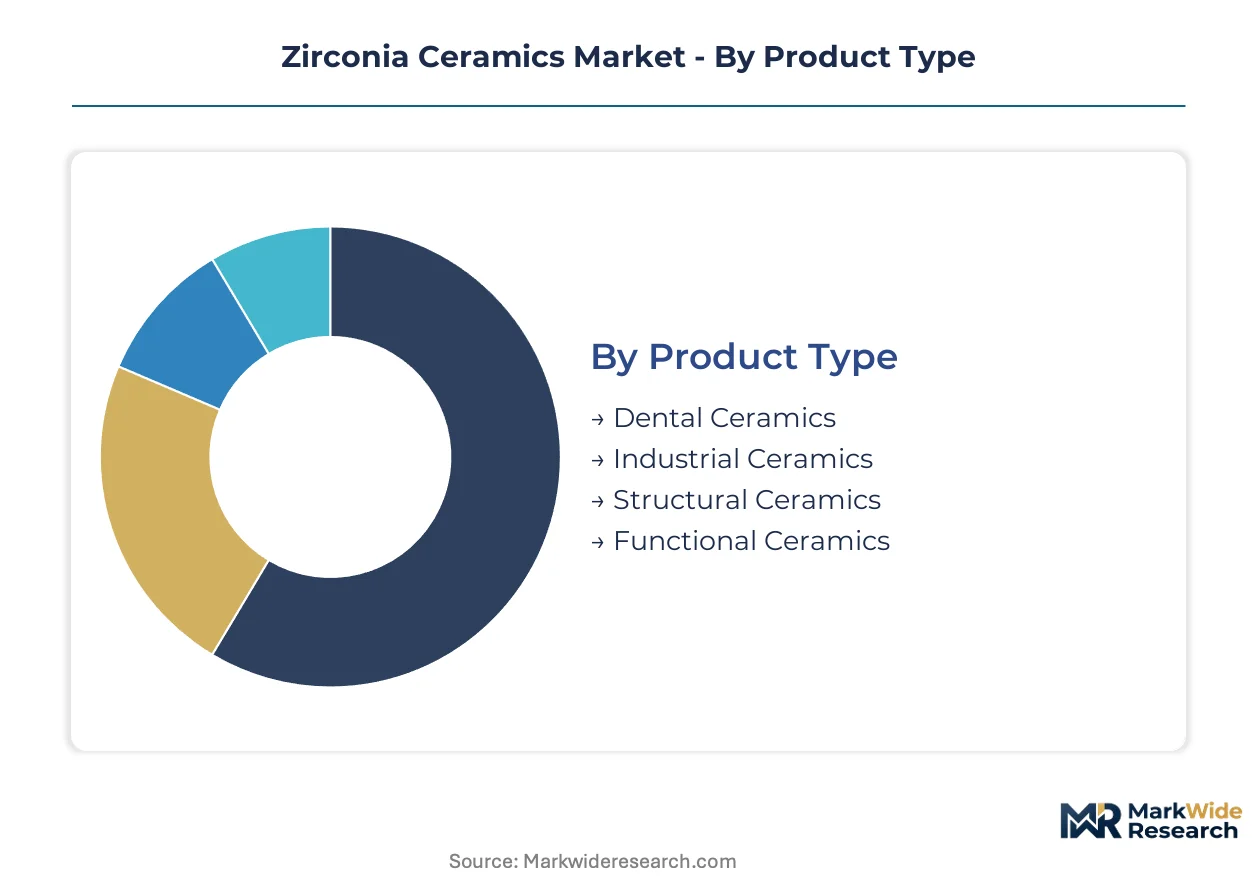
Segmentation in zirconia ceramics reveals divergent capital requirements and margin structures across medical, industrial, and energy applications. Each category carries distinct qualification barriers and supply chain configurations that shape supplier economics.
Product Type:
Dental ceramics command the steepest upfront investment in ISO 13356-certified cleanroom facilities and precision powder metallurgy equipment. Functional ceramics require specialized phase-purity engineering for solid oxide fuel cell electrolytes.
- Dental Ceramics:Y-TZP millable blocks and abutments containing 3-5 mol% yttria achieve fracture toughness above 5 MPa·m½ for crown and bridge applications. Demand concentrates in Japan's precision manufacturing corridor and Germany's dental laboratory clusters, driven by CAD/CAM workflow standardization and open-architecture milling system adoption.
- Functional Ceramics:Phase-engineered Y-TZP membranes for solid oxide fuel cell electrolytes and oxygen sensors operate at elevated temperatures requiring dopant distribution control. Procurement is accelerating in the European Union and Japan under energy sector decarbonization mandates for stationary power generation.
- Industrial Ceramics:Pump seals, valve components, and wear parts where alumina substitution cycles have stabilized.
- Structural Ceramics:Load-bearing components requiring high flexural strength for mechanical applications.
Dental ceramics absorbs the bulk of installed capacity; functional ceramics is expanding most quickly.
End User:
Healthcare end users impose the most stringent biocompatibility documentation and regulatory clearance timelines. Aerospace procurement concentrates among tier-one thermal barrier coating applicators with specialized formulation expertise.
- Healthcare:Dental prosthetics and orthopedic implants requiring FDA 510(k) or EU MDR clearance. Demand clusters in Mumbai and Chennai clinic corridors serving Gulf and Southeast Asian dental tourism patients.
- Aerospace:Thermal barrier coatings for turbine blades utilizing yttria-stabilized zirconia formulations. European producers anchor supply through specialized coating protocols for jet engine manufacturers.
- Electronics:Substrate materials and oxygen sensors for semiconductor equipment subsystems prioritized under Japan METI industrial technology roadmaps.
- Automotive:Oxygen sensors and wear components where cost-performance tradeoffs favor alumina-toughened alternatives in mass-market applications.
Healthcare captures the dominant revenue share; aerospace applications are climbing the fastest as engine efficiency standards tighten.
Form:
Block and disc manufacturing requires captive zircon sand refining and sintering furnace infrastructure with documented renewable electricity procurement under China's MEE dual carbon enforcement.
- Blocks:CAD/CAM millable formats for dental prosthetics, with open-architecture compatibility expanding addressable clinic bases beyond proprietary equipment ecosystems.
- Discs:Standardized geometries for five-axis milling centers in dental laboratories, facing displacement from additive manufacturing for complex lattice structures.
- Coatings:Thermal spray and electron beam physical vapor deposition formats for aerospace thermal barrier applications requiring specialized application equipment.
- Compounds:Feedstock powders and suspensions for binder jet and lithography-based ceramic printing enabling patient-specific orthopedic geometries.
Blocks and discs together hold the majority of current output value; compounds are gaining share fastest as additive manufacturing converges with medical device development.
Application:
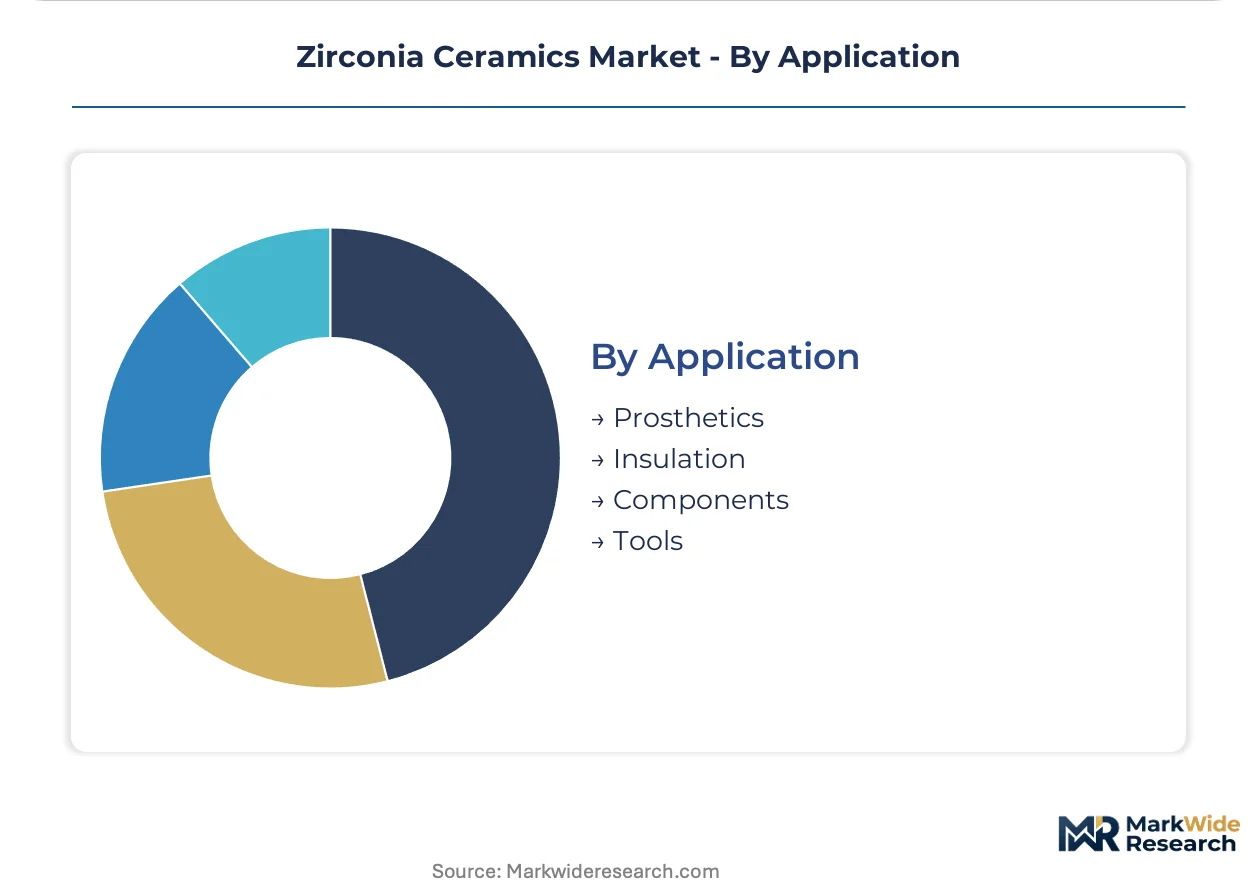
Prosthetics applications carry the highest qualification burden through phase-purity certification and predicate device navigation. Insulation applications operate at mature volume positions with stabilized substitution dynamics.
- Prosthetics:Dental crowns, bridges, and orthopedic implants requiring tetragonal phase retention and yttria dopant distribution control for load-bearing performance.
- Insulation:Refractory linings and thermal barriers where alumina-zirconia composites compete on cost in high-temperature industrial furnaces.
- Components:Bearings, cutting tools, and pump seals for semiconductor equipment subsystems developed under Japanese precision manufacturing priorities.
- Tools:Ceramic cutting inserts and grinding media subject to price pressure from commodity oxide alternatives in cost-sensitive industrial markets.
Prosthetics commands premium pricing tiers; components for semiconductor equipment show the steepest expansion trajectory as fabrication node advancement drives material specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nagoya anchors Japanese precision manufacturing demand for zirconia bearings and cutting tools serving semiconductor equipment subsystems. German dental laboratory clusters drive European CAD/CAM block consumption. Chinese sintering operations face MEE dual carbon compliance deadlines.
Japan
Kyocera Corporation's powder metallurgy protocols dominate dental block exports from Osaka. METI industrial technology roadmaps prioritize zirconia component development for fabrication node advancement. Nagoya's precision manufacturing corridor concentrates demand for bearing and cutting tool applications.
Germany
EU MDR recertification pressures force enhanced biocompatibility documentation for dental implant producers. ECHA REACH compliance governs yttria dopant handling in ceramic processing. Dental laboratory clusters in Baden-Württemberg and Bavaria standardize open-architecture milling workflows.
China
MEE dual carbon enforcement tightens emission standards for ceramic sintering furnaces by 2025. Shandong and Jiangsu producers relocate to western hydroelectric regions or exit entirely. Zhengzhou and Luoyang clusters consolidate toward electric kiln operators with captive renewable power.
United States
FDA 510(k) pathways govern dental implant clearance timelines with narrowing predicate device equivalence. EPA emissions oversight affects thermal spray coating operations for aerospace applications. Greater Boston and Pacific Northwest medical device clusters pilot additive manufacturing for orthopedic scaffolds.
India
Mumbai and Chennai clinic corridors import premium Y-TZP blocks for same-day crown fabrication. CDSCO medical device regulations govern import clearance for dental prosthetics. Dental tourism infrastructure serves Gulf and Southeast Asian patients seeking cost-competitive CAD/CAM procedures.
Zirconia Ceramics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and phase-purity dimensions. The vendor base stratifies between ISO 13356-certified medical specialists and industrial ceramics generalists. Three archetypes dominate: captive zircon sand refiners, precision powder metallurgy houses, and diversified advanced materials conglomerates. Capacity expansion and strategic technology licensing represent the dominant competitive moves.
Among Japanese precision ceramics specialists, Kyocera Corporation and NGK Spark Plug Co., Ltd. exemplify the powder metallurgy archetype with tightly controlled protocols. Tosoh Corporation represents the captive refining model with upstream integration into zircon sand processing. Morgan Advanced Materials and Saint-Gobain Ceramics & Plastics occupy positions within the diversified advanced materials tier, spanning multiple oxide ceramic categories beyond zirconia specialization.
| Leading Market Players |
|---|
| Morgan Advanced Materials |
| Tosoh Corporation |
| CoorsTek, Inc. |
| NGK Spark Plug Co., Ltd. |
| Saint-Gobain Ceramics & Plastics |
| CeramTec GmbH |
| Kyocera Corporation |
| Nishimura Advanced Ceramics Co., Ltd. |
| 3M Company |
| Others |
Value Network & Pricing Analysis
Electric kiln conversion under China's MEE dual carbon enforcement is compressing production economics while concentrating supply among operators with captive renewable power contracts. This technology transition simultaneously elevates fixed costs for sintering capacity and reshapes regional competitive positioning as gas-fired operators in Shandong and Jiangsu provinces face compliance deadlines or exit.
Pricing Analysis
Value-based pricing anchored to CAD/CAM milling throughput and crown fabrication yield dominates dental block procurement. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13356 certification grade and yttria dopant distribution control. Cost compression in commodity alumina-toughened alternatives is intensifying because industrial seal applications tolerate fracture toughness below 5 MPa·m½. Dental laboratories in Germany and Japan show least price sensitivity due to open-architecture workflow standardization.
Supply Chain Analysis
Scrap Y-TZP milling waste and spent sintering kiln refractories flow through specialized ceramic powder recyclers in Japan and Germany. Heavy mineral sand deposits in Australia and South Africa dominate zircon sand feedstock availability. Yttrium oxide supply draws from ion-adsorption clay processing in southern China. Single-source vulnerability in zircon sand concentrate exposes processors to shipping cost volatility. Distribution runs through dental laboratory clusters and precision manufacturing corridors rather than commodity distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as captive zircon sand refining and renewable-powered sintering capacity determine cost discipline. Players are pursuing upstream control over heavy mineral sand processing to secure feedstock margin capture.
For Market Incumbents: Deepen backward integration into zircon sand concentrate processing to offset feedstock price volatility from Australian and South African suppliers. Expand electric kiln capacity in western Chinese provinces with hydroelectric surplus before MEE compliance deadlines consolidate supply. Alumina-toughened substitution in industrial seals threatens volume positions below 5 MPa·m½ fracture toughness thresholds. For New Entrants and Emerging Players: Direct-to-clinic digital procurement platforms offer the lowest-friction route into Japan's consolidating dental clinic chains. White-space exists in Indian dental tourism corridors importing premium Y-TZP blocks for same-day crown fabrication. Binder jet printing compounds for orthopedic lattice structures represent the most penetrable additive manufacturing segment. Target open-architecture ISO 13356 certification without proprietary equipment lock-in. For Investors and Strategic Acquirers: Re-rating potential sits with captive refining specialists given MEE dual carbon enforcement and renewable power access differentiation. Long-term viability over a 5-10 year window favors operators with documented tetragonal phase retention expertise and powder metallurgy protocols. Acquisition targets include mid-cap sintering houses with electric kiln infrastructure and western China location. Monitor yttrium oxide export licensing from Chinese ion-adsorption clay processors as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zircon Sand Refining | Tosoh Corporation's captive processing secures cost discipline across electronic substrate grades. |
| Electric Kiln Capacity Expansion | MEE dual carbon deadlines in China force gas-fired sintering replacement with renewable-powered alternatives. |
| Open-Architecture CAD/CAM Certification | Taiwanese and Korean block suppliers disintermediate proprietary system vendors through ISO 13356 compatibility. |
| Additive Manufacturing Compounds Development | German and Swiss orthopedic developers pilot lithography-based ceramic printing for patient-specific geometries. |
| Solid Oxide Fuel Cell Electrolyte Partnerships | European Union and Japanese decarbonization mandates accelerate Y-TZP membrane procurement for stationary power. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with powder metallurgy directors, dental laboratory procurement managers, and ceramic sintering plant engineers combined with FDA 510(k) databases, ECHA REACH submissions, and China MEE compliance disclosures. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across product categories.
Reconciliation of production capacity data, import-export flows, and end-use consumption patterns informed the analytical framework. Segmentation dimensions modeled include product type, end-user industry, form factor, and geographic production hub. CAGRs derived from slope-log analysis of historical trajectory and policy-driven inflection points. Forecast inputs incorporated MEE dual carbon enforcement timelines and EU MDR recertification burden effects on clearance timelines.
The model holds under stable zircon sand supply and continued MEE enforcement; deviation in yttrium oxide export restrictions or renewable power cost spikes would shift regional competitive positioning. Forecasts reflect assumptions about phase-purity certification divergence between medical and energy applications. Practitioners should monitor Chinese ion-adsorption clay processor licensing and western China hydroelectric capacity allocation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Calcined Bauxite Market
Ceramics
Ceramic Pigments Market
Ceramics
Global High Performance Ceramic Coatings Market
Ceramics
Iran Ceramic Tiles Market
Ceramics
Automotive Ceramics Market
Ceramics
Low Density Ceramic Proppant Market
Ceramics
Europe Ceramic Tiles Market
Ceramics
Advanced Sintering Technologies Market
Ceramics
Potassium Silicate Market
Ceramics
Barium Carbonate Powder Market
Ceramics
Nanoceramic Powder Market
Ceramics
Construction Ceramics Market
Ceramics
Relaxor Ferroelectric Ceramics Market
Ceramics
Clay Market
Ceramics
Activated Alumina Market
Ceramics
North America Ceramic Coatings Market