
 Strontium Carbonate Market | 2026-2036
Strontium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Strontium Carbonate Market Analysis
Buyer concentration in the glass manufacturing sector is decoupling from traditional ceramics demand as electronics and pharmaceutical applications fragment the customer base. Solvay leverages its European production footprint to serve high-specification pharmaceutical grade requirements. Guizhou Redstar Developing Company Limited anchors supply security through captive access to China's celestite ore reserves. Sakai Chemical Industry differentiates via precision control over particle size distribution for ferrite magnet applications.
Strontium carbonate is an inorganic salt with the chemical formula SrCO3, typically produced through black ash reduction of celestite ore or chemical synthesis from strontium sulfide, with purity grades ranging from technical grade at 97% to high-purity electronic grade exceeding 99.5%. The compound functions primarily as a fluxing agent, color stabilizer, and raw material precursor in industrial manufacturing processes. Synthetic strontium carbonate dominates volume flows due to consistent quality and scalable output, while high purity grades command concentrated margin pools in electronics and pharmaceutical channels. Glass manufacturing retains the largest application share though electronics is expanding fastest as ferrite magnet demand accelerates for electric drivetrains and consumer devices.
China's MEE enforces stricter wastewater discharge limits on strontium chemical processors, elevating capital requirements for environmental compliance. REACH registration obligations in Europe constrain market access for non-compliant Asian exporters serving specialty chemical buyers. The EU Green Deal's embodied carbon tracking is pressuring downstream users to document supply chain emissions from strontium raw material extraction through finished goods. Stakeholders must monitor regulatory divergence between Chinese environmental enforcement and European chemical registration requirements when configuring multi-region sourcing strategies.
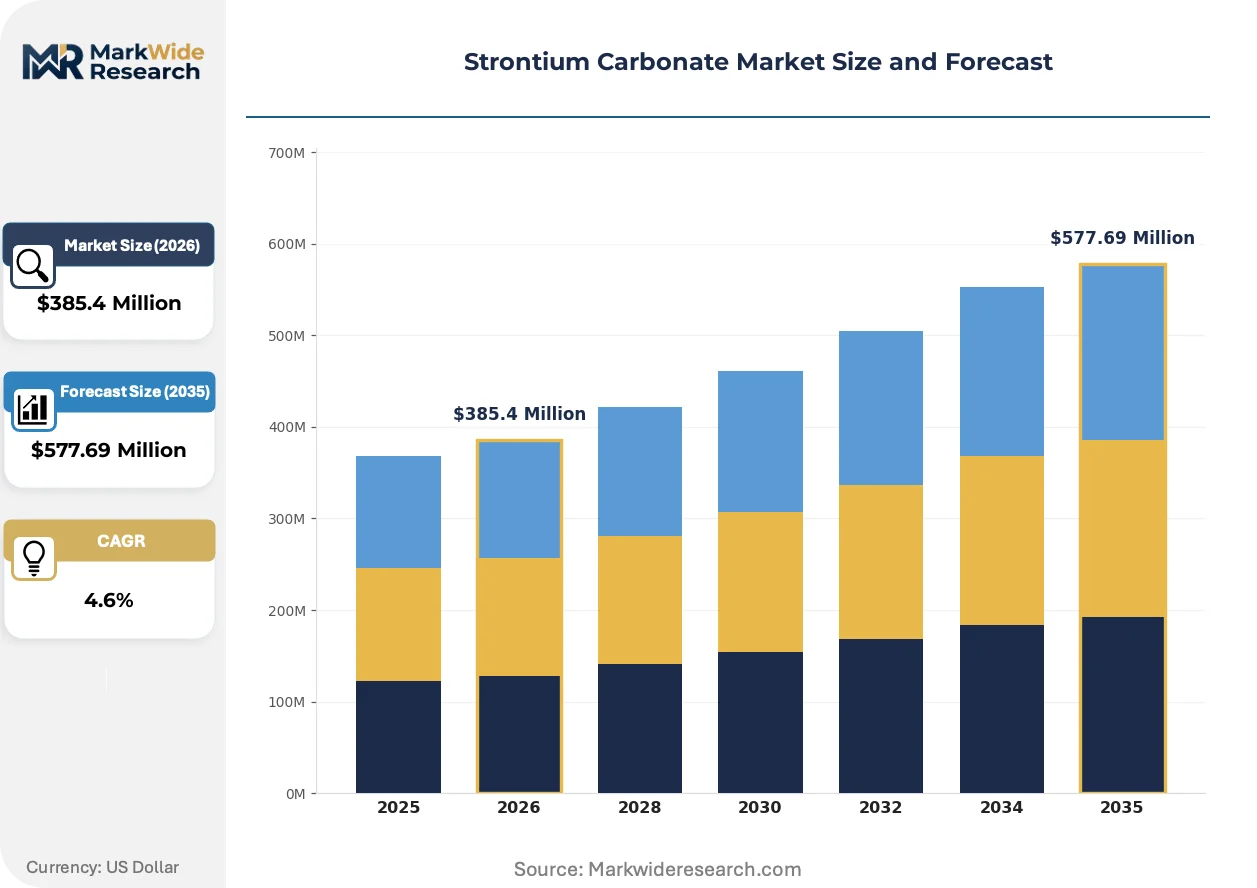
Market Dynamics
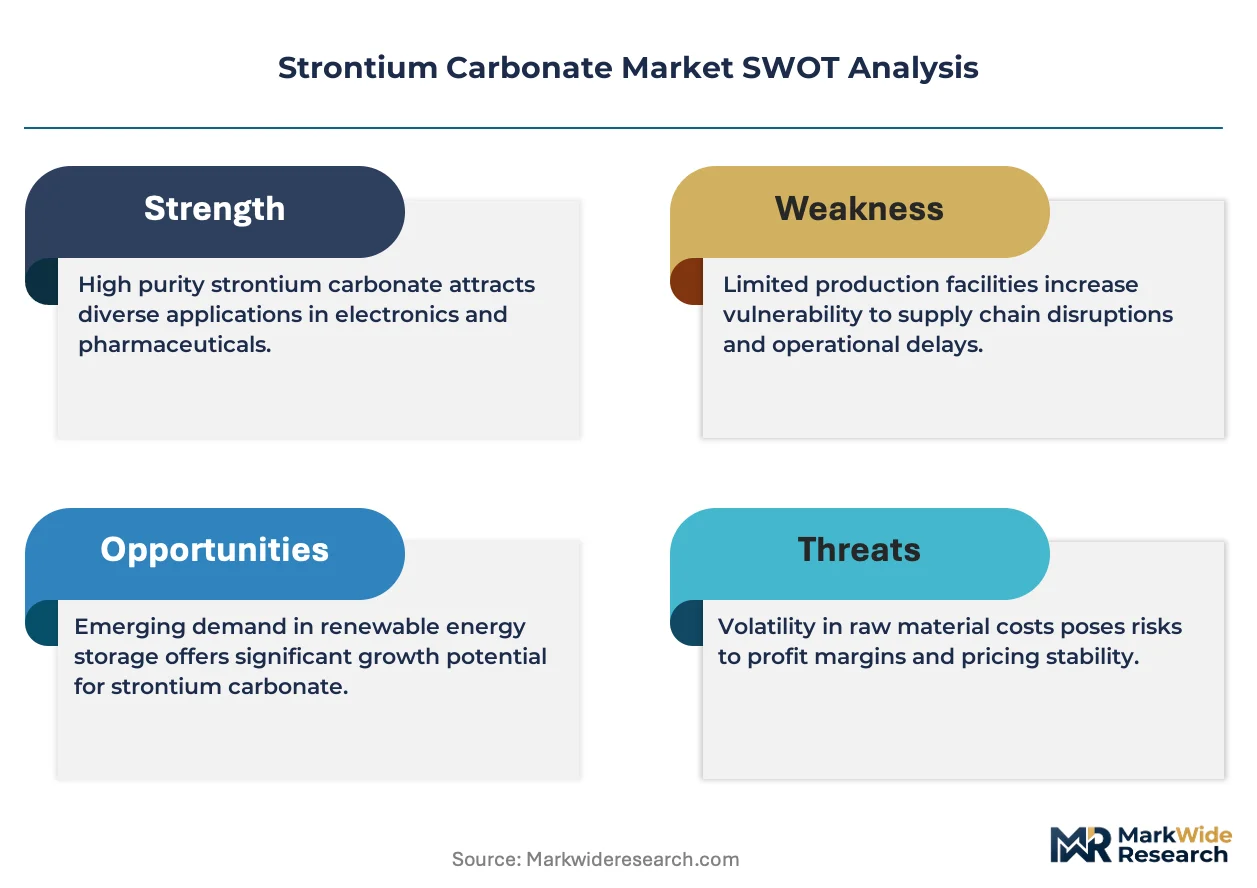
China's MEE wastewater discharge limits are forcing strontium carbonate processors to redirect capital from expansion toward environmental compliance equipment, compressing capacity additions while elevating unit economics for compliant producers.
Growth Catalysts
- Ferrite magnet demand:Electric drivetrain manufacturers in Japan and South Korea are expanding procurement of high-purity strontium carbonate for sintered ferrite core production. Battery-electric vehicle motor programs are accelerating qualification timelines.
- REACH registration:European chemical registration requirements are filtering out non-compliant Asian exporters, creating margin expansion for registered suppliers serving pharmaceutical grade buyers. ECHA enforcement is tightening documentation standards.
- Celestite ore access:Captive mining rights in Chongqing and Guizhou provinces are securing feedstock for integrated Chinese producers. Ore quality variations are driving selective extraction toward higher-grade seams.
Market Restraints
- Energy cost volatility:Natural gas and coal price swings in China directly impact black ash reduction process economics. Process heat requirements expose margins to input cost spikes.
- Supply concentration:Eastern Chinese provinces control over 70% of global synthetic strontium carbonate output. Geographic clustering creates systemic disruption risk from localized environmental enforcement or logistics constraints.
- Barium carbonate substitution:Lower-cost BaCO3 is displacing strontium carbonate in certain glass fluxing applications where color performance requirements permit. Ceramic tile manufacturers are testing reformulated batches.
Strategic Opportunities
- Pharmaceutical grade expansion:US FDA and EMA compliance pathways are opening specialized margin pools for producers with documented GMP manufacturing. Strontium ranelate precursor demand is stabilizing after patent cliff adjustments.
- EU Green Deal embodied carbon tracking:Downstream magnet and glass manufacturers must document Scope 3 emissions from strontium extraction through finished goods. Early-compliant suppliers are securing preferred supplier status.
- Particle size precision:Ferrite magnet producers are specifying tighter particle size distribution tolerances for high-frequency applications. Precision milling capabilities are differentiating technical grade suppliers.
Industry Challenges
- Wastewater treatment capex:China's MEE standards require strontium sulfide leaching operations to install heavy metal precipitation and zero-liquid discharge systems. Retrofit timelines are compressing against enforcement deadlines.
- REACH dossier maintenance:European chemical registration requires ongoing substance evaluation updates and toxicity data generation. Registration costs are concentrating market access among well-capitalized producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strontium Carbonate Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $577.69 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Strontium Carbonate, Synthetic Strontium Carbonate, High Purity Strontium Carbonate, Low Purity Strontium Carbonate Application: Glass Manufacturing, Ceramics Production, Electronics, Pharmaceuticals End User: Construction, Healthcare, Consumer Goods, Agriculture Distribution Channel: Direct Sales, Wholesale, Online Retail, Third-Party Distributors |
| Companies Covered | Solvay, Kandelium, Fertiberia, Sakai Chemical Industry, Guizhou Redstar Developing Company Limited, Nanjing Jinyan Strontium Industry, Shenzhou Jiaxin Chemical, Honjo Chemical Corporation, Zaozhuang Yongli Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strontium Carbonate Market Emerging Trajectories
Continuous flow synthesis and electrochemical reduction methods are displacing batch black ash processing, enabling strontium carbonate producers to tighten purity consistency while modulating output volumes against ferrite magnet demand signals.
Electrochemical strontium carbonate synthesis is decentralizing production economics by enabling smaller-scale units with reduced thermal energy requirements. Japanese specialty chemical producers are piloting membrane cell configurations for electronic grade output. This technology is compressing the minimum efficient scale for high-purity production, fragmenting supply concentration.
REACH authorization and restriction procedures are extending compliance timelines for strontium compound importers into the European Union. ECHA's 2024 substance evaluation work program is prioritizing strontium salts for hazard reassessment. Pharmaceutical and electronics grade suppliers are accelerating substance data gap closures to preempt regulatory friction.
Magnet procurement teams are consolidating supplier relationships around dual-certified sources with both ISO 9001 quality management and IATF 16949 automotive quality credentials. Tier-1 ferrite magnet producers in Japan are reducing qualified supplier lists from multiple sources to two or three strategic partners. This consolidation is most visible in the Kansai region's electric motor component cluster.
Strontium Carbonate Market Segmentation
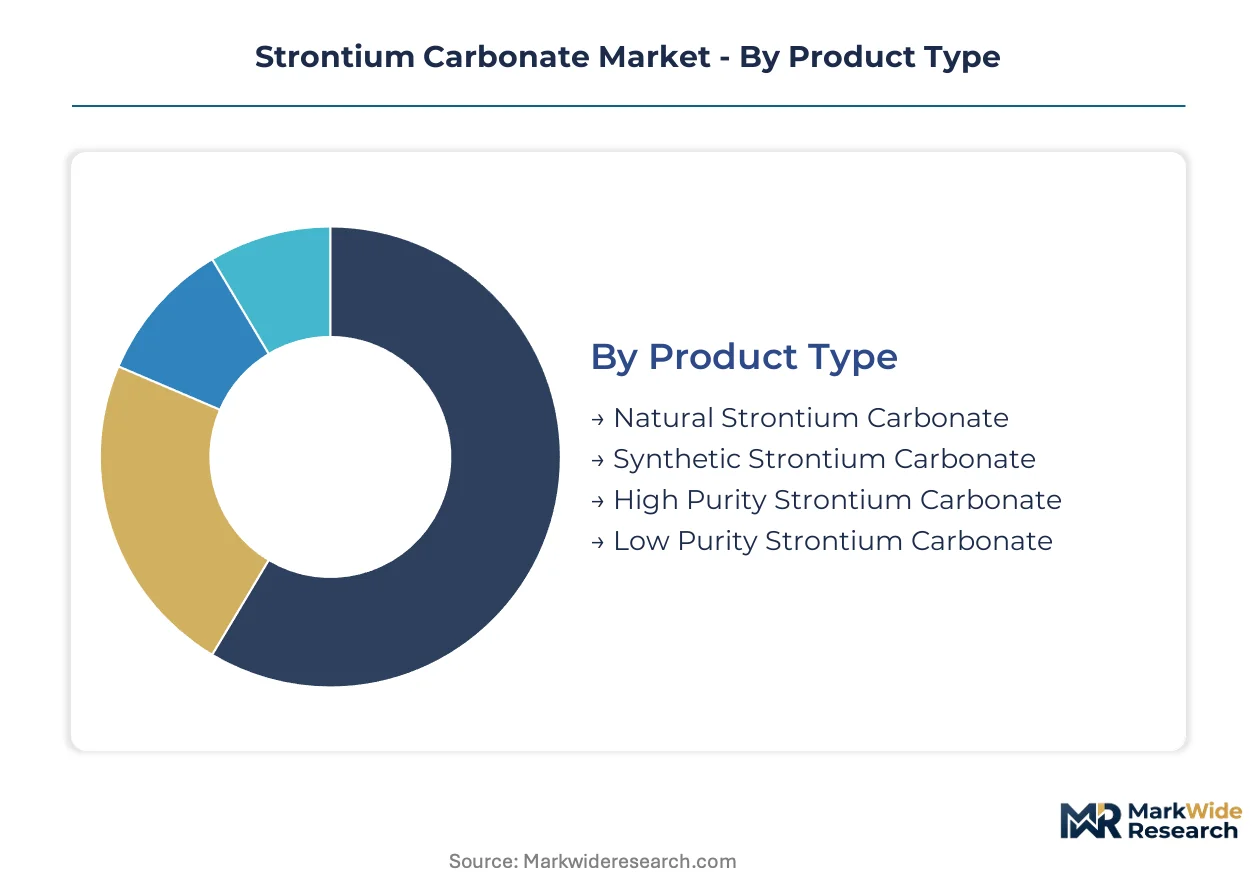
Strontium carbonate specifications fragment sharply across end-use requirements, with purity grades and particle precision determining access to margin-rich pharmaceutical and electronics channels. Technical grade materials compete on cost in mature glass applications while high-purity variants command qualification barriers in ferrite magnet and drug precursor markets.
Product Type:
Purity thresholds and production chemistry define competitive positioning across the specification ladder.
- Synthetic Strontium Carbonate:Produced via black ash reduction of celestite ore or chemical synthesis from strontium sulfide, this grade delivers consistent 97-99% purity with scalable batch output. Demand concentrates in eastern Chinese provinces where integrated processors serve ferrite magnet manufacturers in Japan and South Korea with qualified electronic-grade material.
- High Purity Strontium Carbonate:Exceeding 99.5% purity with tight particle size distribution control, this grade targets pharmaceutical precursors and high-frequency ferrite applications. EMA and FDA compliance requirements filter supply to producers with documented GMP manufacturing and REACH registration.
- Natural Strontium Carbonate:Derived from direct mineral processing with variable impurity profiles, serving cost-sensitive ceramic flux applications where color consistency requirements permit geological variation.
- Low Purity Strontium Carbonate:Technical grade material at 95-97% purity for bulk glass manufacturing and construction materials where fluxing function dominates over optical properties.
Mature deployment sits with Synthetic Strontium Carbonate. Newer deployment is concentrated in High Purity Strontium Carbonate.
Application:
End-use specifications are diverging as electronics and pharmaceutical channels fragment from traditional industrial demand.
- Electronics:Sintered ferrite core production for electric drivetrains and consumer devices requires sub-micron particle control and magnetic property consistency. Battery-electric vehicle motor programs in Japan and South Korea are accelerating qualification timelines for qualified suppliers.
- Pharmaceuticals:Strontium ranelate precursor manufacturing demands documented GMP compliance with EMA and FDA pathway adherence. REACH registration and substance evaluation dossiers create structural barriers to market entry.
- Glass Manufacturing:Fluxing and color stabilization in television panel and specialty optical glass retains volume leadership but faces barium carbonate substitution pressure where performance specifications permit.
- Ceramics Production:Tile and sanitary ware manufacturing utilizes strontium carbonate for glaze modification and thermal expansion control, with procurement consolidating around regional chemical clusters.
Volume concentration remains in Glass Manufacturing. Steepest expansion trajectory is visible in Electronics.
End User:
Customer procurement patterns separate between specification-driven qualification processes and commodity chemical purchasing.
- Healthcare:Pharmaceutical manufacturers and medical device suppliers enforce dual certification requirements with ISO 9001 and IATF 16949 credentials, consolidating supplier relationships around strategic partners.
- Consumer Goods:Electronics OEMs and appliance manufacturers specify ferrite magnet grades with embodied carbon documentation for EU Green Deal compliance.
- Construction:Glass and ceramic tile producers prioritize cost stability and logistics reliability over purity premiums, with procurement tied to regional chemical processing clusters.
- Agriculture:Limited niche applications in soil amendment and specialty fertilizers with minimal purity requirements and price-sensitive procurement.
Procurement sophistication clusters in Healthcare. Price-sensitive purchasing dominates Construction.
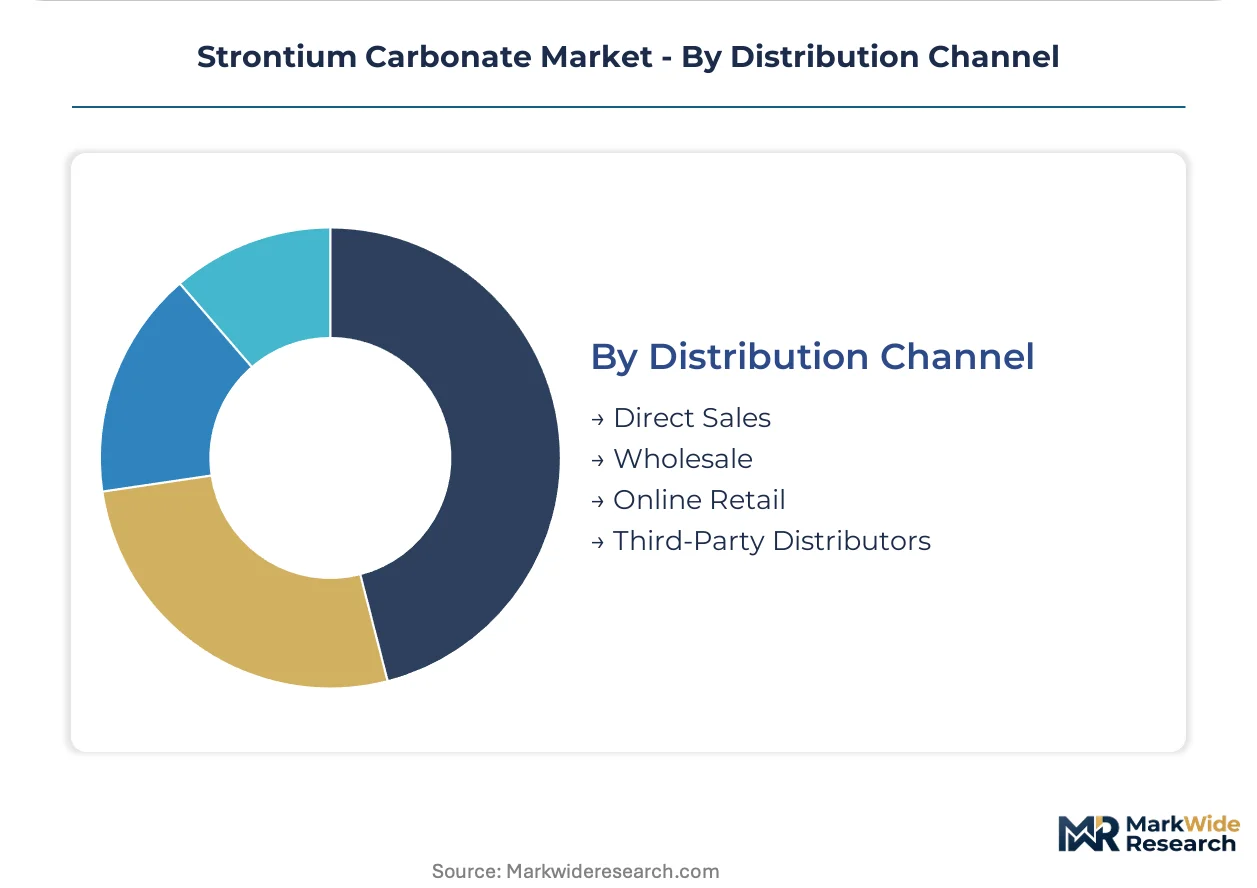
Distribution Channel:
Channel selection correlates with shipment scale, specification complexity, and geographic proximity to production.
- Direct Sales:Long-term contracts link integrated Chinese producers to Japanese and South Korean ferrite magnet manufacturers, with qualified supplier lists narrowing to two or three strategic partners per procurement team.
- Third-Party Distributors:Regional chemical distributors stock technical grades for construction and ceramics customers with fragmented order patterns and delivery reliability requirements.
- Wholesale:Bulk material aggregation for glass manufacturers with predictable consumption schedules and rail or barge logistics optimization.
- Online Retail:Limited to laboratory quantities and research-grade samples with minimal commercial volume.
Relationship-based contracting concentrates in Direct Sales. Transactional purchasing flows through Third-Party Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese processors dominate strontium carbonate supply chains, yet demand-side procurement concentrates in Japanese and South Korean ferrite magnet clusters. European pharmaceutical regulators filter market access through REACH registration barriers. The geographic split between eastern Chinese production and East Asian electronics demand defines regional trade flows.
China
Chongqing and Guizhou provinces host captive celestite mining operations feeding integrated chemical processors. The Ministry of Ecology and Environment enforces stricter wastewater discharge limits on strontium sulfide leaching facilities. Eastern chemical clusters in Shandong and Jiangsu provinces are retrofitting zero-liquid discharge systems ahead of enforcement deadlines.
Japan
Kansai region electric motor manufacturers are consolidating qualified supplier lists for sintered ferrite core procurement. METI industrial standards guide magnet material specifications for battery-electric vehicle programs. Osaka-based procurement teams are narrowing strategic partnerships to dual-certified sources with IATF 16949 credentials.
South Korea
Busan-Ulsan industrial corridor hosts expanding ferrite magnet production for electric drivetrain exports. MFDS pharmaceutical regulations create parallel compliance pathways for strontium ranelate precursor imports. Domestic chemical distributors are stockpiling electronic-grade material against supply concentration risks.
Germany
Specialty glass manufacturers in Bavaria and North Rhine-Westphalia specify REACH-registered strontium carbonate for optical applications. ECHA substance evaluation procedures are extending compliance timelines for imported strontium salts. Ruhr region chemical distributors serve construction ceramics customers with technical-grade material.
United States
FDA pharmaceutical compliance pathways stabilize demand for high-purity strontium ranelate precursors after patent cliff adjustments. EPA industrial chemical regulations govern import documentation for ceramic and glass applications. Texas and Ohio-based magnet assemblers qualify Asian suppliers against automotive quality standards.
Strontium Carbonate Market Vendor Landscape
Chinese producers anchor the volume tier; European and Japanese specialists hold premium-grade positions. The vendor base separates into integrated miners with captive ore access, precision chemical processors serving electronics channels, and regional distributors stocking technical grades. Three archetypes dominate: state-linked resource holders with backward integration into celestite reserves, precision manufacturers with particle size control capabilities, and compliance-focused suppliers with REACH and FDA registration. Competitive moves concentrate on environmental retrofit completion and qualification list consolidation by tier-1 magnet producers.
Within the integrated resource tier, Guizhou Redstar Developing Company Limited and Nanjing Jinyan Strontium Industry exemplify Chinese producers with captive mining advantages. Solvay occupies a position among European specialists leveraging pharmaceutical-grade registration. Sakai Chemical Industry represents Japanese precision manufacturers serving ferrite magnet channels. These anchors illustrate how geographic origin and regulatory positioning stratify competitive access.
| Leading Market Players |
|---|
| Solvay |
| Kandelium |
| Fertiberia |
| Sakai Chemical Industry |
| Guizhou Redstar Developing Company Limited |
| Nanjing Jinyan Strontium Industry |
| Shenzhou Jiaxin Chemical |
| Honjo Chemical Corporation |
| Zaozhuang Yongli Chemical |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers with captive celestite mining rights in Chongqing and Guizhou provinces anchor supply discipline through backward integration into ore reserves, enabling these integrated Chinese processors to maintain pricing power despite environmental compliance cost inflation while commodity-grade competitors face margin compression from MEE wastewater treatment mandates.
Pricing Analysis
Volume concentrates in technical-grade synthetic material at 97-99% purity for glass fluxing and ceramics, while margin pools accrue to high-purity electronic and pharmaceutical grades exceeding 99.5% with documented REACH registration and GMP compliance. Price differentiation rests on certification tier and particle size precision for ferrite magnet applications, with qualified suppliers commanding substantial premia over unregistered Asian exporters. Cost compression in commodity grades is intensifying because barium carbonate substitution is eroding share in color-tolerant glass applications. Construction sector buyers exhibit highest price sensitivity, whereas healthcare procurement teams prioritize supply security and regulatory documentation over unit cost.
Supply Chain Analysis
Reverse-logistics flows are minimal given strontium carbonate's role as a consumable process input rather than finished goods, though spent ferrite magnet recycling in Japan's Kansai region is emerging as a secondary strontium recovery channel. Supply concentrates in China, Japan, and South Korea, with eastern Chinese provinces controlling over 70% of synthetic output. Feedstock draws from celestite ore deposits, coal for black ash reduction thermal energy, and sulfuric acid for sulfide leaching operations. Single-source vulnerability runs through eastern China's clustered chemical processing zones exposed to localized environmental enforcement actions. Distribution runs through long-term direct contracts linking integrated producers to Japanese and South Korean magnet manufacturers, with regional distributors handling fragmented technical-grade orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around environmental compliance capabilities, with MEE wastewater mandates forcing capital-constrained processors to exit or seek acquisition by well-capitalized integrated producers with captive ore access and zero-liquid discharge infrastructure already deployed.
For Market Incumbents: Hedge against barium carbonate substitution in glass applications by accelerating pharmaceutical-grade certification investments to capture strontium ranelate precursor demand stabilized post-patent cliff. Secure preferred supplier status with tier-1 ferrite magnet producers in Japan's Kansai region by completing IATF 16949 automotive quality credentialing ahead of procurement list consolidation. Prioritize zero-liquid discharge retrofit completion in Shandong and Jiangsu facilities to outlast enforcement-driven capacity exits among smaller competitors lacking capital access.
For New Entrants and Emerging Players: E-commerce laboratory chemical platforms offer a viable entry vector for research-grade and sample-quantity distribution, bypassing entrenched direct-sales relationships dominating bulk procurement. Target pharmaceutical-grade production with documented EMA and FDA pathway adherence, as REACH registration barriers filter out incumbent Asian exporters and create structural white space for compliant specialists. Pursue electrochemical synthesis technology licensing from Japanese specialty chemical developers to establish smaller-scale high-purity production with reduced thermal energy exposure and compressed minimum efficient scale.
For Investors and Strategic Acquirers: Completion of zero-liquid discharge retrofit programs by Chongqing and Guizhou integrated producers is the leading indicator that environmental compliance moats are widening and acquisition premiums for compliant assets will escalate. The 5-10 year viability window favors backward-integrated specialists with captive celestite reserves and established REACH registration, as regulatory divergence between Chinese environmental enforcement and European chemical access requirements concentrates margin pools among dual-compliant operators. Monitor ECHA substance evaluation timelines for strontium salts as early signals of potential authorization restrictions that would revalue registered supplier positions.
| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Liquid Discharge Retrofit | MEE enforcement deadlines in eastern Chinese provinces are compressing retrofit timelines and eliminating non-compliant capacity. |
| REACH Registration Completion | ECHA substance evaluation procedures are extending compliance timelines and filtering market access for pharmaceutical-grade suppliers. |
| IATF 16949 Certification | Osaka-based procurement teams are narrowing qualified supplier lists to dual-certified sources for battery-electric vehicle motor programs. |
| Electrochemical Synthesis Pilot | Japanese membrane cell configurations are decentralizing high-purity production economics and fragmenting supply concentration. |
| Captive Celestite Expansion | Guizhou and Chongqing mining rights are securing feedstock advantage as ore quality variations drive selective extraction toward higher-grade seams. |
Methodological Framework
Independent corroboration across plant managers at integrated Chinese processors, procurement leads at Japanese ferrite magnet manufacturers, distribution channel partners in South Korea's Busan-Ulsan corridor, and technical R&D directors at European specialty glass producers underwrites the qualitative findings. Primary interview data were validated against customs and trade flow records, ACC and Cefic chemical industry reports, SEC 10-K filings from listed specialty chemical companies, and ECHA substance registration databases. Bottom-up demand modeling across application segments was triangulated against top-down production capacity assessments from eastern Chinese chemical clusters.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects in synthetic versus high-purity grade tiers, electronics versus pharmaceutical versus glass manufacturing end-uses, and direct sales versus distributor channel structures. CAGRs were derived through iterative convergence of demand elasticity estimates and supply-side capacity utilization trajectories. Key forecast inputs include MEE environmental enforcement intensity projections, ECHA substance evaluation timeline assumptions, and battery-electric vehicle motor program qualification velocity from Japanese and South Korean OEMs.
The model holds under stable regulatory enforcement trajectories and continued ferrite magnet demand expansion; deviation in ECHA authorization restrictions or Chinese environmental policy suspension would shift supply-demand balances materially. Practitioners should monitor ECHA 2024-2025 substance evaluation work program priorities and MEE inspection campaign intensity in Shandong province for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
India Kaolin Market
Ceramics
Global Ceramic Balls Market
Ceramics
Germany Ceramic Tiles Market
Ceramics
Egypt Ceramic Tiles Market
Ceramics
Ceramic Setter Plate Market
Ceramics
Ceramic Proppant Market
Ceramics
US Kaolin Market
Ceramics
Ceramic and Natural Stone Tiles Market
Ceramics
Pottery Ceramics Market
Ceramics
Aragonite Market
Ceramics
Global Metal and Ceramic Injection Molding Market
Ceramics
Advanced Ceramic Additives Market
Ceramics
Cerium Nitride Market
Ceramics
Brazil Ceramic Tiles Market
Ceramics
Polymer-Derived Ceramics Market
Ceramics
China Clay Market