
 Heat-Resistant Ceramic Tableware Market | 2026-2036
Heat-Resistant Ceramic Tableware Market Size, Share, and Industry Trends Forecast 2026-2036
Heat-Resistant Ceramic Tableware Market Foresight
Asset-light leasing models for commercial-grade tableware fleets are reconfiguring competitive entry barriers for hospitality suppliers. Steelite International leverages its UK manufacturing base to sustain institutional contracts across European hotel chains. Rak Porcelain anchors Middle Eastern procurement networks through specialized high-fire vitrified lines.
Heat-resistant ceramic tableware comprises fired clay bodies engineered to withstand thermal shock above 200°C, typically formulated from alumina-enriched porcelain or fully vitrified stoneware through tunnel-kiln sintering at 1,200–1,400°C, serving commercial kitchens and consumer dining environments where microwave-to-oven transitions are routine. Porcelain commands the premium tier due to density and translucency, while stoneware occupies the volume-driven institutional segment through lower firing costs and superior chip resistance. Serveware generates the fastest channel growth as buffet-style and family-style dining formats expand across Asia-Pacific and North American foodservice.
FDA compliance for food-contact surface safety and California Proposition 65 lead-cadmium thresholds shape US market access requirements, while EU REACH and ECHA restrictions on heavy-metal migration compel reformulation of traditional glaze chemistries across export-oriented production. Stakeholders must monitor evolving state-level chemical disclosure mandates and third-party certification schemes as procurement specifications tighten across institutional buyers.
Market Dynamics
EU REACH and ECHA restrictions on heavy-metal migration are compelling wholesale reformulation of traditional glaze chemistries, forcing manufacturers to abandon century-old lead-cadmium formulations and retool tunnel-kiln sintering protocols for alumina-enriched porcelain bodies.
Growth Catalysts
- Open-kitchen restaurant formats:Full-service chains are expanding thermal-shock-resistant serveware procurement to withstand direct flame-to-table service in visible cooking environments.
- EU Green Deal compliance mandates:Binding sustainability targets are accelerating adoption of recycled clay formulations and closed-loop water systems in ceramic production facilities.
- Microwave-to-oven convenience:Consumer demand for single-dish thermal versatility is pulling vitrified stoneware into residential replacement cycles previously served by lower-performance materials.
Market Restraints
- Energy cost volatility:Natural gas prices directly impact tunnel-kiln operating economics, squeezing margins for producers dependent on continuous 1,200–1,400°C sintering cycles.
- Raw material concentration:High-purity alumina and kaolin deposits concentrate in specific extraction regions, exposing supply chains to geopolitical disruption and export licensing friction.
- California Proposition 65 thresholds:Lead-cadmium disclosure requirements create compliance complexity for exporters targeting US foodservice channels, necessitating third-party laboratory verification.
Strategic Opportunities
- Asset-light leasing models:Commercial-grade tableware fleets are reconfiguring hospitality procurement from purchase-to-own to subscription-based rotation services.
- High-fire vitrified specialization:Technical ceramics expertise from industrial applications is hybridizing with tableware production to create ultra-durable institutional serveware lines.
- Lead-free glaze innovation:Regulatory tailwinds from FDA and EFSA are rewarding early movers with preferred-supplier status among institutional buyers tightening chemical specifications.
Industry Challenges
- Refractory engineering talent scarcity:Ceramic material science expertise is concentrating among aging specialists, constraining R&D velocity for thermal-shock-resistant body formulations.
- Certification timeline compression:Third-party food-contact safety verification from NSF International and equivalent bodies is extending new product introduction cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat-Resistant Ceramic Tableware Market |
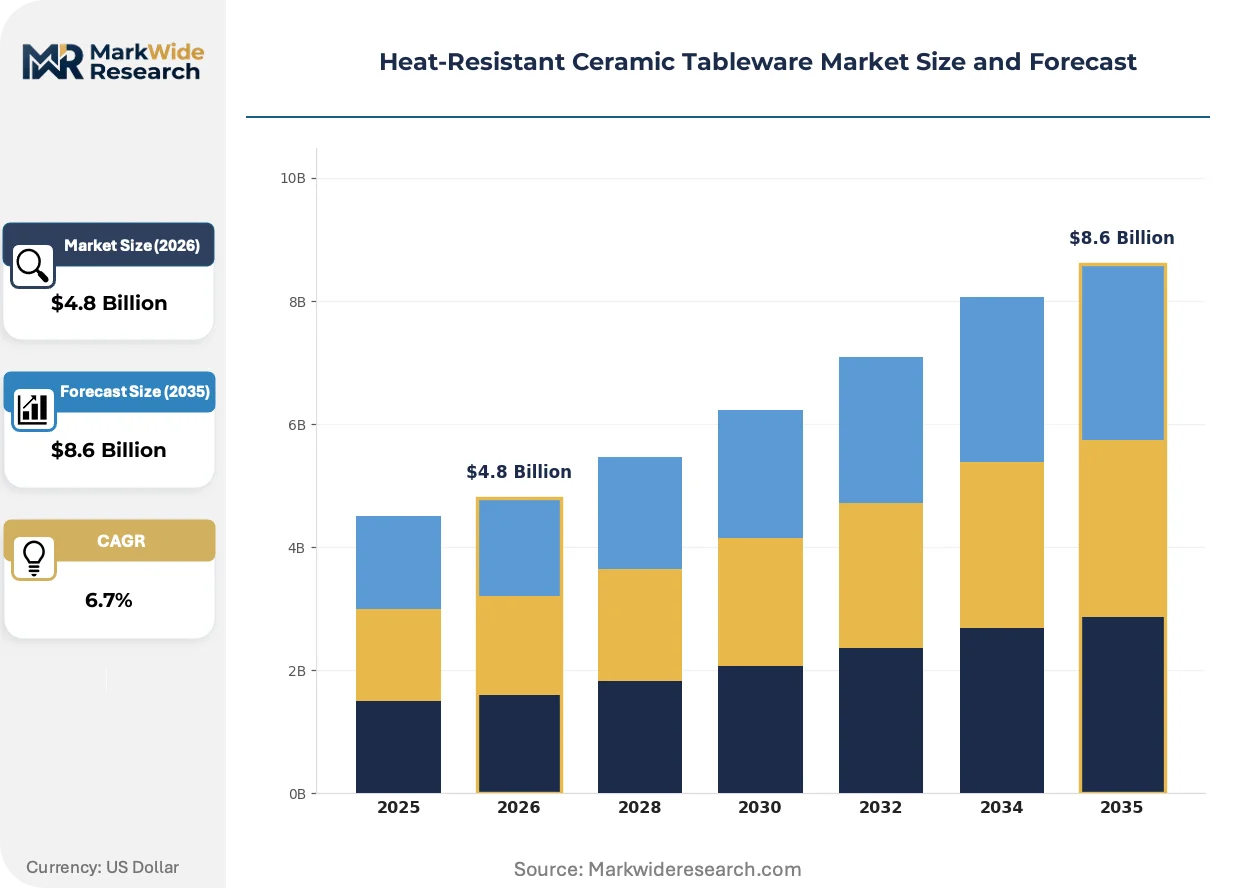
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Bowls, Mugs, Serveware Material: Porcelain, Stoneware, Earthenware, Vitreous China Design Style: Modern, Rustic, Traditional, Minimalist Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Villeroy & Boch AG, Rosenthal GmbH, Lenox Corporation, Steelite International, Libbey Inc., Churchill China, Noritake, Rak Porcelain, Portmeirion Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat-Resistant Ceramic Tableware Market Shifts & Advancements
Formulation science and firing technology are converging to redefine performance benchmarks for thermal-shock resistance, while procurement digitization and sustainability certification are reshaping how commercial buyers evaluate supplier relationships.
Alumina-silicate composite bodies engineered through modified tunnel-kiln protocols are hybridizing traditional porcelain density with stoneware chip resistance. Institutional foodservice operators in Germany and Japan are adopting these hybrid formulations for high-turnover buffet environments. The technology is hybridizing what were previously distinct premium and volume market tiers into a consolidated performance segment.
EU F-Gas Regulation and associated decarbonization mandates are pressuring manufacturers to transition kiln fuel sources from natural gas to renewable hydrogen or electric induction. This industrial consequence is accelerating capital deployment into pilot facilities. German production clusters are most affected, with Villeroy & Boch and Rosenthal anchoring regional retrofit consortiums to share infrastructure investment.
Commercial hospitality buyers are consolidating supplier relationships around vertically integrated manufacturers capable of certifying full chain-of-custody for clay sourcing and glaze chemistry. Asset-light fleet management platforms are displacing traditional distributor networks for hotel and restaurant procurement. This concentration is most visible across European hotel chains, where procurement directors now mandate single-source accountability for thermal-performance warranties and chemical compliance documentation.
Heat-Resistant Ceramic Tableware Market Segmentation
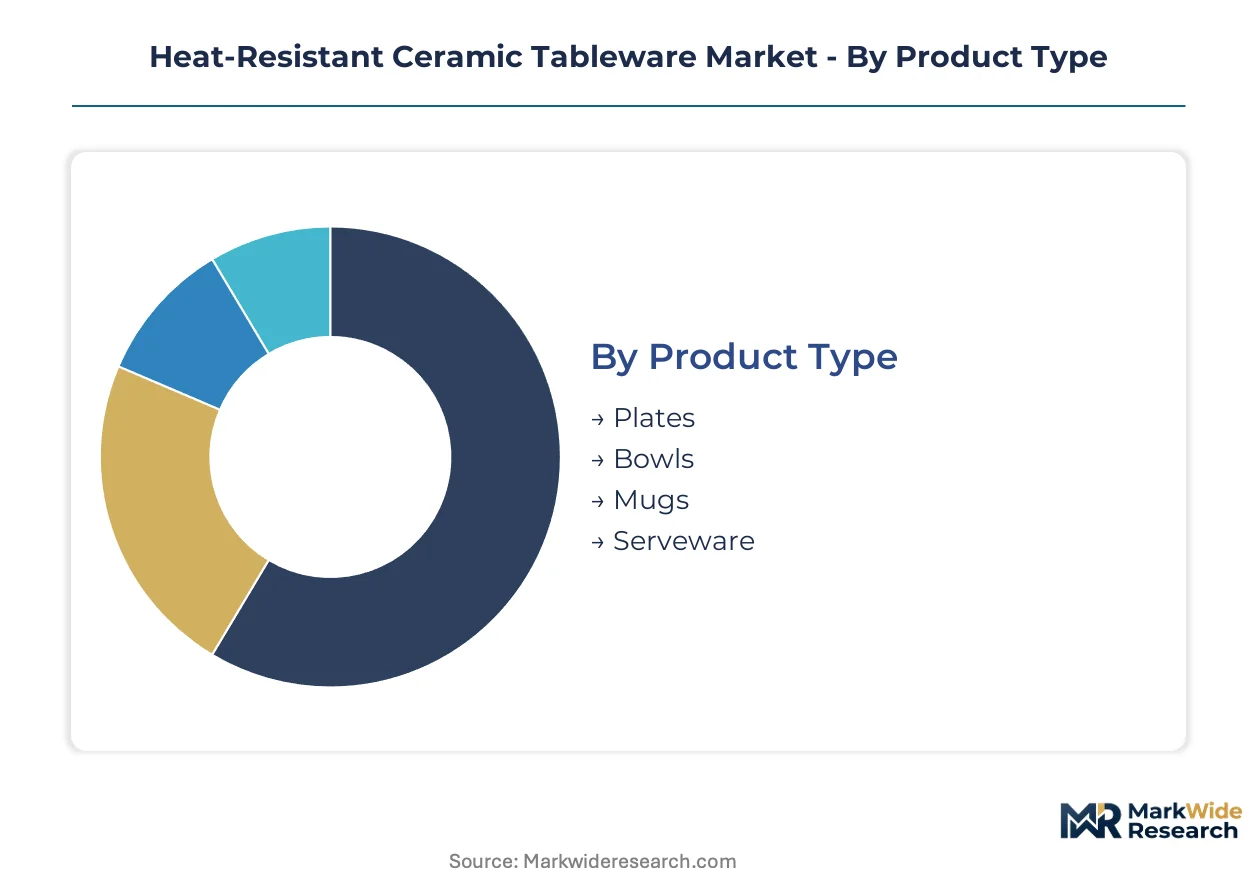
Segmentation in heat-resistant ceramic tableware reveals how thermal performance requirements diverge across use environments. Material chemistry and distribution economics create distinct competitive arenas with different margin structures and regulatory exposure.
Product Type:
Application intensity separates these categories, with thermal shock frequency and visibility driving procurement specifications.
- Plates:Flatware engineered for direct flame contact and rapid temperature cycling commands premium positioning in open-kitchen restaurants. German full-service chains specify alumina-enriched formulations for visible cooking-to-table service.
- Serveware:Buffet platters and sharing dishes face the most severe thermal gradients, pulling demand toward fully vitrified stoneware with thermal shock resistance above 300°C. Asia-Pacific foodservice expansion is accelerating replacement cycles for institutional-grade serveware fleets.
- Bowls:Soup and ramen vessels prioritize microwave-to-oven versatility in residential channels.
- Mugs:Beverage service concentrates volume in hospitality procurement with lower thermal performance thresholds.
Serveware holds installed capacity. Plates is rotating up the share rankings.
Material:
Cost tier and firing economics determine competitive positioning, with energy intensity and raw material purity creating divergent margin profiles.
- Porcelain:Alumina-enriched bodies fired at 1,400°C achieve translucency and density for premium hospitality tiers. EU Green Deal compliance costs are compressing margins for traditional natural-gas kiln operations in German production clusters.
- Stoneware:Lower firing temperatures and superior chip resistance anchor institutional volume procurement. REACH-mandated lead-free glaze reformulation is forcing tunnel-kiln protocol adjustments across export-oriented manufacturers.
- Earthenware:Porous low-fire bodies serve decorative and occasional-use segments with minimal thermal performance requirements.
- Vitreous China:Hybrid formulations bridge porcelain aesthetics with stoneware durability for healthcare and senior living foodservice.
Stoneware holds installed capacity. Porcelain is climbing the fastest despite regulatory headwinds.
Design Style:
Customer type and venue positioning drive aesthetic segmentation, with procurement specifications increasingly tied to brand identity rather than pure performance.
- Modern:Clean lines and neutral palettes dominate urban hotel chains and contemporary casual dining. Japanese and South Korean hospitality buyers specify matte glazes and geometric profiles for social-media-visible table settings.
- Rustic:Hand-finished textures and earth tones serve farm-to-table concepts and boutique hospitality. Artisan production constraints limit scale for thermal-shock-certified rustic lines.
- Traditional:Ornate patterns and classic forms persist in heritage hospitality and residential gift markets.
- Minimalist:Reduced surface ornamentation emphasizes material quality and thermal performance credentials for design-forward procurement.
Modern holds installed capacity. Rustic is gaining share fastest among independent restaurant operators.
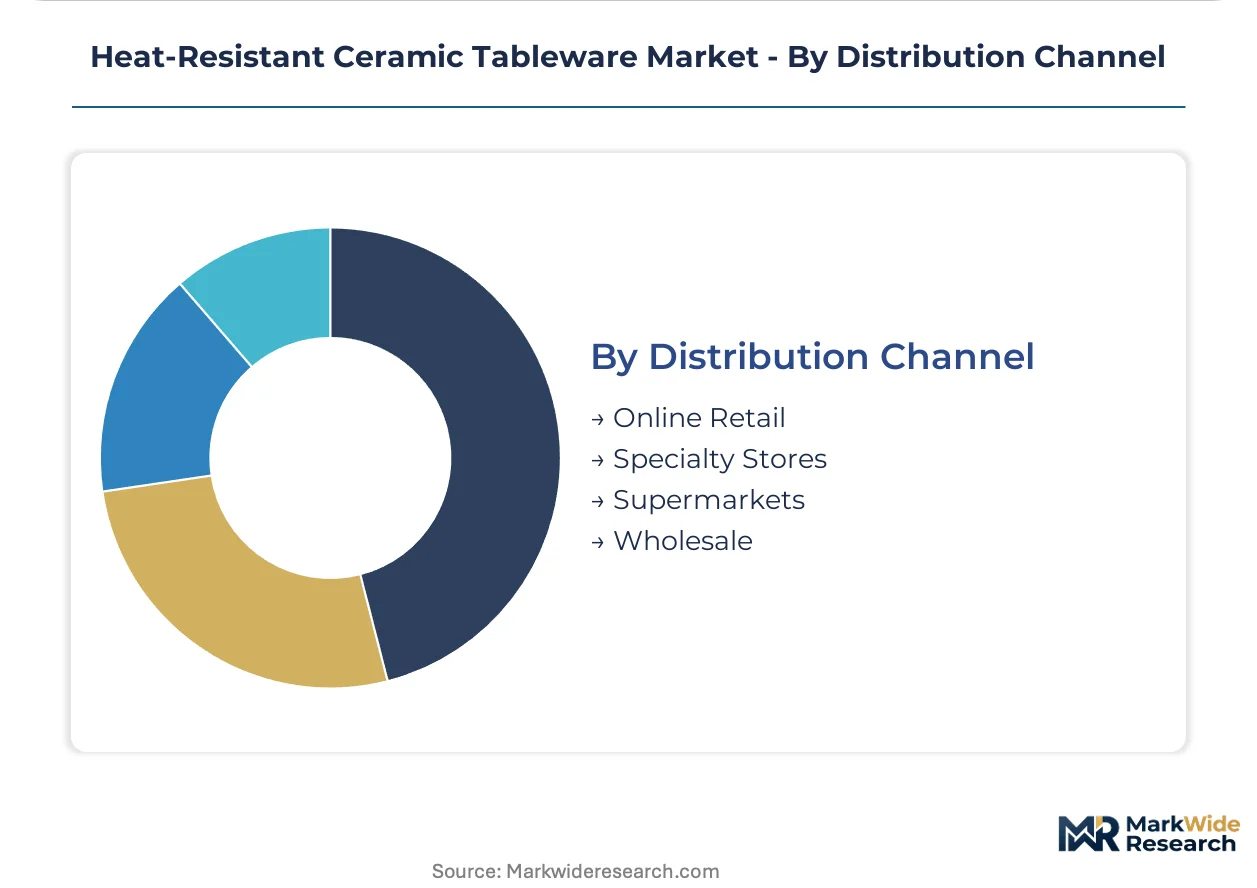
Distribution Channel:
Supply concentration and buyer relationship intensity vary sharply across channel structures, with digitization reshaping procurement patterns.
- Wholesale:Direct manufacturer-to-hospitality relationships dominate institutional volume, with fleet management platforms displacing traditional distributor networks. European hotel chains now mandate single-source accountability for thermal-performance warranties and REACH compliance documentation.
- Online Retail:Direct-to-consumer channels are capturing residential replacement demand for microwave-to-oven certified products. California Proposition 65 disclosure requirements create fulfillment complexity for cross-border e-commerce.
- Specialty Stores:Curated assortments serve design professionals and premium residential buyers with extended product education.
- Supermarkets:Mass-market volume concentrates in seasonal and promotional cycles with limited thermal performance differentiation.
Wholesale holds installed capacity. Online Retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturers in Germany and China dominate international shipment volumes, while import-dependent foodservice operators in the United States and Japan drive premium procurement. Trade flows concentrate alumina-enriched porcelain outbound from European kiln clusters and vitrified stoneware from Asian production bases.
Germany
Full-service restaurant chains in Berlin and Munich specify thermal-shock-resistant serveware for open-kitchen formats visible to diners. EU REACH mandates from ECHA compel Villeroy & Boch and Rosenthal to eliminate legacy lead-cadmium glazes. The Saarland production corridor anchors retrofit consortiums sharing hydrogen kiln infrastructure.
United States
Hotel procurement directors in New York and Los Angeles consolidate supplier relationships around single-source thermal-performance warranties. FDA food-contact surface regulations and California Proposition 65 disclosure thresholds create compliance complexity for imported serveware. The Southeast distribution hub handles cross-border fulfillment from Mexican manufacturing.
China
Buffet-style dining expansion in Shanghai and Guangzhou accelerates institutional-grade serveware replacement cycles. GB standards from SAMR govern microwave-to-oven safety certification for export-bound production. The Zhejiang ceramic belt concentrates tunnel-kiln capacity serving European and Middle Eastern buyers.
Japan
Ramen and specialty soup vendors in Tokyo and Osaka drive demand for microwave-to-oven certified bowls. METI energy efficiency guidelines pressure kiln operators toward electric induction retrofitting. The Aichi prefecture cluster hybridizes traditional porcelain aesthetics with industrial vitrification techniques.
United Arab Emirates
Hospitality procurement in Dubai and Abu Dhabi sources high-fire vitrified lines for luxury hotel buffet operations. MOHAP food-contact material regulations align with GCC standardization for imported tableware. Jebel Ali logistics zones consolidate Middle Eastern distribution for European and Asian manufacturers.
Heat-Resistant Ceramic Tableware Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated manufacturers capable of certifying full chain-of-custody documentation. Mid-scale specialists retain position through technical ceramics hybridization and fleet-management platform partnerships. Three archetypes dominate: heritage European houses with kiln ownership, Asian volume producers with export logistics scale, and asset-light fleet operators reconfiguring hospitality procurement. Competitive moves center on hydrogen kiln retrofit consortiums and subscription-based rotation services displacing traditional distributor networks.
Among heritage European houses, Villeroy & Boch AG and Rosenthal GmbH exemplify the premium-tier archetype through Saarland-based production clusters. Rak Porcelain occupies a position within the Middle Eastern procurement specialist tier. Steelite International represents the UK-manufacturing institutional contract anchor. These named entities illustrate how geographic kiln concentration and regulatory compliance capability determine preferred-supplier status among consolidating hospitality buyers.
| Leading Market Players |
|---|
| Villeroy & Boch AG |
| Rosenthal GmbH |
| Lenox Corporation |
| Steelite International |
| Libbey Inc. |
| Churchill China |
| Noritake |
| Rak Porcelain |
| Portmeirion Group PLC |
| Others |
Supply & Pricing Matrix
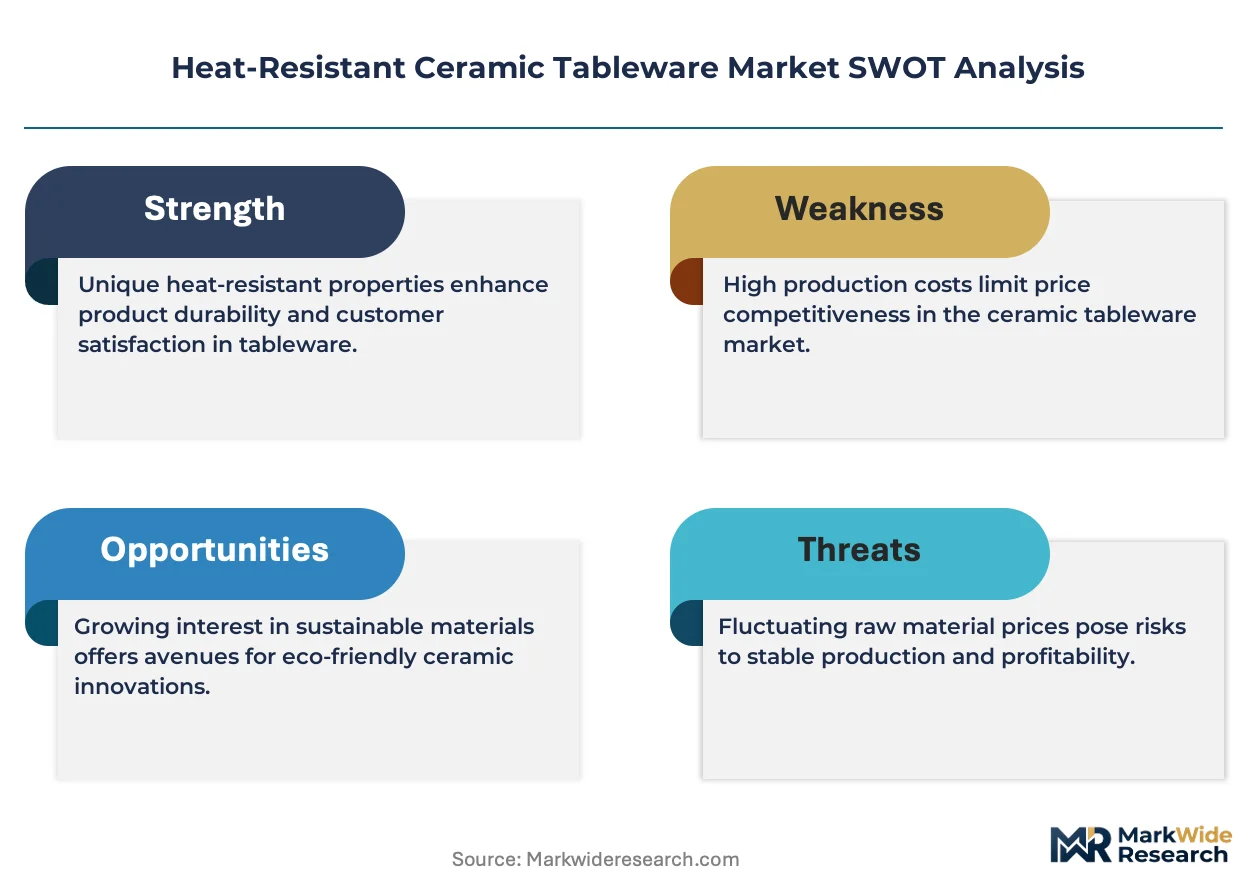
EU REACH compliance costs and California Proposition 65 disclosure mandates compress margins for exporters while widening price spreads between certified and uncertified production tiers. Natural gas volatility in German kiln clusters and alumina sourcing bottlenecks from specific extraction regions force buyers into long-term contract structures that embed regulatory risk premiums into landed costs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across hospitality procurement. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified alumina-enriched porcelain from REACH-compliant stoneware and uncertified earthenware. Cost compression in the standard tier is intensifying because hydrogen kiln retrofit investments concentrate among Saarland producers. Quick-service restaurant chains exhibit highest price sensitivity, while luxury hotel groups absorb certification premiums for single-source accountability.
Supply Chain Analysis
Extended payment terms from European hotel chains and supply-chain finance facilities from German production clusters reconfigure working capital requirements for export-oriented manufacturers. High-purity alumina draws from Australian and Chinese extraction regions, while kaolin feeds from Ukrainian and Brazilian deposits. Single-source vulnerability concentrates in tunnel-kiln sintering equipment suppliers based in Germany and Italy. Distribution runs through vertically integrated manufacturer-direct relationships displacing traditional distributor networks for institutional volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among European hotel procurement directors around single-source thermal-performance warranties has shifted negotiating leverage toward buyers capable of mandating full chain-of-custody documentation.
For Market Incumbents: Pre-empt hydrogen kiln retrofit consortium participation to secure preferred-supplier status as EU F-Gas Regulation deadlines approach. Lock in alumina supply agreements with Australian extraction operators before export licensing friction intensifies. Capture institutional fleet-management platform partnerships before asset-light leasing models displace purchase-to-own procurement across mid-scale hospitality chains. For New Entrants and Emerging Players: Build out high-fire vitrified specialization for Middle Eastern luxury hotel buffet operations where Rak Porcelain has established procurement networks but capacity constraints limit scale. Target the rustic design style segment among independent farm-to-table restaurant operators seeking thermal-shock-certified artisan aesthetics. Enter through direct-to-chef sampling programs that bypass consolidated distributor relationships. For Investors and Strategic Acquirers: The market sits at a regulatory-compliance-investment phase that favors vertically integrated manufacturers with captive kiln infrastructure and in-house glaze formulation capabilities. Long-term viability hinges on hydrogen transition execution and REACH documentation depth rather than pure volume scale. Watch for EU ECHA enforcement actions on heavy-metal migration as the inflection indicator for accelerated consolidation among non-compliant export-oriented producers.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Kiln Retrofit Consortium Participation | Villeroy & Boch and Rosenthal anchor Saarland shared infrastructure investments that reduce individual capital burden for EU F-Gas compliance. |
| Lead-Free Glaze Formulation Patent Filing | Early movers secure preferred-supplier status with institutional buyers tightening chemical specifications under FDA and EFSA regulatory tailwinds. |
| Asset-Light Fleet Management Platform Launch | Subscription-based rotation services displace traditional distributor networks for European hotel chains consolidating procurement relationships. |
| Alumina Supply Agreement with Australian Extractors | Long-term offtake contracts hedge against geopolitical disruption and export licensing friction in high-purity raw material sourcing. |
| High-Fire Vitrified Line Specialization for Middle East | Technical ceramics expertise hybridization creates ultra-durable institutional serveware for Dubai and Abu Dhabi luxury hotel buffet operations. |
Research Methodology
A spread of perspectives from ceramic material scientists, hospitality procurement directors, kiln operations managers, and regulatory compliance officers converged on the working assumptions for thermal-shock resistance benchmarks and glaze chemistry migration thresholds. Primary interviews with German production cluster engineers and Middle Eastern hotel supply chain executives combined with secondary validation from ECHA restriction dossiers, FDA food-contact surface guidance documents, SAMR GB standards filings, and customs trade data for alumina and kaolin shipments. Bottom-up segment sizing across material type, product category, and distribution channel triangulated against top-down production capacity estimates from tunnel-kiln facility assessments.
Demand-supply balance modeling anchored volume projections across the analysis window. Segmentation dimensions included material chemistry tier, thermal performance specification, design style positioning, and buyer procurement archetype. CAGRs derived from replacement cycle analysis for institutional serveware fleets and residential microwave-to-oven adoption curves. Industry-specific forecast inputs incorporated EU Green Deal compliance cost trajectories and natural gas price sensitivity for continuous 1,200–1,400°C sintering operations.
Practitioners should monitor ECHA enforcement patterns, hydrogen infrastructure deployment timelines in German production corridors, and California Proposition 65 litigation trends for early signals of regulatory risk repricing. Forecasts embed assumptions regarding REACH lead-cadmium phase-out adherence and alumina supply chain stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Brazil Ceramic Tiles Market
Ceramics
North America Barium Carbonate Market
Ceramics
Clay Market
Ceramics
UAE Ceramic Tiles Market
Ceramics
Technical Ceramics Market
Ceramics
Global Zirconia Oxygen Sensors Market
Ceramics
Ball Clay Market
Ceramics
Low Temperature Co-Fired Ceramic (LTCC) Market
Ceramics
Porous Ceramic Market
Ceramics
Magnesia Carbon Bricks Market
Ceramics
Co-Fired Ceramic Market
Ceramics
Europe Ceramic Coatings Market
Ceramics
Titanium Carbide Market
Ceramics
Calcium Aluminosilicate Market
Ceramics
Ceramics Market
Ceramics
Ceramic Kilns Market