
 Asia-Pacific Activated Alumina Market | 2026-2036
Asia-Pacific Activated Alumina Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Activated Alumina Market Insights
Zeolite is hardening its position as a partial substitute for activated alumina in select petrochemical drying applications, though the latter retains cost advantages in high-humidity environments. BASF SE leverages its integrated alumina catalyst manufacturing network across Ludwigshafen and Shanghai to sustain supply continuity for Asian refiners. Sumitomo Chemical Co., Ltd. anchors its regional position through specialized adsorbent grades tailored to Japanese electronics-grade solvent purification. CHALCO Shandong Co., Ltd. dominates domestic raw material supply, controlling bauxite-to-alumina conversion capacity that underpins cost structures for downstream activated alumina producers.
Activated alumina is a highly porous, granular form of aluminum oxide (Al₂O₃) produced by thermal dehydration of aluminum hydroxide, with typical surface areas exceeding 200 m²/g and pore diameters optimized for selective adsorption. The material functions primarily as a desiccant, catalyst support, and adsorbent for contaminant removal in industrial process streams. Desiccant-grade material leads volume due to entrenched deployment in compressed air and natural gas drying systems across the region's petrochemical corridor. Adsorbent applications for water treatment represent the fastest-expanding segment, driven by municipal fluoride remediation programs and semiconductor fabrication ultrapure water standards. Catalyst supports occupy the highest margin tier, where custom pore-size distributions command premium pricing from specialty chemical manufacturers.
China's MEE enforces GB standards for industrial wastewater discharge that mandate heavy metal and fluoride removal, directly stimulating activated alumina procurement from water utilities and chemical manufacturers. India's BIS certification requirements for drinking water treatment chemicals create compliance barriers that favor established suppliers with testing documentation. Japan's METI promotes circular economy guidelines encouraging regenerable adsorbent systems, extending product lifecycle expectations among industrial end users. Stakeholders must monitor regulatory divergence between China's tightening effluent rules and India's emerging municipal water infrastructure investments to calibrate capacity allocation across the region.
Market Dynamics
Water utilities across Southeast Asia are accelerating activated alumina procurement for fluoride and arsenic remediation, while China's MEE tightens GB wastewater standards that mandate heavy metal removal from chemical manufacturing clusters.
Growth Catalysts
- MEE effluent mandates:China's Ministry of Ecology and Environment enforces GB standards for industrial wastewater discharge that require fluoride removal, directly stimulating activated alumina procurement from water utilities and chemical manufacturers in eastern manufacturing belts.
- Semiconductor ultrapure water:Fabrication plants in Japan and South Korea deploy activated alumina adsorbents to meet sub-ppb contaminant thresholds for solvent purification and rinse water systems.
- Bauxite conversion capacity:Domestic bauxite-to-alumina infrastructure in Shandong province secures raw material supply continuity for downstream activated alumina producers serving regional petrochemical drying demand.
Market Restraints
- Zeolite substitution in petrochemical drying:Synthetic zeolites are hardening their position as partial replacements for activated alumina in select natural gas dehydration applications, though alumina retains cost advantages in high-humidity environments.
- Regenerable system economics:Japan's METI circular economy guidelines encourage adsorbent regeneration protocols that extend product lifecycles and compress replacement frequency among industrial end users.
- Energy-intensive thermal activation:The calcination process for aluminum hydroxide dehydration requires sustained high-temperature furnace operation, exposing producers to volatile natural gas and electricity input costs.
Strategic Opportunities
- Indian municipal infrastructure:BIS certification requirements for drinking water treatment chemicals create compliance barriers that favor established suppliers with testing documentation as India expands municipal water infrastructure investments.
- Catalyst support premium tier:Custom pore-size distributions for specialty chemical manufacturing command pricing premiums, with custom synthesis capabilities differentiating suppliers in high-margin catalyst support segments.
- Electronics-grade solvent purification:Japanese semiconductor and display panel manufacturers require specialized adsorbent grades with ultra-low trace metal content, opening technical specification gaps for qualified suppliers.
Industry Challenges
- Regenerable system technical integration:Industrial end users in Japan face operational complexity when retrofitting existing fixed-bed adsorption systems with regenerable configurations that require steam or thermal reactivation infrastructure.
- BIS certification documentation:Indian water utilities demand extensive laboratory testing records and batch consistency certificates that extend supplier qualification timelines and raise compliance costs for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Activated Alumina Market |
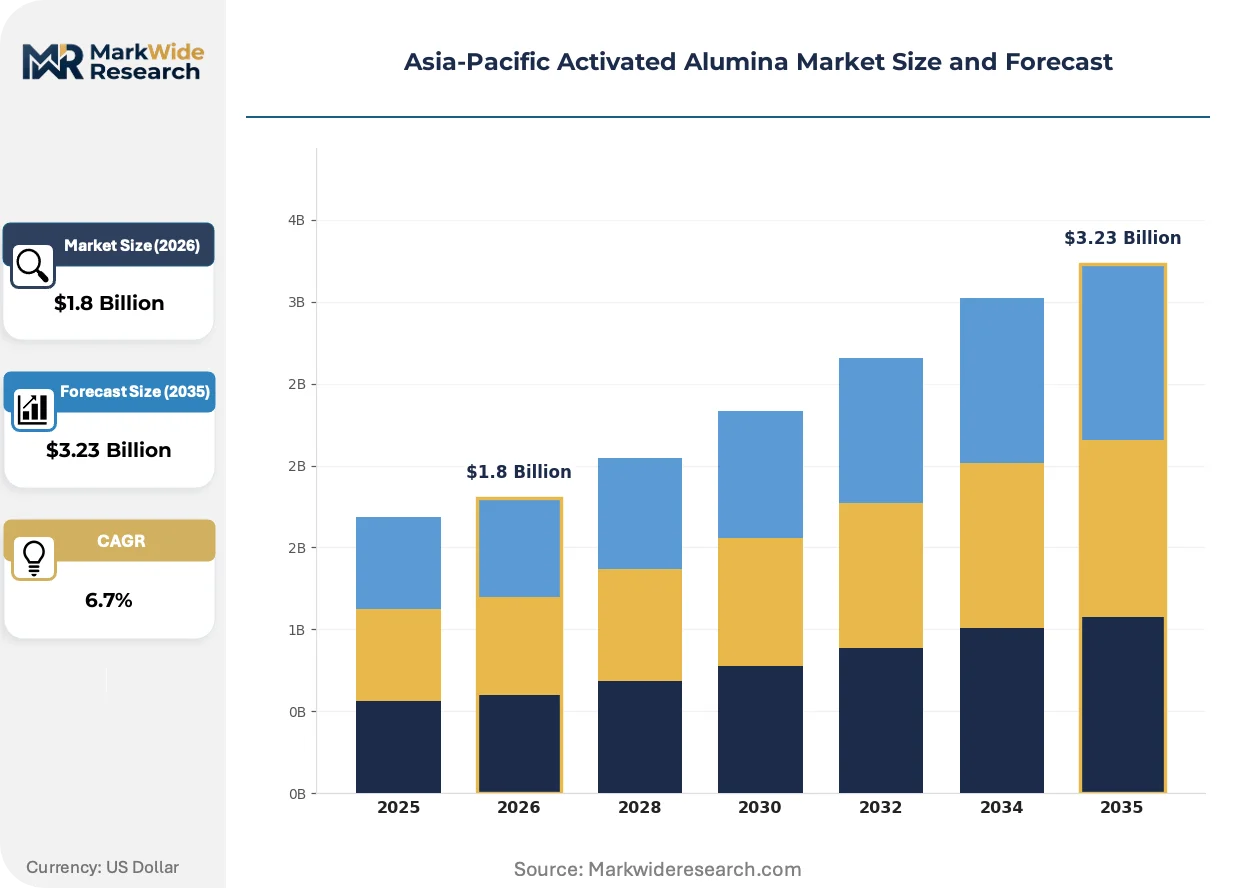
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desiccants, Catalysts, Adsorbents, Filtration Media Application: Water Treatment, Oil & Gas, Refrigerants, Pharmaceutical End User: Industrial, Chemical Manufacturers, Water Utilities, Laboratories Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Axens, Shandong Zhongxin New Material Technology Co., Ltd., BASF SE, CHALCO Shandong Co., Ltd., Luoyang Xinghua Chemical Co., Ltd., Honeywell International Inc., Sorbead India, Jiangsu Jingjing New Material Co. Ltd., Sumitomo Chemical Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Activated Alumina Market Trends and Innovations
Activated alumina manufacturing is absorbing process innovations that reshape competitive positioning across desiccant, adsorbent, and catalyst support grades. Technical differentiation now concentrates on pore architecture control and trace contaminant specifications.
Surface-modified activated alumina with tailored pore-size distributions is absorbing demand from semiconductor fabrication facilities requiring sub-ppb arsenic and fluoride removal. Japanese electronics manufacturers specify these grades for ultrapure water systems and solvent purification. The technology is absorbing market share from standard desiccant grades in high-specification applications, compressing margins for commodity producers while expanding premium tier volumes.
China's GB standards for industrial wastewater discharge are tightening fluoride and heavy metal removal thresholds that apply to chemical manufacturing clusters around Shanghai and Ningbo. The MEE enforcement protocols require continuous monitoring and documented compliance, forcing activated alumina procurement into operational budgets rather than discretionary maintenance. Water utilities and industrial effluent treatment operators in eastern China are responding by locking multi-year supply agreements with certified domestic producers.
Compressed air system operators in Southeast Asian petrochemical corridors are consolidating vendor relationships and demanding performance guarantees that bundle adsorbent supply with regeneration services. This service-integrated procurement model displaces spot purchasing of bulk desiccant material. The shift is most visible in Thai and Indonesian natural gas processing facilities where operator technical staff shortages favor outsourced adsorbent lifecycle management over in-house media replacement programs.
Asia-Pacific Activated Alumina Market Segmentation
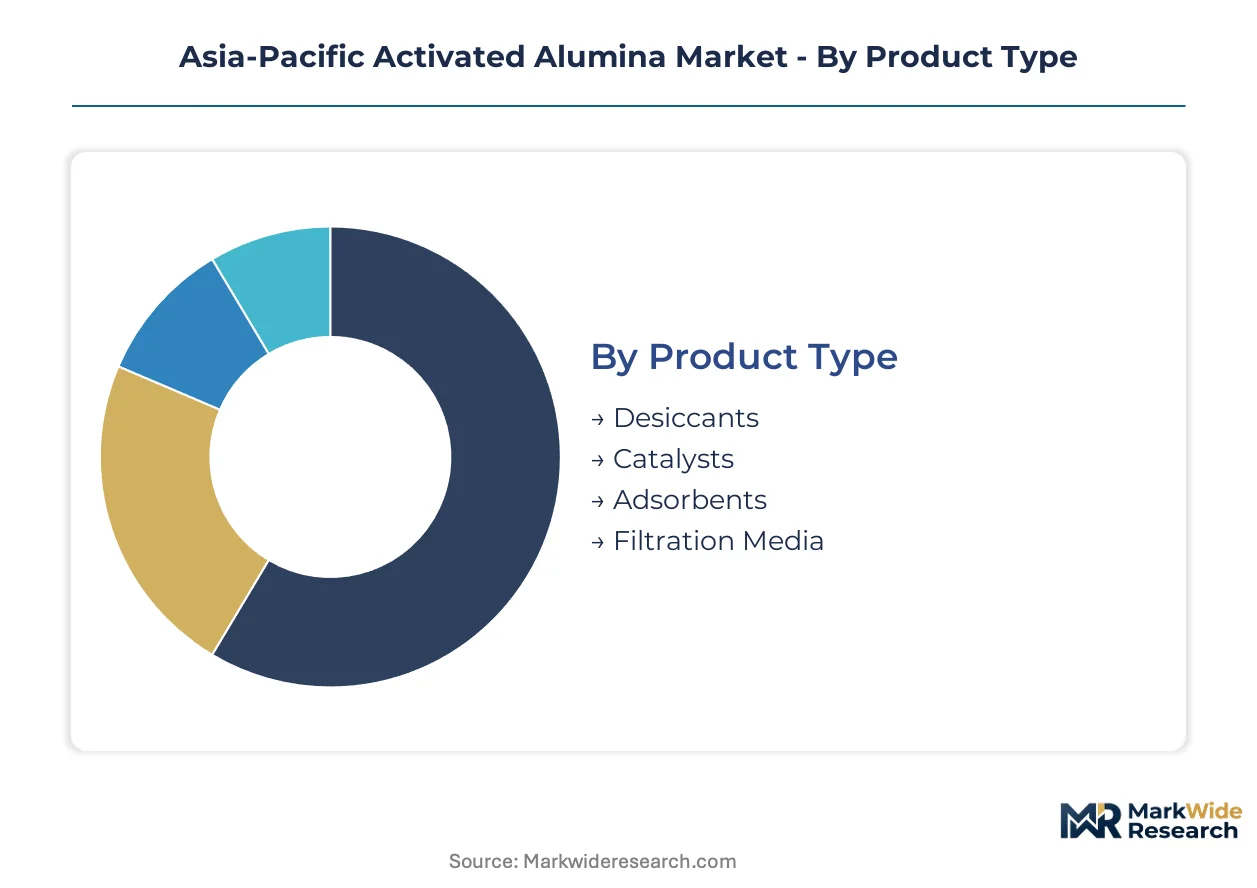
Activated alumina procurement patterns diverge sharply between standalone desiccant cartridges and embedded catalyst systems, with each configuration demanding distinct purity grades and technical specifications. Understanding these integration pathways clarifies why margin structures vary so dramatically across otherwise similar material grades.
Product Type:
Standalone desiccant cartridges dominate spot procurement channels, while embedded catalyst supports require co-development contracts with petrochemical and specialty chemical manufacturers.
- Desiccants:High-purity aluminum oxide spheres engineered for moisture adsorption in compressed air and natural gas systems. Demand concentrates in Thai and Indonesian petrochemical corridors where BASF and CHALCO supply multi-year contracts to operators lacking in-house regeneration infrastructure.
- Catalysts:Custom pore-size distributions tailored for hydrocracking and reforming reactions in regional refineries. Japanese electronics-grade solvent purification commands premium pricing from Sumitomo Chemical's specialized adsorbent grades with ultra-low trace metal content.
- Adsorbents:Granular material deployed for fluoride and arsenic removal in municipal water systems.
- Filtration Media:Porous alumina structures for particulate and dissolved contaminant separation.
Desiccants lead volumes today; catalysts are gaining share fastest.
Application:
Municipal compliance mandates in China and India are pulling material toward water treatment, while semiconductor fabrication standards in Japan and South Korea are expanding ultrapure water specifications.
- Water Treatment:Fluoride and arsenic remediation in municipal systems and industrial effluent treatment. China's MEE enforces GB standards requiring documented heavy metal removal from chemical manufacturing clusters around Shanghai and Ningbo, locking activated alumina into operational budgets.
- Oil & Gas:Natural gas dehydration and compressed air drying in Southeast Asian processing facilities. Thai and Indonesian operators are consolidating vendor relationships and demanding performance guarantees that bundle supply with regeneration services.
- Refrigerants:Moisture removal in cooling system maintenance and manufacturing.
- Pharmaceutical:Solvent purification and process drying in drug manufacturing.
Water treatment applications are expanding most quickly; oil and gas retains the largest installed base.
End User:
Procurement sophistication varies from commodity spot purchasing by industrial maintenance teams to multi-year framework agreements by water utilities facing regulatory deadlines.
- Industrial:Manufacturing facilities deploying desiccants for compressed air and process gas drying. Procurement concentrates through distributors serving maintenance, repair, and operations budgets across diverse manufacturing sectors.
- Chemical Manufacturers:Integrated producers requiring catalyst supports for hydrocracking and specialty chemical synthesis. Eastern China's chemical manufacturing clusters source certified material to meet MEE continuous monitoring and compliance documentation requirements.
- Water Utilities:Municipal operators in Southeast Asia expanding fluoride remediation programs. India's BIS certification requirements create compliance barriers favoring established suppliers with extensive laboratory testing records.
- Laboratories:Research and quality control facilities requiring small-batch high-purity material.
Industrial end users represent the largest volume segment; water utilities are climbing the fastest.
Distribution Channel:
Channel selection reflects procurement scale and technical support requirements, with large utilities favoring direct relationships while smaller industrial buyers rely on distributor networks.
- Online Retail:Small-batch procurement by maintenance teams and laboratory facilities. Transaction sizes remain limited by freight economics for bulk desiccant material, though digital platforms are absorbing spot demand for standardized grades.
- Direct Sales:Multi-year supply agreements between producers and large water utilities or petrochemical operators. Chinese water utilities and industrial effluent treatment operators in eastern manufacturing belts are locking direct contracts with certified domestic producers.
- Distributors:Regional stocking points serving industrial maintenance procurement.
- Wholesalers:Bulk material aggregation for resale to smaller end users and secondary markets.
Direct sales channels command the highest value per ton; online retail is expanding most rapidly at the small-batch tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Eastern China's chemical manufacturing belt around Shanghai and Ningbo commands the dominant share of activated alumina procurement, driven by MEE wastewater compliance mandates and dense petrochemical processing infrastructure.
China
The Ministry of Ecology and Environment enforces GB standards requiring continuous fluoride and heavy metal removal from industrial discharge. Chemical manufacturers in the Yangtze River Delta cluster around Shanghai source certified material to meet documented compliance protocols. Shandong province anchors domestic supply through captive bauxite-to-alumina conversion capacity serving downstream activated alumina producers.
India
Municipal water utilities are expanding fluoride remediation programs across underserved districts. BIS certification requirements for drinking water treatment chemicals create documented compliance barriers favoring established suppliers. Industrial procurement concentrates in Gujarat and Maharashtra where chemical manufacturing clusters require desiccant-grade material for process gas drying systems.
Japan
Semiconductor fabrication facilities in the Kanto region deploy specialized adsorbent grades for ultrapure water and electronics-grade solvent purification. METI circular economy guidelines encourage regenerable adsorbent systems that extend product lifecycles. Osaka-based electronics manufacturers specify ultra-low trace metal content grades that command technical specification premiums.
South Korea
Display panel and memory chip fabrication plants drive demand for sub-ppb contaminant threshold adsorbents in rinse water systems. The country's national environmental regulator enforces discharge standards that mandate fluoride removal from industrial effluent. Procurement concentrates in the Seoul Capital Area and Busan-Ulsan corridor where petrochemical processing complements electronics manufacturing demand.
Southeast Asia
Thai and Indonesian natural gas processing facilities are consolidating vendor relationships around performance-guaranteed supply bundles. Water utilities across Vietnam and the Philippines are accelerating activated alumina procurement for arsenic and fluoride remediation in municipal systems. Technical staff shortages favor outsourced adsorbent lifecycle management over in-house media replacement programs.
Asia-Pacific Activated Alumina Market Competitive Landscape
Global majors compete with regional champions across technical specification tiers and supply chain proximity dimensions. The market structure segments into integrated petrochemical suppliers, specialized adsorbent formulators, and domestic raw material controllers. Three archetypes dominate: multinational chemical conglomerates with catalyst manufacturing networks, China-based bauxite-to-alumina integrated producers, and Japanese electronics-grade specialists. Competitive moves concentrate on multi-year supply agreement lock-ins and certified compliance documentation for regulated water utility procurement.
Among Germany-based chemical conglomerates, BASF SE exemplifies the integrated multinational archetype through its catalyst manufacturing footprint. Chinese producers including CHALCO Shandong Co., Ltd. and Shandong Zhongxin New Material Technology Co., Ltd. occupy positions anchored to domestic bauxite conversion infrastructure. Sumitomo Chemical Co., Ltd. represents the electronics-grade specialization tier. These named entities illustrate how competitive positioning maps to supply chain control, regulatory certification depth, and technical specification granularity rather than scale alone.
| Leading Market Players |
|---|
| Axens |
| Shandong Zhongxin New Material Technology Co., Ltd. |
| BASF SE |
| CHALCO Shandong Co., Ltd. |
| Luoyang Xinghua Chemical Co., Ltd. |
| Honeywell International Inc. |
| Sorbead India |
| Jiangsu Jingjing New Material Co. Ltd. |
| Sumitomo Chemical Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Bauxite calcination energy costs cascade through activated alumina pricing tiers, with Shandong province's captive thermal power insulating domestic Chinese producers from LNG volatility that compresses margins for Southeast Asian importers. The divergence between integrated and merchant supply structures creates a three-tier pricing structure across premium, standard, and economy levels that maps to certification depth and regeneration service bundling.
Pricing Analysis
Input-cost pass-through from natural gas and electricity tariffs shapes contract negotiations, with energy-intensive thermal activation exposing non-integrated producers to margin compression. Price differentiation hinges on BIS certification documentation for Indian water utilities and METI-compliant regenerability for Japanese electronics manufacturers. Pricing pressure stems from zeolite substitution in petrochemical drying, forcing alumina suppliers to absorb freight costs to defend market position. Industrial maintenance teams in Southeast Asia exhibit highest price sensitivity, while semiconductor fabs in Japan and South Korea prioritize trace metal specifications over unit economics.
Supply Chain Analysis
Regional distribution centers in Shanghai, Osaka, and Singapore coordinate hub-and-spoke patterns that consolidate bulk desiccant shipments for downstream blending. Geographic supply concentrates in China, India, and Japan, with Shandong province's bauxite-to-alumina infrastructure feeding downstream activation furnaces. Raw material dependencies encompass Guinean and Australian bauxite, caustic soda for Bayer process refining, and natural gas for thermal dehydration. Single-source vulnerability concentrates in CHALCO's domestic bauxite conversion monopoly. Distribution runs through direct sales channels for large water utilities and petrochemical operators, with distributor networks serving fragmented industrial maintenance procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's MEE effluent mandates and India's BIS certification expansion create structural demand floors that outpace GDP-linked industrial cycles.
For Market Incumbents: Anchor supply continuity through backward integration into bauxite conversion capacity or long-term offtake agreements with Shandong-based raw material controllers. Defend against zeolite substitution by embedding performance guarantees and regeneration services into multi-year contracts with Thai and Indonesian petrochemical operators. Prioritize certification investment for BIS documentation to capture Indian municipal infrastructure expansion.
For New Entrants and Emerging Players: Municipal water utilities in Vietnam and the Philippines represent the most penetrable buyer archetype, with arsenic remediation programs accelerating procurement faster than qualified supplier growth. Electronics-grade solvent purification for Japanese display panel manufacturers offers technical specification gaps where ultra-low trace metal capabilities differentiate new entrants. Pursue joint development contracts with semiconductor fabs rather than commodity spot sales to establish qualification credentials.
For Investors and Strategic Acquirers: Consolidation pressure builds where BIS certification documentation and MEE compliance protocols create compliance barriers that favor scaled incumbents over fragmented regional formulators. Long-term viability centers on captive bauxite supply or specialized adsorbent grades with regenerable system integration. Acquisition targets include domestic Chinese producers with certified GB standard compliance and Japanese electronics-grade specialists. Monitor METI circular economy guideline enforcement as the inflection signal for regenerable system adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Conversion | CHALCO's Shandong infrastructure demonstrates how captive raw material supply insulates margin structures from energy volatility. |
| BIS Certification Investment | Indian water utilities demand extensive laboratory testing records that extend qualification timelines for uncertified suppliers. |
| Regenerable System Development | Japanese METI circular economy guidelines extend product lifecycles and compress replacement frequency among industrial end users. |
| Electronics-Grade Specialization | Sumitomo Chemical's ultra-low trace metal grades command technical specification premiums from Osaka-based display manufacturers. |
| Performance-Guaranteed Supply Bundles | Thai and Indonesian natural gas processors favor outsourced adsorbent lifecycle management over in-house media replacement programs. |
Research Methodology
Coverage spans China, India, Japan, South Korea, and Southeast Asia, with primary inputs from each market gathered through structured interviews with plant managers at activated alumina production facilities, procurement leads at downstream petrochemical and electronics manufacturers, water utility technical directors, and distribution channel partners. Secondary validation draws from Chinese customs and trade data, MEE enforcement disclosures, BIS certification registries, and SEC filings of multinational chemical conglomerates. Bottom-up capacity and demand modeling triangulates against top-down macroeconomic and regulatory scenario analysis.
Granularity-level modeling distinguishes desiccant, catalyst support, and adsorbent grades across water treatment, oil and gas, and electronics applications, with end-user segmentation capturing industrial maintenance procurement, municipal utility frameworks, and semiconductor fabrication standards. CAGRs derive from regression analysis of historical procurement patterns against regulatory milestone timing and industrial capacity expansion schedules. Forecast inputs incorporate bauxite supply continuity assessments, MEE enforcement intensity scenarios, and BIS certification adoption curves.
Underlying measurement precision varies by segment; desiccant-grade volumes carry tighter precision than catalyst support custom synthesis given standardized specifications. Forecasts reflect assumptions around regulatory enforcement continuity, energy cost trajectories, and zeolite substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Mullite Market
Ceramics
Nanoceramic Powder Market
Ceramics
Philippines Ceramic Tiles Market
Ceramics
Activated Alumina Market
Ceramics
Ceramic Ware Market
Ceramics
Dielectric Ceramics Market
Ceramics
Germany Ceramic Tiles Market
Ceramics
Titanium Carbide Market
Ceramics
Co-Fired Ceramic Market
Ceramics
Saudi Arabia Ceramic Tiles Market
Ceramics
Advanced Structural Ceramics Market
Ceramics
Cerium Nitride Market
Ceramics
West Africa Ceramic Tiles Market
Ceramics
Global Metal and Ceramic Injection Molding Market
Ceramics
Liquid Sodium Silicate Market
Ceramics
Low Density Ceramic Proppant Market