
 East Africa Ceramic Tiles Market | 2026-2036
East Africa Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa Ceramic Tiles Market Intelligence
Kenyan tile manufacturing capacity is repositioning toward larger-format production to serve cross-border demand from Uganda and Rwanda. Royal Ceramics leverages its coastal logistics position to control distribution routes into the East African Community. African Ceramic Holdings anchors its competitiveness through captive clay sourcing in the Kenyan Rift Valley. EcoCeramics Africa differentiates via low-emission kiln technology that aligns with tightening environmental standards.
East Africa ceramic tiles are flat, fired clay or porcelain slabs typically measuring 300x300mm to 600x600mm, formed through dry pressing and glazed or vitrified for hardness and stain resistance, serving primarily as surfacing materials for floors and walls in buildings. Porcelain tiles command premium positioning due to water absorption below 0.5 percent and suitability for heavy commercial traffic in Nairobi and Kampala shopping complexes. The residential end-use segment sustains volume leadership across single-family housing estates in Tanzania's Arusha corridor, while direct sales channels to large construction firms capture margin pools through project-specific bulk contracting.
Kenya's KEBS enforces KS 1804 standards for dimensional tolerances and breaking strength, while Tanzania's TBS applies TZS 772 specifications that restrict entry of substandard imports from Asian suppliers. Rwanda's Rwanda Standards Board mandates ISO 13006 alignment for all ceramic construction materials entering through the Central Corridor. Stakeholders must monitor harmonization progress under the East African Community Customs Union Protocol, where divergent national standards still fragment procurement decisions.
Market Dynamics
Urban construction corridors across Kenya and Tanzania are pulling tile specification toward large-format porcelain, while KEBS certification tightening is filtering out informal import channels and consolidating compliant supply bases.
Growth Catalysts
- KEBS KS 1804 Enforcement:Dimensional tolerance mandates are eliminating substandard Asian imports and clearing shelf space for certified domestic producers in Nairobi's distribution hubs.
- Commercial Real Estate Specification:Shopping complex developers in Kampala and Dar es Salaam are mandating vitrified tiles for high-traffic atriums, creating pull-through demand for premium-grade inventory.
- Dry-Pressing Technology Migration:Kenyan manufacturers are upgrading from wet-casting to automated dry-pressing lines, cutting firing cycles and enabling 600x600mm production at scale.
Market Restraints
- Natural Gas Price Volatility:Kiln operations in Mombasa and Athi River depend on imported LNG, exposing margin structures to freight-driven cost spikes.
- Clay Deposit Concentration:High-grade kaolin reserves cluster in the Kenyan Rift Valley, forcing Tanzanian and Ugandan producers into cross-border raw material dependence.
- Substandard Ceramic Substitution:Uncertified Vietnamese glazed wall tiles continue penetrating informal retail channels in Kigali and Bujumbura, compressing price floors.
Strategic Opportunities
- Rwanda Construction Uplift:Kigali's masterplan densification is generating demand for 400x400mm floor tiles in mid-rise residential towers, a format segment currently underserved by regional supply.
- East African Community Tariff Harmonization:Pending Customs Union Protocol alignment could eliminate double-duty stacking on Ugandan imports transiting through Mombasa.
- Digital Specification Platforms:Nairobi-based architects are adopting BIM-integrated tile libraries, opening direct-to-designer channels that bypass traditional distributor markups.
Industry Challenges
- Kiln Technician Scarcity:Automated roller-hearth operation requires specialized firing curve management skills that training institutes in Tanzania and Uganda have not yet scaled.
- Multi-Jurisdiction Certification Lag:Products seeking simultaneous KEBS, TBS, and Rwanda Standards Board approval face non-overlapping test protocols that extend time-to-market by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa Ceramic Tiles Market |
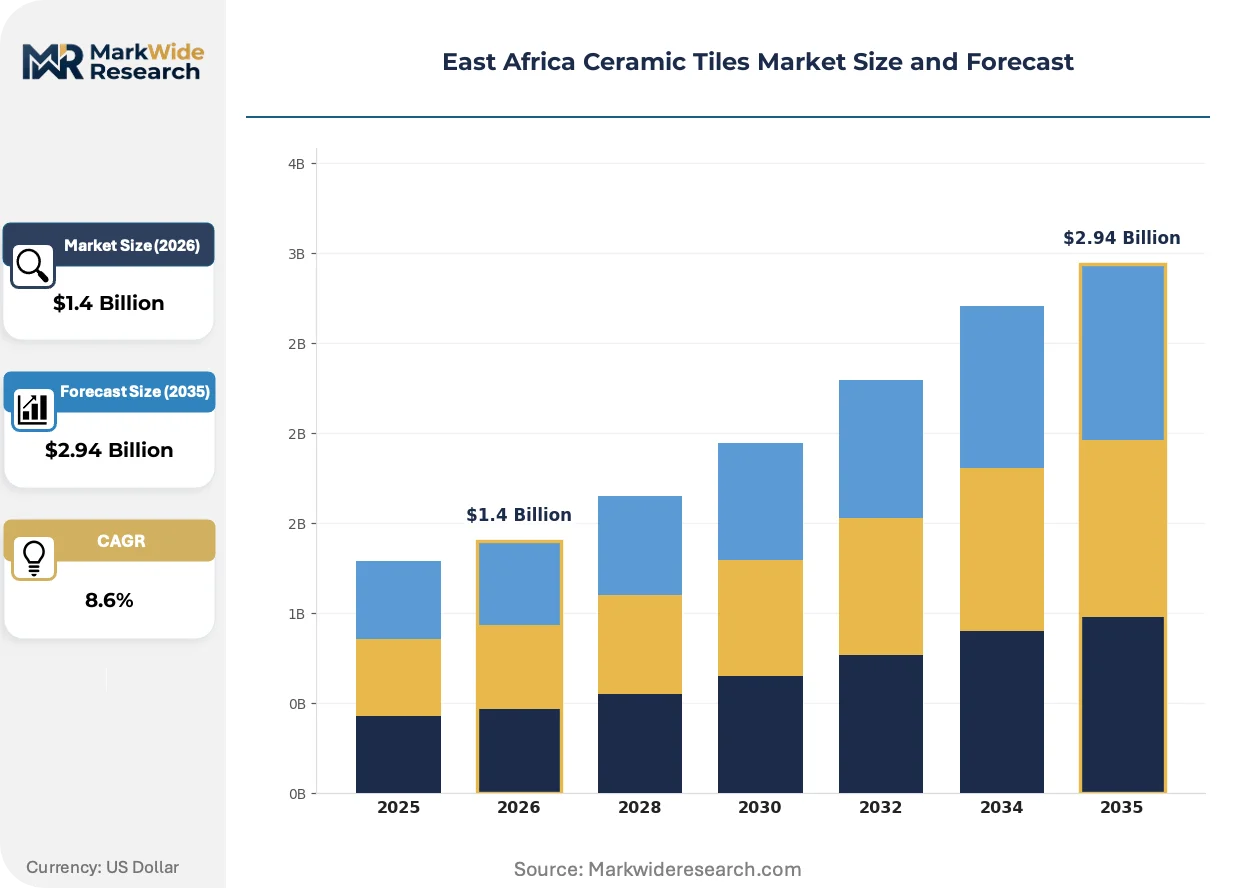
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed Tiles, Unglazed Tiles, Vitrified Tiles, Porcelain Tiles End Use: Residential, Commercial, Industrial, Institutional Distribution Channel: Direct Sales, Distributors, Retailers, Online Design Style: Modern, Traditional, Rustic, Contemporary |
| Companies Covered | Royal Ceramics, African Ceramic Holdings, EcoCeramics Africa, Maghreb Ceramics SA, West African Ceramics Ltd, Equatorial Ceramics Group, CeramicMasters Limited, Innovative Ceramics Co. Ltd, Nile Ceramics, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa Ceramic Tiles Market Strategic Shifts & Innovations
Digital inkjet decoration and low-emission firing systems are redefining product differentiation in East Africa, while procurement behavior shifts toward specification-led bulk contracting.
Roller-hearth kiln automation is automating temperature uniformity control across extended firing zones. Commercial tile producers in Kenya's Athi River corridor are adopting these systems to reduce thermal variation defects in large-format porcelain. The technology is automating quality consistency at speeds that manual kiln monitoring cannot sustain, compressing rejection rates and enabling just-in-time production scheduling.
Tanzania's TBS has tightened TZS 772 enforcement on water absorption testing for imported glazed tiles. The regulation is forcing Mombasa port clearance delays for non-compliant shipments and redirecting procurement toward pre-certified regional suppliers. Ugandan distributors are responding by consolidating orders through Kenyan intermediaries with established TBS documentation pipelines.
Construction firms in Nairobi and Dar es Salaam are consolidating tile procurement under master service agreements with volume-tiered pricing. Direct contracting is displacing spot-market purchasing through fragmented hardware retailers. The shift is most visible in Tanzania's commercial sector, where developers like those in the Bagamoyo corridor are locking three-year supply commitments to secure project financing.
East Africa Ceramic Tiles Market Segmentation
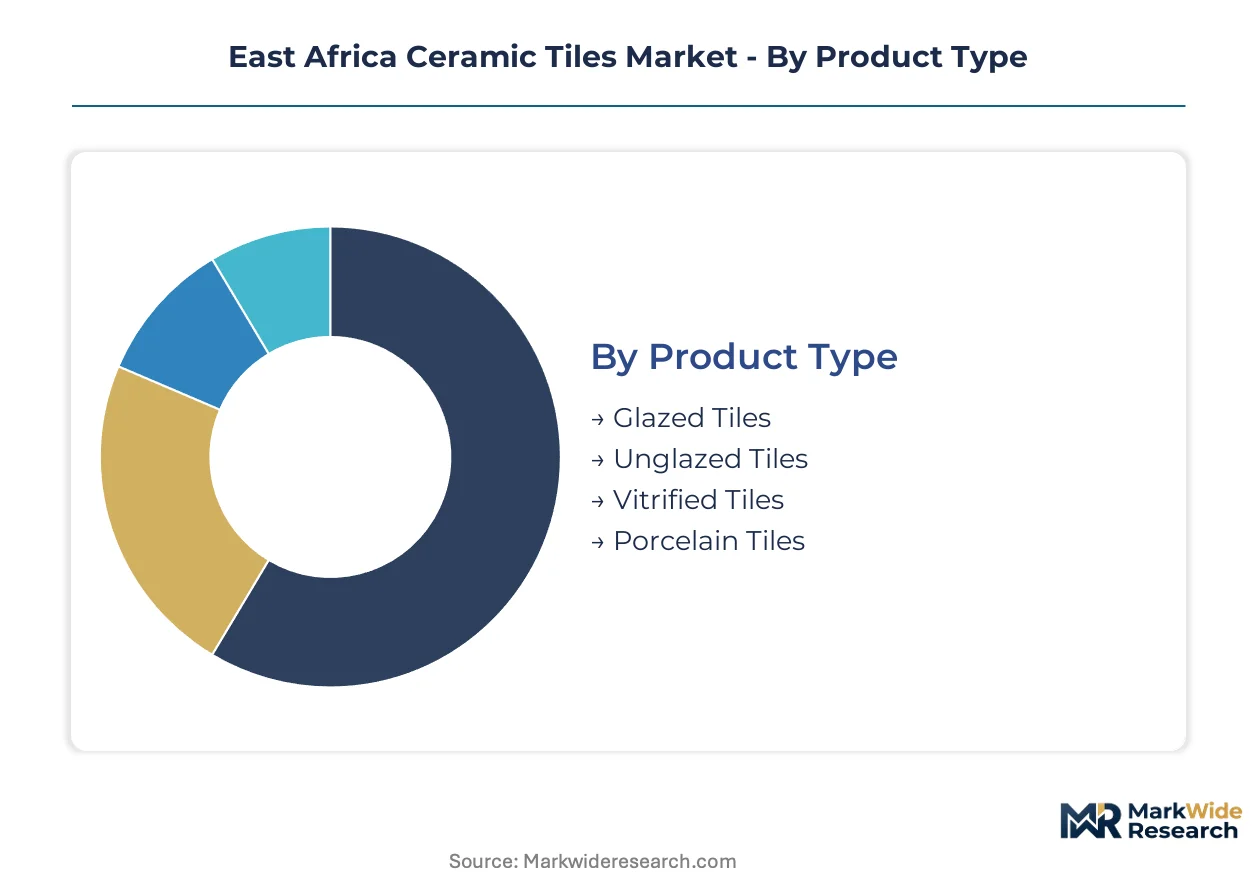
Tile specification in East Africa splits across material performance grades, project scale, and procurement sophistication. Understanding these divides reveals where margin pools concentrate and which channels are consolidating.
Product Type:
Buyers in this category differentiate by water absorption thresholds, traffic load requirements, and installation substrate conditions.
- Glazed Tiles:Ceramic bodies receive liquid glass coatings that create decorative surfaces with moderate stain resistance. Single-family housing estates in Tanzania's Arusha corridor specify these for interior walls where foot traffic remains light and cost sensitivity runs high.
- Vitrified Tiles:Clay bodies undergo full vitrification, achieving near-zero porosity and Mohs hardness above 6. Nairobi shopping complex developers mandate these for high-traffic atriums where KEBS KS 1804 breaking strength requirements exceed 1300N.
- Unglazed Tiles:Fired clay surfaces retain natural texture without glass coating, suited to exterior applications where slip resistance matters. Industrial warehouse flooring in Dar es Salaam's industrial zones absorbs modest volumes.
- Porcelain Tiles:Fine kaolin compositions fired above 1200°C yield water absorption below 0.5 percent. Kampala commercial towers specify these for premium positioning, though Kenyan Rift Valley clay dependence constrains regional supply.
Glazed tiles lead volumes today; vitrified tiles are gaining share fastest.
End Use:
Project scale and specification authority determine procurement channel and price tier accessed.
- Residential:Single-family housing and multi-unit apartments drive bulk consumption across format sizes from 300x300mm to 400x400mm. Tanzania's satellite corridor construction absorbs consistent flow through distributor networks serving owner-developers.
- Commercial:Retail complexes, office towers, and hospitality projects command 600x600mm porcelain with master service agreement pricing. Bagamoyo corridor developers lock multi-year supply commitments to satisfy project financing covenants.
- Industrial:Manufacturing facilities and logistics warehouses prioritize mechanical durability over aesthetic variation. Athi River industrial zone flooring specifications emphasize abrasion resistance class ratings.
- Institutional:Government buildings, schools, and healthcare facilities operate under public procurement frameworks with mandatory KEBS or TBS certification. Kigali's masterplan densification is expanding this segment's specification influence.
Residential commands absolute volume; commercial is expanding most quickly as shopping complex development accelerates.
Distribution Channel:
Customer size and project complexity determine whether buyers access direct manufacturer pricing or absorb distributor markups.
- Direct Sales:Large construction firms and commercial developers negotiate project-specific bulk contracts bypassing retail layers. Dar es Salaam developers in the Bagamoyo corridor leverage this channel for three-year volume commitments.
- Distributors:Regional wholesalers control inventory positioning across Mombasa port clearance through Nairobi and Kampala secondary markets. Royal Ceramics leverages coastal logistics to dominate this channel into the East African Community.
- Retailers:Hardware stores and specialty tile shops serve owner-builders and renovation contractors with spot-market purchasing. Kigali's informal retail channels remain vulnerable to uncertified Vietnamese glazed wall tile penetration.
- Online:Digital specification platforms and B2B procurement portals are emerging in Nairobi's architect community. BIM-integrated tile libraries enable direct-to-designer channels that bypass traditional distributor structures.
Distributors still handle majority volume; direct sales are climbing the fastest as commercial project scale concentrates.
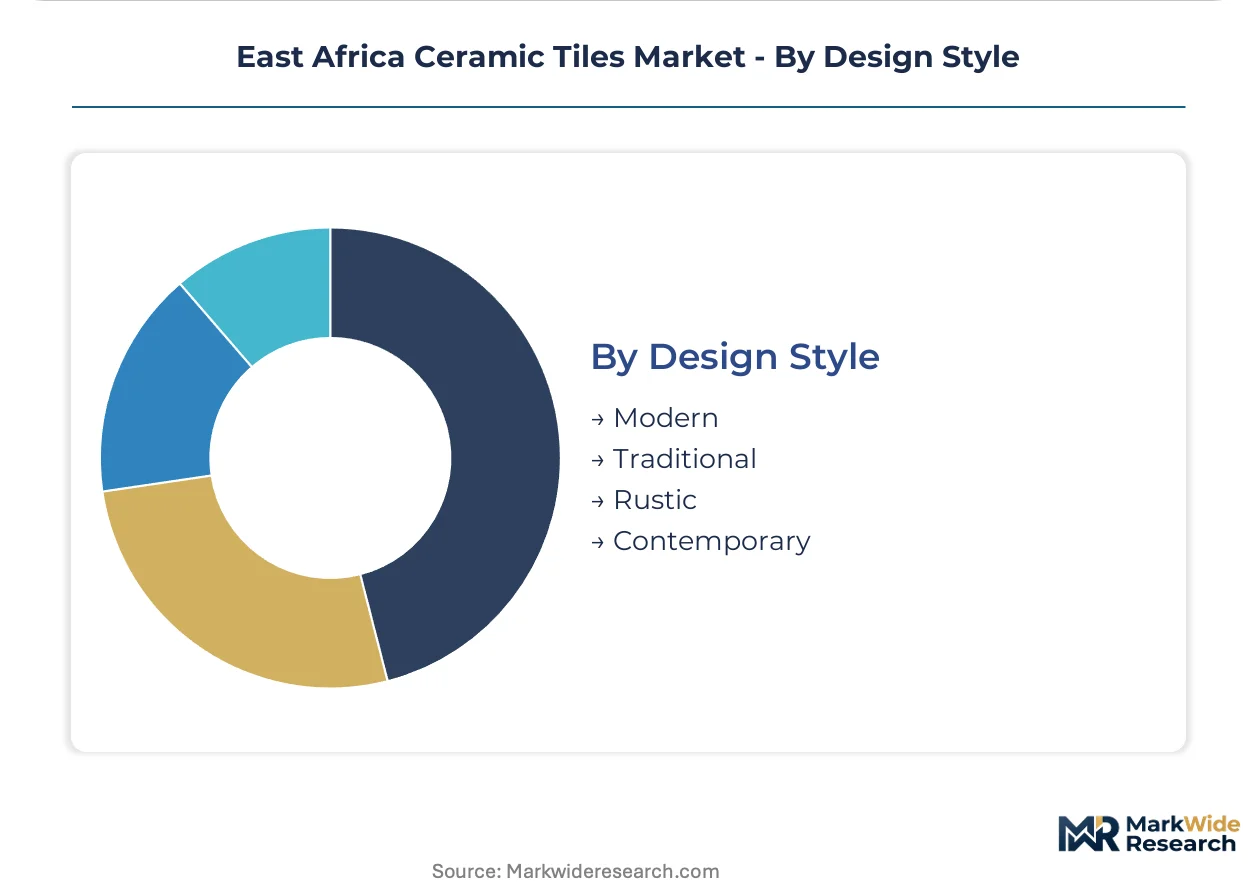
Design Style:
Aesthetic preference correlates with building typology, client sophistication, and export market orientation of specification teams.
- Modern:Clean lines, minimal grout visibility, and large-format rectified edges dominate Nairobi commercial towers. Kenyan manufacturers are upgrading dry-pressing lines to serve this specification at 600x600mm scale.
- Contemporary:Updated interpretations of classic patterns with digital inkjet decoration enable wood-grain and stone-look surfaces. Tanzanian mid-rise residential towers in Kigali's densification zones specify these for differentiated positioning.
- Traditional:Ornate patterns and heritage color palettes persist in institutional and religious building specifications. Limited local production capacity drives import dependence for authentic reproductions.
- Rustic:Textured surfaces and natural tonal variation suit leisure hospitality and eco-tourism developments. Uganda's safari lodge construction generates niche demand through specialized distributors.
Modern styling leads specification frequency today; contemporary is gaining share fastest as digital decoration technology spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward Kenya as KEBS certification tightens, widening the compliance-cost gap with neighbors and concentrating compliant capacity around Mombasa port logistics.
Kenya
Nairobi's satellite corridors and Athi River industrial zone absorb large-format porcelain for residential estates and commercial towers. KEBS enforces KS 1804 dimensional tolerances and breaking strength mandates that filter substandard imports. Royal Ceramics leverages coastal positioning to control distribution routes into Uganda and Rwanda.
Tanzania
Dar es Salaam's industrial zones and Bagamoyo corridor drive vitrified tile demand for high-traffic commercial applications. TBS applies TZS 772 water absorption specifications that delay Mombasa port clearance for non-compliant shipments. Master service agreements with three-year supply commitments are displacing spot-market purchasing.
Uganda
Kampala shopping complexes specify premium porcelain for atriums, though producers depend on cross-border clay from Kenya's Rift Valley. The country's national standards regulator mandates alignment with EAC Customs Union protocols. Distributors consolidate orders through Kenyan intermediaries with established documentation pipelines.
Rwanda
Kigali's masterplan densification generates demand for 400x400mm floor tiles in mid-rise residential towers. The Rwanda Standards Board requires ISO 13006 alignment for all ceramic construction materials entering through the Central Corridor. Informal retail channels remain vulnerable to uncertified Vietnamese glazed wall tile penetration.
Burundi
Bujumbura's construction sector absorbs modest volumes through informal import channels that bypass regional certification requirements. The country's standards enforcement capacity lags EAC neighbors, creating price-floor compression from substandard Asian supply. Distributor networks from Tanzania's Lake Victoria corridor dominate inbound logistics.
East Africa Ceramic Tiles Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue low-emission kiln differentiation and digital specification channels. Kenyan manufacturers anchor supply through captive Rift Valley clay sourcing, while coastal logistics operators control cross-border distribution into landlocked neighbors. Three archetypes define positioning: standards-compliant domestic producers with KEBS certification, coastal logistics-integrated distributors, and technology-differentiated specialists with environmental credentials. Capacity expansion and direct-to-developer contracting represent the dominant competitive moves as commercial project scale concentrates procurement authority.
Among Kenya-based fabricators, Royal Ceramics and African Ceramic Holdings exemplify the coastal-logistics and captive-resource archetypes respectively, while EcoCeramics Africa occupies a position within the environmental-technology tier. Royal Ceramics leverages its Mombasa-adjacent positioning to anchor distribution control, African Ceramic Holdings represents backward integration into clay sourcing, and EcoCeramics Africa exemplifies low-emission differentiation aligned with tightening standards. These three companies illustrate how compliance positioning, resource control, and technology credentials are reshaping competitive boundaries.
| Leading Market Players |
|---|
| Royal Ceramics |
| African Ceramic Holdings |
| EcoCeramics Africa |
| Maghreb Ceramics SA |
| West African Ceramics Ltd |
| Equatorial Ceramics Group |
| CeramicMasters Limited |
| Innovative Ceramics Co. Ltd |
| Nile Ceramics |
| Others |
Cost & Logistics Intelligence
Natural gas costs for kiln firing migrate from imported LNG landed at Mombasa through manufacturing cost structures to final tile pricing tiers, with energy-intensive vitrified production commanding premium positioning over glazed alternatives.
Pricing Analysis
Distributor margins absorb the primary pricing compression as Kenyan manufacturers bypass retail layers through direct-to-developer contracting. Three-tier pricing structure across premium, standard, and economy levels separates KEBS-certified vitrified tiles from uncertified imports and basic glazed wall products. Price differentiation rests on certification grade and volume scale, with master service agreements securing 15-20 point discounts below spot distributor rates. Cost compression in the economy tier intensifies because Vietnamese glazed tiles penetrate informal Kigali and Bujumbura channels. Residential owner-builders exhibit highest price sensitivity; commercial developers with project financing covenants prioritize specification compliance over unit cost.
Supply Chain Analysis
Kiln technician scarcity in Tanzania and Uganda constrains automated roller-hearth operation scaling despite equipment availability. Supply concentrates in Kenya's Athi River corridor and Mombasa-adjacent zones, with secondary nodes forming around Dar es Salaam's industrial districts. Raw material dependencies center on Rift Valley kaolin deposits, imported LNG for firing energy, and digital inkjet decoration pigments from European suppliers. Single-source vulnerability runs through Kenyan clay dominance over regional vitrified production. Distribution runs through coastal logistics operators controlling Mombasa port clearance into landlocked East African Community markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
KEBS KS 1804 enforcement acts as a regulatory compounder, tightening dimensional tolerance mandates that eliminate substandard imports and consolidate compliant domestic capacity around certified producers.
For Market Incumbents: Lock in captive clay sourcing through Rift Valley lease consolidation to defend against Tanzanian and Ugandan producers seeking backward integration. Secure multi-year master service agreements with Bagamoyo corridor developers before project financing covenants standardize procurement. Certification investment represents the critical lever against emerging low-emission kiln specialists.
For New Entrants and Emerging Players: Mid-rise residential tower developers in Kigali's densification zones remain underserved for 400x400mm format supply, creating white-space entry opportunity. Rwanda's ISO 13006 alignment mandate filters informal competitors while rewarding pre-certified regional suppliers. Direct BIM-integrated specification channels to Nairobi architects bypass entrenched distributor markups.
For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction certification lag extends time-to-market by quarters for cross-border suppliers. Long-term viability favors vertically integrated producers with captive raw material and coastal logistics positioning. Watch harmonization progress under East African Community Customs Union Protocol as inflection signal for tariff-driven margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Clay Source Development | Rift Valley lease consolidation secures vitrified tile feedstock against cross-border dependence. |
| Automated Dry-Pressing Line Upgrade | 600x600mm production capability captures Nairobi commercial tower specification demand. |
| Multi-Jurisdiction Certification Investment | Simultaneous KEBS, TBS, and Rwanda Standards Board approval compresses competitor time-to-market. |
| Direct-to-Developer Contracting | Master service agreements with Dar es Salaam commercial developers displace spot-market purchasing. |
| Low-Emission Kiln Technology Deployment | Roller-hearth automation aligns with tightening environmental standards and reduces thermal defect rates. |
Research Approach
Coverage spans Kenya, Tanzania, Uganda, Rwanda, and Burundi, with primary inputs from each national market. The research combines structured interviews with plant operations managers, procurement leads at commercial developers, distribution channel partners, and regulatory affairs specialists at national standards bodies with secondary validation. Secondary sources include KEBS and TBS certification registries, East African Community customs documentation, construction sector procurement databases, and industrial energy consumption disclosures. Bottom-up production capacity modeling and top-down demand estimation from construction permit data provide triangulation anchors.
Granularity-level framing applies country-level modeling for production capacity and end-use segment splits across residential, commercial, industrial, and institutional applications. The analytical framework projects volume and value across the analysis window using product type segmentation by water absorption threshold and format size. CAGRs derive from construction sector growth correlations, urbanization rate trajectories, and certification penetration assumptions. Forecast inputs incorporate KEBS enforcement intensity scenarios and natural gas price volatility bands.
Underlying measurement precision varies by segment; Kenyan and Tanzanian market data carry tighter precision than Burundian estimates where informal channel dominance obscures volume tracking. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and construction sector credit availability. Material deviation in KEBS enforcement intensity or East African Community tariff alignment warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Solid-Ion Conductors Market
Ceramics
Strontium Carbonate Market
Ceramics
North America Barium Carbonate Market
Ceramics
Traditional Ceramic Market
Ceramics
Ball Clay Market
Ceramics
Europe Ceramic Tiles Market
Ceramics
Global Alumina Trihydrate Market
Ceramics
Refractories Market
Ceramics
Ceramic Substrate Market
Ceramics
2N High Purity Alumina Market
Ceramics
Ceramic Tiles Market
Ceramics
China Clay Market
Ceramics
Ceramic Proppant Market
Ceramics
United Kingdom Ceramic Tiles Market
Ceramics
Asia-Pacific Ceramic Coatings Market
Ceramics
Stoneware Market