
 2N High Purity Alumina Market | 2026-2036
2N High Purity Alumina Market Size, Share, and Industry Trends Forecast 2026-2036
2N High Purity Alumina Market Insights
Subscription-based technical support and predictive purity monitoring is broadening what buyers expect from 2N alumina contracts. Sumitomo Chemical leverages captive hydrolysis technology to sustain premium positioning in Japanese semiconductor supply chains. Sasol Limited anchors African feedstock advantages through integrated bayer-hydrolysis refining. Baikowski SAS differentiates via French precision powder engineering for optical-grade applications.
2N high purity alumina denotes aluminum oxide with minimum 99% purity, typically synthesized via alkoxide hydrolysis or bayer process refinement followed by calcination at 1,200–1,400°C to achieve controlled particle size distribution and low sodium content for electronic substrate applications. Powder formulations dominate procurement volumes due to established integration into ceramic tape casting and sapphire crystal growth processes, while granular grades capture margin pools in specialized refractory linings where thermal shock resistance commands premium pricing. Electronics applications lead absolute consumption as multilayer ceramic capacitor manufacturers standardize on 2N alumina for dielectric layer stability.
Japan's METI enforces JIS standards for electronic-grade ceramics that mandate trace metal thresholds below 50 ppm total impurities, directly filtering market access for non-compliant imports. China's SAMR and MIIT coordinate GB standard revisions for battery separator ceramics that extend purity requirements toward 2N thresholds, reshaping qualification protocols for domestic suppliers. REACH registration in Europe obliges full impurity disclosure for alumina imports above one tonne annually, elevating compliance costs for smaller exporters. Stakeholders must monitor divergence between Asian purity benchmarks and European chemical safety documentation requirements when structuring multi-region supply agreements.
Market Dynamics
China's GB standard revisions for battery separator ceramics are compressing qualification timelines for domestic refiners while Japanese semiconductor buyers tighten incoming impurity thresholds. This regulatory divergence is fragmenting contract structures across East Asian supply chains.
Growth Catalysts
- Alkoxide hydrolysis refinement:Advanced synthesis routes enable sodium content below 100 ppm, satisfying METI JIS standards for multilayer capacitor substrates in Japan's semiconductor corridor.
- MIIT battery separator mandates:China's 2024 GB standard extensions toward 2N purity thresholds are forcing domestic alumina producers into capacity upgrades for ceramic-coated separators.
- East Asian ceramic substrate expansion:Multilayer capacitor manufacturers in Taiwan and South Korea are standardizing on 2N alumina for dielectric stability in 5G base station components.
Market Restraints
- Feedstock concentration:High-quality bauxite reserves concentrate in Guinea and Australia, exposing refiners to maritime logistics volatility and geopolitical supply interruptions.
- Energy cost intensity:Calcination at 1,200–1,400°C demands sustained natural gas or electricity inputs, with European producers facing F-Gas Regulation compliance premiums on thermal processing equipment.
- Synthetic sapphire substitution:Kyropoulos-grown sapphire wafers for LED substrates are displacing alumina ceramic approaches in high-brightness applications, compressing powder demand in optical-grade segments.
Strategic Opportunities
- Indian battery materials corridor:PLI scheme incentives for advanced cell manufacturing are creating first-mover windows for 2N alumina suppliers to localize separator ceramic supply.
- Predictive purity monitoring:IoT-enabled real-time sodium and iron tracking during hydrolysis is enabling subscription-based technical service contracts that extend supplier stickiness beyond commodity pricing.
- REACH registration arbitrage:Full impurity disclosure obligations above one tonne annually are elevating compliance costs for smaller exporters, creating consolidation opportunities for registrant-compliant European distributors.
Industry Challenges
- Hydrolysis process engineering talent:Captive alkoxide synthesis expertise resides with a narrow cohort of Japanese and French specialists, constraining capacity expansion at second-tier refiners.
- Dual certification timelines:Simultaneous qualification under JIS R 1601 and evolving GB/T standards for battery ceramics extends customer approval cycles to 18–24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2N High Purity Alumina Market |
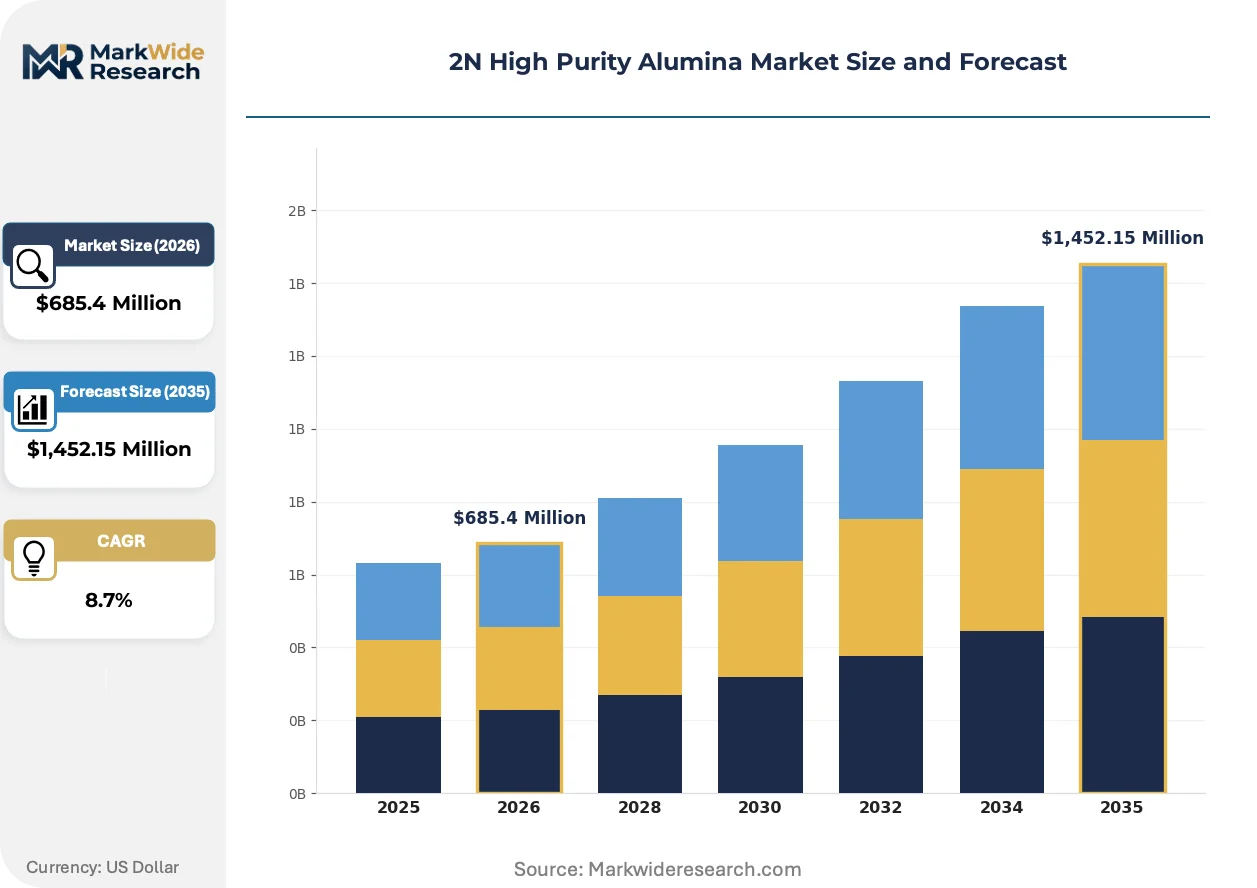
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Pellets, Rods Application: Electronics, Optics, Ceramics, Refractories End User: Aerospace, Automotive, Healthcare, Renewable Energy Delivery Mode: Bulk Shipment, Small Packages, Direct Delivery, Freight |
| Companies Covered | Sumitomo Chemical Co., Ltd., Nippon Light Metal Holdings Co., Ltd., Sasol Limited, Altech Chemicals Limited, Baikowski SAS, CHALCO Advanced Material Co., Ltd., Alpha HPA Ltd., Xuancheng Jingrui New Material Co., Ltd., Zibo Honghe Chemical Co., LTD., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2N High Purity Alumina Market Trends and Innovations
Continuous powder engineering and regulatory disclosure obligations are restructuring how purity is verified, priced, and contracted across electronic-grade alumina markets. Technical service unbundling from material supply is gaining traction among capacitor manufacturers.
Alkoxide hydrolysis with in-line laser diffraction particle sizing is rewriting process control economics in 2N alumina production. Semiconductor ceramic manufacturers in Japan's Kansai corridor are adopting these closed-loop systems to compress batch-to-batch variability. Real-time sodium monitoring is enabling just-in-time qualification that shortens customer approval cycles from months to weeks.
REACH Article 33 disclosure extensions for ceramic raw materials are forcing importers into comprehensive impurity documentation above one tonne annual volume. European capacitor substrate fabricators now require full supply chain substance registration from Asian refiners. German ceramic tape casting operations are consolidating procurement around registrant-compliant suppliers to avoid customs interruption.
Subscription-based purity assurance contracts are displacing traditional spot purchasing for multilayer capacitor manufacturers. Japanese electronics conglomerates now bundle predictive sodium monitoring with multi-year alumina supply agreements. South Korean battery separator producers are piloting similar outcome-linked pricing models for ceramic coating materials.
2N High Purity Alumina Market Segmentation
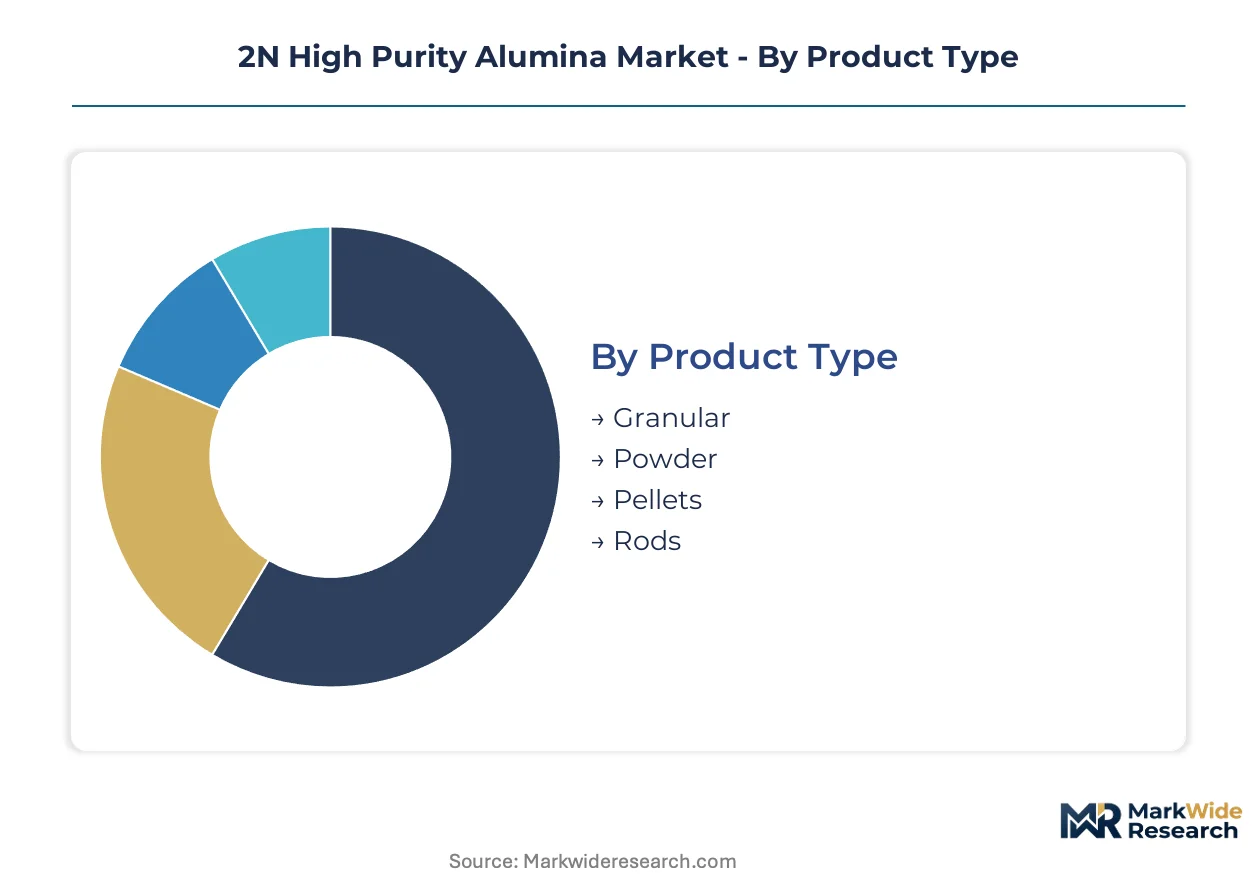
2N high purity alumina procurement patterns fragment sharply across physical form factors and delivery modalities. End-use specifications from semiconductor dielectric layers to ceramic-coated battery separators impose distinct purity thresholds and particle size requirements that reshape supplier qualification protocols.
Product Type:
Supply concentration in alkoxide hydrolysis capacity favors producers with captive powder engineering capabilities, tilting procurement toward integrated refiners over merchant traders.
- Powder:Dominant physical form for ceramic tape casting and sapphire crystal growth, with sodium content below 100 ppm demanded by METI JIS standards for multilayer capacitor substrates. Japanese semiconductor material corridors in Osaka and Kyoto standardize procurement on spray-dried powder with laser-diffusion-controlled particle distribution. Sumitomo Chemical and Nippon Light Metal anchor regional supply chains through captive hydrolysis infrastructure.
- Granular:Captures margin pools in specialized refractory linings where thermal shock resistance commands premium pricing over standard powder grades. Demand concentrates in German steel continuous casting operations and Japanese glass melting furnace rebuilds where F-Gas Regulation compliance elevates equipment longevity requirements.
- Pellets:Compact feedstock for automated ceramic pressing operations in Taiwanese passive component fabs.
- Rods:Precision-machined preforms for optical lens grinding spindles in French precision engineering clusters.
Today's leader: Powder. Tomorrow's challenger: Granular.
Application:
Cost tier stratification separates qualification-intensive electronics substrates from commodity refractory consumption, with purity premiums widening across the value stack.
- Electronics:Absolute consumption leader as multilayer ceramic capacitor manufacturers standardize on 2N alumina for dielectric layer stability. Taiwan's Yageo and Samsung Electro-Mechanics drive volume through 5G base station component ramps. China's GB standard revisions for battery separator ceramics are compressing qualification timelines for domestic refiners serving CATL and BYD supply chains.
- Optics:Synthetic sapphire grown via Kyropoulos method is displacing alumina ceramic approaches in high-brightness LED substrates, compressing powder demand in optical-grade segments. German precision optics houses in Jena and Oberkochen sustain niche demand for ultra-low-iron grades in ultraviolet lithography systems.
- Ceramics:Technical ceramic structural components for semiconductor wafer handling equipment.
- Refractories:High-temperature furnace linings in aluminum smelting and petrochemical cracking units.
Electronics commands current procurement volumes. Optics faces substitution pressure from crystalline alternatives.
End User:
Customer type diversity spans capital-intensive process industries to precision manufacturing, with aerospace and automotive imposing divergent certification burdens.
- Automotive:Battery separator ceramics for electric vehicle cell manufacturing represent the steepest expansion trajectory, with India's PLI scheme incentives creating first-mover windows for localized 2N alumina supply. South Korean battery producers pilot outcome-linked pricing models for ceramic coating materials.
- Aerospace:Thermal protection system tiles and radome substrates demand lot-traceable purity documentation. REACH Article 33 disclosure extensions force importers into comprehensive impurity documentation above one tonne annual volume.
- Healthcare:Bioceramic implants and dental prosthesis frameworks.
- Renewable Energy:Concentrated solar power receiver coatings and wind turbine bearing ceramics.
Automotive scales fastest. Aerospace maintains tightest documentation requirements.
Delivery Mode:
Volume concentration in East Asian electronics corridors favors bulk shipment economies, while European specialty demand sustains packaged flexibility premiums.
- Bulk Shipment:Tanker and railcar delivery to Japanese semiconductor material corridors and Chinese battery separator ceramic plants. Maritime logistics volatility from Guinea-Australia bauxite concentration exposes refiners to geopolitical interruption risk.
- Small Packages:Drum and pail formats for European specialty ceramic researchers and prototype shops. German tape casting operations consolidate procurement around registrant-compliant suppliers to avoid customs interruption.
- Direct Delivery:Vendor-managed inventory at Taiwanese multilayer capacitor fabs.
- Freight:Containerized spot market movement for refractory grade spot purchases.
Bulk shipment anchors contract economics. Small packages defend margin in fragmented demand pockets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands battery separator ceramic volumes while Japan dominates semiconductor-grade procurement, with both nations driving divergent purity benchmarks across East Asian supply chains.
China
CATL and BYD are scaling ceramic-coated separator production for electric vehicle cells, consuming 2N alumina at unprecedented rates. MIIT's 2024 GB standard extensions toward 2N thresholds are compressing qualification timelines for domestic refiners. Zibo and Xuancheng industrial clusters in Shandong and Anhui provinces are consolidating hydrolysis capacity to serve battery material corridors.
Japan
Multilayer ceramic capacitor manufacturers in Osaka and Kyoto standardize on 2N alumina for 5G base station dielectric stability. METI enforces JIS R 1601 standards mandating trace metal thresholds below 50 ppm total impurities, filtering market access for non-compliant imports. Sumitomo Chemical and Nippon Light Metal anchor the Kansai semiconductor materials corridor through captive alkoxide hydrolysis infrastructure.
South Korea
Samsung Electro-Mechanics and passive component fabs in Suwon are ramping 2N alumina procurement for automotive-grade capacitor substrates. The national industrial regulator coordinates with MFDS on chemical safety documentation for ceramic raw material imports. Busan-Ulsan chemical processing complexes are expanding precursor synthesis capacity to reduce dependency on Japanese powder imports.
Germany
Precision optics houses in Jena and Oberkochen sustain niche demand for ultra-low-iron 2N grades in ultraviolet lithography systems. ECHA's REACH Article 33 disclosure obligations force importers into comprehensive impurity documentation above one tonne annual volume. Bavarian ceramic tape casting operations are consolidating procurement around registrant-compliant suppliers to avoid customs interruption.
India
PLI scheme incentives for advanced cell manufacturing are creating first-mover windows for 2N alumina suppliers to localize separator ceramic supply. The central electricity authority coordinates with BIS on evolving purity standards for battery materials. Gujarat and Maharashtra industrial corridors are attracting hydrolysis technology partnerships to bypass import dependency on East Asian powder sources.
2N High Purity Alumina Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated refiners commanding premium-tier electronics contracts while merchant traders serve refractory spot demand. The vendor base concentrates around alkoxide hydrolysis specialists with captive powder engineering capabilities, creating tiered access to semiconductor-qualified supply. Three archetypes dominate: Japanese-French purity specialists with JIS certification heritage, Chinese state-linked refiners scaling battery-grade output, and South African-Australian feedstock-integrated producers. Competitive moves center on backward integration into bauxite sourcing and multi-region REACH registration to defend European market access.
Among Japanese specialists, Sumitomo Chemical Co., Ltd. and Nippon Light Metal Holdings Co., Ltd. exemplify the premium-tier archetype through their positioning within METI-regulated supply chains. Sasol Limited represents the feedstock-integrated model with African bauxite advantages. These three occupy positions that reflect divergent strategic bets: purity certification depth versus raw material security versus integrated refining scale.
| Leading Market Players |
|---|
| Sumitomo Chemical Co., Ltd. |
| Nippon Light Metal Holdings Co., Ltd. |
| Sasol Limited |
| Altech Chemicals Limited |
| Baikowski SAS |
| CHALCO Advanced Material Co., Ltd. |
| Alpha HPA Ltd. |
| Xuancheng Jingrui New Material Co., Ltd. |
| Zibo Honghe Chemical Co., LTD. |
| Others |
Pricing and Supply Chain Analysis
Hydrolysis process engineering talent concentration in Japan's Kansai corridor and France's Rhône-Alpes region feeds directly into pricing-tier spreads, with labor-cost differentials between captive specialists and second-tier refiners widening premium-standard-economy gaps by certification depth.
Pricing Analysis
Capacity additions in China's Shandong and Anhui provinces are reshaping price floors for battery-grade powder, compressing margins at standard-tier suppliers while METI JIS-certified Japanese producers defend semiconductor premiums. Three-tier pricing structure across premium, standard, and economy levels separates subscription-bundled technical service contracts from spot-market refractory grades. Cost compression in standard-tier battery separator feedstock is intensifying because domestic Chinese refiners accelerate GB-compliant hydrolysis expansions. Automotive battery producers exhibit highest price sensitivity; Japanese multilayer capacitor manufacturers show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Guinea-Australia bauxite concentration, exposing calcination-dependent refiners to maritime logistics disruption. Feedstock draws from West African mines and Australian deposits, with alkoxide precursors sourced from petrochemical complexes in South Korea and Japan. Tariff exposure runs through European REACH registration compliance for imports above one tonne annually. Distribution feeds from East Asian electronics corridors through bulk tanker and railcar into Japanese semiconductor material hubs and Chinese battery ceramic plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story: battery separator ceramic specifications are tightening toward semiconductor-grade purity thresholds, rewarding suppliers with pre-qualified hydrolysis infrastructure.
For Market Incumbents: Deepen captive alkoxide synthesis capabilities to defend against Chinese state-linked refiners scaling battery-grade output. Sumitomo Chemical's JIS certification heritage demonstrates how backward integration into powder engineering sustains premium positioning. Invest in predictive purity monitoring subscriptions to extend customer stickiness beyond commodity pricing cycles. For New Entrants and Emerging Players: India's PLI scheme for advanced cell manufacturing opens a window for localized separator ceramic supply partnerships with Reliance and Ola Electric. Target Gujarat and Maharashtra industrial corridors where hydrolysis technology partnerships can bypass East Asian import dependency. Lead with REACH-registered supply to capture European specialty ceramic researchers seeking registrant-compliant alternatives. For Investors and Strategic Acquirers: Specialty chemical conglomerates with battery materials portfolios are the most active acquirer in this space, seeking JIS-certified hydrolysis assets. Five-to-ten year viability hinges on qualification speed under diverging Asian purity benchmarks. Signal to watch: GB standard revision timelines compressing domestic Chinese refiner approval cycles below eighteen months.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Sourcing | Guinea-Australian feedstock control reduces maritime logistics exposure for calcination-dependent refiners. |
| Predictive Purity Monitoring Subscription | IoT-enabled sodium tracking extends supplier stickiness with Japanese capacitor manufacturers beyond spot pricing. |
| Multi-Region REACH Registration | ECHA compliance above one tonne annual volume defends European market access against customs interruption. |
| Dual Certification Investment | Simultaneous JIS R 1601 and GB/T qualification accelerates customer approval cycles for battery separator ceramics. |
| Localized Hydrolysis Partnership | Indian PLI scheme alignment creates first-mover positioning in Gujarat-Maharashtra battery material corridors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hydrolysis plant managers, procurement leads at multilayer capacitor OEMs, ceramic tape casting technical directors, and battery separator R&D heads with secondary validation from customs/trade data, MIIT GB standard filings, METI JIS documentation, and SEC 10-K disclosures from listed refiners. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Segment-weighting applied product form factors, application purity tiers, and regional regulatory clusters across the projection horizon. CAGRs derived from slope analysis of capacity-expansion pipelines against end-use demand curves, with specific inputs including calcination energy cost trajectories and dual-certificate qualification timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under GB standard acceleration or bauxite supply interruption scenarios. Forecasts reflect documented assumptions on hydrolysis yield improvements and regulatory divergence paths. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Fly Ash and Ceramic Microsphere Market
Ceramics
Ceramic Setter Plate Market
Ceramics
United Kingdom Ceramic Tiles Market
Ceramics
High Purity Mullite Powder Market
Ceramics
Taiwan Ceramic Tiles Market
Ceramics
Global Industrial Clay Market
Ceramics
White Fused Alumina Market
Ceramics
Advanced Structural Ceramics Market
Ceramics
Yttria-Stabilized Zirconia (YSZ) Market
Ceramics
Boiler Refractory Material Market
Ceramics
Ceramic Kilns Market
Ceramics
Cement Castables Market
Ceramics
Malaysia Ceramic Tiles Market
Ceramics
Carbon-Ceramic Discs Market
Ceramics
Strontium Carbonate Market
Ceramics
Global Functional Ceramics Market