
 Aluminium Nitride Market | 2026-2036
Aluminium Nitride Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium Nitride Market Outlook
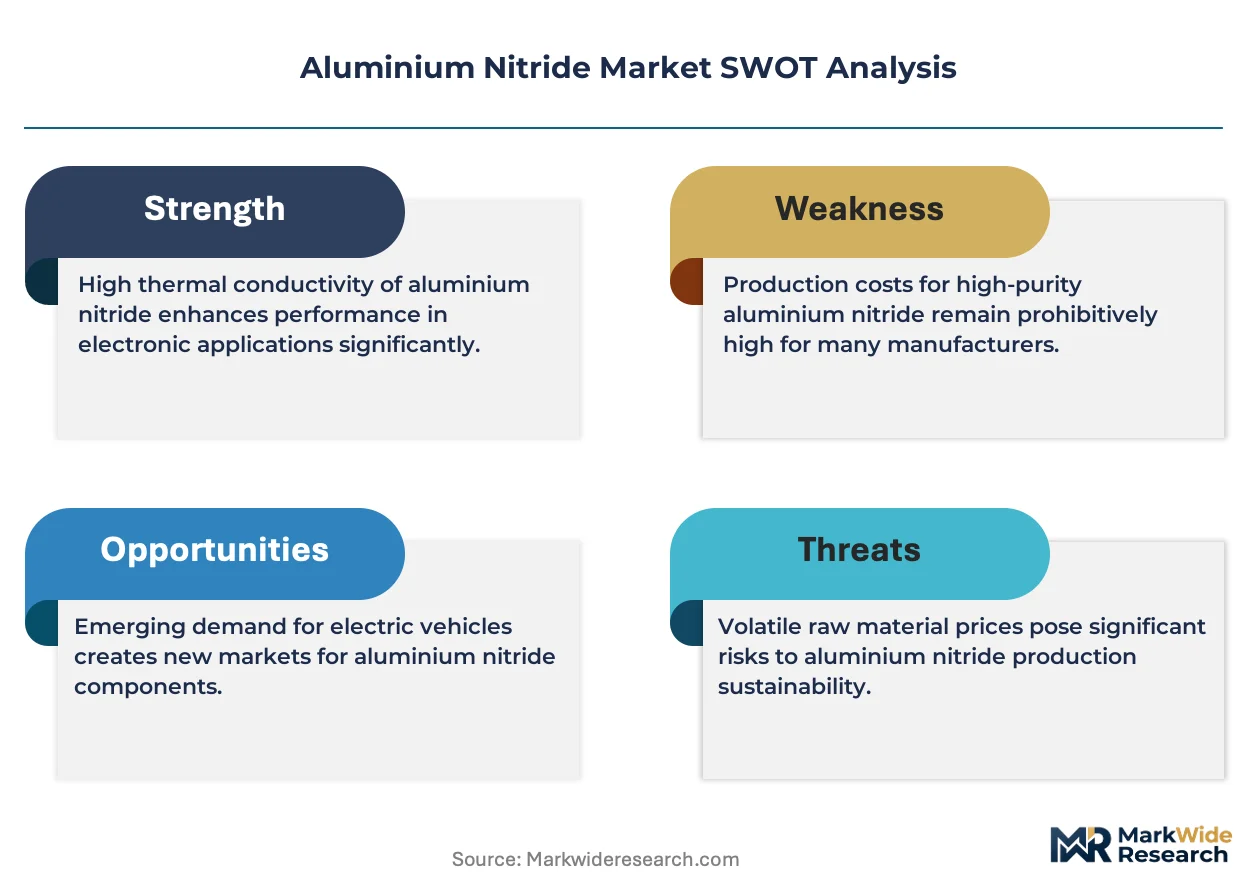
Multi-source procurement for high-purity aluminium nitride powder is rebalancing toward qualified Asian suppliers as European energy costs destabilize legacy contracts. Tokuyama Corporation anchors Japanese substrate output through captive carbothermal reduction capacity. Kyocera Corporation leverages its ceramics heritage to dominate precision sintering for radio-frequency modules. Morgan Advanced Materials competes from British powder plants, though it navigates volatile natural gas pricing that threatens margin stability.
Aluminium nitride is a covalent ceramic with hexagonal wurtzite crystal structure, synthesized via direct nitridation or carbothermal reduction, delivering thermal conductivity exceeding 170 W/m·K alongside electrical insulation for power electronics and LED thermal management. The substrate segment leads value capture because wafer-level packaging for gallium nitride RF devices commands premium pricing tied to thickness uniformity below 25 micrometers. Powder grades for thermal interface materials represent the fastest-growing demand pool as electric vehicle inverters adopt sintered aluminium nitride fillers. The ceramics segment remains mature in industrial heater markets where price sensitivity limits innovation returns.
REACH registration in Europe and China's GB standards enforced by SAMR impose escalating trace-metal limits on powder purity, effectively filtering smaller carbothermal reduction operators from qualified supplier lists. Japan's METI directs national subsidy programs toward domestic aluminium nitride capacity as a designated critical mineral under economic security legislation. Stakeholders must monitor how tightening fluorinated gas regulations under the EU F-Gas Regulation alter CVD process economics for thin-film deposition, since alternative nitridation routes remain unproven at commercial scale.
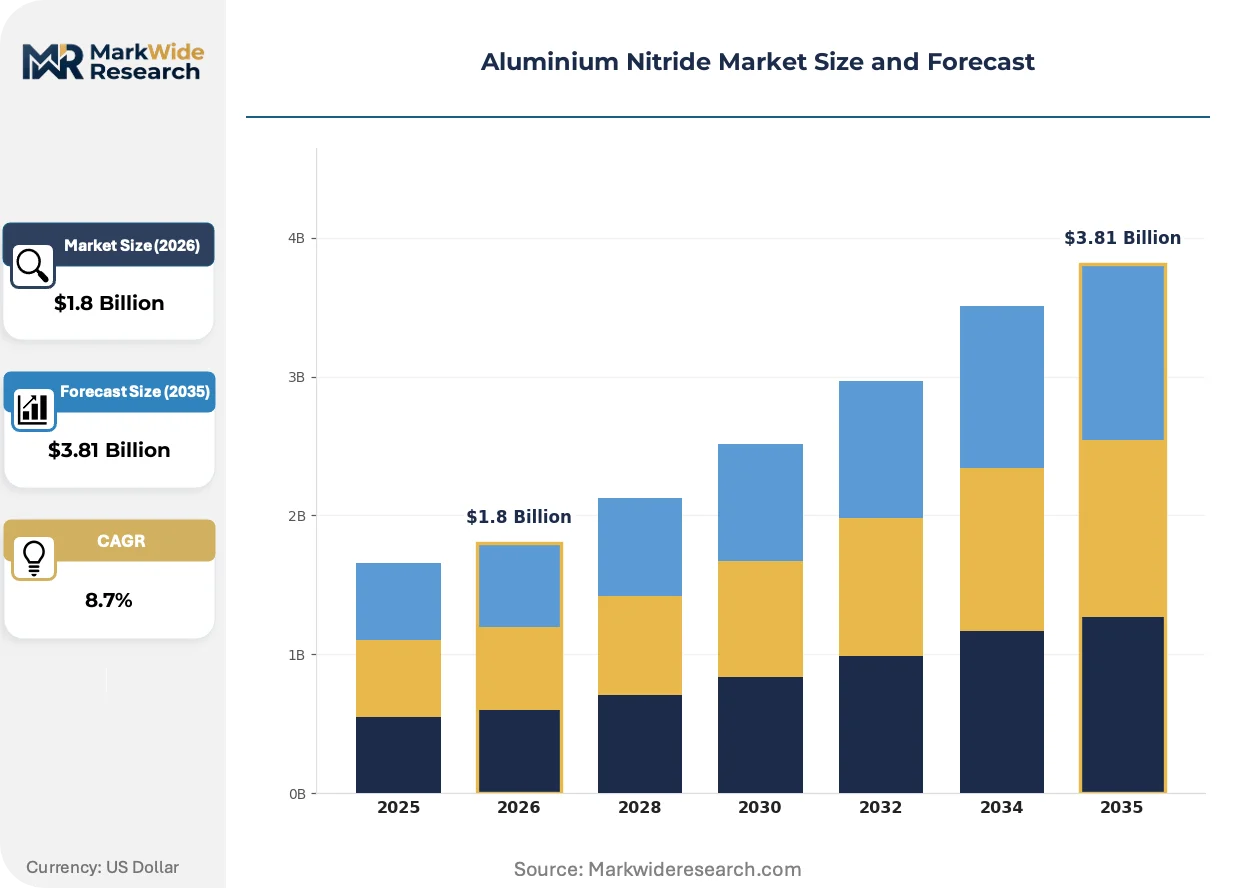
Market Dynamics
Semiconductor packaging lines in Taiwan, South Korea, and Japan are absorbing larger aluminium nitride substrate volumes as gallium nitride power densities exceed legacy thermal management thresholds. This demand concentration is restructuring qualified supplier lists and tightening purity benchmarks across the carbothermal reduction supply base.
Growth Catalysts
- GB standards enforcement:SAMR's escalating trace-metal limits on powder purity are filtering smaller carbothermal reduction operators from qualified supplier lists, consolidating volume with certified producers.
- Gallium nitride RF proliferation:Wafer-level packaging for high-frequency devices commands premium substrate pricing tied to thickness uniformity below 25 micrometers.
- Electric vehicle inverter adoption:Sintered aluminium nitride fillers for thermal interface materials are displacing legacy boron nitride compounds in power module designs.
Market Restraints
- Natural gas cost volatility:European carbothermal reduction operations face margin compression from destabilized energy input pricing that threatens legacy contract structures.
- Fluorinated gas regulatory tightening:EU F-Gas Regulation alters CVD process economics for thin-film deposition, with alternative nitridation routes unproven at commercial scale.
- Boron nitride substitution:Lower-cost hexagonal boron nitride retains share in industrial heater markets where price sensitivity limits aluminium nitride penetration.
Strategic Opportunities
- India PLI scheme alignment:Domestic semiconductor packaging incentives create qualified supplier entry points for high-purity powder producers meeting BIS certification timelines.
- Radio-frequency module convergence:Precision sintering for 5G base station power amplifiers merges thermal management with dielectric property tuning in single-substrate solutions.
- Direct nitridation process innovation:Non-carbothermal synthesis routes reduce energy intensity and align with China's dual carbon goals for ceramic powder production.
Industry Challenges
- Carbothermal reduction expertise scarcity:Qualified furnace operators and powder metallurgists concentrate in Japanese and German industrial clusters, constraining capacity expansion elsewhere.
- REACH registration timeline compression:ECHA's escalating documentation requirements for high-purity grades extend certification cycles beyond typical customer qualification windows.
- Substrate-thickness uniformity certification:Wafer-level packaging customers demand sub-25 micrometer tolerance validation protocols that smaller sintering operations cannot replicate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium Nitride Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Substrates, Powders, Ceramics, Composites End User: Electronics, Aerospace, Automotive, Industrial Application: Semiconductors, LED Modules, Thermal Management, Coatings Technology: CVD, Sintering, Direct Bonding, Others |
| Companies Covered | Tokuyama Corporation, Kyocera Corporation, Morgan Advanced Materials, CeramTec Group, Höganäs AB, Sumitomo Electric Industries, Toyo Aluminium K.K., Maruwa Co., Ltd., CoorsTek Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium Nitride Market Strategic Shifts
Process innovation in aluminium nitride synthesis and substrate fabrication is compressing thermal conductivity thresholds while regulatory frameworks reshape where production capacity can locate. These shifts are redrawing competitive boundaries between carbothermal and direct nitridation camps.
Direct nitridation of aluminium metal is overtaking carbothermal reduction as the preferred synthesis route for high-purity powder destined for semiconductor substrates. Japanese producers are adopting this method to circumvent energy-intensive carbon-based processes and meet METI-designated critical mineral security targets. The structural consequence is a geographic rebalancing of qualified supply toward captive nitridation capacity in East Asian electronics corridors.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing CVD equipment manufacturers to redesign thin-film deposition chambers for aluminium nitride coating applications. The regulation compresses process economics for legacy CVD lines while accelerating development of plasma-enhanced chemical vapor deposition alternatives. Radio-frequency module fabricators in Germany and France face the steepest compliance cost escalation, driving joint development programs with equipment suppliers.
Automotive tier-one suppliers are consolidating thermal interface material procurement through qualified supplier lists that bypass traditional distributor channels. Sintered aluminium nitride filler specifications for electric vehicle inverters now route directly from powder producers to power module assemblers, eliminating compounder intermediaries. This disintermediation is most visible in South Korean and Chinese electric vehicle supply chains where vertical integration between battery and inverter manufacturers compresses sourcing layers.
Aluminium Nitride Market Segmentation
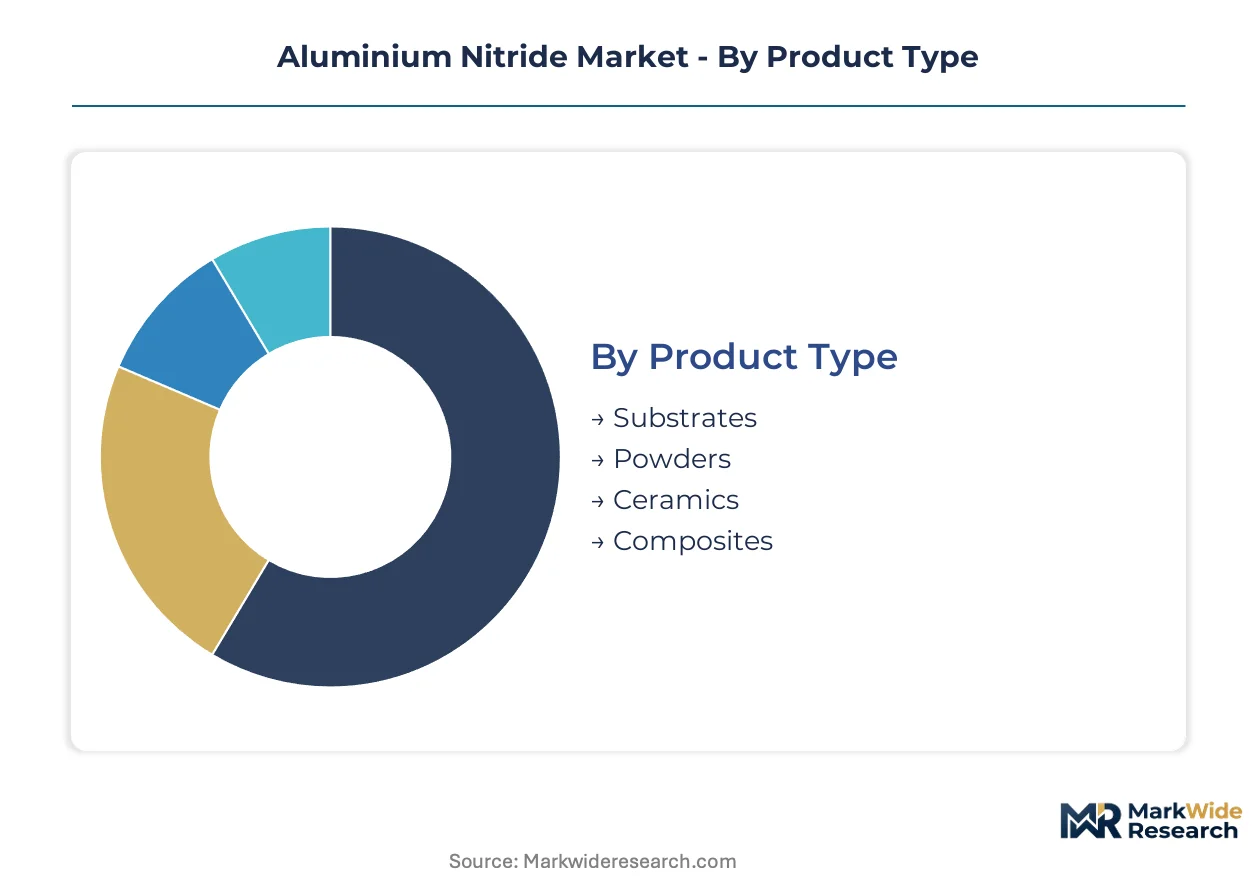
Aluminium nitride's thermal conductivity range from 170 to 285 W/m·K creates distinct value tiers across product categories. Substrate thickness tolerances and powder purity grades determine which segments capture premium pricing versus commoditized volume.
Product Type:
Substrates demand the heaviest capital deployment, requiring precision sintering furnaces and sub-25 micrometer grinding equipment that smaller operators cannot finance.
- Substrates:Hexagonal wurtzite ceramic wafers deliver thermal conductivity exceeding 170 W/m·K for gallium nitide RF device packaging. Taiwan, South Korea, and Japan absorb the largest volumes as chip power densities rise.
- Powders:Carbothermal reduction and direct nitridation grades span thermal interface material fillers to high-purity semiconductor feedstock. Sintered aluminium nitride fillers for electric vehicle inverters are climbing the fastest.
- Ceramics:Industrial heater components and crucibles serve mature markets where price sensitivity limits margin expansion.
- Composites:Polymer-matrix formulations with aluminium nitride dispersion target mid-range thermal management applications.
Substrates absorb the bulk of installed capacity; powders are expanding most quickly.
End User:
Electronics manufacturers command the steepest purity premiums, while automotive procurement consolidates through qualified supplier lists that bypass traditional distributors.
- Electronics:Semiconductor packaging lines in Taiwan, South Korea, and Japan drive substrate specifications exceeding thermal conductivity thresholds of 170 W/m·K. Wafer-level packaging commands premium pricing tied to thickness uniformity.
- Automotive:Electric vehicle inverter manufacturers adopt sintered aluminium nitride fillers for thermal interface materials, displacing legacy boron nitride compounds.
- Aerospace:Satellite thermal management systems utilize high-reliability substrates with radiation-hardened specifications.
- Industrial:Heater markets and metallurgical applications tolerate lower purity grades at compressed price points.
Electronics dominates revenue concentration; automotive is gaining share fastest.
Application:
Semiconductor packaging generates the highest margin per kilogram, while thermal interface materials scale through volume procurement in electric vehicle supply chains.
- Semiconductors:Gallium nitride RF device substrates require sub-25 micrometer thickness uniformity. Radio-frequency module fabricators in Germany and France face compliance cost escalation from EU F-Gas Regulation.
- Thermal Management:Electric vehicle power modules specify sintered aluminium nitride fillers with direct routing from powder producers to assemblers. South Korean and Chinese supply chains show the most visible disintermediation.
- LED Modules:High-brightness lighting applications utilize aluminium nitride substrates for heat dissipation in compact form factors.
- Coatings:Thin-film deposition via CVD serves protective and dielectric layer applications with alternative nitridation routes unproven at commercial scale.
Semiconductors capture the steepest pricing premium; thermal management shows the steepest expansion trajectory.
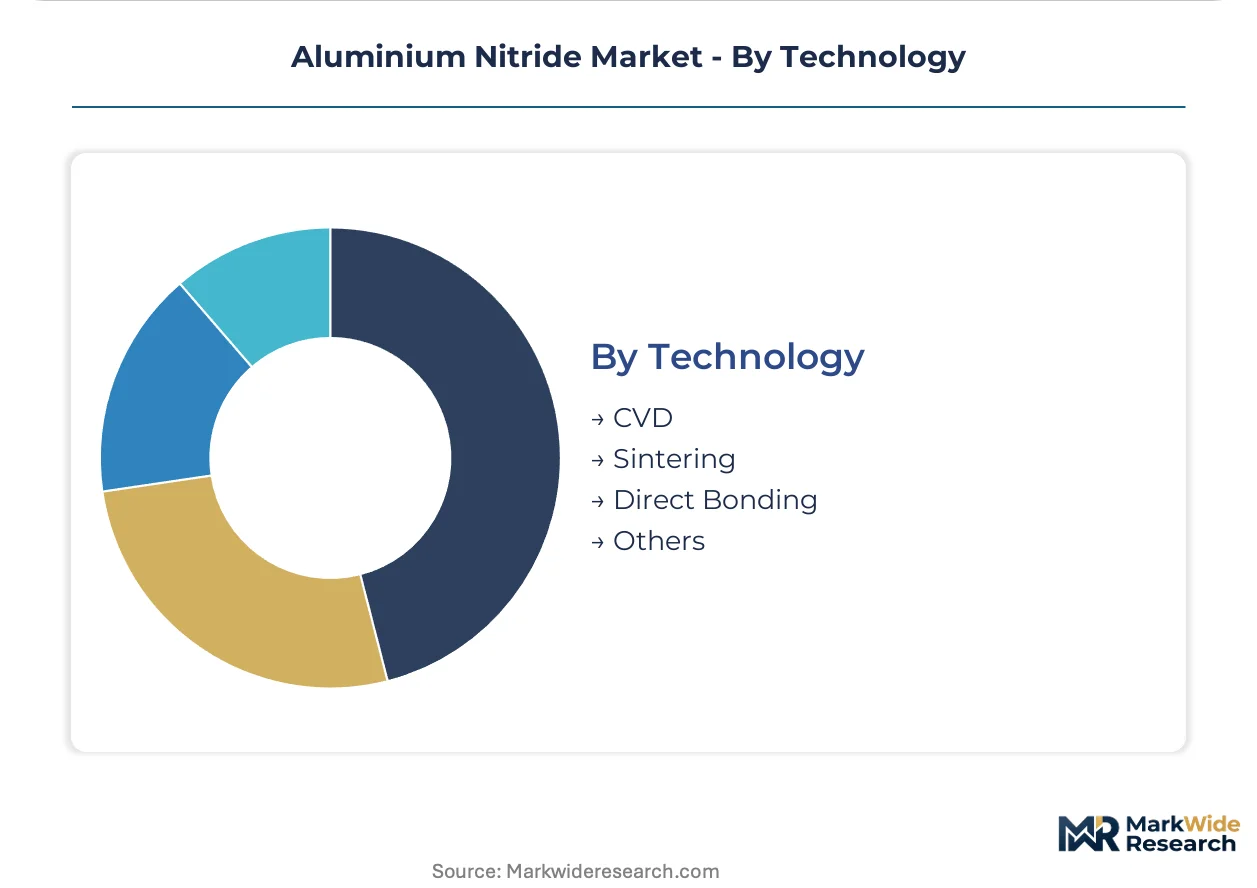
Technology:
Sintering operations concentrate qualified expertise in Japanese and German industrial clusters, constraining capacity expansion elsewhere.
- Sintering:Precision densification of aluminium nitride powder achieves full theoretical density for substrate applications. Kyocera Corporation leverages ceramics heritage to dominate radio-frequency module fabrication.
- CVD:Chemical vapor deposition for thin-film coatings faces process economics compression from EU F-Gas Regulation restrictions on fluorinated greenhouse gases.
- Direct Bonding:Metallization techniques attach aluminium nitride substrates to heat spreaders in power module assemblies.
- Others:Emerging plasma-enhanced chemical vapor deposition alternatives accelerate development in response to regulatory pressure.
Sintering anchors installed capacity; CVD equipment redesigns are accelerating most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor packaging lines in Taiwan, South Korea, and Japan absorb the largest aluminium nitride substrate volumes as gallium nitride power densities rise. Demand concentrates in East Asian electronics manufacturing corridors where substrate specifications now exceed thermal conductivity thresholds of 170 W/m·K. Regional regulatory frameworks and industrial policy are reshaping where qualified supply can locate.
Japan
Domestic substrate output serves METI-designated critical mineral security targets through captive carbothermal reduction capacity. Japan's economic security legislation directs national subsidy programs toward aluminium nitride production as a strategic priority. Industrial clusters in Kanto and Kansai regions concentrate precision sintering expertise for radio-frequency module fabrication.
South Korea
Electric vehicle inverter manufacturers drive sintered aluminium nitride filler demand through direct procurement from powder producers. MFDS-aligned quality frameworks govern thermal interface material specifications for automotive power modules. Seoul Capital Area packaging facilities specify sub-25 micrometer substrate thickness tolerances for gallium nitride RF devices.
China
GB standards enforced by SAMR impose escalating trace-metal limits on powder purity, filtering smaller carbothermal reduction operators from qualified supplier lists. Dual carbon goals tighten energy-use rules for ceramic powder production and favor direct nitridation process innovation. Yangtze River Delta electronics corridors absorb expanding substrate volumes for high-frequency device packaging.
Germany
Radio-frequency module fabricators face compliance cost escalation from EU F-Gas Regulation restrictions on fluorinated greenhouse gases in CVD thin-film deposition. REACH registration timelines extend certification cycles for high-purity powder grades beyond typical customer qualification windows. Bavaria and Baden-Württemberg industrial clusters concentrate plasma-enhanced chemical vapor deposition equipment development.
United States
Automotive tier-one suppliers consolidate thermal interface material procurement through qualified supplier lists that bypass traditional distributor channels. EPA industrial emissions frameworks intersect with state-level clean energy procurement rules for ceramic powder production. Southeast and Southwest manufacturing corridors scale packaging capacity for defense and aerospace thermal management applications.
Aluminium Nitride Market Competitive Environment
Capacity expansion dominates the current landscape as producers respond to East Asian electronics corridor demand. The vendor base stratifies across three tiers: integrated ceramics conglomerates with captive powder supply, specialized substrate fabricators with precision sintering expertise, and regional powder producers serving thermal interface material compounders. Two strategic archetypes define competitive positioning: vertically integrated players controlling carbothermal reduction through substrate finishing, and technology licensors monetizing direct nitridation process patents. Geographic expansion and portfolio diversification represent the dominant competitive moves, with producers establishing qualified supply positions near Taiwan, South Korea, and Japan packaging lines.
Among Japanese industrial conglomerates, Tokuyama Corporation and Kyocera Corporation exemplify the integrated archetype, anchoring substrate output through ceramics heritage and captive synthesis capacity. Morgan Advanced Materials occupies a position among European material specialists competing from British powder plants. These three represent contrasting geographic and structural approaches to qualified supplier status in a market where purity benchmarks and energy-use rules increasingly determine competitive viability.
| Leading Market Players |
|---|
| Tokuyama Corporation |
| Kyocera Corporation |
| Morgan Advanced Materials |
| CeramTec Group |
| Höganäs AB |
| Sumitomo Electric Industries |
| Toyo Aluminium K.K. |
| Maruwa Co., Ltd. |
| CoorsTek Inc. |
| Others |
Value Chain & Pricing Dynamics
Family-owned Japanese ceramics conglomerates anchor supply discipline through captive carbothermal reduction capacity, translating upstream control into pricing power over wafer-level packaging customers in Taiwan and South Korea. Their ownership structure insulates long-term contract negotiations from quarterly margin pressure that destabilizes European competitors facing volatile natural gas input costs.
Pricing Analysis
High-volume substrate contracts trade at compressed margins while precision sintering for sub-25 micrometer gallium nitride RF packaging commands premium pricing. Three-tier pricing structure across premium, standard, and economy levels separates certified semiconductor-grade substrates from industrial heater ceramics and thermal interface material fillers. Pricing pressure stems from REACH registration cost absorption in Europe and SAMR purity compliance investments in China. Automotive power module assemblers exhibit the sharpest price sensitivity, while radio-frequency module fabricators tolerate premium positioning for thickness uniformity validation.
Supply Chain Analysis
Regional distribution centers in Kanto, Seoul Capital Area, and Yangtze River Delta operate hub-and-spoke patterns feeding precision grinding facilities. Supply concentrates in Japan, South Korea, and China for carbothermal reduction and direct nitridation feedstock. The chain draws from aluminium metal ingots, carbon black reductants, and high-purity nitrogen gas inputs. Single-source vulnerability runs through Japanese precision sintering furnace operators whose expertise constrains capacity replication. Distribution runs through qualified supplier lists that bypass traditional compounder channels for electric vehicle thermal interface materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into aluminium nitride powder synthesis represents the decisive competitive lever as substrate fabricators race to secure captive carbothermal reduction or direct nitridation capacity.
For Market Incumbents: Lock in qualified supplier status with Taiwan and South Korean packaging lines through sub-25 micrometer thickness certification investments. Kyocera Corporation's precision sintering heritage demonstrates how ceramics expertise creates switching costs for radio-frequency module customers. Defend margin position by establishing direct nitridation capacity to circumvent European energy cost volatility that threatens Morgan Advanced Materials' British powder plant economics. For New Entrants and Emerging Players: Indian automotive tier-one suppliers present an underserved buyer archetype seeking BIS-certified thermal interface material fillers under PLI scheme alignment. Target electric vehicle inverter manufacturers in the Seoul Capital Area bypassing traditional distributor channels through direct powder producer relationships. Enter via plasma-enhanced chemical vapor deposition equipment partnerships serving German and French radio-frequency fabricators facing EU F-Gas Regulation compliance cost escalation. For Investors and Strategic Acquirers: Distressed-cycle entries favor European carbothermal reduction specialists in Germany and Britain confronting natural gas margin compression. Long-term viability hinges on direct nitridation process licensing portfolios and METI-designated critical mineral subsidy access in Japan. Monitor SAMR enforcement intensity against smaller Chinese operators as a consolidation trigger signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Synthesis | Captive carbothermal reduction capacity insulates Tokuyama Corporation from European energy cost volatility. |
| Direct Nitridation Process Licensing | Patent monetization accelerates as Chinese producers seek lower-carbon synthesis routes under dual carbon goals. |
| Sub-25 Micrometer Certification Investment | Thickness uniformity validation protocols lock in wafer-level packaging customers for gallium nitride RF devices. |
| India PLI Scheme Alignment | BIS certification timelines create qualified supplier entry points for domestic semiconductor packaging incentives. |
| Plasma-Enhanced CVD Equipment Partnership | Joint development programs address EU F-Gas Regulation restrictions on fluorinated greenhouse gases in Germany. |
Study Parameters
Document review covered trade customs data, SEC 10-K filings from ceramics conglomerates, and SAMR regulatory bulletins, complemented by interviews with precision sintering furnace operators, automotive power module procurement leads, and thermal interface material compounders. Primary fieldwork with substrate fabricators in Kanto and Kansai industrial clusters validated powder purity grade specifications. Secondary sources included METI subsidy program disclosures, ECHA REACH registration databases, and MFDS-aligned quality frameworks. Bottom-up substrate volume estimates triangulated against top-down electronics manufacturing corridor absorption metrics.
Segment-level outputs across product type, end user, application, and technology dimensions informed the analytical framework over the projection horizon. CAGRs derived from regression against gallium nitride RF device shipment trajectories and electric vehicle inverter adoption curves. Modeled inputs incorporated carbothermal reduction energy intensity differentials and direct nitridation yield improvement curves without specifying timeline endpoints.
Revisions become necessary when SAMR escalates trace-metal limits beyond current carbothermal reduction capability, EU F-Gas Regulation tightens fluorinated gas phase-out schedules, or Japanese METI redirects critical mineral subsidies. Forecasts reflect documented assumptions around qualified supplier list consolidation and purity benchmark trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramic Additives Market
Ceramics
Automotive Ceramics Market
Ceramics
Asia-Pacific Activated Alumina Market
Ceramics
Zirconia Ceramics Market
Ceramics
Relaxor Ferroelectric Ceramics Market
Ceramics
United States Ceramics Tableware Market
Ceramics
GCC Ceramic Tiles and Sanitary Ware Market
Ceramics
Graphite Crucibles Market
Ceramics
Glazed Bricks Market
Ceramics
Ceramic Frit Glass Market
Ceramics
Zirconia Ceramic Balls Market
Ceramics
West Africa Ceramic Tiles Market
Ceramics
Advanced Sintering Technologies Market
Ceramics
Zirconium Dioxide Market
Ceramics
Global Ceramic Foams Market
Ceramics
Potassium Silicate Market