
 Dielectric Ceramics Market | 2026-2036
Dielectric Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Dielectric Ceramics Market Analytics
Telecommunications infrastructure providers are collapsing their traditional procurement thresholds for high-capacitance dielectric ceramics as 5G densification accelerates. Kyocera Corporation anchors its position through captive sapphire and ceramic substrate production across Japanese and Southeast Asian facilities. Murata Manufacturing dominates MLCC supply for smartphone OEMs with proprietary thin-layer dielectric technology. Prosperity Dielectrics Co., Ltd specializes in mid-voltage ceramic capacitors for automotive module suppliers seeking AEC-Q200 qualification paths.
Dielectric ceramics are polycrystalline inorganic materials engineered to store and release electrical energy through polarization mechanisms, with formulations typically based on barium titanate, strontium titanate, or lead zirconate titanate processed via tape casting, dry pressing, or thin-film deposition to achieve precise permittivity and loss tangent specifications for resonant and capacitive applications. Ferroelectric ceramics occupy the largest volume share due to their superior permittivity in multilayer ceramic capacitors, while thin film ceramics represent the fastest-expanding technology segment as semiconductor packaging demands sub-micron dielectric layers for integrated passives. Composite ceramics are gaining traction in automotive radar modules where thermal stability and dielectric constant tunability justify premium positioning over conventional formulations.
The EPA regulates hazardous material content in dielectric formulations under TSCA, while REACH and RoHS in Europe restrict lead-bearing PZT compositions and mandate full material disclosure for electronics supply chain access. Japan's METI promotes domestic ceramic material independence through critical mineral stockpiling directives that shield capacitor manufacturers from rare earth supply shocks. Stakeholders must monitor evolving halogen-free dielectric mandates and qualification timelines for next-generation wide-bandgap power electronics packaging.
Market Dynamics
5G base station densification is compressing procurement cycles for high-capacitance dielectric ceramics, forcing telecommunications infrastructure providers to secure multiyear supply commitments ahead of traditional qualification timelines.
Growth Catalysts
- Telecommunications infrastructure buildout:5G network densification across China and the United States is accelerating consumption of multilayer ceramic capacitors for base station power amplifiers and filtering modules.
- REACH material purity mandates:European RoHS and REACH frameworks are phasing out lead-bearing PZT formulations, creating replacement demand for barium titanate-based dielectrics in automotive and industrial applications.
- Electric vehicle module proliferation:Onboard chargers and DC-DC converters in battery electric vehicles require AEC-Q200 qualified ceramic capacitors with extended temperature ratings.
Market Restraints
- Rare earth supply concentration:Lanthanum and neodymium dependencies for high-permittivity formulations concentrate in Chinese processing facilities, exposing capacitor manufacturers to export quota volatility.
- Halogen-free formulation costs:Bromine and chlorine-free dielectric development requires modified sintering profiles that elevate energy consumption per batch.
- Piezoelectric ceramic substitution:Polymer-based film capacitors are displacing ceramic alternatives in low-voltage consumer electronics where volumetric efficiency matters less than cost.
Strategic Opportunities
- Wide-bandgap power electronics packaging:Silicon carbide and gallium nitride inverter modules require thin-film dielectric ceramics with sub-micron layer precision for integrated passive networks.
- India electronics manufacturing incentives:The country's PLI scheme for semiconductor and component production is attracting ceramic substrate investments for domestic smartphone and automotive supply chains.
- Automotive radar module composites:Ceramic-polymer hybrid formulations with tunable dielectric constants address thermal stability requirements in 77 GHz advanced driver-assistance systems.
Industry Challenges
- Thin-layer deposition expertise scarcity:Tape casting and chemical solution deposition of sub-micron dielectric films requires specialized ceramic engineering talent concentrated in Japanese and Korean research institutes.
- AEC-Q200 qualification timelines:Automotive module suppliers face 18-24 month validation cycles for new dielectric formulations, compressing product development windows against rapid technology turnover.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dielectric Ceramics Market |
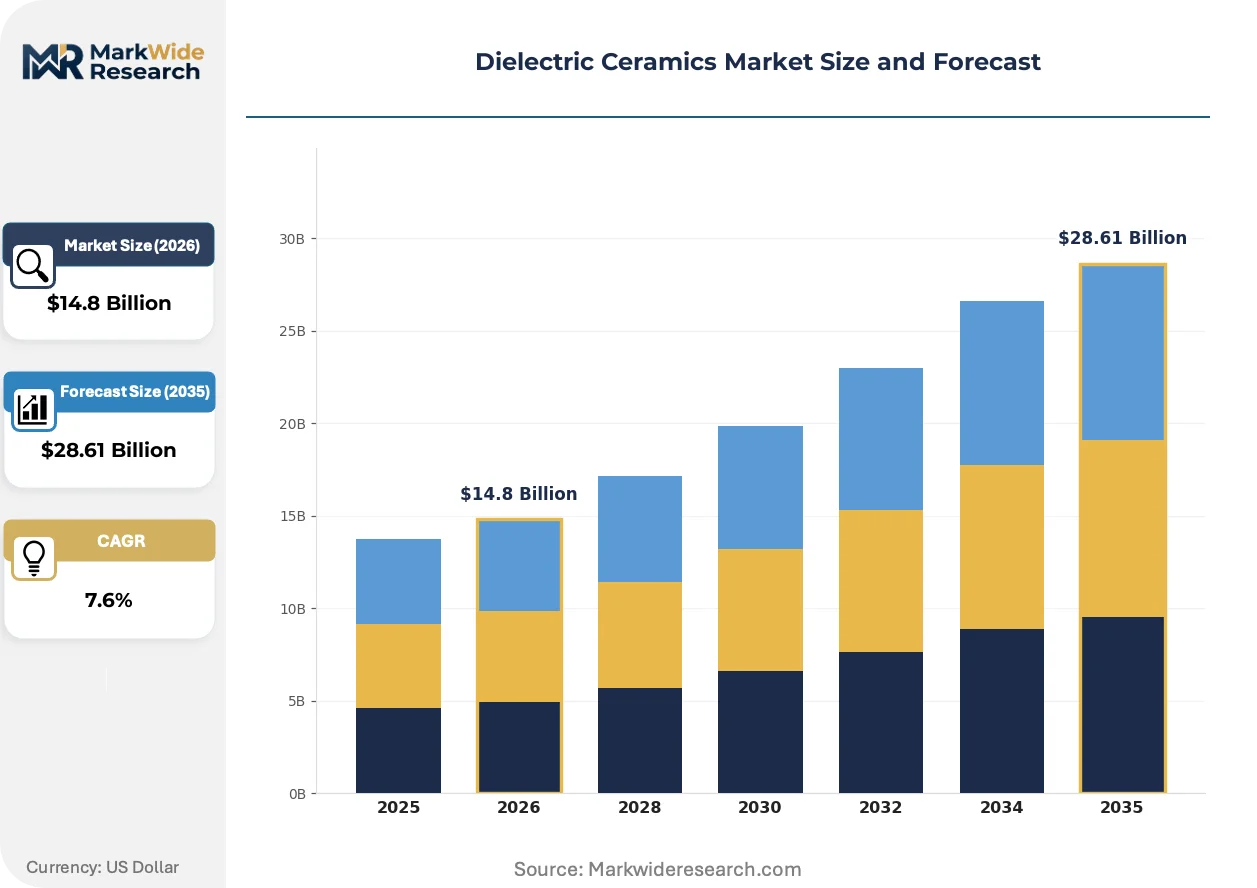
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $28.61 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ferroelectric Ceramics, Non-Ferroelectric Ceramics, Composite Ceramics, Thin Film Ceramics Application: Telecommunications, Consumer Electronics, Automotive Electronics, Medical Devices End User: Manufacturers, OEMs, Research Institutions, Industrial Users Technology: PZT, Barium Titanate, Strontium Titanate, Others |
| Companies Covered | Gavish, Advanced Technical Ceramics, Kyocera Corporation, Maruwa Co. Ltd, Murata Manufacturing, Rubicon Technology, San Jose Delta Associates, Prosperity Dielectrics Co., Ltd, Monocrystal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dielectric Ceramics Market Evolving Landscape
Dielectric ceramic manufacturing is splitting between commodity multilayer capacitor production and precision thin-film deposition for advanced packaging, with equipment and formulation know-how diverging accordingly.
Thin-film dielectric deposition is bifurcating the supplier base into high-volume MLCC specialists and precision semiconductor packaging providers. Semiconductor foundries in Taiwan and South Korea are integrating sub-micron barium strontium titanate layers directly onto interposers for system-in-package modules. This capability compression is marginalizing traditional ceramic component vendors from the highest-value dielectric applications.
Japan's METI critical mineral stockpiling directives are reshaping raw material procurement strategies for domestic capacitor manufacturers. The framework mandates six-month inventory buffers for rare earth oxides used in high-permittivity formulations, elevating working capital requirements. Kyushu-based ceramic producers are responding by qualifying Australian and Canadian alternative suppliers for tantalum and niobium precursors.
Smartphone OEMs are consolidating capacitor suppliers from fragmented multivendor arrangements toward single-source qualification for flagship device platforms. Procurement teams at major electronics assemblers in Shenzhen and Hanoi now require dielectric vendors to co-locate failure analysis laboratories within 500 kilometers of final assembly facilities. This geographic compression favors Chinese and Southeast Asian ceramic substrate producers over distant Japanese competitors.
Dielectric Ceramics Market Segmentation
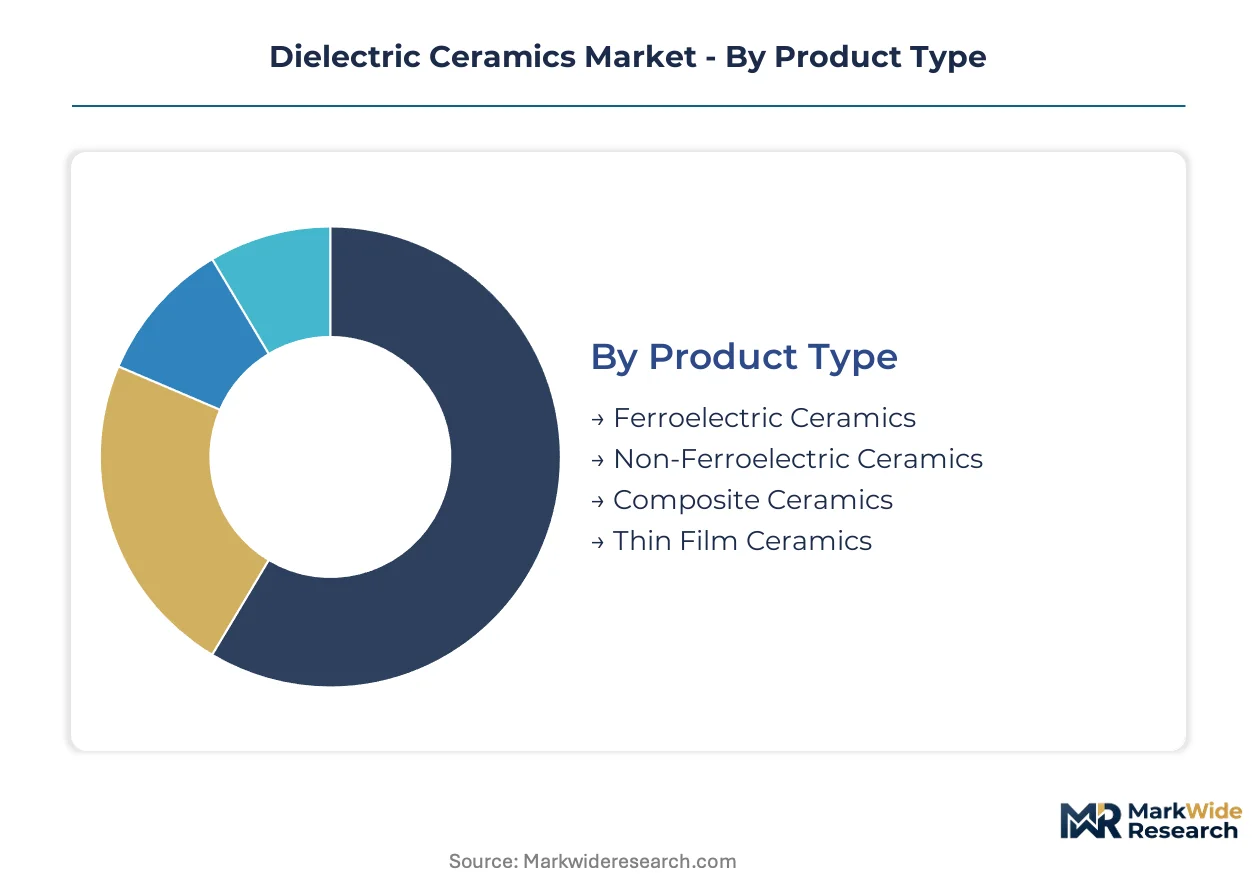
Dielectric ceramics serve divergent performance requirements across frequency ranges, voltage tolerances, and thermal envelopes. Segmentation reveals where polymer film capacitors and aluminum electrolytic alternatives exert substitution pressure versus where ceramic formulations maintain irreplaceable advantages.
Product Type:
Substitution pressure intensifies against commodity formulations while precision thin-film and composite variants defend ceramic positioning against polymer alternatives.
- Ferroelectric Ceramics:Barium titanate-based polycrystalline formulations deliver permittivity values exceeding 10,000 for multilayer ceramic capacitor stacks. Smartphone OEM procurement teams in Shenzhen specify these for decoupling circuits where volumetric efficiency dominates cost sensitivity.
- Thin Film Ceramics:Sub-micron chemical solution deposition achieves nanoscale thickness control for integrated passive networks. Taiwan semiconductor foundries consume these for system-in-package interposers serving gallium nitride power modules.
- Non-Ferroelectric Ceramics:Linear dielectric response suits high-frequency resonator applications in 5G base station filtering modules.
- Composite Ceramics:Ceramic-polymer hybrid matrices tune dielectric constant across temperature ranges for automotive radar substrates.
Ferroelectric ceramics retain volume leadership; thin film ceramics hold the steepest expansion curve.
Application:
Cost tolerance varies dramatically across end-use contexts, with automotive and medical segments absorbing premium formulations that consumer electronics reject.
- Telecommunications:5G base station power amplifiers and massive MIMO arrays require Class II dielectrics with X7R temperature characteristics. Chinese infrastructure deployment timelines compress procurement cycles for high-capacitance MLCCs.
- Automotive Electronics:AEC-Q200 qualification mandates govern onboard charger DC-link capacitors and DC-DC converter filtering. Extended temperature ratings to 150°C exclude most polymer alternatives from under-hood placement.
- Consumer Electronics:Laptop and tablet motherboard designers trade capacitance density for cost in non-critical decoupling positions.
- Medical Devices:Implantable defibrillator and pacemaker manufacturers specify medical-grade dielectrics with biocompatibility documentation and lot traceability.
Telecommunications commands the largest absolute volume; automotive electronics climbs fastest as electrification penetrates vehicle platforms.
End User:
Procurement sophistication separates vertically integrated OEMs from fragmented industrial purchasers.
- OEMs:Apple, Samsung, and Tesla capacitor qualification teams impose co-located failure analysis requirements within 500 kilometers of final assembly. Geographic compression favors Southeast Asian ceramic substrate producers.
- Manufacturers:Contract electronics assemblers in Vietnam and Mexico manage multivendor MLCC portfolios with quarterly price renegotiation.
- Research Institutions:University and national laboratory materials science departments prototype next-generation relaxor ferroelectrics and lead-free formulations.
- Industrial Users:Motor drive and welding equipment producers specify standard-grade ceramics with 10-year availability guarantees.
OEMs dominate premium segment procurement; manufacturers handle the highest transaction velocity.
Technology:
Regulatory phase-outs and raw material dependencies differentiate formulation trajectories.
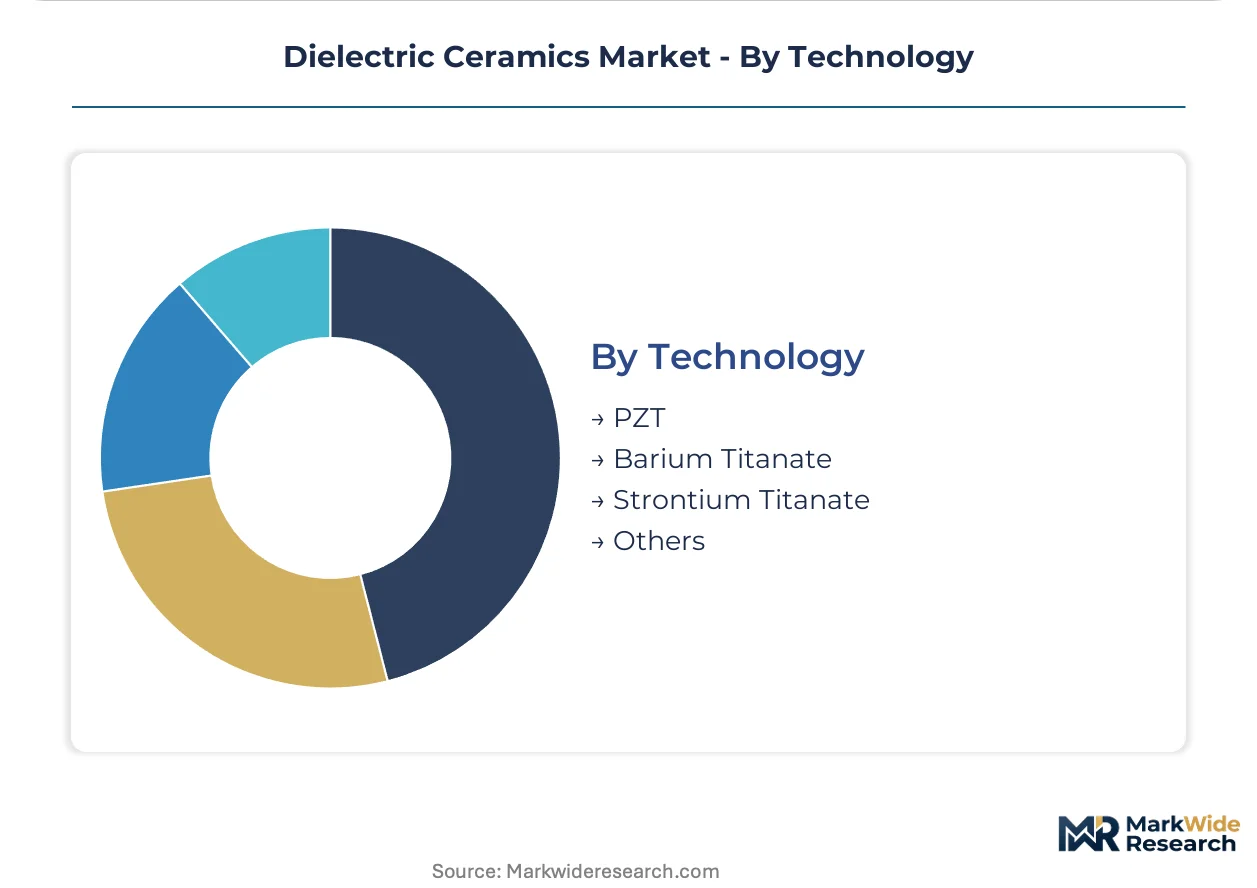
- Barium Titanate:Perovskite-structured ceramic achieves room-temperature permittivity above 2,000 with low dielectric loss. REACH and RoHS compliance positions this as the primary lead-free alternative for European automotive module suppliers.
- PZT:Lead zirconate titanate delivers superior piezoelectric coupling coefficients for ultrasonic transducer and actuator applications. ECHA restriction proposals threaten medical imaging equipment supply chains dependent on this formulation.
- Strontium Titanate:Quantum paraelectric behavior enables temperature-stable capacitance for cryogenic electronics and precision measurement instrumentation.
- Others:Calcium copper titanate and bismuth-based relaxors address niche high-permittivity requirements.
Barium titanate holds installed base dominance; strontium titanate gains fastest in specialized low-temperature applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity dielectric formulations concentrate in East Asian ceramic substrate corridors, with Japanese and South Korean producers commanding thin-layer deposition expertise. Chinese domestic capacity is scaling rapidly for multilayer ceramic capacitor supply chains. European REACH compliance mandates are reshaping formulation portfolios for automotive module suppliers.
China
Domestic ceramic substrate production is scaling for consumer electronics and electric vehicle supply chains. MIIT promotes critical mineral independence through stockpiling directives for rare earth oxides. Shenzhen capacitor procurement teams now require co-located failure analysis laboratories within 500 kilometers of final assembly facilities.
Japan
METI mandates six-month inventory buffers for lanthanum and neodymium precursors used in high-permittivity formulations. Kyushu-based producers are qualifying Australian and Canadian alternative suppliers for tantalum and niobium. Tokyo and Osaka anchor thin-film deposition research for sub-micron dielectric layers.
United States
Telecommunications infrastructure providers are compressing procurement cycles for 5G base station densification. EPA regulates hazardous material content under TSCA for dielectric formulations. Texas and Arizona semiconductor packaging corridors consume precision thin-film ceramics for gallium nitride power modules.
Germany
Automotive module suppliers face ECHA restriction proposals threatening lead-bearing PZT formulations in medical imaging equipment. REACH and RoHS frameworks mandate full material disclosure for electronics supply chain access. Bavaria hosts qualification laboratories for AEC-Q200 ceramic capacitor validation.
South Korea
Taiwan semiconductor foundries integrate sub-micron barium strontium titanate layers onto interposers for system-in-package modules. Seoul Capital Area producers specialize in thin-layer chemical solution deposition. Busan-Ulsan ceramic clusters supply smartphone OEMs with high-capacitance MLCC stacks.
Dielectric Ceramics Market Competitive Landscape
Concentration sits with vertically integrated Japanese conglomerates possessing captive sapphire and ceramic substrate production across Southeast Asian facilities. Tiered competition separates high-volume MLCC specialists from precision thin-film deposition providers for semiconductor packaging. Strategic archetypes include raw material-integrated formulators, thin-layer technology licensors, and automotive-qualified specialists. Dominant competitive moves encompass geographic co-location with OEM assembly corridors and backward integration into rare earth precursor supply.
Among Japanese diversified ceramics producers, Kyocera Corporation and Murata Manufacturing exemplify vertically integrated formulators with in-house substrate production. Prosperity Dielectrics Co., Ltd occupies a position within the automotive-qualified specialist tier, representing mid-voltage ceramic capacitor capabilities for AEC-Q200 qualification paths. These three anchors illustrate how geographic proximity to Shenzhen and Hanoi assembly corridors now determines procurement access for flagship smartphone platforms.
| Leading Market Players |
|---|
| Gavish |
| Advanced Technical Ceramics |
| Kyocera Corporation |
| Maruwa Co. Ltd |
| Murata Manufacturing |
| Rubicon Technology |
| San Jose Delta Associates |
| Prosperity Dielectrics Co., Ltd |
| Monocrystal |
| Others |
Value Network & Pricing Analysis
Six-month inventory buffers mandated by Japan's METI compress working capital cycles while amplifying pricing power for rare earth oxide holders. This lead-time regime concentrates procurement leverage among vertically integrated Japanese and South Korean ceramic substrate producers.
Pricing Analysis
REACH and RoHS dictate the pricing tier structure across European automotive module supply chains, separating AEC-Q200 qualified formulations from standard industrial grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, volume scale, and geographic proximity to Shenzhen assembly corridors. Cost compression in commodity MLCC tiers intensifies because Chinese domestic producers scale barium titanate capacity. Contract electronics assemblers in Vietnam exhibit highest price sensitivity, while medical device OEMs absorb premium positioning for biocompatibility documentation.
Supply Chain Analysis
Japan and South Korea anchor thin-film dielectric deposition expertise, while China scales multilayer ceramic capacitor production for consumer electronics and electric vehicle supply chains. Formulations draw from lanthanum, neodymium, and tantalum precursors concentrated in Chinese processing facilities. Single-source vulnerability in rare earth oxide supply exposes capacitor manufacturers to export quota volatility. Distribution runs through vertically integrated Japanese conglomerates with captive substrate production across Southeast Asian facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dielectric ceramics function as a platform technology where 5G densification and wide-bandgap power electronics interoperability create winner-take-most dynamics. Ecosystem lock-in through co-located failure analysis laboratories now determines procurement access.
For Market Incumbents: Compound geographic proximity advantages by qualifying Australian and Canadian tantalum suppliers under METI stockpiling directives. Deepen in-house production of sub-micron deposition equipment to counter thin-layer expertise scarcity at Japanese and Korean research institutes. Defend against Chinese domestic producers scaling barium titanate capacity through AEC-Q200 certification investment in automotive modules.
For New Entrants and Emerging Players: Anchor in India's PLI scheme for semiconductor and component production, where ceramic substrate investments lag smartphone and automotive demand. Target automotive radar module composites as the most penetrable white-space, where thermal stability requirements justify premium positioning over conventional formulations. Pursue licensing arrangements with Taiwan semiconductor foundries for system-in-package interposer integration.
For Investors and Strategic Acquirers: Long-term, this sits as a critical materials infrastructure play because rare earth oxide dependencies and thin-layer deposition expertise scarcity create durable moats. Acquisition target archetype: mid-voltage automotive-qualified specialists with established AEC-Q200 validation timelines. Monitor halogen-free dielectric mandate adoption as the inflection signal for formulation replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Precursors | METI stockpiling directives shield Japanese producers from Chinese export quota volatility. |
| Thin-Film Deposition Capability Buildout | Taiwan foundries consume sub-micron layers for gallium nitride power module interposers. |
| AEC-Q200 Certification Investment | Automotive module suppliers face 18-24 month validation cycles compressing development windows. |
| Geographic Co-Location with OEM Assembly | Shenzhen procurement teams require failure analysis laboratories within 500 kilometers. |
| Halogen-Free Formulation Development | REACH and RoHS phase-outs create replacement demand for modified sintering profiles. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, customs and trade data, and EPA regulatory filings. Primary interviews engaged capacitor procurement managers at telecommunications infrastructure providers, ceramic engineering directors at substrate producers, and regulatory affairs leads navigating REACH compliance. Secondary validation drew from METI critical mineral directives, ECHA restriction proposals, and MIIT stockpiling frameworks. Bottom-up demand modeling triangulated against top-down supply capacity assessments.
Segmentation dimensions modeled include product type, application, end user, and technology across the analysis window. Ferroelectric, thin-film, non-ferroelectric, and composite ceramic categories were cross-referenced against telecommunications, automotive electronics, consumer electronics, and medical device demand. CAGRs derived from production capacity expansion announcements, rare earth oxide inventory cycles, and qualification timeline compression observed in AEC-Q200 pathways. Forecast inputs incorporated 5G base station deployment trajectories and wide-bandgap power electronics packaging adoption.
Material uncertainties — rare earth export quota volatility, ECHA restriction timeline acceleration, halogen-free sintering cost escalation — sit outside the modeled envelope. Forecasts reflect assumptions about continued MIIT and METI stockpiling enforcement and sustained semiconductor foundry integration of dielectric layers. Recalibration cycles align with material shifts in wide-bandgap inverter module procurement and next-generation relaxor ferroelectric commercialization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Global Ceramic Coating Market
Ceramics
Magnesia Carbon Bricks Market
Ceramics
Asia-Pacific Ceramic Coatings Market
Ceramics
Medical Ceramics Market
Ceramics
Ceramic Armor Materials Market
Ceramics
Strontium Carbonate Market
Ceramics
Potassium Feldspar Market
Ceramics
Aragonite Market
Ceramics
Philippines Ceramic Tiles Market
Ceramics
Nano Ceramic Coatings Market
Ceramics
Earthenware Market
Ceramics
Zeolite 4A Market
Ceramics
Ceramic Lining Market
Ceramics
Ceramic Pigments Market
Ceramics
ME K-Feldspar Market
Ceramics
Tetra-N-Butyl Titanate Market