
 Titanates Market | 2026-2036
Titanates Market Size, Share, and Industry Trends Forecast 2026-2036
Titanates Market Outlook
Aftermarket service revenue for titanate powder processing is fragmenting across regional toll manufacturers and captive refiners. Sakai Chemical Industry leverages its vertical integration from ore to electronic-grade powder, sustaining margin control through in-house milling capabilities. Mitsubishi Gas Chemical competes on high-purity strontium titanate for medical imaging substrates, differentiating through pharmaceutical-grade certification pathways.
Titanates are inorganic compounds containing titanium and oxygen in a perovskite or related crystal structure, typically synthesized via solid-state calcination of metal oxides at temperatures exceeding 1,000°C to achieve controlled dielectric constants and piezoelectric response. Barium titanate dominates electronics applications as the foundational material for multilayer ceramic capacitors, while strontium titanate serves emerging quantum computing substrate markets where ultra-low loss tangents matter. Powder form commands the highest value share in capacitor manufacturing, whereas bulk titanates remain mature in structural ceramics with thinner margin profiles.
REACH in Europe and China's GB standards restrict heavy-metal impurities in electronic-grade titanates, forcing producers to upgrade calcination and leaching protocols. Japan's METI oversees export licensing of advanced ceramic materials, shaping market access for non-domestic capacitor manufacturers. Stakeholders must monitor regulatory divergence between Asian purity standards and European chemical registration requirements when siting new production capacity.
Market Dynamics
Capacitor-grade barium titanate procurement is consolidating around vertically integrated Japanese and South Korean suppliers, compressing margins for independent toll processors while elevating purity certification as the primary competitive differentiator.
Growth Catalysts
- MLCC miniaturization protocols:Smartphone and automotive electronics manufacturers require sub-micron titanate powders with tighter particle size distributions, pulling investment toward advanced milling and classification equipment.
- China's dual carbon goals:Energy-intensive calcination operations face carbon intensity caps, accelerating adoption of electric kiln retrofits and waste-heat recovery systems among domestic producers.
- South Korea's K-Semiconductor Belt:Government-backed clustering near Pyeongtaek and Yongin is concentrating demand for pharmaceutical-grade strontium titanate substrates among domestic medical imaging OEMs.
Market Restraints
- Rutile ore supply concentration:Over seventy percent of titanium feedstock for electronic-grade titanates originates from Australian and South African mineral sands operations, exposing processors to shipping cost volatility and geopolitical disruption.
- REACH substance registration thresholds:ECHA's tonnage-based compliance costs disproportionately burden small and mid-cap European toll refiners, forcing consolidation or exit from electronic ceramics supply chains.
- Aluminum nitride substitution:Thermal management applications in high-frequency power electronics are partially migrating to aluminum nitride substrates, capping titanate volume growth in RF device packaging.
Strategic Opportunities
- Quantum computing substrate qualification:Strontium titanate's ultra-low dielectric loss at cryogenic temperatures positions it for wafer-level integration in superconducting qubit architectures, with early procurement from IBM and Google research divisions.
- India's PLI scheme for electronic components:Domestic manufacturing incentives are attracting joint venture proposals for capacitor-grade powder plants in Gujarat and Tamil Nadu, targeting import substitution for consumer electronics assembly.
- Solid-state battery electrolyte convergence:Lithium lanthanum titanate garnets are emerging as promising ceramic electrolyte candidates, creating technical overlap between traditional capacitor powder capabilities and next-generation battery material processing.
Industry Challenges
- Cryogenic characterization expertise:Qualifying strontium titanate for quantum applications requires specialized dilution refrigerator testing infrastructure that few commercial labs outside Japan currently maintain.
- Cross-border export licensing friction:Japan's METI advanced materials controls create documentation delays for non-domestic capacitor manufacturers seeking pharmaceutical-grade substrate shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Titanates Market |
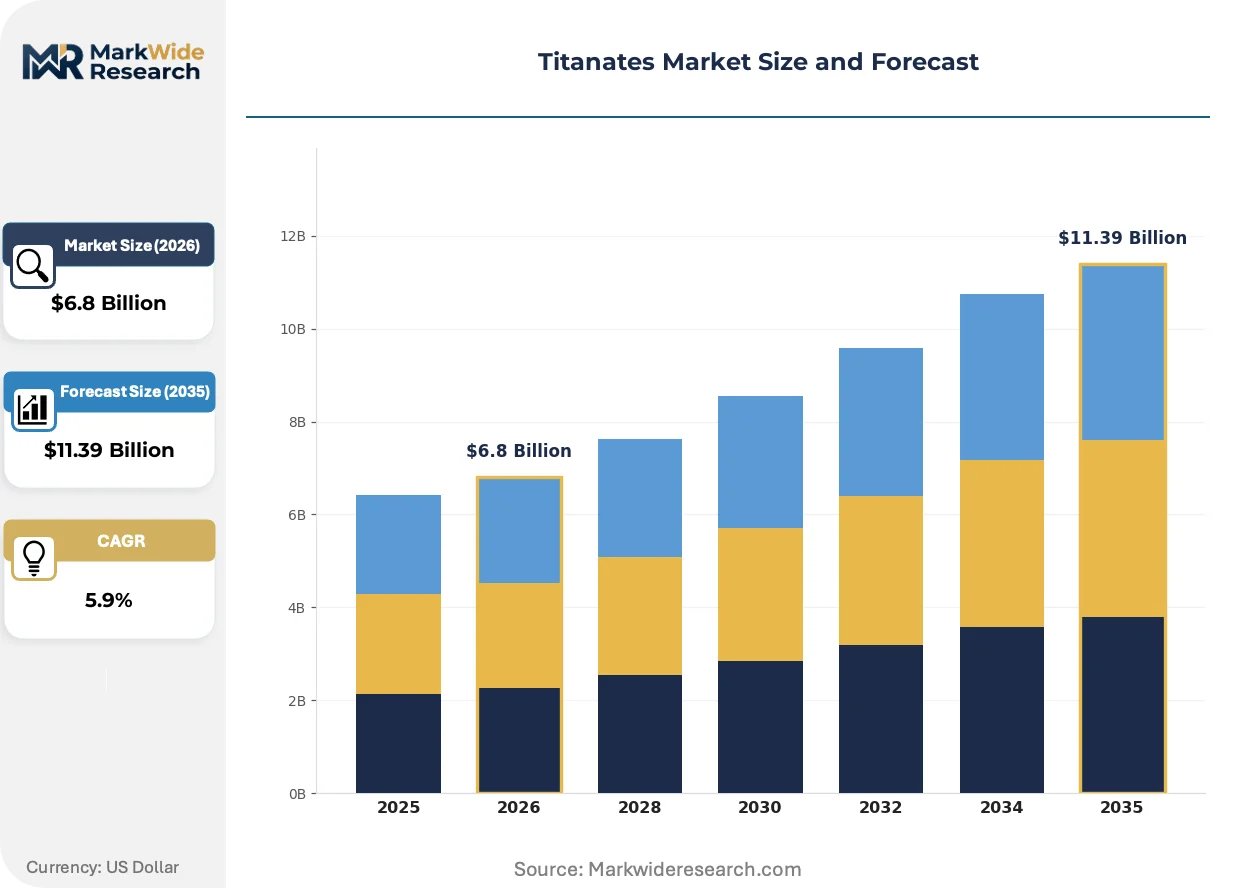
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Titanate, Barium Titanate, Strontium Titanate, Calcium Titanate Application: Electronics, Ceramics, Medical Devices, Energy Storage End User: Telecommunications, Aerospace, Consumer Electronics, Automotive Form: Powder, Granule, Coating, Bulk |
| Companies Covered | Kenrich Petrochemicals, Dorf Ketal Chemicals, Mitsubishi Gas Chemical, Nippon Chemical Industrial, Sakai Chemical Industry, AB Enterprises, Chem Pharma, Akaiyo Chem Tech, Huangshan KBR New Material Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Titanates Market Strategic Shifts
Hydrothermal synthesis routes are displacing conventional solid-state calcination for sub-100 nanometer powder production, altering capital intensity benchmarks and regional competitive positioning in electronic-grade titanate supply chains.
Solvothermal processing is collapsing the particle size distribution variance that previously required multi-stage ball milling and air classification. Japanese capacitor manufacturers are qualifying hydrothermal barium titanate for 0201 and smaller MLCC formats, compressing the process step count from ore to sinter-ready powder by approximately forty percent while tightening dielectric constant batch consistency.
REACH Annex XIV authorization requirements for titanium dioxide are extending downstream to titanate derivatives, forcing European processors to document substance safety across the full manufacturing chain. Specialty chemical distributors are absorbing compliance documentation costs, passing through premiums to medical imaging substrate buyers who lack direct ECHA registration capabilities.
Direct mill-to-OEM contracting is displacing multi-tier distribution for high-volume capacitor-grade powder. South Korean semiconductor material divisions are establishing annual volume commitments with Sakai Chemical and Nippon Chemical Industrial, bypassing traditional trading houses that previously managed inventory and logistics. This concentration is most visible in Seoul's Pangyo and Hwaseong industrial corridors, where MLCC manufacturers now negotiate powder specifications directly with calcination operators.
Titanates Market Segmentation
Titanate procurement cycles vary dramatically by segment—capacitor-grade powders turn monthly while bulk structural ceramics sit in inventory for quarters. Understanding these velocity differentials shapes working capital deployment and pricing power across the value chain.
Product Type:
Cycle times compress from ore to powder based on end-use purity requirements, with electronic grades demanding rapid batch qualification while industrial titanates tolerate longer certification windows.
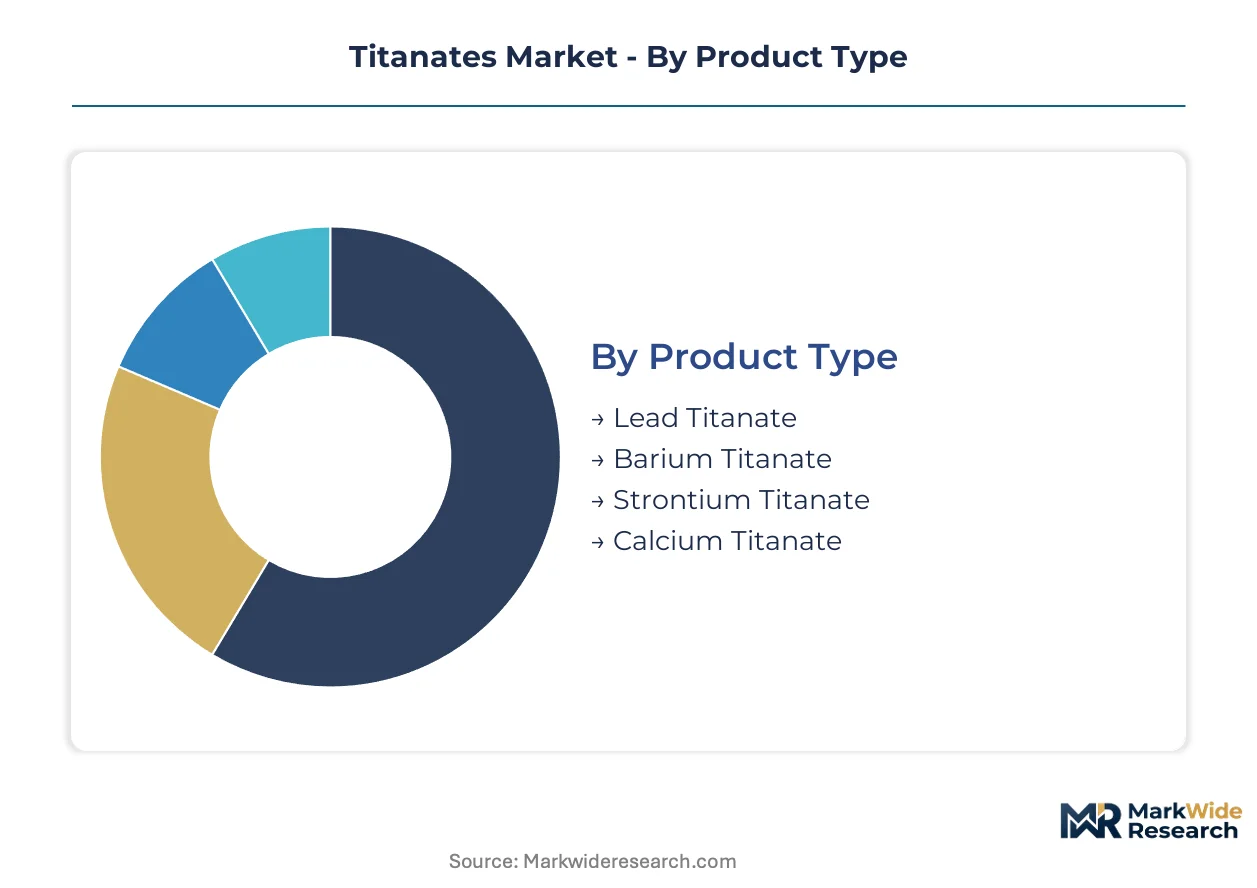
- Barium Titanate:Perovskite-structured dielectric ceramic synthesized via solid-state calcination of barium carbonate and titanium dioxide above 1,000°C. Japan's capacitor supply chain—centered on Osaka and Tokyo industrial corridors—absorbs the majority of electronic-grade output, driven by MLCC miniaturization protocols requiring sub-micron particle distributions.
- Strontium Titanate:Quantum-grade substrate material with ultra-low dielectric loss tangent at cryogenic temperatures. South Korea's semiconductor belt near Pyeongtaek concentrates emerging demand from medical imaging OEMs seeking pharmaceutical-grade certification for CT detector substrates.
- Lead Titanate:High-curie-point piezoelectric compound used in ultrasonic transducer arrays and high-temperature sensors.
- Calcium Titanate:Refractory ceramic employed in steelmaking slag conditioning and specialized optical coatings.
Barium titanate dominates installed base. Strontium titanate is where expansion concentrates.
Application:
Margin profiles diverge sharply across applications—electronics commands certification premiums while ceramics competes on throughput efficiency.
- Electronics:Multilayer ceramic capacitor dielectrics, piezoelectric actuators, and varistor formulations requiring precise dielectric constant control. South Korean smartphone manufacturers and Japanese automotive Tier 1s drive specification tightening for 0201 and smaller MLCC formats.
- Energy Storage:Lithium lanthanum titanate garnet solid-state electrolytes for next-generation batteries. Research procurement from national laboratories in Japan and Germany is validating ceramic processing protocols for lithium-metal cell architectures.
- Ceramics:Structural refractories and thermal barrier coatings for industrial furnace linings.
- Medical Devices:Imaging substrate applications requiring biocompatibility documentation.
Electronics generates the highest revenue per kilogram. Energy storage is climbing the fastest as battery developers scale pilot lines.
End User:
Customer concentration patterns vary—telecommunications demands just-in-time delivery while aerospace tolerates long-lead scheduling.
- Consumer Electronics:Smartphone, tablet, and wearable manufacturers sourcing capacitor-grade powders through direct mill-to-OEM contracts. Seoul's Pangyo corridor and Shenzhen assembly hubs concentrate procurement volume for high-K dielectric formulations.
- Automotive:EV power electronics and ADAS sensor modules requiring AEC-Q200 qualified components. German and Japanese automotive Tier 1s are qualifying new titanate suppliers for 800V inverter capacitor banks.
- Telecommunications:Base station and optical network infrastructure deploying high-frequency ceramic components.
- Aerospace:Satellite and avionics applications demanding radiation-hardened dielectric materials.
Consumer electronics anchors current volume. Automotive is where specification premiums are expanding.
Form:
Processing intensity and logistics economics separate powder from bulk—fine powders require contamination-controlled handling while bulk shipments move via standard industrial freight.
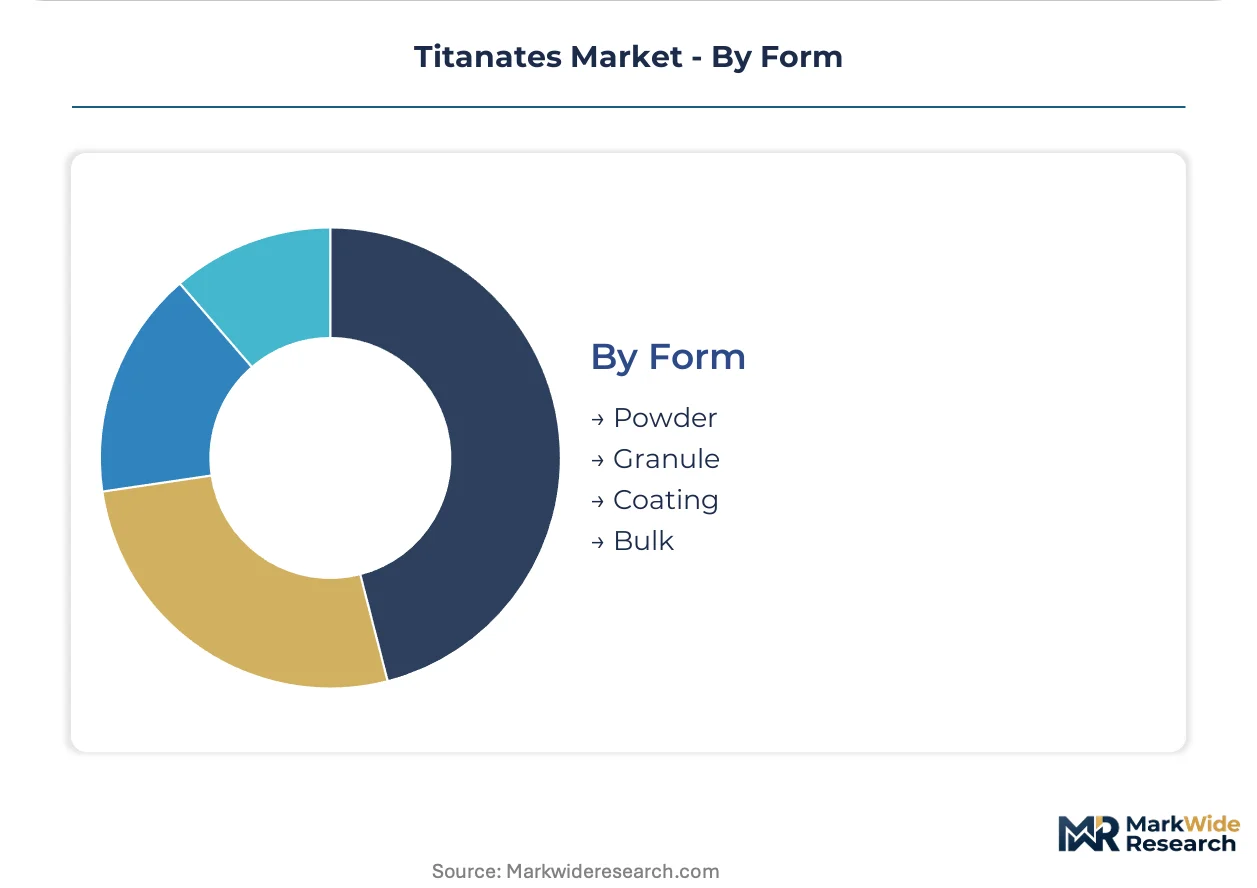
- Powder:Sub-micron to micron-scale particles for tape-casting, screen printing, and dry pressing into green bodies. Japanese and South Korean capacitor manufacturers specify surface area and particle size distribution tolerances that hydrothermal synthesis routes now achieve without multi-stage milling.
- Coating:Suspension-based formulations for thermal spray and chemical vapor deposition processes.
- Granule:Spray-dried agglomerates for isostatic pressing and injection molding feedstock.
- Bulk:Sintered blocks and machined shapes for structural applications.
Powder commands pricing power. Coating is gaining share fastest in thermal management applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan consumes titanates predominantly for multilayer ceramic capacitors, whereas China deploys them across battery electrolyte research and structural ceramics, creating divergent purity specifications and procurement rhythms between these manufacturing centers.
Japan
Osaka and Tokyo industrial corridors concentrate capacitor-grade barium titanate demand from smartphone and automotive electronics manufacturers. METI oversees export licensing of advanced ceramic materials, shaping market access protocols for non-domestic buyers. Sakai Chemical Industry maintains vertical integration from ore to electronic-grade powder in this region.
China
GB standards for electronic ceramics and dual carbon goals are tightening purity requirements while capping carbon intensity for energy-intensive calcination operations. Yangtze River Delta and Pearl River Delta clusters host domestic producers retrofitting electric kilns and waste-heat recovery systems to meet compliance.
South Korea
Pyeongtaek and Yongin industrial corridors concentrate demand for pharmaceutical-grade strontium titanate substrates from medical imaging OEMs. The K-Semiconductor Belt government initiative is accelerating clustering of semiconductor material divisions. Domestic capacitor manufacturers now negotiate powder specifications directly with calcination operators in Seoul's Pangyo corridor.
Germany
Automotive Tier 1 suppliers are qualifying new titanate suppliers for 800V inverter capacitor banks in EV power electronics. ECHA's REACH substance registration thresholds and Annex XIV authorization requirements for titanium dioxide derivatives burden toll refiners with compliance documentation costs. Specialty chemical distributors in the country's industrial regions absorb these premiums.
United States
Research procurement from national laboratories is validating ceramic processing protocols for lithium lanthanum titanate garnet solid-state electrolytes. The Southeast and Midwest manufacturing corridors host emerging interest in quantum computing substrate applications where ultra-low loss tangents matter. IBM and Google research divisions drive early qualification activity.
Titanates Market Competitive Environment
Capability concentration sits with Japanese and South Korean integrated specialists; scale advantage sits with Chinese toll processors and regional distributors. The vendor base organizes around three tiers: vertically integrated ore-to-powder operators, high-purity certification specialists, and regional toll refiners serving industrial ceramics. Dominant competitive moves include direct mill-to-OEM contracting displacing multi-tier distribution, and hydrothermal synthesis route adoption collapsing particle size distribution variance without multi-stage milling.
Within the integrated specialist tier, Sakai Chemical Industry and Nippon Chemical Industrial represent archetypal positions through their geographic anchoring in Japan's Osaka-Tokyo industrial corridor. Mitsubishi Gas Chemical occupies a certification-focused position. Among Chinese material technology enterprises, Huangshan KBR New Material Technology exemplifies regional toll processing capabilities. Kenrich Petrochemicals and Dorf Ketal Chemicals represent specialty chemical distribution archetypes serving compliance-heavy European and North American markets.
| Leading Market Players |
|---|
| Kenrich Petrochemicals |
| Dorf Ketal Chemicals |
| Mitsubishi Gas Chemical |
| Nippon Chemical Industrial |
| Sakai Chemical Industry |
| AB Enterprises |
| Chem Pharma |
| Akaiyo Chem Tech |
| Huangshan KBR New Material Technology |
| Others |
Value Chain & Pricing Dynamics
Rutile ore supply concentration from Australian and South African mineral sands operations exposes processors to shipping cost volatility that compresses margins for independent toll refiners while elevating long-term offtake premiums for vertically integrated Japanese and South Korean suppliers. This feedstock dependency shapes both the spread between spot and contract pricing tiers and the geographic clustering of calcination capacity.
Pricing Analysis
Long-term offtake agreements dominate procurement for capacitor-grade barium titanate, with annual volume commitments replacing spot transactions as South Korean MLCC manufacturers negotiate directly with Sakai Chemical and Nippon Chemical Industrial. Price differentiation rests on pharmaceutical-grade certification for strontium titanate substrates and hydrothermal synthesis capability for sub-micron particle distributions. Cost compression in standard-grade powders is intensifying because Chinese toll processors are retrofitting electric kilns to meet dual carbon goals. Consumer electronics OEMs in Seoul's Pangyo corridor exhibit highest price sensitivity, while quantum computing research divisions at IBM and Google tolerate significant premiums for cryogenic-characterized material.
Supply Chain Analysis
Contract manufacturing concentration sits with Japanese integrated specialists Sakai Chemical Industry and Mitsubishi Gas Chemical, alongside South Korean semiconductor material divisions near Pyeongtaek and Yongin. Titanium feedstock draws from Australian and South African mineral sands, while barium carbonate sources from Chinese chemical producers and strontium compounds from Mexican celestite deposits. Single-source vulnerability in rutile ore exposes processors to geopolitical disruption in mineral sands operations. Distribution runs through direct mill-to-OEM contracting that bypasses traditional trading houses, concentrating inventory management within Seoul's Pangyo and Hwaseong industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum nitride substitution in high-frequency power electronics threatens titanate volume growth in RF device packaging, forcing incumbents to defend position through purity certification and quantum substrate qualification.
For Market Incumbents: Pre-empt aluminum nitride encroachment by accelerating pharmaceutical-grade strontium titanate certification for medical imaging OEMs and securing backward integration into rutile ore through long-term offtake with Australian mineral sands operators. METI export licensing friction creates captive supply advantages for domestic Japanese manufacturers. For New Entrants and Emerging Players: Pursue India's PLI scheme for electronic components through joint venture proposals in Gujarat and Tamil Nadu, targeting capacitor-grade powder import substitution for consumer electronics assembly. White-space concentrates in solid-state battery electrolyte convergence, where lithium lanthanum titanate garnet processing capabilities overlap with traditional capacitor powder expertise. For Investors and Strategic Acquirers: The market sits at a substitution defense phase that favors vertically integrated ore-to-powder operators with in-house hydrothermal synthesis routes. Long-term viability hinges on quantum computing substrate qualification and cryogenic characterization infrastructure. Watch for early procurement signals from IBM and Google research divisions as inflection indicators for strontium titanate demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rutile Ore | Secures titanium feedstock from Australian mineral sands against shipping volatility. |
| Hydrothermal Synthesis Adoption | Collapses particle size variance for 0201 MLCC formats without multi-stage milling. |
| Pharmaceutical-Grade Certification | Unlocks South Korean medical imaging OEM demand for CT detector substrates. |
| Quantum Substrate Qualification | Positions strontium titanate for IBM and Google superconducting qubit architectures. |
| India PLI Joint Venture | Captures domestic manufacturing incentives for capacitor-grade powder in Gujarat. |
Study Parameters
Desk research of customs and trade data, SEC filings from specialty chemical distributors, and ECHA REACH registration databases preceded structured interviews with capacitor manufacturer procurement directors, calcination plant managers, and medical imaging OEM substrate engineers. Primary fieldwork with Japanese and South Korean semiconductor material divisions validated purity specification trends and direct contracting patterns. Secondary sources included METI export licensing records, China's GB standards documentation, and India PLI scheme administrative filings. Bottom-up powder volume estimates triangulated against top-down electronics demand projections.
Assumptions held fixed include regulatory compliance timelines for REACH Annex XIV and China's dual carbon intensity caps, while variables included hydrothermal synthesis adoption rates and quantum computing substrate procurement acceleration. Segmentation modeling spanned product type, application, end user, and form dimensions across the analysis window. CAGR derivation incorporated electronics miniaturization protocols, automotive electrification content per vehicle, and battery electrolyte research funding trajectories. Forecast inputs weighted MLCC format shrinkage and cryogenic characterization infrastructure availability.
Macroeconomic conditions sit as an overlay; deviation in shipping cost volatility for mineral sands feedstock or semiconductor capital expenditure cycles would shift the trajectory. Forecasts reflect assumptions about regulatory divergence between Asian purity standards and European chemical registration requirements. Quarterly review of METI export licensing volumes, ECHA authorization timelines, and national laboratory procurement for solid-state battery electrolytes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Advanced Ceramics Market
Ceramics
Advanced Sintering Technologies Market
Ceramics
USA and Canada Alumina Market
Ceramics
ME K-Feldspar Market
Ceramics
Ceramic Frit Market
Ceramics
Global Functional Ceramics Market
Ceramics
Controlled Pore Metal Oxide Market
Ceramics
India Kaolin Market
Ceramics
South Korea Ceramic Sanitaryware Market
Ceramics
Calcium Silicate Market
Ceramics
North America Activated Alumina Market
Ceramics
Technical Ceramics Market
Ceramics
Ceramic Injection Molding Market
Ceramics
Europe Ceramic Coatings Market
Ceramics
China Clay Market
Ceramics
Ceramic Lining Market