
 Cordierite Market | 2026-2036
Cordierite Market Size, Share, and Industry Trends Forecast 2026-2036
Cordierite Market Analysis
Automotive catalytic converter demand is pivoting toward higher cell-density honeycomb substrates as gasoline particulate filter mandates spread. Corning Inc. leverages its fused deposition expertise to anchor North American OEM supply chains. NGK Insulators dominates extruded ceramic production for Asian vehicle platforms. Kyocera Corporation differentiates through fine-cordierite compositions optimized for thermal shock resistance in hybrid powertrains.
Cordierite denotes a magnesium aluminum silicate ceramic (2MgO·2Al₂O₃·5SiO₂) with low thermal expansion coefficient near 1.5×10⁻⁶/°C, manufactured via extrusion, pressing, or tape casting for applications requiring rapid thermal cycling stability. Honeycomb structures command the largest volume share in automotive exhaust filtration, while monolithic kiln furniture retains margin concentration in industrial ceramics due to longer replacement cycles and custom engineering requirements. Powder and granule forms supply additive manufacturing and refractory coating growth segments where batch consistency determines specification adherence.
EPA Tier 3 and NHTSA CAFE standards in the United States, EU Green Deal F-Gas Regulation and Euro 7 emission frameworks in Europe, and China's GB 18352.6-2016 national standards collectively tighten particulate matter thresholds and expand certified substrate demand. Japan's METI carbon neutrality roadmap accelerates domestic ceramic filter R&D funding. Stakeholders must monitor divergence between regional test cycles and substrate durability specifications when allocating capacity across manufacturing footprints.
Market Dynamics
Tightening emission thresholds across major automotive markets are compressing substrate certification timelines while simultaneously extending durability specifications, forcing ceramic manufacturers to reconcile faster product validation with longer warranty obligations.
Growth Catalysts
- Euro 7 particulate limits:Gasoline particulate filter mandates across European Union member states are expanding addressable substrate volume for cell densities above 600 cpsi.
- Hybrid powertrain thermal cycling:Stop-start engine regimes in electrified vehicles impose rapid temperature fluctuation requirements that favor cordierite's thermal shock resistance over alternative ceramics.
- East Asian manufacturing corridor concentration:Integrated supplier parks in Aichi Prefecture, Zhejiang Province, and Gyeonggi-do reduce logistics friction between substrate producers and catalytic converter assemblers.
Market Restraints
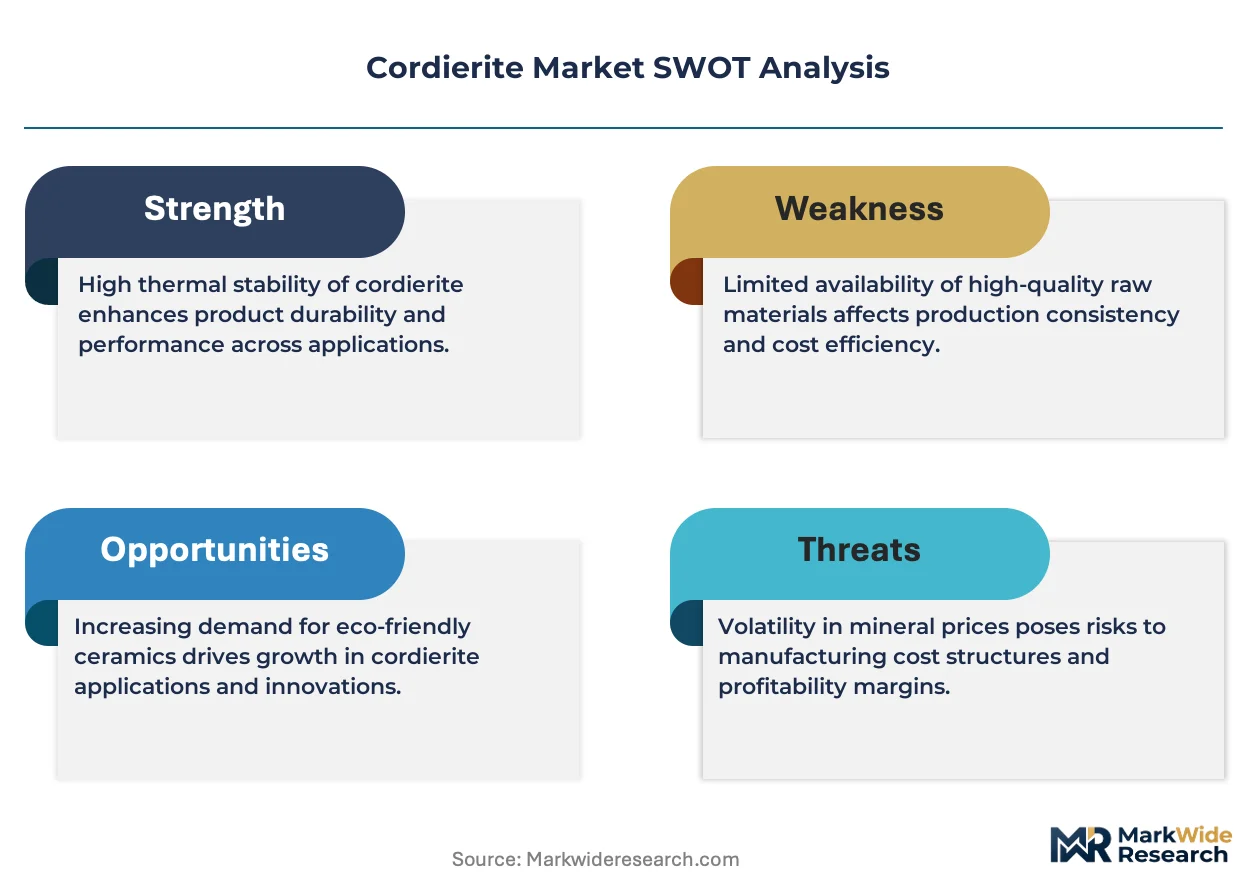
- Talc and alumina input volatility:Refractory-grade raw material costs fluctuate with Chinese mining quota adjustments and Indonesian export licensing shifts.
- Extrusion die supply concentration:Precision tooling for thin-wall honeycomb structures depends on a limited German and Japanese machine-tool vendor base.
- Silicon carbide substitution in heavy-duty:Diesel particulate filter applications above 3.5L displacement increasingly specify SiC for higher melting point tolerance.
Strategic Opportunities
- India BS-VI Phase II implementation:Stricter real-driving emission testing from April 2023 creates fresh demand for coated cordierite substrates in domestic passenger vehicle platforms.
- Additive manufacturing feedstock:Spherical cordierite powders for binder jetting and selective laser sintering address aerospace and medical ceramic prototyping segments.
- Japan METI carbon-neutral R&D funding:Domestic ceramic filter development subsidies support next-generation exhaust aftertreatment for hydrogen combustion engines.
Industry Challenges
- ISO/TS 16949 transition to IATF 16949:Automotive quality management system recertification compresses audit preparation timelines for tier-two ceramic suppliers.
- Thin-wall extrusion yield management:Cell wall thickness below 2mil raises crack propagation risk during thermal debinding, requiring statistical process control investments.
- Cross-border substrate testing reciprocity:Divergent EPA, WLTP, and GB 18352.6-2016 test cycles force parallel validation programs for multi-region OEM contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cordierite Market |
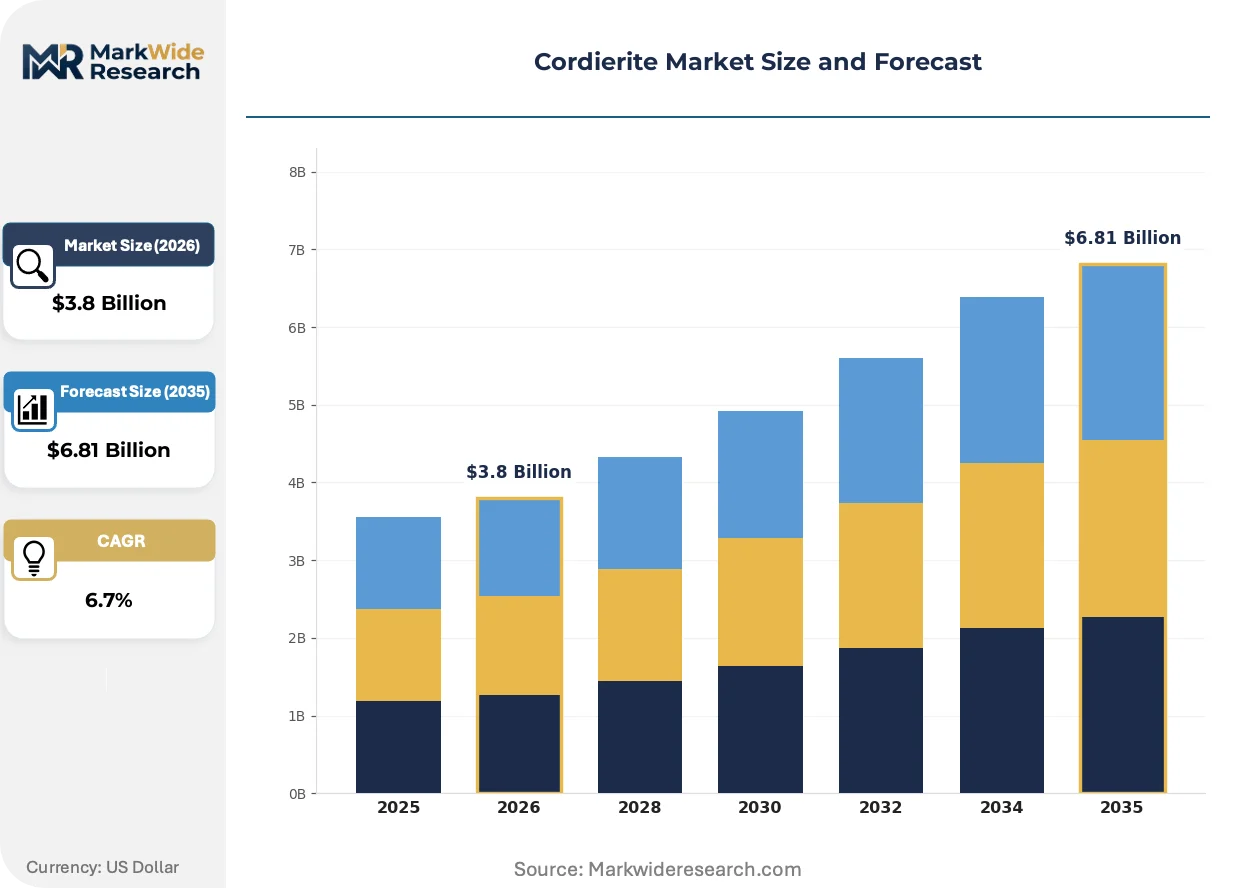
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monolithic, Honeycomb, Filter, Ceramic Application: Automotive, Aerospace, Electronics, Cookware Form: Powder, Granules, Bulk, Thin Film End User: Manufacturers, OEMs, Research Institutions, Distributors |
| Companies Covered | Corning Inc., NGK Insulators, Kyocera Corporation, Saint-Gobain, CeramTec, CoorsTek, Vesuvius Plc, DENSO Corporation, TOTO Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cordierite Market Emerging Trajectories
Digital twin modeling of firing kiln thermal profiles is compressing development cycles for custom cordierite compositions while reducing physical prototype waste in industrial ceramics manufacturing.
Advanced extrusion die design incorporating variable cell geometry is decentralizing substrate production from centralized mega-facilities toward regional satellite plants serving single OEM platforms. Tier-one suppliers in Stuttgart and Nagoya are adopting modular extrusion lines that reconfigure within 48 hours for different cell densities. This flexibility is compressing minimum viable scale thresholds and enabling just-in-sequence delivery to assembly plants.
China's GB 18352.6-2016 national standard and its anticipated Phase 6b amendments are mandating real-driving emission monitoring hardware integration. Ceramic substrate specifications now incorporate sensor mounting bosses and wiring channel geometries previously handled by downstream metal canning operations. Domestic Chinese OEMs are responding by qualifying local substrate suppliers ahead of multinational incumbents.
Converter assemblers are consolidating purchase specifications around coated substrate modules rather than bare honeycomb ceramics. This specification shift transfers catalyst loading responsibility upstream to ceramic manufacturers with in-house washcoating capabilities. The change is most visible in South Korean supply chains, where Hyundai-Kia platform standardization drives volume concentration toward vertically integrated substrate-coating operations.
Cordierite Market Segmentation
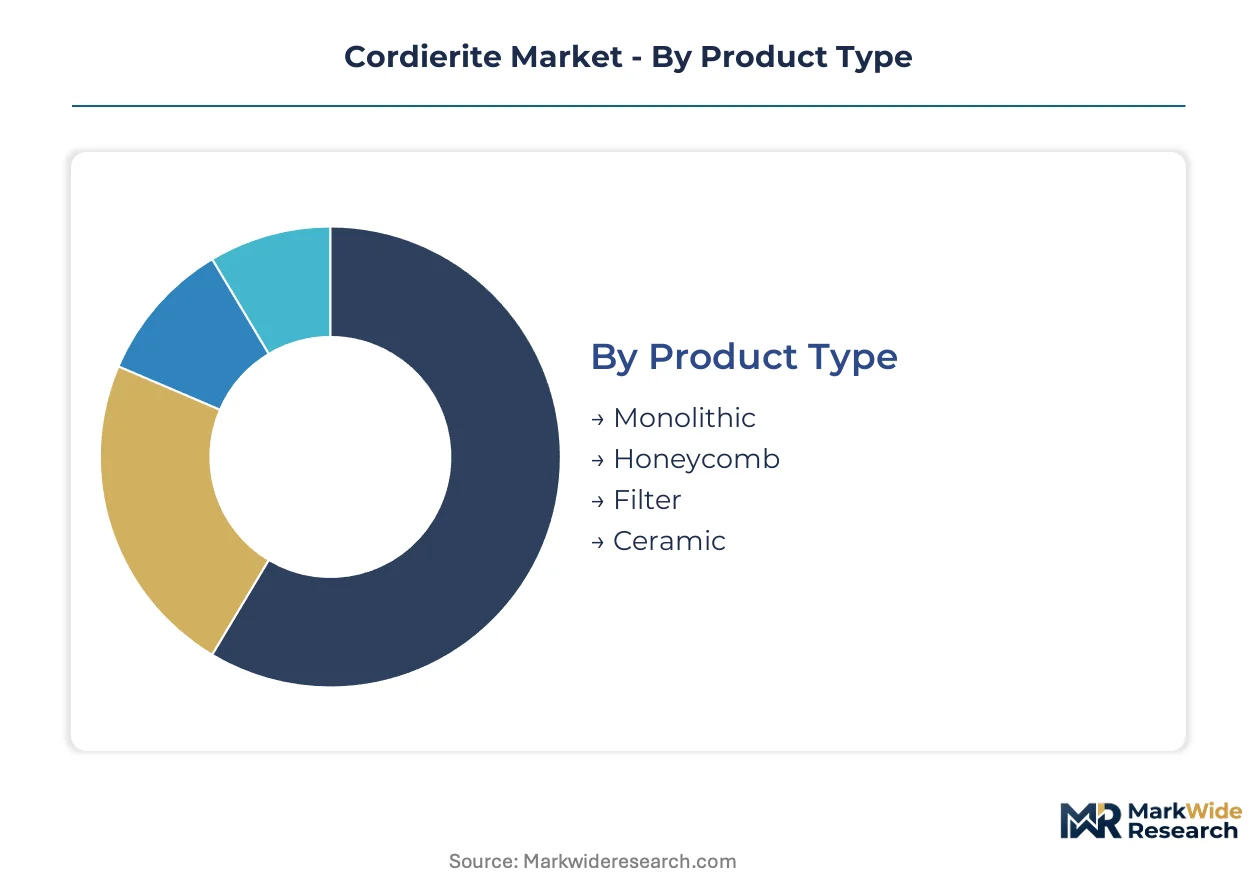
Cordierite specification requirements diverge sharply across thermal cycling intensity, geometric complexity, and certification burden. Procurement decisions pivot on whether the application demands rapid heat dissipation, filtration surface area, or dimensional stability under mechanical load.
Product Type:
Buyers select product architecture based on thermal shock frequency and structural loading requirements.
- Honeycomb:Extruded cellular structures with 400-900 cells per square inch dominate gasoline particulate filter substrates. Cell density above 600 cpsi concentrates in European OEM supply chains responding to Euro 7 particulate thresholds.
- Monolithic:Solid kiln furniture and setter plates withstand repeated firing cycles in ceramic tile and sanitaryware production. Replacement cycles extend to 18-24 months in industrial furnace applications, anchoring margin stability despite lower shipment velocity.
- Filter:Porous cordierite bodies with controlled pore size distribution serve diesel exhaust filtration and molten metal processing. Demand from foundry operations in Aichi Prefecture and Zhejiang Province shapes regional specification standards.
- Ceramic:General-grade cordierite ware spans refractory linings, crucibles, and specialty insulators. Volume sits with Honeycomb; growth tilts toward Filter as emission monitoring hardware integration expands substrate complexity.
Volume sits with Honeycomb; growth tilts toward Filter.
Application:
End-use thermal regimes dictate purity grades and forming process selection.
- Automotive:Catalytic converter substrates and diesel particulate filters impose strict cordierite thermal expansion coefficients near 1.5×10⁻⁶/°C. China's GB 18352.6-2016 standard and anticipated Phase 6b amendments mandate sensor-integrated substrate geometries previously handled by downstream metal canning.
- Aerospace:Thermal protection systems and radome applications leverage cordierite's dielectric properties and oxidation resistance. Qualification timelines stretch to 36-48 months for commercial aviation platforms, concentrating procurement with established ceramic houses possessing AS9100 certification.
- Electronics:Circuit substrate carriers and semiconductor processing equipment demand fine-cordierite compositions with sub-micron grain structure. Hybrid powertrain inverter modules in Japanese vehicle platforms drive specification tightening for thermal management components.
- Cookware:Thermal shock-resistant bakeware and pizza stones target consumer retail channels with lower technical barriers to entry. Margin compression from commoditized imports limits domestic manufacturing viability in high-labor-cost geographies.
Automotive commands current volume; aerospace and electronics segments are expanding most quickly as electrification intensifies thermal management requirements.
Form:
Downstream processing method determines feedstock morphology and batch consistency requirements.
- Powder:Spray-dried spherical particles serve binder jetting and selective laser sintering in aerospace prototyping. Sphericity and particle size distribution tolerances tighten for medical ceramic applications.
- Granules:Agglomerated feedstock for dry pressing and isostatic forming balances flowability with green strength. Refractory coating applications in steel ladles and cement kilns specify controlled moisture content ranges.
- Bulk:Pre-formed blocks and custom-machined blanks reduce downstream shaping operations for kiln furniture and specialty insulators. Long replacement cycles in industrial ceramics favor established supplier relationships over spot purchasing.
- Thin Film:Tape-cast substrates and deposited coatings address microelectronic packaging and sensor applications. Thickness uniformity below 50 micrometers requires cleanroom manufacturing environments that constrain supplier base expansion.
Granules dominate shipment tonnage; powder forms are gaining share fastest as additive manufacturing qualification protocols mature.
End User:
Procurement sophistication and volume scale separate customer tiers.
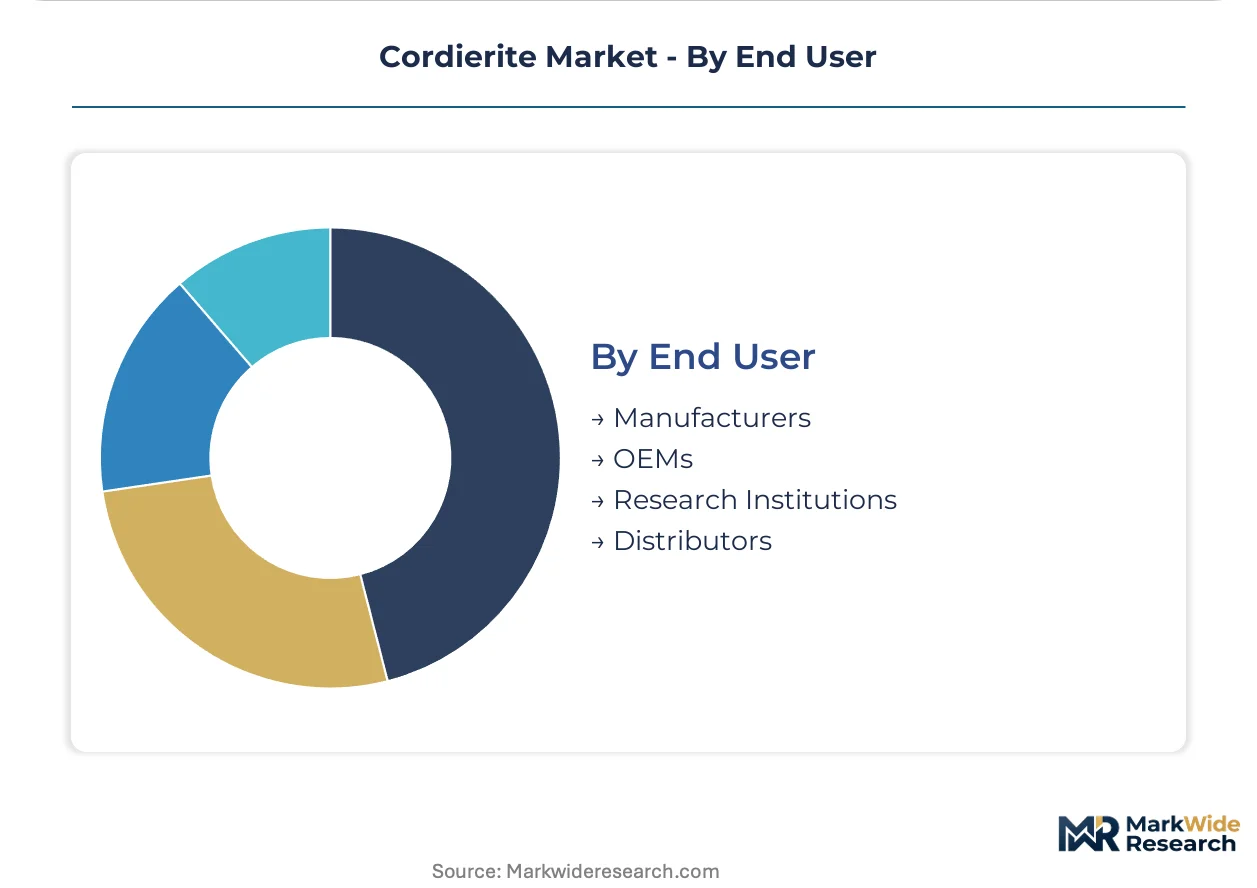
- OEMs:Tier-one automotive and aerospace assemblers specify coated substrate modules rather than bare honeycomb ceramics, transferring catalyst loading responsibility upstream. Hyundai-Kia platform standardization in South Korea concentrates volume toward vertically integrated substrate-coating operations.
- Manufacturers:Industrial ceramic producers and refractory fabricators purchase bulk cordierite for kiln furniture, crucibles, and custom-engineered components. Japanese tile manufacturers in Seto and Tokoname maintain long-term supply agreements with domestic ceramic houses.
- Research Institutions:University and national laboratory procurement focuses on high-purity powders and custom compositions for materials science investigation. Small lot sizes and specification variability limit supplier interest despite premium pricing.
- Distributors:Inventory-holding intermediaries serve fragmented foundry, glass, and pottery operations with standardized granule and bulk offerings. Geographic coverage and technical support capabilities determine competitive positioning.
OEMs anchor revenue concentration; research institutions represent the steepest expansion trajectory as hydrogen combustion engine development accelerates ceramic filter R&D funding through Japan's METI carbon neutrality roadmap.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated supplier parks in Aichi Prefecture, Zhejiang Province, and Gyeonggi-do reduce logistics friction between substrate producers and catalytic converter assemblers, concentrating cordierite demand in East Asian manufacturing corridors.
China
Domestic OEMs are qualifying local substrate suppliers ahead of multinational incumbents as GB 18352.6-2016 Phase 6b amendments mandate sensor-integrated substrate geometries. The NMPA and MIIT influence ceramic substrate certification pathways. Zhejiang Province hosts concentrated honeycomb extrusion capacity serving BYD and Geely platform standardization.
Japan
Hybrid powertrain inverter modules in Toyota and Honda platforms drive specification tightening for thermal management components. METI carbon neutrality roadmap accelerates domestic ceramic filter R&D funding. Aichi Prefecture maintains integrated supplier parks linking NGK Insulators to Toyota catalytic converter assembly.
United States
EPA Tier 3 and NHTSA CAFE standards tighten particulate matter thresholds and expand certified substrate demand. Corning Inc. leverages fused deposition expertise to anchor North American OEM supply chains. Michigan and Ohio manufacturing corridors concentrate converter assembly operations for Detroit Three platforms.
Germany
Euro 7 particulate limits expand addressable substrate volume for cell densities above 600 cpsi across European Union member states. EU Green Deal F-Gas Regulation shapes emission framework compliance. Stuttgart hosts modular extrusion line adoption for rapid reconfiguration between cell densities.
South Korea
Hyundai-Kia platform standardization drives volume concentration toward vertically integrated substrate-coating operations. MFDS regulatory alignment with EU emission test cycles simplifies export certification. Gyeonggi-do supplier parks reduce inbound logistics costs for coated substrate modules.
Cordierite Market Vendor Landscape
Top-tier vendors anchor automotive OEM supply chains, while mid-tier specialists serve industrial kiln furniture and refractory segments. The market structure reflects tiered certification barriers rather than pure scale concentration. Strategic archetypes include vertically integrated honeycomb extruders, fine-ceramic composition specialists, and refractory-grade bulk suppliers. Capacity expansion and backward integration into raw material processing represent dominant competitive moves.
Among Japanese ceramic houses, NGK Insulators and Kyocera Corporation exemplify the fine-ceramic specialization archetype, while Corning Inc. anchors the North American fused deposition tier. Saint-Gobain and CeramTec occupy positions within the European refractory and technical ceramics segment, reflecting geographic clustering around regional automotive production bases.
| Leading Market Players |
|---|
| Corning Inc. |
| NGK Insulators |
| Kyocera Corporation |
| Saint-Gobain |
| CeramTec |
| CoorsTek |
| Vesuvius Plc |
| DENSO Corporation |
| TOTO Ltd. |
| Others |
Supply Flow & Price Mechanics
Extrusion die specialists concentrated in Stuttgart and Nagoya command wage premiums that translate into pricing-tier spreads between just-in-sequence coated substrate modules and commoditized bulk cordierite granules.
Pricing Analysis
Lead-time-driven pricing separates expedited delivery premiums from spot inventory discounts in honeycomb substrate procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden divergence between IATF 16949-automotive grade and industrial kiln furniture specifications. Price differentiation hinges on cell density tolerance and thermal shock testing documentation. Cost compression in economy-grade refractory feedstock is intensifying because Indonesian talc export licensing shifts disrupt raw material cost baselines. Distributors serving fragmented foundry operations exhibit highest price sensitivity; OEMs specifying coated substrate modules demonstrate lowest sensitivity due to warranty pass-through mechanisms.
Supply Chain Analysis
Single-source vulnerability sits with precision extrusion die vendors in Germany and Japan that control thin-wall honeycomb tooling below 2mil cell thickness. Geographic supply concentration centers on China, Japan, and South Korea for fused cordierite substrate production. Raw material sourcing draws from Chinese talc mining corridors, Indonesian alumina refineries, and Brazilian magnesium oxide processors. Supply chain risk manifests as tariff exposure on refractory-grade inputs crossing ASEAN trade boundaries. Distribution runs through integrated supplier parks in Aichi Prefecture, Zhejiang Province, and Gyeonggi-do that feed just-in-sequence delivery to catalytic converter assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cordierite market sits in a technology-transition phase as silicon carbide substrates displace legacy cordierite in heavy-duty diesel particulate filters above 3.5L displacement.
For Market Incumbents: Deepen backward integration into refractory-grade talc and alumina processing to buffer input cost volatility from Chinese mining quota adjustments. Expand in-house washcoating capabilities to capture catalyst loading value pools transferring upstream from converter assemblers. Prioritize IATF 16949 recertification investments to defend tier-two supplier status against emerging Chinese substrate producers qualifying under GB 18352.6-2016 Phase 6b amendments. For New Entrants and Emerging Players: Capture additive manufacturing feedstock white space in spherical cordierite powders for aerospace binder jetting applications where AS9100 certification barriers remain penetrable. Target research institution procurement channels for hydrogen combustion engine ceramic filter development funded through Japan's METI carbon neutrality roadmap. Lead with technical specification support and small-lot flexibility rather than volume scale. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated substrate-coating operations given Hyundai-Kia platform standardization concentrating South Korean supply chain volume. Long-term viability favors archetypes controlling both honeycomb extrusion and catalyst washcoating capabilities within single manufacturing footprints. Watch for divergence between EPA, WLTP, and GB 18352.6-2016 test cycle harmonization as inflection indicator for multi-region capacity allocation decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Processing | Captive talc and alumina supply buffers margin compression from Indonesian export licensing volatility. |
| In-House Washcoating Capability Expansion | Upstream catalyst loading capture responds to Hyundai-Kia coated substrate module consolidation. |
| Modular Extrusion Line Deployment | 48-hour reconfiguration between cell densities enables just-in-sequence delivery to Stuttgart OEM platforms. |
| Additive Manufacturing Feedstock Qualification | Spherical powder production for binder jetting addresses aerospace prototyping segments requiring AS9100 certification. |
| Sensor-Integrated Substrate Geometry Development | GB 18352.6-2016 Phase 6b compliance mandates wiring channel integration previously handled by metal canning. |
Methodological Framework
Independent corroboration across ceramic plant managers, Tier 1 automotive procurement leads, extrusion die tooling specialists, and refractory distribution channel partners underwrites the qualitative findings. Primary fieldwork combined structured interviews with downstream converter assemblers in Aichi Prefecture and Zhejiang Province with technical validation from kiln furniture operators in Seto and Tokoname. Secondary sources encompassed customs and trade data tracking talc and alumina flows, SEC filings from publicly traded ceramic houses, NMPA and MIIT regulatory filings, and METI R&D funding disclosure databases. Bottom-up shipment tallies by product form and application triangulated against top-down OEM platform content-per-vehicle estimates.
Rate-of-change decomposition across the analysis window isolated volume drivers by propulsion architecture transition, emission regulation phase-in schedules, and regional manufacturing footprint shifts. Segmentation dimensions modeled encompassed product architecture, thermal cycling intensity, forming process, and end-user procurement sophistication tier. CAGRs derived from regression against historical OEM platform volumes and projected powertrain mix trajectories. Industry-specific inputs incorporated GB 18352.6-2016 Phase 6b amendment timing assumptions and Euro 7 particulate limit enforcement pathways.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to silicon carbide substitution rates in heavy-duty applications and divergence between regional emission test cycle reciprocity agreements. Forecasts reflect documented assumptions regarding raw material cost baselines, certification timeline compressions, and OEM platform standardization trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Global Barium Carbonate Market
Ceramics
Potassium Silicate Market
Ceramics
Mullite Market
Ceramics
Ceramic Fabrication Services Market
Ceramics
Glazed Bricks Market
Ceramics
White Fused Alumina Market
Ceramics
Ceramic Additives Market
Ceramics
Vaterite Market
Ceramics
Global Ceramic and Porcelain Tiles Market
Ceramics
Asia-Pacific Kaolin Market
Ceramics
Calcined Alumina Market
Ceramics
Europe Activated Alumina Market
Ceramics
Porous Ceramic Market
Ceramics
Ceramic Lining Market
Ceramics
Global Ceramic Foams Market
Ceramics
Potassium Feldspar Market