
 Tetra-N-Butyl Titanate Market | 2026-2036
Tetra-N-Butyl Titanate Market Size, Share, and Industry Trends Forecast 2026-2036
Tetra-N-Butyl Titanate Market Analytics
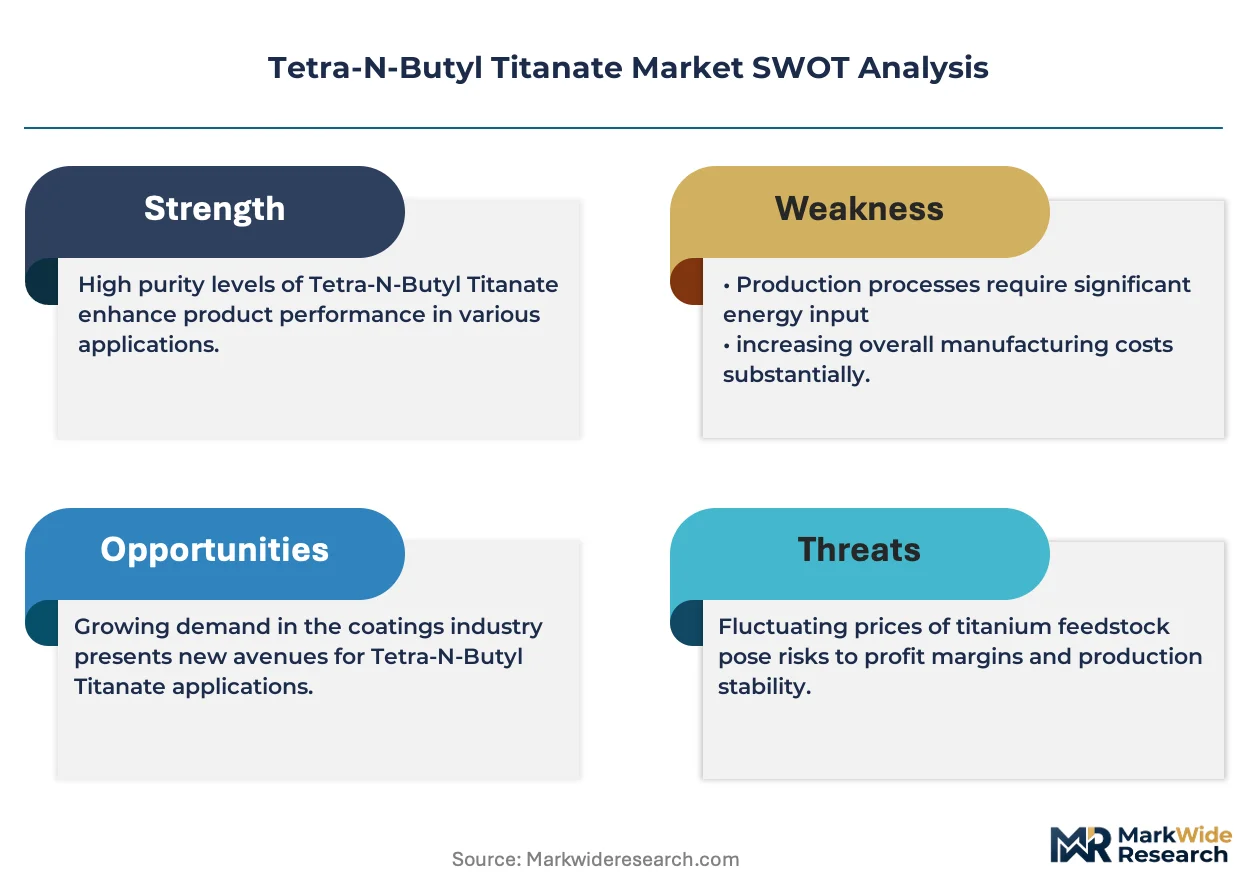
REACH compliance is restructuring the cost-of-entry calculus for European coatings formulators seeking titanium alkoxide supply chains. Wuhan Fortuna Chemical leverages integrated butanol-to-alkoxide production to sustain margin resilience against feedstock volatility. Nanjing Shuguang Chemical anchors its position through specialized high-purity grades targeting electronics-grade applications. GYC Group differentiates via backward integration into titanium tetrachloride feedstock, controlling upstream material flows across multiple end-use channels.
Tetra-N-Butyl Titanate functions as a titanium(IV) alkoxide with the molecular formula Ti(OC4H9)4, synthesized through alcoholysis of titanium tetrachloride with n-butanol under controlled anhydrous conditions; it serves primarily as a cross-linking agent, catalyst precursor, and sol-gel precursor in surface modification processes. The liquid product form dominates volume flows due to its direct applicability in continuous coating lines and chemical synthesis operations, while powder and granule formats capture premium positioning in moisture-sensitive electronics applications where controlled hydrolysis rates determine processing yields. Catalyst applications represent the fastest-expanding demand segment as refiners and polymer producers adopt organotitanate activators to replace tin-based systems facing toxicological scrutiny.
China's MIIT enforces GB standards on chemical purity and hazardous substance limits that directly shape domestic production specifications and export eligibility. The EPA in the United States monitors titanium compound discharges under TSCA reporting requirements, influencing formulation decisions for coatings entering North American supply chains. ECHA's ongoing substance evaluations under REACH continue to tighten hazard classification thresholds for alkoxide compounds, compelling reformulation investments across European industrial coatings. Stakeholders must monitor regulatory divergence between Asian purity standards and European hazard classifications when configuring regional product portfolios and certification strategies.
Market Dynamics
REACH restrictions on volatile organic compound emissions are restructuring formulation investments across European coatings, redirecting capital toward low-VOC titanium alkoxide systems and compressing margins for legacy high-solvent processes.
Growth Catalysts
- Sol-gel aerospace coatings:Aerospace manufacturers in the United States and Germany are accelerating uptake of high-purity organotitanates for thermal barrier and corrosion-resistant surface treatments on turbine components.
- GB standards compliance:China's MIIT enforcement of chemical purity specifications is expanding export eligibility for domestic producers meeting electronics-grade certification thresholds.
- Tin-to-titanium substitution:Polymer producers and refiners are adopting organotitanate activators to replace tin-based catalyst systems facing toxicological scrutiny under ECHA evaluations.
Market Restraints
- N-butanol feedstock volatility:Integrated butanol-to-alkoxide producers maintain margin resilience while non-integrated formulators absorb raw material price swings.
- Jiangsu-Zhejiang supply concentration:Over sixty percent of Chinese production capacity clusters in two eastern provinces, creating geographic risk exposure to regional environmental enforcement actions.
- Hydrolysis sensitivity:Moisture-controlled handling requirements limit distribution radius and elevate logistics costs for liquid product formats.
Strategic Opportunities
- India specialty chemicals:Formulators serving India's automotive and construction sectors present underpenetrated demand for catalyst-grade alkoxides as domestic production scales under PLI scheme incentives.
- Electronics-grade powder formats:Semiconductor packaging and display manufacturing in South Korea and Taiwan are generating premium positioning for granule formats with controlled hydrolysis rates.
- Dual carbon alignment:China's MEE carbon intensity targets are creating procurement preference for producers with captive titanium tetrachloride feedstock and closed-loop energy systems.
Industry Challenges
- Anhydrous process engineering:Maintaining moisture-free synthesis environments requires specialized vessel infrastructure and skilled operations personnel that concentrate at established chemical manufacturing clusters.
- REACH registration timelines:ECHA substance evaluation deadlines compress reformulation windows for European coatings formulators, forcing parallel certification tracks across purity grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tetra-N-Butyl Titanate Market |
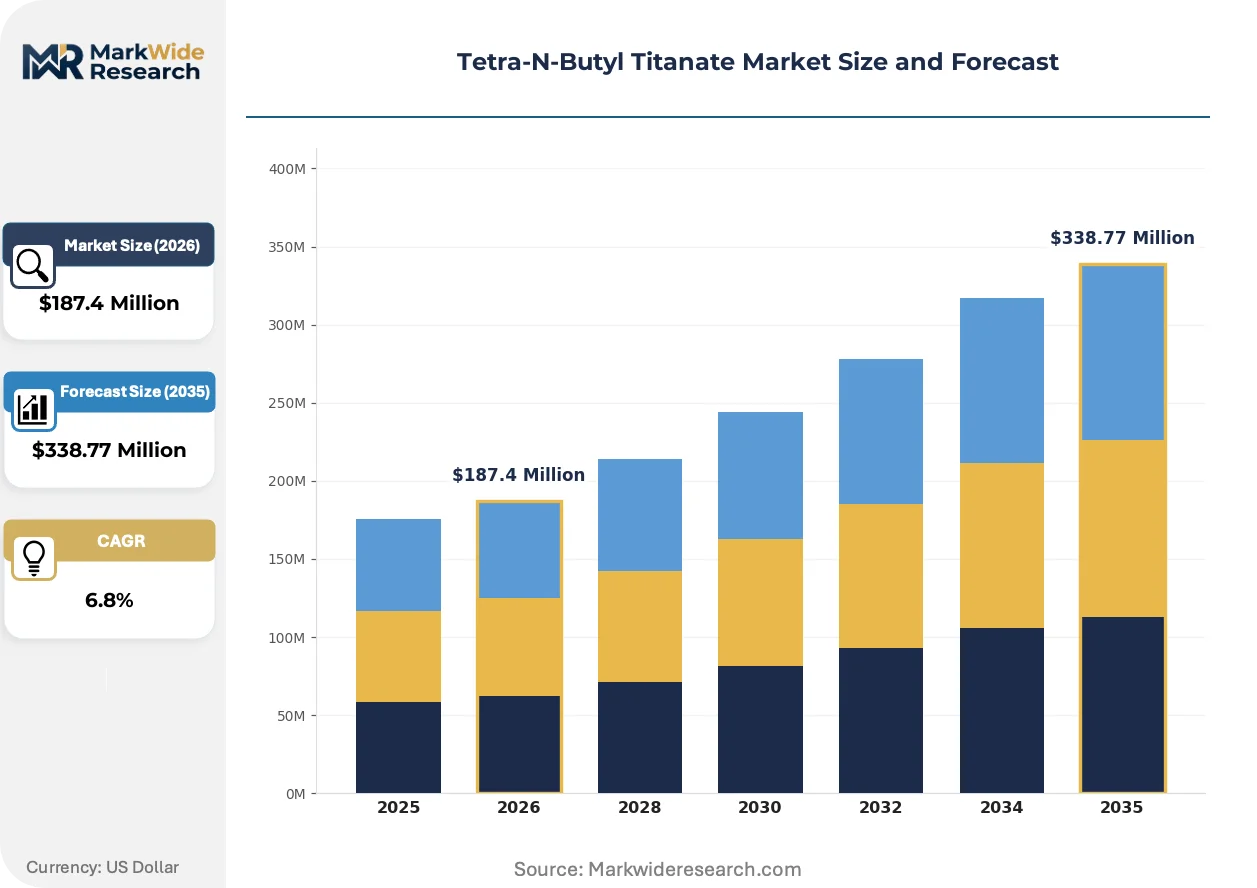
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granules, Paste Application: Chemical Synthesis, Coatings, Adhesives, Catalysts End User: Aerospace, Electronics, Construction, Automotive Packaging Type: Tank, Drum, Bottle, Bulk |
| Companies Covered | Wuhan Fortuna Chemical, Nanjing Shuguang Chemical, GYC Group, TC Chemicals, Zhejiang Feidian Chemical, Jinan Haohua Industry, Jiaxing Isen Chemical, Shanghai HeChuang Chemical, Hangzhou Dayangchem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tetra-N-Butyl Titanate Market Evolving Landscape
Formulation chemistry is pivoting toward waterborne and high-solids systems, compressing the addressable market for traditional solvent-borne titanium alkoxides while elevating specification requirements for modified grades.
Continuous-flow synthesis of titanium alkoxides is converging with automated process analytical technology to enable real-time purity monitoring. Specialty chemical producers in Germany and Japan are retrofitting batch facilities with continuous reactors to reduce solvent inventory and improve lot-to-lot consistency. This convergence is compressing capital requirements for high-purity production and enabling mid-scale entrants to compete on electronics-grade specifications.
REACH authorization procedures for titanium compounds are tightening hazard classification thresholds, compelling formulators to submit extended safety data packages. Industrial coatings producers in France and Italy are reformulating standard-grade alkoxides to meet downstream user communication obligations. The construction and automotive refinish segments are absorbing compliance costs through qualified supplier lists that exclude non-registered import sources.
Specification-driven procurement is consolidating supplier relationships around certified purity tiers rather than spot commodity purchases. Coatings formulators in China's Pearl River Delta are implementing vendor-managed inventory programs with locked quarterly pricing against GB-standard certificates. This behavioral shift is most visible in electronics applications where hydrolysis rate specifications determine processing yields and reject rates.
Tetra-N-Butyl Titanate Market Segmentation
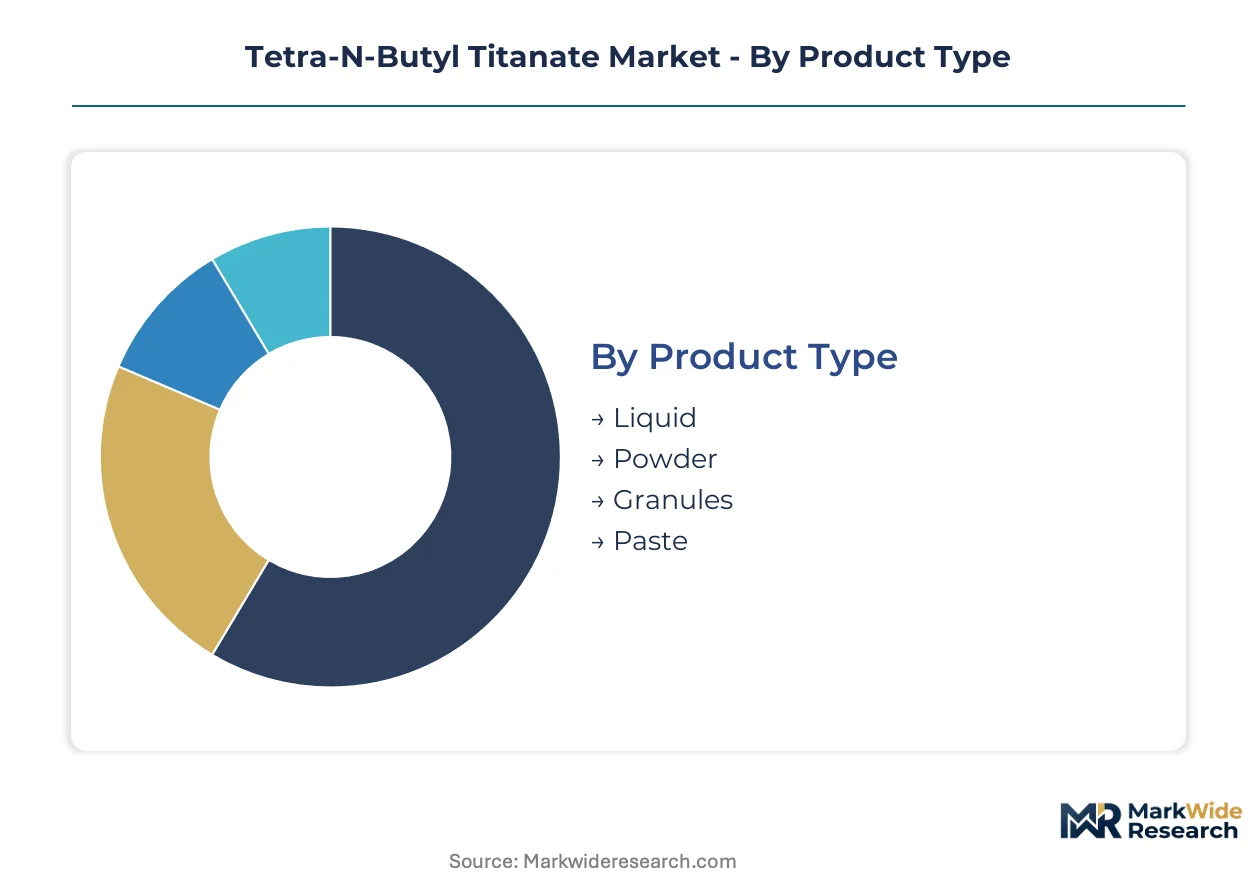
Segmentation in the Tetra-N-Butyl Titanate market reveals how capital allocation, regulatory exposure, and end-use specifications fragment supply chains. Each dimension carries distinct margin profiles and certification requirements that reshape competitive positioning across geographies.
Product Type:
Capital intensity varies sharply across physical formats, with anhydrous synthesis infrastructure and moisture-controlled packaging systems demanding differentiated upfront investment.
- Liquid:Standard Ti(OC4H9)4 solution in n-butanol carrier dominates volume flows through continuous coating lines and chemical synthesis operations. Demand concentrates in Germany's automotive refinish sector where REACH-compliant low-VOC formulations are displacing solvent-heavy legacy systems.
- Powder:Spray-dried particulate with sub-micron particle size distribution enables precise dosing in moisture-sensitive electronics manufacturing. South Korean semiconductor packaging operations are absorbing premium-priced powder grades where hydrolysis rate control determines yield performance.
- Granules:Agglomerated solid format with delayed dissolution kinetics for controlled-release catalyst applications.
- Paste:Thickened dispersion for specialized adhesive bonding and gap-filling formulations.
Most installed capacity flows through liquid production trains. Expansion is steepest in powder formats.
Application:
Margin structures diverge based on technical service intensity and regulatory documentation burdens inherent to each use case.
- Catalysts:Organotitanate activators replace tin-based systems in polyester production and petroleum refining. Polymer producers in India's Gujarat chemical belt are adopting titanium alkoxides under PLI scheme incentives as domestic specialty chemical capacity scales.
- Chemical Synthesis:Cross-linking agent and sol-gel precursor for titanium dioxide nanoparticle production. Zhejiang province manufacturers supply electronics-grade alkoxides to Taiwan's display panel fabrication clusters.
- Coatings:Surface modification agent for thermal barrier and corrosion-resistant films on turbine components.
- Adhesives:Moisture-cure accelerator in structural bonding systems for construction and transportation applications.
Coatings applications retain the largest revenue base. Catalyst-grade alkoxides are gaining share fastest.
End User:
Customer concentration and procurement sophistication create tiered pricing power dynamics across industrial verticals.
- Electronics:Semiconductor packaging, display manufacturing, and printed circuit board fabrication demand electronics-grade certification with sub-ppm metallic impurity limits. Taiwan's Hsinchu Science Park fabs enforce vendor-managed inventory programs with quarterly pricing locked against hydrolysis rate specifications.
- Aerospace:Thermal barrier coatings on turbine blades and corrosion protection for airframe components require lot traceability and extended safety data packages. Germany's MTU Aero Engines and Pratt & Whitney's Connecticut operations specify high-purity organotitanates for sol-gel surface treatments.
- Construction:Adhesive and sealant formulations for structural glazing and infrastructure waterproofing.
- Automotive:Refinish coatings and OEM corrosion protection systems with VOC compliance documentation.
Electronics commands the steepest purity premiums. Aerospace procurement volumes are climbing most quickly.
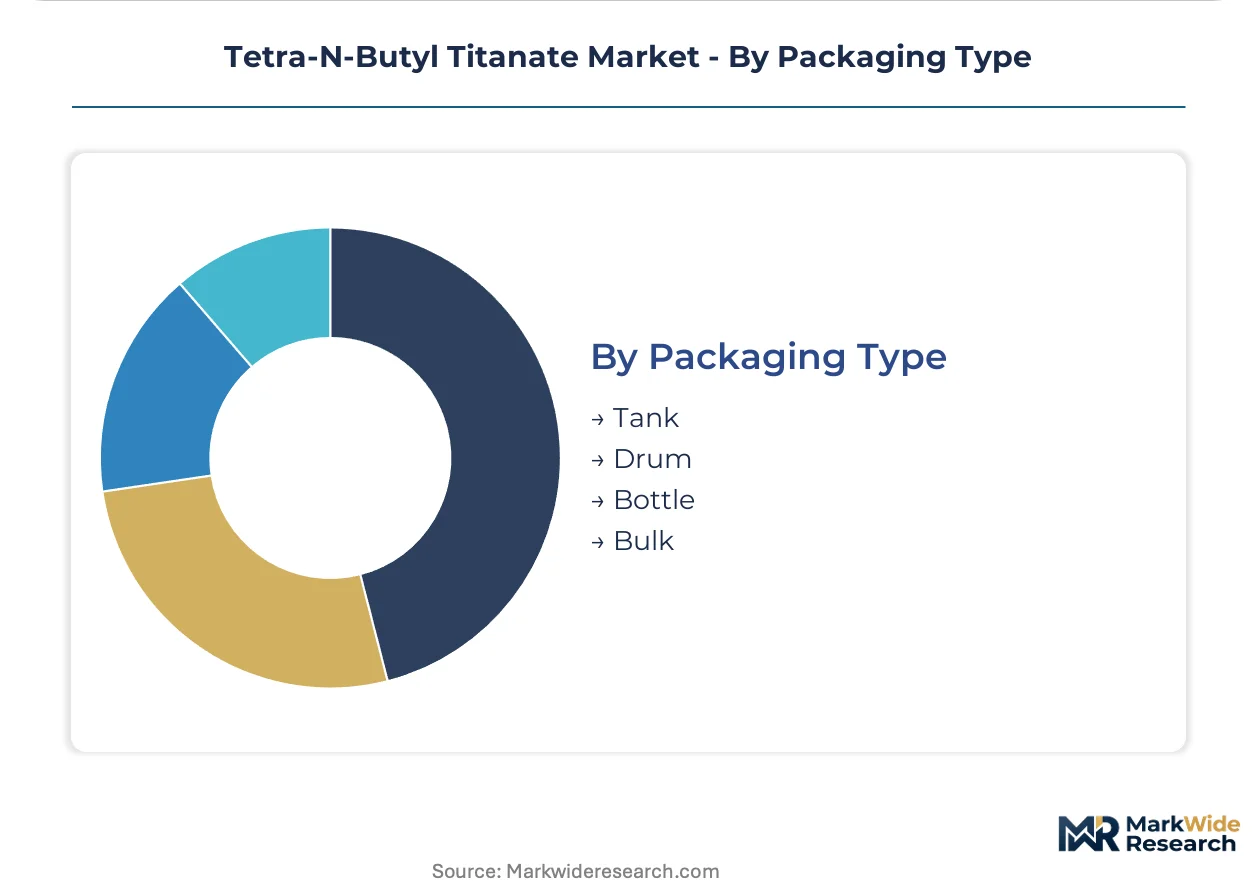
Packaging Type:
Logistics infrastructure and handling protocols segment supply chains by distribution radius and customer scale.
- Drum:Standard 200-liter steel containers with nitrogen blanket for liquid product distribution to mid-scale formulators. Jiangsu province producers serve China's Pearl River Delta coatings clusters through drum-based supply chains with moisture-controlled warehousing.
- Tank:Bulk liquid transport via ISO tank containers for integrated chemical manufacturers with captive alkoxide consumption. Wuhan Fortuna Chemical leverages tank delivery to anchor long-term contracts with domestic polymer producers.
- Bottle:Laboratory-scale packaging for R&D sampling and specialty formulation development.
- Bulk:Unpackaged powder and granule shipments for large-volume catalyst and ceramics manufacturers with dedicated handling systems.
Drum shipments handle the broadest customer base. Tank deliveries are expanding most rapidly among integrated consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical conglomerates pioneered industrial organotitanate synthesis in the 1960s, establishing the technical foundations that Chinese producers later scaled into high-volume manufacturing corridors.
China
Jiangsu and Zhejiang provinces concentrate over sixty percent of domestic production capacity, with Zhejiang Feidian Chemical and Nanjing Shuguang Chemical anchoring supply chains. MIIT enforces GB standards on chemical purity that determine export eligibility for electronics-grade consignments. The Yangtze River Delta chemical corridor ships alkoxides to Taiwan's display panel fabrication clusters under vendor-managed inventory programs.
Germany
REACH authorization procedures compel coatings formulators to submit extended safety data packages for titanium alkoxide imports. ECHA substance evaluations tighten hazard classification thresholds, forcing parallel certification tracks across purity grades. MTU Aero Engines in Munich specifies high-purity organotitanates for sol-gel thermal barrier coatings on turbine components.
United States
Pratt & Whitney's Connecticut operations accelerate uptake of aerospace-grade alkoxides for corrosion-resistant surface treatments. EPA monitors titanium compound discharges under TSCA reporting requirements, influencing formulation decisions for coatings entering North American supply chains. The Southeast chemical manufacturing belt absorbs drum shipments from integrated butanol-to-alkoxide producers.
South Korea
Semiconductor packaging operations in Hsinchu Science Park enforce hydrolysis rate specifications that determine processing yields and reject rates. MFDS maintains pharmaceutical-grade chemical standards that overlap with electronics purity thresholds. Busan-Ulsan industrial corridor imports powder formats with controlled dissolution kinetics for catalyst applications.
India
Polymer producers in Gujarat's chemical belt adopt organotitanate activators under PLI scheme incentives as domestic specialty chemical capacity scales. BIS certification requirements shape import specifications for catalyst-grade alkoxides. Maharashtra's automotive refinish sector presents underpenetrated demand for tin-to-titanium substitution in polyester production.
Tetra-N-Butyl Titanate Market Competitive Landscape
The competitive structure tilts toward integrated feedstock controllers with captive titanium tetrachloride supply. Mid-scale specialists compete on electronics-grade purity certification rather than volume scale. Three archetypes dominate: backward-integrated upstream controllers, regional purity specialists, and diversified alkoxide portfolio operators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as producers secure long-term catalyst supply contracts.
Among Chinese producers, Wuhan Fortuna Chemical exemplifies the integrated archetype with butanol-to-alkoxide production systems. Nanjing Shuguang Chemical occupies a position within the high-purity specialist tier, while GYC Group anchors the upstream control segment through titanium tetrachloride feedstock integration. These three represent distinct strategic postures visible across the supplier base.
| Leading Market Players |
|---|
| Wuhan Fortuna Chemical |
| Nanjing Shuguang Chemical |
| GYC Group |
| TC Chemicals |
| Zhejiang Feidian Chemical |
| Jinan Haohua Industry |
| Jiaxing Isen Chemical |
| Shanghai HeChuang Chemical |
| Hangzhou Dayangchem |
| Others |
Value Network & Pricing Analysis
Captive titanium tetrachloride production anchors pricing power for integrated Chinese producers while forcing non-integrated formulators to absorb n-butanol feedstock volatility through compressed margins. Wuhan Fortuna Chemical's butanol-to-alkoxide integration insulates against raw material swings that erode competitor positions in Jiangsu and Zhejiang provinces.
Pricing Analysis
Bundled technical service and certification documentation commands premium positioning over unbundled commodity spot transactions. Electronics-grade powder formats with hydrolysis rate guarantees price at substantial premiums to standard liquid grades, while drum-based deliveries to mid-scale coatings formulators compete on volume discounts and locked quarterly contracts. Pricing pressure intensifies in standard liquid grades as REACH compliance costs concentrate procurement around qualified supplier lists with registered import sources. Polymer producers in India's Gujarat chemical belt exhibit highest price sensitivity due to PLI scheme margin constraints, whereas Taiwan's semiconductor fabs prioritize specification certainty over unit cost.
Supply Chain Analysis
Skilled anhydrous process engineers concentrate in Germany's Rhine-Ruhr chemical corridor and China's Yangtze River Delta, limiting viable expansion sites for moisture-controlled synthesis infrastructure. Supply draws from titanium tetrachloride feedstock anchored in China, United States, and Ukraine, with n-butanol sourcing from petrochemical complexes in Saudi Arabia and Singapore. Single-source vulnerability runs through Jiangsu-Zhejiang production concentration, where regional environmental enforcement actions risk disproportionate supply disruption. Distribution runs through nitrogen-blanketed drum shipments for mid-scale formulators and ISO tank containers for integrated chemical manufacturers with captive consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-regulated European formulation costs and MIIT-certified Chinese production economics, with carbon intensity differentials under China's dual carbon goals widening the procurement preference gap.
For Market Incumbents: Deepen backward integration into titanium tetrachloride feedstock to defend margin position against n-butanol volatility and emerging Indian capacity under PLI incentives. Anchor long-term catalyst supply contracts with polymer producers through locked pricing against GB-standard certificates, while retrofitting batch facilities with continuous-flow synthesis to reduce solvent inventory and improve lot-to-lot consistency for electronics-grade specifications. For New Entrants and Emerging Players: Continuous-flow synthesis with automated process analytical technology offers entry into high-purity segments without legacy batch infrastructure investment. Target India's automotive refinish and polyester production sectors where tin-to-titanium substitution creates qualified supplier list vacancies, entering through technical service partnerships with Gujarat chemical belt distributors rather than direct bulk commodity sales. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale purity specialists because electronics-grade certification scarcity concentrates vendor relationships around hydrolysis rate guarantees that determine processing yields. Five-to-ten year viability hinges on captive feedstock control and closed-loop energy systems aligning with procurement preferences under carbon intensity targets. Monitor ECHA substance evaluation timelines as inflection indicators for reformulation investment windows and import source consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Tetrachloride | GYC Group's upstream feedstock control secures margin resilience across multiple end-use channels against raw material swings. |
| Continuous-Flow Synthesis Retrofit | German and Japanese specialty chemical producers reduce solvent inventory and improve lot-to-lot consistency for electronics-grade specifications. |
| Electronics-Grade Powder Format Expansion | South Korean semiconductor packaging operations absorb premium-priced grades where hydrolysis rate control determines yield performance. |
| Vendor-Managed Inventory Programs | Pearl River Delta coatings formulators lock quarterly pricing against GB-standard certificates with Jiangsu province producers. |
| REACH Registration Parallel Certification | European coatings formulators submit extended safety data packages to ECHA before substance evaluation deadlines compress reformulation windows. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at alkoxide synthesis facilities, procurement leads at downstream polymer and coatings OEMs, distribution channel partners in China's chemical manufacturing corridor, and technical R&D directors specializing in sol-gel formulation chemistry. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of listed chemical conglomerates, and MIIT enforcement notices on GB standard compliance. Bottom-up capacity and consumption estimates triangulated against top-down market sizing from production value chain analysis.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation modeling across grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs derived from slope-log regression against normalized production indices and end-use consumption elasticities. Forecast inputs incorporated REACH registration timelines, PLI scheme capacity buildout schedules in India, and aerospace procurement cycles for thermal barrier coating specifications.
The model holds under stable n-butanol feedstock pricing and sustained REACH enforcement intensity; deviation in ECHA hazard classification thresholds or regional environmental shutdowns in Jiangsu-Zhejiang would shift supply availability and pricing trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Strontium Carbonate Market
Ceramics
Europe Ceramic Coatings Market
Ceramics
Fire Clay Market
Ceramics
Earthenware Market
Ceramics
Solid-Ion Conductors Market
Ceramics
Ceramic Kilns Market
Ceramics
United Kingdom Ceramic Tiles Market
Ceramics
Electronics Ceramics and Electrical Ceramics Market
Ceramics
Global Ceramic Coating Market
Ceramics
Ceramic Lining Market
Ceramics
Taiwan Ceramic Tiles Market
Ceramics
North America Activated Alumina Market
Ceramics
UAE Ceramic Tiles Market
Ceramics
2N High Purity Alumina Market
Ceramics
Graphite Crucibles Market
Ceramics
Relaxor Ferroelectric Ceramics Market