
 White Fused Alumina Market | 2026-2036
White Fused Alumina Market Size, Share, and Industry Trends Forecast 2026-2036
White Fused Alumina Market Outlook
Refractory refurbishment services is reshaping margin distribution across the value chain, pulling profitability downstream from raw material sales toward technical application support. Imerys leverages its vertically integrated bauxite-to-refractory pipeline to control input costs across European operations. Rusal anchors its position through captive alumina refining capacity in Siberia, insulating against feedstock volatility. Saint-Gobain competes by specializing in precision grain sizing for aerospace turbine blade finishing, where tolerances tighten annually.
White fused alumina consists of nearly pure alpha-aluminum oxide crystals produced by electric-arc melting of calcined alumina at temperatures exceeding 2000°C, yielding material with hardness of 9 on the Mohs scale and primary utility in bonded abrasives and high-temperature refractory linings. Grades destined for abrasive tools command premium pricing due to controlled friability requirements in precision grinding wheels. Powders for ceramic matrix composites represent the fastest-expanding application segment as turbine manufacturers substitute oxide ceramics for superalloys. Refractories in bulk material form remain the volume anchor, though margin compression intensifies from Chinese oversupply in standard grades.
REACH registration requirements in Europe constrain import pathways for uncharacterized powder formulations, while China's MEE enforces emissions caps on fused alumina smelters in Henan and Shandong provinces. The EPA's National Emission Standards for Hazardous Air Pollutants shape US producer investment in baghouse and scrubber retrofits. Stakeholders must monitor divergence between EU carbon border adjustment mechanisms and China's dual carbon enforcement timelines to anticipate cost-pass-through dynamics in cross-border trade.
Market Dynamics
China's dual carbon enforcement and tightening GB emission standards are forcing fused alumina smelters toward electric-arc furnace retrofits and captive renewable energy, restructuring cost bases across Henan province's industrial cluster and redirecting export-grade supply flows.
Growth Catalysts
- Refractory refurbishment services:Integrated steel mills in Germany and Japan now bundle technical application support with powder procurement, pulling margin downstream from commodity sales toward engineered solutions.
- Ceramic matrix composite substitution:Aerospace turbine manufacturers are replacing nickel superalloys with oxide ceramic thermal barrier coatings, creating specification-grade demand for controlled-friability white fused alumina powders.
- REACH registration pathways:ECHA's characterization requirements for unregistered powder formulations are consolidating import channels toward established EU-registered suppliers, advantaging compliant producers.
Market Restraints
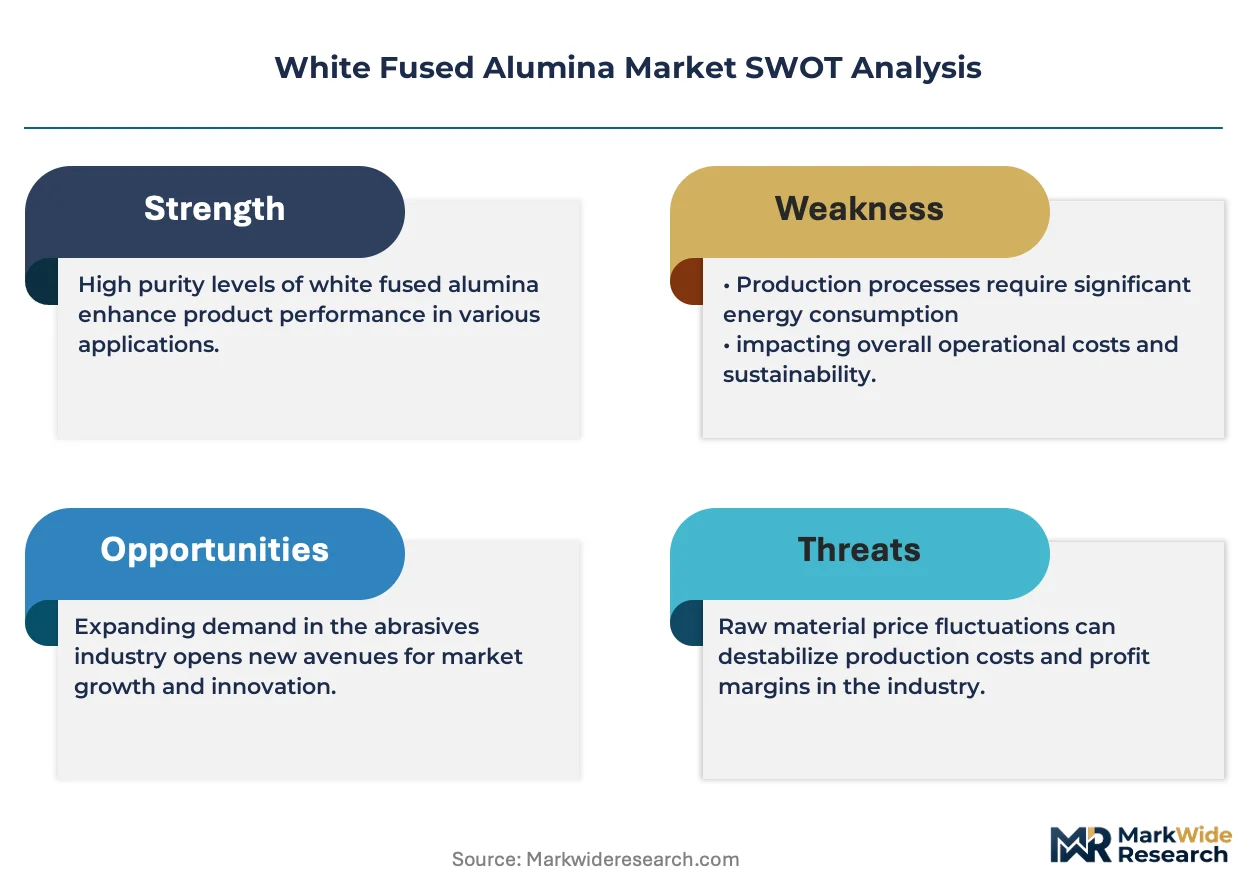
- Feedstock cost volatility:Calcined alumina prices track bauxite refining margins in China's Shanxi and Guizhou provinces, exposing non-integrated smelters to input squeeze during energy price spikes.
- Supply concentration risk:Over 60% of global fused alumina capacity sits within 200 kilometers of Zhengzhou, creating single-point vulnerability to regional power rationing or environmental enforcement waves.
- Technical friability ceiling:Standard-grade powders cannot meet aerospace turbine blade tolerances below 5 microns, capping addressable market share for commodity producers.
Strategic Opportunities
- India's refractory import substitution:BIS certification requirements for steel plant linings are creating local specification-grade production incentives for domestic fused alumina investment.
- Precision grain sizing for additive manufacturing:Binder jet and selective laser sintering of alumina ceramics require narrow particle distribution feeds, opening premium pricing tiers for classification-capable suppliers.
- EU carbon border adjustment mechanism:CBAM phase-in on imported aluminum products is incentivizing European refractory buyers to source from low-carbon verified smelters, rewarding early decarbonization investments.
Industry Challenges
- Electric-arc furnace engineering talent scarcity:Smelter retrofits for emission compliance require specialized refractory and electrode management expertise concentrated among retiring cohorts in Henan and Shandong.
- Baghouse and scrubber capex cycles:MEE enforcement timelines demand simultaneous investment in particulate capture and sulfur dioxide abatement, straining balance sheets of mid-cap producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Fused Alumina Market |
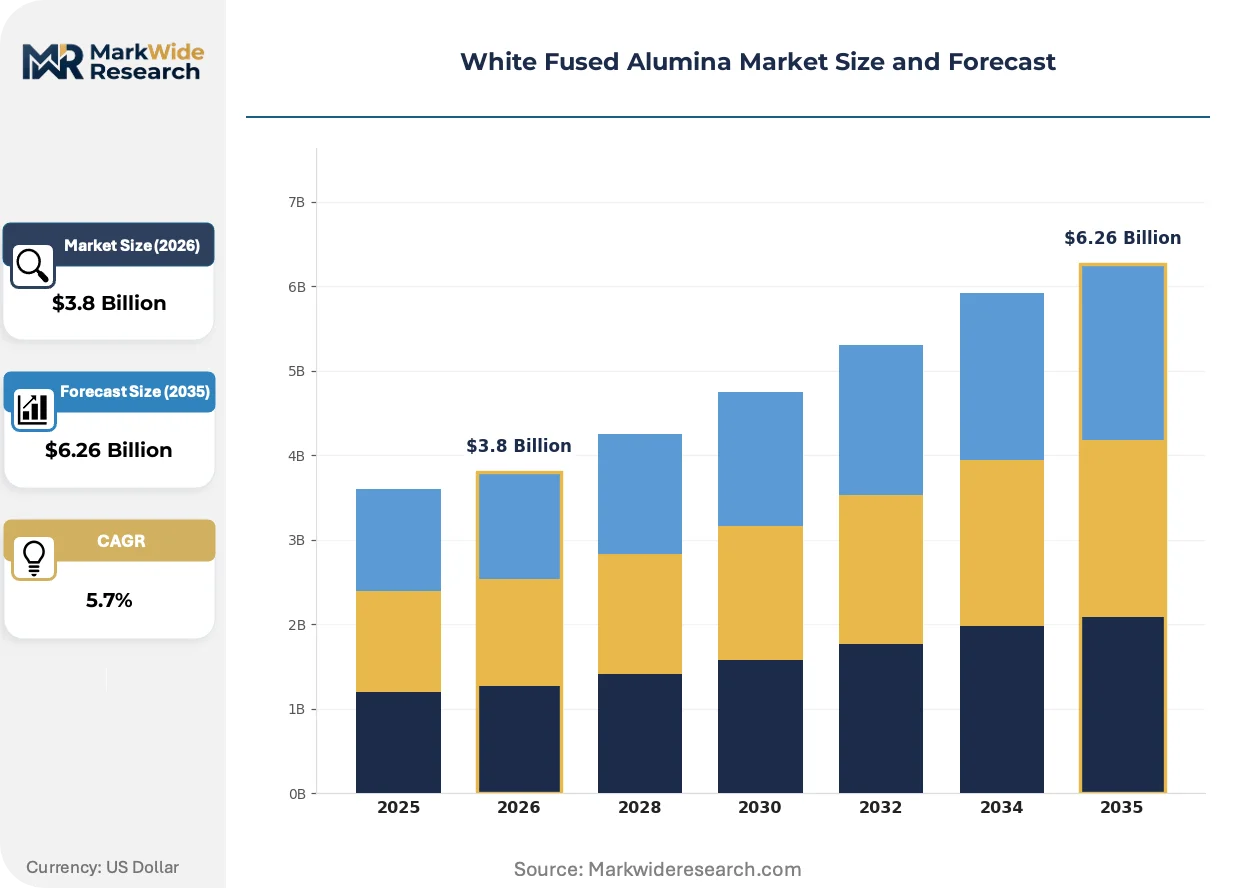
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grains, Powders, Abrasive Tools, Refractories Application: Abrasives, Coatings, Ceramics, Electronics End User: Manufacturers, Construction, Automotive, Aerospace Form: Fused Aggregate, Bulk Material, Micronized Powder, Refractory Mixes |
| Companies Covered | Imerys, Rusal, Washington Mills, Zhengzhou Yufa Group, Saint-Gobain, Almatis, Norton Abrasives, Hindalco Industries Limited, MOTIM Electrocorundum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Fused Alumina Market Strategic Shifts
Active transformation across this market centers on precision manufacturing requirements, environmental compliance technology, and the unbundling of technical services from commodity supply relationships.
Advanced classification systems using air-jet and electrostatic separation are rendering obsolete traditional mesh-screen sizing for aerospace and semiconductor polishing applications. Turbine blade finishers in France and Japan now specify particle distribution curves tighter than legacy equipment can achieve, compressing margins for undifferentiated powder suppliers while rewarding capital-intensive precision processors.
REACH registration deadlines for nano-scale alumina powders are forcing reformulation of European abrasive product lines. ECHA's 2024 guidance on characterization requirements has triggered supplier consolidation, with unregistered Asian imports facing customs detention at Rotterdam and Hamburg. German tool manufacturers are responding by qualifying alternative domestic and Turkish supply channels.
Steel mill procurement teams are unbundling refractory installation and technical troubleshooting from raw material contracts. Japanese integrated mills now source white fused alumina powders through commodity tenders while contracting application engineering separately to Imerys or local service specialists. This bifurcation is most visible in blast furnace and electric-arc furnace lining refurbishment, where technical risk retention commands premium fees independent of material costs.
White Fused Alumina Market Segmentation
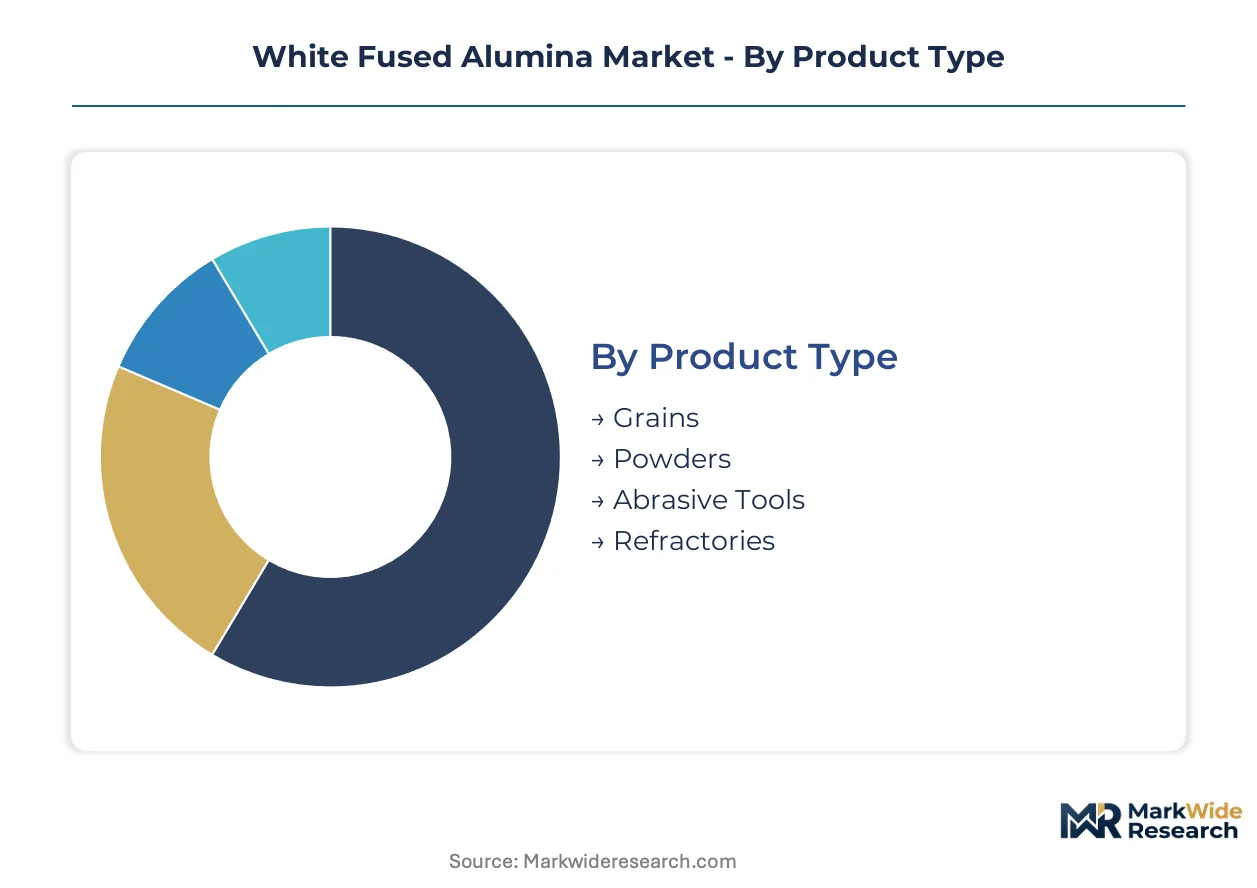
White fused alumina markets fragment across technical specifications that determine pricing power and service intensity. After-sales technical support requirements vary dramatically by segment, with aerospace and precision electronics demanding sustained application engineering while commodity refractory sales operate on volume tenders.
Product Type:
After-sales service intensity peaks in precision-grade segments where technical troubleshooting and application engineering separate premium suppliers from commodity traders.
- Grains:Coarse crystalline particles ranging from 8 to 220 mesh, produced by controlled crushing and magnetic separation of fused alumina ingots. Demand concentrates in German and Japanese bonded abrasive manufacturers, where grain toughness specifications determine grinding wheel performance in automotive camshaft finishing. Technical service teams troubleshoot wheel wear rates and thermal damage patterns.
- Powders:Finely milled material below 240 mesh with precise particle distribution curves for lapping and polishing applications. Aerospace turbine blade finishers in France and Japan now specify distribution tolerances tighter than legacy air-jet classification equipment can achieve, forcing capital upgrades among suppliers.
- Abrasive Tools:Bonded and coated products incorporating white fused alumina as the cutting medium. Indian and Turkish manufacturers compete on cost for standard grinding wheels.
- Refractories:Pre-formed shapes and monolithic mixes for high-temperature containment. Chinese oversupply compresses margins in standard-grade bulk supply.
Refractories hold the largest share; momentum sits with powders.
Application:
Cost tier stratification separates specification-grade applications with certified supply chains from price-sensitive commodity segments.
- Abrasives:Grinding, cutting, and surface preparation across metalworking and fabrication. Automotive powertrain manufacturers in Germany and Japan drive demand for friability-controlled grains that balance cutting speed with dimensional stability.
- Coatings:Thermal spray and protective layers for wear resistance. Aerospace component suppliers specify plasma-sprayed alumina for turbine blade thermal barriers.
- Ceramics:Structural and functional ceramic components including substrates and insulators. Expanding most quickly as oxide ceramics displace nickel superalloys in turbine hot sections.
- Electronics:Semiconductor wafer polishing and substrate preparation. Korean and Taiwanese foundries demand sub-micron particle consistency.
Abrasives dominate current volumes; ceramics are climbing the fastest.
End User:
Customer type determines procurement sophistication, with integrated multinationals bundling technical services while regional players compete on delivered cost.
- Manufacturers:Industrial producers of finished goods across machinery, electronics, and consumer products. Japanese integrated steel mills now unbundle refractory installation from material supply, contracting application engineering separately.
- Construction:Infrastructure and building material producers. Demand concentrates in cement kiln lining refurbishment.
- Automotive:OEMs and tier suppliers requiring precision finishing for powertrain components. German transmission manufacturers specify grain toughness for gear grinding operations.
- Aerospace:Engine and airframe producers with stringent certification requirements. Turbine blade tolerances below 5 microns exclude standard-grade suppliers.
Manufacturers represent the broadest base; aerospace commands the steepest expansion trajectory.
Form:
Supply concentration in Henan province's Zhengzhou cluster shapes availability across form factors, with micronized powders requiring additional classification investment.
- Fused Aggregate:Crushed and sized raw material for further processing. Captive consumption dominates within vertically integrated refractory producers.
- Bulk Material:Unclassified shipments for large-scale refractory manufacture. Chinese exports face margin pressure from emission compliance costs.
- Micronized Powder:Sub-45 micron material for precision applications. Binder jet and selective laser sintering of alumina ceramics require narrow particle distribution feeds.
- Refractory Mixes:Pre-blended formulations with binders and additives. Steel mill procurement teams source through commodity tenders while retaining technical risk with service specialists.
Bulk material anchors volume; micronized powder gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in aerospace and precision electronics show minimal price elasticity, while commodity refractory purchasers in construction and bulk steelmaking remain highly sensitive to delivered cost fluctuations.
China
Henan province's Zhengzhou industrial cluster concentrates over sixty percent of global fused alumina capacity, with feedstock bauxite refining and smelting operations co-located. The Ministry of Ecology and Environment enforces emissions caps on smelters, forcing electric-arc furnace retrofits and captive renewable energy investments. Shandong province faces parallel MEE enforcement, redirecting export-grade supply flows toward domestic electric-arc furnace steelmaking demand.
Germany
Integrated steel mills in the Ruhr region now bundle refractory refurbishment services with powder procurement, pulling margin downstream from commodity sales. REACH registration requirements through ECHA constrain import pathways for uncharacterized powder formulations. Bavarian precision abrasive manufacturers drive specification-grade demand for automotive powertrain finishing applications.
United States
The EPA's National Emission Standards for Hazardous Air Pollutants shape producer investment in baghouse and scrubber retrofits across Appalachian and Midwestern operations. Aerospace turbine manufacturers in the Southeast specify plasma-sprayed alumina for thermal barrier coatings. Texas and Louisiana host refractory service specialists unbundling technical risk retention from material supply contracts.
Japan
Japanese integrated mills pioneered the separation of refractory installation and technical troubleshooting from raw material contracts. METI industrial standards enforce stringent grain toughness specifications for automotive camshaft and transmission gear grinding. The Chubu region around Nagoya anchors precision abrasive tool manufacturing for export markets.
India
BIS certification requirements for steel plant linings create local specification-grade production incentives for domestic fused alumina investment. Maharashtra and Gujarat host emerging refractory manufacturers targeting import substitution for integrated mill procurement. The country's national steel policy directs capacity expansion toward electric-arc furnace routes, amplifying demand for refractory-grade powders.
White Fused Alumina Market Competitive Environment
Vertically integrated multinationals and regional specialists split the market along specification-grade versus commodity-grade fault lines. Three to four global players control premium-tier supply for aerospace and semiconductor applications, while Chinese provincial producers dominate standard-grade bulk refractory volumes. Strategic archetypes include captive-resource smelters with upstream bauxite control, precision processors with advanced classification capabilities, and service-integrated refractory specialists bundling technical application support. Capacity expansion and portfolio diversification toward ceramic matrix composite feedstocks represent the dominant competitive moves.
Within the captive-resource tier, Rusal anchors positions through Siberian alumina refining capacity insulating against feedstock volatility. Imerys exemplifies the vertically integrated archetype, controlling input costs across European bauxite-to-refractory pipelines. Saint-Gobain occupies the precision-specialist position, with naming conventions suggesting French origin and focused expertise in controlled-friability applications.
| Leading Market Players |
|---|
| Imerys |
| Rusal |
| Washington Mills |
| Zhengzhou Yufa Group |
| Saint-Gobain |
| Almatis |
| Norton Abrasives |
| Hindalco Industries Limited |
| MOTIM Electrocorundum |
| Others |
Value Chain & Pricing Dynamics
Zhengzhou-Hamburg container freight corridors transmit emission-compliance cost surges from Henan smelters directly into European abrasive pricing spreads, amplifying divergence between specification-grade premiums and commodity-grade compression while rewarding precision processors with captive renewable energy.
Pricing Analysis
After-sales technical support contracts now generate lifetime value multiples exceeding raw material sales for refractory specialists serving Japanese integrated steel mills. Three-tier pricing structure across premium, standard, and economy levels stratifies by grain toughness certification and friability control, with aerospace blade finishers showing minimal price elasticity below 5-micron tolerances. Cost compression in standard refractory grades intensifies from Chinese oversupply and MEE enforcement capex pass-through. Commodity refractory purchasers in construction and bulk steelmaking exhibit highest price sensitivity, while semiconductor foundries and turbine manufacturers absorb premium tiers without volume reduction.
Supply Chain Analysis
Extended payment terms from Zhengzhou trading houses to European distributors mask working capital strain from baghouse retrofit cycles and renewable energy certificates. Supply concentrates in China, Germany, and Japan, with raw material flows drawing from Guizhou bauxite deposits, Siberian alumina refineries, and captive calcination facilities. Single-source vulnerability concentrates in Henan province's Zhengzhou cluster where over sixty percent of global capacity faces regional power rationing risk. Distribution runs through vertically integrated refractory specialists bundling technical risk retention with material supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized electric-arc furnace engineering expertise is retiring faster than apprenticeship pipelines replenish, constraining smelter retrofit execution and creating asymmetric advantage for operators with captive technical talent.
For Market Incumbents: Build certification moats around REACH-registered nano-powder formulations before ECHA deadlines consolidate import channels. Deepen captive bauxite control through Shanxi province offtake agreements to insulate against calcined alumina margin squeeze. Defend against precision-classification entrants by accelerating air-jet and electrostatic separation capex in French and Japanese aerospace supply chains. For New Entrants and Emerging Players: Build out micronized powder classification capabilities targeting India's BIS-certified refractory import substitution, where Maharashtra and Gujarat steel mill procurement creates specification-grade entry points. Capture additive manufacturing feedstock demand from binder jet and selective laser sintering ceramic processors requiring narrow particle distribution curves. Lead with technical application support contracts unbundled from commodity supply, mirroring Japanese integrated mill procurement patterns. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded fused alumina assets lacking REACH compliance or precision-classification infrastructure. Long-term viability hinges on decarbonization verification for EU carbon border adjustment mechanism eligibility. Watch for MEE enforcement waves triggering distressed capacity availability in Henan and Shandong as inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Refining | Rusal's Siberian captive supply insulates against Guizhou price volatility. |
| Precision Grain Sizing Capacity Expansion | Saint-Gobain's aerospace turbine blade tolerances command premium pricing tiers. |
| REACH Registration Compliance Program | ECHA characterization requirements consolidate European import channels toward registered suppliers. |
| Refractory Refurbishment Service Unbundling | Imerys bundles technical risk retention with powder procurement in German steel mills. |
| Renewable Energy Certificate Procurement | Henan smelters redirect export-grade supply toward domestic electric-arc furnace demand. |
Study Parameters
Desk research of customs trade databases, SEC 10-K filings, and ECHA registration records preceded structured interviews with fused alumina plant managers, refractory procurement leads at German and Japanese steel mills, aerospace turbine blade finishers, and technical R&D directors at precision abrasive manufacturers. Bottom-up capacity modeling triangulated against top-down demand segmentation across grain toughness grades and application specifications.
Assumptions held fixed include MEE enforcement timelines, REACH registration deadlines, and EU carbon border adjustment mechanism phase-in schedules, while bauxite refining margins and renewable energy penetration rates varied across the analysis window. Segmentation dimensions modeled encompass product type, application tier, end-user procurement sophistication, and regional production hub classification. CAGRs derived from installed capacity utilization trajectories and substitution elasticity estimates for ceramic matrix composites in turbine hot sections.
Sensitivities concentrate around MEE emission cap stringency, ECHA nano-powder characterization guidance evolution, and integrated steel mill unbundling adoption rates across the analysis window. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Saudi Arabia Ceramic Tiles Market
Ceramics
Japan Ceramic Tiles Market
Ceramics
India Kaolin Market
Ceramics
Global Ceramic and Porcelain Tiles Market
Ceramics
Global Thermal Ceramics Market
Ceramics
Fire Clay Market
Ceramics
Optical Ceramics Market
Ceramics
Potassium Silicate Market
Ceramics
2N High Purity Alumina Market
Ceramics
China Ceramic Tiles Market
Ceramics
Cement Castables Market
Ceramics
Global Zirconia Oxygen Sensors Market
Ceramics
Ceramic Proppant Market
Ceramics
Ceramic Fabrication Services Market
Ceramics
Ball Clay Market
Ceramics
Global Magnesium Silicate Market