
 Titanium Carbide Market | 2026-2036
Titanium Carbide Market Size, Share, and Industry Trends Forecast 2026-2036
Titanium Carbide Market Analytics
Direct supply relationships between carbide producers and cutting-tool OEMs is tilting away from layered distributors. H.C. Starck GmbH leverages its European refining footprint to sustain long-term contracts with German precision-tool manufacturers. Changsha Langfeng Metallic Material anchors Chinese domestic supply for mining-grade compacts. Sandvik AB competes through captive powder-to-tool integration across Scandinavian and Asian facilities.
Titanium carbide denotes a binary ceramic compound with a face-centered cubic crystal structure, melting point near 3,160°C, and exceptional hardness that positions it as a reinforcement phase in cemented carbides and thermal barrier coatings. Coatings command the widest aerospace adoption due to oxidation resistance at turbine operating temperatures, while Powders concentrate margin pools where sub-micron particle control differentiates suppliers. Cutting Tools represents the most structurally entrenched application segment, though Ceramics is expanding fastest as semiconductor fabrication equipment demands erosion-resistant chamber components.
REACH compliance in Europe restricts hexavalent chromium in surface-finishing processes, pushing carbide coaters toward vacuum deposition alternatives. China's SAMR enforces GB standards on tungsten-titanium carbide classifications that affect import eligibility and domestic pricing bands. The US FAA maintains material qualification protocols for engine-component coatings that extend approval timelines. Stakeholders must monitor how dual carbon goals in Beijing and Brussels reshape energy-intensive carbide reduction furnace operations.
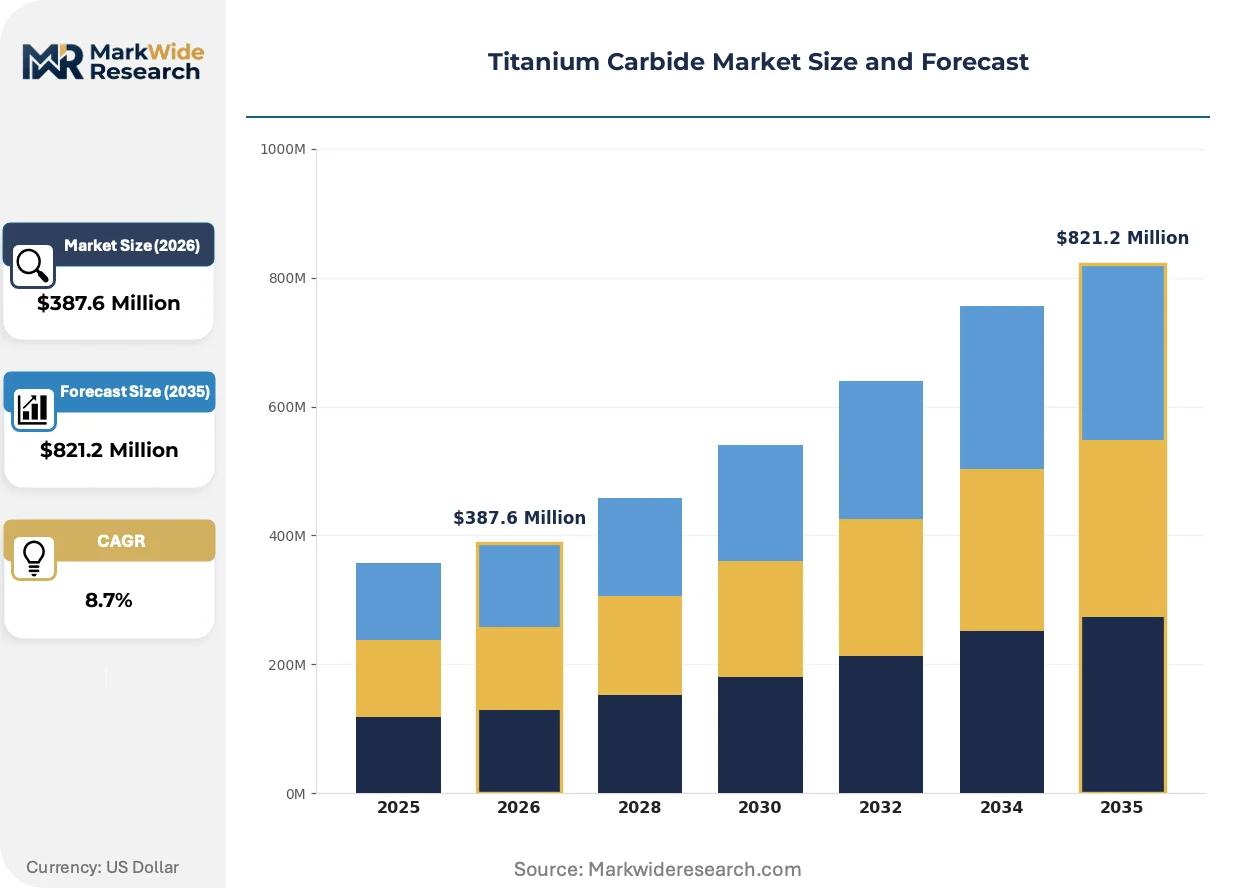
Market Dynamics
Direct supply relationships between carbide producers and cutting-tool OEMs are tilting away from layered distributors, compressing margin capture for intermediaries while rewarding integrated powder-to-tool manufacturers with captive refining capabilities.
Growth Catalysts
- REACH compliance in Europe:Restrictions on hexavalent chromium in surface-finishing processes push carbide coaters toward vacuum deposition alternatives, expanding addressable market for compliant suppliers.
- Aerospace turbine blade coatings:Engine OEMs pursuing higher operating temperatures drive specification upgrades toward oxidation-resistant TiC thermal barrier systems.
- Sub-micron particle control:Mining-grade compacts in China anchor domestic demand as GB standards tighten purity benchmarks and redirect procurement toward certified suppliers.
Market Restraints
- Tungsten price volatility:Raw material input costs fluctuate with concentrate supply from primary mining regions, squeezing margin stability for non-integrated producers.
- Supply concentration in Japan and Germany:Specialty tool-grade demand concentrates in two manufacturing clusters, creating geographic dependency risk for buyers.
- Ceramic matrix composite substitution:Silicon carbide fiber-reinforced systems displace TiC in select high-temperature aerospace applications above 1,400°C.
Strategic Opportunities
- Semiconductor fabrication equipment:Erosion-resistant chamber components represent the fastest-expanding application vertical as wafer processing node sizes shrink.
- Dual carbon goals in Beijing:Energy-intensive carbide reduction furnace operations face restructuring incentives, creating first-mover advantage for electrified production investments.
- Direct-to-OEM powder contracting:Tool manufacturers bypass distributor tiers to secure long-term supply agreements with certified refiners.
Industry Challenges
- FAA material qualification protocols:Approval timelines for engine-component coatings extend development cycles and delay revenue recognition for aerospace suppliers.
- Sub-micron particle engineering talent:Specialized powder metallurgy expertise concentrates in legacy industrial regions, constraining expansion for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Titanium Carbide Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Powders, Compacts, Tools Application: Cutting Tools, Wear Parts, Abrasives, Ceramics End User: Aerospace, Automotive, Mining, Manufacturing Form: Granules, Pellets, Paste, Thin Films |
| Companies Covered | DAAO Industry, Changsha Langfeng Metallic Material, H.C. Starck GmbH, Western Minmetals (SC) Corporation, ZhuZhou GuangYuan Cemented Material, Materion Corporation, Chengdu Nuclear 857 New Materials, Sandvik AB, Micron Metals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Titanium Carbide Market Evolving Landscape
Process intensification in thermal spray deposition and powder synthesis is compressing cost curves while elevating performance specifications across aerospace and precision tooling verticals.
Plasma-enhanced chemical vapor deposition is hybridizing with conventional atmospheric plasma spray systems to produce functionally graded TiC coatings with superior adhesion and thermal cycling resistance. Aerospace maintenance, repair, and overhaul facilities in Germany and Japan are retrofitting existing lines to accommodate hybrid equipment. This convergence is compressing the performance gap between premium electron-beam physical vapor deposition and mid-tier atmospheric spray, reshaping tiered supplier positioning.
China's SAMR enforcement of GB standards on tungsten-titanium carbide classifications affects import eligibility and domestic pricing bands, forcing non-certified foreign suppliers to establish local joint ventures or exit the market. Domestic producers with in-house analytical certification capabilities capture displaced import volume. The mining-grade compact segment bears the greatest compliance burden as purity documentation requirements intensify.
Long-term contracting is displacing spot purchasing for sub-micron tool-grade powders as cutting-tool OEMs secure supply continuity against concentrate market volatility. German precision-tool manufacturers lead this behavioral shift, locking in multi-year agreements with European refiners. Japanese semiconductor equipment makers are replicating this model for chamber component feedstocks, consolidating procurement around vertically integrated suppliers with captive powder production.
Titanium Carbide Market Segmentation
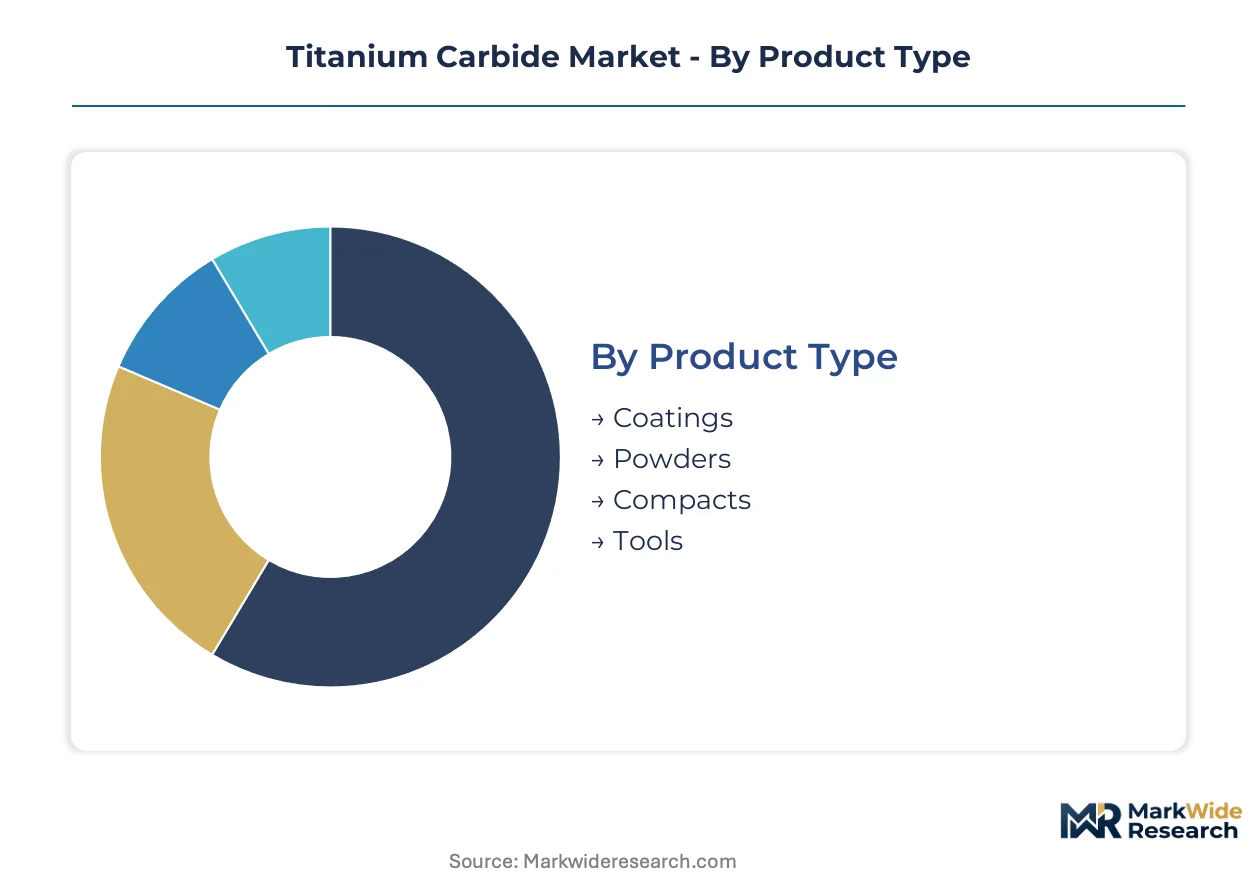
Titanium carbide market segmentation reveals distinct service intensity profiles across product tiers. Coatings demand intensive application engineering support, while powder supply relationships center on analytical certification and long-term volume commitments.
Product Type:
After-sales service intensity varies sharply across product categories, with coatings requiring field application engineering and powders demanding analytical certification support.
- Coatings:Thermal spray and CVD-deposited layers serve aerospace turbine blade protection and cutting tool surface enhancement. German MRO facilities and Japanese engine component shops drive specification tightening toward functionally graded architectures. REACH compliance in Europe accelerates vacuum deposition adoption over hexavalent chromium processes.
- Powders:Sub-micron spherical and angular grades feed cemented carbide production and additive manufacturing feedstocks. Chinese GB standards enforcement redirects procurement toward certified domestic suppliers with in-house analytical capabilities. Long-term contracting displaces spot purchasing as tool OEMs secure supply continuity.
- Compacts:Mining-grade button inserts and wear-resistant components anchor demand from extraction equipment manufacturers.
- Tools:Finished cutting inserts and drilling systems represent captive consumption by integrated manufacturers.
Coatings hold the largest share; momentum sits with powders.
Application:
Cost tier differentiation separates premium aerospace-qualified systems from standard industrial grades, with certification burden driving margin stratification.
- Cutting Tools:Indexable inserts and solid carbide endmills consume the majority of tool-grade powder supply. German precision-tool manufacturers and Japanese cutting-tool OEMs concentrate demand through direct refiner relationships. FAA material qualification protocols extend development cycles for aerospace-facing suppliers.
- Ceramics:Semiconductor fabrication equipment chamber components represent the steepest expansion trajectory as wafer processing node sizes shrink. Plasma etch resistance requirements drive specification toward ultra-high-purity grades. Japanese semiconductor equipment makers consolidate procurement around vertically integrated suppliers.
- Wear Parts:Mining extraction tools and industrial machinery components prioritize fracture toughness over extreme hardness.
- Abrasives:Grinding wheels and polishing compounds serve precision finishing applications in automotive and bearing manufacturing.
Cutting tools command the revenue base; ceramics is climbing the fastest.
End User:
Customer type determines procurement sophistication, with aerospace and automotive OEMs imposing qualification protocols that distributor-dependent suppliers cannot satisfy.
- Aerospace:Engine OEMs and tier-one component suppliers specify oxidation-resistant thermal barrier systems for turbine hot-section components. Dual carbon goals in Beijing and Brussels reshape energy-intensive carbide reduction furnace operations. Plasma-enhanced CVD hybrid systems gain traction for superior adhesion and thermal cycling resistance.
- Mining:Extraction equipment manufacturers anchor Chinese domestic demand through mining-grade compact procurement. Changsha Langfeng Metallic Material and similar certified suppliers capture volume as GB standards tighten purity benchmarks.
- Automotive:Powertrain and transmission component manufacturers drive wear-part specifications toward cost-optimized performance.
- Manufacturing:General industrial machinery and tooling shops represent fragmented, price-sensitive demand.
Aerospace generates premium pricing; mining provides volume stability.
Form:
Supply concentration in granule and pellet production creates dependency on legacy powder metallurgy expertise concentrated in Germany and Japan.
- Granules:Free-flowing spherical particles serve thermal spray feedstock and powder metallurgy compaction. Sub-micron particle engineering talent constraints limit expansion for new market entrants. H.C. Starck GmbH leverages European refining footprint to sustain long-term aerospace contracts.
- Thin Films:Sputtering targets and CVD precursors enable precision coating deposition for semiconductor and optical applications. Sandvik AB competes through captive powder-to-tool integration across Scandinavian and Asian facilities.
- Pellets:Compacted preforms facilitate handling and metering in automated thermal spray operations.
- Paste:Binder-containing suspensions support screen printing and dip coating of complex geometries.
Granules dominate industrial volume; thin films capture the highest value per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in specialty carbide distribution, while China's coastal port infrastructure enables concentrated raw material throughput for domestic reduction furnace operations.
Germany
Precision-tool manufacturers in the Stuttgart and Solingen clusters drive specification-grade powder demand through direct refiner relationships. REACH compliance accelerates vacuum deposition adoption across surface-finishing operations. Bavaria's industrial corridor hosts captive powder-to-tool integration facilities serving aerospace maintenance contracts.
China
Mining-grade compact procurement anchors domestic volume as GB standards enforcement redirects import eligibility toward certified suppliers. SAMR purity documentation requirements intensify compliance burdens for non-certified foreign producers. Changsha's cemented carbide district concentrates analytical certification capabilities that capture displaced import volume.
Japan
Semiconductor equipment makers consolidate procurement around vertically integrated suppliers for erosion-resistant chamber components. METI industrial standards govern sub-micron particle specifications for wafer processing applications. The Nagoya-Tokyo manufacturing belt concentrates plasma etch resistance engineering talent.
United States
Engine OEMs pursuing higher operating temperatures drive FAA material qualification protocols for thermal barrier coating systems. The FAA approval timelines extend development cycles for aerospace-facing suppliers. Texas and Ohio industrial corridors host turbine component shops retrofitting hybrid plasma deposition lines.
Sweden
Scandinavian facilities compete through captive powder-to-tool integration across cutting insert manufacturing. The country's dual carbon alignment pressures energy-intensive reduction furnace operations toward electrification investments. Sandviken's precision materials cluster sustains long-term aerospace supply contracts.
Titanium Carbide Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in powder and coating supply. The vendor base stratifies between integrated manufacturers with captive refining and independent powder merchants dependent on concentrate spot markets. Three archetypes dominate: European precision refiners with aerospace qualification heritage, Chinese domestic suppliers with GB certification leverage, and Scandinavian tool-makers with backward integration into powder production. Competitive moves center on direct-to-OEM contracting displacement of distributor tiers and electrified furnace investments under dual carbon restructuring incentives.
Among German-based refiners, H.C. Starck GmbH occupies a position exemplifying European aerospace qualification heritage, while Sandvik AB anchors Scandinavian captive integration capabilities. Changsha Langfeng Metallic Material represents Chinese domestic suppliers capturing volume through GB certification compliance. These three entities illustrate the geographic specialization pattern where regulatory proximity and infrastructure access determine competitive positioning.
| Leading Market Players |
|---|
| DAAO Industry |
| Changsha Langfeng Metallic Material |
| H.C. Starck GmbH |
| Western Minmetals (SC) Corporation |
| ZhuZhou GuangYuan Cemented Material |
| Materion Corporation |
| Chengdu Nuclear 857 New Materials |
| Sandvik AB |
| Micron Metals |
| Others |
Value Network & Pricing Analysis
Changsha's cemented carbide district concentrates analytical certification capabilities that capture displaced import volume, translating upstream capacity control into pricing leverage over mining-grade compact procurement. GB standards enforcement redirects procurement toward certified suppliers, compressing margin pools for non-compliant foreign producers while rewarding domestic refiners with captive analytical infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified coatings from industrial tool-grade powders and mining compacts. Price differentiation rests on sub-micron particle certification and REACH compliance status, with German precision-tool manufacturers locking in long-term contracts to insulate against tungsten concentrate volatility. Cost compression in economy-tier mining compacts intensifies because Changsha's certified suppliers capture volume from displaced imports. Mining equipment OEMs exhibit highest price sensitivity, while Japanese semiconductor equipment makers accept premium positioning for erosion-resistant chamber component feedstocks.
Supply Chain Analysis
Tariff exposure between China and Germany dominates supply chain risk as specialty tool-grade demand concentrates in Stuttgart and Solingen clusters. Raw material flows draw from tungsten concentrate sources, titanium sponge reduction operations, and sub-micron powder engineering capacity anchored in Germany, Japan, and China. Single-source vulnerability concentrates in legacy powder metallurgy expertise regions, constraining expansion for new market entrants. Distribution runs through direct refiner-to-OEM relationships that displace layered distributor tiers, compressing margin capture for intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The titanium carbide market sits in early-cycle recovery as aerospace turbine blade coating specifications tighten and semiconductor fabrication equipment demand accelerates. Engine OEMs pursuing higher operating temperatures and wafer processing node shrinkage provide synchronized cyclical uplift.
For Market Incumbents: Entrench captive powder-to-tool integration across Scandinavian and Asian facilities to defend against ceramic matrix composite substitution above 1,400°C. H.C. Starck GmbH's European refining footprint exemplifies the aerospace qualification heritage lever that sustains long-term German precision-tool contracts. Electrified reduction furnace investments under Beijing's dual carbon goals create first-mover advantage for integrated producers with energy-intensive operations restructuring capacity. For New Entrants and Emerging Players: Pursue semiconductor fabrication equipment chamber components as the most penetrable vertical, where Japanese equipment makers consolidate procurement around vertically integrated suppliers with captive powder production. Plasma etch resistance requirements for shrinking wafer processing nodes create specification entry points for certified analytical capabilities. A go-to-market angle anchored in GB standards compliance for Chinese domestic mining-grade compact procurement captures displaced import volume from non-certified foreign suppliers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors European precision refiners with aerospace qualification heritage and captive analytical certification infrastructure. Long-term viability across the 5-10 year window hinges on electrified furnace asset bases and direct-to-OEM contracting relationships that displace distributor tiers. The signal to watch is FAA material qualification protocol approval velocity for thermal barrier coating systems, which indicates aerospace revenue recognition timing for supplier portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Refining | Captive sub-micron particle control insulates Sandvik AB against tungsten concentrate spot market volatility. |
| Electrified Reduction Furnace Investment | Dual carbon restructuring incentives in Beijing reward first-movers with compliant energy-intensive carbide operations. |
| GB Standards Certification Acquisition | Changsha Langfeng Metallic Material captures displaced import volume through SAMR purity documentation compliance. |
| Direct-to-OEM Long-term Contracting | German precision-tool manufacturers lock in multi-year supply agreements that bypass distributor margin extraction. |
| Hybrid Plasma Deposition Line Retrofit | German MRO facilities accommodate plasma-enhanced CVD systems for functionally graded aerospace coating specifications. |
Research Methodology
Desk research of trade customs data, SEC filings from powder metallurgy specialists, and SAMR regulatory bulletins preceded structured interviews with carbide refinery plant managers, cutting-tool OEM procurement leads, aerospace coating application engineers, and semiconductor equipment chamber component designers. Primary fieldwork with distribution channel partners and technical R&D directors at cemented carbide producers validated secondary intelligence from ECHA REACH compliance databases and FAA material qualification protocols. Bottom-up volume modeling across product tiers triangulated against top-down end-use industry demand aggregation.
Assumptions held tungsten concentrate supply volatility and dual carbon policy implementation pace as fixed boundary conditions, while varying aerospace engine temperature specification trajectories and semiconductor node shrinkage rates across sensitivity scenarios. Segmentation dimensions spanned product type, application vertical, end-user industry, and regional production hub concentration. CAGRs derived from logistic curve fitting to historical volume patterns and elasticity-adjusted demand projections. Industry-specific inputs included plasma etch resistance specification tightening and GB standards enforcement timelines.
Sensitivities concentrate around FAA approval velocity for thermal barrier coatings, ceramic matrix composite substitution thresholds above 1,400°C, and SAMR certification enforcement intensity for tungsten-titanium carbide classifications. Forecasts reflect documented assumptions regarding aerospace OEM specification upgrade cadence and mining equipment procurement cyclicality. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
East Africa Ceramic Tiles Market
Ceramics
Ceramic Substrate Market
Ceramics
Calcined Kaolin Market
Ceramics
Glazed Ceramic Tile Market
Ceramics
Controlled Pore Metal Oxide Market
Ceramics
Activated Alumina Market
Ceramics
Solid-Ion Conductors Market
Ceramics
Global Industrial Clay Market
Ceramics
Refractories Market
Ceramics
Global Ceramic Tube Market
Ceramics
US Kaolin Market
Ceramics
Global Ceramic Coating Market
Ceramics
Ceramic Binders Market
Ceramics
Clay Market
Ceramics
Global Wollastonite Powder Market
Ceramics
Advanced Ceramic Additives Market