
 Ceramic Armor Materials Market | 2026-2036
Ceramic Armor Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Armor Materials Market Analysis
China is reconfiguring ceramic armor supply chains through expanded domestic sintering capacity and state-backed materials science institutes. Morgan Advanced Materials leverages its alumina and silicon carbide expertise to anchor European defense contracts. CoorsTek Inc. sustains vertically integrated production from powder synthesis to finished plates, dominating North American military procurement. CeramTec GmbH competes on precision-engineered boron carbide solutions for vehicle armor applications.
Ceramic armor materials are high-hardness, low-density ceramics—primarily alumina, silicon carbide, and boron carbide—engineered to fracture and deflect ballistic projectiles through controlled microcracking at hardness values exceeding 2,500 HV. These materials serve military, law enforcement, and private security end users requiring protection against armor-piercing threats while minimizing weight penalties. Boron carbide commands premium positioning due to its superior hardness-to-density ratio for helicopter and maritime platforms where every kilogram determines operational range. Silicon carbide occupies the fastest-growing material tier as manufacturing scale reduces unit costs for ground vehicle integration. Ballistic plates generate the deepest margin pools, while helmets and shields represent emerging volume segments driven by law enforcement modernization.
NIJ ballistic resistance standards in the United States, NATO STANAG 4569 for vehicle protection, and China's GJB military specifications collectively shape product certification requirements and cross-border market access. The EU Green Deal's embodied carbon tracking is forcing European suppliers to document energy-intensive sintering emissions or risk exclusion from public procurement. Stakeholders must monitor how export control expansions under ITAR and emerging dual-use classifications reshape supply relationships between Western and Asian ceramic armor producers.
Market Dynamics
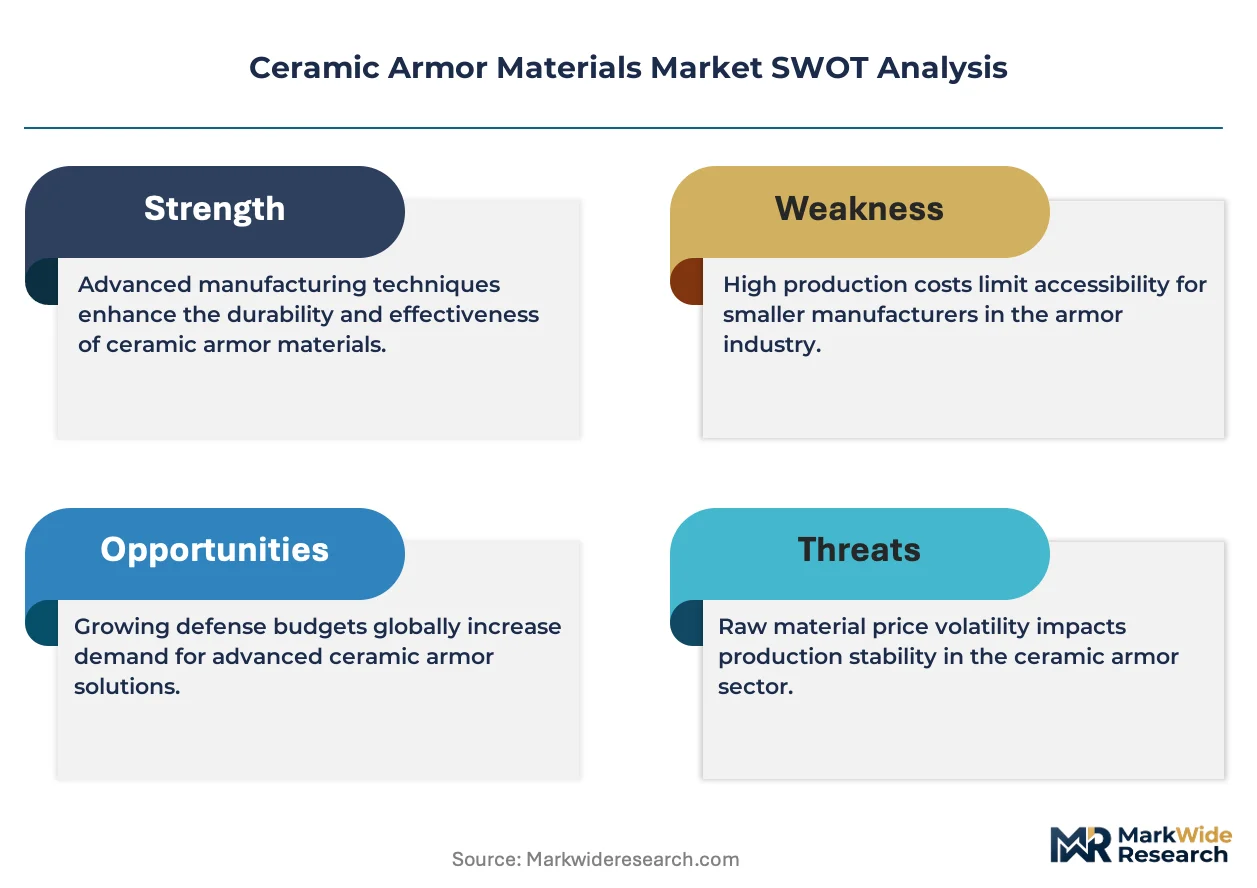
Defense procurement agencies are consolidating supplier bases around certified domestic sintering capacity, compressing the viable vendor pool while elevating technical qualification barriers for new entrants into military ceramic armor supply chains.
Growth Catalysts
- ITAR-controlled domestic sourcing mandates:United States military procurement rules now require armor plate fabrication within ITAR-compliant facilities, redirecting contract flows toward domestic powder synthesis and hot pressing operations.
- Silicon carbide composite densification:Advances in reaction-bonded silicon carbide manufacturing are lowering unit costs for ground vehicle armor integration without sacrificing multi-hit ballistic performance against armor-piercing threats.
- Helicopter platform weight constraints:Maritime and rotary-wing operators in Germany and France are specifying boron carbide for crew protection systems where every kilogram reduction extends operational range.
Market Restraints
- Boron carbide feedstock concentration:Over eighty percent of metallurgical-grade boron reserves and processing capacity sits within a single Central Asian supplier geography, exposing armor manufacturers to geopolitical supply interruptions.
- Energy-intensive sintering economics:Hot isostatic pressing and pressureless sintering operations consume electricity-intensive thermal cycles, making European producers vulnerable to carbon border adjustment mechanisms under EU Green Deal embodied carbon tracking.
- Polymer-matrix composite substitution:Ultra-high molecular weight polyethylene laminates are capturing segments of law enforcement and private security demand where threat levels permit lower areal density solutions at reduced cost.
Strategic Opportunities
- Law enforcement helmet modernization:Municipal police departments across the United States are replacing legacy Kevlar helmets with ceramic-composite hybrid systems rated for rifle threats, opening volume segments outside traditional military procurement.
- EU Green Deal carbon documentation:Early compliance with embodied carbon disclosure requirements positions European suppliers for preferential access to NATO STANAG 4569 vehicle armor contracts as environmental criteria integrate into technical evaluations.
- Additive manufacturing convergence:Binder jet printing of silicon carbide preforms combined with reactive melt infiltration is enabling complex-curve plate geometries previously unattainable through conventional pressing, reducing machining waste for custom vehicle integration.
Industry Challenges
- NIJ certification timeline compression:Third-party ballistic testing protocols for body armor require six-to-twelve month validation cycles, delaying product launches and tying up working capital in pre-certified inventory.
- Hot isostatic pressing equipment scarcity:The specialized high-pressure argon vessels required for full-density boron carbide densification face eighteen-month lead times from a concentrated base of European and Japanese equipment fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Armor Materials Market |
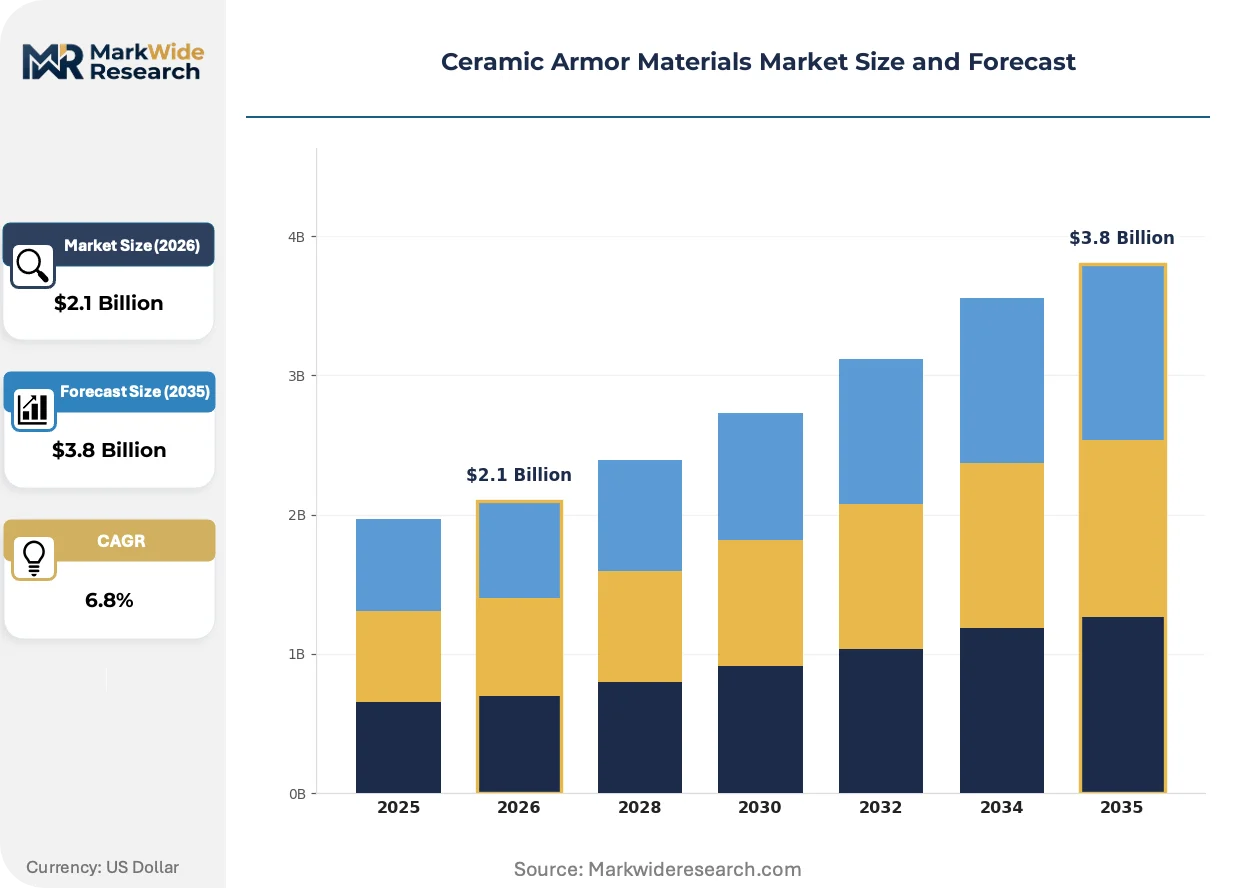
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballistic Plates, Helmets, Vests, Shields Material: Alumina, Silicon Carbide, Boron Carbide, Titanium Dioxide End User: Military, Law Enforcement, Civilian, Private Security Deployment: Onshore, Offshore, Vehicles, Personal Use |
| Companies Covered | Morgan Advanced Materials, BAE Systems, CeramTec GmbH, DuPont, ArmorWorks Enterprises, LLC, CoorsTek Inc., Saint-Gobain, MKU Limited, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Armor Materials Market Emerging Trajectories
Process control technologies are penetrating ceramic armor manufacturing at unprecedented depth, linking powder characterization to finished plate ballistics through sensor-integrated production lines that compress variation and accelerate qualification cycles.
Reaction-bonded silicon carbide is digitizing quality assurance workflows through in-line acoustic emission monitoring during densification. United States ground vehicle integrators are specifying these sensor-validated plates for next-generation combat vehicle side armor. Real-time fracture detection during processing is compressing the rejection rate for multi-hit certification lots.
EU Green Deal embodied carbon tracking is forcing sintering operations to document Scope 2 emissions from thermal processing or risk exclusion from public procurement pools. German and French armor fabricators are investing in renewable-powered hot pressing to maintain NATO contract eligibility. The regulatory pressure is bifurcating the supplier base between carbon-documented and undocumented producers.
United States military procurement is consolidating contract awards around sole-source relationships with vertically integrated powder-to-plate manufacturers. Small and mid-tier armor integrators are losing access to prime contractor supply chains as technical qualification costs rise. The concentration is most visible in body armor programs where the Army's Soldier Protection System has reduced qualified vendors to a handful of domestic sintering operations.
Ceramic Armor Materials Market Segmentation
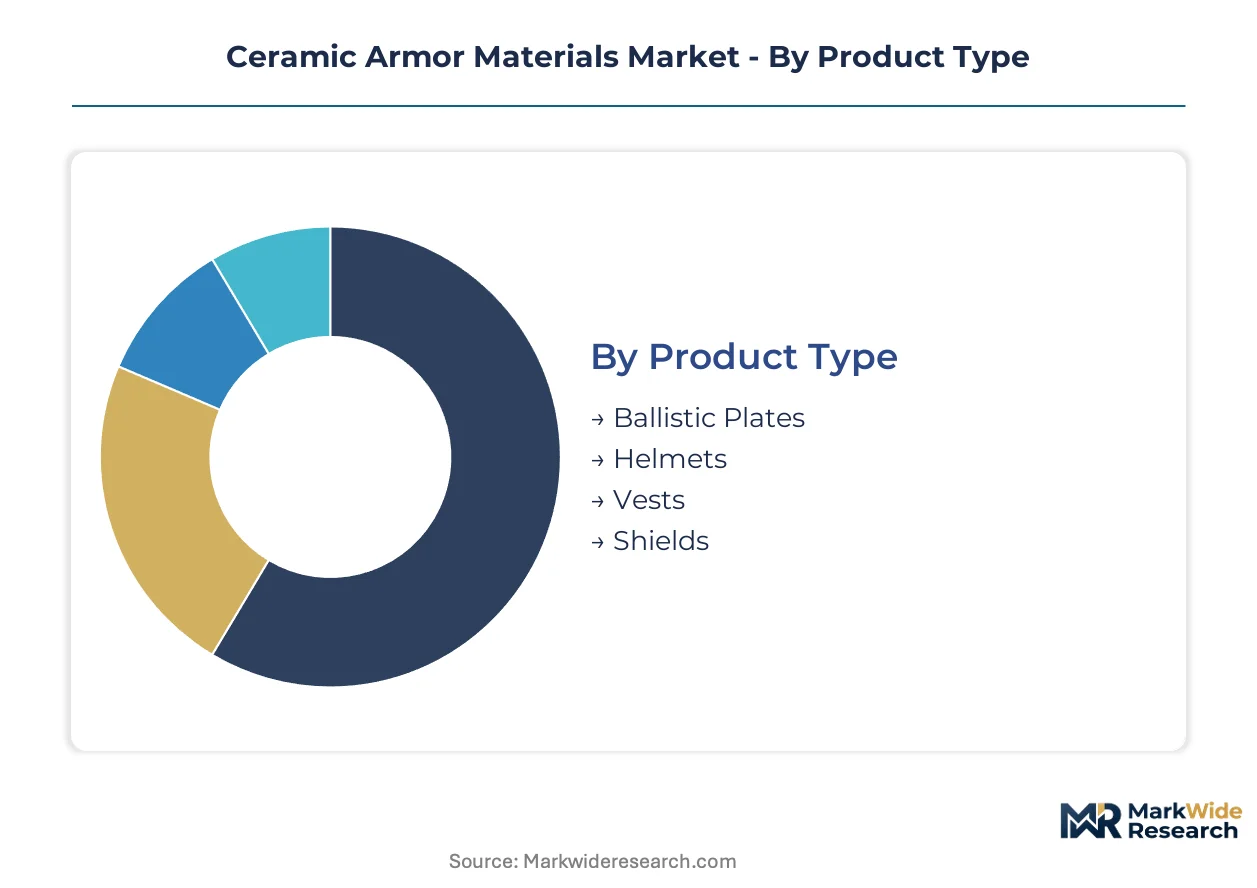
Ceramic armor procurement cycles vary dramatically by application—ballistic plates refresh on multi-year military contracts while personal helmets turn over through annual municipal budgets. Understanding these velocity differentials shapes inventory positioning and qualification investment priorities for suppliers.
Product Type:
Replacement cycles stretch from months for shields used in training to decades for vehicle-integrated plates, creating divergent margin and working capital profiles across the category.
- Ballistic Plates:Multi-curve ceramic composite panels engineered for rifle-rated protection against armor-piercing threats. United States Army Soldier Protection System procurement concentrates demand here, with sole-source contracts favoring domestic hot-pressed silicon carbide suppliers.
- Helmets:Molded ceramic-composite shells with aramid backing for fragmentation and ballistic protection. Law enforcement modernization across United States municipal departments is accelerating volume as departments replace legacy Kevlar systems.
- Vests:Soft armor carriers with optional ceramic rifle plate pockets for flexible threat response. Private security firms in Germany specify modular vest systems for executive protection details requiring discrete profiles.
- Shields:Hand-held or mounted transparent and opaque ceramic barriers for tactical entry teams. Training wear drives replacement frequency higher than operational equipment in most agencies.
Ballistic plates dominate installed base value. Helmets are where expansion concentrates.
Material:
Cost tiers separate boron carbide premium positioning from alumina economy applications, with silicon carbide capturing ground vehicle integration through manufacturing scale.
- Alumina:Aluminum oxide ceramics offering baseline hardness at lowest unit cost for training and secondary protection applications. China's expanded domestic sintering capacity is compressing alumina plate export pricing.
- Silicon Carbide:Reaction-bonded and hot-pressed variants delivering multi-hit performance at intermediate density. United States ground vehicle integrators specify these plates for next-generation combat vehicle side armor programs.
- Boron Carbide:Highest hardness-to-density ratio ceramic for helicopter crew seats and maritime platforms where weight reduction extends operational range. Central Asian feedstock concentration creates supply vulnerability for Western armorers.
- Titanium Dioxide:Emerging ceramic additive for specialized coating and composite matrix applications in signature management systems.
Alumina holds the largest installed base. Silicon carbide is climbing the fastest.
End User:
Customer type determines certification burden—military NIJ and STANAG protocols impose twelve-month validation timelines that law enforcement and private markets rarely require.
- Military:National defense agencies specifying body armor and vehicle protection under ITAR-controlled procurement rules. United States domestic sourcing mandates now require powder-to-plate fabrication within compliant facilities.
- Law Enforcement:Municipal and federal police departments modernizing individual protection equipment. Rifle-rated helmet adoption is accelerating replacement cycles previously measured in decades.
- Civilian:Individual purchasers in jurisdictions permitting personal protective equipment ownership. Demand concentrates in discrete concealable systems rather than overt tactical configurations.
- Private Security:Corporate protection details and high-risk facility operators requiring flexible threat response. German executive protection specialists prioritize weight-minimized boron carbide solutions for extended wear.
Military contracts anchor revenue stability. Law enforcement is gaining share fastest.
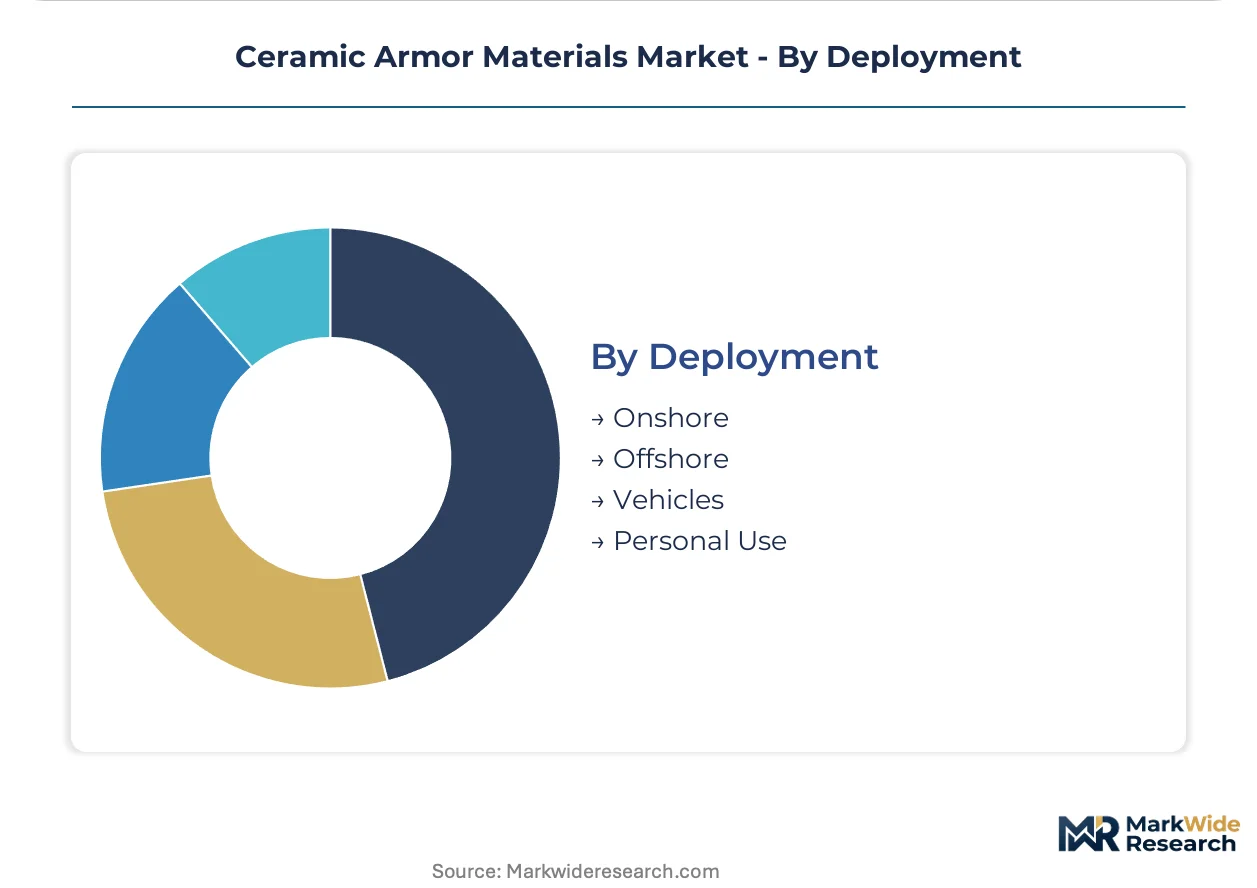
Deployment:
Integration complexity rises from personal carry systems through vehicle appliqué to maritime and offshore platforms requiring environmental sealing.
- Onshore:Ground-based military and security operations across fixed installations and mobile patrol routes. United States continental base operations generate recurring plate replacement demand through training wear.
- Offshore:Maritime platform protection including naval vessels and coastal security craft. Corrosion-resistant packaging specifications add engineering complexity for salt-environment durability.
- Vehicles:Appliqué and integrated armor for ground combat vehicles, helicopters, and transport aircraft. France and Germany specify boron carbide for rotary-wing crew protection to maximize payload-range tradeoffs.
- Personal Use:Individual-worn systems for bodyguards, journalists, and private citizens in high-threat environments. Concealability requirements favor thin-profile ceramic composites over traditional steel.
Vehicle integration commands the deepest margin pools. Personal use applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ITAR-controlled procurement rules in the United States are redirecting contract flows toward domestic powder synthesis and hot pressing operations, while EU Green Deal embodied carbon tracking forces European suppliers to document energy-intensive sintering emissions.
United States
The Army's Soldier Protection System concentrates demand around sole-source relationships with domestic sintering operations. ITAR mandates now require armor plate fabrication within compliant facilities, compressing the qualified vendor pool. Hot pressing clusters in Colorado and Tennessee anchor military procurement fulfillment.
Germany
Helicopter platform weight constraints drive boron carbide specification for crew protection systems in rotary-wing programs. NATO STANAG 4569 vehicle protection standards shape certification requirements for Bundeswehr contracts. Precision-engineered solutions from Bavaria-based fabricators serve Franco-German defense integration.
China
Expanded domestic sintering capacity and state-backed materials science institutes are reconfiguring regional supply chains. GJB military specifications govern product certification for People's Liberation Army procurement. Yangtze River Delta production bases are scaling alumina plate output for export compression.
France
Maritime and rotary-wing operators specify boron carbide for payload-range optimization in naval aviation programs. EU Green Deal carbon documentation requirements integrate into NATO technical evaluations for vehicle armor contracts. Defense industrial bases in Provence-Alpes-Côte d'Azur cluster around aerospace-armor integration.
United Kingdom
Law enforcement helmet modernization accelerates replacement cycles as municipal departments adopt rifle-rated ceramic-composite systems. UK defense procurement aligns with NATO STANAG standards for interoperability. Midlands-based manufacturing retains legacy alumina capacity for training and secondary protection applications.
Ceramic Armor Materials Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. Vertically integrated powder-to-plate manufacturers capture sole-source military contracts through ITAR compliance and domestic sintering assets. Fragmented mid-tier integrators face exclusion as technical qualification costs rise. Three archetypes dominate: captive-feedstock specialists, precision-engineered solution providers, and diversified materials conglomerates. Consolidation around certified domestic capacity and carbon-documented European production represent the dominant competitive moves.
Among UK-based advanced materials specialists, Morgan Advanced Materials occupies a position anchoring European defense contracts through alumina and silicon carbide expertise. German precision-engineered solution providers include CeramTec GmbH, which exemplifies boron carbide specialization for vehicle armor applications. At the vertically integrated end, CoorsTek Inc. represents captive-feedstock dominance through powder synthesis-to-finished-plate control over North American military procurement flows.
| Leading Market Players |
|---|
| Morgan Advanced Materials |
| BAE Systems |
| CeramTec GmbH |
| DuPont |
| ArmorWorks Enterprises, LLC |
| CoorsTek Inc. |
| Saint-Gobain |
| MKU Limited |
| 3M Company |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific container routes from Shanghai to Long Beach transmit cost volatility directly into landed pricing for boron carbide feedstock, amplifying the spread between ITAR-compliant domestic plates and import-dependent alternatives while compressing margins for non-integrated fabricators.
Pricing Analysis
Geographic price spreads between United States ITAR-compliant production and Asian import alternatives have widened as domestic hot-pressing capacity commands certification premiums. Three-tier pricing structure across premium, standard, and economy levels separates boron carbide helicopter armor from silicon carbide vehicle plates and alumina training systems. Cost compression in alumina segments is intensifying because China's expanded Yangtze River Delta sintering capacity floods export markets. Law enforcement departments exhibit highest price sensitivity through municipal budget constraints, while maritime operators absorbing boron carbide premiums show least elasticity due to payload-range optimization requirements.
Supply Chain Analysis
Metallurgical-grade boron reserves concentrate in Central Asian extraction zones, Chinese powder processing clusters, and limited United States domestic deposits. Ceramic armor production draws from boron carbide feedstock, silicon carbide precursor chemicals, and high-purity alumina powders as primary inputs. Single-source vulnerability pervades hot isostatic pressing equipment, where European and Japanese fabricators maintain eighteen-month order backlogs. Distribution runs through defense prime contractor networks for military procurement, direct municipal contracting for law enforcement, and specialized security distributors for private end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement cyclicality is recovering through sustained Soldier Protection System modernization budgets, with multi-year contract visibility providing anchor demand for qualified suppliers.
For Market Incumbents: Harden sole-source positioning by expanding captive boron carbide feedstock arrangements before Central Asian supply interruptions materialize. Accelerate carbon documentation compliance under EU Green Deal embodied tracking to preempt NATO contract exclusion. ITAR facility certification investments represent the critical defensive lever against mid-tier integrator displacement.
For New Entrants and Emerging Players: Law enforcement helmet modernization across United States municipal departments represents the most penetrable entry point, bypassing military qualification barriers through NIJ Level IIIA certification pathways. Additive manufacturing convergence for silicon carbide preforms offers a differentiated go-to-market angle for custom vehicle integration contracts outside prime contractor supply chains.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated powder-to-plate manufacturers with ITAR-compliant domestic assets and established military contract relationships. Long-term viability over the coming decade rests on sintering capacity scarcity and rising technical qualification costs that protect incumbent returns. Monitor Army Soldier Protection System contract award timing as the critical inflection signal for capacity utilization and pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| ITAR Facility Certification Investment | Army procurement rules now mandate domestic powder-to-plate fabrication, compressing qualified vendor pools. |
| Backward Integration into Boron Feedstock | Central Asian supply concentration creates vulnerability that captive sourcing mitigates for Western armorers. |
| EU Green Deal Carbon Documentation Compliance | German and French NATO contracts now integrate embodied carbon tracking into technical evaluations. |
| Additive Manufacturing Capability Buildout | Binder jet printing of silicon carbide preforms enables complex-curve geometries for custom vehicle integration. |
| Law Enforcement Channel Partnership Expansion | Municipal helmet modernization accelerates replacement cycles outside traditional military procurement cycles. |
Methodological Framework
Cross-validation between defense procurement officer interviews and customs trade data anchors the qualitative findings on supply chain concentration. Primary fieldwork engaged program managers at United States Army PEO Soldier, Bundeswehr procurement officials, and hot pressing equipment fabricators in Germany and Japan. Secondary validation drew from ITAR compliance filings, NATO STANAG 4569 certification records, EU Green Deal embodied carbon disclosures, and SEC 10-K filings from listed advanced materials suppliers. Bottom-up demand modeling across ballistic plate, helmet, and vehicle armor segments was triangulated against top-down defense budget appropriation analysis.
Calibration against historical contract award patterns and production capacity utilization rates shaped the projection framework. Segmentation modeling spanned material type, product configuration, end-user category, and deployment platform across the analysis window. CAGRs were derived from elasticity-adjusted demand curves incorporating military procurement cycle timing, law enforcement budget velocity, and private security penetration rates. Boron carbide feedstock availability constraints and silicon carbide manufacturing scale trajectories served as primary industry-specific forecast inputs.
Practitioners should monitor Army Soldier Protection System contract award delays, Central Asian boron export restrictions, and EU carbon border adjustment implementation timing for early signals requiring forecast revision. Cross-checking against Department of Defense budget justification documents and NATO defense expenditure databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
GCC Ceramic Tiles and Sanitary Ware Market
Ceramics
Carbon-Ceramic Discs Market
Ceramics
Global Wollastonite Powder Market
Ceramics
Glazed Ceramic Tile Market
Ceramics
Earthenware Market
Ceramics
Zirconia Ceramic Balls Market
Ceramics
South Korea Ceramic Sanitaryware Market
Ceramics
Ceramic Ware Market
Ceramics
Magnesia Carbon Bricks Market
Ceramics
Philippines Ceramic Tiles Market
Ceramics
Ceramic Solid End Mills Market
Ceramics
Ceramic Kilns Market
Ceramics
Europe Aluminum Oxide Market
Ceramics
Global Industrial Clay Market
Ceramics
Cerium Nitride Market
Ceramics
Egypt Ceramic Tiles Market