
 Global Barium Carbonate Market | 2026-2036
Global Barium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Barium Carbonate Market Foresight
The split between high-purity electronic-grade material and standard industrial-grade supply is hardening as downstream specifications tighten. Solvay leverages its European fluorochemical heritage to sustain premium product positioning in specialty glass applications. Shaanxi Ankang Jianghua Group anchors volume production for domestic ceramics customers through integrated barite mining operations. Nippon Chemical Industrial differentiates via stringent particulate control for Japanese electronics fabricators requiring sub-50 ppm strontium content.
Barium carbonate (BaCO₃) is an inorganic salt synthesized primarily through the black ash method from barite ore and coke reduction, yielding a white crystalline solid with specific gravity near 4.3 and decomposition near 811°C to barium oxide and carbon dioxide; its primary industrial purpose centers on fluxing action in glass and ceramic matrices, reducing melting temperatures while enhancing refractive index and chemical durability. Powder formulations lead volume consumption across glass manufacturing, where fine particle distribution accelerates batch homogenization and energy efficiency in furnace operations. Granular grades capture expanding share in oil well drilling fluids, where controlled dissolution kinetics support density modulation in high-pressure formations. Prills and coated variants command margin premiums in electronics fabrication, where anti-caking surface treatments prevent agglomeration during automated dispensing processes.
REACH registration requirements in Europe and China's GB standards under SAMR oversight impose escalating purity and trace-metal documentation burdens on importers and domestic producers alike. EPA hazardous substance reporting in the United States shapes handling protocols for barium-containing materials across chemical processing and paint manufacturing facilities. Stakeholders must monitor regulatory divergence between jurisdictions, as divergent classification thresholds for soluble barium compounds create compliance complexity for multinational supply chain operators serving catalyst and coatings customers simultaneously.
Market Dynamics
The barium carbonate market is experiencing a fundamental restructuring as purity thresholds for specialty glass and electronics applications diverge sharply from standard industrial grades, forcing producers to choose between capital-intensive purification investments and commodity volume plays.
Growth Catalysts
- Optical glass expansion:Specialty glass manufacturers in China and India are scaling procurement of high-purity barium carbonate for display panel substrates and precision optical components, pulling material through integrated supply chains in Jiangsu province.
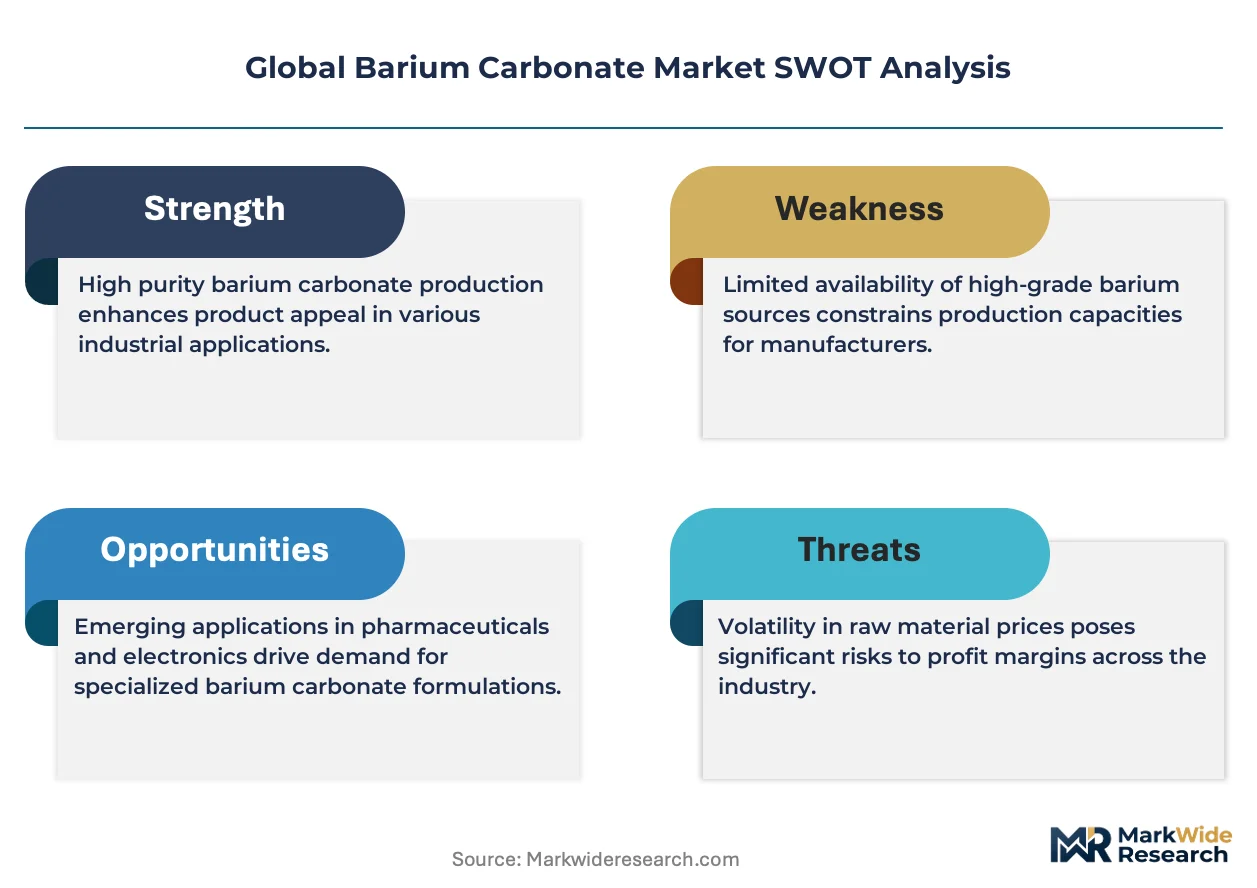
- REACH compliance premiums:European ECHA registration requirements for barium compounds are tightening impurity documentation, rewarding producers with advanced analytical capabilities and certified trace-metal controls.
- Electronics fabrication density:Japanese electronics fabricators are specifying sub-50 ppm strontium content for ceramic capacitor feedstocks, creating specification premiums for particulate-controlled prill formulations.
Market Restraints
- Barite ore concentration:Mining operations for feedstock barite concentrate in select Chinese provinces, creating geographic supply vulnerability for non-integrated processors dependent on spot market sourcing.
- Strontium substitution in ceramics:Strontium carbonate is displacing barium carbonate in certain dielectric ceramic formulations where electrical properties permit lower-cost mineral substitution.
- Black ash method emissions:Coke reduction processes face escalating carbon intensity scrutiny under China's dual carbon goals and EU Carbon Border Adjustment Mechanism provisions, threatening cost structures for legacy producers.
Strategic Opportunities
- Brazilian ceramics growth:ANVISA-regulated pharmaceutical glass and sanitary ware producers in São Paulo state represent underpenetrated demand for high-purity flux materials as domestic manufacturing scales.
- Coated prill automation:Surface-treated anti-caking variants for automated electronics dispensing lines capture margin premiums as Japanese and Korean fabricators expand unmanned batching operations.
- India BIS standard alignment:Bureau of Indian Standards certification mandates for ceramic raw materials are creating first-mover advantages for producers achieving GB-equivalent purity documentation ahead of formal adoption.
Industry Challenges
- Particulate engineering talent scarcity:Formulation chemists capable of designing sub-micron particle distribution for electronics-grade material are concentrated among Japanese and German specialty chemical firms, constraining new entrant capability building.
- SAMR documentation timelines:China's State Administration for Market Regulation is extending approval cycles for revised GB standards on soluble barium compound classifications, delaying product reformulation launches by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Barium Carbonate Market |
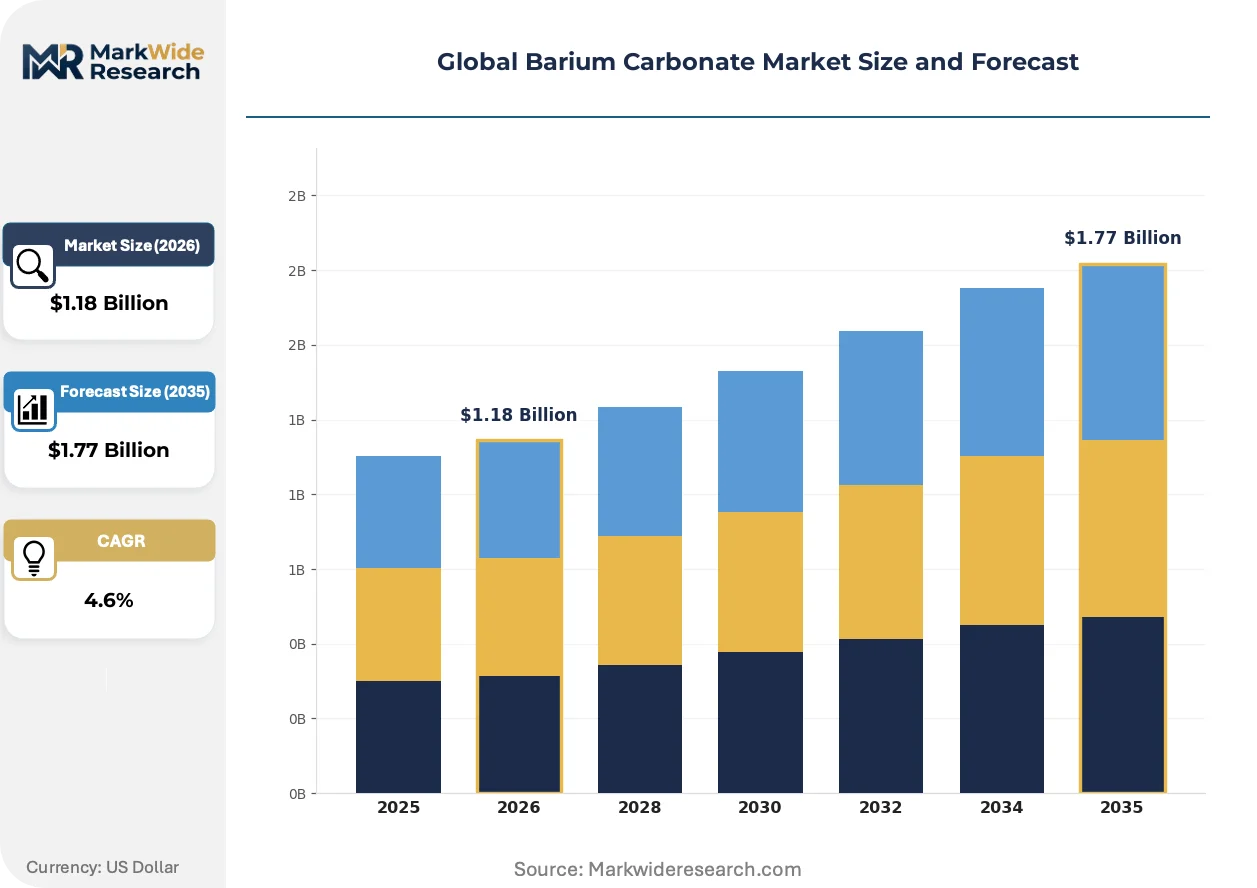
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $1.77 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Prills, Crystals, Coated Application: Ceramics, Glass Manufacturing, Oil Well Drilling, Chemicals Production, Fireworks End User Industry: Catalyst Manufacturers, Paint & Coatings, Chemical Processing, Electronics Fabrication, Agriculture Packaging Type: Bulk Bags, Paper Bags, Plastic Drums, Fiber Drums, Reusable Containers |
| Companies Covered | Hebei Xinji Chemical Group Co., Ltd., Nippon Chemical Industrial Co., Ltd., Sakai Chemical Industry Co., Ltd., Solvay, Honeywell International Inc., Shaanxi Ankang Jianghua Group Co., Ltd., Hubei Jingshan Chutian Barium Salt Corp. Ltd., Zaozhuang Yongli Chemical Co., Ltd., Chemical Products Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Barium Carbonate Market Shifts & Advancements
Continuous crystallization control systems are displacing batch black ash production, enabling real-time purity adjustment that aligns output specifications with downstream electronics and pharmaceutical glass requirements.
Membrane filtration technology for barium salt purification is electrifying the competitive landscape for electronic-grade material. Korean and Taiwanese capacitor manufacturers are qualifying membrane-refined carbonate for multilayer ceramic chip production at accelerated rates. This technology is compressing the historical premium between standard industrial and high-purity grades by enabling mid-tier producers to achieve sub-100 ppm total impurity levels without German or Japanese engineering partnerships.
REACH Annex XVII restrictions on soluble barium compound classifications are tightening occupational exposure thresholds across European chemical processing facilities. Industrial glass and paint manufacturers are reformulating handling protocols and personal protective equipment specifications to maintain market access. Specialty ceramic producers in Germany and France are absorbing compliance costs through supply chain requalification rather than material substitution, preserving barium carbonate's flux performance advantages.
Direct mill-to-furnace supply contracts are displacing distributor-mediated procurement for large-volume glass manufacturers. Chinese flat glass and container producers in the Yangtze River Delta are negotiating multi-year offtake agreements with integrated barite-carbonate producers, securing price stability in exchange for volume commitments. This pattern is most visible in Jiangsu and Zhejiang provinces where energy-intensive furnace operations prioritize feedstock cost predictability over spot market flexibility.
Global Barium Carbonate Market Segmentation
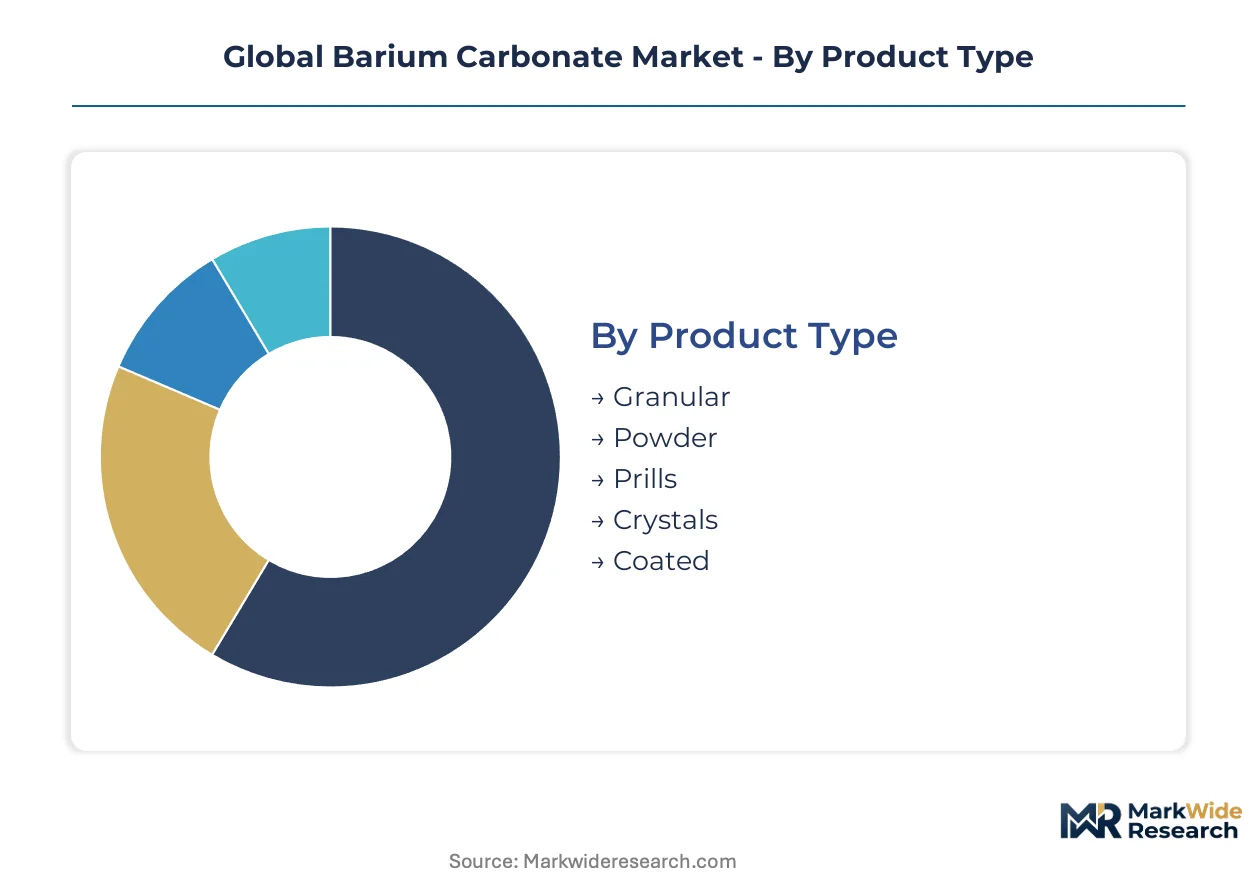
Barium carbonate procurement patterns diverge sharply across physical form, downstream application, and customer sophistication. Specification tiers now command distinct supply chains, with high-purity electronics grades requiring particulate engineering capabilities absent from commodity ceramic flux channels.
Product Type:
Customization intensity spans from bulk powder formulations to precision-engineered prills with anti-caking surface treatments.
- Powder:Fine particle distribution below 45 microns dominates glass manufacturing batch preparation, where rapid dissolution kinetics reduce furnace energy consumption. Yangtze River Delta container glass producers in Jiangsu province specify powder grades for continuous furnace feed systems.
- Prills:Spherical agglomerates with controlled porosity serve automated dispensing lines in Japanese electronics fabrication, where sub-50 ppm strontium content and anti-caking coatings prevent bridging in pneumatic transfer systems. Korean multilayer ceramic capacitor manufacturers are accelerating qualification of membrane-refined prill formulations.
- Granular:Coarse fractions with delayed dissolution profiles support density modulation in high-pressure oil well drilling fluids.
- Crystals:High-density crystalline material serves specialty optical glass requiring precise refractive index control.
- Coated:Surface-treated variants command margin premiums where moisture sensitivity or automated handling demands modified flow characteristics.
Most installed capacity flows through Powder. Expansion is steepest in Prills.
Application:
Volume concentration sits with mature furnace-based industries while value capture shifts toward electronic-grade specifications.
- Glass Manufacturing:Fluxing action reduces silica melting temperatures from 1700°C to 1400°C range while enhancing chemical durability and refractive index. Chinese flat glass producers in Zhejiang province negotiate multi-year offtake agreements with integrated barite-carbonate suppliers to secure feedstock cost predictability.
- Ceramics:Dielectric formulations for multilayer ceramic capacitors specify ultra-low strontium content, with Japanese fabricators driving particulate control standards. Strontium carbonate substitution threatens certain barium titanate formulations where electrical properties permit lower-cost mineral alternatives.
- Oil Well Drilling:Controlled dissolution kinetics in high-pressure formations support density modulation without premature barite sag.
- Chemicals Production:Precursor for barium ferrite magnets and other specialty salts.
- Fireworks:Green colorant applications face declining share amid environmental scrutiny of perchlorate formulations.
Glass Manufacturing retains the largest volume position. Electronics-adjacent Ceramics applications are expanding most quickly.
End User Industry:
Customer sophistication tiers separate specification-heavy electronics fabricators from price-sensitive agricultural and coatings buyers.
- Electronics Fabrication:Japanese and Korean capacitor manufacturers impose sub-100 ppm total impurity thresholds with documented trace-metal certificates. Membrane filtration qualification is compressing historical premiums between industrial and electronic grades.
- Chemical Processing:Catalyst manufacturers and barium derivative producers consume consistent volumes with moderate purity requirements.
- Paint & Coatings:EPA hazardous substance reporting shapes handling protocols across US manufacturing facilities.
- Catalyst Manufacturers:Petroleum refining and chemical synthesis applications demand consistent lot-to-lot quality.
- Agriculture:Lowest specification tier with minimal purity documentation requirements.
Electronics Fabrication commands the steepest specification escalation. Chemical Processing provides the most stable demand baseline.
Packaging Type:
Handling automation and contamination control drive packaging selection across customer tiers.
- Bulk Bags:One-ton flexible intermediate bulk containers dominate high-volume glass and ceramics procurement in Chinese manufacturing clusters.
- Paper Bags:Standard 25-50 kg multi-wall sacks serve mid-tier chemical processing and coatings customers.
- Plastic Drums:Sealed containment for moisture-sensitive electronics-grade material.
- Fiber Drums:Intermediate durability for specialty chemical applications.
- Reusable Containers:Closed-loop systems emerging for large-scale furnace operations prioritizing waste reduction.
Bulk Bags move the largest tonnage. Reusable Containers are gaining adoption fastest among sustainability-focused glass manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process engineers with black ash method expertise concentrate in Chinese industrial clusters, while particulate control specialists cluster around Japanese electronics fabrication centers. This workforce geography shapes regional competitive advantages and supply chain configurations.
China
Specialty glass and ceramics manufacturers in Jiangsu and Zhejiang provinces are expanding procurement of high-purity barium carbonate for optical and display glass production. SAMR oversight of evolving GB standards is tightening impurity thresholds, favoring producers with advanced purification capabilities. The Yangtze River Delta hosts integrated ceramic and electronics supply chains consuming significant volumes through multi-year offtake agreements.
Japan
Electronics fabricators in the Osaka-Kobe industrial corridor specify sub-50 ppm strontium content for ceramic capacitor feedstocks, creating specification premiums for particulate-controlled formulations. METI industrial standards shape quality documentation requirements for chemical processing facilities. Japanese multilayer ceramic capacitor manufacturers are accelerating qualification of membrane-refined carbonate grades.
Germany
Specialty ceramic producers in Germany and France absorb REACH compliance costs through supply chain requalification rather than material substitution. ECHA registration requirements for barium compounds reward producers with advanced analytical capabilities and certified trace-metal controls. Industrial glass manufacturers in the Rhine-Ruhr region prioritize feedstock cost predictability through direct mill-to-furnace contracts.
India
Bureau of Indian Standards certification mandates for ceramic raw materials are creating first-mover advantages for producers achieving GB-equivalent purity documentation. Specialty glass manufacturers in Gujarat and Maharashtra are scaling procurement of high-purity flux materials as domestic manufacturing expands. The Delhi-Mumbai industrial corridor hosts emerging electronics fabrication clusters qualifying new carbonate suppliers.
Brazil
ANVISA-regulated pharmaceutical glass and sanitary ware producers in São Paulo state represent underpenetrated demand for high-purity flux materials. Domestic manufacturing scaling is pulling material through distributor channels as local ceramics production expands. The São Paulo industrial belt hosts glass manufacturers reformulating handling protocols to meet evolving regulatory documentation requirements.
Global Barium Carbonate Market Competitive Landscape
Capital-heavy producers compete with asset-light specialty chemical designers across distinct specification tiers. The vendor base separates into integrated mining-carbonate operators, membrane-refined purification specialists, and legacy black ash method producers. Three strategic archetypes dominate: upstream-integrated volume players, technology-licensed purity specialists, and regional commodity suppliers. Competitive moves center on backward integration into barite mining and membrane filtration technology licensing.
Within the integrated mining tier, Shaanxi Ankang Jianghua Group Co., Ltd. and Hubei Jingshan Chutian Barium Salt Corp. Ltd. exemplify Chinese producers with captive barite ore access. Solvay occupies a position among European heritage chemical groups leveraging fluorochemical process knowledge. Nippon Chemical Industrial Co., Ltd. sits within the Japanese particulate control specialist tier serving electronics fabricators with stringent impurity requirements.
| Leading Market Players |
|---|
| Hebei Xinji Chemical Group Co., Ltd. |
| Nippon Chemical Industrial Co., Ltd. |
| Sakai Chemical Industry Co., Ltd. |
| Solvay |
| Honeywell International Inc. |
| Shaanxi Ankang Jianghua Group Co., Ltd. |
| Hubei Jingshan Chutian Barium Salt Corp. Ltd. |
| Zaozhuang Yongli Chemical Co., Ltd. |
| Chemical Products Corporation |
| Others |
Supply & Pricing Matrix
Backward integration into captive barite mining anchors both supply security and pricing power for Chinese producers serving Jiangsu province glass manufacturers, while European specialty chemical groups leverage fluorochemical process heritage to sustain premium positioning against commodity imports. SAMR-mandated GB standard evolution and REACH Annex XVII compliance burdens are bifurcating procurement economics between documentation-heavy electronics grades and price-sensitive industrial flux markets.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement for Yangtze River Delta furnace operators, unbundling spot market exposure from logistics and certification services. Three-tier pricing structure across electronic-grade, specialty glass-grade, and industrial-grade levels reflects strontium content thresholds and particulate distribution precision. Cost compression in standard powder grades is intensifying because membrane filtration technology enables mid-tier producers to achieve sub-100 ppm purity without German or Japanese engineering partnerships. Chemical processing and agricultural buyers exhibit highest price sensitivity, while Japanese electronics fabricators absorb specification premiums for anti-caking prill formulations.
Supply Chain Analysis
Process engineers with black ash method expertise concentrate in Shaanxi and Hubei provinces, while particulate control specialists cluster around Osaka-Kobe electronics fabrication centers, creating geographic capability asymmetries that shape supplier qualification timelines. Feedstock barite ore draws from Guizhou and Hunan mining districts, with coke reduction reagents sourced from Shanxi coking operations. Single-source vulnerability concentrates in Chinese barite concentrate supply for non-integrated processors dependent on spot market sourcing. Distribution runs through direct mill-to-furnace contracts displacing distributor channels for high-volume glass manufacturers, while specialty electronics grades move through certified chemical distributors with trace-metal documentation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate in India, where BIS certification mandates lag China's GB-equivalent purity documentation requirements by 12-18 months, allowing early entrants to capture specification premiums before domestic competition intensifies.
For Market Incumbents: Cement supply chain control through backward integration into Guizhou barite mining concessions and membrane filtration technology licensing from Korean equipment vendors. Strontium carbonate substitution in dielectric ceramics threatens volume positions in standard-grade material, demanding defensive certification investments in sub-50 ppm strontium documentation ahead of formal BIS adoption in India.
For New Entrants and Emerging Players: Capture white-space demand from ANVISA-regulated pharmaceutical glass producers in São Paulo state, where domestic manufacturing scaling outpaces local high-purity flux supply. Brazil's sanitary ware expansion represents the most penetrable geography for GB-equivalent purity documentation. Pursue joint-venture structures with established Brazilian chemical distributors to bypass capital-intensive furnace customer qualification cycles.
For Investors and Strategic Acquirers: Consolidation pressure builds where membrane filtration technology compresses historical premiums between industrial and electronic grades, eroding margin differentiation for legacy black ash method producers without purification capabilities. Five-to-ten year viability favors integrated mining-carbonate operators with captive ore access and SAMR-registered GB documentation capabilities. Monitor SAMR approval timelines for revised soluble barium compound classifications as early inflection signals for product reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barite Mining | Captive ore access secures feedstock cost predictability for Jiangsu province furnace customers. |
| Membrane Filtration Technology Licensing | Enables mid-tier producers to achieve electronic-grade purity without Japanese engineering partnerships. |
| Long-term Supply Agreement | Direct mill-to-furnace contracts displace distributor channels in Yangtze River Delta glass manufacturing. |
| Green Manufacturing Transition | Coke reduction processes face carbon intensity scrutiny under China's dual carbon goals and EU CBAM provisions. |
| Joint Venture | Accelerates market entry for foreign producers targeting ANVISA-regulated Brazilian pharmaceutical glass demand. |
Research Methodology
Multiple input streams — technical discussions with specialty glass plant managers and ceramic capacitor procurement leads, trade flow analysis from Chinese customs data, and validation against ECHA registration filings — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged process engineers at black ash method facilities in Shaanxi province, electronics-grade formulation chemists in Osaka-Kobe industrial corridor, and distribution channel partners serving Yangtze River Delta manufacturing clusters. Secondary sources included SAMR GB standard draft publications, REACH Annex XVII restriction notices, BIS certification mandate announcements, and SEC filings from disclosed barium carbonate consumers.
Historical volume trajectories were cross-referenced against panel input from procurement directors at multilayer ceramic capacitor manufacturers and specialty optical glass fabricators across the analysis window. Segmentation modeling incorporated grade tier differentiation, end-use industry concentration, physical form specifications, and regional production hub classification. CAGRs were derived from weighted regression against downstream demand indicators including flat glass furnace operating rates and electronics fabrication capacity expansion announcements. Forecast inputs specifically tracked membrane filtration qualification rates among Korean and Taiwanese capacitor manufacturers and SAMR documentation timeline extensions for revised GB standards.
Barite ore supply disruptions in Guizhou mining districts, accelerated strontium substitution in dielectric ceramic formulations, and regulatory reclassification of soluble barium compounds under evolving GB standards are the dominant revision risks to modeled outputs. Practitioners should monitor SAMR approval cycle extensions, ECHA restriction proposal comment periods, and Korean membrane filtration equipment order backlogs for early signals of forecast trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramic Binders Market
Ceramics
Carbon-Ceramic Discs Market
Ceramics
Ceramic Substrate Market
Ceramics
US Kaolin Market
Ceramics
Potassium Feldspar Market
Ceramics
White Fused Alumina Market
Ceramics
Zirconia Ceramic Balls Market
Ceramics
Glass Ceramics Market
Ceramics
Active Calcium Silicate Market
Ceramics
Construction Ceramics Market
Ceramics
Cerium Carbonate Market
Ceramics
Solid-Ion Conductors Market
Ceramics
North America Ceramic Coatings Market
Ceramics
Wollastonite Market
Ceramics
Dielectric Ceramics Market
Ceramics
China Ceramic Market