
 Abdominal Pads Market | 2026-2036
Abdominal Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Abdominal Pads Market Intelligence
Hospital-grade sterile specifications is bifurcating the competitive landscape into premium-certified suppliers and cost-focused volume producers. Medline Industries leverages extensive North American distribution networks to sustain institutional contracts. Mölnlycke Health Care differentiates through advanced wound-care technology leadership in hydrocolloid segments. Dynarex Corporation competes on manufacturing scale across non-adhesive and bulk-pack formats for price-sensitive channels.
Abdominal pads are multi-layer absorbent dressings, typically comprising a non-woven outer layer, cellulose or super-absorbent polymer core, and fluid-resistant backing, designed for high-exudate wound management and post-operative site protection. The sterile pad category commands premium positioning due to surgical suite requirements, while hydrocolloid pads represent the fastest-growing product type driven by extended wear properties and reduced dressing change frequency. Application demand concentrates in post-surgical dressings where infection control protocols and reimbursement standards create durable margin pools, with burn care emerging as a specialized growth corridor requiring advanced absorption and thermal protection specifications.
FDA 510(k) clearance requirements and EU MDR conformity assessments shape product development timelines and market access barriers for abdominal pad manufacturers. ISO 13485 quality management systems and AAMI sterility assurance standards further govern production protocols, with Health Canada and TGA recognition extending commercial reach into additional regulated jurisdictions. Stakeholders must monitor evolving post-market surveillance obligations and biocompatibility testing expansions that will determine which product portfolios retain commercial viability across major procurement systems.
Market Dynamics
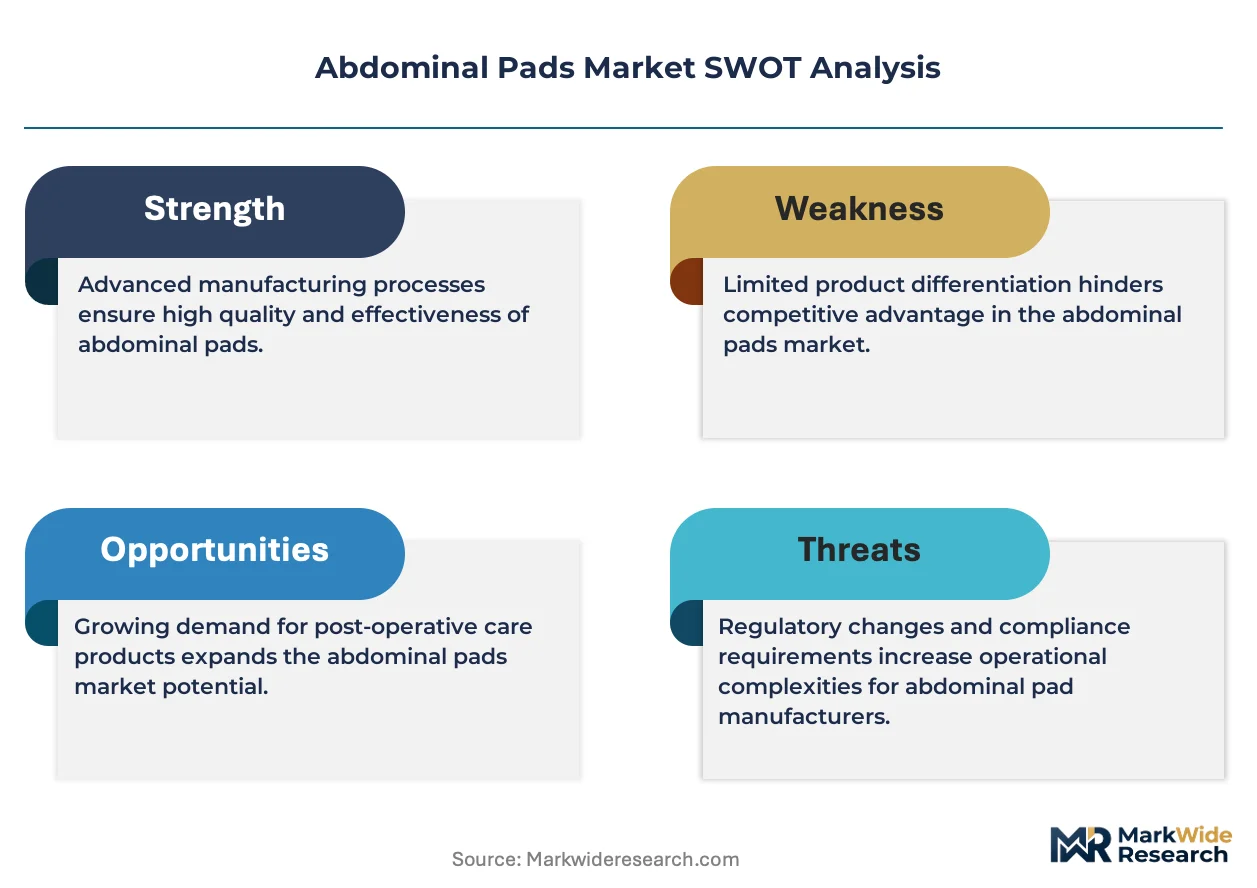
EU MDR sterility assurance requirements are compressing production timelines and elevating quality system investments across abdominal pad manufacturing, forcing suppliers to consolidate certification portfolios or exit surgical-grade segments entirely.
Growth Catalysts
- Outpatient surgical volume expansion:Ambulatory surgical centers in the United States are scaling procedure throughput, driving recurring demand for sterile post-operative dressings with consistent reorder patterns.
- REACH-compliant absorbent polymer innovation:Super-absorbent polymer cores meeting EU chemical safety standards enable extended wear protocols that reduce nursing labor intensity in hospital settings.
- Aging demographic concentration:Japan's geriatric population sustains elevated surgical intervention rates, creating durable demand for infection-control wound management products.
Market Restraints
- Cellulose pulp input volatility:Fluctuating softwood pulp prices compress margin predictability for manufacturers reliant on commodity absorbent cores.
- Single-source sterilization dependency:Ethylene oxide sterilization capacity concentrates in specialized contract facilities, creating supply vulnerability during facility shutdowns.
- Reusable negative pressure wound therapy:Advanced NPWT systems substitute for traditional absorbent pads in high-exudate cases, constraining addressable market expansion.
Strategic Opportunities
- Underpenetrated home care transition:Post-acute home care settings in Germany lack standardized high-absorbency dressing protocols, presenting white-space for specialized product education.
- ISO 13485-certified private label expansion:Retail pharmacy chains seek compliant white-label suppliers to capture margin from branded incumbents in non-surgical segments.
- Biodegradable backing material convergence:PLA-based fluid-resistant layers combined with compostable non-woven substrates align with EU Green Deal procurement criteria.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity validation queues at accredited laboratories extend product launch timelines by six to nine months.
- Legacy ERP integration friction:MDR-compliant batch traceability requirements strain paper-based inventory systems at mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Abdominal Pads Market |
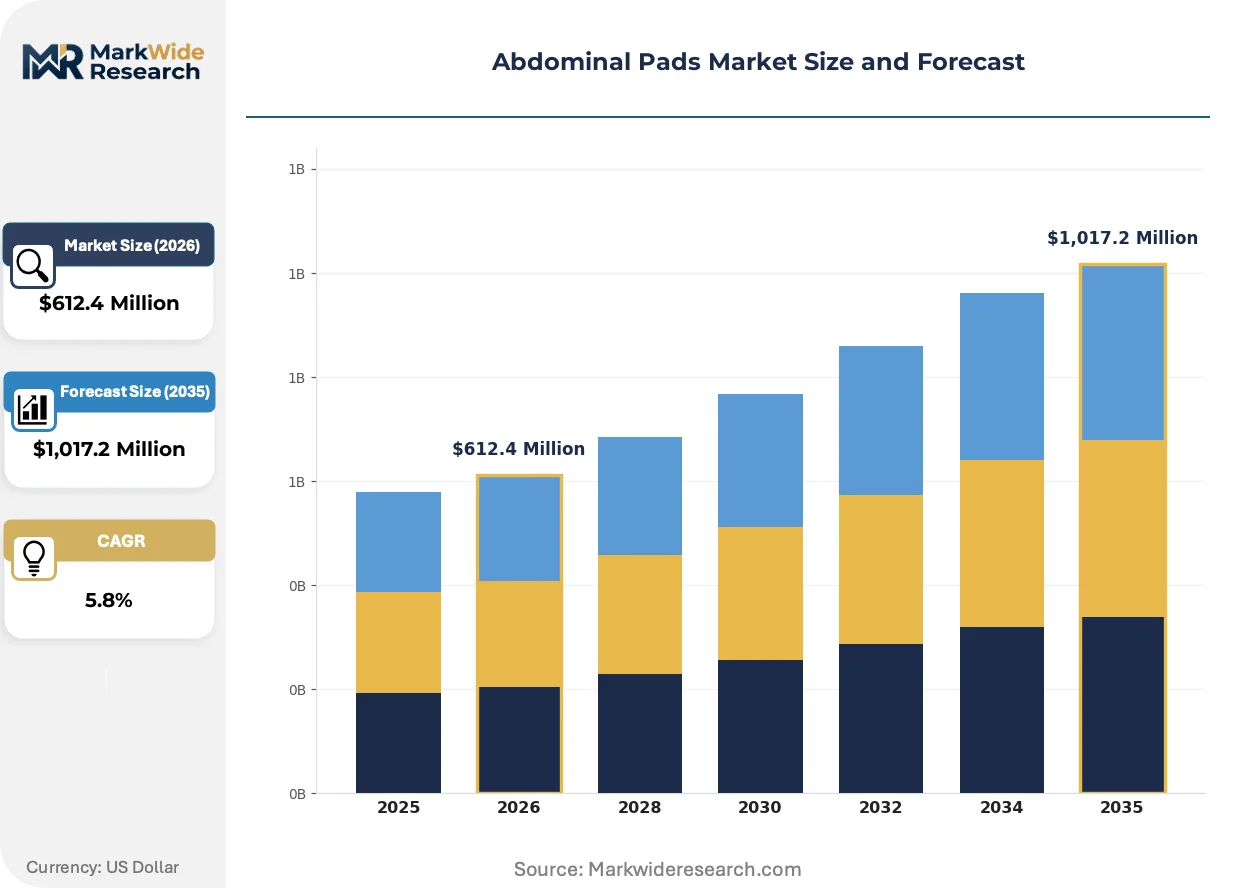
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Pads, Non-Adhesive Pads, Sterile Pads, Non-Sterile Pads, Hydrocolloid Pads Application: Wound Protection, Post-Surgical Dressings, Absorption, Infection Control, Burn Care End User: Hospitals, Ambulatory Surgical Centers, Clinics, Home Care Settings, Medical Transport Services Packaging Type: Individual Packs, Bulk Packs, Sterile Pouches, Boxed Sets, Reusable Containers |
| Companies Covered | Medline Industries, Smith & Nephew, Medtronic, Cardinal Health, 3M, Dukal Corporation, Integra Life Sciences, Dynarex Corporation, Mölnlycke Health Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Abdominal Pads Market Strategic Shifts & Innovations
Material science advances and regulatory harmonization pressures are compressing traditional product lifecycles while opening differentiation pathways through sustainability credentials and extended-wear performance.
Silver-ion antimicrobial integration is fragmenting the premium sterile pad category into distinct efficacy tiers. Surgical suites in tertiary hospitals are adopting iontophoretic delivery systems for complex abdominal procedures. This technology is fragmenting procurement specifications into standard, advanced, and extended-protection categories with diverging price points.
EU MDR post-market surveillance obligations are mandating systematic adverse event reporting across all sterile dressing classifications. Manufacturers must maintain vigilance databases with direct healthcare professional feedback channels. German notified bodies are conducting unannounced audits that compress quality system update cycles.
Hospital purchasing consortiums are consolidating vendor panels through single-source agreements with performance-based compliance clauses. Integrated delivery networks in the United States are displacing fragmented departmental buying with centralized sterile supply contracts. Burn centers and trauma units retain limited direct procurement authority for specialized high-absorbency formats.
Abdominal Pads Market Segmentation
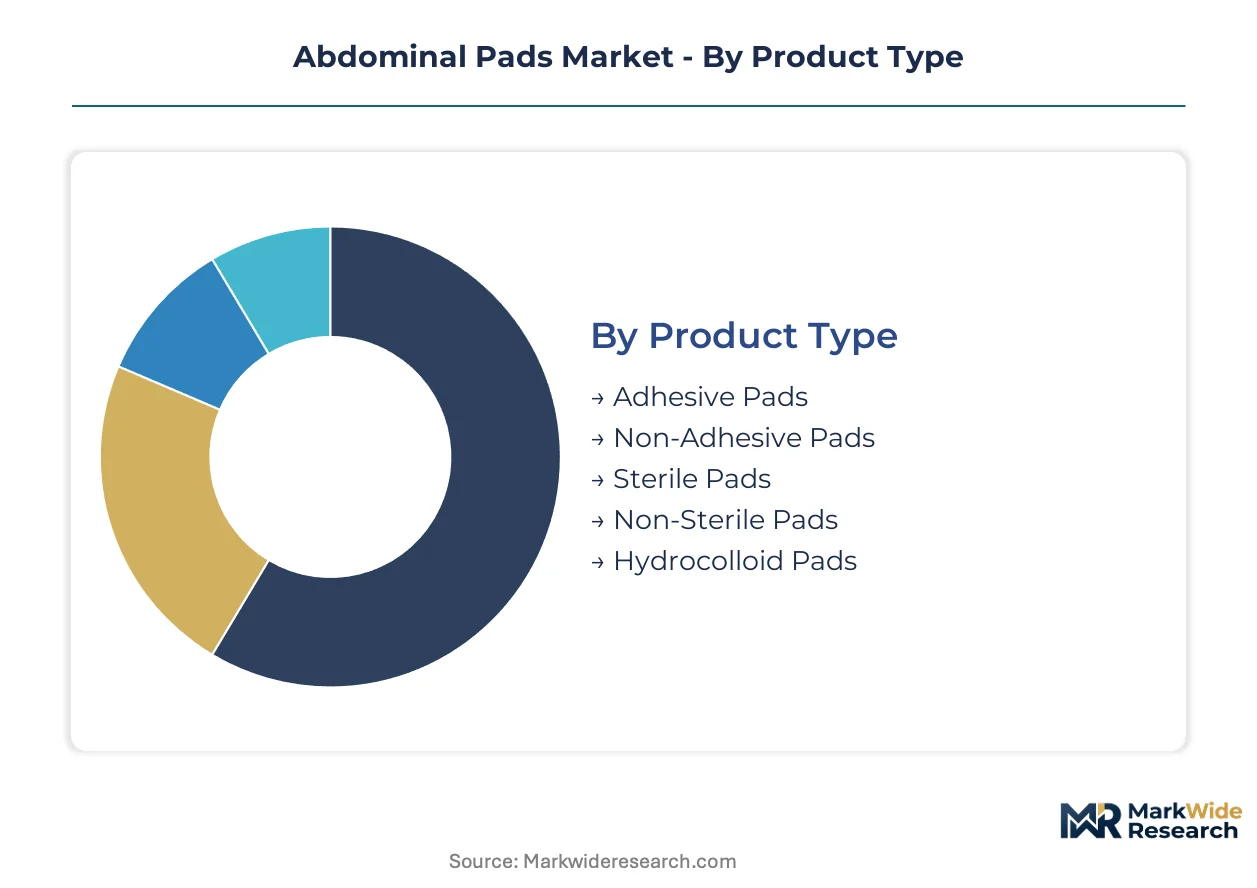
Abdominal pad procurement channels diverge sharply between institutional bulk contracts and retail pharmacy distribution. Product specifications, sterility requirements, and packaging formats determine which segments flow through hospital supply chains versus home care retail. Understanding these channel dynamics enables targeted positioning across divergent margin structures.
Product Type:
Channel mix splits sterile formats through surgical supply distributors while non-sterile variants dominate retail pharmacy and long-term care procurement.
- Sterile Pads:Gamma or ethylene oxide sterilized with validated sterility assurance levels per FDA 510(k) requirements. United States hospital systems mandate sterile formats for all operative site dressings, with procurement centralized through integrated delivery networks.
- Hydrocolloid Pads:Gel-forming polymer matrix bonded to breathable polyurethane film enables extended wear protocols. Japan's geriatric home care sector drives fastest uptake where nursing labor shortages favor reduced dressing change frequency.
- Adhesive Pads:Medical-grade acrylic adhesive border secures pad without secondary tape in ambulatory settings.
- Non-Adhesive Pads:Relies on external retention methods preferred for fragile skin in burn units.
- Non-Sterile Pads:Cleanroom-manufactured without terminal sterilization for non-operative wound management.
Sterile pads dominate installed base in surgical suites. Hydrocolloid formats are where expansion concentrates.
Application:
Cost tier stratification separates premium reimbursed surgical applications from commoditized basic wound coverage.
- Post-Surgical Dressings:Multi-layer absorbent construction with fluid-resistant backing protects operative sites during critical healing phases. Germany's statutory health insurance reimbursement codes sustain premium pricing for certified post-operative formats.
- Burn Care:Specialized high-absorbency cores with thermal protection layers manage exudate in partial-thickness burns. United States burn centers maintain direct procurement authority for advanced formats outside standard vendor contracts.
- Wound Protection:Barrier function against mechanical trauma and bacterial contamination in chronic wounds.
- Absorption:Core function managing exudate volume across all wound types.
- Infection Control:Antimicrobial-integrated formats for contaminated or high-risk wound environments.
Post-surgical dressings command margin concentration. Burn care represents the steepest expansion trajectory.
End User:
Customer type determines volume scale versus specification intensity across procurement relationships.
- Hospitals:Tertiary medical centers in the United States negotiate multi-year sterile supply agreements with performance metrics for delivery reliability and lot traceability.
- Ambulatory Surgical Centers:High-throughput outpatient facilities in Texas and Florida drive recurring demand for standardized sterile formats with predictable reorder patterns.
- Clinics:Physician office-based procedures require flexible inventory with mixed sterile and non-sterile SKUs.
- Home Care Settings:Post-acute discharge destinations in Germany lack standardized high-absorbency protocols.
- Medical Transport Services:Emergency medical services require compact sterile packaging for field trauma management.
Hospitals anchor volume concentration. Ambulatory surgical centers are where procurement momentum builds.
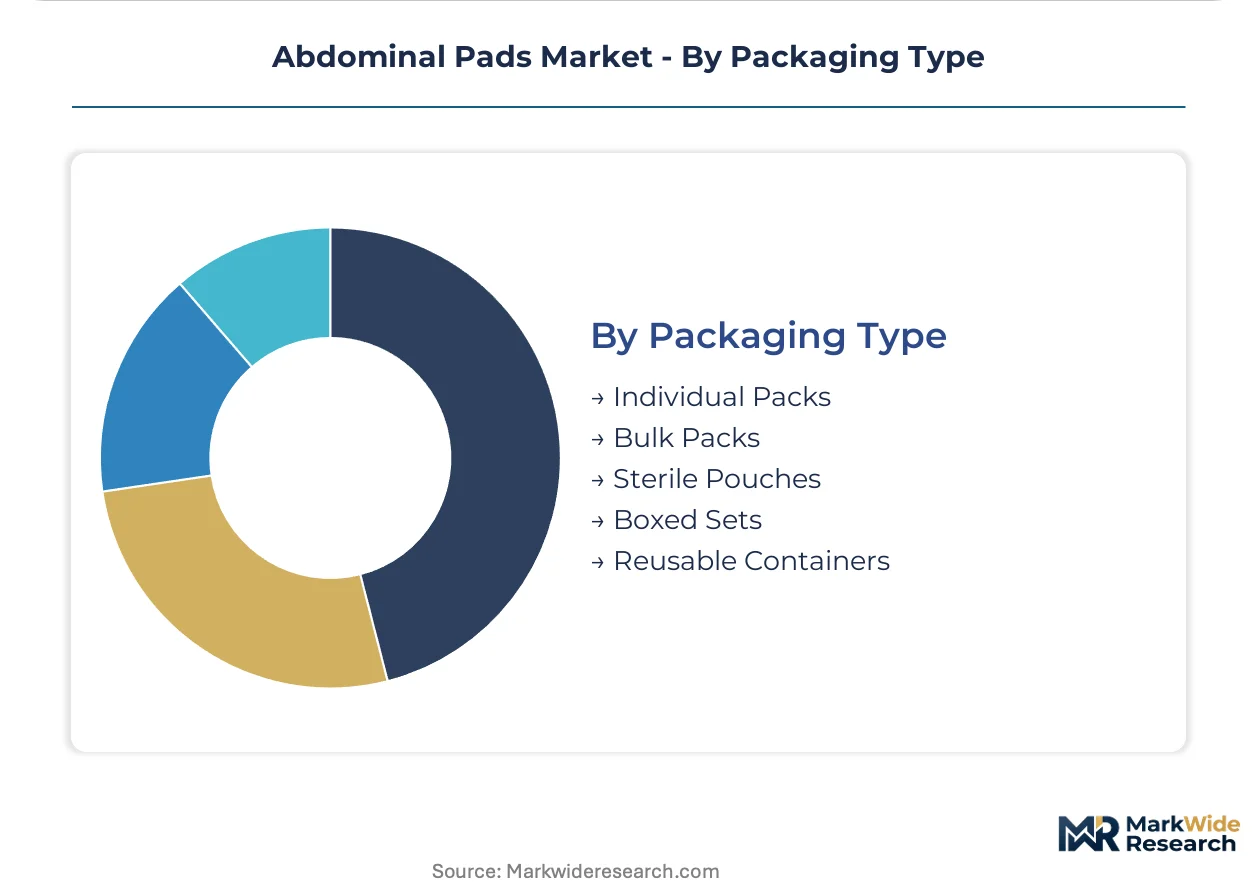
Packaging Type:
Supply concentration in contract sterilization facilities shapes packaging format availability and cost structures.
- Sterile Pouches:Tyvek-laminated peel pouches with validated seal integrity for individual sterile field presentation. FDA-registered contract sterilizers in Ohio and North Carolina concentrate capacity for gamma-irradiated formats.
- Bulk Packs:Polybagged non-sterile quantities for high-consumption units with automated dispensing systems.
- Individual Packs:Single-unit retail packaging for pharmacy and home care channels.
- Boxed Sets:Procedure-matched assortments for specific operative protocols.
- Reusable Containers:Rigid sterilization cases for surgical instrument sets with integrated dressing compartments.
Sterile pouches dominate surgical procurement. Bulk packs capture price-sensitive volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export REACH-compliant sterile pads to United States hospital systems, establishing the primary transatlantic trade corridor for premium surgical dressings.
United States
Ambulatory surgical centers in Texas and Florida drive recurring procurement volumes for standardized sterile formats. FDA 510(k) clearance timelines shape product launch schedules for domestic suppliers. Ohio and North Carolina host gamma-irradiation contract sterilizers that concentrate terminal sterilization capacity for surgical-grade pads.
Germany
Statutory health insurance reimbursement codes sustain premium pricing for certified post-operative formats. EU MDR conformity assessments elevate quality system investments across domestic manufacturing. Bavaria's medical technology corridor houses notified bodies conducting unannounced audits that compress compliance update cycles.
Japan
Geriatric home care demand favors hydrocolloid formats that reduce nursing labor intensity. PMDA regulatory frameworks govern biocompatibility testing protocols for antimicrobial-integrated products. Kansai region distributors channel extended-wear pads into aging rural prefectures with limited healthcare staffing.
United Kingdom
NHS procurement consolidation favors vendors with ISO 13485-certified quality systems and validated lot traceability. MHRA recognition of EU MDR certificates maintains market access continuity post-Brexit. London-based integrated delivery networks centralize sterile supply contracts that displace fragmented departmental buying.
Australia
TGA recognition of FDA and EU MDR approvals accelerates market entry for imported surgical dressings. Remote regional hospitals prioritize bulk-pack non-sterile formats for cost-sensitive wound management. New South Wales burn centers retain limited direct procurement authority for specialized high-absorbency formats.
Abdominal Pads Market Key Industry Players
Listed leaders compete with private specialists across certification depth and channel access, producing a tiered structure where scale advantages clash with regulatory agility. Tier-one suppliers anchor institutional contracts through integrated delivery networks. Mid-tier fabricators compete on manufacturing scale for price-sensitive retail channels. Strategic moves concentrate on M&A consolidation of sterilization assets and backward integration into absorbent core production.
Within the premium-certified tier, Medline Industries and Mölnlycke Health Care exemplify archetypes of institutional contract holders with extensive distribution networks. Dynarex Corporation occupies a position representing scale-driven competition across non-adhesive and bulk-pack formats. These three anchors illustrate the competitive divergence between premium-certified suppliers and cost-focused volume producers that defines procurement segmentation across hospital and retail channels.
| Leading Market Players |
|---|
| Medline Industries |
| Smith & Nephew |
| Medtronic |
| Cardinal Health |
| 3M |
| Dukal Corporation |
| Integra Life Sciences |
| Dynarex Corporation |
| Mölnlycke Health Care |
| Others |
Cost & Logistics Intelligence
FDA 510(k) sterility clearance and EU MDR conformity assessment requirements simultaneously gate supply qualification and stratify price tiers across the abdominal pads market, forcing manufacturers to absorb elevated quality system investments that translate into premium positioning for surgical-grade formats.
Pricing Analysis
Hospital purchasing committees anchor pricing stratification across premium-certified, standard institutional, and economy retail tiers. Price differentiation hinges on ISO 13485 certification depth and gamma-irradiation validation status, with sterile surgical formats commanding substantial premiums over cleanroom-manufactured alternatives. Cost compression in non-sterile retail segments intensifies as private-label pharmacy chains consolidate volume procurement. Ambulatory surgical centers exhibit moderate price sensitivity, prioritizing delivery reliability over marginal cost savings.
Supply Chain Analysis
Inventory lead times for ethylene oxide sterilization capacity stretch procurement cycles as contract facilities in Ohio and North Carolina operate at utilization thresholds. Geographic supply concentration centers on United States domestic manufacturing for sterile formats, German REACH-compliant production for premium exports, and Chinese non-woven substrate fabrication for cost-optimized tiers. Raw material dependencies encompass softwood cellulose pulp, super-absorbent polymer resins, and medical-grade polyurethane films. Single-source sterilization vulnerability creates supply risk during facility maintenance windows. Distribution runs through integrated delivery networks for hospital systems and pharmaceutical wholesalers for retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in sterile supply management and dressing protocol training expand faster than hardware margins, as hospital systems outsource inventory optimization and clinical education to vendor partners.
For Market Incumbents: Shield institutional contract positions by deepening captive sterilization capacity in gamma-irradiation facilities and securing multi-year GPO agreements with performance-based compliance clauses. Reusable negative pressure wound therapy systems threaten high-exudate pad volumes; counter with extended-wear hydrocolloid innovation and bundled clinical support services. For New Entrants and Emerging Players: Anchor in Germany's underpenetrated home care transition segment, where post-acute discharge protocols lack standardized high-absorbency dressing standards. Target ISO 13485-certified private label supply to retail pharmacy chains seeking compliant white-label alternatives. Pursue direct-to-clinic distribution bypassing consolidated hospital vendor panels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates with underoptimized wound care divisions lacking dedicated sterilization assets. Five-to-ten-year viability favors suppliers with backward integration into absorbent core production and validated EU MDR technical documentation. Monitor ethylene oxide sterilization capacity utilization rates as inflection signal for supply-constrained pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Bavarian notified body audits compress compliance cycles for surgical-grade manufacturers. |
| Backward Integration into SAP Core Production | Captive super-absorbent polymer supply insulates margin from cellulose pulp volatility. |
| Hospital System Partnership Program | Integrated delivery network single-source agreements displace fragmented departmental procurement. |
| Biodegradable Backing Material Transition | PLA-based fluid-resistant layers align with EU Green Deal public procurement criteria. |
| Reimbursement Strategy Development | German statutory health insurance code certification sustains premium post-surgical pricing. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation databases, hospital GPO contract repositories, and trade customs data. Interviews with hospital purchasing committee directors, ambulatory surgical center operations managers, biomedical engineers, sterile supply coordinators, and wound care clinicians inform demand-side validation. Bottom-up volume modeling triangulates against top-down market sizing across sterile and non-sterile product categories.
Segmentation dimensions modeled encompass product type hierarchy, application severity tier, end-user facility scale, packaging format requirements, and regional regulatory cluster across the projection horizon. CAGRs derive from procedure volume elasticity analysis, reimbursement code stability assessment, and input cost trajectory modeling. Super-absorbent polymer innovation cycles and sterilization capacity expansion schedules constitute industry-specific forecast inputs.
Material uncertainties — cellulose pulp commodity swings, ethylene oxide facility regulatory actions, and NPWT substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding outpatient surgical volume trajectories and MDR compliance cost pass-through. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Care Supplies
Therapy Pillow Market
Patient Care Supplies
Disposable Incontinence Products (Dips) Market
Patient Care Supplies
Air-Assisted Patient Transfer Systems Market
Patient Care Supplies
External Urine Management Products Market
Patient Care Supplies
Reusable Incontinence Products Market
Patient Care Supplies
Hip Shield Market
Patient Care Supplies
US Pressure Ulcer Prevention Market
Patient Care Supplies
Reusable Nursing Pads Market
Patient Care Supplies
Ice Packs for Pain Market
Patient Care Supplies
Global Incontinence and Ostomy Care Product Market
Patient Care Supplies
Asia-Pacific Hospital Supplies Market
Patient Care Supplies
Stoma Care Market
Patient Care Supplies
GCC Adult Diaper Market
Patient Care Supplies
Shoe Cover Market
Patient Care Supplies
Global Patient Lateral Transfer Market
Patient Care Supplies
Self Inflating Bag Market