
 Medical Transport Box Market | 2026-2036
Medical Transport Box Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Transport Box Market Analysis
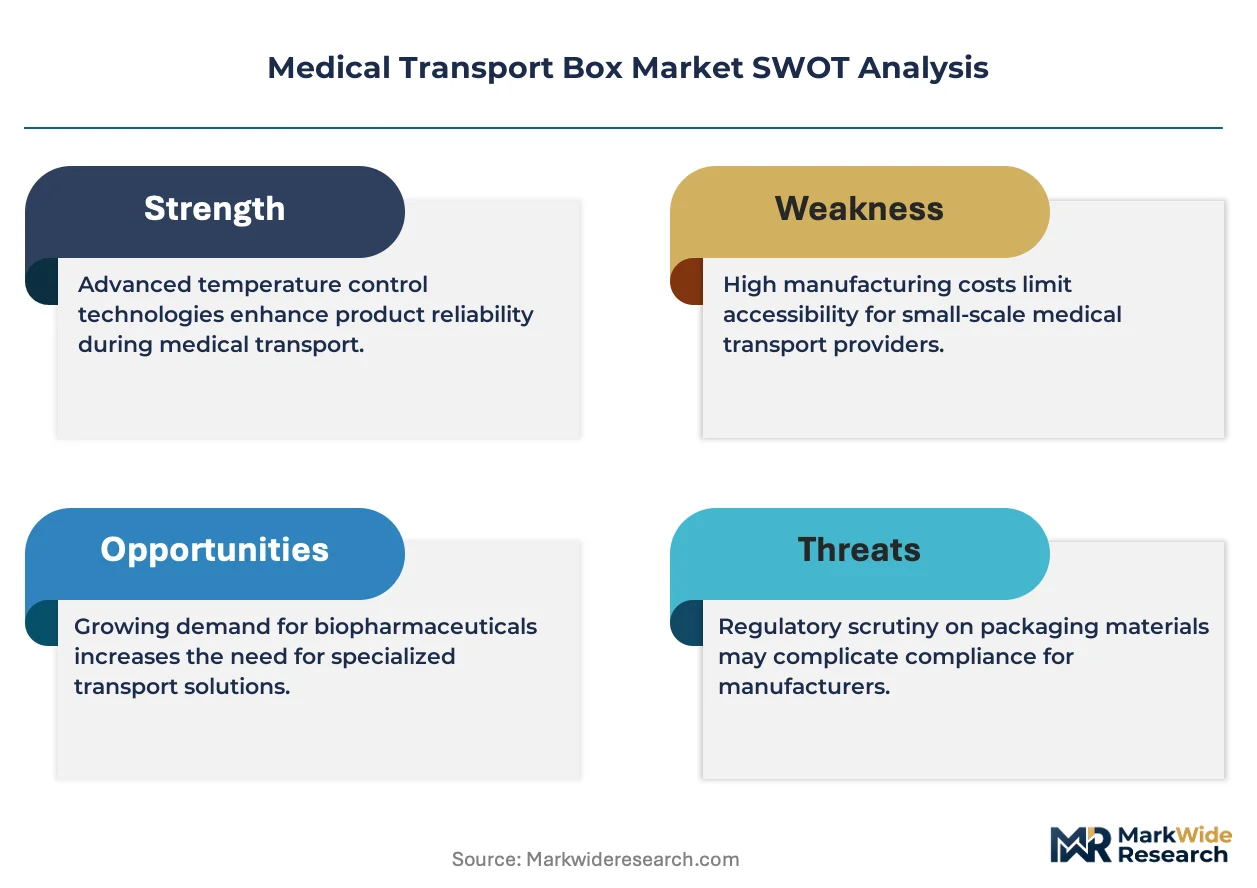
Hospital procurement channels are reshaping how medical transport box suppliers reach end users, with group purchasing organizations and direct-to-facility contracts replacing traditional distributor layers. Thermo Fisher Scientific leverages its laboratory equipment footprint to bundle transport solutions with diagnostic workflows. Haier Group anchors its position through biomedical cold-chain specialization extending from refrigeration into portable transport units. Pelican BioThermal differentiates via phase-change material technology leadership in temperature-controlled packaging for pharmaceutical shipments.
A medical transport box is a thermally engineered container designed to maintain specified temperature ranges—typically 2°C to 8°C for refrigerated payloads or sub-zero conditions for frozen specimens—during transit of biological materials, pharmaceuticals, or diagnostic samples. Construction incorporates vacuum-insulated panels, polyurethane foam, or phase-change materials with data-logging integration to ensure chain-of-custody documentation. Blood transport applications dominate current volume, with insulated boxes commanding the largest installed base while refrigerated units capture premium margins from biologics and cell therapy logistics. Emergency services represent the fastest-growing end-user channel as pre-hospital specimen collection protocols expand.
The FDA enforces thermal-validation requirements under pharmaceutical distribution guidelines, while the EU's GDP (Good Distribution Practice) framework mandates continuous temperature monitoring for medicinal products in transit across member states. Japan's PMDA imposes equally stringent cold-chain documentation standards for imported biologics, creating compliance-driven replacement cycles for non-conforming equipment. Stakeholders must monitor evolving pharmacopeial standards and energy-efficiency regulations as these frameworks increasingly dictate material selection and digital connectivity requirements in next-generation transport designs.
Market Dynamics
The FDA's tightened pharmaceutical distribution guidelines are compressing replacement cycles for non-validated transport containers while blood banks accelerate cold-chain procurement of insulated and refrigerated units. This regulatory pressure intersects with biologics logistics scaling in the United States, Germany, and Japan.
Growth Catalysts
- Biologics Cold-Chain Expansion:Cell therapy logistics networks in Germany and Japan are generating premium demand for phase-change material containers with continuous temperature monitoring.
- Emergency Services Protocols:Pre-hospital specimen collection mandates across US metropolitan health systems are driving volume for portable insulated transport units.
- GDP Compliance Mandates:The EU's Good Distribution Practice framework requires temperature documentation for cross-border medicinal shipments, forcing container upgrades.
Market Restraints
- Vacuum-Insulated Panel Supply Concentration:Production of high-performance thermal panels clusters in East Asian manufacturing hubs, exposing buyers to input cost volatility and extended lead times.
- Phase-Change Material Technical Limitations:Current PCM formulations exhibit thermal degradation after repeated freeze-thaw cycles, constraining reuse economics for high-frequency logistics operators.
- FDA Validation Friction:Thermal-qualification documentation requirements for pharmaceutical distribution create extended approval timelines for new container designs.
Strategic Opportunities
- Underpenetrated Indian Diagnostics Networks:CDSCO-regulated cold-chain gaps in tier-2 and tier-3 cities present white space for validated transport solutions as diagnostic sample collection expands.
- Reusable Container-as-a-Service Models:Logistics providers are piloting subscription-based container pooling systems that bundle hardware with digital chain-of-custody platforms.
- IoT-Thermal Convergence:Integration of real-time temperature loggers with cloud-based validation software is creating new value layers beyond passive insulation.
Industry Challenges
- Thermal Engineering Talent Scarcity:Cross-disciplinary expertise combining materials science with pharmaceutical regulatory requirements remains concentrated among a narrow specialist cohort.
- Multi-Jurisdiction Certification Complexity:Container manufacturers must navigate simultaneous FDA, EMA, and PMDA validation pathways, fragmenting product development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Transport Box Market |
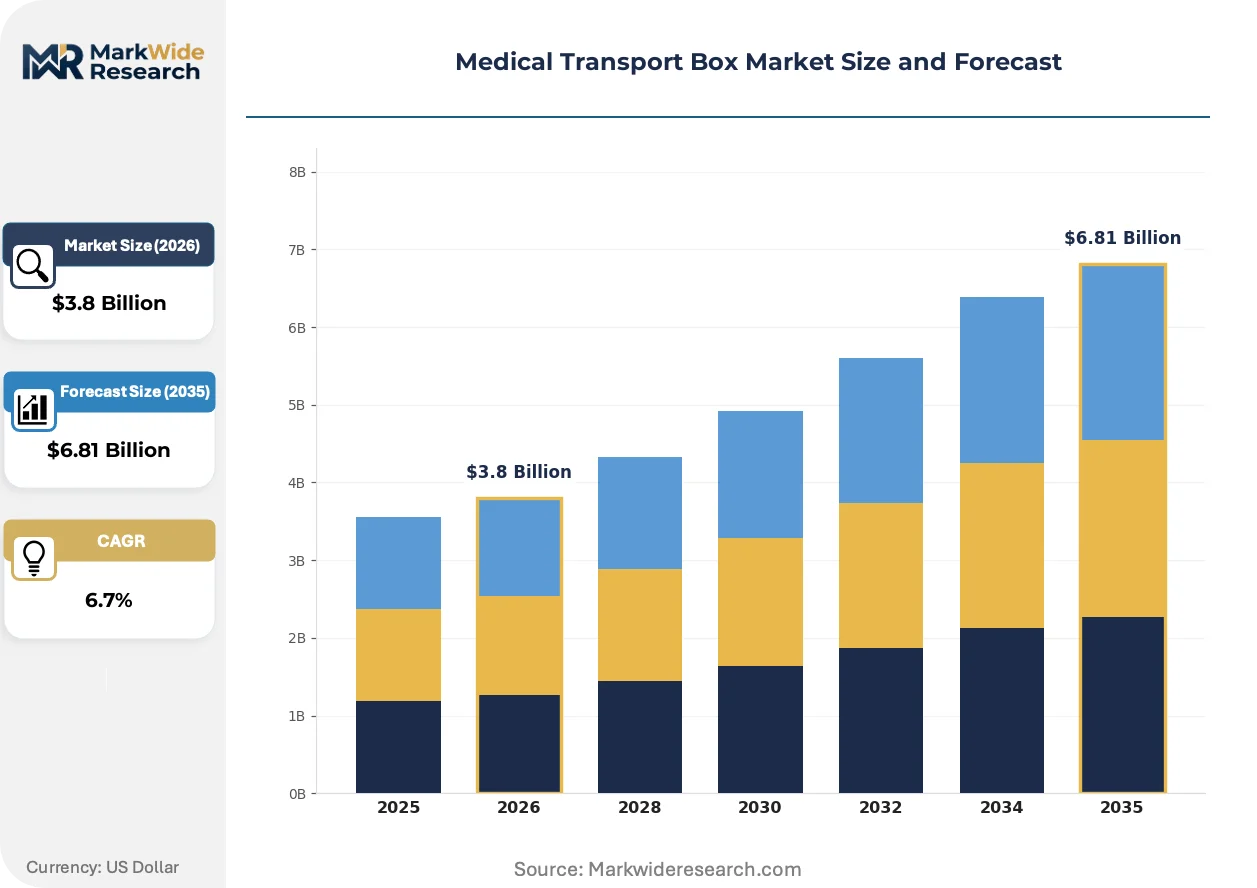
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Boxes, Refrigerated Units, Portable Coolers, Medical Bags Application: Blood Transport, Organ Preservation, Vaccine Storage, Tissue Transport End User: Hospitals, Blood Banks, Research Labs, Emergency Services Material: Plastic, Aluminum, Fiberglass, Composite |
| Companies Covered | Avantor, Haier Group, Thermo Fisher Scientific, BITO-Lagertechnik Bittmann GmbH, Nilkamal, B Medical Systems, SARSTEDT AG & Co. KG, Pelican BioThermal, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Transport Box Market Emerging Trajectories
Digital validation infrastructure is displacing paper-based chain-of-custody documentation across pharmaceutical and diagnostic logistics networks. Three convergent developments are compressing innovation cycles and reshaping supplier competitive requirements.
Cloud-based temperature monitoring systems are virtualizing the compliance documentation function that previously required manual logger downloads and physical record retention. Third-party logistics providers handling biologics shipments for US health systems are adopting these platforms fastest. The technology is virtualizing audit preparation and reducing insurance liability exposure for temperature excursions.
The EU's F-Gas Regulation is restricting hydrofluorocarbon-based refrigeration technologies in transport applications, accelerating investment in solid-state cooling and advanced insulation alternatives. Container manufacturers serving European pharmaceutical distributors must redesign thermal systems around prohibited refrigerant categories. German logistics hubs are responding fastest, with retrofit programs already underway for refrigerated transport fleets.
Group purchasing organizations are consolidating hospital procurement decisions for transport equipment, displacing individual facility purchasing autonomy. Blood banks and academic medical centers in the United States are channeling volume through fewer contracted suppliers with bundled service agreements. This concentration is most visible in the Northeast and Midwest hospital networks, where GPOs now control substantial transport container specification authority.
Medical Transport Box Market Segmentation
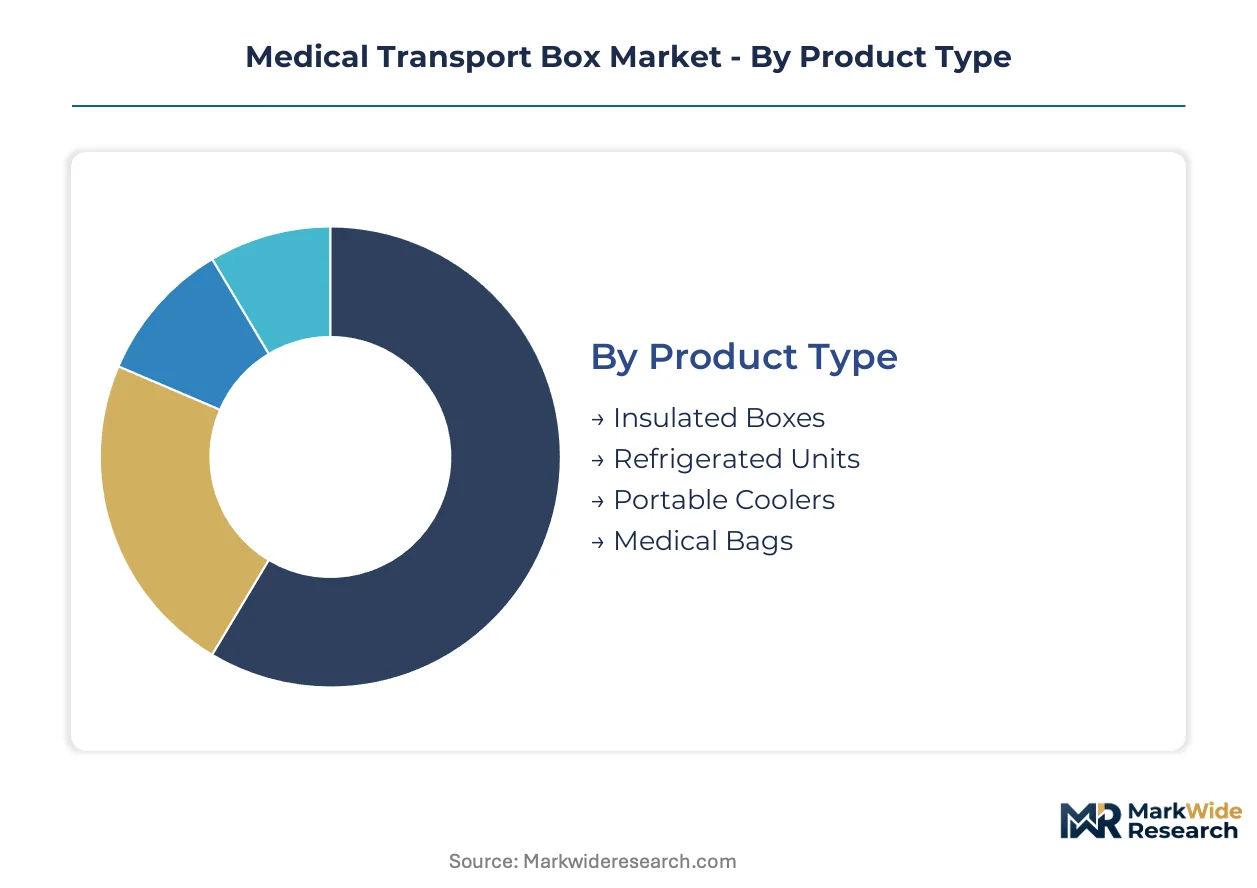
Segmentation in the medical transport box market maps directly to regulatory compliance tiers and thermal performance requirements. Product construction, application criticality, and end-user procurement scale determine pricing architecture and replacement cycles across each category.
Product Type:
Cost tier differentiation separates passive insulation from active refrigeration systems, with capital intensity and operating expense profiles diverging sharply across the four product classes.
- Insulated Boxes:Vacuum-insulated panels or high-density polyurethane foam form the thermal barrier without mechanical cooling. Blood banks in the United States deploy these for short-haul specimen collection where duration stays under 48 hours.
- Refrigerated Units:Compressor-based or thermoelectric active cooling maintains precise setpoints for cell therapy shipments. Germany's expanding biologics logistics networks are concentrating procurement of these units for temperature-critical pharmaceutical distribution.
- Portable Coolers:Lightweight phase-change material systems suit emergency response and field collection protocols. Japan's metropolitan ambulance services are standardizing on these for pre-hospital specimen handling.
- Medical Bags:Soft-sided insulated carriers with gel pack integration serve last-mile delivery and patient-facing applications. Diagnostic sample collection expansion in India is driving volume for CDSCO-compliant bag configurations.
Insulated boxes command the established base. The steepest expansion runs through refrigerated units.
Application:
Application segmentation tracks biological material sensitivity, with thermal tolerance windows narrowing from whole blood to engineered cellular products.
- Blood Transport:Whole blood and component therapy logistics dominate current installed volume. US hospital networks and blood centers operate the largest fleet of validated transport containers for red cell and platelet distribution.
- Organ Preservation:Hypothermic machine perfusion containers and static cold storage units serve transplant logistics. Specialized procurement concentrates at academic medical centers with established transplant programs.
- Vaccine Storage:Ultra-cold and standard cold-chain transport for immunization programs. National distribution infrastructure investments in Japan and Germany are accelerating container standardization for mRNA and conventional vaccine platforms.
- Tissue Transport:Dermal, ocular, and musculoskeletal graft logistics require intermediate temperature maintenance. Tissue bank networks in the United States maintain dedicated container inventories with chain-of-custody documentation systems.
Blood transport anchors current revenue. Organ preservation is climbing the fastest as transplant volumes expand and preservation technology advances.
End User:
Customer type segmentation reveals procurement scale divergence, from enterprise hospital contracts to distributed emergency service deployments.
- Hospitals:Central laboratories and pharmacy operations drive bulk purchasing through group purchasing organization channels. Northeast and Midwest US health systems are consolidating transport equipment specifications under fewer contracted suppliers.
- Blood Banks:Collection, processing, and distribution operations require validated cold-chain integrity. American Red Cross and independent blood center networks are replacing non-compliant containers under FDA thermal-validation pressure.
- Research Labs:Biobanking and clinical trial material logistics demand documented temperature control. Academic medical centers and contract research organizations specify containers with integrated data logging for regulatory submission support.
- Emergency Services:Pre-hospital specimen collection and trauma blood product delivery are expanding fastest. Metropolitan ambulance authorities in the United States are mandating insulated transport units for stroke and sepsis protocol compliance.
Hospitals retain the largest procurement scale. Emergency services are gaining share fastest as field diagnostic protocols proliferate.
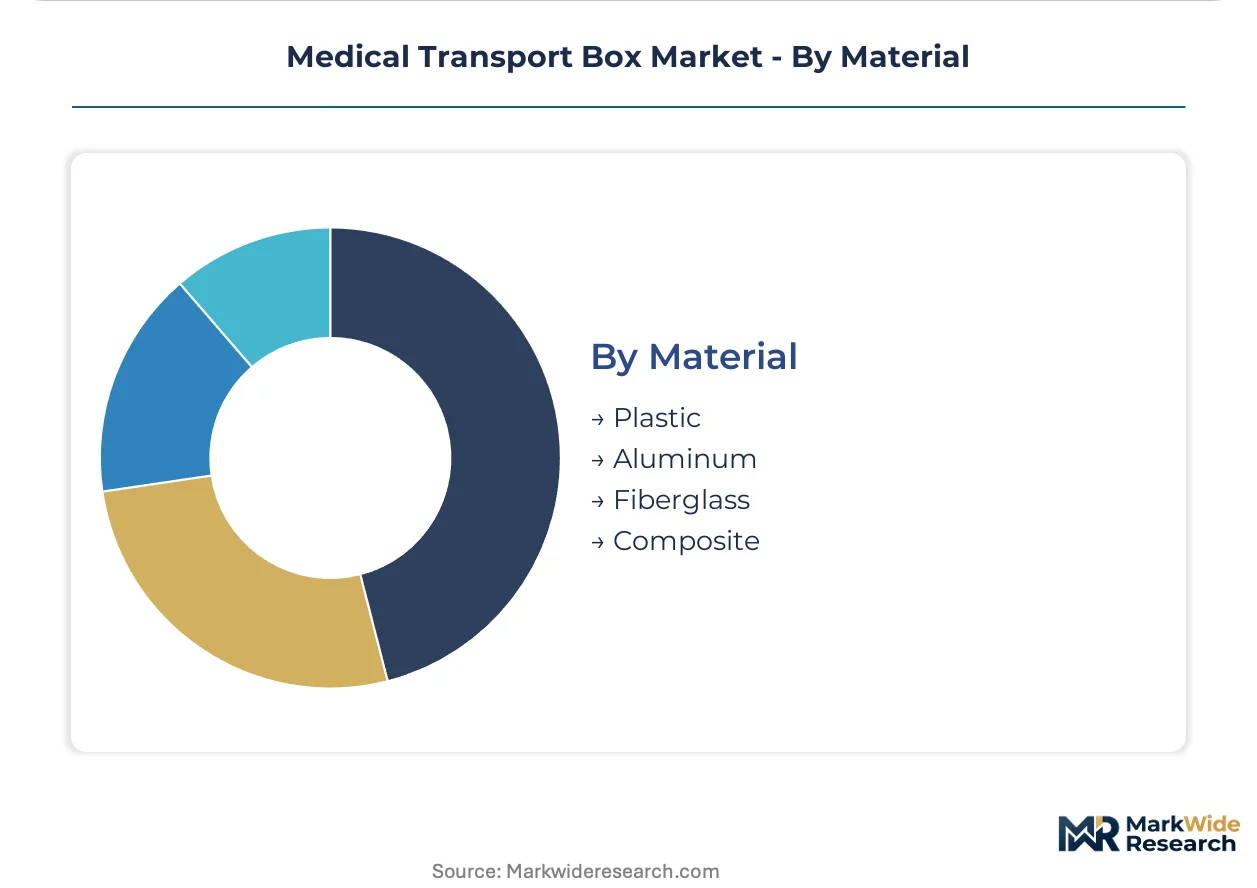
Material:
Supply concentration and manufacturing geography differentiate material selection, with thermal performance, weight, and regulatory compliance driving specification.
- Plastic:Injection-molded polypropylene and polycarbonate shells with foam insulation dominate mass-market production. East Asian manufacturing hubs concentrate supply for cost-sensitive diagnostic transport applications.
- Aluminum:Rolled alloy construction with polyurethane foam cores serves reusable container programs. European pharmaceutical logistics providers favor aluminum for durability in high-frequency rotation systems.
- Fiberglass:Reinforced composite shells offer impact resistance for emergency services and military medical applications. Specialized procurement runs through defense and disaster response supply chains.
- Composite:Carbon fiber and advanced polymer laminates enable lightweight, high-performance thermal envelopes. Premium biologics shipments and cell therapy logistics are concentrating demand for composite-constructed containers.
Plastic holds the volume base. Composite materials are expanding most quickly at the premium tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA thermal-validation mandates and EU GDP compliance frameworks are compressing replacement cycles for transport containers across major pharmaceutical distribution corridors. National biologics logistics investments in the United States, Germany, and Japan are establishing concentrated demand centers for validated cold-chain equipment.
United States
American Red Cross and independent blood center networks are replacing non-compliant containers under FDA pharmaceutical distribution guidelines. The FDA enforces continuous temperature monitoring documentation for cross-state medicinal shipments. Northeast and Midwest hospital networks channel procurement through consolidated group purchasing organization contracts.
Germany
Expanding cell therapy logistics networks generate premium demand for phase-change material containers with integrated data logging. The EU F-Gas Regulation restricts hydrofluorocarbon refrigeration in transport applications, forcing thermal system redesigns. Bavarian and North Rhine-Westphalian logistics hubs operate retrofit programs for refrigerated transport fleets.
Japan
Metropolitan ambulance authorities standardize on portable insulated transport units for pre-hospital specimen collection protocols. PMDA imposes stringent cold-chain documentation standards for imported biologics, accelerating compliance-driven equipment replacement. Tokyo and Osaka biologics distribution clusters concentrate procurement of temperature-validated containers.
India
CDSCO-regulated diagnostic sample collection expansion in tier-2 and tier-3 cities creates demand for validated transport solutions. The country's national pharmaceutical regulator tightens cold-chain requirements for vaccine distribution infrastructure. Maharashtra and Karnataka diagnostic networks represent primary deployment zones for compliant transport bag configurations.
United Kingdom
NHS blood and transplant services maintain dedicated container inventories with chain-of-custody documentation systems. MHRA alignment with EU GDP frameworks mandates temperature documentation for cross-border medicinal shipments. London and Southeast England academic medical centers concentrate specialized procurement for clinical trial material logistics.
Medical Transport Box Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers: diversified laboratory equipment conglomerates, biomedical cold-chain specialists, and temperature-controlled packaging technology leaders. Laboratory equipment conglomerates leverage diagnostic workflow bundling to capture hospital procurement channels. Biomedical cold-chain specialists extend refrigeration expertise into portable transport units. Technology leaders differentiate through phase-change material formulations and digital validation platforms. Dominant competitive moves include strategic partnerships with third-party logistics providers and portfolio diversification into subscription-based container pooling systems.
Among the named participants, Thermo Fisher Scientific exemplifies the laboratory equipment conglomerate archetype through its diagnostic workflow integration capabilities. Haier Group anchors the biomedical cold-chain specialist tier with refrigeration-to-transport vertical extension. Pelican BioThermal occupies a position within the temperature-controlled packaging technology segment, representing phase-change material innovation leadership. These three entities collectively illustrate the strategic positioning vectors that define competitive differentiation in pharmaceutical and diagnostic logistics equipment supply.
| Leading Market Players |
|---|
| Avantor |
| Haier Group |
| Thermo Fisher Scientific |
| BITO-Lagertechnik Bittmann GmbH |
| Nilkamal |
| B Medical Systems |
| SARSTEDT AG & Co. KG |
| Pelican BioThermal |
| Sonoco Products Company |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on East Asian vacuum-insulated panel manufacturers compresses pricing power for European and North American container producers while simultaneously dictating supply chain geography. This input concentration forces tiered pricing spreads between validated FDA-grade units and basic insulated configurations, with procurement lead times becoming the binding constraint for premium refrigerated systems.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA-validated containers commanding substantial premiums over basic CE-marked alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects thermal performance duration, data-logging integration depth, and reuse-cycle durability. Cost compression in the economy tier is intensifying because Indian and Southeast Asian manufacturers are scaling injection-molded plastic production for diagnostic bag applications. Emergency services represent the most price-sensitive buyer segment, while cell therapy logistics operators show minimal sensitivity due to payload value concentration.
Supply Chain Analysis
Extended payment terms from German pharmaceutical logistics providers are reshaping supplier cash-flow structures, with 90-day cycles now standard for refrigerated unit procurement. Manufacturing concentrates in China, South Korea, and Germany, with vacuum-insulated panels and phase-change materials drawing from East Asian chemical processing hubs. Single-source vulnerability runs through specialized PCM formulation suppliers, where thermal degradation patents cluster among three Japanese specialty chemical houses. Distribution runs through third-party logistics providers with cold-chain certification, bypassing traditional medical equipment distributors for direct hospital and blood bank fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-disciplinary expertise combining materials science with multi-jurisdiction regulatory navigation remains concentrated among a narrow specialist cohort, creating acquisition premiums for teams with simultaneous FDA, EMA, and PMDA validation experience.
For Market Incumbents: Pre-empt margin erosion in passive insulation by integrating IoT temperature logging as standard rather than optional, while securing captive supply of phase-change material formulations through backward integration into specialty chemical partnerships. Thermo Fisher Scientific's diagnostic workflow bundling represents the template for displacing standalone container competitors through system-level contracts. For New Entrants and Emerging Players: Pursue CDSCO-compliant transport bag deployment in India's tier-2 and tier-3 diagnostic networks, where cold-chain infrastructure gaps outpace regulatory enforcement capacity. Container-as-a-Service subscription models offer the most penetrable entry angle, bundling hardware with digital chain-of-custody platforms to bypass capital-intensive inventory builds. For Investors and Strategic Acquirers: FDA's updated pharmaceutical distribution guidelines reshape the acquisition landscape by accelerating replacement cycles for non-validated equipment and consolidating procurement through group purchasing organizations. Five-to-ten-year viability favors biomedical cold-chain specialists with vertical control from refrigeration into portable transport, particularly those with established PMDA relationships for Japanese biologics distribution. Watch for EU F-Gas Regulation enforcement intensity as the signal indicating retrofit program scale for refrigerated transport fleets.| Strategic Initiative | Industry Significance |
|---|---|
| Phase-Change Material Patent Licensing | Secures thermal performance differentiation for cell therapy logistics in German distribution hubs. |
| IoT Logger Platform Integration | Virtualizes FDA compliance documentation and reduces insurance liability for temperature excursions. |
| GPO Contract Consolidation | Captures Northeast and Midwest US hospital network procurement through bundled service agreements. |
| CDSCO Validation Pathway Investment | Unlocks tier-2 and tier-3 Indian diagnostic network expansion ahead of regulatory enforcement tightening. |
| Refrigerated Fleet Retrofit Program | Addresses EU F-Gas Regulation compliance for Bavarian and North Rhine-Westphalian logistics operations. |
Methodological Framework
Desk research of FDA guidance documents, EU GDP framework updates, and PMDA cold-chain advisories preceded structured interviews with biomedical cold-chain engineers, hospital GPO contracts managers, blood bank logistics directors, and third-party pharmaceutical distribution executives. Secondary validation drew from customs trade data for vacuum-insulated panel imports, SEC filings of laboratory equipment conglomerates, and CDSCO regulatory circulars. Bottom-up container shipment estimates triangulated against top-down biologics logistics spend projections.
Assumptions held fixed include prevailing FDA thermal-validation enforcement intensity, EU F-Gas Regulation implementation pace, and East Asian vacuum-insulated panel production capacity. Variables tested across the analysis window encompassed cell therapy logistics network expansion rates, emergency services pre-hospital protocol adoption, and Indian diagnostic sample collection infrastructure investment. CAGRs derived from segmented volume modeling across product type, application, end user, and material dimensions, with biologics cold-chain spend and transplant volume growth serving as primary demand-side inputs.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles, cross-border pharmaceutical trade flows, or specialty chemical input costs would shift the trajectory. Forecasts reflect documented assumptions, with regulatory enforcement intensity, technology substitution rates for solid-state cooling, and multi-jurisdiction certification complexity representing specific risk factors that could prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Disposable Masks Market
Medical Supplies
Casting and Splints Market
Medical Supplies
Finger Splint Market
Medical Supplies
Global Contact Lens Solution Market
Medical Supplies
Venipuncture Needles and Syringes Market
Medical Supplies
Single-Use Syringe Market
Medical Supplies
Nitrile Gloves Market
Medical Supplies
Safety Pen Needles Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
Luer Plug Market
Medical Supplies
Compression Socks Market
Medical Supplies
Empty IV Bags Market
Medical Supplies
Suture Tapes Market
Medical Supplies
Serum Separating Tubes Market
Medical Supplies
Asia-Pacific Ostomy Drainage Bags Market
Medical Supplies
GCC Syringes and Needles Market