
 Asia-Pacific Womens Health Diagnostics Market | 2026-2036
Asia-Pacific Womens Health Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Womens Health Diagnostics Market Analytics
Aftermarket service revenue for imaging and molecular diagnostics platforms is tilting toward multi-year maintenance contracts and remote calibration services. Hologic, Inc. leverages its installed base of mammography systems across Japan and Australia to sustain recurring revenue streams. Siemens Healthineers AG anchors its regional position through localized production of ultrasound systems in China. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. competes aggressively on cost while extending its distribution network into India's secondary cities.
Women's health diagnostics encompasses clinical assays, imaging modalities, and molecular tests designed to detect, monitor, and manage conditions specific to female physiology, including reproductive function, hormonal status, and gynecologic malignancies. These systems operate with sensitivity thresholds measured in picograms per milliliter for hormone panels and sub-millimeter spatial resolution for breast imaging, serving the essential purpose of enabling early intervention and personalized treatment pathways. Imaging systems occupy the largest revenue pool across the region, reflecting capital-intensive replacement cycles in hospital radiology departments. Genetic testing represents the fastest-expanding segment, propelled by non-invasive prenatal screening uptake and BRCA testing expansion in South Korea and Singapore. Blood tests maintain stable volume through routine antenatal and menopausal health panels, though margin compression persists in commoditized chemistry assays.
Japan's PMDA and China's NMPA enforce divergent clinical evidence requirements for novel biomarker approvals, fragmenting product registration timelines and inflating compliance costs for multinational manufacturers. India's CDSCO and the BIS medical device rules are tightening quality standards for imported diagnostics, creating market access barriers that favor localized manufacturing partnerships. Stakeholders must monitor regulatory harmonization initiatives between ASEAN member states, as mutual recognition agreements could reshape competitive positioning for instrument and reagent suppliers across Southeast Asian markets.
Market Dynamics
Automated screening platforms are compressing turnaround times for cervical and breast cancer diagnostics across hospital laboratories in China, India, and Southeast Asia. This capital-intensive infrastructure buildout is reshaping competitive positioning toward vendors capable of delivering integrated imaging-to-molecular workflows.
Growth Catalysts
- India's PLI scheme:The production-linked incentive program for medical devices accelerates domestic manufacturing of diagnostic reagents and imaging systems, reducing import dependency for hospital procurement teams.
- Non-invasive prenatal screening uptake:Expanded genetic testing adoption in South Korea and Singapore drives molecular diagnostics volume through private hospital chains and specialized fertility clinics.
- Tier-one city hospital consolidation:China's private healthcare groups deploy centralized women's health screening hubs in Beijing, Shanghai, and Guangzhou, concentrating demand for high-throughput platforms.
Market Restraints
- Regulatory fragmentation:Japan's PMDA and China's NMPA enforce divergent clinical evidence requirements for novel biomarker approvals, inflating compliance costs and extending product registration timelines.
- Reagent import dependency:India's CDSCO and BIS medical device rules tighten quality standards for imported diagnostics, creating supply bottlenecks for laboratories awaiting localized manufacturing partnerships.
- Capital replacement cycles:Imaging systems require 7-10 year depreciation schedules, constraining hospital budget flexibility for platform upgrades despite technological advances.
Strategic Opportunities
- Secondary city penetration:Shenzhen Mindray Bio-Medical Electronics Co., Ltd. extends distribution networks into India's tier-two and tier-three urban centers, accessing underserved patient populations.
- Remote calibration services:Aftermarket revenue tilts toward multi-year maintenance contracts with telemedicine-enabled technical support, reducing field engineer dispatch requirements.
- ASEAN regulatory harmonization:Mutual recognition agreements under negotiation between member states could streamline instrument and reagent approvals across Southeast Asian markets.
Industry Challenges
- Skilled cytotechnologist shortage:Pap smear and liquid-based cytology analysis requires specialized training that outpaces educational program output in Vietnam and Indonesia.
- Legacy system integration:Hospital information systems in older Japanese and Australian facilities resist seamless connectivity with cloud-based diagnostic platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Womens Health Diagnostics Market |
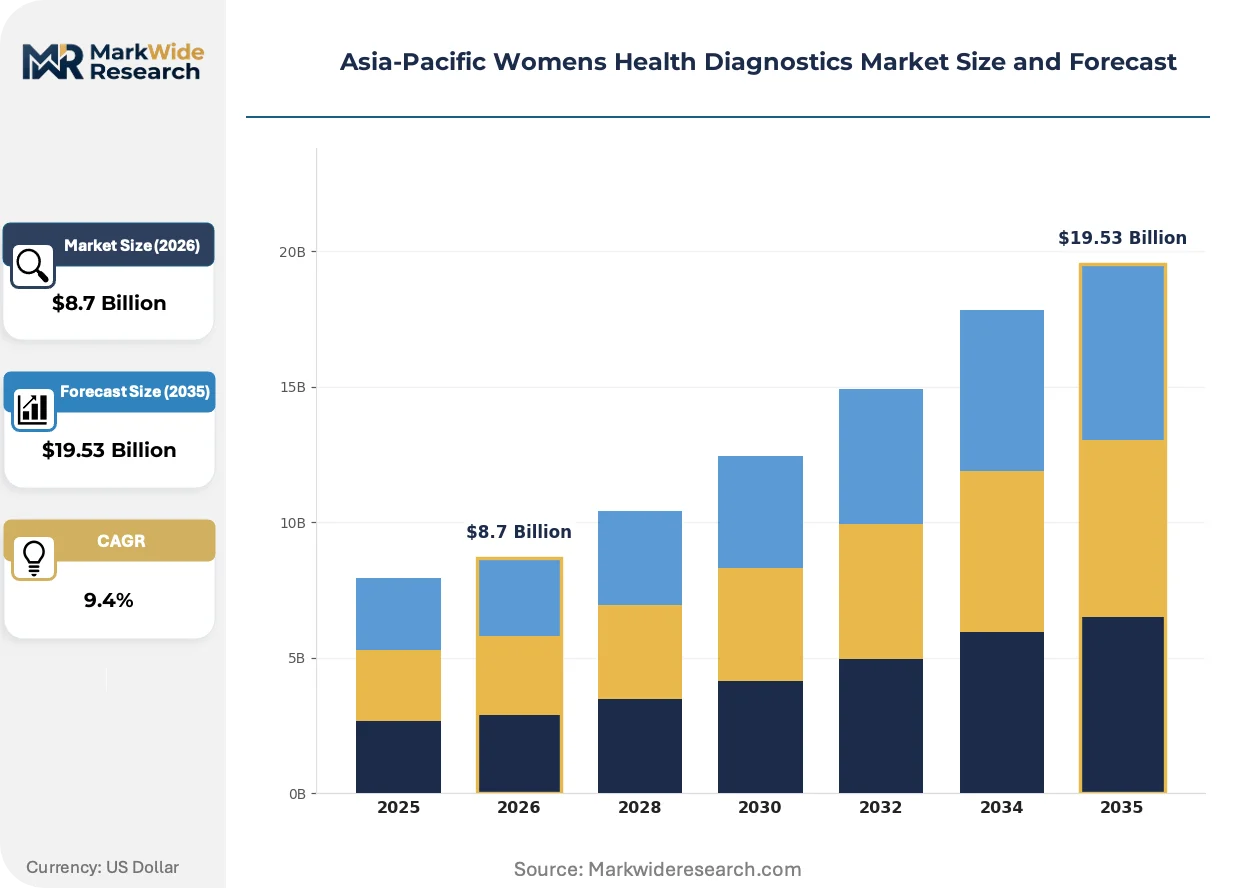
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging, Blood Tests, Genetic Testing, Urinalysis Technology: ELISA, PCR, Lateral Flow Assays, Mass Spectrometry Application: Reproductive Health, Infectious Diseases, Hormonal Disorders, Cancer Detection End User: Hospitals, Clinics, Diagnostic Laboratories, Home Care |
| Companies Covered | Hologic, Inc., F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, Abbott, BD, Quest Diagnostics Incorporated, GE HealthCare, Koninklijke Philips N.V., Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Womens Health Diagnostics Market Evolving Landscape
Digital pathology and artificial intelligence are converging with molecular diagnostics to redefine screening accuracy and operational throughput. These technological layers are compressing the traditional separation between imaging interpretation and biomarker quantification.
Digital breast tomosynthesis is hybridizing with synthetic mammography reconstruction algorithms to reduce false-positive recall rates. Large private hospital chains in China's eastern provinces adopt these systems at replacement-cycle pace. The technology is hybridizing radiologist workflow by collapsing diagnostic steps that previously required separate equipment and specialist consultations.
China's NMPA tightened clinical trial data requirements for AI-assisted diagnostic software in 2023, mandating prospective validation studies for algorithm approvals. This policy compresses the competitive set to vendors with sufficient capital for multi-site trials. High-complexity molecular assays face the steepest compliance burden, favoring established manufacturers over emerging entrants.
After-sales service unbundling is fragmenting traditional equipment procurement models. Hospital procurement teams in Australia and Japan now separate hardware acquisition from maintenance contracts and software subscriptions. This behavioral shift concentrates negotiating leverage with group purchasing organizations while pressuring vendor margin structures in the region's most mature markets.
Asia-Pacific Womens Health Diagnostics Market Segmentation
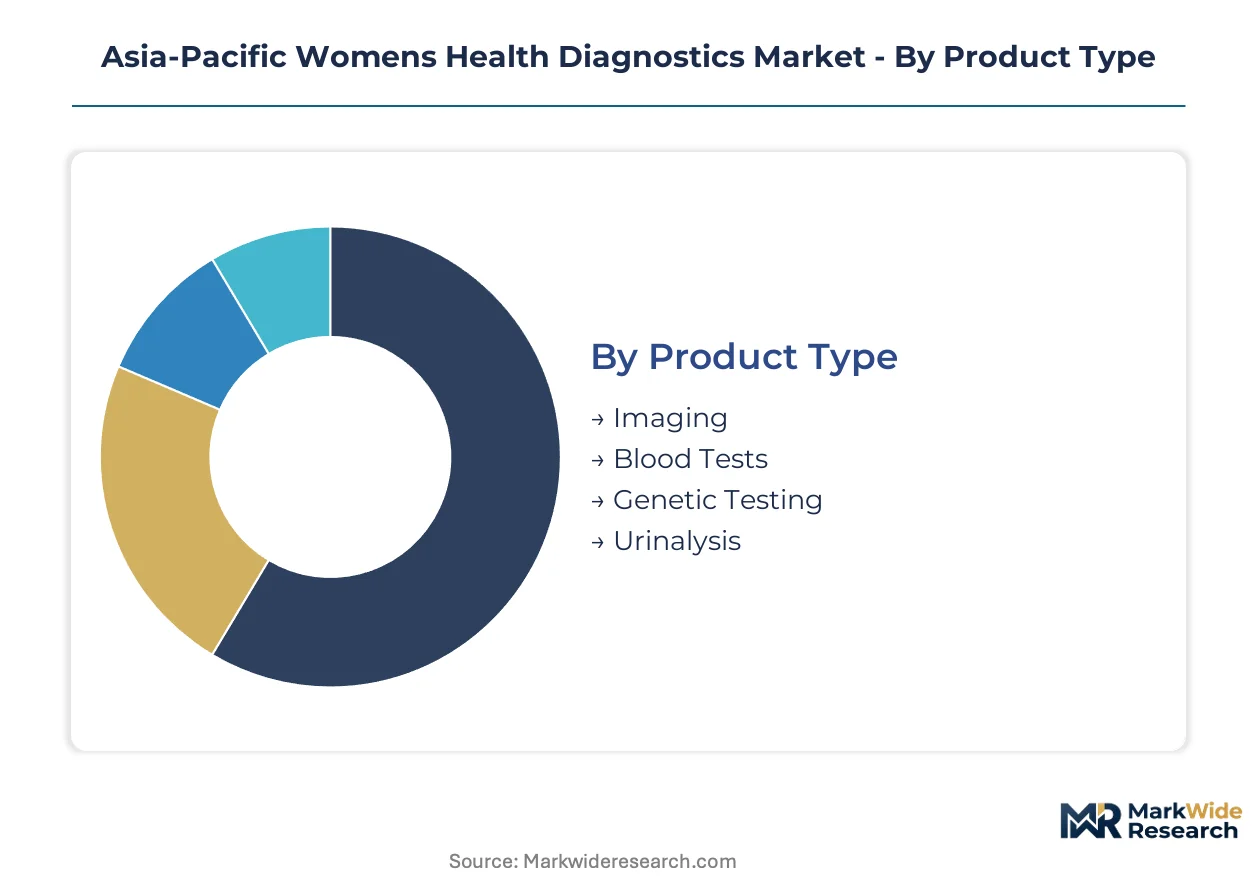
Segmentation in Asia-Pacific women's health diagnostics reveals distinct service intensity profiles across product categories. Imaging platforms demand multi-year maintenance contracts and remote calibration infrastructure, while molecular assays concentrate reagent supply negotiations with hospital procurement teams.
Product Type:
After-sales service intensity varies sharply across product categories, with imaging systems requiring field engineer networks and genetic testing platforms demanding continuous reagent supply contracts.
- Imaging:Capital-intensive modalities including mammography, ultrasound, and MRI systems operate with sub-millimeter spatial resolution thresholds. China's private hospital chains in Beijing and Shanghai deploy automated screening hubs that compress radiologist workflow through integrated reconstruction algorithms. Service contracts typically span 7-10 year depreciation cycles with remote calibration capabilities.
- Genetic Testing:Non-invasive prenatal screening and BRCA panels operate at the molecular level with high sensitivity thresholds. South Korea and Singapore drive volume through specialized fertility clinics and private hospital chains seeking expanded reproductive health portfolios. Reagent supply agreements dominate vendor relationships more than equipment maintenance.
- Blood Tests:Routine antenatal and menopausal hormone panels sustain stable laboratory volume. Chemistry assays face margin compression in commoditized segments across Indian hospital networks.
- Urinalysis:Point-of-care and laboratory-based systems serve pregnancy confirmation and metabolic screening. Deployment concentrates in China's tier-one city clinic networks.
By volume, imaging leads. By growth pace, genetic testing is ahead.
Technology:
Technology selection determines capital deployment patterns and consumables economics, with ELISA and PCR platforms anchoring distinct customer segments.
- ELISA:Enzyme-linked immunosorbent assays quantify hormone panels with picogram-per-milliliter sensitivity for thyroid, fertility, and menopausal health monitoring. Indian hospital laboratories expand ELISA infrastructure under PLI scheme incentives for domestic reagent manufacturing.
- PCR:Polymerase chain reaction enables high-complexity molecular detection for HPV genotyping and infectious disease screening. China's NMPA tightened clinical trial requirements for high-complexity assays, favoring established manufacturers with multi-site validation capabilities.
- Lateral Flow Assays:Rapid diagnostic strips serve pregnancy testing and infectious disease screening at point-of-care. Cost positioning enables penetration into India's secondary cities.
- Mass Spectrometry:High-resolution detection supports steroid profiling and vitamin D quantification in reference laboratories. Adoption concentrates in Japan's advanced hospital networks.
By installed base, ELISA dominates. By capability expansion, PCR shows the steepest trajectory.
Application:
Application focus shapes regulatory pathway complexity and reimbursement negotiations across Asia-Pacific jurisdictions.
- Cancer Detection:Cervical and breast cancer screening programs drive molecular testing and imaging replacement cycles. Australia's public health infrastructure maintains mature screening registries with defined recall protocols.
- Reproductive Health:Fertility assessment and prenatal screening concentrate demand in private healthcare networks. Singapore's specialized clinics anchor regional adoption of expanded carrier screening panels.
- Infectious Diseases:STI and TORCH panels sustain routine laboratory volume through antenatal protocols. Southeast Asian markets show diagnostic infrastructure gaps in Vietnam and Indonesia.
- Hormonal Disorders:Thyroid and metabolic panels serve menopausal health management across aging demographics. Japan's hospital networks maintain stable demand for endocrine monitoring.
Cancer detection commands the highest per-test revenue. Reproductive health is expanding most quickly.
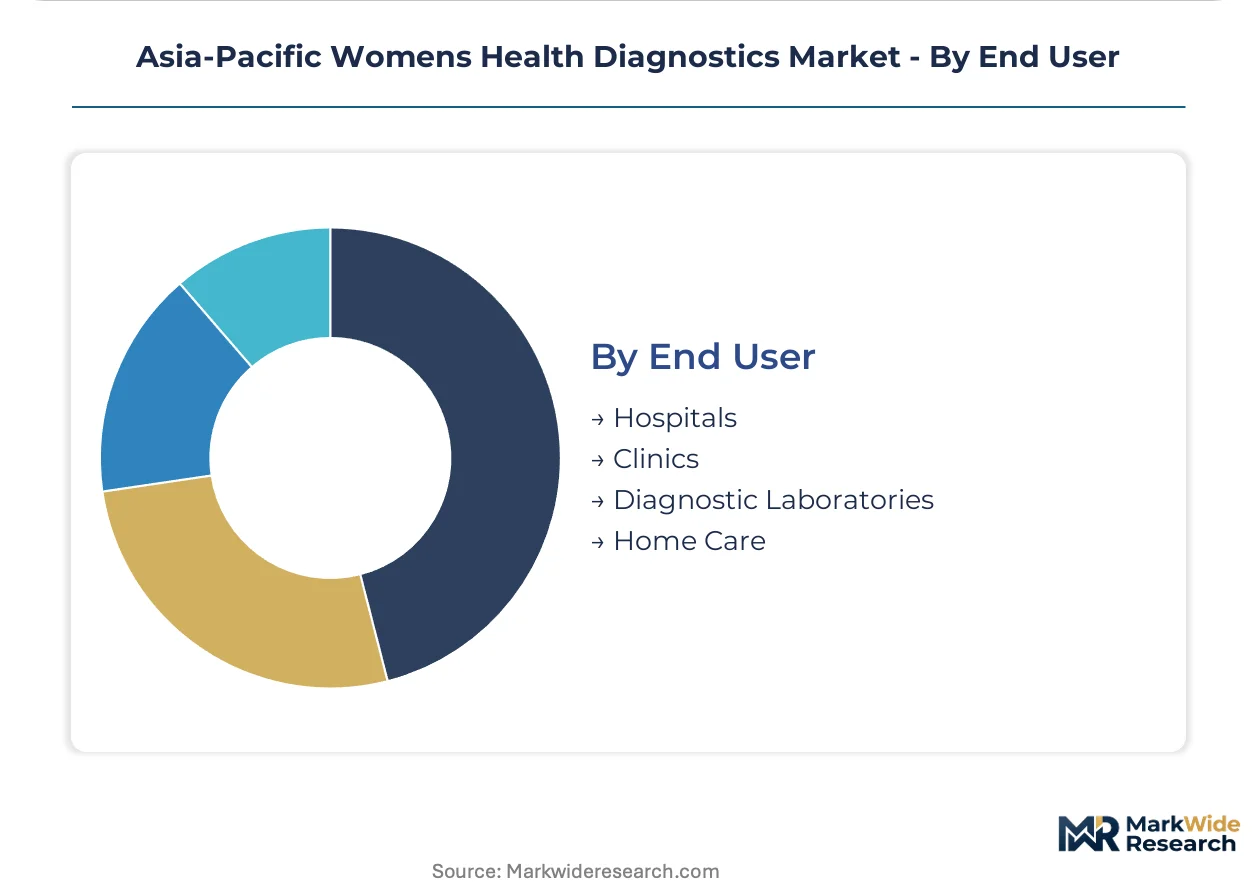
End User:
End-user category determines procurement authority structures and platform specification requirements.
- Hospitals:Integrated health systems deploy centralized women's health screening hubs with automated workflow platforms. China's private hospital chains in Guangzhou and Shenzhen concentrate capital deployment for competitive differentiation.
- Diagnostic Laboratories:Independent reference labs aggregate high-complexity molecular testing volume across multiple hospital clients. India's CDSCO quality standards for imported reagents create supply bottlenecks awaiting localized manufacturing partnerships.
- Clinics:Outpatient facilities favor point-of-care and rapid diagnostic platforms with minimal infrastructure requirements. Australia's general practice networks integrate women's health screening into primary care workflows.
- Home Care:Self-testing devices serve fertility tracking and pregnancy confirmation in privacy-sensitive segments. Distribution runs through pharmacy retail and direct-to-consumer channels in South Korea's digital health ecosystem.
Hospitals anchor capital expenditure. Diagnostic laboratories capture the fastest volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the region, with India's secondary cities demanding cost-optimized platforms while Japan's hospital networks absorb premium imaging systems without procurement friction.
China
Private hospital chains in Beijing and Shanghai deploy centralized screening hubs with automated mammography-to-molecular workflows. NMPA tightened clinical trial requirements for AI-assisted diagnostic software in 2023, mandating prospective validation studies. The Yangtze River Delta concentration around Shanghai anchors high-throughput platform adoption for competitive differentiation among healthcare groups.
Japan
Aging demographics sustain stable demand for endocrine monitoring and cancer screening programs. PMDA enforces stringent clinical evidence requirements for novel biomarker approvals that fragment product registration timelines. The Kanto region surrounding Tokyo maintains mature hospital infrastructure with defined recall protocols for breast and cervical cancer registries.
India
Hospital laboratories expand molecular testing infrastructure for cervical and breast cancer screening under aggressive volume targets. CDSCO and BIS medical device rules tighten quality standards for imported diagnostics, creating supply bottlenecks. Maharashtra and Karnataka host expanding domestic manufacturing of diagnostic reagents under PLI scheme incentives.
South Korea
Specialized fertility clinics drive expanded carrier screening panel adoption for reproductive health portfolios. The national pharmaceutical regulator maintains structured pathways for genetic test approvals that favor established validation capabilities. Seoul Capital Area concentrates private healthcare investment in non-invasive prenatal screening infrastructure.
Australia
Public health infrastructure maintains mature screening registries with defined recall protocols for cervical and breast cancer detection. TGA oversight shapes diagnostic platform specifications for hospital procurement. New South Wales and Victoria anchor regional adoption of digital pathology and AI-assisted interpretation systems.
Asia-Pacific Womens Health Diagnostics Market Competitive Landscape
Capability concentration sits with integrated imaging-to-molecular workflow vendors; scale advantage sits with diversified medical technology conglomerates. The market structure tilts toward tiered competition where premium-tier players anchor recurring revenue through installed base maintenance contracts while mid-tier competitors penetrate price-sensitive segments through distribution depth. Three archetypes dominate: integrated platform specialists, regional cost-optimized manufacturers, and service-intensive incumbents. M&A activity concentrates on molecular assay capabilities, while geographic expansion targets India's secondary cities and Southeast Asian growth corridors.
Within the integrated platform tier, Hologic, Inc. and Siemens Healthineers AG exemplify vendors sustaining recurring revenue through installed base leverage and localized production strategies. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. occupies a position representing regional cost-optimized competition with distribution network extension into underserved urban centers. These three anchors illustrate the competitive tension between premium workflow integration and accessible platform economics across the region's heterogeneous procurement environments.
| Leading Market Players |
|---|
| Hologic, Inc. |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers AG |
| Abbott |
| BD |
| Quest Diagnostics Incorporated |
| GE HealthCare |
| Koninklijke Philips N.V. |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Maharashtra and Karnataka manufacturing clusters anchor domestic reagent production capacity under India's PLI scheme, compressing landed costs for hospital procurement teams while elevating pricing power for localized suppliers against import-dependent competitors. This geographic concentration of diagnostic manufacturing feeds directly into tiered procurement negotiations across public and private health systems.
Pricing Analysis
Multi-year maintenance contracts and remote calibration services drive lifetime value for imaging platform vendors. Three-tier pricing structure across premium, standard, and economy levels separates integrated workflow systems from modular equipment and refurbished installations. Cost compression in economy-tier reagents is intensifying because of domestic chemistry assay manufacturing expansion. Public hospital networks in India and Southeast Asia exhibit highest price sensitivity; private hospital chains in China's tier-one cities absorb premium positioning without procurement friction.
Supply Chain Analysis
Tariff exposure between China and key export markets for AI-assisted diagnostic software dominates supply chain risk calculations for multinational vendors. Component manufacturing concentrates in China, Germany, and Japan for imaging system assemblies. Reagent production draws from India, China, and South Korea for molecular assay inputs. Single-source vulnerability persists for specialized optical sensors and rare-earth magnet components in MRI systems. Distribution runs through hospital group purchasing organizations in mature markets and direct field sales networks in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific women's health diagnostics market rewards vendors who control scarce capabilities in integrated imaging-to-molecular workflows and regulatory navigation across fragmented approval pathways. Success hinges on securing specialized talent pools and validation infrastructure that outpaces educational program output.
For Market Incumbents: Build installed base moats through predictive maintenance platforms and embedded software subscriptions that increase switching costs for hospital radiology departments. Deepen reagent supply agreements with diagnostic laboratories to lock in consumables revenue streams. Counter emerging cost-optimized competitors by accelerating AI-assisted interpretation capabilities ahead of NMPA tightening. Anchor capacity addition in India's PLI-eligible zones to neutralize import dependency vulnerabilities. For New Entrants and Emerging Players: Build out distribution infrastructure in India's tier-two and tier-three urban centers where hospital laboratory expansion outpaces established vendor coverage. Target reproductive health applications in Vietnam and Indonesia where skilled cytotechnologist shortages create demand for automated screening platforms. Penetrate through point-of-care and rapid diagnostic formats requiring minimal capital infrastructure. Partner with local distributors possessing existing hospital procurement relationships rather than building direct sales organizations. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because diagnostic platforms generate decade-long consumables streams and maintenance contracts that compound customer lifetime value. Acquisition targets should demonstrate regulatory approval momentum across multiple Asia-Pacific jurisdictions and established reagent supply contracts with hospital networks. Watch NMPA and PMDA harmonization negotiations as the signal for competitive consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | Early NMPA engagement accelerates AI-assisted software market access ahead of competitors. |
| Hospital System Partnership | Exclusive reagent supply agreements with private chains in Guangzhou lock in volume commitments. |
| Software Companion Development | Cloud-based pathology platforms overcome legacy HIS integration resistance in Japanese facilities. |
| Backward Integration | In-house reagent manufacturing under PLI scheme shields margins from CDSCO import bottlenecks. |
| Geographic Expansion | Secondary city penetration in India accesses patient populations underserved by premium-tier vendors. |
Research Methodology
A standing panel of hospital procurement managers, biomedical engineers, GPO contracts specialists, and clinical laboratory directors provided ongoing calibration against operating reality throughout the research process. Primary interviews across these stakeholder roles combined with secondary validation from NMPA filings, PMDA approval databases, CDSCO medical device registrations, and hospital procurement contract repositories. Bottom-up volume modeling and top-down market sizing triangulated to convergence.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation dimensions spanning product type, technology platform, application focus, and end-user category. CAGRs derived from installed base expansion rates, replacement cycle timing, and consumables attach ratios. Industry-specific inputs incorporated PLI scheme incentive trajectories, regulatory approval pipeline visibility, and reimbursement pathway evolution across national health systems.
Stress conditions across regulatory harmonization timelines, domestic manufacturing scale-up velocity, and capital expenditure cycles in hospital infrastructure were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology adoption curves and procurement authority shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Animal Auto-Immune Disease Diagnostics Market
Diagnostics
Global Oral Cancer Rapid Test Kit Market
Diagnostics
Blood Urea Nitrogen Diagnostics Market
Diagnostics
Canada Latent Tuberculosis Infection Detection Market
Diagnostics
Japan in-Vitro Diagnostics Market
Diagnostics
Clostridium Diagnostics Market
Diagnostics
Global Hemoglobin A1c Testing Devices Market
Diagnostics
North America Syndromic Multiplex Diagnostic Market
Diagnostics
Asia-Pacific Molecular Diagnostics Market
Diagnostics
Middle East and Africa HIV Diagnosis and Treatment Market
Diagnostics
North America Point of Care Diagnostics Market
Diagnostics
Diagnostic Reagents Market
Diagnostics
North America Breast Cancer Screening Tests Market
Diagnostics
Infectious Respiratory Disease Diagnostics Market
Diagnostics
Fertility Testing Devices Market
Diagnostics
Diagnostic Exosome Biomarkers Market