
 US Tissue Diagnostics Market | 2026-2036
US Tissue Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
US Tissue Diagnostics Market Intelligence
The capital-intensity gap between integrated digital pathology system development and high-volume consumable manufacturing is redrawing the competitive landscape. Roche Diagnostics leverages its extensive portfolio in digital pathology and automated staining systems. Thermo Fisher Scientific competes through its broad offering of specialized reagents and molecular probes. Danaher Corporation differentiates with its life sciences and diagnostics platforms, covering multiple workflow stages.
US tissue diagnostics involves the microscopic analysis of cellular and tissue samples to identify disease markers. The process includes specimen preparation using instruments like microtomes and the application of specific biological markers for visualization. Cancer detection remains the primary application, driving volume for both histopathology stains and advanced immunohistochemistry reagents. Within end-user segments, large diagnostic laboratories and hospital pathology labs constitute the core customer base for these technologies.
The US market operates under strict regulatory oversight from the Food and Drug Administration (FDA), which classifies instruments and reagents as medical devices. Concurrently, Clinical Laboratory Improvement Amendments (CLIA) standards dictate the operational and quality requirements for diagnostic laboratories performing these tests. Navigating the reimbursement pathways for novel digital pathology and AI-driven diagnostic tools is a critical focus for market participants.
Market Dynamics
The central force shaping the US tissue diagnostics market is the convergence of high-throughput digital scanning with AI-powered image analysis. This combination is fundamentally altering pathology workflows, moving the field from a qualitative, manual discipline toward a quantitative, data-driven science, directly impacting diagnostic speed and accuracy.
Growth Catalysts
- AI-Powered Analytics:The integration of artificial intelligence and machine learning algorithms into digital pathology platforms accelerates image analysis for applications in oncology. These tools assist pathologists in identifying, counting, and classifying cells, which improves diagnostic consistency and turnaround times in high-volume laboratories.
- Oncology Test Volume:A persistent rise in cancer incidence and the expanding use of companion diagnostics to guide targeted therapies are major catalysts. This drives demand for both routine histopathology and advanced immunohistochemistry (IHC) tests, forming the core revenue base for consumables and instruments.
- FDA Digital Health Policy:The Food and Drug Administration's evolving policies, including clearer pathways for Software as a Medical Device (SaMD), encourage investment and innovation. Regulatory clarity for digital pathology systems and AI algorithms lowers market entry barriers for developers.
Market Restraints
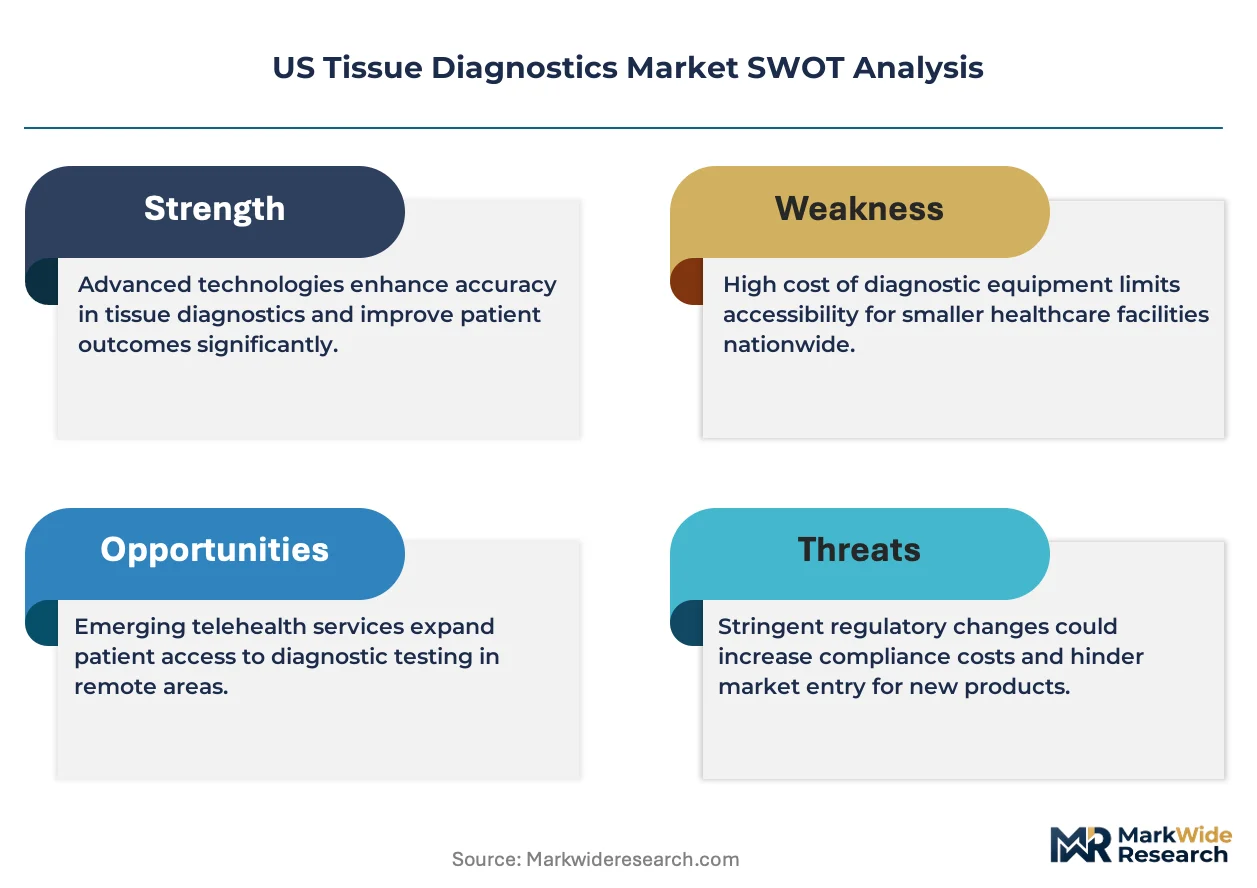
- High Capital Investment:The upfront cost of acquiring and implementing a complete digital pathology system, including whole-slide scanners, image management software, and high-capacity data storage, presents a significant barrier for smaller laboratories and community hospitals in the US.
- Reimbursement Complexity:Navigating reimbursement for novel diagnostic tests, particularly for digital and AI-assisted pathology, is a major restraint. Securing appropriate CPT codes and convincing payers of the clinical and economic value can be a prolonged and resource-intensive process for manufacturers and labs.
- Interoperability Standards:A lack of universal standards for digital slide formats and communication protocols hinders interoperability between systems from different vendors. This fragmentation complicates data sharing and can lock laboratories into a single supplier's ecosystem, limiting flexibility.
Strategic Opportunities
- Telepathology for Underserved Areas:Digital pathology platforms create a significant opportunity to provide telepathology services, connecting specialists at major medical centers with rural and remote hospitals. This model addresses regional shortages of subspecialty pathologists and improves access to expert consultations.
- Multiplex Assay Development:There is a growing opportunity in the development and commercialization of multiplexed assays, such as multiplex immunofluorescence. These advanced tests allow for the simultaneous analysis of numerous biomarkers on a single tissue sample, maximizing data from small biopsies.
- Expansion into Non-Oncology Fields:While oncology dominates, there is white space for applying tissue diagnostics in other disease areas. Expanding applications in neurology, immunology, and infectious disease diagnostics represents a key avenue for market diversification and growth.
Industry Challenges
- Pathologist and Technologist Skill Gaps:A critical challenge is the shortage of pathologists and histotechnologists with expertise in digital pathology, image analysis, and bioinformatics. The transition from glass slides to digital workflows requires significant training and a new set of technical skills across the laboratory workforce.
- Legacy System Integration:Integrating new digital pathology platforms with existing hospital IT infrastructure, particularly Laboratory Information Systems (LIS) and Electronic Health Records (EHR), is a complex technical hurdle. Ensuring seamless data flow and maintaining data integrity is a primary operational concern.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Tissue Diagnostics Market |
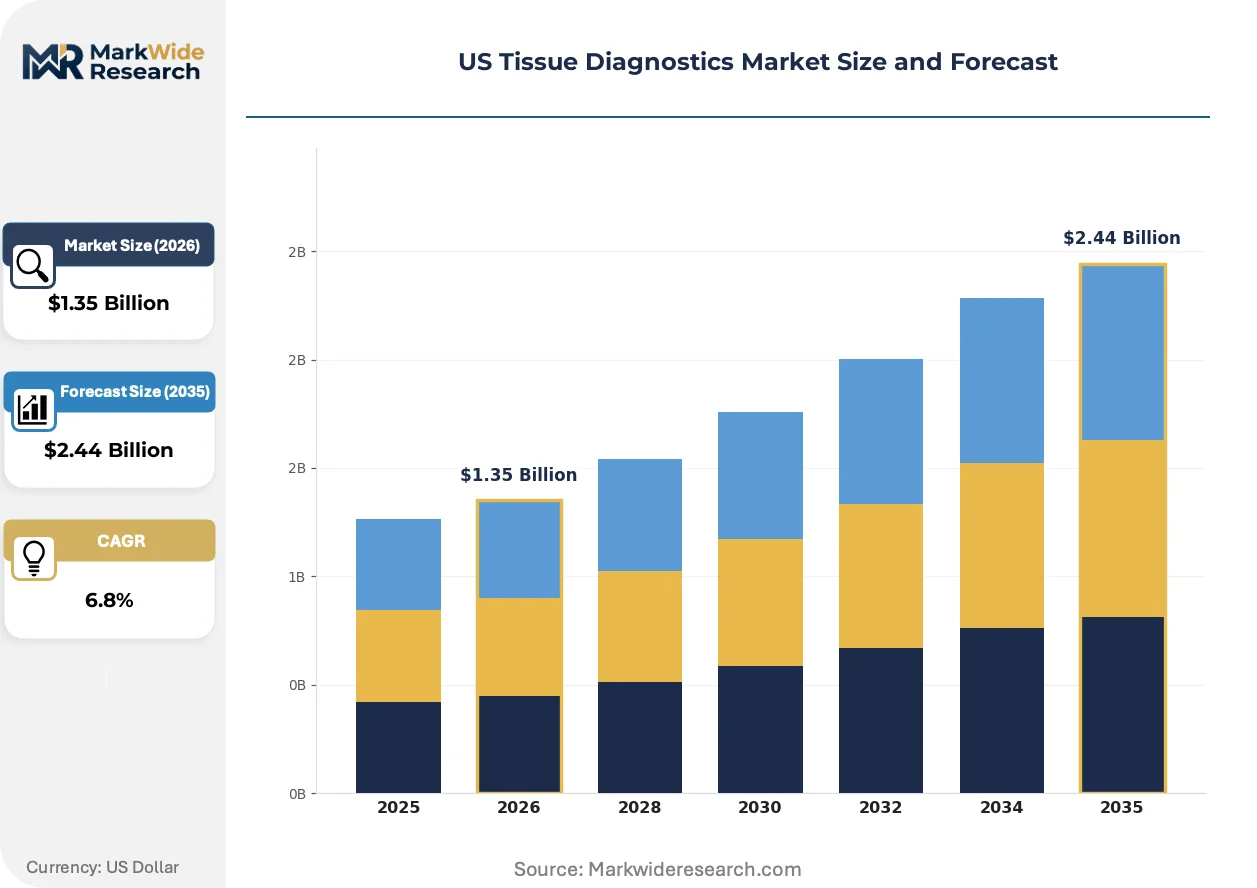
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.44 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Histopathology Stains, Immunohistochemistry Reagents, Molecular Probes, Digital Slide Scanners, Microtomes Application: Cancer Detection, Infectious Disease Analysis, Genetic Disorder Identification, Biomarker Research, Drug Development End User: Diagnostic Laboratories, Research Institutes, Biotechnology Companies, Pathology Labs, Academic Centers Distribution Channel: Direct Sales, Distributors, Online Platforms, Hospital Supply Chains, Specialty Retailers |
| Companies Covered | Roche Diagnostics, Danaher Corporation, Thermo Fisher Scientific, Abbott Laboratories, Siemens Healthineers, Agilent Technologies, Merck KGaA, QIAGEN, Becton, Dickinson & Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Tissue Diagnostics Market Strategic Shifts & Innovations
The US tissue diagnostics field is transitioning from subjective microscopic evaluation to automated, quantitative analysis. This shift is driven by technologies that extract more objective data from tissue samples, improving diagnostic precision and enabling the development of more personalized therapies, particularly in oncology.
Multiplex immunofluorescence (mIF) technology enables the simultaneous detection and spatial analysis of numerous protein biomarkers within a single tissue section. Research-focused institutions and contract research organizations in the US are leading adoption for complex tumor microenvironment studies. This multi-marker capability is supplanting traditional single-plex immunohistochemistry, providing a far richer dataset from limited biopsy material and accelerating translational research.
Establishment of clearer regulatory pathways by the FDA for AI and machine learning-based Software as a Medical Device (SaMD) is a pivotal trend. This guidance provides a more predictable process for developers seeking clearance for analytical tools that support pathologists. Consequently, digital pathology vendors and specialized AI firms are accelerating the validation and launch of algorithms for tasks like tumor grading and biomarker quantification in the US clinical market.
A pronounced shift toward value-based purchasing is altering how large US hospital networks procure diagnostic platforms. Decision-making criteria now extend beyond the per-test cost to include a technology's impact on reducing downstream medical expenses or improving patient outcomes. This change is most evident in integrated delivery networks, particularly in states like Massachusetts, where providers and payers are collaborating to control total healthcare costs.
US Tissue Diagnostics Market Segmentation
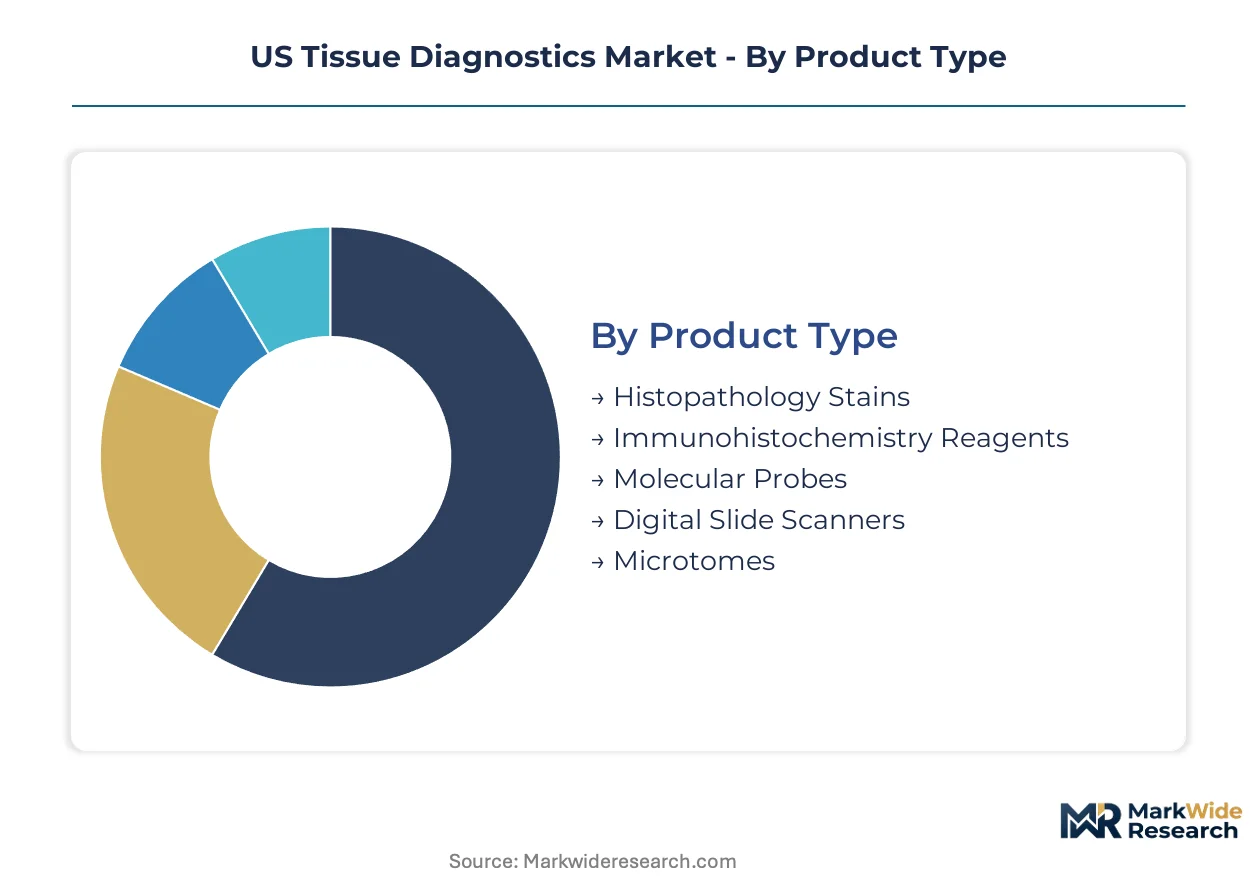
Understanding the segmentation of the US tissue diagnostics market is crucial for identifying distinct customer needs and strategic investment areas. This analysis categorizes the market by product type, application, end user, and distribution channel, revealing varied growth dynamics and competitive landscapes across each segment.
Product Type:
The product types in the US tissue diagnostics market flow through diverse distribution channels, from specialized direct sales to broader hospital supply chains.
- Histopathology Stains:These are chemical dyes and reagents utilized for microscopic visualization of tissue morphology, providing fundamental diagnostic information. Demand for these basic consumables remains consistently high across US diagnostic laboratories for routine cancer screening and diagnosis.
- Immunohistochemistry Reagents:These are antibody-based reagents that specifically bind to target antigens within tissue samples, enabling precise biomarker detection and characterization. Oncology applications in US hospital pathology labs drive significant demand for these advanced diagnostic tools, particularly for personalized medicine.
- Molecular Probes:Genetic sequences or antibodies used to detect specific DNA, RNA, or protein targets within tissue, primarily for advanced cancer diagnostics and genetic testing in the US.
- Digital Slide Scanners:Automated imaging systems that convert glass slides into high-resolution digital images, enabling remote pathology consultations and AI integration in US laboratories.
- Microtomes:Precision instruments used to cut extremely thin tissue sections from paraffin blocks, representing a fundamental step in tissue preparation for all US pathology labs.
By volume, Histopathology Stains lead the segment. By growth pace, Digital Slide Scanners are ahead.
Application:
Applications within US tissue diagnostics vary significantly in their complexity and associated cost tiers, from routine screening to highly specialized analyses.
- Cancer Detection:This represents the primary application, involving the identification and classification of various cancer types through morphological and molecular analysis of tissue. This application drives the largest volume of tests in US diagnostic laboratories, supported by increasing incidence rates nationwide.
- Biomarker Research:This involves the identification and validation of novel biological indicators for disease diagnosis, prognosis, or therapeutic response using tissue samples. US research institutes and biotechnology companies are heavily invested in this area, pushing the boundaries of personalized medicine development.
- Infectious Disease Analysis:Detection of pathogens and host responses within tissue samples, crucial for diagnosing infections like viral hepatitis or tuberculosis in US clinical settings.
- Genetic Disorder Identification:Analysis of tissue to identify chromosomal abnormalities or gene mutations, primarily used in prenatal diagnostics and rare disease studies across US academic centers.
- Drug Development:Utilizing tissue diagnostics to assess drug efficacy, toxicity, and mechanism of action during preclinical and clinical trials for pharmaceutical companies in the US.
The dominant application is Cancer Detection, while Biomarker Research is experiencing rapid expansion.
End User:
End users in the US tissue diagnostics market exhibit diverse operational scales and testing volumes, from high-throughput commercial labs to specialized academic research facilities.
- Diagnostic Laboratories:These include commercial and reference laboratories performing a broad range of tissue tests for external clients, processing high volumes of samples daily. These labs form the core customer base for instruments and reagents across the United States healthcare system.
- Pathology Labs:These are departments within hospitals or independent practices focused on microscopic examination of tissues and cells for disease diagnosis and patient management. These labs are critical for direct patient care and directly utilize a wide array of tissue diagnostic products in the US healthcare system.
- Research Institutes:Organizations focused on scientific inquiry and discovery, frequently utilizing advanced tissue diagnostic techniques for basic and translational research in the US.
- Biotechnology Companies:Firms developing and commercializing novel diagnostic assays and therapeutics, often employing tissue diagnostics for product development and validation in the US.
- Academic Centers:University-affiliated institutions combining patient care, research, and education, integrating tissue diagnostics into their multidisciplinary activities across the US.
Growth in this segment is primarily driven by Diagnostic Laboratories, and Research Institutes demonstrate significant potential.
Distribution Channel:
Distribution channels for US tissue diagnostics span various levels of maturity, from established direct sales models to newer online platforms.
- Direct Sales:Manufacturers sell products directly to end-users, facilitating specialized technical support and direct customer relationships crucial for complex instruments and high-value reagents. This channel is critical for maintaining strong market presence in the US market.
- Distributors:Third-party companies resell products from multiple manufacturers to a broad customer base, offering logistical support and broader market reach. Distributors play a vital role in reaching smaller laboratories and regional hospitals across the United States.
- Hospital Supply Chains:Integrated procurement and logistics networks within large hospital systems, managing the acquisition and delivery of diagnostic products for their internal pathology labs in the US.
- Online Platforms:E-commerce websites and digital marketplaces facilitating the sale of diagnostic reagents and consumables, gaining traction for standardized products among US research buyers.
- Specialty Retailers:Niche outlets focusing on specific diagnostic product categories or serving particular scientific communities in the US, offering curated selections and expert advice.
The dominant channel for high-value products is Direct Sales, while Online Platforms are expanding their reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US tissue diagnostics market exhibits a varied consumption mix, with certain states demonstrating higher demand for advanced digital and AI-driven solutions compared to others. This differential reflects regional disparities in healthcare infrastructure, research funding, and the concentration of specialized medical facilities. States with robust biotech ecosystems often prioritize innovative diagnostic tools.
California
California's market for tissue diagnostics benefits from extensive biotechnology investment and a high volume of cancer research. The state's stringent HIPAA regulations necessitate robust data security for digital pathology systems. Major academic medical centers in San Francisco and San Diego drive demand for multiplex assays and advanced biomarker research.
Massachusetts
Massachusetts presents a strong demand for integrated digital pathology systems, supported by its concentration of leading academic hospitals and research institutes. The FDA's evolving digital health policy encourages innovation among local tech and biotech firms. The Greater Boston area is a hub for AI-powered diagnostic tool development and adoption.
New York Metro
The New York Metro area, with its dense population and numerous large hospital networks, drives significant volume for routine histopathology stains and immunohistochemistry reagents. CLIA standards ensure consistent quality across the region's diverse diagnostic laboratories. Academic institutions like those in New York City are actively integrating telepathology services.
Texas
Texas shows a growing demand for tissue diagnostics, particularly in oncology applications, fueled by its expanding population and major medical centers. State-level initiatives often support access to advanced diagnostic services in both urban and rural areas. The Houston medical center complex is a critical site for clinical trials and specialized cancer diagnostics.
US Tissue Diagnostics Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the US tissue diagnostics market structure. This market shows a tiered consolidation, with major corporations offering comprehensive solutions across the diagnostic workflow, from sample preparation to digital analysis. Strategic archetypes include diversified diagnostics giants, specialized reagent providers, and emerging AI-driven analytics firms. Dominant competitive moves involve continuous portfolio diversification and strategic partnerships to integrate novel technologies and expand digital offerings.
Within the diversified diagnostics giants tier, Roche Diagnostics and Danaher Corporation exemplify companies with extensive portfolios spanning instruments, reagents, and digital pathology solutions. Thermo Fisher Scientific, a US-based company, occupies a position as a leading provider of specialized reagents and molecular probes, anchoring the consumables segment. Abbott Laboratories, another prominent US player, also sits within this group, offering a broad range of diagnostic platforms. These companies leverage their broad market presence and R&D capabilities to address the evolving needs of diagnostic laboratories and research institutes across the United States.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Abbott Laboratories |
| Siemens Healthineers |
| Agilent Technologies |
| Merck KGaA |
| QIAGEN |
| Becton, Dickinson & Company |
| Others |
Cost & Logistics Intelligence
The extended lead times for specialized digital pathology scanners, often exceeding six months, directly influence the capital investment cycle for laboratories and impact pricing power for advanced instrumentation. This dynamic creates a tiered market where manufacturers with robust supply chains can command premium pricing for immediate availability and integrated service packages.
Pricing Analysis
Long-term contract-based agreements dominate the procurement of high-value digital pathology systems and automated staining platforms in the US. Price differentiation stems from the level of FDA clearance for diagnostic algorithms and the breadth of integrated after-sales service and support. Pricing softness is evident in routine histopathology stains due to increased competition and commoditization of basic reagents. Diagnostic laboratories, especially smaller community hospitals, exhibit higher price sensitivity compared to large academic research institutes.
Supply Chain Analysis
Single-source dependencies for high-precision optical components and specialized microfluidic systems represent a chokepoint in the tissue diagnostics supply chain. Geographic supply concentration for these critical inputs largely resides in Germany and the United States. Key raw materials include highly purified antibodies, specific chemical dyes, and advanced semiconductor components. Regulatory restrictions, particularly those governing import/export of biological materials, pose a structural risk. Distribution runs through direct sales channels for complex instruments and a mix of distributors and hospital supply chains for reagents and consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US tissue diagnostics market requires a substitution defense strategy, as incumbents must navigate the increasing threat from non-invasive diagnostic alternatives like liquid biopsies.
For Market Incumbents: Shield core histopathology revenue by accelerating integration of AI-powered image analysis into existing digital pathology platforms. Consolidate market positions through strategic acquisitions of specialized AI software developers to enhance diagnostic accuracy and workflow efficiency. The advancing capabilities of molecular diagnostics present a named threat. Invest in R&D to develop multi-modal diagnostic solutions that combine tissue analysis with other data types, leveraging advanced data analytics as a key lever.
For New Entrants and Emerging Players: Specialized AI algorithm development for rare disease diagnostics represents a service-layer gap where incumbents under-serve. Target underserved rural hospitals with telepathology solutions, offering a cost-effective alternative to on-site pathologist staffing. The most penetrable application segment involves assisting in quantitative biomarker analysis for complex oncology cases. A compelling go-to-market angle involves partnering with integrated delivery networks to demonstrate clear cost savings and improved diagnostic turnaround times.
For Investors and Strategic Acquirers: Long-term, this sits as a technology-driven growth play because AI integration and digital transformation are fundamentally reshaping diagnostic workflows. Acquisition targets should prioritize firms specializing in advanced multiplex assay development or those with proprietary, FDA-cleared AI algorithms for pathology. A critical signal to watch is the pace and scope of FDA clearances for novel AI-assisted diagnostic tools, indicating regulatory acceptance and market readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Development | This enhances diagnostic precision and turnaround times for complex cancer cases, improving patient outcomes. |
| Telepathology Platform Expansion | It addresses pathologist shortages in remote areas, improving access to expert diagnostic services across the US. |
| Multiplex Assay Commercialization | This maximizes data extraction from limited tissue samples, supporting personalized medicine in oncology. |
| Digital Pathology System Integration | It streamlines laboratory workflows and enables seamless data sharing within hospital IT infrastructures. |
| Regulatory Pathway Investment | This accelerates market entry for novel diagnostic tools by securing necessary FDA clearances for commercialization. |
Research Approach
Initial hypotheses were tested against primary input from pathologists, laboratory directors, biotech R&D leads, and hospital administrators, and refined through iterative analysis. This involved in-depth interviews combined with rigorous secondary validation. Secondary sources included FDA databases, CLIA guidelines, academic research papers, and company financial reports. A combination of bottom-up and top-down triangulation ensured comprehensive market sizing and forecast accuracy.
Variance decomposition informed the analytical framework used to project market performance across the analysis window. The model segmented the market by product type, application, end user, distribution channel, and digital adoption rates. Compound annual growth rates were derived from historical data trends and projected future demand. Key forecast inputs included cancer incidence rates and FDA clearance trends for AI-powered diagnostic solutions.
Underlying assumptions cover regulatory stability and the pace of technological advancement, with deviation risk concentrated in reimbursement policy shifts. Practitioners should keep alternative scenarios live as reimbursement policies and technological breakthroughs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Swine Disease Diagnostic Kit Market
Diagnostics
Middle East and Africa Liver Cancer Diagnostics Market
Diagnostics
Allergy Diagnostics Market
Diagnostics
North America Ovarian Cancer Diagnostics Market
Diagnostics
Global Alzheimers Disease Diagnostic Market
Diagnostics
Urinary Protein Reagents Market
Diagnostics
Global Hemoglobin A1c Testing Devices Market
Diagnostics
Preterm Birth Diagnostic Test Kits Market
Diagnostics
Global Renal Biomarkers Market
Diagnostics
BRIC in-Vitro Diagnostics (IVD) Market
Diagnostics
HIV Diagnostics Market
Diagnostics
Global Comprehensive Metabolic Panel Market
Diagnostics
Pancreatic Cyst Diagnostics Market
Diagnostics
Melanoma Cancer Diagnostics Market
Diagnostics
Shrimps Disease Diagnostics Market
Diagnostics
Cancer IVD Market