
 Malaria Diagnostics Market | 2026-2036
Malaria Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Malaria Diagnostics Market Intelligence
Loop-mediated isothermal amplification is narrowing the performance gap between point-of-care rapid tests and centralized laboratory diagnostics in malaria-endemic regions. Abbott Laboratories leverages its established distribution networks across African health systems to sustain high-volume test kit deployment. bioMérieux anchors its competitive position through specialized molecular diagnostics expertise and targeted R&D investment in tropical disease platforms.
Malaria diagnostics encompass laboratory and field-based methods for detecting Plasmodium parasites in human blood, including microscopic examination of Giemsa-stained thick and thin blood smears, immunochromatographic lateral flow devices, and nucleic acid amplification techniques with sensitivity thresholds reaching 1–5 parasites per microliter. The primary purpose is enabling timely therapeutic intervention and epidemiological surveillance in resource-limited settings. Rapid diagnostic tests occupy the largest volume share due to their minimal infrastructure requirements and suitability for community health worker deployment. Molecular diagnostics, particularly polymerase chain reaction and LAMP assays, represent the fastest-expanding segment as programs prioritize species differentiation and drug resistance marker detection.
WHO prequalification requirements and national regulatory authorities in endemic countries shape product registration timelines and performance benchmarks for malaria test manufacturers. FDA oversight applies to US-exporting manufacturers, while CE marking under EU IVDR governs European market access and influences standards adopted by procurement bodies elsewhere. Stakeholders must monitor evolving WHO policy guidance on diagnostic algorithm updates and prequalification delisting mechanisms.
Market Dynamics
WHO prequalification standards are compressing product registration timelines while simultaneously elevating performance thresholds, forcing manufacturers to recalibrate R&D pipelines and manufacturing quality systems ahead of competitive displacement.
Growth Catalysts
- Sub-Saharan African procurement centralization:National malaria control programs in Nigeria and the Democratic Republic of Congo are consolidating purchasing through global health financing mechanisms, creating volume aggregation that rewards scale-efficient suppliers.
- Loop-mediated isothermal amplification (LAMP):This nucleic acid amplification technology is enabling near-molecular sensitivity at point-of-care temperatures without thermal cycling infrastructure, expanding diagnostic reach into peripheral health posts.
- India's PLI scheme for medical devices:Production-linked incentives are attracting component manufacturing and finished test kit assembly capacity to reduce import dependency for rapid diagnostic test materials.
Market Restraints
- Plasmodium falciparum histidine-rich protein 2 (HRP2) gene deletions:Parasite genetic variation in the Horn of Africa and South America is producing false-negative rapid diagnostic test results, undermining confidence in lateral flow platforms and triggering algorithm revisions.
- Specialized cold chain requirements for molecular reagents:Polymerase chain reaction consumables demand sustained 2–8°C distribution integrity through last-mile health networks where refrigeration gaps persist.
- WHO prequalification delisting mechanisms:Accelerated post-market surveillance protocols are removing underperforming test lots from procurement eligibility faster than replacement products gain approval, creating supply discontinuities.
Strategic Opportunities
- Drug resistance surveillance integration:Molecular platforms capable of detecting kelch13 mutations for artemisinin resistance are creating new demand from elimination programs in the Greater Mekong Subregion.
- Community health worker deployment models:Task-shifting policies in Kenya and Tanzania are authorizing non-laboratory personnel to perform and interpret rapid diagnostic tests, expanding addressable testing volume beyond facility walls.
- Digital connectivity integration:Diagnostic devices with embedded near-field communication or cellular data transmission are enabling real-time surveillance reporting to national health management information systems.
Industry Challenges
- Microscopist training pipeline collapse:Giemsa stain expertise is aging out of national reference laboratories faster than competency-based training programs replenish qualified personnel, creating quality assurance vulnerabilities for microscopy-dependent confirmation protocols.
- Multiplex panel development complexity:Combining Plasmodium species identification with concurrent detection of dengue, chikungunya, and leishmaniasis antigens is extending validation timelines and complicating regulatory submission dossiers across multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaria Diagnostics Market |
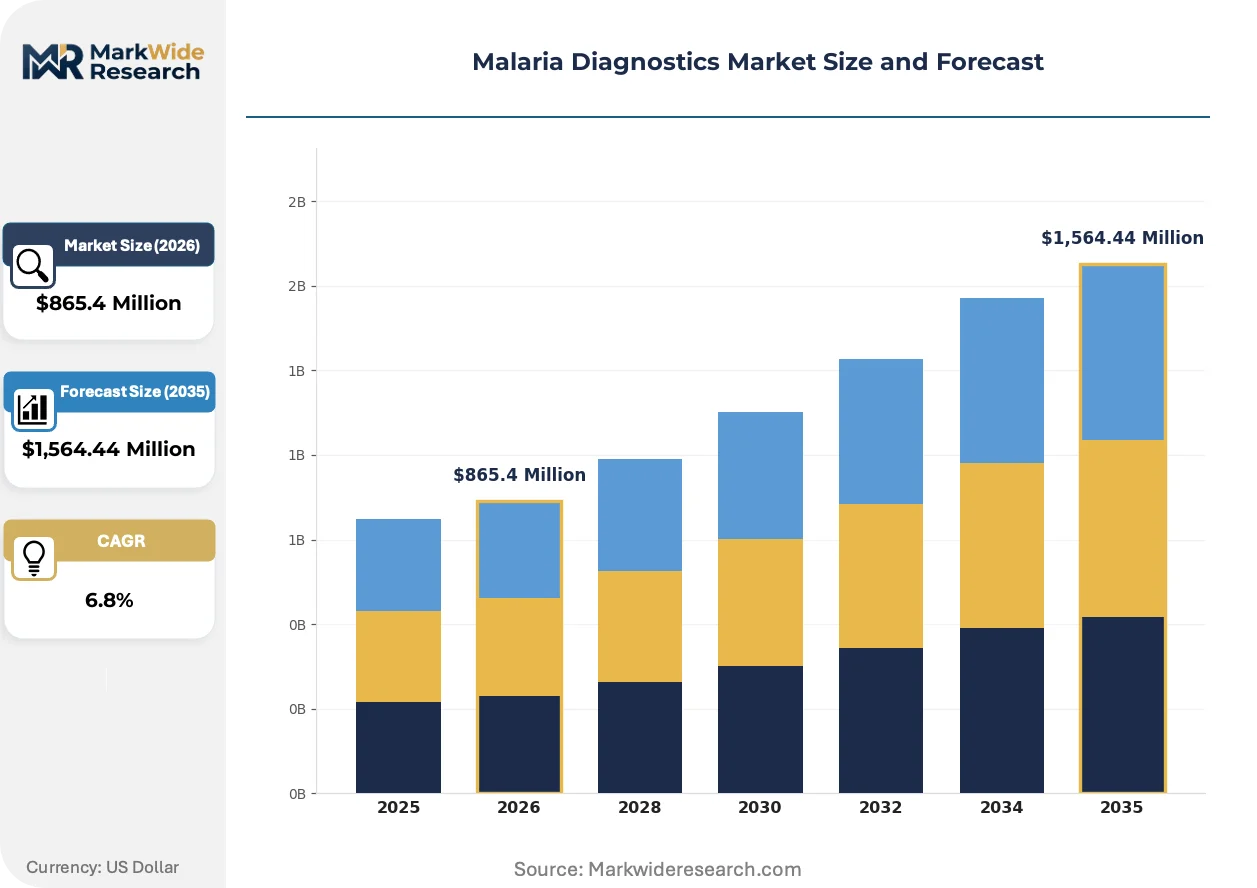
| Market Size in 2026 | $865.4 Million |
| Market Size in 2035 | $1,564.44 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Diagnostic Tests, Blood Smear Microscopy, Polymerase Chain Reaction, LAMP Assays End User: Hospitals, Diagnostic Laboratories, Home Care Settings, Public Health Organizations Technology: Immunoassays, Molecular Diagnostics, Microscopy, Microfluidics Application: Clinical Diagnosis, Epidemiological Studies, Prevention Programs, Research |
| Companies Covered | Abbott Laboratories, bioMérieux, Access Bio, Inc., Siemens Healthineers, Beckman Coulter, Inc., Bio-Rad Laboratories, Inc., Premier Medical Corporation, Sysmex Partec GmbH, Roche Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaria Diagnostics Market Strategic Shifts & Innovations
Diagnostic platform architectures are fragmenting into specialized tiers optimized for distinct use cases rather than converging on universal solutions, with each tier demanding differentiated manufacturing scale and service models.
Ultrasensitive rapid diagnostic tests targeting Plasmodium falciparum lactate dehydrogenase (Pf-LDH) and aldolase antigens are achieving detection thresholds approaching 200 parasites per microliter. Elimination programs in Cambodia and Vietnam are piloting these platforms for mass screen-and-treat campaigns where conventional HRP2-based tests miss low-density infections. The technology is migrating from centralized reference laboratories into village-level deployment through simplified buffer systems and ambient temperature stability.
FDA enforcement discretion policies for malaria in vitro diagnostics are creating parallel regulatory pathways distinct from WHO prequalification routes. US-based manufacturers serving research and traveler health markets face bifurcated compliance obligations that extend product development timelines. The research-use-only segment is absorbing additional validation burden as clinical trial sponsors demand diagnostic endpoint standardization.
Volume-based procurement contracts with multilateral health financiers are consolidating supplier relationships around prequalified manufacturers with demonstrated manufacturing scale. National central medical stores in endemic countries are reducing supplier counts to simplify quality audits and lot release testing. This concentration is visible most acutely in Nigeria's Federal Ministry of Health tendering, where three-year framework agreements now dominate annual spot purchasing.
Malaria Diagnostics Market Segmentation
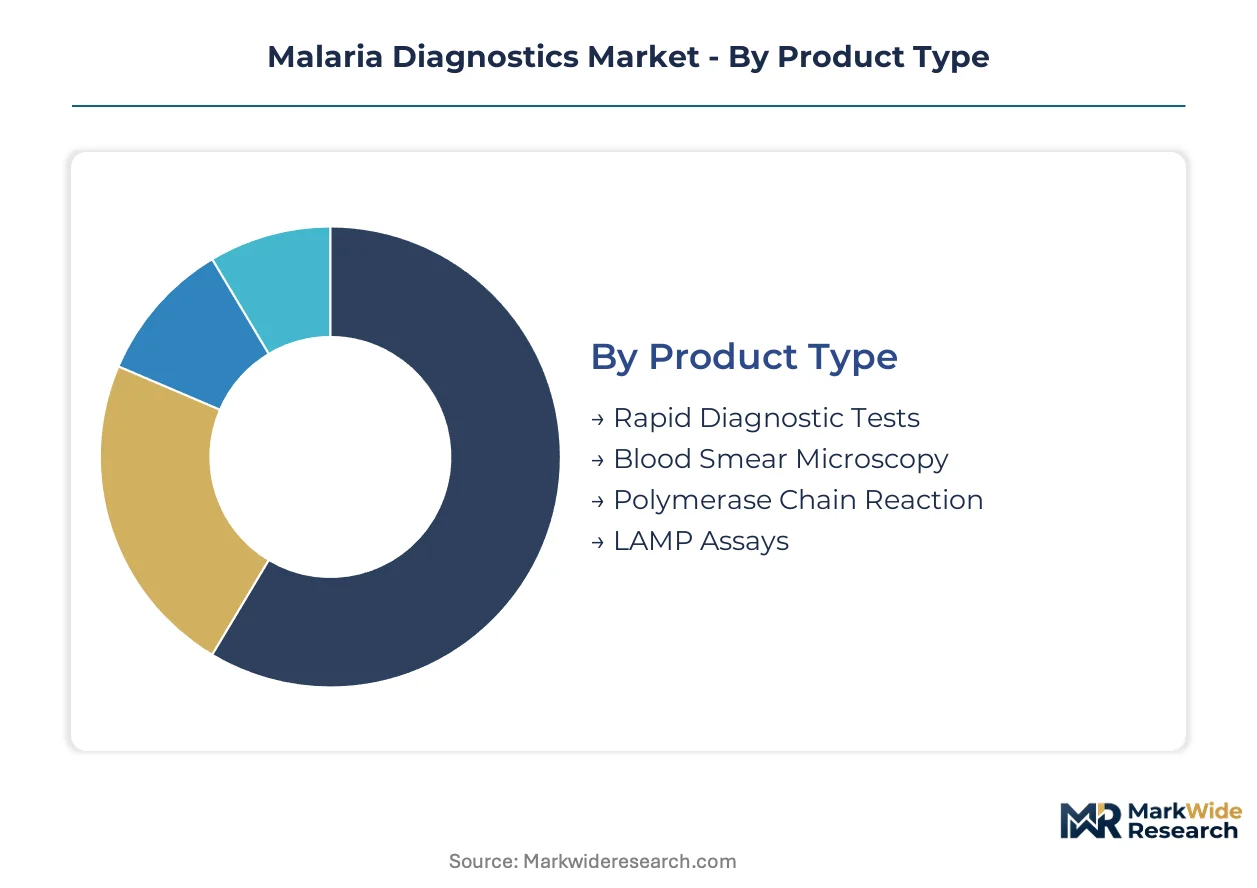
Malaria diagnostics fragment across four intersecting dimensions that determine procurement patterns, margin structures, and regulatory pathways. Product type and end-user configurations dominate volume allocation, while technology and application segments shape R&D investment intensity and reimbursement frameworks.
Product Type:
Rapid diagnostic tests turn inventory fastest through community health networks, while molecular platforms sit longer in procurement pipelines due to prequalification complexity and cold chain validation requirements.
- Rapid Diagnostic Tests:Lateral flow immunochromatographic devices detecting Plasmodium falciparum histidine-rich protein 2 or lactate dehydrogenase antigens with 15-20 minute turnaround. Nigeria's Federal Ministry of Health and the Democratic Republic of Congo's national malaria control program drive bulk procurement through Global Fund and PMI financing mechanisms, though HRP2 gene deletions in the Horn of Africa are forcing algorithm revisions toward Pf-LDH targets.
- Polymerase Chain Reaction:Nucleic acid amplification achieving 1-5 parasites per microliter sensitivity with species differentiation and drug resistance marker detection. Demand concentrates in elimination programs across Cambodia, Vietnam, and the Greater Mekong Subregion where kelch13 mutation surveillance guides therapeutic policy.
- Blood Smear Microscopy:Giemsa-stained thick and thin film examination requiring trained microscopists and quality-assured laboratory infrastructure. Reference laboratories in India and academic medical centers maintain demand despite workforce attrition.
- LAMP Assays:Isothermal amplification operating at constant temperature without thermal cyclers, enabling near-molecular sensitivity at peripheral health posts. Kenya and Tanzania pilot village-level deployment through task-shifting authorization.
Rapid diagnostic tests anchor the volume base while LAMP assays gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive hospital laboratories from minimal-infrastructure community settings, with procurement mechanisms diverging accordingly.
- Public Health Organizations:National malaria control programs and global health financiers aggregating demand through centralized tenders with WHO prequalification requirements. Volume concentrates in sub-Saharan African ministries of health pursuing universal diagnostic coverage.
- Hospitals:Secondary and tertiary facilities requiring species identification, parasitemia quantification, and severe malaria triage capabilities. India's district hospital networks and Nigerian teaching hospitals sustain demand for microscopy confirmation and molecular backup.
- Diagnostic Laboratories:Private and public reference facilities processing samples from multiple collection points. Quality assurance programs and external competency assessment drive reagent standardization.
- Home Care Settings:Self-testing applications limited by regulatory restrictions, with current deployment confined to research protocols and traveler health markets in Europe and North America.
Public health organizations dominate procurement volume while diagnostic laboratories deliver the highest margin per test.
Technology:
Supply concentration clusters around immunoassay manufacturers with established African distribution, while molecular specialists compete on assay menu breadth.
- Immunoassays:Antibody-antigen binding platforms spanning lateral flow, ELISA, and chemiluminescence formats. Abbott Laboratories and Standard Diagnostics maintain manufacturing scale for high-volume RDT production.
- Molecular Diagnostics:PCR, LAMP, and emerging CRISPR-based detection systems. bioMérieux and Cepheid compete on platform portability and reagent stability under ambient temperature conditions.
- Microscopy:Light microscopy with Giemsa staining remains the diagnostic reference standard despite workforce constraints. Automated cell imaging systems attempt to bridge the competency gap.
- Microfluidics:Lab-on-chip platforms integrating sample preparation, amplification, and detection for point-of-care molecular testing. Early-stage deployment in research and elimination program settings.
Immunoassays capture the installed base while molecular diagnostics expands most quickly through resistance surveillance funding.
Application:
Customer maturity separates established clinical workflows from emerging digital-integrated surveillance architectures.
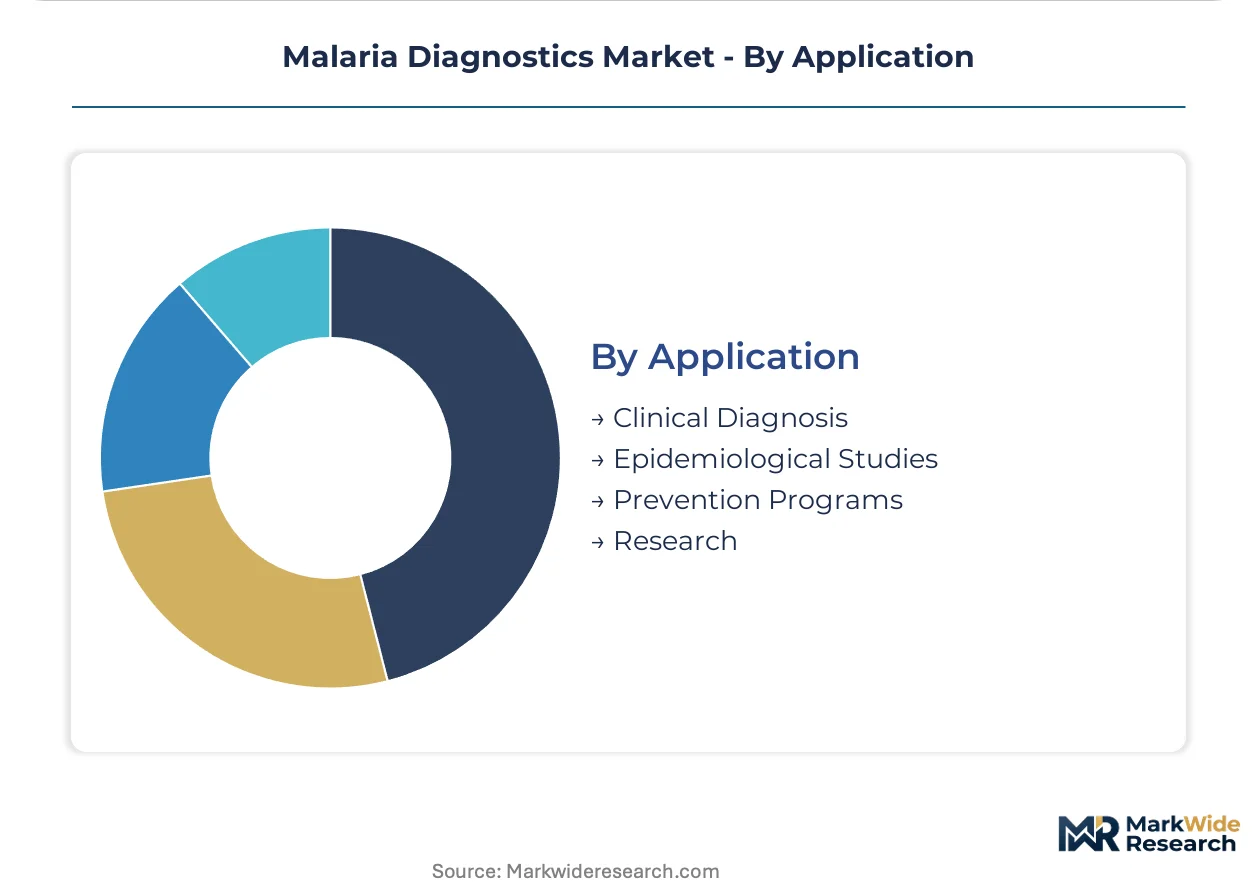
- Clinical Diagnosis:Symptomatic patient testing for treatment initiation across outpatient and inpatient settings. WHO test-treat guidelines mandate diagnostic confirmation before antimalarial administration.
- Prevention Programs:Mass screen-and-treat campaigns, intermittent preventive treatment in pregnancy, and seasonal malaria chemoprevention with diagnostic monitoring. Cambodia and Vietnam pilot ultrasensitive RDTs for asymptomatic reservoir detection.
- Epidemiological Studies:Cross-sectional prevalence surveys and therapeutic efficacy studies generating public health intelligence. Standardized endpoints require diagnostic harmonization across multicenter protocols.
- Research:Vaccine trials, drug development, and transmission biology investigations demanding ultrasensitive quantification and species-specific characterization. Academic institutions and product development partnerships drive specialized reagent demand.
Clinical diagnosis absorbs the majority of test volume while prevention programs show the steepest expansion trajectory as elimination funding intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public health organizations in sub-Saharan Africa and South Asia concentrate procurement authority, while elimination programs in Southeast Asia drive molecular diagnostics demand. National malaria control programs in high-burden countries aggregate volume through global health financing mechanisms.
Nigeria
The Federal Ministry of Health consolidates rapid diagnostic test procurement through three-year framework agreements with Global Fund and PMI financing. WHO prequalification standards govern product eligibility for national tenders. Lagos and Abuja anchor distribution networks for last-mile deployment to peripheral health posts.
Democratic Republic of Congo
The national malaria control program coordinates centralized purchasing for community health worker networks across 26 provinces. Cold chain gaps in eastern provinces constrain molecular reagent distribution to Kinshasa and Lubumbashi reference laboratories. Kinshasa's central medical store manages quality assurance and lot release testing.
India
The Production-Linked Incentive scheme for medical devices attracts component manufacturing and finished test kit assembly to reduce import dependency. CDSCO regulates diagnostic kit registration under the Medical Devices Rules. Gujarat and Karnataka host emerging manufacturing clusters for lateral flow device components.
Cambodia
Elimination programs in the Greater Mekong Subregion deploy ultrasensitive rapid diagnostic tests for mass screen-and-treat campaigns targeting asymptomatic reservoirs. The national malaria program coordinates kelch13 mutation surveillance for artemisinin resistance. Phnom Penh reference laboratories anchor molecular confirmation capacity.
Kenya
Task-shifting policies authorize community health workers to perform and interpret rapid diagnostic tests beyond facility walls. The Ministry of Health pilots loop-mediated isothermal amplification deployment in village-level settings. Nairobi and Mombasa concentrate quality assurance oversight for decentralized testing networks.
Malaria Diagnostics Market Key Industry Players
Channel-controlling players compete with product-specialist players across procurement tiers. The vendor base clusters around three strategic archetypes: diversified multinationals with African distribution networks, molecular diagnostics specialists with tropical disease platforms, and regional manufacturers serving price-sensitive tenders. Competitive moves center on WHO prequalification maintenance and manufacturing scale expansion to qualify for volume-based framework agreements.
Among diversified multinationals, Abbott Laboratories and Siemens Healthineers occupy positions shaped by established health system relationships. bioMérieux represents the molecular specialist archetype with targeted tropical disease expertise. These three exemplify distinct competitive vectors: channel control through distribution scale, platform specialization through assay menu breadth, and regulatory positioning through prequalification portfolio depth.
| Leading Market Players |
|---|
| Abbott Laboratories |
| bioMérieux |
| Access Bio, Inc. |
| Siemens Healthineers |
| Beckman Coulter, Inc. |
| Bio-Rad Laboratories, Inc. |
| Premier Medical Corporation |
| Sysmex Partec GmbH |
| Roche Diagnostics |
| Others |
Cost & Logistics Intelligence
HRP2 gene deletion risk in the Horn of Africa and South America determines both the accelerated shift toward Pf-LDH antigen targets and the geographic restructuring of rapid diagnostic test sourcing. WHO prequalification delisting mechanisms compress supplier eligibility timelines while procurement centralization through Nigeria's Federal Ministry of Health and the Democratic Republic of Congo's national malaria control program amplifies volume-based pricing power for qualified manufacturers.
Pricing Analysis
Cost-plus contracts with Global Fund and PMI financing index raw material costs to nitrocellulose membrane and colloidal gold conjugate prices. Three-tier pricing structure across WHO-prequalified premium, nationally registered standard, and non-prequalified economy levels separates procurement eligibility tiers. Cost compression in economy-grade lateral flow devices intensifies as India's PLI scheme attracts component manufacturing capacity. Public health organizations in sub-Saharan Africa exhibit the highest price sensitivity, while elimination programs in Cambodia and Vietnam prioritize assay sensitivity over unit cost.
Supply Chain Analysis
Tariff exposure between China and India dominates nitrocellulose membrane sourcing decisions for lateral flow device manufacturers. Finished test kit assembly concentrates in India, China, and South Korea, drawing from specialized reagent production in the United States and Germany. Single-source vulnerability persists for thermostable polymerase enzymes used in LAMP assays. Distribution runs through national central medical stores in Nigeria and the Democratic Republic of Congo with last-mile deployment to peripheral health posts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The malaria diagnostics market functions as a regulatory-moat arena where WHO prequalification portfolio depth creates switching costs that entrench incumbent positions against emerging competitors.
For Market Incumbents: Insulate manufacturing scale advantages by deepening backward integration into nitrocellulose membrane production and expanding cold chain-validated reagent stability for molecular platforms. The HRP2 gene deletion threat demands accelerated Pf-LDH assay validation to preempt algorithm displacement. Certification investment in LAMP assay prequalification secures position in Kenya and Tanzania village-level deployment pilots. For New Entrants and Emerging Players: Eastern Democratic Republic of Congo provinces with persistent cold chain gaps present the most penetrable geography for ambient-temperature-stable molecular platforms. India's emerging manufacturing clusters under the PLI scheme offer white-space entry for component suppliers to lateral flow device assemblers. A go-to-market angle anchored in digital connectivity integration for real-time surveillance reporting differentiates against established RDT-only suppliers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors molecular diagnostics specialists with tropical disease assay menus. Long-term viability hinges on resistance surveillance funding durability across the Greater Mekong Subregion. Acquisition targets with demonstrated kelch13 mutation detection capabilities and WHO prequalification progress offer defensive positioning. The signal to watch is accelerated post-market surveillance protocol implementation triggering supply discontinuities.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Prequalification portfolio depth unlocks Global Fund and PMI procurement eligibility in Nigeria and DRC. |
| LAMP Assay Development | Thermostable reagent formulations enable task-shifting deployment in Kenya's village-level health posts. |
| Backward Integration into Membranes | In-house nitrocellulose production reduces import dependency and buffers raw material cost volatility. |
| Digital Connectivity Integration | Embedded NFC and cellular transmission capabilities align with national health management information system requirements. |
| Drug Resistance Surveillance Partnership | kelch13 mutation detection contracts with Cambodia's national malaria program secure elimination program revenue streams. |
Research Approach
Cross-validation between procurement database analysis and regulatory filing review anchors the qualitative findings in documented purchasing patterns. Primary interviews with national malaria control program directors, WHO prequalification assessors, biomedical engineers at reference laboratories, and GPO contracts managers combined with secondary validation against FDA enforcement discretion policies, CDSCO Medical Devices Rules filings, Global Fund tender documents, and PMI procurement reports. Bottom-up test volume modeling and top-down health financing flow analysis triangulate market sizing across the analysis window.
Calibration against historical procurement volumes from Nigeria's Federal Ministry of Health and the Democratic Republic of Congo's central medical store informs the projection framework. Segmentation dimensions span product type, end user, technology platform, and application with regional regulatory cluster differentiation. CAGRs derive from multivariate regression across epidemiological burden indices, health financing commitment trajectories, and diagnostic algorithm update schedules. Assay sensitivity thresholds and cold chain infrastructure penetration serve as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated membrane-to-device manufacturers would shift outcomes. Macroeconomic volatility in health financing commitments, regulatory acceleration of prequalification delisting, or technological breakthrough in CRISPR-based detection would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Cellular Health Screening Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Global Chromoendoscopy Agents Market
Diagnostics
GCC in-Vitro Diagnostic Devices Market
Diagnostics
Prostate Cancer Diagnostics Market
Diagnostics
Infectious Disease in Vitro Diagnostics Market
Diagnostics
Global Blood Transfusion Diagnostics Market
Diagnostics
Global Phytopathological Disease Diagnostics Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
Hospital Clinical Chemistry and Immunodiagnostics Market
Diagnostics
Europe Ovarian Cancer Diagnostics Market
Diagnostics
Global Companion Diagnostic Technologies Market
Diagnostics
Sperm Density Testing Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
Global Liver Cancer Diagnostics Market
Diagnostics
Digital Companion Diagnostics Market