
 Veterinary Ultrasound Scanners Market | 2026-2036
Veterinary Ultrasound Scanners Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Ultrasound Scanners Market Analysis
The capital-intensity divergence between full-platform manufacturers and focused point-of-care specialists is rotating competitive dynamics across the sector. GE Healthcare leverages its human-healthcare imaging heritage to sustain premium positioning in cart-based systems for university hospitals. Shenzhen Mindray Animal Medical Technology anchors volume production of portable units for price-sensitive clinics across Asia. Esaote SpA differentiates through dedicated veterinary software workflows and transducer ergonomics purpose-built for equine and companion-animal anatomy.
Veterinary ultrasound scanners employ piezoelectric crystal arrays generating acoustic frequencies between two and fifteen megahertz, with beamforming processors constructing real-time tomographic images for non-invasive assessment of soft tissue, cardiac function, and reproductive status in animal patients. Portable systems now capture the fastest expansion trajectory as ambulatory large-animal practitioners and emergency clinics prioritize field-deployable diagnostics with battery-operated Doppler capability. Cart-based platforms retain the deepest margin pools in tertiary referral centers where 3D imaging integration supports complex surgical planning. Wireless connectivity segments are gaining traction as telemedicine protocols enable remote specialist interpretation of scans captured in rural or mobile settings.
The FDA Center for Veterinary Medicine oversees device safety labeling for diagnostic equipment used in food-producing animals, while ISO 10993 biocompatibility standards govern transducer materials contacting patient tissue. The EU Medical Device Regulation through notified bodies extends conformity requirements to imported veterinary scanners sold in European clinics. Stakeholders must monitor how evolving AI-enabled diagnostic software interfaces trigger novel regulatory classification debates across jurisdictions with divergent software-as-medical-device frameworks.
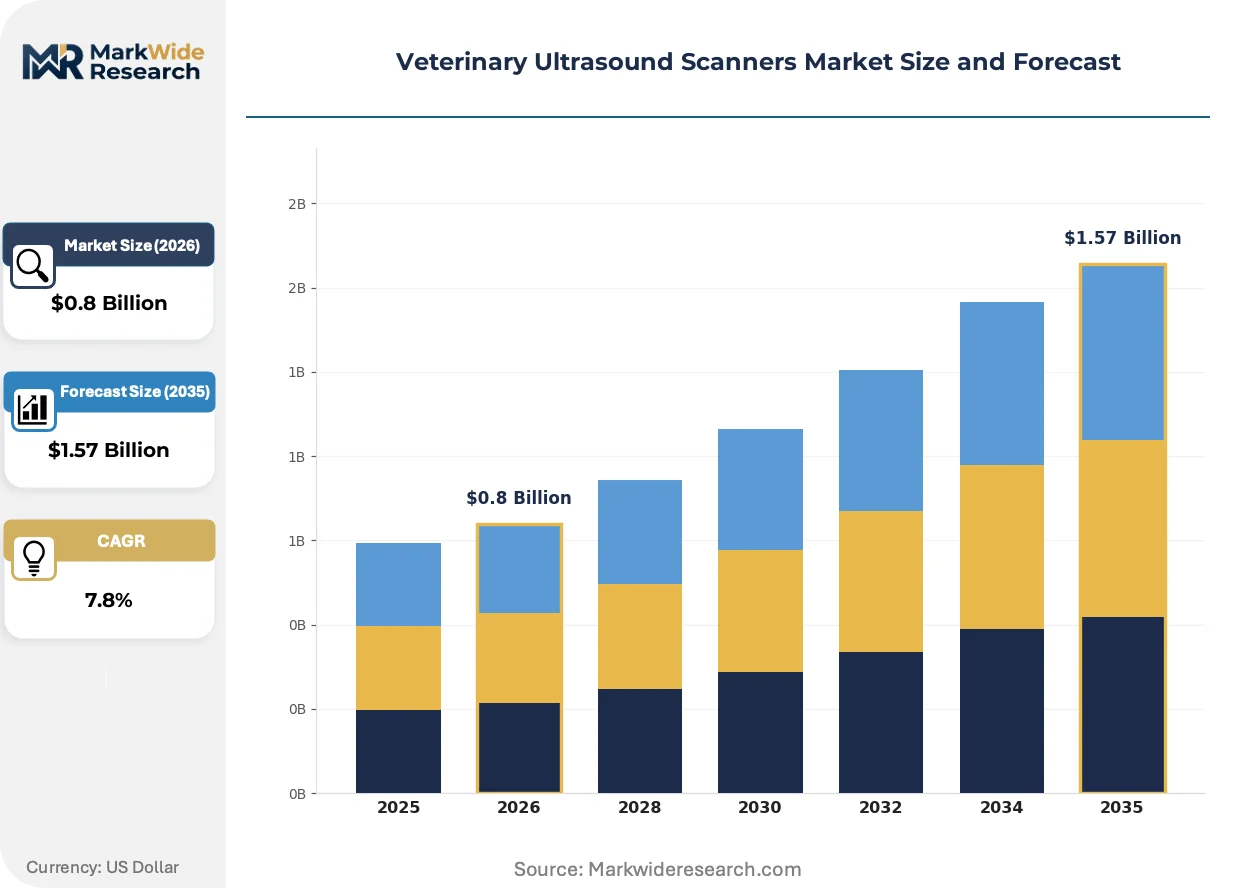
Market Dynamics
The migration from cart-based to portable ultrasound systems is compressing capital cycles and fragmenting procurement authority across veterinary practices of all sizes.
Growth Catalysts
- Pet Insurance Penetration:Reimbursement coverage for diagnostic imaging in the United States lowers effective cost barriers for companion-animal owners, expanding addressable demand for elective procedures.
- ISO 10993 Compliance:Harmonized biocompatibility standards for transducer materials accelerate cross-border equipment approvals, reducing time-to-market for manufacturers targeting multiple jurisdictions.
- Telemedicine Protocols:Wireless image transmission enables remote specialist interpretation, extending diagnostic reach into rural ambulatory large-animal practices lacking on-site radiologists.
Market Restraints
- Piezoelectric Crystal Supply:Concentrated sourcing of high-purity ceramic substrates from East Asian suppliers exposes manufacturers to input volatility and geopolitical friction.
- FDA Center for Veterinary Medicine Labeling:Device safety requirements for food-producing animals impose extended validation timelines that deter development of dual-use systems.
- Computed Radiography Substitution:Digital X-ray systems with lower per-scan operating costs compete for orthopedic and thoracic imaging cases in price-sensitive clinics.
Strategic Opportunities
- AI-Enabled Diagnostic Software:Machine learning algorithms for automated cardiac measurement and gestational aging create premium pricing tiers and recurring revenue streams.
- Equine Sports Medicine:Tendon and ligament assessment protocols in competitive racing stables drive demand for high-frequency linear transducers with specialized presets.
- EU Medical Device Regulation:Conformity assessment requirements for imported veterinary scanners favor notified-body-certified manufacturers with established European service networks.
Industry Challenges
- Sonographer Training Bottlenecks:Shortage of credentialed veterinary imaging specialists limits utilization rates of advanced Doppler features in general practice settings.
- Legacy PACS Integration:Incompatibility between proprietary image formats and existing hospital information systems complicates enterprise-wide deployment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Ultrasound Scanners Market |
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.57 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Cart-based, Handheld, Wireless Technology: Digital, Analog, 3D Imaging, Doppler End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Mobile Units Application: Cardiology, Obstetrics, Abdominal Imaging, Musculoskeletal |
| Companies Covered | GE Healthcare, Esaote SpA, IDEXX Laboratories, Shenzhen Mindray Animal Medical Technology, FUJIFILM Corporation, Siemens Healthineers, Carestream Health, Heska Corporation, Samsung Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Ultrasound Scanners Market Emerging Trajectories
Wireless connectivity and artificial intelligence are redefining how ultrasound data moves through veterinary care networks, from point-of-capture to specialist interpretation.
Semiconductor-based capacitive micromachined ultrasonic transducers (CMUTs) are supplanting conventional piezoelectric arrays in next-generation portable systems. CMUTs enable broader bandwidth and improved thermal efficiency in battery-operated devices. Emergency and ambulatory practitioners are accelerating adoption, compressing the performance gap between handheld units and premium cart-based platforms.
The EU Medical Device Regulation's software-as-medical-device classification framework is forcing manufacturers to reassess AI diagnostic modules sold as standalone upgrades. Veterinary-specific algorithms for automated ejection fraction calculation now trigger conformity assessment requirements previously limited to human healthcare. European notified bodies are extending review timelines for systems with machine-learning components, advantaging vendors with pre-established quality management systems.
Subscription-based equipment access models are displacing outright purchase arrangements in multi-site veterinary groups. Corporate consolidators favor per-procedure leasing with bundled maintenance and software updates over capital-intensive ownership. This shift is most visible in the United States, where private equity-backed practice networks prioritize balance-sheet flexibility and technology refresh guarantees.
Veterinary Ultrasound Scanners Market Segmentation
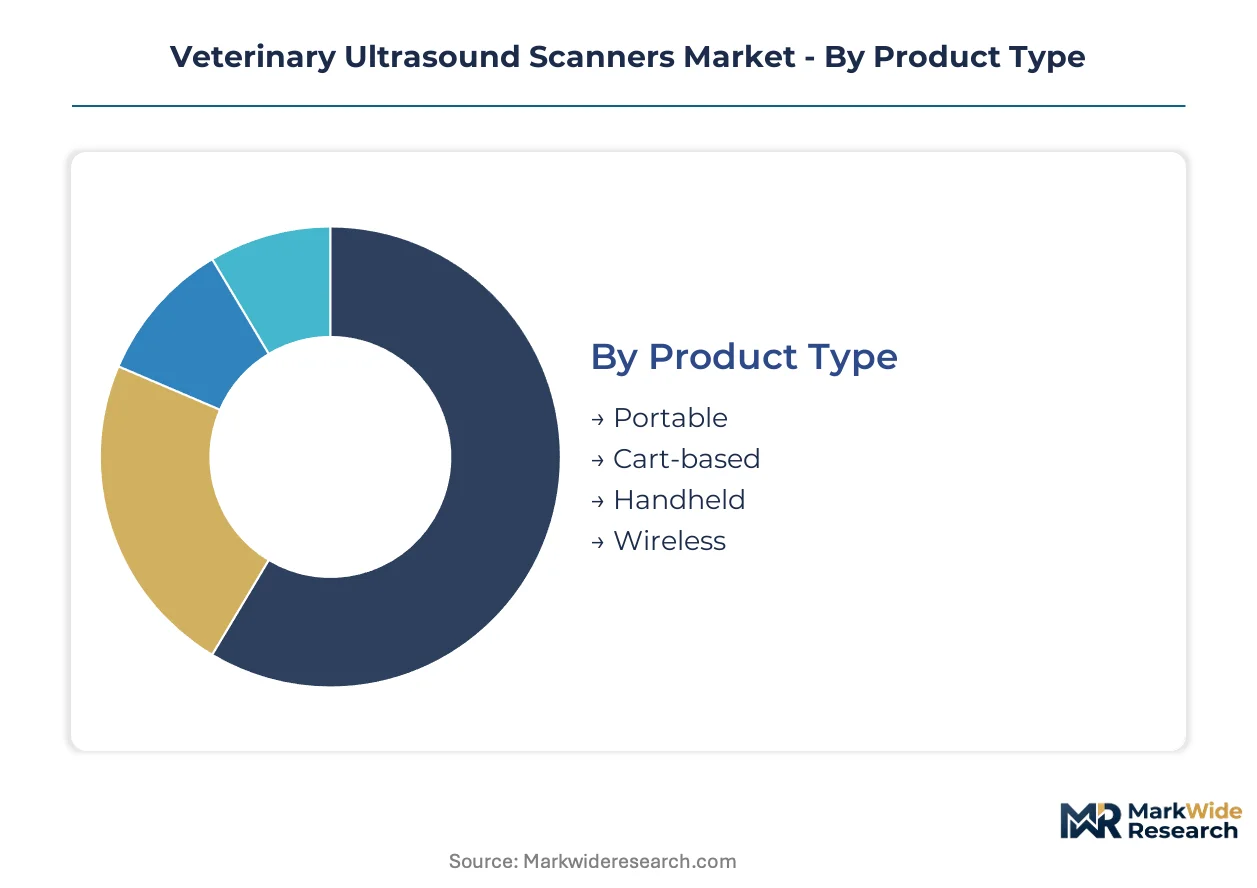
Veterinary ultrasound scanner segmentation reveals how regulatory pathways, clinical workflows, and capital constraints fragment procurement decisions across practice types. Equipment choices now diverge sharply between tertiary referral centers pursuing advanced imaging certifications and ambulatory practitioners prioritizing field mobility.
Product Type:
FDA Center for Veterinary Medicine labeling requirements for food-producing animals compress development timelines for dual-use portable systems while exempting companion-animal-only handheld units from extended validation.
- Portable:Battery-operated systems with integrated Doppler processors serve ambulatory large-animal practitioners across rural United States. Equine sports medicine stables in Kentucky and Florida drive replacement cycles as tendon imaging protocols demand higher-frequency linear transducers.
- Cart-based:Premium platforms anchor university veterinary hospitals where 3D reconstruction and elastography modules support complex surgical planning. Tertiary referral networks in metropolitan clusters sustain the deepest margin pools through extended service contracts.
- Handheld:Smartphone-tethered probes reduce capital barriers for entry-level companion-animal clinics. Compact form factors bypass ISO 10993 biocompatibility complexities that burden full-platform manufacturers.
- Wireless:Untethered image transmission enables telemedicine protocols linking rural capture sites to urban specialist interpreters. Battery thermal management constraints limit sustained frame rates in extended cardiac studies.
Established volume favors cart-based systems; emerging adoption favors portable configurations.
Technology:
Cost tier differentiation separates premium digital platforms from legacy analog installations in price-sensitive markets.
- Digital:Beamforming processors with programmable gain amplifiers deliver dynamic range exceeding 160 decibels for soft-tissue contrast resolution. University teaching hospitals in the United States specify digital backends for research reproducibility.
- Analog:Discrete component architectures persist in refurbished equipment markets and developing-region clinics with limited service infrastructure. Maintenance simplicity offsets performance limitations for general pregnancy detection workflows.
- 3D Imaging:Volume-rendered reconstructions support pre-surgical planning in orthopedic and oncologic cases. Reconstruction latency demands dedicated graphics processing unavailable in handheld form factors.
- Doppler:Pulsed-wave and continuous-wave modalities quantify blood flow across cardiac valve planes and umbilical vasculature. Credentialing requirements for spectral interpretation limit utilization in general practice settings.
Mature installed base concentrates in digital systems; steepest expansion trajectory appears in Doppler-equipped configurations.
End User:
Customer type determines procurement authority consolidation versus fragmentation across multi-site networks.
- Veterinary Clinics:Independent small-animal practices in suburban United States markets balance equipment utilization against lease obligations. Corporate consolidators impose standardization mandates that displace individual physician preferences.
- Animal Hospitals:24-hour emergency centers require redundant imaging capacity for trauma triage. Specialty referral density in metropolitan corridors sustains premium pricing for advanced modalities.
- Research Institutions:Academic veterinary medical centers prioritize imaging protocols compatible with longitudinal study designs. NIH and USDA funding streams dictate equipment specifications for grant compliance.
- Mobile Units:Ambulatory services serving feedlot operations and breeding facilities across the Great Plains prioritize ruggedized chassis and rapid boot sequences. Weather sealing specifications exceed clinic-grade requirements.
Procurement consolidation favors animal hospitals; entrepreneurial entry favors mobile unit configurations.
Application:
Clinical indication segmentation tracks how reimbursement coding and specialist credentialing concentrate demand in specific procedure categories.
- Cardiology:Echocardiographic measurement of fractional shortening and left atrial dimensions guides therapeutic monitoring in canine valvular disease. Board-certified veterinary cardiologists command premium interpretation fees that justify equipment investment.
- Obstetrics:Gestational aging and fetal viability assessment dominate small-animal reproductive practice. High-volume spay-neuter clinics deploy basic ultrasound for pre-surgical pregnancy detection.
- Abdominal Imaging:Hepatic, splenic, and urinary tract evaluation represents the most frequent indication in general practice. Pancreatic visualization limitations drive referral to advanced imaging modalities.
- Musculoskeletal:Tendon and ligament assessment protocols in competitive equine stables demand high-frequency linear transducers with specialized presets. Racing regulatory bodies mandate imaging documentation for injury disclosure.
Procedure volume concentrates in abdominal imaging; specialist premium pricing favors cardiology applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of veterinary ultrasound scanners concentrate in East Asian manufacturing hubs while import demand clusters in North American and European veterinary service markets. Trade balances favor production-heavy jurisdictions with established medical device ecosystems. Currency volatility and shipping cost fluctuations are redirecting procurement patterns toward regional sourcing strategies.
United States
Pet insurance penetration exceeding forty percent in metropolitan corridors lowers effective cost barriers for companion-animal diagnostic imaging. The FDA Center for Veterinary Medicine maintains device safety labeling requirements for food-producing animal applications. University veterinary medical centers in California and North Carolina anchor procurement volume for premium cart-based systems with 3D reconstruction modules.
Germany
Specialty referral networks in Bavaria and North Rhine-Westphalia sustain demand for advanced Doppler-equipped platforms. The EU Medical Device Regulation through German notified bodies imposes conformity assessment requirements on imported scanners with AI-enabled diagnostic software. Esaote SpA maintains European headquarters and service infrastructure in Genoa, channeling distribution through Frankfurt logistics clusters.
China
Domestic production capacity for portable ultrasound systems serves price-sensitive clinics across tier-two and tier-three cities. The National Medical Products Administration harmonizes veterinary device registration with human healthcare standards under revised classification rules. Shenzhen Mindray Animal Medical Technology anchors volume manufacturing in the Pearl River Delta for export to Southeast Asian markets.
Japan
Aging livestock populations and equine sports medicine protocols drive replacement cycles for high-frequency linear transducers. The Ministry of Health, Labour and Welfare delegates veterinary device oversight to prefectural agricultural authorities under streamlined notification procedures. Tokyo metropolitan specialty hospitals concentrate procurement authority for premium systems with elastography capabilities.
United Kingdom
Corporate consolidators in Greater London and the Southeast impose standardization mandates across multi-site practice networks. The Veterinary Medicines Directorate coordinates with MHRA on device safety surveillance for imported equipment. Manchester and Liverpool clusters host independent small-animal practices balancing equipment utilization against lease obligations.
Veterinary Ultrasound Scanners Market Vendor Landscape
Concentration sits with diversified medical imaging conglomerates and dedicated veterinary specialists. The vendor base spans three tiers: premium-platform manufacturers leveraging human healthcare heritage, mid-market portable specialists, and handheld probe assemblers. Strategic moves center on AI software integration and subscription-based equipment access models displacing outright purchase arrangements.
Within the diversified imaging tier, GE Healthcare and Siemens Healthineers occupy positions anchored by hospital system relationships. Esaote SpA exemplifies the veterinary-dedicated specialist archetype with purpose-built transducer ergonomics. Shenzhen Mindray Animal Medical Technology represents the volume-production portable segment serving price-sensitive Asian clinics.
| Leading Market Players |
|---|
| GE Healthcare |
| Esaote SpA |
| IDEXX Laboratories |
| Shenzhen Mindray Animal Medical Technology |
| FUJIFILM Corporation |
| Siemens Healthineers |
| Carestream Health |
| Heska Corporation |
| Samsung Healthcare |
| Others |
Supply Flow & Price Mechanics
ISO 10993 biocompatibility certification gates both transducer material qualification and tiered price positioning across veterinary ultrasound markets. Manufacturers lacking notified-body endorsement face exclusion from European procurement channels while certified suppliers command premium positioning in university hospital segments.
Pricing Analysis
The customization-premium spread separates configured-to-order cart-based platforms from standard portable configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Price differentiation hinges on FDA Center for Veterinary Medicine labeling depth and 3D imaging module inclusion. Price erosion runs through handheld probe segments as smartphone-tethered assemblers compete on capital barrier reduction. Corporate consolidators exhibit lowest price sensitivity through subscription-based equipment access models.
Supply Chain Analysis
Piezoelectric ceramic substrate sourcing from Japanese and Chinese suppliers creates chokepoint exposure for transducer array manufacturers. High-purity PZT ceramics and CMUT semiconductor wafers draw from concentrated East Asian production hubs. Single-source vulnerability in ceramic substrate supply threatens production continuity during geopolitical friction. Distribution runs through regional service networks anchored by Frankfurt, Singapore, and Dallas logistics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of credentialed veterinary sonographers constrains utilization expansion and creates acquisition premiums for training-capable platforms. This capability gap rewards vendors bundling education with hardware deployment.
For Market Incumbents: Compound defensive positioning through AI software module integration and captive service network expansion. Defend against portable specialists by embedding predictive maintenance algorithms that lock in multi-year contracts. Prioritize backward integration into transducer ceramic sourcing to secure margin control against input volatility. For New Entrants and Emerging Players: Differentiate on wireless telemedicine protocols targeting rural ambulatory large-animal practices lacking on-site radiologists. White-space concentration sits with equine sports medicine stables in Kentucky and Florida demanding high-frequency linear transducers. Pursue direct-to-practice digital marketing bypassing established distributor markups. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed veterinary practice networks seeking technology refresh guarantees. Five-to-ten year viability favors vendors with established European notified-body relationships and AI diagnostic software pipelines. Watch FDA software-as-medical-device classification debates as inflection signal for regulatory-compressed valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| AI Diagnostic Software Development | Machine learning modules for automated cardiac measurement trigger premium pricing tiers and recurring revenue streams. |
| Notified-Body Certification Investment | EU MDR conformity assessment accelerates market access for imported scanners across German and French referral networks. |
| Subscription Equipment Access Models | Per-procedure leasing with bundled maintenance displaces capital-intensive ownership in US corporate consolidators. |
| CMUT Transducer Platform Transition | Semiconductor-based arrays enable thermal efficiency gains in battery-operated portable configurations. |
| Telemedicine Protocol Integration | Wireless image transmission extends specialist interpretation reach into rural Great Plains feedlot operations. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU notified-body conformity databases, and veterinary practice procurement records. Interviews with biomedical engineers at university teaching hospitals, GPO contracts managers at corporate consolidators, and regulatory affairs leads at transducer manufacturers informed demand-side validation. Bottom-up equipment shipment analysis triangulates against top-down veterinary service market sizing.
Segmentation dimensions modeled span product type, technology tier, end-user category, and application indication across the projection horizon. CAGRs derive from installed base replacement cycles, pet insurance penetration trajectories, and specialty referral network expansion rates. Forecast inputs incorporate AI software adoption curves and CMUT platform transition timelines.
Material uncertainties — regulatory reclassification of AI diagnostic modules, piezoelectric ceramic supply disruptions, and corporate consolidator procurement standardization — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as FDA software-as-medical-device guidance and EU MDR enforcement patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Market
Medical Devices
Soft Tissue Release Systems Market
Medical Devices
Automated Compounding Systems Market
Medical Devices
Arthroscopy Visualization Systems Market
Medical Devices
Global Anesthesia Gas Blender Market
Medical Devices
Heel Incision Devices Market
Medical Devices
Pancreatic and Biliary Stents Market
Medical Devices
Face Mask Device Market
Medical Devices
Stimulation Therapies Market
Medical Devices
Ovulation Microscope Market
Medical Devices
Pelvic Floor Electrical Stimulation Devices Market
Medical Devices
US Contact Lenses Market
Medical Devices
Global Embolic Protection Device Market
Medical Devices
Polymer-Based Prefilled Syringe Market
Medical Devices
Intravascular Temperature Management Systems Market
Medical Devices
India Hemostats Market