
 Human Anatomical Models Market | 2026-2036
Human Anatomical Models Market Size, Share, and Industry Trends Forecast 2026-2036
Human Anatomical Models Market Outlook
The EU Green Deal is broadening procurement criteria for medical education equipment across European teaching hospitals. Materialise leverages additive manufacturing expertise to produce patient-specific anatomical replicas. Stratasys anchors polymer-based model production with multi-material jetting systems. Laerdal Medical dominates high-fidelity simulation integration alongside traditional anatomical forms.
Human anatomical models are three-dimensional physical representations of body structures, typically fabricated from thermoplastics, platinum-cured silicone, or resin composites via injection molding, CNC machining, or additive manufacturing, serving primarily to support spatial understanding in medical pedagogy and preoperative planning. Skeleton models and organ models occupy the largest revenue share due to their foundational role in core curricula, while 3D anatomical maps represent the fastest-expanding category as institutions adopt patient-derived imaging workflows. Medical schools command the dominant end-user channel, though surgical training applications within hospitals are yielding higher per-unit margins.
The FDA oversees device classification for anatomical models used in diagnostic or surgical planning contexts, while ISO 13485 quality management standards govern manufacturing consistency for clinical-grade replicas; the EU MDR framework extends conformity requirements to educational devices with patient-contact potential. Accreditation bodies including the Liaison Committee on Medical Education in the United States and the General Medical Council in the United Kingdom mandate hands-on anatomical training, embedding institutional purchasing cycles. Stakeholders must evaluate whether to prioritize regulatory-compliant clinical-grade production or scale standardized educational catalogs as procurement standards diverge.
Market Dynamics
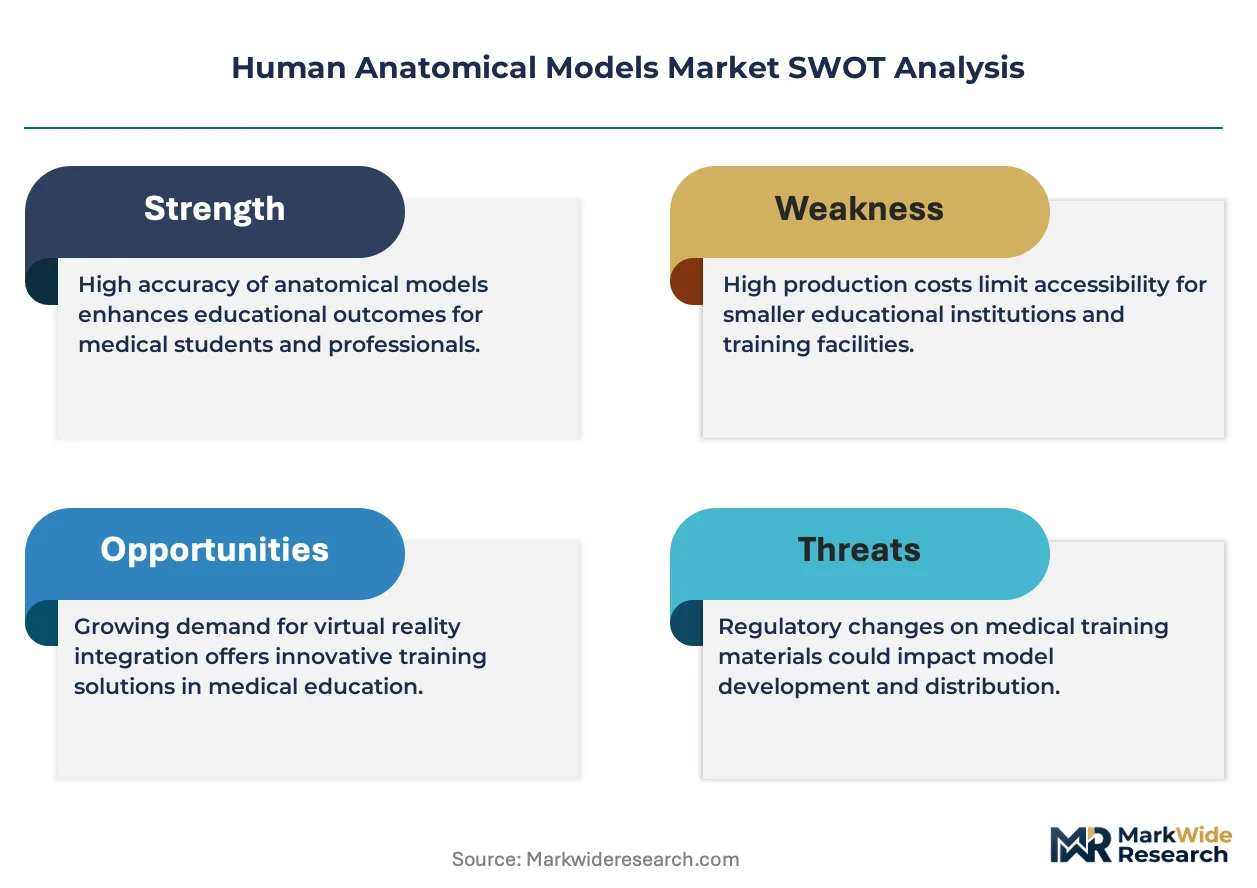
EU MDR conformity requirements are compressing procurement timelines for educational devices with patient-contact potential, forcing manufacturers to choose between clinical-grade certification investments and standardized catalog scaling.
Growth Catalysts
- Simulation-based curriculum expansion:Medical schools across the United States are embedding hands-on anatomical training into core pedagogy, accelerating institutional purchasing cycles.
- EU Green Deal procurement criteria:European teaching hospitals now prioritize sustainable material sourcing in medical education equipment tenders, favoring recyclable thermoplastics and bio-based resins.
- Patient-derived imaging workflows:3D anatomical maps fabricated from DICOM datasets are displacing generic models in preoperative planning, creating pull from hospital surgical departments.
Market Restraints
- Platinum-cured silicone cost volatility:Medical-grade elastomer prices fluctuate with precious metal markets, compressing margins on high-fidelity organ replicas.
- German university hospital cluster concentration:Demand aggregation within Bavaria and Baden-Württemberg creates pricing power asymmetry for large-volume purchasers.
- ISO 13485 certification timelines:Eighteen-month quality management system audits delay market entry for clinical-grade replica producers.
Strategic Opportunities
- Surgical training application expansion:Hospital-based procedural simulation yields higher per-unit margins than medical school skeleton model sales.
- Multi-material jetting convergence:Polymer-based systems combining rigid and flexible photopolymers enable single-print organ replicas with tissue-mimetic properties.
- United Kingdom General Medical Council mandates:Updated accreditation standards require demonstrable tactile anatomical competence, embedding recurring procurement into institutional budgets.
Industry Challenges
- Additive manufacturing technician scarcity:Patient-specific replica production requires DICOM segmentation and build orientation expertise rarely found in traditional medical model workshops.
- EU MDR technical documentation burden:Educational device manufacturers must now compile clinical evidence for models with incidental patient-contact potential, extending time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Anatomical Models Market |
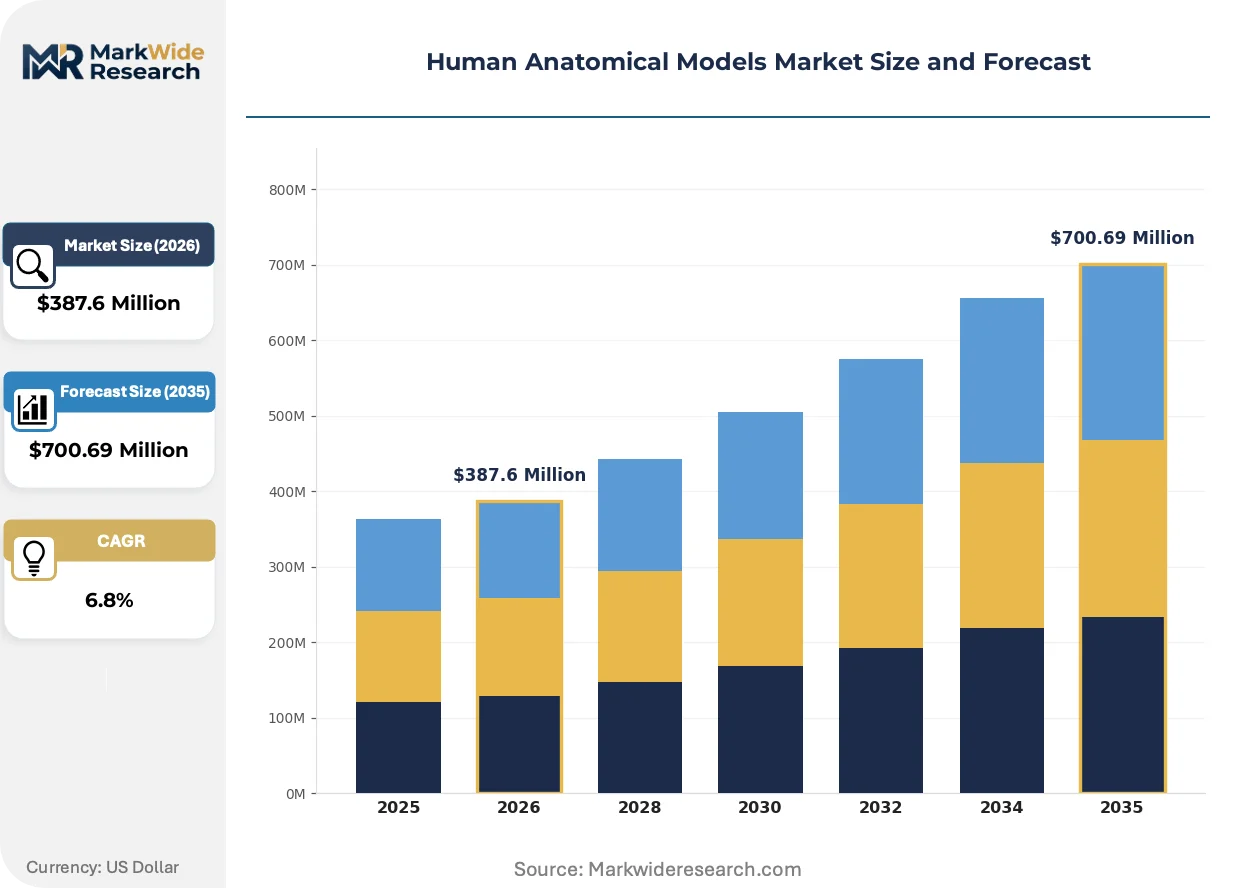
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skeleton Models, Organ Models, Surface Models, 3D Anatomical Maps Material: Plastic, Silicone, Wood, Metal End User: Medical Schools, Hospitals, Research Institutions, Clinics Application: Education, Surgical Training, Patient Education, Research |
| Companies Covered | 3B Scientific, Stratasys, Laerdal Medical, Erler-Zimmer, Materialise, CAE Healthcare, Kyoto Kagaku, GPI Anatomicals, Gaumard Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Anatomical Models Market Strategic Shifts
Digital manufacturing workflows are displacing conventional injection molding for complex anatomical geometries, while regulatory frameworks increasingly distinguish between educational display pieces and clinical planning tools.
Additive manufacturing is converging with diagnostic imaging pipelines to produce patient-specific anatomical replicas directly from CT and MRI datasets. Teaching hospitals in Germany and the United States are adopting these workflows for preoperative team briefings. This convergence compresses the traditional supply chain from generic catalog orders to same-facility production, altering distributor relationships and inventory models.
EU MDR Article 1 scope expansion now captures educational anatomical models with potential patient contact, requiring conformity assessment procedures previously reserved for clinical devices. Manufacturers serving European teaching hospitals must maintain technical documentation and post-market surveillance systems. Small-scale educational model producers without ISO 13485 infrastructure face market exit or acquisition.
Buying committees at United States medical schools are unbundling anatomical model procurement from simulation center capital budgets, creating discrete purchasing authority for department-level acquisition. This fragmentation favors specialized vendors with direct institutional relationships over broadline medical distributors. Procurement visibility has shifted toward procurement officers with clinical backgrounds rather than general supply chain managers.
Human Anatomical Models Market Segmentation
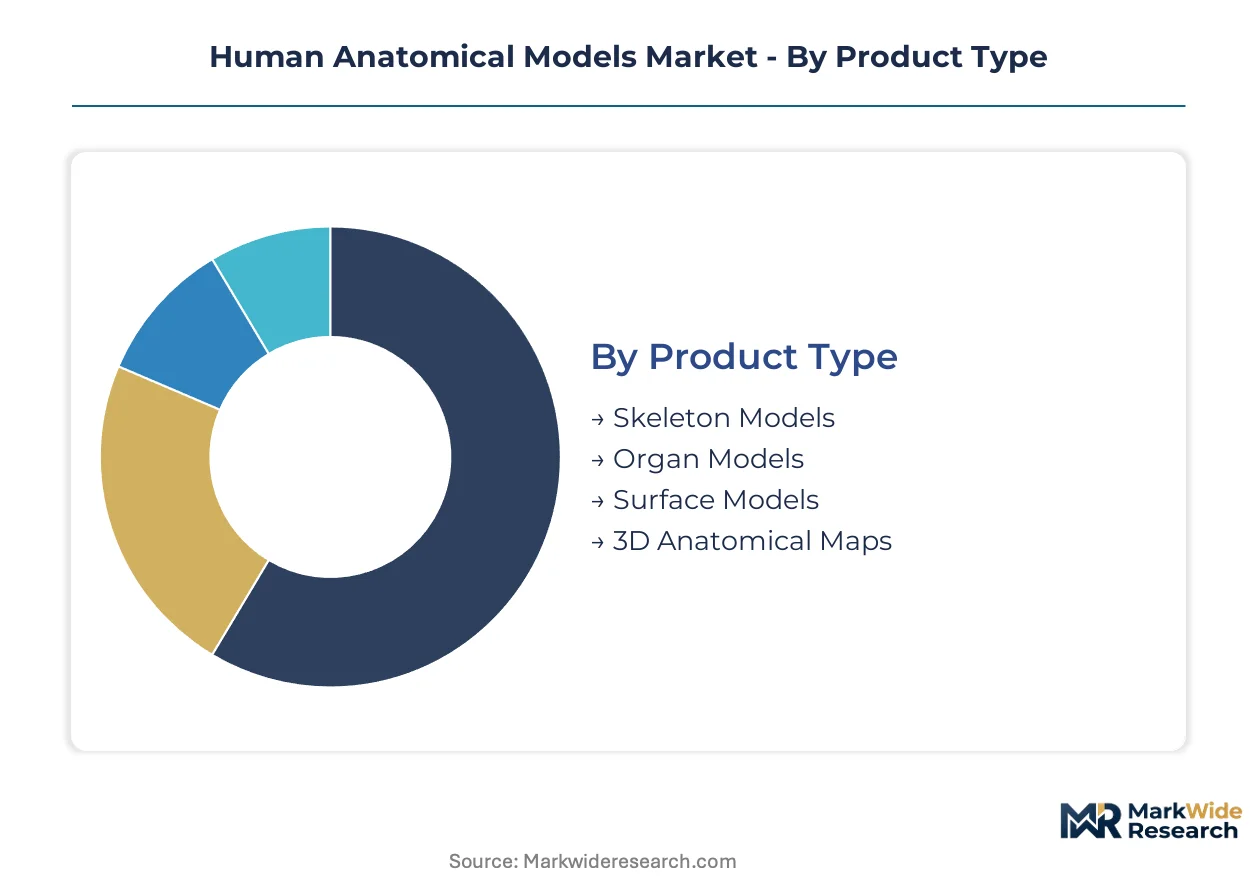
Segmentation in human anatomical models reveals distinct capital requirements and margin profiles across fabrication methods and end-use channels. Procurement patterns diverge sharply between high-volume educational catalogs and low-volume patient-specific replicas.
Product Type:
Capital intensity peaks in 3D anatomical maps requiring additive manufacturing infrastructure, while skeleton models demand conventional injection molding investments at scale.
- Skeleton Models:Full-scale osteological replicas fabricated from thermoplastic polymers or resin composites via injection molding. Demand concentrates in United States medical school core curricula, where LCME accreditation mandates hands-on anatomical training. Procurement cycles align with academic budget years.
- Organ Models:Visceral replicas span rigid display pieces to platinum-cured silicone simulacra with tissue-mimetic compliance. Hospital surgical departments in Germany's university hospital clusters drive demand for procedure-specific configurations. Silicone cost volatility compresses margins on high-fidelity variants.
- Surface Models:Dermatological and superficial anatomy displays for dermatology and plastic surgery training.
- 3D Anatomical Maps:Patient-derived replicas from DICOM segmentation workflows.
Most installed capacity flows through skeleton models. Expansion is steepest in 3D anatomical maps.
Material:
Cost tiering separates commodity thermoplastics from medical-grade elastomers, with bio-based resins gaining procurement preference under EU Green Deal criteria.
- Plastic:ABS, PVC, and recyclable thermoplastics dominate high-volume educational production. United States medical schools prioritize durability and cost efficiency in skeleton and organ displays. EU teaching hospitals increasingly specify post-consumer recycled content in tenders.
- Silicone:Platinum-cured medical-grade elastomers enable tissue-mimetic compliance for surgical simulation. German hospital procurement aggregates demand for procedure-specific organ replicas. Precious metal price volatility creates margin pressure.
- Wood:Traditional osteological teaching specimens with limited contemporary procurement.
- Metal:Stainless steel and aluminum alloys for articulated joint mechanisms.
Plastic commands the largest production volume. Silicone captures the highest per-unit margins.
End User:
Customer type determines pricing power, with hospital surgical departments yielding premium margins versus medical school volume purchasing.
- Medical Schools:Primary channel for standardized anatomical curricula. United States institutions unbundle procurement from simulation center budgets, creating discrete departmental purchasing authority. LCME and GMC accreditation mandates embed recurring demand.
- Hospitals:Surgical training applications generate highest per-unit margins. Patient-derived 3D replicas for preoperative planning command premium pricing. EU MDR compliance requirements extend to educational devices with patient-contact potential.
- Research Institutions:Specialized replicas for biomechanical and morphological studies.
- Clinics:Limited procurement for patient education and informed consent demonstrations.
Medical schools anchor volume demand. Hospitals drive margin expansion.
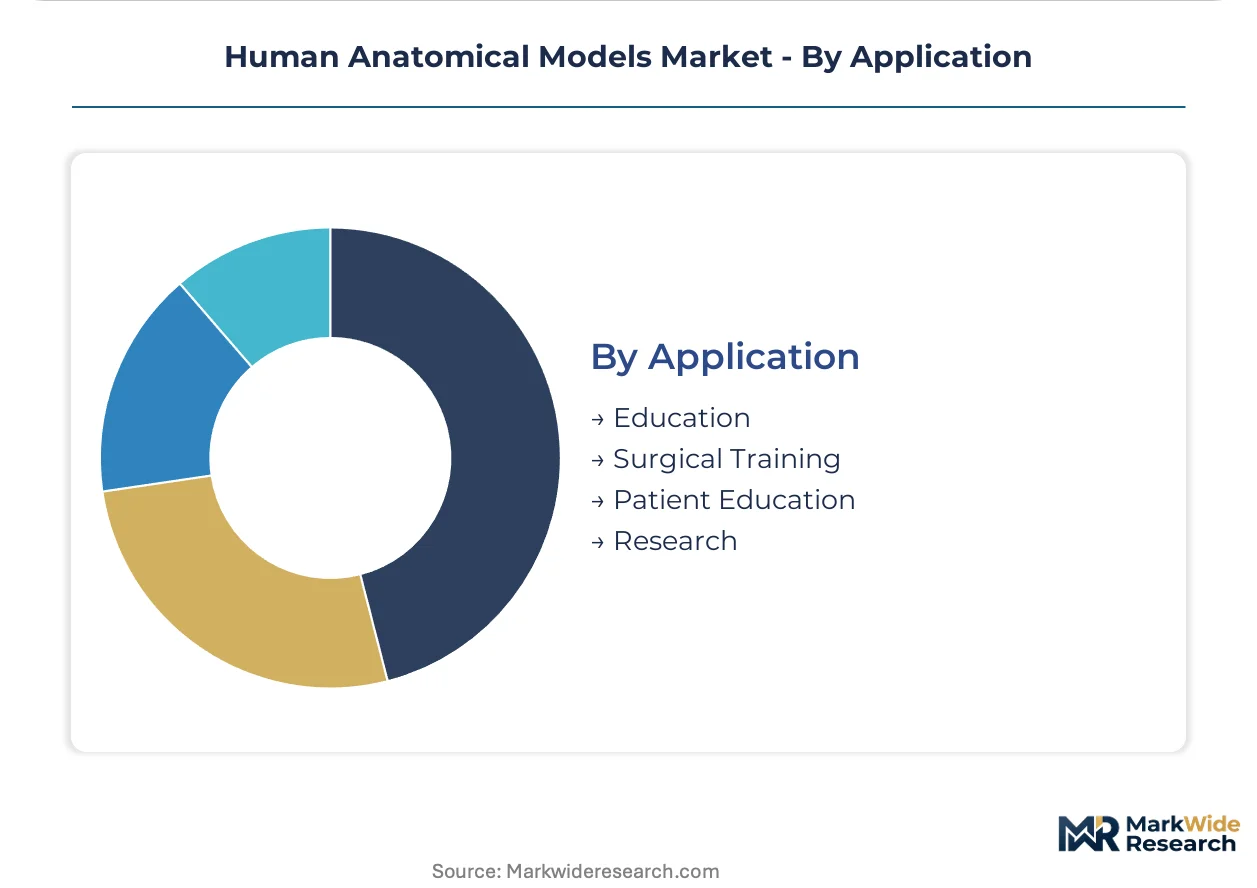
Application:
Maturity gradients separate established educational workflows from emerging surgical simulation protocols, with regulatory scope determining market access requirements.
- Education:Foundational anatomical pedagogy in medical, nursing, and allied health programs. United Kingdom GMC updated standards require demonstrable tactile competence, embedding recurring procurement. Standardized catalog production avoids ISO 13485 certification burdens.
- Surgical Training:Procedural simulation yields highest value capture. Hospital-based adoption of patient-specific replicas for team briefings is gaining share fastest. FDA device classification applies to diagnostic and surgical planning contexts.
- Patient Education:Informed consent and preoperative communication tools.
- Research:Morphological and biomechanical investigation substrates.
Education absorbs the most units. Surgical training is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The human anatomical models industry traces its modern commercial roots to nineteenth-century German scientific instrument workshops in Leipzig and Berlin, where precision-crafted osteological specimens first standardized medical pedagogy across European universities.
United States
Medical schools in the United States embed simulation-based curricula through LCME accreditation mandates, driving recurring procurement cycles aligned with academic budget years. FDA device classification applies to anatomical models used in diagnostic or surgical planning contexts. The Greater Boston and Baltimore corridors concentrate teaching hospital clusters where patient-derived 3D replicas command premium pricing for preoperative team briefings.
Germany
German university hospital clusters in Bavaria and Baden-Württemberg aggregate demand for procedure-specific organ configurations, creating pricing power asymmetry for large-volume purchasers. EU MDR conformity requirements now extend to educational devices with incidental patient-contact potential. Frankfurt and Stuttgart host additive manufacturing service bureaus supplying patient-specific replicas directly to surgical departments.
United Kingdom
General Medical Council updated accreditation standards require demonstrable tactile anatomical competence, embedding recurring procurement into institutional budgets across English and Scottish medical schools. NHS procurement frameworks increasingly specify sustainable material sourcing under broader UK net-zero commitments. London and Manchester teaching hospitals pilot same-facility 3D production workflows from DICOM datasets.
Japan
Japanese medical device regulation through PMDA creates structured pathways for clinical-grade anatomical replicas used in surgical planning. METI industrial policy supports additive manufacturing adoption in precision medical equipment. Tokyo and Osaka metropolitan areas concentrate university hospital demand for high-fidelity silicone organ models in minimally invasive surgery training programs.
China
China's NMPA oversees classification of anatomical models with diagnostic or therapeutic intent, while medical education expansion drives volume demand for standardized skeleton and organ displays. National dual carbon goals increasingly influence procurement criteria for educational equipment materials. Beijing and Shanghai teaching hospitals represent the primary adoption nodes for patient-specific 3D printed replicas in complex surgical cases.
Human Anatomical Models Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification-grade and application-intensity dimensions, with clinical-grade replica producers capturing value multiples above standardized educational catalog vendors. The vendor base organizes into three tiers: ISO 13485-certified clinical device manufacturers, specialized educational model fabricators, and diversified simulation technology conglomerates. Consolidation pressure concentrates among mid-scale educational producers lacking quality management infrastructure. Dominant competitive moves include M&A targeting additive manufacturing capabilities and strategic partnerships bridging imaging software with physical replica production.
Among diversified simulation technology providers, Laerdal Medical and CAE Healthcare occupy positions spanning high-fidelity manikins through anatomical display pieces, representing the integrated-simulation archetype. Materialise and Stratasys exemplify the digital-manufacturing tier, anchoring additive production workflows for patient-specific replicas. Japanese specialist Kyoto Kagaku and German fabricator Erler-Zimmer sit within the precision-educational segment, supplying standardized catalog products to institutional procurement channels.
| Leading Market Players |
|---|
| 3B Scientific |
| Stratasys |
| Laerdal Medical |
| Erler-Zimmer |
| Materialise |
| CAE Healthcare |
| Kyoto Kagaku |
| GPI Anatomicals |
| Gaumard Scientific |
| Others |
Value Chain & Pricing Dynamics
German university hospital cluster procurement aggregation for procedure-specific organ configurations is compressing margins on standardized educational catalogs while forcing suppliers to absorb ISO 13485 certification costs or exit European tenders entirely.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates platinum-cured silicone surgical replicas from thermoplastic educational displays and resin composite skeleton models. Price differentiation centers on ISO 13485 certification grade and patient-contact compliance tier. Cost compression in the standard tier is intensifying because EU MDR technical documentation burdens fall heaviest on mid-scale producers lacking quality infrastructure. Medical schools in the United States exhibit highest price sensitivity due to unbundled departmental budgets, while hospital surgical departments in Germany show lowest sensitivity for patient-derived 3D replicas.
Supply Chain Analysis
Direct-to-institutional channels handle medical school volume demand, while additive manufacturing service bureaus feed hospital surgical departments with patient-specific replicas. Production concentrates in Germany, the United States, and Japan for clinical-grade silicone organ models. Raw material sourcing draws from platinum-group metal markets for medical-grade elastomers, petrochemical feedstocks for thermoplastics, and photopolymer resins for multi-material jetting systems. Single-source vulnerability in platinum-cured silicone supply creates margin volatility when precious metal prices spike.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The human anatomical models market operates as a regulatory compounder where EU MDR scope expansion to educational devices with patient-contact potential is embedding recurring compliance investment into institutional procurement cycles.
For Market Incumbents: Cement market position by acquiring additive manufacturing service bureaus in Frankfurt and Stuttgart to capture patient-specific replica demand from German university hospital clusters. Accelerate ISO 13485 certification timelines for educational catalog lines before EU MDR enforcement eliminates uncertified competitors from European tenders. Channel control through direct institutional relationships offers defensive moats against distributor disintermediation. For New Entrants and Emerging Players: Imaging software vendors represent the most accessible channel partner type for bypassing established distributor relationships and embedding directly into hospital DICOM-to-replica workflows. White-space concentration sits in United Kingdom medical schools where General Medical Council updated standards mandate tactile competence without entrenched incumbent relationships. Surgical training applications in NHS teaching hospitals offer the most penetrable premium segment for entrants with bio-based resin material credentials under UK net-zero procurement frameworks. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale educational model producers facing EU MDR-induced market exit pressure and seeking acquisition by ISO 13485-certified clinical device manufacturers. Long-term viability favors vertically integrated players controlling both DICOM segmentation software and multi-material jetting production capacity. Watch for inflection signals in United States medical school unbundling trends where discrete departmental purchasing authority fragments procurement away from broadline distributors.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment unlocks access to German university hospital cluster tenders. |
| Hospital System Partnership | Direct relationships with Greater Boston teaching hospitals secure premium pricing for patient-derived replicas. |
| Software Companion Development | DICOM segmentation tools embedded in radiology workflows pull through physical replica orders. |
| Backward Integration | In-house platinum-cured silicone compounding insulates margins from precious metal price volatility. |
| Reimbursement Strategy | FDA device classification for surgical planning models enables hospital capital budget allocation. |
Study Parameters
Multiple input streams — primary interviews with hospital purchasing committee members, biomedical engineers, and GPO contracts managers; secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement records; plus customs data on thermoplastic and silicone resin trade flows — were reconciled through bottom-up unit economics modeling and top-down market sizing triangulation.
Historical shipment patterns from injection molding and additive manufacturing service bureaus were cross-referenced against panel input from LCME-accredited medical school procurement officers across the analysis window. Segmentation dimensions modeled include product type, material grade tier, end-user channel, and application intensity. CAGRs were derived from installed base replacement cycles and patient-derived imaging workflow adoption curves, with surgical training margin expansion and EU Green Deal material specification shifts serving as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to platinum-group metal price volatility, EU MDR enforcement consistency, and additive manufacturing technician labor availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Dermatoscope Market
Medical Devices
Intelligent Prosthetics Market
Medical Devices
Assisted Walking Devices Market
Medical Devices
Remote Magnetic Catheter Systems Market
Medical Devices
Global Ureteral Stent Market
Medical Devices
Japan Ultrasound Devices Market
Medical Devices
Mucus Clearance Devices Market
Medical Devices
Global Cosmetic Contact Lens Market
Medical Devices
Endoscope Reprocessing Device Market
Medical Devices
Laser Aesthetic Devices Market
Medical Devices
Foot Massage Machine Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Hemoconcentrators Market
Medical Devices
Global Smart Biopsy Devices Market
Medical Devices
Australia Clear Aligner Market
Medical Devices
Global Pulse Oximetry Market