
 Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market | 2026-2036
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market Size, Share, and Industry Trends Forecast 2026-2036
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market Analysis
Transducer manufacturing in Japan is pivoting toward higher-frequency arrays for intracardiac applications. Boston Scientific Corporation leverages its integrated electrophysiology portfolio to anchor ICE catheter supply chains across North American hospital networks. Abbott Laboratories sustains competitive positioning through specialized IVUS consoles designed for coronary intervention workflows. Siemens Healthineers AG dominates premium imaging software development, extending its reach into catheter navigation systems.
Intracardiac echocardiography and intravascular ultrasound comprise catheter-delivered ultrasound modalities operating at frequencies between five and twenty megahertz, generating real-time cross-sectional images of cardiac chambers, valves, and vascular endothelium to guide minimally invasive structural and coronary procedures. The ICE Devices category leads current revenue contribution as electrophysiology labs standardize on disposable catheter systems for atrial fibrillation ablation guidance. IVUS Systems represent the fastest-growing product type as interventional cardiologists adopt intravascular imaging for complex lesion assessment before stent deployment. Ultrasound Catheters concentrate margin pools in single-use consumables, while 3D Imaging technology reshapes procedural efficiency in structural heart applications.
The FDA regulates ICE and IVUS devices as Class II medical devices under 510(k) pathways, requiring substantial equivalence demonstrations that shape product development timelines and clinical trial investments. CE marking under the EU MDR imposes enhanced post-market surveillance obligations, compelling manufacturers to maintain vigilant adverse event reporting systems across European markets. ISO 13485 quality management certification functions as a baseline threshold for supplier qualification by major hospital purchasing groups. Stakeholders must monitor evolving reimbursement coding decisions by CMS and parallel national authorities, as coverage determinations directly influence catheter utilization rates in outpatient versus inpatient settings.
Market Dynamics
Electrophysiology labs in the United States are consolidating imaging platform procurement around single-vendor catheter ecosystems, compressing supplier diversity and amplifying switching costs for hospital systems.
Growth Catalysts
- 510(k) pathway standardization:The FDA's streamlined substantial equivalence demonstrations for Class II intravascular devices reduce clinical trial burdens and accelerate catheter-to-market timelines for manufacturers targeting structural heart procedures.
- Coronary imaging adoption:Interventional cardiology suites are mandating intravascular ultrasound assessment for complex lesion characterization before stent deployment, embedding IVUS into standard-of-care protocols.
- Japan transducer manufacturing:Japanese component suppliers are pivoting production lines toward higher-frequency ultrasound arrays specifically engineered for intracardiac echocardiography applications.
Market Restraints
- Single-use consumable cost structure:Disposable ICE catheter pricing creates per-procedure cost burdens that constrain utilization in outpatient settings where reimbursement rates lag inpatient equivalents.
- EU MDR surveillance obligations:Enhanced post-market adverse event reporting requirements under European Medical Device Regulation impose compliance overhead that disproportionately burdens mid-tier manufacturers without established European infrastructure.
- Capacitive micromachined ultrasound transducer yield rates:CMUT fabrication complexity limits production scale and concentrates supply among specialized semiconductor foundries.
Strategic Opportunities
- India cath lab expansion:Private hospital chains in Mumbai and Delhi are installing integrated electrophysiology suites where ICE guidance for atrial fibrillation ablation remains underpenetrated relative to Western procedural volumes.
- AI-integrated catheter navigation:Machine learning algorithms for real-time anatomical segmentation are converging with robotic catheter steering systems to reduce operator learning curves.
- CMS outpatient reimbursement recalibration:Coverage determination reviews for structural heart procedures performed in ambulatory surgical centers could unlock demand compression currently gated by site-of-service payment differentials.
Industry Challenges
- Electrophysiology fellowship training gaps:ICE image interpretation competency lags catheter manipulation skills among graduating interventional cardiologists, extending proctoring requirements and slowing lab productivity ramp.
- Legacy imaging console incompatibility:Hospital systems with installed Siemens and GE ultrasound platforms face integration friction when adopting third-party catheter systems lacking native software protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market |
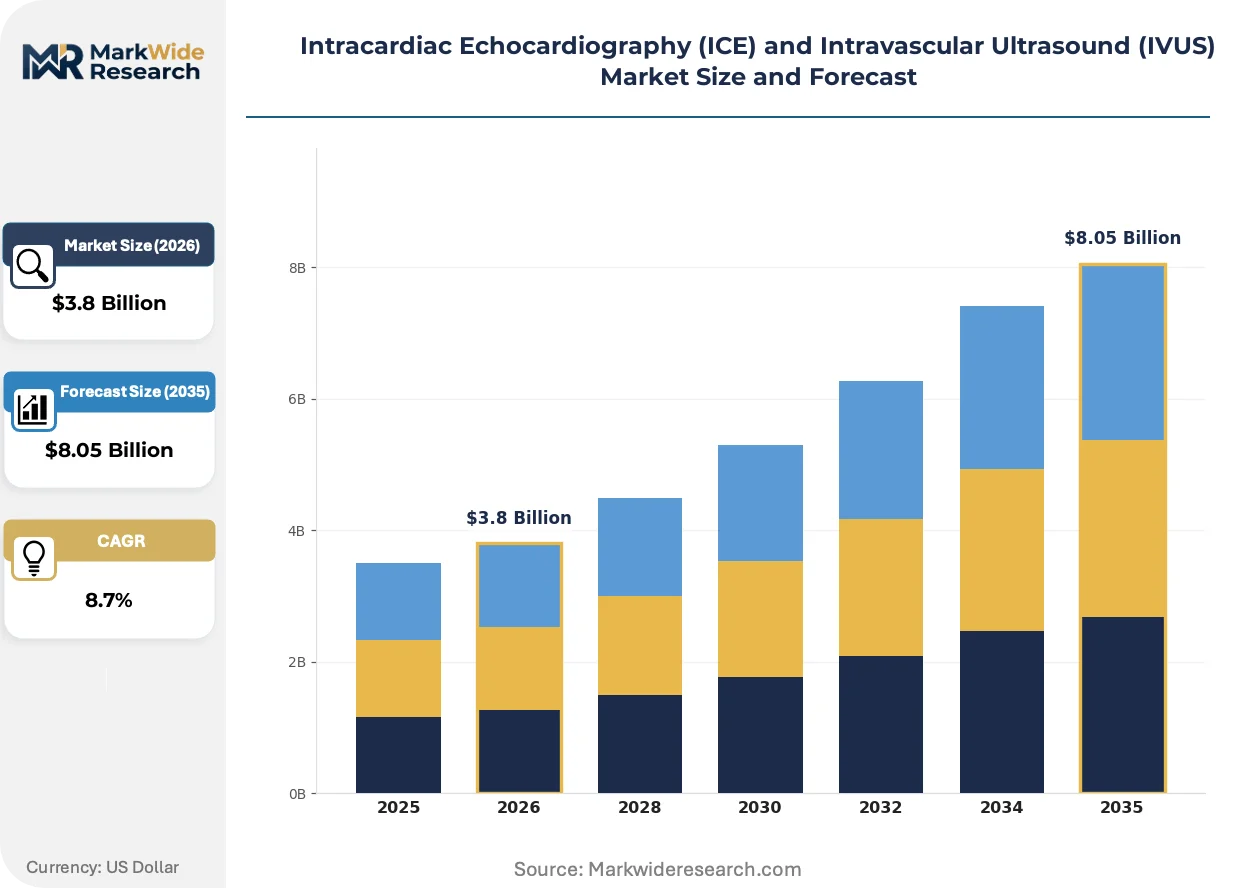
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ICE Devices, IVUS Systems, Ultrasound Catheters, Imaging Software End User: Cardiology Clinics, Hospitals, Surgical Centers, Research Institutions Technology: 2D Imaging, 3D Imaging, Doppler Ultrasound, Contrast Imaging Application: Structural Heart Procedures, Coronary Interventions, Catheter Navigation, Diagnostic Imaging |
| Companies Covered | Abbott Laboratories, Boston Scientific Corporation, Johnson & Johnson Services Inc. (Biosense Webster Inc.), Siemens Healthineers AG, Koninklijke Philips N.V., GE Healthcare, Medtronic plc, CONAVI MEDICAL, NIPRO (Infraredx, Inc.), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market Emerging Trajectories
Catheter-delivered imaging is bifurcating toward disposable single-use systems and premium reusable platforms, with software-defined image processing becoming the primary differentiation axis rather than hardware specifications alone.
Capacitive micromachined ultrasound transducer technology is overtaking traditional piezoelectric arrays in next-generation ICE catheters. CMUT elements enable broader bandwidth and improved near-field resolution for left atrial appendage visualization. Electrophysiology labs at Cleveland Clinic and Mayo Clinic are piloting these catheters for complex ablation procedures. The technology is overtaking legacy piezoelectric dominance by eliminating ceramic bonding failures and enabling smaller catheter French sizes.
The FDA's updated guidance on intravascular device biocompatibility testing is compressing predicate device reliance for 510(k) submissions. Manufacturers must now generate more primary clinical data rather than leaning on historical equivalence chains. ICE catheter suppliers targeting pediatric structural heart applications face the steepest compliance curve given limited predicate availability.
Hospital purchasing cooperatives are consolidating imaging platform decisions at the integrated delivery network level rather than individual cath lab autonomy. Banner Health and Kaiser Permanente are centralizing catheter procurement through single-source agreements spanning multiple facilities. This concentration is most visible in the United States where health system consolidation has accelerated since 2022.
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market Segmentation
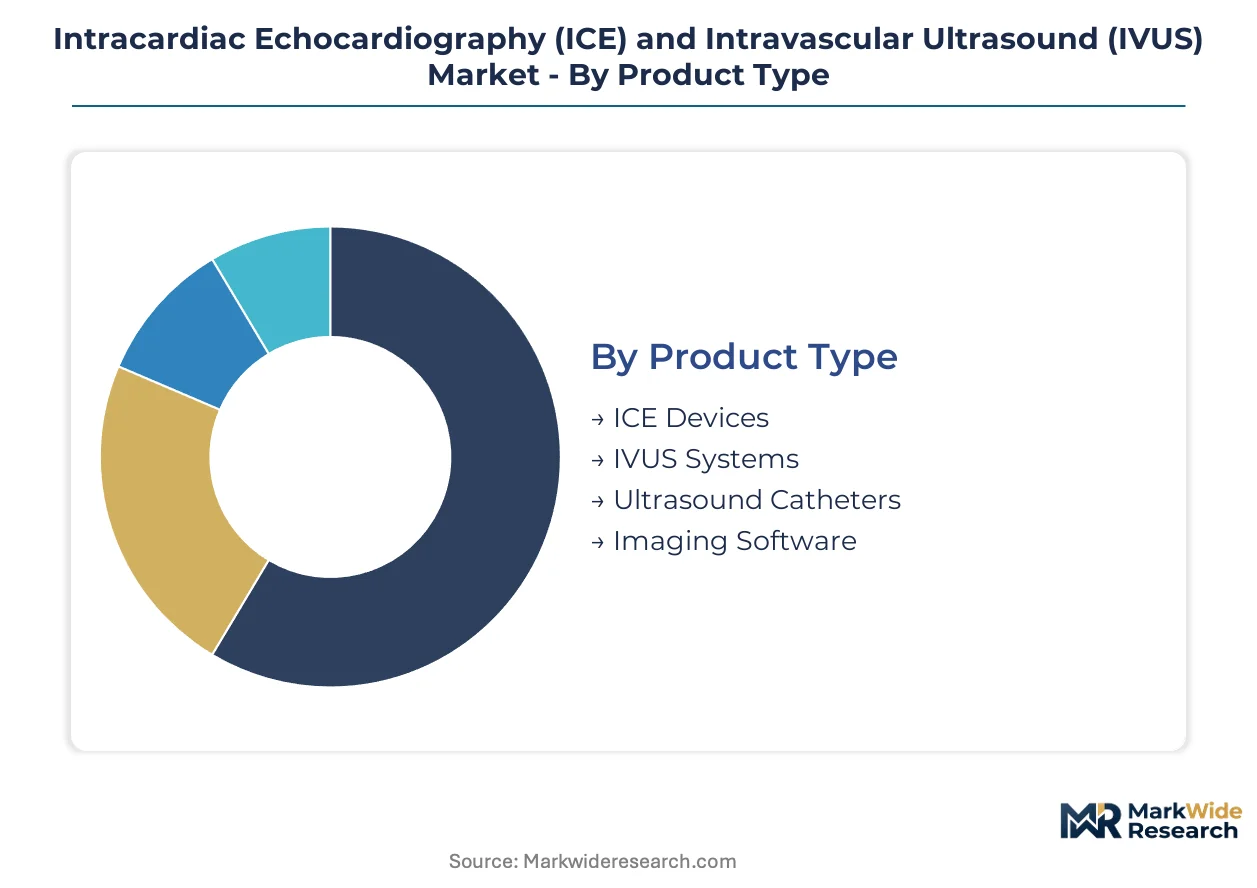
Catheter-based imaging markets fragment along disposable-reusable and hardware-software fault lines. Each segment carries distinct margin profiles, regulatory pathways, and procurement dynamics that shape vendor strategy and hospital purchasing behavior.
Product Type:
Standardization dominates high-volume catheter consumables while customization concentrates in integrated console systems.
- ICE Devices:Disposable catheter systems with phased-array transducers at 5-10 MHz frequencies generate real-time cardiac chamber visualization. Electrophysiology labs in the United States are standardizing these for atrial fibrillation ablation guidance, with procurement consolidating around single-vendor ecosystems that lock in recurring catheter revenue.
- IVUS Systems:Motorized pullback consoles with intravascular transducers operating at 20-40 MHz enable coronary plaque characterization. Interventional cardiology suites in Germany and Japan are mandating pre-stent deployment assessment, embedding these systems into complex lesion protocols.
- Ultrasound Catheters:Single-use delivery vehicles concentrate manufacturer margins through disposable economics.
- Imaging Software:Real-time reconstruction algorithms differentiate console platforms through proprietary processing pipelines.
Leading the category by volume: Ultrasound Catheters. Growing fastest: IVUS Systems.
End User:
Site-of-service reimbursement differentials create tiered adoption patterns across care settings.
- Cardiology Clinics:Outpatient electrophysiology facilities perform catheter ablations under ambulatory surgical center payment schedules. United States clinic chains in Florida and Texas are expanding ICE-guided atrial fibrillation volumes where site-neutral payment reforms improve per-procedure economics.
- Hospitals:Academic medical centers with structural heart programs deploy integrated ICE-IVUS platforms for transcatheter valve procedures. Cleveland Clinic and Mayo Clinic anchor premium system adoption through fellowship training pipelines and proctoring networks.
- Surgical Centers:Freestanding facilities face catheter cost constraints under compressed outpatient reimbursement.
- Research Institutions:Preclinical and first-in-human studies drive next-generation transducer validation.
Hospitals command the highest absolute spending. Cardiology Clinics are expanding most quickly as site-of-service migration accelerates.
Technology:
Maturity gradients separate established 2D modalities from emerging volumetric reconstruction.
- 2D Imaging:Planar ultrasound slices remain the workhorse for real-time catheter guidance in electrophysiology. Legacy consoles at mid-tier United States hospitals maintain installed-base dominance through lower capital replacement cycles.
- 3D Imaging:Volumetric reconstruction enables en-face valve visualization and left atrial appendage assessment. Siemens Healthineers and Philips are competing through proprietary software-defined beamforming that reduces acquisition time.
- Doppler Ultrasound:Blood flow velocity mapping supports hemodynamic assessment during structural procedures.
- Contrast Imaging:Microbubble enhancement improves endocardial border definition in challenging acoustic windows.
2D Imaging retains the largest installed base. 3D Imaging shows the steepest expansion trajectory as structural heart complexity demands volumetric orientation.
Application:
Procedure type determines catheter specification, imaging frequency, and reimbursement coding.
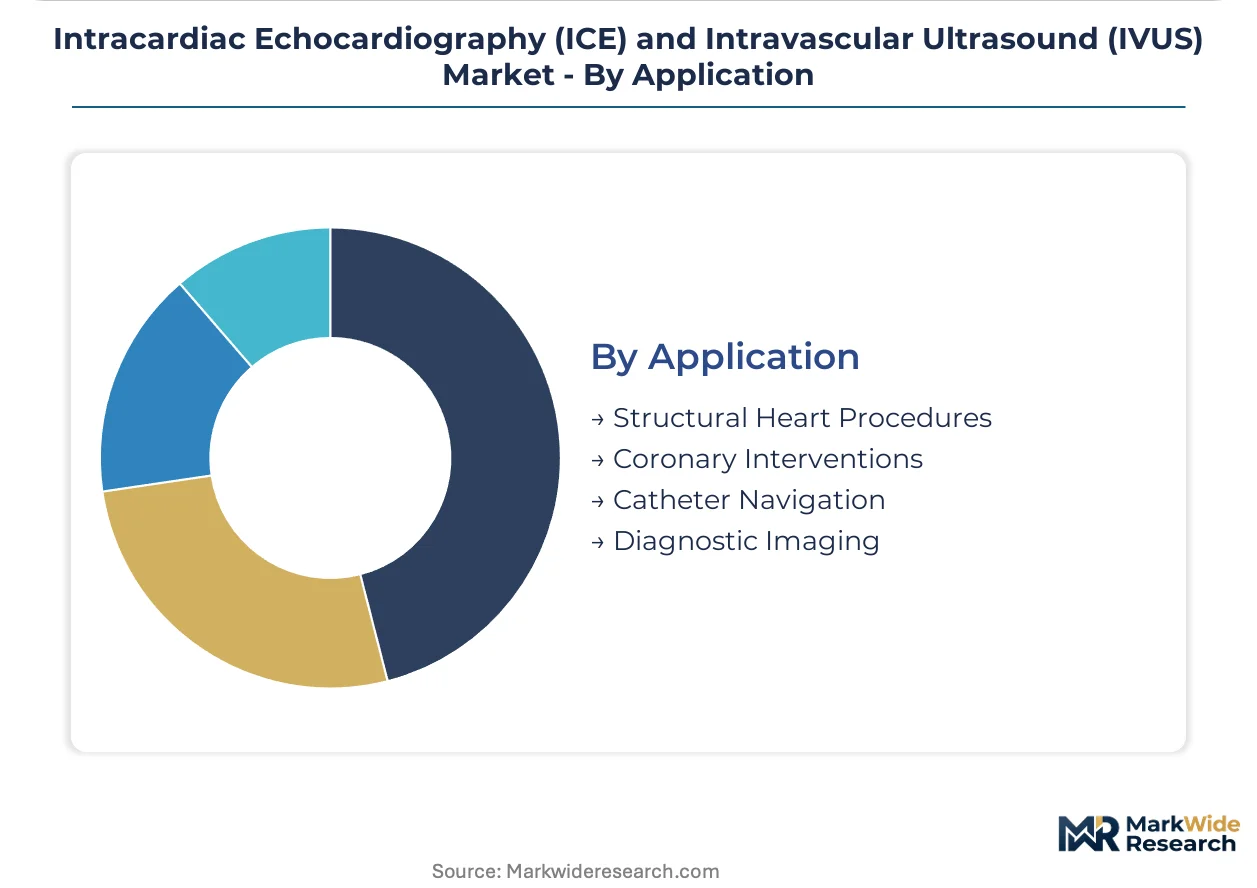
- Structural Heart Procedures:Transcatheter valve repair and left atrial appendage closure demand high-resolution ICE guidance. United States hospital systems are consolidating these cases into specialized valve centers where imaging platform standardization reduces training variance.
- Coronary Interventions:IVUS-guided stent optimization reduces restenosis in complex bifurcation lesions. Japanese and Korean interventionalists lead percutaneous coronary intervention imaging penetration rates.
- Catheter Navigation:Electroanatomic mapping integration requires real-time ICE confirmation of catheter-tissue contact.
- Diagnostic Imaging:Intravascular characterization supports lesion severity assessment when angiography proves ambiguous.
Structural Heart Procedures generate the highest revenue per case. Coronary Interventions are gaining share fastest as IVUS standardization spreads beyond specialized centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese semiconductor foundries in Kyoto and Osaka prefectures supply the high-frequency piezoelectric arrays that power next-generation ICE catheter transducers. These component clusters anchor the upstream supply chain for catheter-based imaging systems deployed across electrophysiology labs worldwide.
United States
Hospital systems in Texas and Florida are expanding ambulatory surgical center networks for ICE-guided atrial fibrillation ablation. FDA 510(k) pathway standardization accelerates catheter approval timelines for structural heart applications. Cleveland Clinic anchors premium system adoption through integrated electrophysiology fellowship training pipelines.
Germany
Interventional cardiology suites in Munich and Heidelberg mandate IVUS assessment for complex coronary lesion characterization before stent deployment. EU MDR post-market surveillance obligations compel manufacturers to maintain vigilant adverse event reporting systems. The Baden-Württemberg medical technology cluster concentrates console manufacturing for European hospital networks.
Japan
Electrophysiology labs in Tokyo and Osaka are piloting CMUT-based ICE catheters for left atrial appendage visualization. PMDA regulatory harmonization with FDA standards reduces duplicate clinical trial requirements for device approvals. Nagoya-area transducer foundries are pivoting production lines toward higher-frequency arrays specifically engineered for intracardiac applications.
India
Private hospital chains in Mumbai and Delhi are installing integrated electrophysiology suites where ICE guidance remains underpenetrated relative to Western procedural volumes. CDSCO medical device registration requirements are streamlining for Class B and C intravascular products. The Karnataka medical device park near Bangalore is attracting catheter assembly operations for South Asian market supply.
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized transducer architectures and AI-integrated software modules. The market structures around three maturity tiers: diversified medical technology conglomerates with integrated electrophysiology portfolios, specialized catheter manufacturers with disposable consumable focus, and imaging software developers with proprietary reconstruction algorithms. Dominant competitive moves include strategic partnerships between catheter suppliers and robotic navigation platforms, plus backward integration into transducer semiconductor fabrication.
Among diversified health technology conglomerates, Abbott Laboratories, Boston Scientific Corporation, and Siemens Healthineers AG exemplify the integrated-platform archetype. Abbott Laboratories occupies a position within specialized IVUS console development for coronary intervention workflows. Boston Scientific Corporation anchors supply chain relationships across North American hospital networks through its electrophysiology portfolio breadth. Siemens Healthineers AG represents the premium imaging software tier with extension into catheter navigation system integration.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Boston Scientific Corporation |
| Johnson & Johnson Services Inc. (Biosense Webster Inc.) |
| Siemens Healthineers AG |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Medtronic plc |
| CONAVI MEDICAL |
| NIPRO (Infraredx, Inc.) |
| Others |
Supply Flow & Price Mechanics
Transducer fabrication specialists concentrated in Japan's Kyoto-Osaka corridor command wage premiums that compress margin spreads between economy-grade piezoelectric arrays and premium CMUT architectures. Labor-cost differentials between Japanese semiconductor foundries and emerging assembly operations in India widen pricing-tier spreads for ICE catheter systems across hospital procurement categories.
Pricing Analysis
Service-bundling separates capital-intensive console platforms from unbundled disposable catheter procurement. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, ISO 13485 certification status, and native software protocol compatibility with installed Siemens or GE ultrasound bases. Pricing pressure stems from hospital purchasing cooperative consolidation compressing supplier margins through single-source agreements. Outpatient cardiology clinics exhibit highest price sensitivity due to site-of-service reimbursement differentials, while academic medical centers prioritize integration over per-unit cost.
Supply Chain Analysis
Workforce availability constraints in Japanese precision manufacturing hubs limit CMUT foundry expansion, tethering high-frequency transducer supply to established Kyoto-Osaka operations. Raw material dependencies center on specialty piezoelectric ceramics, silicon-on-insulator wafers, and biocompatible catheter polymers sourced from Japan, Germany, and the United States. Single-source vulnerability concentrates in CMUT semiconductor fabrication where yield-rate complexity restricts qualified suppliers. Distribution runs through integrated delivery network procurement offices rather than individual cath lab autonomy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacitive micromachined ultrasound transducer technology is displacing legacy piezoelectric arrays in next-generation ICE catheters, creating a technology-transition window where manufacturing capability determines competitive survival.
For Market Incumbents: To counter CMUT-based entrants from Japanese semiconductor specialists, backward integration into transducer foundry partnerships secures supply continuity, while exclusive software protocol development with Siemens Healthineers and Philips locks hospital systems into integrated catheter-console ecosystems that amplify switching costs. For New Entrants and Emerging Players: Enter via India's underpenetrated electrophysiology suites in Mumbai and Delhi where ICE-guided atrial fibrillation volumes lag Western benchmarks, leveraging CDSCO streamlined registration for Class B and C intravascular devices and local catheter assembly at Karnataka medical device parks to compress landed cost against incumbent imports. For Investors and Strategic Acquirers: Re-rating potential sits with CMUT-capable mid-tier manufacturers given FDA biocompatibility guidance compression forcing primary clinical data generation that favors technical specialists over diversified conglomerates; long-term viability hinges on catheter navigation software integration with robotic platforms, with PMDA-FDA harmonization progress as the inflection signal to monitor.| Strategic Initiative | Industry Significance |
|---|---|
| CMUT Transducer Manufacturing Scale-Up | Japanese foundry expansion eliminates ceramic bonding failures and enables smaller French sizes for complex ablation access. |
| FDA 510(k) Biocompatibility Pathway Investment | Primary clinical data generation capabilities accelerate approval timelines for pediatric structural heart predicates. |
| Hospital System Partnership Consolidation | Banner Health and Kaiser Permanente single-source agreements lock recurring catheter revenue across multi-facility networks. |
| AI-Integrated Catheter Navigation Development | Real-time anatomical segmentation algorithms reduce operator learning curves and proctoring requirements in electrophysiology labs. |
| Reimbursement Strategy for Ambulatory Settings | CMS outpatient coverage determination advocacy unlocks demand compression currently gated by site-of-service payment differentials. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with electrophysiology lab directors, hospital GPO contracts managers, biomedical engineers at Cleveland Clinic and Mayo Clinic, and catheter procurement leads at Banner Health and Kaiser Permanente. FDA 510(k) clearance databases, PMDA submission records, EU MDR post-market surveillance reports, and hospital procurement databases provided secondary validation. Bottom-up catheter unit shipment estimates triangulated against top-down imaging platform installation counts across analysis window.
Data-stream reconciliation across product type, end user, technology, and application segmentation dimensions generated volume and value outputs over the projection horizon. CAGRs derived from procedure volume growth rates, catheter utilization per procedure, and site-of-service migration patterns. Industry-specific forecast inputs incorporated electrophysiology fellowship training pipeline expansion and CMUT yield-rate improvement trajectories.
Revisions become necessary when FDA guidance shifts on intravascular device biocompatibility testing, EU MDR surveillance obligations intensify, or CMUT foundry yield breakthroughs alter supply economics. Forecasts reflect assumptions on reimbursement coding stability and hospital consolidation continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiac Ablation Market
Cardiovascular Devices
Perfusion Systems Market
Cardiovascular Devices
Implantable Infusion Pumps Market
Cardiovascular Devices
Cardiac Sutures Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Cardiovascular and Soft Tissue Repair Patches Market
Cardiovascular Devices
Cardiac Implantable Electronic Device Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Disposable Blood Pressure Cuffs Market
Cardiovascular Devices
Global Critical Limb Ischemia Treatment Market
Cardiovascular Devices
Endovascular Aneurysm Repair Market
Cardiovascular Devices
Global PTA Balloon Catheter Market
Cardiovascular Devices
Infusion System Market
Cardiovascular Devices
Global Sclerotherapy Market
Cardiovascular Devices
Wearable Artificial Organs Market
Cardiovascular Devices
Bioresorbable Coronary Stents Market