
 Global Companion Animal Diagnostics Market | 2026-2036
Global Companion Animal Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Companion Animal Diagnostics Market Foresight
Point-of-care polymerase chain reaction miniaturization is reconfiguring how veterinary clinics process infectious disease samples without external lab dependency. IDEXX Laboratories leverages integrated hardware-software platforms to dominate benchtop chemistry workflows in North American clinics. Zoetis sustains R&D intensity across companion animal immunoassay portfolios, while Thermo Fisher Scientific anchors molecular reagent supply chains for third-party diagnostic manufacturers.
Companion animal diagnostics encompasses instruments, consumables, and services used to detect, monitor, and manage diseases in dogs, cats, and other household pets, employing technologies such as enzyme-linked immunosorbent assay with detection thresholds reaching picogram-per-milliliter sensitivity. The primary commercial purpose centers on enabling rapid clinical decisions that shorten therapeutic pathways and reduce antimicrobial misuse in veterinary practice. Molecular diagnostics now captures the fastest expansion trajectory as PCR-based panels displace culture methods for vector-borne pathogen identification. Imaging systems occupy mature margin pools where hardware replacement cycles and service contracts generate predictable recurring revenue. Wellness screening applications are gaining structural weight as pet insurance penetration pushes preventive care protocols into routine clinic workflows.
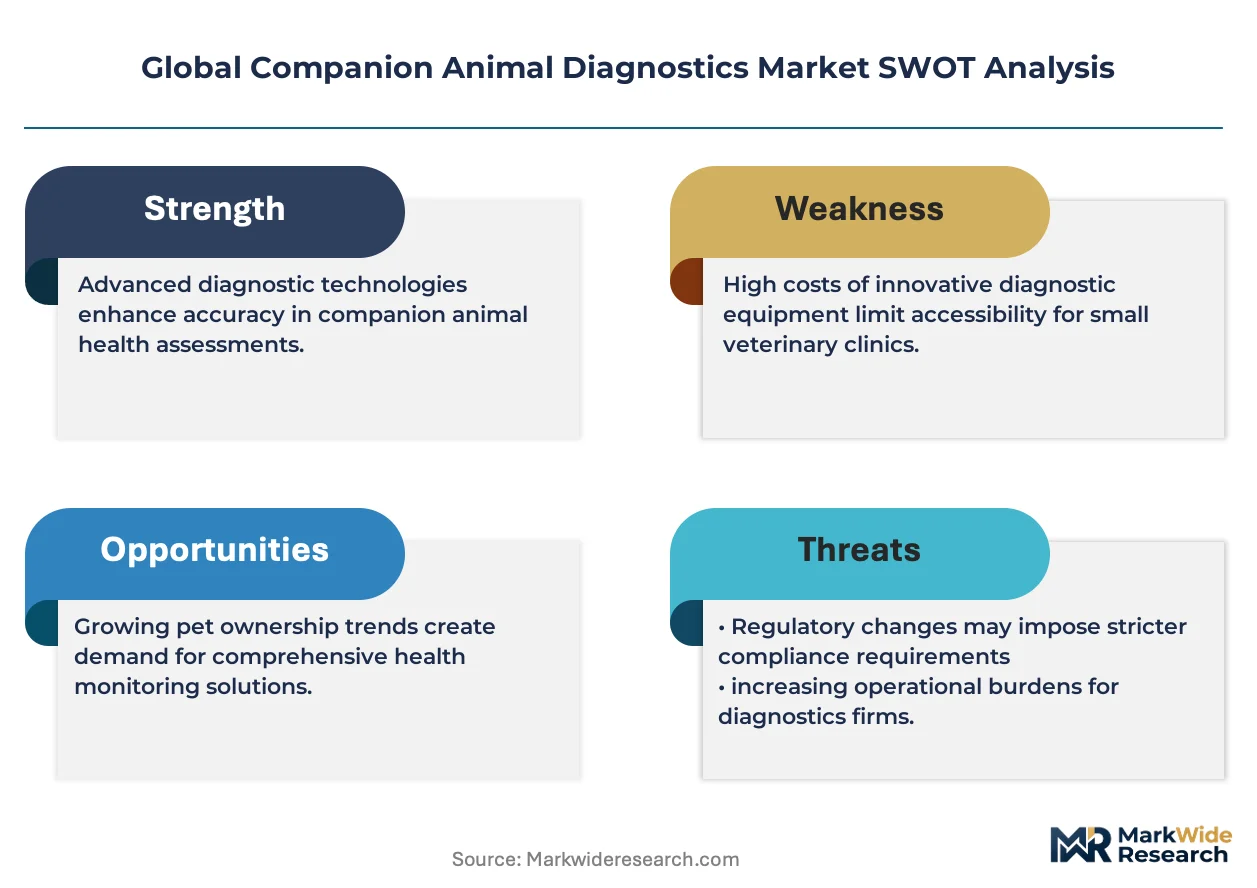
The FDA Center for Veterinary Medicine regulates diagnostic kit accuracy claims and manufacturing quality in the United States, while the EU Veterinary Medicines Regulation and EMA guidelines shape market access requirements across European member states. Japan's Ministry of Agriculture, Forestry and Fisheries enforces import testing standards that foreign manufacturers must satisfy before commercial placement. Stakeholders must monitor how divergent approval timelines between national regulators affect product launch sequencing and regional competitive positioning.
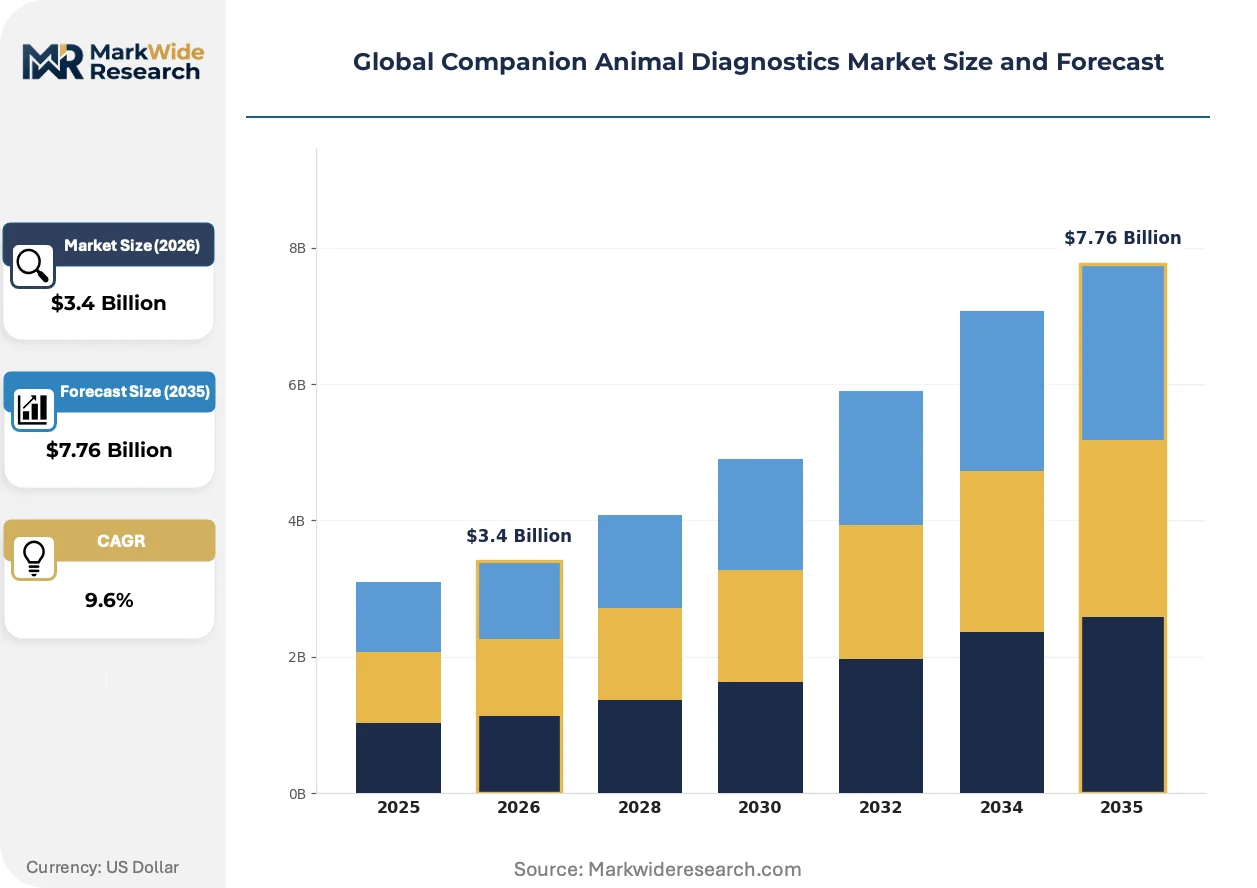
Market Dynamics
Point-of-care PCR miniaturization is compressing diagnostic turnaround times from days to hours, forcing veterinary clinics to reconfigure workflow layouts and staff training protocols around benchtop molecular systems.
Growth Catalysts
- Pet insurance expansion:Rising policy penetration in the United States and Germany is embedding preventive screening protocols into routine clinic visits, generating recurring test volume for wellness panels.
- FDA Center for Veterinary Medicine streamlining:Accelerated review pathways for veterinary diagnostic kits are shortening commercialization timelines for multiplex infectious disease panels.
- Antimicrobial stewardship mandates:Regulatory pressure to reduce empirical antibiotic prescribing is driving adoption of rapid pathogen identification technologies in small animal practice.
Market Restraints
- Reagent supply concentration:Critical PCR enzymes and fluorescent probes rely on a limited supplier base concentrated in the United States and Germany, creating vulnerability to batch inconsistencies.
- Instrument capex burden:Full chemistry analyzer deployments require capital commitments that independent clinics in rural Japan and southern Italy struggle to finance without equipment leasing programs.
- Veterinary pathologist shortage:Histopathology and cytology interpretation bottlenecks limit throughput for oncology and dermatology diagnostic services regardless of instrument availability.
Strategic Opportunities
- Telemedicine-integrated remote monitoring:Home-based sample collection kits paired with digital veterinary consultations are opening channel access for suburban pet owners in Australia and Canada.
- One Health surveillance convergence:Zoonotic pathogen monitoring mandates under WHO guidelines are creating demand for cross-species diagnostic panels that veterinary laboratories can repurpose.
- Subscription-based wellness programs:Preventive care bundles incorporating quarterly screening are penetrating underinsured markets in France and the United Kingdom through employer-sponsored pet benefits.
Industry Challenges
- Cross-platform data interoperability:Proprietary instrument software formats from dominant manufacturers block seamless integration with practice management systems, forcing manual transcription workflows.
- Quality control standardization gaps:Absence of harmonized reference materials for novel biomarker assays complicates inter-laboratory result comparability and clinical validation studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Companion Animal Diagnostics Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.76 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hematology Analyzers, Biochemistry Analyzers, Immunoassay Analyzers, Molecular Diagnostics, Imaging Systems Technology: ELISA, PCR, Flow Cytometry, Ultrasound, Spectrophotometry Application: Disease Diagnosis, Wellness Screening, Nutritional Assessment, Genetic Testing, Infectious Disease Detection End User: Veterinary Clinics, Diagnostic Laboratories, Referral Centers, Research Institutions |
| Companies Covered | IDEXX Laboratories, Zoetis, Neogen Corporation, Thermo Fisher Scientific, Heska Corporation, Virbac, bioMérieux, Randox Laboratories, Antech Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Companion Animal Diagnostics Market Shifts & Advancements
Digital pathology and artificial intelligence classification tools are reconfiguring how veterinary laboratories handle high-volume cytology and histology workflows, compressing specialist interpretation bottlenecks while raising accuracy benchmarks.
CRISPR-based diagnostic platforms are virtualizing infectious disease detection in companion animal practice. These systems enable isothermal amplification without thermal cycling hardware, cutting instrument costs for mobile veterinary units and shelter medicine programs. Field deployment in rural Brazil and Indonesia is accelerating as cold-chain independence eliminates logistics constraints.
EU Veterinary Medicines Regulation implementation is tightening manufacturing quality documentation requirements for diagnostic kit suppliers seeking European Economic Area market access. The regulation's Annex I technical specifications now mandate extended stability validation data that smaller reagent manufacturers struggle to generate. German and Dutch veterinary distributors are consolidating supplier portfolios to reduce compliance audit burdens.
Subscription-based preventive care models are displacing fee-for-service testing in urban United States markets. Corporate veterinary groups in metropolitan Texas and California are bundling quarterly wellness panels with vaccination schedules, locking in predictable reagent consumption while capturing client lifetime value. Independent clinics in the Pacific Northwest are responding with loyalty-program discounts to retain price-sensitive pet owners.
Global Companion Animal Diagnostics Market Segmentation
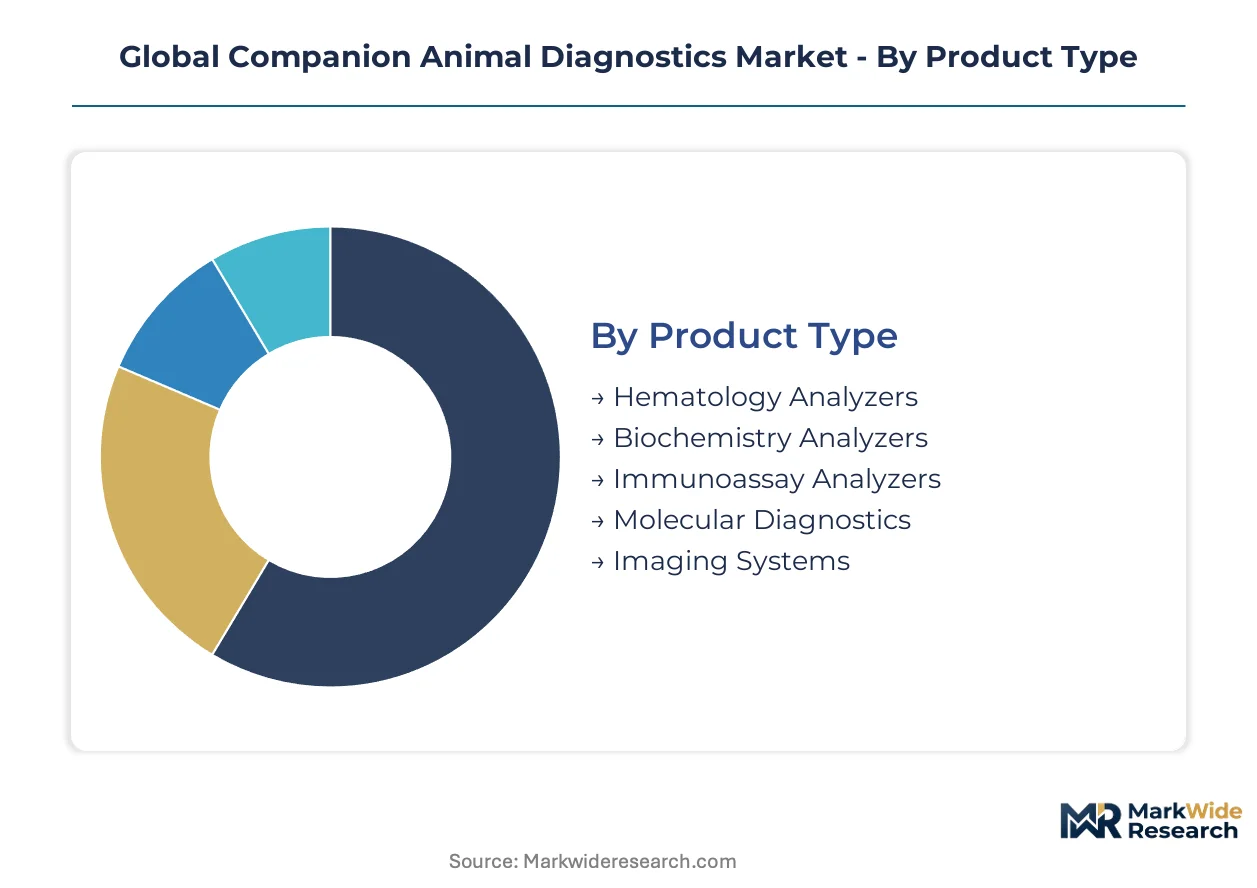
Diagnostic workflows in companion animal practice demand precise alignment between instrument capabilities and clinical decision requirements. Segmentation reveals how technology specialization, end-user infrastructure, and application urgency shape procurement patterns across veterinary settings.
Product Type:
Use-case spectrum spans emergency triage bloodwork to elective genetic screening, with hardware footprints and reagent economics determining placement in high-volume clinics versus mobile practices.
- Hematology Analyzers:Automated cell counters process complete blood counts with five-part differential leukocyte analysis. Demand concentrates in urban United States veterinary groups where high surgical caseloads require rapid pre-anesthetic screening.
- Biochemistry Analyzers:Benchtop systems measure electrolytes, enzymes, and metabolites from serum or plasma samples. German and Japanese clinics prioritize these for chronic disease monitoring in aging pet populations, driving replacement cycles every five to seven years.
- Immunoassay Analyzers:Quantitative hormone and therapeutic drug monitoring platforms.
- Molecular Diagnostics:PCR and isothermal amplification systems for pathogen identification.
- Imaging Systems:Digital radiography and ultrasound hardware with PACS integration.
The dominant share belongs to Biochemistry Analyzers, while Molecular Diagnostics is closing the gap fastest.
Technology:
Cost tier stratification separates capital-intensive platform investments from consumable-heavy assay workflows, with reimbursement patterns influencing adoption sequencing.
- ELISA:Enzyme-linked immunosorbent assays deliver picogram-per-milliliter detection sensitivity for antibody and antigen quantification. Wellness screening programs in France and the United Kingdom embed ELISA-based heartworm and tick-borne disease panels into preventive care bundles.
- PCR:Polymerase chain reaction enables pathogen DNA amplification with species-specific primer design. Point-of-care miniaturization is compressing turnaround times in Australian and Canadian suburban clinics, displacing external laboratory send-outs.
- Flow Cytometry:Laser-based cell sorting for immunophenotyping and leukemia classification.
- Ultrasound:Real-time imaging without ionizing radiation for abdominal and cardiac assessment.
- Spectrophotometry:Light absorption quantification for chemistry panel readouts.
PCR commands the steepest expansion trajectory as benchtop systems penetrate mid-tier clinics, though ELISA retains volume leadership in routine screening.
Application:
Volume concentration varies by pet insurance penetration and regulatory pressure on antimicrobial prescribing, with infectious disease workups generating episodic spikes versus steady wellness panel demand.
- Disease Diagnosis:Acute illness workups encompassing nephrology, hepatology, and endocrine panels. United States emergency and specialty hospitals drive consumption through 24-hour diagnostic capabilities.
- Wellness Screening:Asymptomatic health assessments for early disease detection. German pet insurance mandates are embedding biannual panels into standard care protocols, creating predictable reagent demand.
- Nutritional Assessment:Metabolic profiling for therapeutic diet optimization.
- Genetic Testing:Breed-specific disease predisposition and parentage verification.
- Infectious Disease Detection:Vector-borne and respiratory pathogen identification.
Disease Diagnosis captures the largest procedure volume, yet Wellness Screening is expanding most quickly as preventive care models displace reactive treatment.
End User:
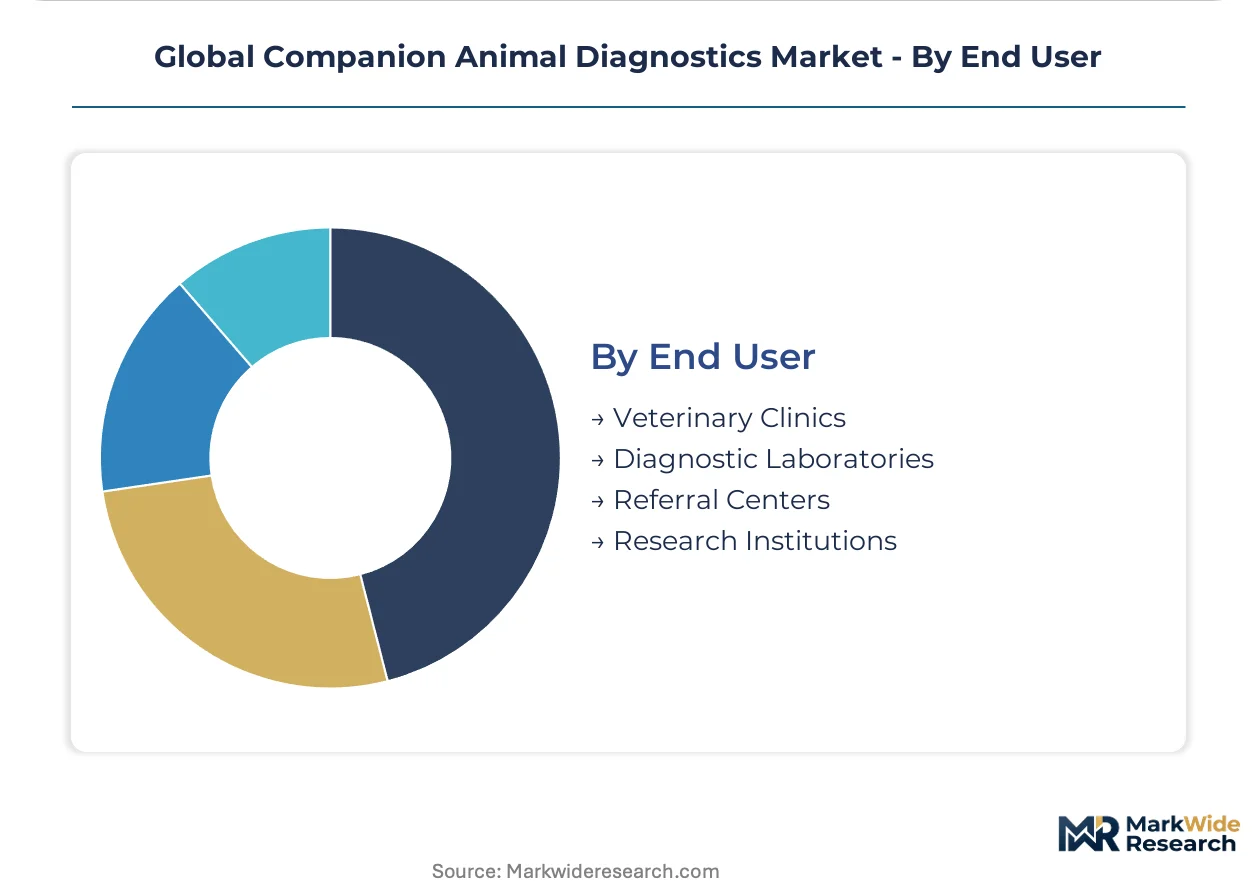
Customer type determines capital availability, with corporate veterinary groups deploying standardized instrument fleets while independent practices prioritize leasing flexibility.
- Veterinary Clinics:Primary care and specialty practices performing in-house diagnostics. Corporate groups in metropolitan Texas and California are standardizing on integrated chemistry-immunoassay platforms to capture client lifetime value through subscription bundles.
- Diagnostic Laboratories:Reference laboratories processing samples from multiple clinic clients. Centralized PCR and histopathology capacity in the United States and Germany absorbs overflow from clinics lacking on-site molecular or pathology expertise.
- Referral Centers:Specialty hospitals with advanced imaging and oncology services.
- Research Institutions:Academic veterinary schools and pharmaceutical development programs.
Veterinary Clinics hold the dominant placement share, though Diagnostic Laboratories are gaining ground fastest as regional reference networks consolidate testing volume from rural practices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Veterinary clinic buyers concentrate in affluent metropolitan zones where pet insurance penetration and disposable income thresholds support in-house diagnostic capital deployment. Corporate veterinary groups in Texas and California drive standardized instrument procurement at scale.
United States
Emergency and specialty hospitals in metropolitan Texas and California generate concentrated demand for 24-hour chemistry and immunoassay capabilities. The FDA Center for Veterinary Medicine regulates diagnostic kit accuracy claims and manufacturing quality standards. Corporate veterinary groups in Dallas-Fort Worth and Los Angeles are standardizing on integrated hardware-software platforms to capture client lifetime value through subscription preventive care bundles.
Germany
Aging pet populations in Bavaria and North Rhine-Westphalia sustain replacement cycles for biochemistry analyzers every five to seven years. The EU Veterinary Medicines Regulation and EMA guidelines shape market access requirements for diagnostic kit suppliers. Veterinary distributors in Munich and Düsseldorf are consolidating supplier portfolios to reduce compliance audit burdens under tightened Annex I technical specifications.
Japan
Chronic disease monitoring protocols in Tokyo and Osaka drive steady reagent consumption for senior companion animals. The Ministry of Agriculture, Forestry and Fisheries enforces import testing standards that foreign manufacturers must satisfy before commercial placement. Independent clinics in rural prefectures struggle to finance full chemistry analyzer deployments without equipment leasing programs.
United Kingdom
Preventive screening applications gain structural weight as pet insurance penetration pushes wellness protocols into routine clinic workflows in London and Southeast England. The country's national veterinary regulator oversees diagnostic service quality standards. Corporate groups in Greater Manchester and Birmingham are bundling quarterly wellness panels with vaccination schedules to lock in predictable reagent consumption.
Australia
Suburban pet owners in Sydney and Melbourne are adopting home-based sample collection kits paired with digital veterinary consultations. The Therapeutic Goods Administration regulates diagnostic device safety and performance standards. Regional reference networks in Queensland and Western Australia are consolidating testing volume from rural practices lacking on-site molecular expertise.
Global Companion Animal Diagnostics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across instrument, consumable, and service segments. The vendor base clusters around three tiers: integrated platform providers dominating North American clinic networks, regional reagent specialists serving European reference laboratories, and emerging point-of-care innovators compressing turnaround times. Dominant competitive moves include strategic partnerships between instrument manufacturers and reference laboratory networks, plus portfolio diversification into subscription-based preventive care bundles.
Within the integrated platform tier, IDEXX Laboratories and Zoetis exemplify archetypes of hardware-software convergence and R&D-intensive immunoassay development respectively. Thermo Fisher Scientific anchors the molecular reagent supply chain position for third-party diagnostic manufacturers. These three entities represent distinct strategic postures: channel control through clinic workflow integration, therapeutic adjacency through pharmaceutical-diagnostic linkage, and upstream supply security through enzyme and probe manufacturing scale.
| Leading Market Players |
|---|
| IDEXX Laboratories |
| Zoetis |
| Neogen Corporation |
| Thermo Fisher Scientific |
| Heska Corporation |
| Virbac |
| bioMérieux |
| Randox Laboratories |
| Antech Diagnostics |
| Others |
Supply & Pricing Matrix
PCR enzyme manufacturing concentrates in the United States and Germany, anchoring margin capture upstream while veterinary clinics downstream face compressed procurement leverage on benchtop molecular systems. This upstream concentration shapes pricing power dynamics across reagent supply tiers and instrument procurement cycles.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate reagent supply agreements between German enzyme manufacturers and North American diagnostic platform vendors. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated assay kits from CE-marked equivalents and unregistered research-use-only products. Pricing pressure stems from corporate veterinary group purchasing consolidation in Texas and California, where standardized fleet procurement squeezes independent distributor margins. Price-sensitive buyers cluster in rural Japanese prefectures and southern Italian provinces, while least-sensitive demand concentrates in United States emergency and specialty hospitals requiring 24-hour turnaround guarantees.
Supply Chain Analysis
Export-control restrictions on thermal cycler components and fluorescent probe chemistries limit technology flows from United States and German suppliers to veterinary diagnostic manufacturers in Asia-Pacific markets. Geographic supply concentration rests on enzyme production in Germany, optical component fabrication in Japan, and plastic consumable molding in China. Critical dependencies include Taq polymerase enzymes, FAM-labeled probes, and precision injection-molded reaction vessels. Single-source vulnerability runs through qualified supplier audits for FDA Center for Veterinary Medicine compliance. Distribution runs through regional veterinary distributors in Munich, Dallas-Fort Worth, and Tokyo who consolidate compliance documentation for clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary pathologist interpretation capacity represents the binding constraint across oncology and dermatology diagnostic workflows, creating scarcity premiums for automated digital pathology platforms and AI-assisted cytology classification tools.
For Market Incumbents: Entrench workflow integration advantages by deepening software-hardware convergence in practice management system connectivity, neutralizing interoperability threats from emerging open-platform entrants. Prioritize captive supply of PCR enzymes through backward integration into German reagent manufacturing or long-term offtake agreements with qualified suppliers, defending against batch inconsistency risks that disrupt clinic service level agreements. For New Entrants and Emerging Players: Build out telemedicine-integrated remote monitoring capabilities targeting suburban pet owners in Australia and Canada, where home-based sample collection kits paired with digital consultations remain underpenetrated relative to United States saturation. Pursue shelter medicine and mobile veterinary units in rural Brazil and Indonesia with CRISPR-based isothermal platforms that eliminate cold-chain dependencies, leveraging go-to-market partnerships with regional animal health NGOs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional reference laboratory networks in Germany and the United Kingdom that have consolidated histopathology capacity but lack molecular diagnostics scale. Long-term viability hinges on 5-10 year pet insurance penetration trajectories embedding preventive screening into routine care protocols. Watch subscription-based wellness program attach rates in metropolitan United States corporate veterinary groups as the inflection signal for recurring revenue model durability.| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Care PCR Miniaturization | Benchtop molecular systems displace external laboratory send-outs in Australian and Canadian suburban clinics. |
| Subscription-Based Wellness Programs | Quarterly screening bundles lock in predictable reagent consumption for corporate groups in Texas and California. |
| Digital Pathology AI Integration | Automated cytology classification compresses veterinary pathologist bottlenecks in United States reference laboratories. |
| CRISPR Diagnostic Platform Deployment | Isothermal amplification eliminates thermal cycling hardware costs for mobile units in rural Brazil and Indonesia. |
| EU Veterinary Medicines Regulation Compliance | Annex I stability validation requirements consolidate supplier portfolios among German and Dutch distributors. |
Research Methodology
Cross-validation between regulatory filing analysis and distributor procurement data anchors the qualitative findings on market access timelines and reagent consumption patterns. Primary interviews with veterinary clinic practice managers, reference laboratory operations directors, diagnostic platform R&D heads, and pet insurance product specialists combined with secondary validation against FDA Center for Veterinary Medicine 510(k) clearances, EU Veterinary Medicines Regulation Annex I technical specifications, and Japanese Ministry of Agriculture import testing standards. Bottom-up instrument placement counts and top-down reagent revenue estimates triangulate market sizing across the analysis window.
Calibration against historical replacement cycles for biochemistry analyzers in German and Japanese clinics informs the projection framework across product type, technology, application, and end-user segments. Modeled dimensions span instrument versus consumable revenue mix, point-of-care versus reference laboratory workflow split, and preventive versus reactive testing indication. CAGRs derive from segmented growth rate blending weighted by base-year revenue contribution. Forecast inputs incorporate pet insurance policy penetration trajectories and antimicrobial stewardship regulatory enforcement intensity.
Stress conditions across PCR reagent supply disruption, veterinary pathologist shortage persistence, and corporate veterinary group consolidation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory approval pathway durations and instrument capital expenditure availability. Material shifts in FDA Center for Veterinary Medicine review timeline acceleration or EU Veterinary Medicines Regulation Annex I stability data requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Creatine Kinase Reagent Market
Diagnostics
Global Stroke Diagnostics Market
Diagnostics
Bilirubin Blood Test Market
Diagnostics
Blood Glucose Testing Devices Market
Diagnostics
Diabetes Testing System Market
Diagnostics
Veterinary Diagnostics Market
Diagnostics
Cryptococcal Antigen Lateral Flow Assay Test Market
Diagnostics
Global Artificial Intelligence (AI) in Diagnostics Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Cushing's Syndrome Diagnostics and Therapeutics Market
Diagnostics
Predictive Disease Analytics Market
Diagnostics
Global Digital Diagnostics Market
Diagnostics
Chile in Vitro Diagnostics Market
Diagnostics
France in-Vitro Diagnostics Market
Diagnostics
Creatinine Test Market
Diagnostics
Hepatitis B Diagnostic Tests Market