
 FISH Probe Market | 2026-2036
FISH Probe Market Size, Share, and Industry Trends Forecast 2026-2036
FISH Probe Market Analysis
CE marking under the EU MDR is hardening the cost-of-entry calculus for FISH probe manufacturers seeking European market access. Thermo Fisher Scientific leverages its vertically integrated reagent-to-instrument ecosystem to sustain compliance economies that smaller competitors cannot match. Agilent Technologies anchors its position through specialized cytogenomics workflows that dominate hospital pathology labs. Abbott Molecular competes by controlling distribution through captive diagnostic platform relationships.
A FISH probe is a fluorescently labeled nucleic acid sequence—typically 10-400 nucleotides in length, conjugated to dyes such as FITC, Texas Red, or Alexa Fluor—designed to hybridize to complementary chromosomal targets for visualization under fluorescence microscopy; its primary purpose is detecting gene amplifications, translocations, or copy number variations in fixed cell preparations. DNA probes dominate current revenue owing to entrenched use in HER2 and ALK testing protocols, while RNA probes represent the fastest-growing category as single-molecule FISH techniques expand into spatial transcriptomics. Cancer diagnostics commands the largest application share, though pathogen detection is gaining traction in antimicrobial resistance surveillance programs.
The FDA regulates FISH probes as either analyte-specific reagents or in vitro diagnostics depending on intended use, creating divergent validation burdens that reshape product development timelines. EMA's MDR transition and Japan's PMDA quality management requirements further fragment the regulatory landscape for multinational suppliers. Stakeholders must monitor evolving companion diagnostic co-labeling mandates and premarket notification pathways that determine which probe formats achieve reimbursable clinical status.
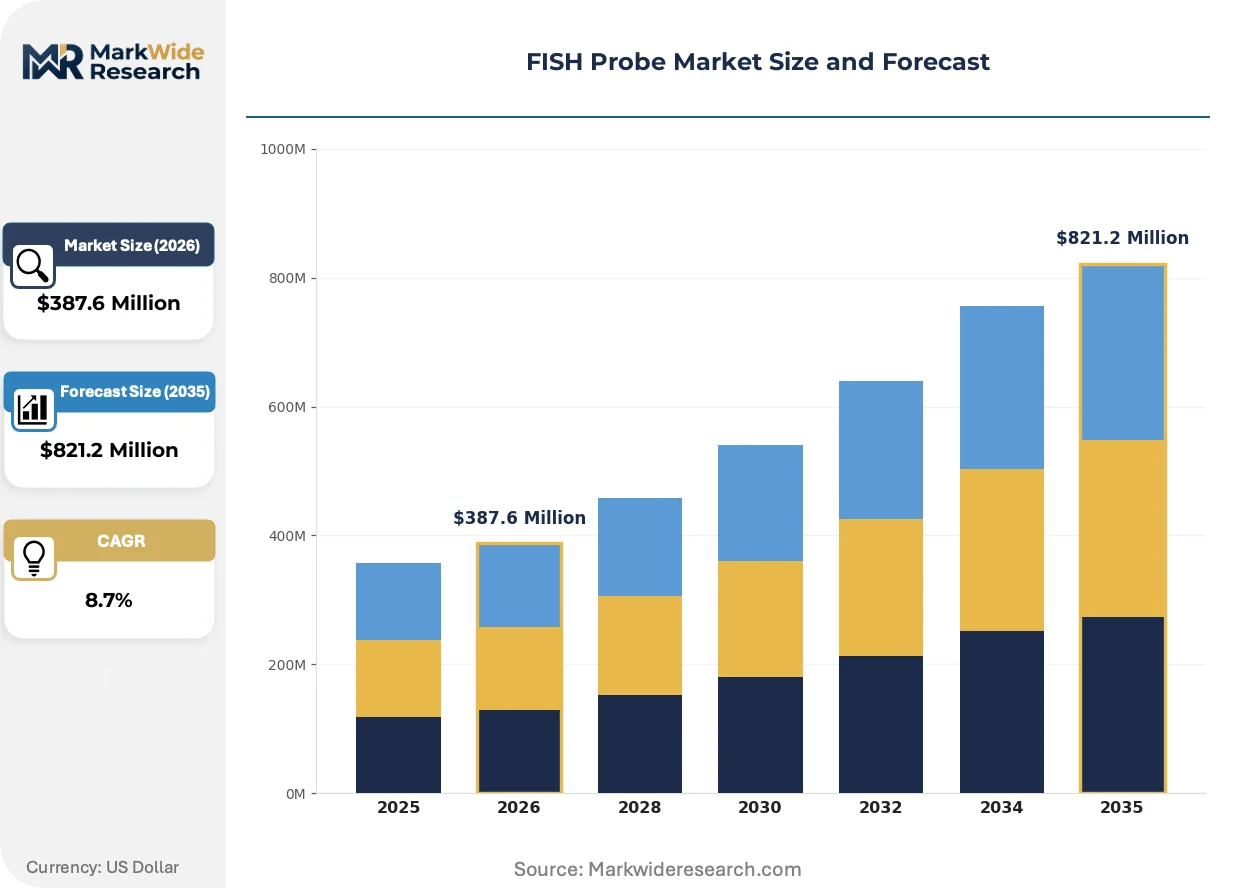
Market Dynamics
FDA companion diagnostic co-labeling mandates are compressing product development timelines while elevating validation costs, forcing manufacturers to restructure R&D priorities around reimbursable clinical pathways rather than research-use-only formats.
Growth Catalysts
- Companion diagnostic mandates:FDA's tightening oversight of oncology therapeutics creates binding demand for validated FISH probes in HER2, ALK, and ROS1 testing protocols across clinical laboratories.
- Spatial transcriptomics expansion:Single-molecule RNA FISH techniques are penetrating neuroscience and developmental biology research, opening adjacent revenue streams beyond traditional cytogenetics.
- Antimicrobial resistance surveillance:Hospital infection control programs are adopting FISH-based pathogen detection for rapid resistance gene identification in bloodstream infections.
Market Restraints
- Fluorophore supply concentration:Specialty dye chemistries for Alexa Fluor and Cy-series conjugates depend on concentrated European and Japanese chemical suppliers, creating input vulnerability.
- MDR compliance burden:CE marking under EU MDR requires expanded clinical evidence and quality management audits that extend European market entry timelines by 18-24 months.
- Optical microscopy saturation:Automated digital pathology platforms with whole-slide imaging capabilities threaten to displace manual fluorescence microscopy in high-throughput screening workflows.
Strategic Opportunities
- Liquid biopsy convergence:Circulating tumor cell FISH protocols are bridging tissue-based and blood-based oncology diagnostics, creating hybrid test formats for treatment monitoring.
- India laboratory buildout:Central government cancer center expansion and private diagnostic chain consolidation are establishing molecular cytogenetics infrastructure in previously underserved metropolitan markets.
- CRISPR-FISH integration:Gene editing validation workflows are incorporating FISH-based off-target analysis, embedding probes into therapeutic development pipelines.
Industry Challenges
- Probe design automation:Computational biologist shortages are constraining bioinformatics pipelines for repeat-masked sequence selection and specificity validation.
- Cross-platform standardization:Variability in hybridization protocols across Thermo Fisher, Agilent, and Abbott instrument ecosystems complicates kit development for multi-platform compatibility.
- Reimbursement coding lag:CPT code updates for novel FISH applications trail clinical adoption by multiple years, compressing margins on innovative test formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FISH Probe Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Probes, RNA Probes, Fluorescent Probes, Molecular Probes Application: Cancer Diagnostics, Genetic Research, Prenatal Testing, Pathogen Detection Technology: Fluorescence In Situ Hybridization, Next-Generation Sequencing, Microarray, PCR End User: Hospitals, Research Institutes, Diagnostic Laboratories, Academic Institutions |
| Companies Covered | Thermo Fisher Scientific Inc., Agilent Technologies, Abbott Molecular Inc., Oxford Gene Technology, Creative Biolabs, Abnova Corporation, F. Hoffmann-La Roche AG, Biosearch Technologies, Genemed Biotechnologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FISH Probe Market Emerging Trajectories
Multiplexed fluorescence imaging architectures are displacing single-target assays across cancer research and diagnostic workflows. Probe chemistry, instrumentation, and computational analysis are converging to enable higher-information-content cellular characterization.
Multiplexed FISH panels with spectrally resolved barcode systems are electrifying tumor microenvironment mapping by enabling simultaneous visualization of ten or more genomic loci. Academic medical centers and pharmaceutical translational groups are adopting these platforms for biomarker discovery cohorts. The technology is compressing study timelines that previously required serial single-probe experiments.
EMA's MDR transition is fragmenting European market access pathways for IVD-classified FISH products. Manufacturers face divergent notified body interpretations of clinical evidence requirements across member states. Smaller suppliers are withdrawing from CE-marked portfolios rather than absorbing compliance costs, concentrating available probe formats among vertically integrated multinationals.
Hospital laboratory consolidation is restructuring procurement around centralized molecular pathology hubs. Independent reference laboratories and health system core facilities are displacing distributed hospital-based testing for complex FISH assays. The United States exhibits the most advanced concentration, with integrated delivery networks negotiating multi-year supply agreements that lock in probe volumes and technical support commitments.
FISH Probe Market Segmentation
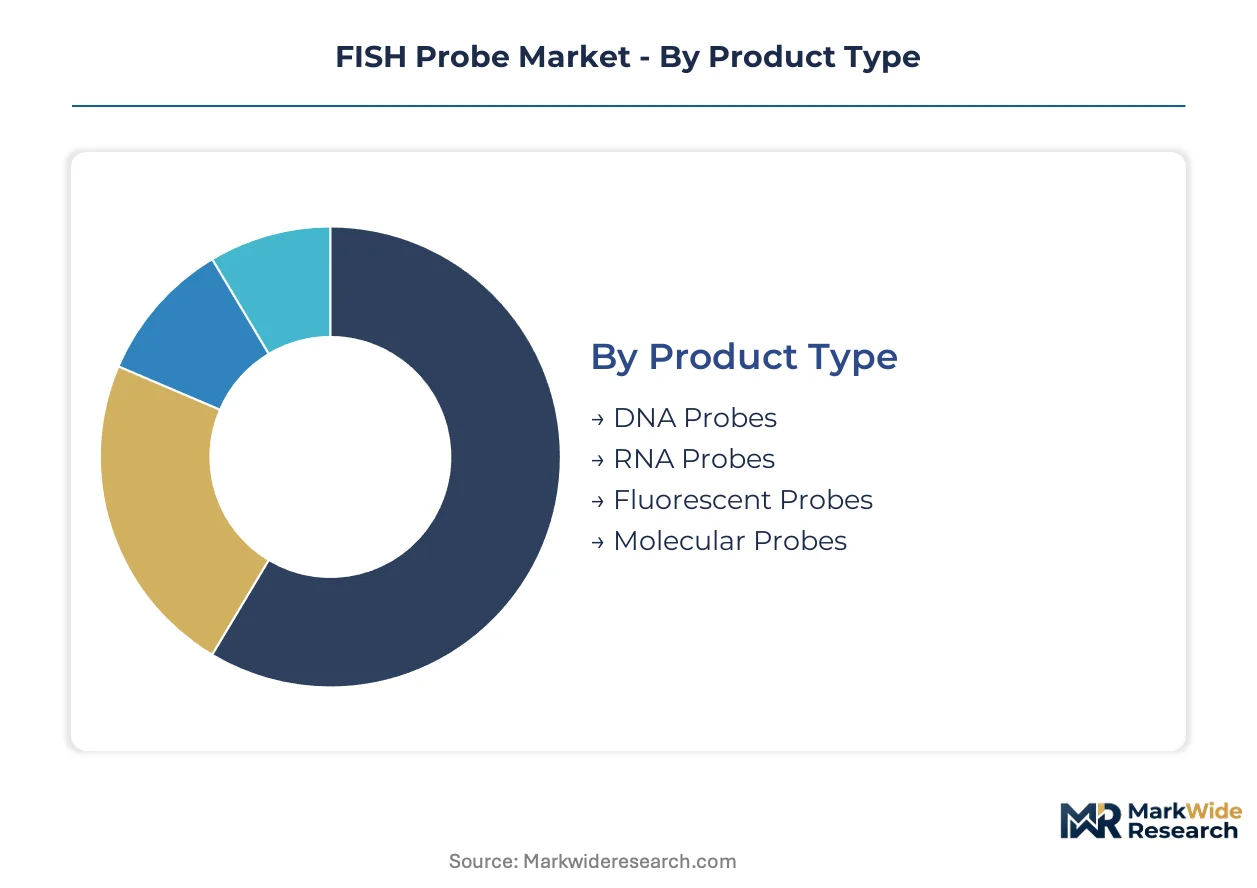
FISH probe segmentation reflects divergent technical specifications across clinical and research environments. Standardization pressures from regulatory bodies clash with customization demands from specialized oncology workflows. Manufacturers navigate this tension through modular probe architectures that accommodate both high-volume diagnostic protocols and bespoke research applications.
Product Type:
Customization intensity varies sharply across this category, with research-grade probes demanding bespoke synthesis while clinical diagnostics favor mass-produced standardized formats.
- DNA Probes:Synthetic oligonucleotides or cloned sequences 10-400 base pairs in length, conjugated to fluorophores for chromosomal target detection. Demand concentrates in United States clinical laboratories running HER2 and ALK companion diagnostic protocols under FDA oversight, where reimbursement pathways for validated assays create binding procurement requirements.
- RNA Probes:Single-stranded nucleic acid sequences designed for transcript-level visualization via single-molecule FISH techniques. Academic medical centers in Germany and Switzerland are adopting these for spatial transcriptomics workflows, driven by EMA-funded precision medicine initiatives requiring subcellular resolution.
- Fluorescent Probes:Dye-conjugated detection reagents optimized for specific microscopy platforms.
- Molecular Probes:Broader reagent category encompassing modified nucleotides and labeling chemistries for hybridization-based assays.
Most installed capacity flows through DNA Probes. Expansion is steepest in RNA Probes.
Application:
Revenue concentration tilts toward high-margin clinical segments, though research applications sustain pricing premiums through customization services.
- Cancer Diagnostics:Solid tumor and hematologic malignancy testing for gene amplification, translocation, and copy number variation detection. United States hospital pathology departments dominate procurement, with integrated delivery networks negotiating multi-year supply agreements that lock in probe volumes.
- Pathogen Detection:Rapid identification of antimicrobial resistance genes in bloodstream infections using species-specific ribosomal RNA targeting. Hospital infection control programs in Japan and South Korea are expanding adoption under PMDA and MFDS quality management frameworks.
- Genetic Research:Cytogenomic studies in model organisms and cell line characterization.
- Prenatal Testing:Aneuploidy screening and microdeletion detection in amniotic fluid or chorionic villus samples.
Cancer Diagnostics commands the dominant revenue share. Pathogen Detection is gaining share fastest.
Technology:
Platform selection determines probe design specifications, with hybridization-based methods requiring distinct chemistries compared to amplification-dependent alternatives.
- Fluorescence In Situ Hybridization:Direct chromosomal visualization through labeled probe hybridization and fluorescence microscopy. Clinical laboratories in the United States, Germany, and Japan represent core demand centers, with FDA, EMA, and PMDA regulatory pathways shaping validation requirements.
- Next-Generation Sequencing:Probe-based target enrichment for massively parallel sequencing workflows. Pharmaceutical translational groups in Switzerland and the United Kingdom are adopting these for biomarker discovery cohorts, embedding FISH validation into therapeutic development pipelines.
- Microarray:High-throughput comparative genomic hybridization using immobilized probe sets.
- PCR:Amplification-based detection with fluorescent probe readout.
Fluorescence In Situ Hybridization retains the largest installed base. Next-Generation Sequencing shows the steepest adoption curve.
End User:
Procurement sophistication varies across institutional types, with consolidated health systems extracting volume discounts unavailable to fragmented academic purchasers.
- Diagnostic Laboratories:Centralized molecular pathology hubs processing high-complexity FISH assays for regional health networks. United States reference laboratories and European hospital core facilities are displacing distributed testing, concentrating probe procurement among fewer buyers with greater negotiating leverage.
- Hospitals:In-house pathology departments with captive diagnostic platforms and direct manufacturer relationships. Academic medical centers in the United States maintain the most advanced infrastructure, with technical support commitments and training services factoring heavily into supplier selection.
- Research Institutes:Basic science and translational research facilities with project-specific probe requirements.
- Academic Institutions:University-affiliated laboratories with grant-dependent purchasing cycles.
Diagnostic Laboratories channel the majority of commercial probe volume. Hospitals represent the fastest-expanding segment through in-house platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cytogeneticists and molecular pathologists concentrate in metropolitan medical centers across four core markets. These talent clusters anchor probe procurement patterns and shape regulatory compliance investments.
United States
Integrated delivery networks in Boston, Houston, and San Diego drive HER2 and ALK companion diagnostic volumes. FDA premarket notification pathways for IVD-classified probes create binding validation timelines that favor established suppliers with regulatory affairs infrastructure. Academic medical centers in the Research Triangle and Bay Area anchor spatial transcriptomics adoption for single-molecule RNA FISH workflows.
Germany
Hospital pathology consolidation in Berlin, Munich, and Hamburg concentrates procurement leverage among fewer buyers. EMA MDR transition requirements and divergent notified body interpretations extend CE marking timelines for IVD probe formats. The Heidelberg-Mannheim medical technology corridor hosts core facilities adopting multiplexed FISH panels for tumor microenvironment mapping.
Japan
PMDA quality management frameworks shape probe validation requirements for hospital infection control programs in Tokyo, Osaka, and Nagoya. Antimicrobial resistance surveillance drives FISH-based pathogen detection adoption in bloodstream infection protocols. The Kobe biomedical cluster anchors translational research bridging cytogenetic diagnostics and therapeutic development pipelines.
India
Central government cancer center expansion in Mumbai, Delhi-NCR, and Bangalore establishes molecular cytogenetics infrastructure in previously underserved markets. CDSCO medical device registration requirements and state-level laboratory accreditation standards reshape import-dependent supply chains. Private diagnostic chain consolidation in Hyderabad and Chennai concentrates probe procurement among regional reference laboratory networks.
Switzerland
Swissmedic oversight of companion diagnostics aligns with EMA frameworks while maintaining distinct quality system requirements. Pharmaceutical translational groups in Basel and Zurich adopt FISH validation for biomarker discovery cohorts. The Lausanne-Geneva life sciences corridor embeds probe suppliers into therapeutic development partnerships with multinational drug developers.
FISH Probe Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered vendor base. Vertically integrated life science toolmakers command compliance economies that smaller competitors cannot match. Three archetypes dominate: captive platform suppliers, modular workflow providers, and research-grade customization shops. Competitive moves center on M&A for regulatory capabilities and strategic partnerships for distribution reach.
Among diversified conglomerates, Thermo Fisher Scientific Inc. and Agilent Technologies exemplify the captive platform archetype, leveraging reagent-to-instrument ecosystems to sustain European MDR compliance costs. Abbott Molecular Inc. occupies a distinct position through diagnostic platform relationships that control distribution channels. F. Hoffmann-La Roche AG represents the pharmaceutical-integrated tier, embedding probe development within companion diagnostic co-labeling mandates.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Agilent Technologies |
| Abbott Molecular Inc. |
| Oxford Gene Technology |
| Creative Biolabs |
| Abnova Corporation |
| F. Hoffmann-La Roche AG |
| Biosearch Technologies |
| Genemed Biotechnologies |
| Others |
Supply Flow & Price Mechanics
IVD-classified probe formats versus research-use-only catalog offerings create a sharp bifurcation in both margin structures and fulfillment architectures across the FISH probe market. FDA-validated companion diagnostic probes command premium pricing through bundled technical support and regulatory documentation, while commoditized DNA oligonucleotides flow through distributor networks with minimal value-added services.
Pricing Analysis
Bundled validation services and unbundled reagent-only transactions split the pricing landscape across clinical and research segments. Three-tier pricing structure across premium, standard, and economy levels aligns with FDA 510(k) clearance status, CE marking under EU MDR, and uncataloged custom synthesis grades. Pricing pressure stems from integrated delivery network consolidation in the United States, where multi-year supply agreements compress margins on high-volume HER2 and ALK testing protocols. Academic research institutes exhibit the highest price sensitivity due to grant-dependent purchasing cycles, while hospital pathology departments prioritize assay reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in Massachusetts, California, and North Carolina anchor hub-and-spoke fulfillment patterns for North American clinical laboratories. Fluorophore chemistries draw from concentrated Japanese and European specialty dye manufacturers, while oligonucleotide synthesis capacity clusters in the United States, Germany, and South Korea. Single-source vulnerability in Alexa Fluor and Cy-series conjugate supply creates exposure to logistics disruptions at Rotterdam and Yokohama ports. Distribution runs through captive platform relationships for Abbott Molecular and Thermo Fisher Scientific instruments, with independent reference laboratories sourcing through authorized distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA companion diagnostic co-labeling mandates compound regulatory complexity into sustainable competitive advantage for validated probe suppliers. The EMA MDR transition elevates compliance costs that filter out undercapitalized competitors.
For Market Incumbents: Deploy regulatory affairs infrastructure as a moat-building mechanism. Thermo Fisher Scientific and Agilent Technologies should deepen captive instrument-probe ecosystems to lock in hospital pathology platform commitments. Consolidate technical support capabilities around multiplexed FISH panel launches before digital pathology platforms displace manual fluorescence microscopy workflows. Cross-platform standardization investments will defend against modular workflow competitors. For New Entrants and Emerging Players: CDSCO medical device registration in India opens a window for import-substitution strategies in Mumbai and Delhi-NCR cancer center buildouts. Target antimicrobial resistance surveillance applications in Japanese hospital infection control programs where PMDA quality frameworks favor specialized probe formats over commoditized alternatives. Partner with regional reference laboratory networks for co-development of liquid biopsy FISH protocols. For Investors and Strategic Acquirers: Consolidation pressure builds where MDR compliance costs exceed revenue thresholds for sub-scale European probe portfolios. Mid-tier customization shops with proprietary repeat-masked sequence libraries represent attractive acquisition targets for platform companies seeking spatial transcriptomics capabilities. Watch for FDA premarket notification backlog clearance rates as an inflection indicator for companion diagnostic pipeline velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR transition extends market access timelines for IVD-classified FISH products. |
| Hospital System Partnership | Integrated delivery networks in Boston and Houston lock in multi-year probe volumes. |
| Software Companion Development | Computational analysis modules for multiplexed barcode systems enable tumor microenvironment mapping. |
| Reimbursement Strategy | CPT code alignment for novel FISH applications determines commercial viability of innovative test formats. |
| Regulatory Approval Pathway | FDA 510(k) clearance for HER2 and ALK companion diagnostics creates binding procurement requirements. |
Methodological Framework
Bottom-up clinical laboratory procurement modeling reconciled against top-down reagent manufacturer shipment tracking forms the analytical core of this study. Primary interviews with molecular pathologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement schedules, and hospital procurement records. Triangulation between demand-side utilization patterns and supply-side production capacity ensures consistency across volume and value estimates.
Input-output matrices map probe chemistry inputs through hybridization protocol outputs across the projection horizon. Segmentation dimensions include product type, application, technology platform, and end-user institutional category, with regional regulatory cluster as an additional modeling layer. CAGRs derive from fitted growth curves anchored to installed base expansion and replacement cycle timing. Forecast inputs incorporate companion diagnostic approval velocity and spatial transcriptomics adoption rates in academic medical centers.
Revisions become necessary when FDA premarket notification timelines extend materially, EU MDR notified body capacity constraints intensify, or digital pathology platform displacement accelerates beyond modeled assumptions. Forecasts reflect documented assumptions regarding reimbursement pathway stability and fluorophore supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Hepatitis E Diagnostic Tests Market
Diagnostics
Italy in Vitro Diagnostics Market
Diagnostics
US Prostate Cancer Nuclear Medicine Diagnostics Market
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market
Diagnostics
H. Pylori Breath Test Kit Market
Diagnostics
In Vitro Diagnostics Test Kit Market
Diagnostics
Infectious Disease Point-Of-Care (POC) Diagnostics Market
Diagnostics
Bilirubin Blood Test Market
Diagnostics
Global Artificial Intelligence (AI) in Diagnostics Market
Diagnostics
Europe Colorectal Cancer Diagnostics Market
Diagnostics
India in-Vitro Diagnostics Market
Diagnostics
Middle East and Africa in-Vitro Diagnostics Market
Diagnostics
Global Saliva Collection and Diagnosis Market
Diagnostics
United States Melanoma Diagnostics & Therapeutics Market
Diagnostics
Thyroid Cancer Diagnostics Market
Diagnostics
Rapid Plasma Reagin Test Market