
 Blood Urea Nitrogen Diagnostics Market | 2026-2036
Blood Urea Nitrogen Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Urea Nitrogen Diagnostics Market Outlook
CLIA laboratory certification is unwinding the competitive landscape for BUN diagnostics, raising barriers for new entrants while favoring incumbents with established quality management systems. Siemens Healthineers leverages its automated analyzer portfolio to dominate high-throughput hospital laboratories. Roche Diagnostics sustains competitive positioning through integrated reagent-analyzer ecosystems that lock in recurring consumable demand.
Blood urea nitrogen diagnostics measure nitrogen in the blood derived from urea, a waste product of protein metabolism filtered by the kidneys, with clinical thresholds typically reported in mg/dL for renal function assessment. Laboratory analyzers process serum or plasma samples using enzymatic or conductivity-based detection methods, while portable and point-of-care devices enable rapid creatinine-BUN ratio calculations at the bedside. Test kits and reagents generate the most stable recurring revenue streams as consumables tied to installed instrument bases, whereas point-of-care testing represents the fastest-expanding delivery mode driven by emergency department throughput pressures and ambulatory surgery center decentralization.
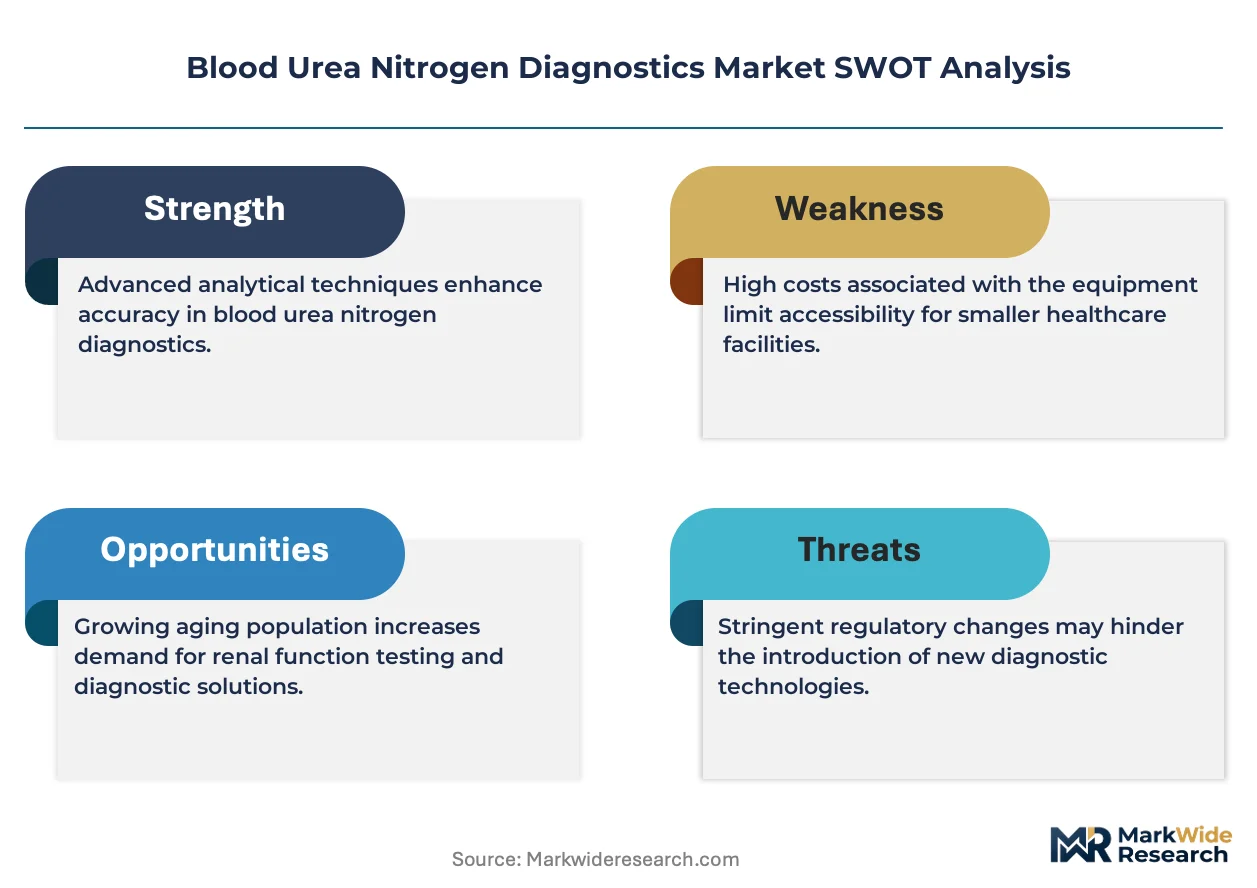
FDA premarket notification requirements for new diagnostic platforms shape product development timelines and clinical validation costs in the United States, while the EU In Vitro Diagnostic Regulation imposes stricter performance scrutiny and post-market surveillance obligations on manufacturers seeking CE marking. CLIA, CAP, and ISO 15189 accreditation frameworks collectively determine which laboratories can offer reimbursable BUN testing, directly constraining addressable end-user expansion. Stakeholders must weigh automated platform consolidation against point-of-care decentralization strategies as reimbursement pathways diverge across care settings.
Market Dynamics
Automated analyzer consolidation in hospital laboratories is compressing vendor margins while CLIA certification barriers protect incumbent positions. Siemens Healthineers and Roche Diagnostics lock in consumable demand through integrated reagent-analyzer ecosystems that raise switching costs for laboratory buyers.
Growth Catalysts
- Emergency department throughput mandates:Bedside BUN-creatinine ratio testing accelerates triage decisions in US trauma centers facing capacity constraints.
- CLIA laboratory certification tightening:Quality management requirements favor established diagnostic platforms with proven compliance track records.
- Enzymatic detection methods:Next-generation reagent chemistries reduce interference from hemolysis and lipemia in high-volume processing.
Market Restraints
- Reagent supply concentration:Three specialty chemical suppliers dominate enzyme substrate manufacturing for BUN test kits.
- FDA premarket notification timelines:Clinical validation requirements extend new platform development cycles by 18-24 months.
- Point-of-care reimbursement compression:CMS fee schedule adjustments reduce margin capture for decentralized testing modalities.
Strategic Opportunities
- Ambulatory surgery center expansion:Pre-operative renal function screening demand outpaces hospital laboratory capacity in Texas and Florida markets.
- EU In Vitro Diagnostic Regulation performance scrutiny:Stricter CE marking requirements create first-mover advantage for manufacturers with robust post-market surveillance systems.
- AI-assisted result interpretation:Machine learning integration with automated analyzers enables predictive acute kidney injury flagging.
Industry Challenges
- ISO 15189 accreditation timelines:Documentation and proficiency testing requirements delay new laboratory market entry.
- Legacy analyzer integration complexity:Middleware compatibility issues obstruct seamless connectivity between point-of-care devices and hospital information systems.
- Specialized clinical laboratory scientist shortages:Workforce gaps in automated platform operation constrain testing volume expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Urea Nitrogen Diagnostics Market |
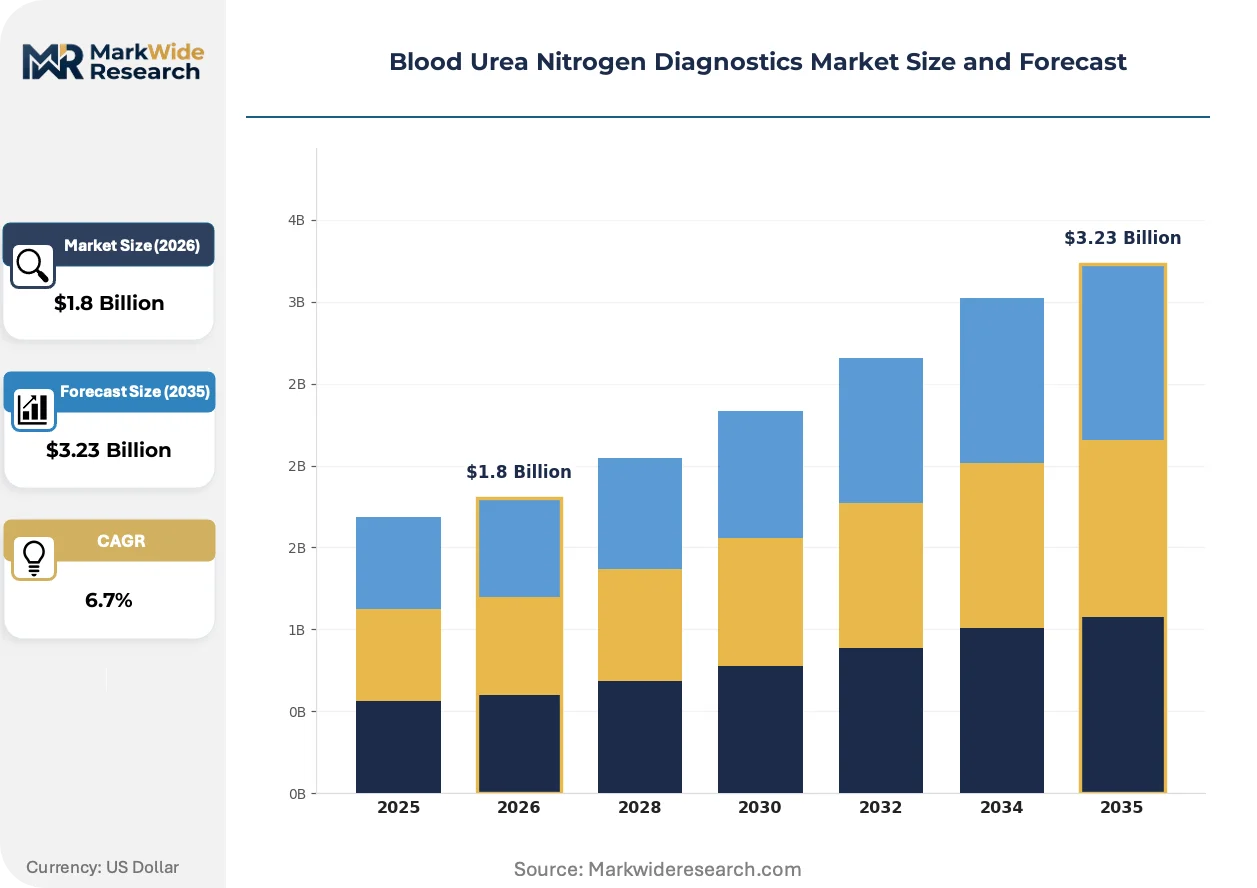
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Reagents, Laboratory Analyzers, Test Kits End User: Hospitals, Clinics, Diagnostic Laboratories, Home Care Settings Delivery Mode: Manual Testing, Automated Testing, Point-of-Care Testing, Centralized Testing Application: Chronic Kidney Disease, Diabetes Management, Hypertension Monitoring, Routine Health Checkups |
| Companies Covered | Roche Diagnostics, Siemens Healthineers, Abbott Laboratories, Beckman Coulter, Thermo Fisher Scientific, Sysmex Corporation, Danaher Corporation, Bio-Rad Laboratories, Mindray Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Urea Nitrogen Diagnostics Market Strategic Shifts
Diagnostic platform architecture is bifurcating between high-throughput centralized automation and distributed point-of-care miniaturization. This divergence reshapes vendor R&D allocation and go-to-market strategies across hospital, ambulatory, and home settings.
Microfluidic cartridge technology is fragmenting the traditional laboratory analyzer market. Disposable polymer chips integrate sample preparation, enzymatic reaction, and optical detection in palm-sized formats. Urgent care networks in Germany and Japan deploy these systems for same-visit renal function assessment. The technology compresses capital equipment sales while expanding recurring consumable revenue per test.
The EU In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for BUN test kit CE marking. Manufacturers must demonstrate analytical performance against reference methods and maintain post-market surveillance registries. German notified bodies prioritize submissions from vendors with established quality management systems, delaying market access for smaller competitors.
Hospital procurement committees now bundle chemistry panel contracts across multiple analytes including BUN, creatinine, and electrolytes. Integrated reagent supply agreements displace standalone test kit purchasing. This consolidation concentrates vendor selection authority within US health system supply chain offices, compressing price negotiation leverage for specialized BUN reagent suppliers.
Blood Urea Nitrogen Diagnostics Market Segmentation
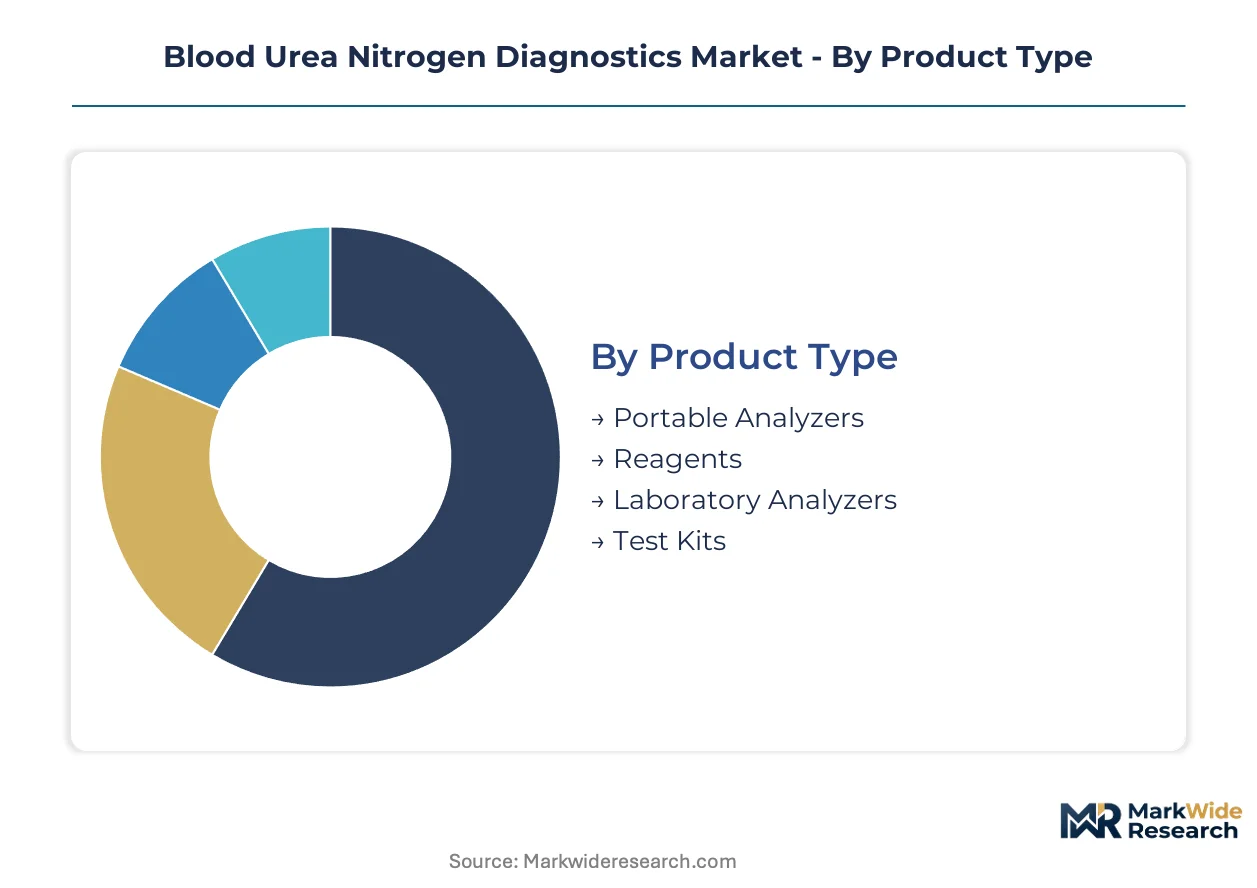
Blood urea nitrogen diagnostics fragment across four dimensions that reshape vendor go-to-market economics. Product type and delivery mode determine capital intensity and recurring revenue mix, while end-user concentration and application specificity dictate regulatory compliance burdens and reimbursement pathways.
Product Type:
Margin pools concentrate in consumable reagents and test kits where installed instrument bases lock in recurring demand, while analyzer hardware competes on capital efficiency and throughput specifications.
- Reagents:Enzymatic substrate formulations drive recurring revenue per test in high-volume hospital laboratories. Demand clusters in Siemens Healthineers and Roche Diagnostics integrated ecosystems across Germany, Japan, and the United States, where CLIA certification requirements protect incumbent supply positions.
- Test Kits:Disposable cartridge systems bundle sample preparation and detection chemistry for decentralized deployment. Urgent care networks in Texas and Florida markets absorb volume as ambulatory surgery center expansion outpaces hospital laboratory capacity.
- Laboratory Analyzers:High-throughput platforms process serum and plasma samples using conductivity-based or enzymatic detection methods.
- Portable Analyzers:Palm-sized devices enable bedside creatinine-BUN ratio calculations in emergency department triage settings.
The dominant share belongs to Reagents, while Test Kits are closing the gap fastest.
End User:
Procurement authority concentrates in hospital supply chain offices and diagnostic laboratory networks, compressing price negotiation leverage for specialized vendors while fragmenting access in decentralized care settings.
- Diagnostic Laboratories:CLIA-certified reference laboratories process bulk chemistry panels including BUN, creatinine, and electrolytes under bundled contracts. Automated platform consolidation in the United States, Germany, and Japan favors vendors with established quality management systems.
- Hospitals:Centralized testing platforms anchor renal function assessment in acute care settings. Procurement committees bundle multi-analyte chemistry contracts, displacing standalone BUN reagent purchasing.
- Clinics:Physician office laboratories face ISO 15189 accreditation timelines that delay market entry for new testing capacity.
- Home Care Settings:Patient-operated devices for chronic kidney disease monitoring remain underpenetrated due to reimbursement pathway fragmentation.
Diagnostic Laboratories command the largest volume position, though Hospitals retain pricing power through contract consolidation.
Delivery Mode:
Technology architecture bifurcates between high-throughput automation and distributed miniaturization, fragmenting vendor R&D allocation and capital deployment strategies.
- Automated Testing:Conveyor-based analyzer systems integrate sample handling, reagent dispensing, and optical detection for continuous processing. Hospital laboratories across Germany and the United States deploy these platforms under multi-year reagent supply agreements.
- Point-of-Care Testing:Microfluidic cartridge technology compresses capital equipment sales while expanding consumable revenue per test. Urgent care networks in Japan deploy palm-sized systems for same-visit renal function assessment.
- Centralized Testing:Reference laboratory hubs aggregate samples from satellite collection sites for batch processing.
- Manual Testing:Benchtop spectrophotometric methods persist in resource-constrained settings with limited automation infrastructure.
Automated Testing retains installed base dominance, yet Point-of-Care Testing is gaining share fastest through emergency department throughput mandates.
Application:
Clinical utility concentrates in chronic disease management where reimbursement codes align with longitudinal monitoring, while routine screening faces margin compression from preventive care bundling.
- Chronic Kidney Disease:Serial BUN-creatinine ratio monitoring tracks disease progression and dialysis timing. Medicare reimbursement pathways in the United States support frequent testing intervals for stage 3-5 patients.
- Diabetes Management:Renal function surveillance integrates with glycemic control protocols in endocrinology practices. Microalbuminuria screening bundles drive chemistry panel demand in Germany and Japan.
- Hypertension Monitoring:ACE inhibitor and ARB therapy adjustments require periodic renal function verification.
- Routine Health Checkups:Annual physical examinations include BUN as standard chemistry panel component.
Chronic Kidney Disease anchors revenue concentration, while Diabetes Management is climbing the fastest on comorbidity screening expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CLIA certification tightening in the United States and EU In Vitro Diagnostic Regulation implementation are redrawing competitive boundaries across major diagnostic markets. Hospital procurement consolidation and point-of-care decentralization create divergent growth trajectories by geography.
United States
Emergency department throughput mandates drive bedside BUN-creatinine testing adoption in trauma centers facing capacity constraints. FDA premarket notification requirements extend new platform development cycles by 18-24 months, favoring incumbents with established 510(k) pathways. Texas and Florida ambulatory surgery centers absorb expanding pre-operative renal screening volume as hospital laboratory capacity saturates.
Germany
Reference laboratory automation investment concentrates in Bavaria and North Rhine-Westphalia under bundled multi-analyte chemistry contracts. German notified bodies prioritize EU In Vitro Diagnostic Regulation submissions from vendors with established quality management systems, delaying smaller competitor market access. Urgent care networks deploy microfluidic cartridge systems for same-visit renal function assessment in metropolitan clusters.
Japan
Hospital-based centralized testing platforms anchor renal function assessment in acute care settings across Kanto and Kansai regions. METI industrial policy supports diagnostic platform export competitiveness through precision manufacturing subsidies. Palm-sized point-of-care systems penetrate urgent care networks in Tokyo and Osaka metro areas for rapid triage decisions.
China
Domestic analyzer manufacturers capture share in tier-two and tier-three city hospital laboratories under NMPA accelerated review pathways for innovative devices. Dual carbon goals drive energy-efficient automated platform adoption in provincial medical center expansions. Yangtze River Delta diagnostic reagent production clusters supply enzymatic substrate formulations for regional test kit assembly.
India
Chronic kidney disease screening expansion targets diabetes-hypertension comorbidity corridors in Maharashtra and Tamil Nadu under national non-communicable disease programs. CDSCO medical device rules impose clinical validation requirements on imported analyzer platforms, creating regulatory lag for multinational entrants. Diagnostic laboratory chains in Bengaluru and Hyderabad deploy automated chemistry panels for outpatient renal monitoring.
Blood Urea Nitrogen Diagnostics Market Competitive Environment
Player mix skews toward integrated diagnostic conglomerates with automated analyzer-reagent ecosystems and point-of-care specialists with microfluidic cartridge platforms. Siemens Healthineers and Roche Diagnostics lock in consumable demand through multi-year supply agreements that raise laboratory switching costs. Three strategic archetypes dominate: high-throughput automation incumbents, decentralized testing specialists, and reagent chemistry suppliers. Competitive moves concentrate on analyzer-reagent bundle consolidation and point-of-care geographic expansion.
Within the integrated diagnostics tier, Siemens Healthineers and Roche Diagnostics occupy positions as anchor vendors for hospital laboratory automation. Abbott Laboratories exemplifies the point-of-care specialist archetype with decentralized testing platform deployment. Beckman Coulter sits within the reference laboratory automation segment. These three companies collectively represent the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Siemens Healthineers |
| Abbott Laboratories |
| Beckman Coulter |
| Thermo Fisher Scientific |
| Sysmex Corporation |
| Danaher Corporation |
| Bio-Rad Laboratories |
| Mindray Medical |
| Others |
Value Chain & Pricing Dynamics
High-throughput analyzer installed bases in Germany, Japan, and the United States generate scale economies that compress per-test reagent costs while elevating price floors for CLIA-certified laboratory buyers. This concentration of automated platform capacity simultaneously locks in consumable demand for incumbent vendors and raises switching costs that protect margin structures across the diagnostics value chain.
Pricing Analysis
Certification level (CLIA/CAP/ISO 15189-grade) creates the primary spread between premium and standard tier positioning in hospital laboratory procurement. Three-tier pricing structure across premium, standard, and economy levels reflects analyzer-reagent bundle consolidation, with integrated ecosystems commanding loyalty premiums from high-volume reference laboratories. Cost compression in point-of-care modalities is intensifying because CMS fee schedule adjustments reduce margin capture for decentralized testing. Physician office laboratories and urgent care networks exhibit highest price sensitivity due to reimbursement pathway fragmentation, while academic medical centers demonstrate lowest sensitivity given bundled chemistry panel contracting authority.
Supply Chain Analysis
Enzyme substrate inventory cycles extend 12-16 weeks for specialty chemical inputs, constraining just-in-time reagent manufacturing flexibility for test kit assemblers. Manufacturing concentration clusters in Germany, the United States, and China, with Yangtze River Delta production hubs supplying enzymatic formulations for regional cartridge assembly. The supply chain rests on purified enzyme substrates, polymer microfluidic substrates, and optical detection components as critical inputs. Single-source vulnerability concentrates in three specialty chemical suppliers dominating enzyme substrate manufacturing. Distribution runs through health system supply chain offices and diagnostic laboratory networks, with GPO contracts consolidating vendor selection authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care testing penetration in ambulatory surgery centers and urgent care networks signals early-cycle expansion, with emergency department throughput mandates accelerating bedside BUN-creatinine adoption ahead of traditional laboratory capacity constraints.
For Market Incumbents: Fortify analyzer-reagent ecosystem lock-in through multi-year CLIA-certified laboratory supply agreements that raise switching costs for hospital procurement committees. Deepen backward integration into enzyme substrate manufacturing to reduce exposure to the three-dominant-supplier concentration risk in specialty chemical inputs. Prioritize middleware compatibility investments to obstruct seamless connectivity between emerging point-of-care devices and hospital information systems. For New Entrants and Emerging Players: Service-layer gaps in AI-assisted result interpretation and predictive acute kidney injury flagging present white-space opportunities where Siemens Healthineers and Roche Diagnostics under-serve mid-tier hospital laboratories. Texas and Florida ambulatory surgery centers represent the most penetrable geography given pre-operative renal screening demand outpacing hospital laboratory capacity. Pursue microfluidic cartridge platform partnerships with urgent care networks as the primary go-to-market angle, emphasizing same-visit turnaround value against centralized testing delays. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors point-of-care specialists with palm-sized microfluidic platforms over mature centralized automation incumbents. Long-term viability hinges on regulatory pathway execution across FDA premarket notification and EU In Vitro Diagnostic Regulation CE marking timelines. Target acquisition archetypes include microfluidic cartridge developers with established German notified body relationships. Watch for inflection signal in CMS point-of-care reimbursement pathway stabilization that would validate decentralized testing economics.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Certification Investment | Quality management system accreditation protects incumbent reagent supply positions in United States hospital laboratories. |
| Microfluidic Platform Launch | Palm-sized cartridge systems penetrate urgent care networks in Germany and Japan for same-visit renal assessment. |
| EU IVDR CE Marking Pathway | Stricter performance scrutiny creates first-mover advantage for manufacturers with robust post-market surveillance infrastructure. |
| Hospital System Partnership | Bundled multi-analyte chemistry contracts displace standalone BUN reagent purchasing in United States health systems. |
| AI Companion Development | Machine learning integration enables predictive acute kidney injury flagging on automated analyzer platforms. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital laboratory directors, diagnostic reagent procurement managers, CLIA compliance officers, and point-of-care device engineers. Secondary validation drew from FDA 510(k) premarket notification databases, CMS Medicare fee schedule filings, EU In Vitro Diagnostic Regulation implementation guidance, and hospital GPO contract repositories. Bottom-up instrument installation counts and top-down chemistry panel revenue estimates were triangulated to anchor market sizing.
Across the analysis window, forecasting employed segmented modeling by product type, delivery mode, end user, and application with geographic regulatory clusters as an overlay dimension. CAGRs were derived from installed base expansion trajectories, consumable pull-through rates per analyzer, and point-of-care penetration curves. Industry-specific inputs included CLIA laboratory certification timelines, enzymatic detection method adoption rates, and ambulatory surgery center capacity expansion patterns in target states.
Underlying assumptions cover stable CLIA enforcement intensity and EU IVDR notified body processing capacity, with deviation risk concentrated in CMS reimbursement pathway adjustments and enzyme substrate supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
United States Melanoma Diagnostics & Therapeutics Market
Diagnostics
Febrile Antigen Kits Market
Diagnostics
In Vitro Diagnostic Substrate Market
Diagnostics
Global Lateral Flow Assay Market
Diagnostics
Japan in-Vitro Diagnostics Market
Diagnostics
HIV Diagnostics Market
Diagnostics
Europe Colorectal Cancer Diagnostics Market
Diagnostics
Infectious Disease in Vitro Diagnostics Market
Diagnostics
Global Stroke Diagnostics Market
Diagnostics
Heart Attack Diagnostics Market
Diagnostics
In Vitro Diagnostics (IVD) Quality Control Market
Diagnostics
Global RSV Diagnostics Market
Diagnostics
Middle East and Africa Syndromic Multiplex Diagnostic Market
Diagnostics
Global Saliva Collection and Diagnosis Market
Diagnostics
Global Hemoglobin A1c Testing Devices Market
Diagnostics
Anatomic Pathology Market