
 Glaucoma Diagnostics Market | 2026-2036
Glaucoma Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Glaucoma Diagnostics Market Foresight
Artificial intelligence integration into retinal imaging workflows is reshaping how glaucoma diagnostics are delivered across care settings. Carl Zeiss Meditec leverages its established OCT platform to anchor premium positioning in academic medical centers. Heidelberg Engineering competes through specialized confocal scanning technology for corneal nerve assessment. NIDEK sustains manufacturing scale across Asia-Pacific distribution channels.
Glaucoma diagnostics encompass instruments and software systems that measure intraocular pressure, map retinal nerve fiber layer thickness, and quantify visual field loss to detect progressive optic neuropathy before functional vision impairment occurs. Optical coherence tomography systems dominate installed bases due to sub-micron axial resolution and automated progression analysis, while visual field analyzers retain essential status for functional staging despite longer test durations. Perimetry technology leads in disease monitoring applications where longitudinal sensitivity data guides treatment escalation, and early detection programs increasingly deploy fundus cameras with AI overlay for population-scale screening.
FDA premarket notification requirements for Class II ophthalmic devices shape product development timelines and clinical evidence standards, while the EU MDR's tightened conformity assessment for active implantable and software-driven diagnostics extends certification cycles for European market entry. ISO 10993 biocompatibility testing and IEC 60601 electrical safety standards govern hardware design across all regulated jurisdictions. Stakeholders must weigh regulatory capital requirements against the margin structure of subscription-based AI diagnostic software as reimbursement models fragment across public and private payers.
Market Dynamics
AI-enabled diagnostic software is compressing the traditional hardware-software value stack, forcing incumbent OCT manufacturers to restructure pricing models and accelerate regulatory submissions for algorithm-based screening tools.
Growth Catalysts
- AI Screening Mandates:Public health programs in South Korea and Singapore now fund population-scale glaucoma detection using automated fundus analysis, expanding addressable patient pools beyond specialty clinics.
- MDR Streamlining:The EU's Medical Device Regulation has clarified software-as-a-medical-device pathways, reducing certification uncertainty for European ophthalmic AI developers seeking CE marking.
- Optic Nerve Biomarker Validation:Multi-center longitudinal studies establishing retinal nerve fiber layer thickness as a surrogate endpoint are accelerating payer acceptance of OCT-based monitoring protocols.
Market Restraints
- Capital Equipment Intensity:High-resolution spectral-domain OCT systems require substantial upfront investment, constraining deployment in resource-limited settings and smaller private practices.
- Supply Concentration:Superluminescent diode and swept-source laser component manufacturing concentrates in Japanese and German optical suppliers, creating vulnerability to regional production disruptions.
- Visual Field Test Duration:Standard automated perimetry requires 15-20 minutes per eye, limiting throughput in high-volume screening environments despite its functional staging utility.
Strategic Opportunities
- Teleophthalmology Networks:Rural India and sub-Saharan Africa present substantial underpenetrated demand for portable tonometer and fundus camera combinations with cloud-based specialist interpretation.
- Convergence of OCT-A and AI:Integration of optical coherence tomography angiography with deep learning vascular quantification is opening microcirculation assessment applications beyond traditional structural imaging.
- US Reimbursement Expansion:Medicare's coverage determinations for remote patient monitoring create financial pathways for home-based intraocular pressure tracking devices.
Industry Challenges
- Algorithm Validation Burden:FDA premarket submissions for AI diagnostic tools require extensive multi-site clinical performance data, extending development timelines and consuming technical resources.
- Interoperability Friction:Legacy hospital information systems and picture archiving platforms lack standardized interfaces for seamless AI overlay integration, forcing custom engineering work.
- Specialist Workforce Constraints:Glaucoma fellowship-trained ophthalmologists concentrate in urban academic centers, creating interpretation bottlenecks for community-based screening programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glaucoma Diagnostics Market |
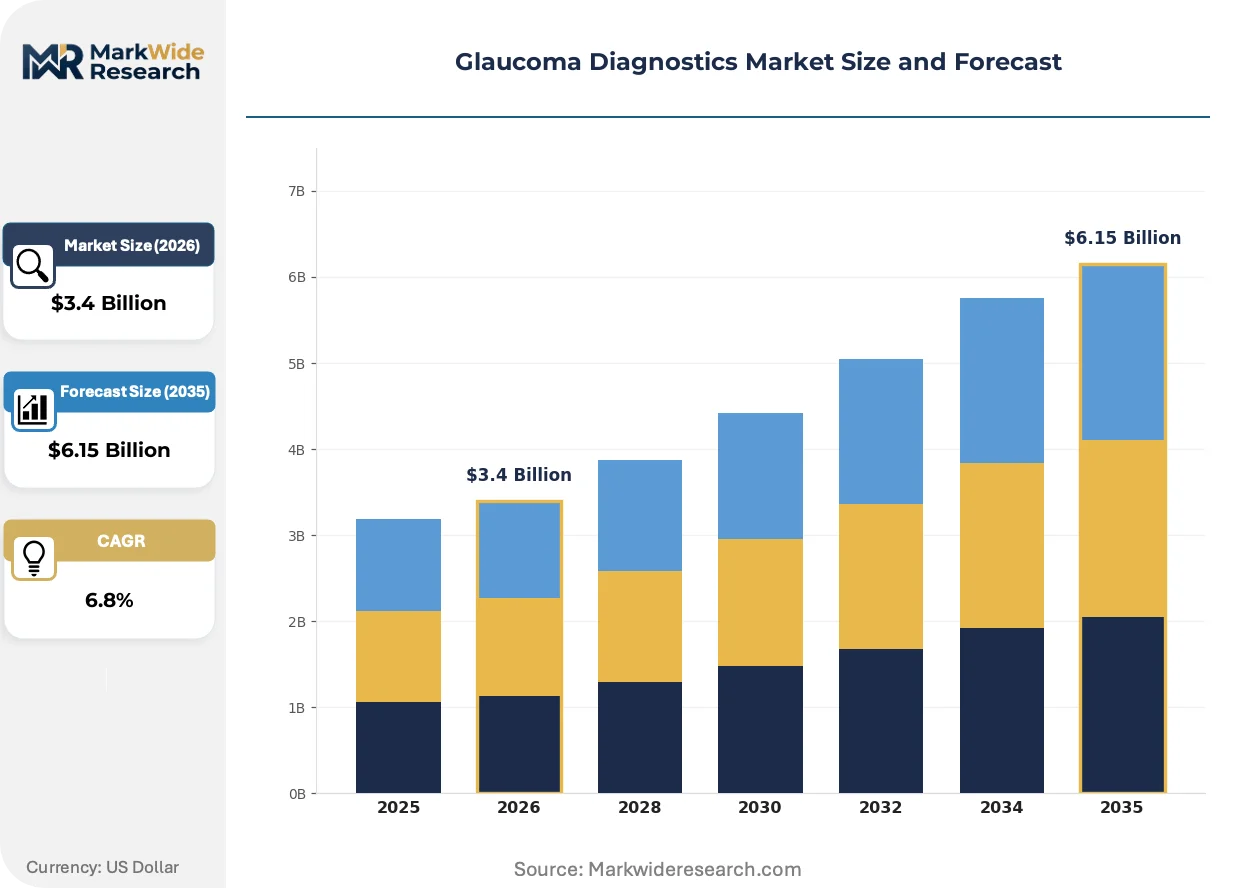
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tonometry Devices, Optical Coherence Tomography, Visual Field Analyzers, Pachymeters, Fundus Cameras Technology: Laser Scanning, Digital Imaging, Ultrasound, Perimetry, Confocal Microscopy Application: Early Detection, Disease Monitoring, Risk Assessment, Postoperative Evaluation, Screening Programs End User: Ophthalmology Clinics, Diagnostic Laboratories, Specialty Eye Centers, Research Institutions, Optometry Practices |
| Companies Covered | NIDEK, Topcon Corporation, Heidelberg Engineering, Carl Zeiss Meditec, Optovue Incorporated, Haag-Streit Group, Leica Microsystems, Abbott Laboratories, Bausch + Lomb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glaucoma Diagnostics Market Shifts & Advancements
Diagnostic workflows are fragmenting across point-of-care, home-monitoring, and centralized reading center models, requiring manufacturers to architect flexible platform architectures rather than monolithic hospital-based systems.
Adaptive optics ophthalmoscopy is digitizing cellular-level retinal ganglion cell imaging for research applications. Academic medical centers in Japan and the United States are piloting these systems for early glaucoma progression detection. The technology is digitizing how researchers correlate structural changes with functional vision loss, compressing the timeline between biological discovery and clinical translation.
The FDA's evolving premarket review pathways for AI-enabled ophthalmic devices are accelerating clearance timelines for algorithm-based diagnostic tools. Manufacturers now structure clinical validation studies around real-world performance data rather than controlled laboratory settings. Software-driven diagnostics face compressed regulatory cycles in the United States compared to hardware-heavy traditional submissions.
Eye care networks are consolidating procurement decisions under centralized value analysis committees, displacing individual physician purchasing authority. Integrated delivery systems in the United States now negotiate enterprise-wide imaging platform contracts spanning multiple facilities. This concentration is most visible in metropolitan markets where health system mergers have created regional oligopsony conditions for diagnostic equipment vendors.
Glaucoma Diagnostics Market Segmentation
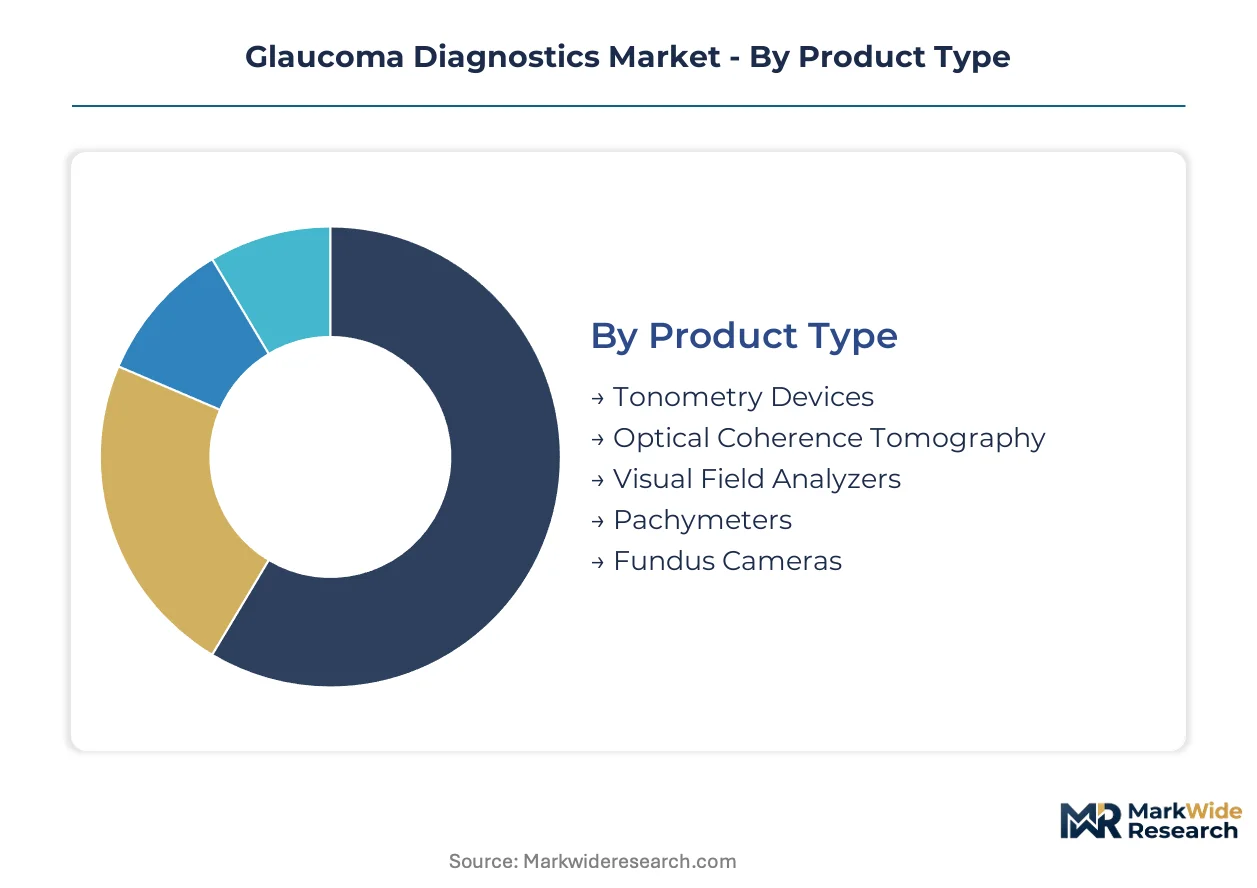
Glaucoma diagnostics fragment across hardware generations, software capabilities, and care delivery models. Understanding these divides clarifies where capital investment concentrates versus where subscription economics are displacing traditional equipment sales.
Product Type:
Mature imaging platforms anchor hospital procurement budgets while emerging portable devices unlock community access points.
- Optical Coherence Tomography:Spectral-domain and swept-source systems deliver sub-micron axial resolution for retinal nerve fiber layer mapping. Demand concentrates in United States academic medical centers where progression analysis software drives replacement cycles.
- Visual Field Analyzers:Standard automated perimetry quantifies functional vision loss through sensitivity threshold mapping. United States specialty eye centers retain these for longitudinal staging despite 15-20 minute test durations limiting throughput.
- Tonometry Devices:Contact and non-contact tonometers measure intraocular pressure for screening and monitoring.
- Pachymeters:Ultrasound and optical pachymetry assess central corneal thickness to correct pressure readings.
- Fundus Cameras:Digital retinal imaging systems with AI overlay enable population-scale screening programs.
OCT retains volume leadership; fundus cameras hold the steepest expansion curve.
Technology:
Cost tiers separate premium institutional systems from deployable point-of-care alternatives.
- Laser Scanning:Confocal and scanning laser ophthalmoscopy enables high-resolution optic nerve head imaging. Japan's manufacturing base supplies superluminescent diodes that power these systems for Heidelberg Engineering and Carl Zeiss Meditec platforms.
- Digital Imaging:CMOS and CCD sensor arrays capture fundus photographs for AI-assisted interpretation. Singapore's national screening program deploys these at polyclinics to address specialist workforce constraints.
- Perimetry:Automated static and kinetic perimetry maps visual field defects for functional assessment.
- Ultrasound:A-scan and B-scan ocular biometry supports axial length measurement and anterior segment imaging.
- Confocal Microscopy:Corneal nerve fiber assessment extends glaucoma evaluation to ocular surface diagnostics.
Digital imaging commands the broadest installed base; laser scanning maintains the highest per-unit margins.
Application:
Customer type stratification separates acute diagnostic episodes from longitudinal management relationships.
- Disease Monitoring:Serial OCT and perimetry track structural and functional progression to guide treatment escalation. United States integrated delivery systems bundle these into value-based care contracts with pharmaceutical manufacturers.
- Early Detection:Population screening identifies pre-perimetric glaucoma before functional vision loss occurs. South Korea's national health insurance funds automated fundus analysis in community health centers.
- Risk Assessment:Intraocular pressure, family history, and corneal thickness evaluation stratify progression probability.
- Postoperative Evaluation:Trabeculectomy and MIGS follow-up protocols mandate scheduled imaging intervals.
- Screening Programs:Workplace and community detection initiatives target high-risk demographic cohorts.
Disease monitoring generates recurring revenue streams; early detection programs are expanding most quickly through public health mandates.
End User:
Geography determines procurement concentration, with urban academic centers diverging from distributed primary care networks.
- Specialty Eye Centers:Dedicated glaucoma practices combine multimodal imaging with surgical consultation under one roof. United States metropolitan markets concentrate these in vertically integrated ophthalmology platforms.
- Ophthalmology Clinics:General eye care practices incorporate screening diagnostics into comprehensive examination workflows. India's tier-2 cities are adding OCT capacity as medical device financing extends beyond tier-1 hospitals.
- Optometry Practices:Primary eye care providers perform initial screening and referral triage.
- Diagnostic Laboratories:Centralized reading centers interpret captured images for remote or underserved regions.
- Research Institutions:Academic medical centers validate biomarkers and train AI algorithms on curated datasets.
Specialty eye centers dominate capital equipment procurement; diagnostic laboratories are gaining share fastest through teleophthalmology network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German optical component manufacturers export superluminescent diodes and swept-source lasers to United States diagnostic equipment assemblers, creating a transatlantic supply corridor that anchors premium imaging platform production.
United States
Medicare reimbursement clarity for remote patient monitoring and AI-enabled screening drives hospital procurement of integrated diagnostic networks. FDA premarket review pathways for software-as-a-medical-device compress regulatory timelines for algorithm-based tools. Boston and San Francisco academic medical centers pilot adaptive optics systems for cellular-level retinal ganglion cell imaging.
Germany
Heidelberg Engineering's confocal scanning technology and Carl Zeiss Meditec's OCT platforms sustain demand from university hospitals and specialty eye centers. EU MDR conformity assessment pathways for software-driven diagnostics now clarify CE marking requirements for European ophthalmic AI developers. Baden-Württemberg's precision optics cluster in Oberkochen and Jena supplies laser components to global equipment manufacturers.
Japan
NIDEK sustains manufacturing scale for tonometry and perimetry devices across domestic and Asia-Pacific distribution channels. PMDA regulatory frameworks align with international standards for active implantable and software-driven ophthalmic diagnostics. Tokyo and Osaka metropolitan areas concentrate glaucoma fellowship-trained specialists in vertically integrated academic platforms.
South Korea
National health insurance funds automated fundus analysis for population-scale glaucoma detection in community health centers, expanding addressable patient pools beyond specialty clinics. MFDS streamlined approval processes for AI-enabled screening software reduce time-to-market for domestic developers. Seoul Capital Area health authorities deploy digital retinal imaging at polyclinics to address specialist workforce constraints.
Singapore
National screening programs deploy fundus cameras with AI overlay at polyclinics, targeting pre-perimetric glaucoma detection before functional vision loss occurs. Health Sciences Authority regulatory frameworks support software-as-a-medical-device pathways for automated diagnostic algorithms. Biopolis research cluster validates retinal nerve fiber layer thickness biomarkers for surrogate endpoint acceptance.
Glaucoma Diagnostics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base concentrates around three strategic archetypes: integrated optical conglomerates with captive component supply, specialized ophthalmic equipment manufacturers with deep clinical workflow integration, and diversified medtech portfolios with cross-category leverage. Dominant competitive moves include enterprise-wide imaging platform contracts negotiated through centralized value analysis committees, and accelerated regulatory submissions for algorithm-based screening tools that compress traditional hardware-software value stacks.
Among Germany-based precision optics specialists, Carl Zeiss Meditec and Heidelberg Engineering exemplify the integrated equipment archetype with established OCT and confocal scanning platforms. NIDEK represents the Asia-Pacific manufacturing scale archetype, sustaining distribution breadth across regional channels. These three anchors occupy positions that span premium academic medical center procurement and broader clinical access points, reflecting how geographic origin and corporate structure map to competitive positioning in diagnostic imaging workflows.
| Leading Market Players |
|---|
| NIDEK |
| Topcon Corporation |
| Heidelberg Engineering |
| Carl Zeiss Meditec |
| Optovue Incorporated |
| Haag-Streit Group |
| Leica Microsystems |
| Abbott Laboratories |
| Bausch + Lomb |
| Others |
Supply & Pricing Matrix
Overcapacity in Japanese superluminescent diode fabrication is compressing component pricing and forcing suppliers to extend payment terms to diagnostic equipment assemblers in Germany and the United States. This utilization slack cascades downstream, enabling OCT manufacturers to hold hardware margins steady while absorbing AI software development costs through supply-chain finance facilities.
Pricing Analysis
Cost-plus contracts with Japanese yen indexation dominate component procurement for spectral-domain OCT systems. Pricing stratifies across premium, standard, and economy tiers based on axial resolution specifications and FDA clearance status. Cost compression in the economy tier is intensifying because South Korean and Chinese fundus camera manufacturers are scaling CMOS sensor production. Community health centers exhibit the highest price sensitivity, while United States academic medical centers prioritize progression analysis software capabilities over unit cost.
Supply Chain Analysis
Supply-chain finance facilities from Japanese trading houses now cover 90-day payment windows for German optical component buyers. Manufacturing concentrates in Japan, Germany, and the United States. Superluminescent diodes, swept-source lasers, and precision optical assemblies constitute critical input dependencies. Single-source vulnerability runs through Oberkochen-based precision optics clusters where Carl Zeiss Meditec maintains captive supply relationships. Distribution runs through regional equipment distributors with biomedical engineering service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glaucoma diagnostics market is entering a cyclical recovery phase as deferred replacement cycles for spectral-domain OCT systems release pent-up demand following pandemic-era capital expenditure freezes.
For Market Incumbents: Build regulatory data moats through FDA 510(k) submissions for AI-enabled progression analysis algorithms. Incumbent manufacturers should accelerate software-as-a-medical-device clearances to defend against cloud-native diagnostic entrants, while securing exclusive supply agreements with Japanese superluminescent diode manufacturers to lock in component access. For New Entrants and Emerging Players: Build out portable tonometer-fundus camera combinations for teleophthalmology networks in rural India and sub-Saharan Africa. Community-based screening programs present the most penetrable demand segment. A software-first go-to-market approach with cloud-based specialist interpretation bypasses capital equipment intensity barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among AI diagnostic software developers with hospital system partnerships. Long-term viability hinges on reimbursement pathway clarity rather than hardware shipment volumes. Acquisition targets should demonstrate established Medicare coverage determinations for remote patient monitoring. The signal to monitor is FDA premarket notification volume for algorithm-based screening tools.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for AI Screening Algorithm | Accelerated 510(k) pathways compress regulatory timelines for software-driven diagnostics. |
| CE Marking Pathway under EU MDR | Clarified software-as-a-medical-device requirements reduce certification uncertainty for European market entry. |
| Hospital System Partnership | Integrated delivery networks in the United States consolidate procurement under enterprise-wide imaging contracts. |
| Software Companion Development | AI overlay integration with legacy OCT platforms enables subscription revenue without hardware replacement. |
| Reimbursement Strategy | Medicare coverage for remote patient monitoring creates financial pathways for home-based pressure tracking. |
Research Methodology
The analysis maps optical coherence tomography systems, visual field analyzers, tonometry devices, and AI-enabled screening software, each validated through ophthalmology practice administrators, biomedical equipment procurement officers, and glaucoma fellowship-trained clinicians. Primary interviews with hospital purchasing committee members and GPO contracts managers combined with secondary validation against FDA 510(k) databases, CMS Medicare reimbursement schedules, and EU MDR notified body guidance documents. Bottom-up equipment shipment estimates and top-down healthcare expenditure allocations were triangulated to anchor market sizing.
Assumptions held fixed include current FDA premarket review timelines and existing Medicare coverage determinations, while AI algorithm performance thresholds and teleophthalmology reimbursement expansion were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, technology platform, application purpose, and end-user facility category. CAGRs were derived from equipment replacement cycle analysis and software subscription attach rate projections. Forecast inputs incorporated PMDA regulatory alignment trends in Japan and MFDS streamlined approval pathways in South Korea.
Sensitivities concentrate around FDA guidance evolution for AI-enabled devices and Medicare remote monitoring coverage expansion. Forecasts reflect these documented assumptions and prevailing macroeconomic conditions. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Viral Antigens Market
Diagnostics
BRIC in-Vitro Diagnostics (IVD) Market
Diagnostics
Europe Breast Cancer Screening Tests Market
Diagnostics
Clostridium Diagnostics Market
Diagnostics
Global Phytopathological Disease Diagnostics Market
Diagnostics
Global Immunoprotein Diagnostic Testing Market
Diagnostics
North America Ovarian Cancer Diagnostics Market
Diagnostics
UAE in Vitro Diagnostics Market
Diagnostics
Global Renal Biomarkers Market
Diagnostics
Global Rheumatoid Arthritis Diagnostic Tests Market
Diagnostics
Mycology Immunoassays Testing Market
Diagnostics
Asia Pacific Predictive Disease Analytics Market
Diagnostics
Fertility Testing Devices Market
Diagnostics
Veterinary Chemistry Analyzers Market
Diagnostics
France in-Vitro Diagnostics Market
Diagnostics
Global Diagnostic Radiopharmaceuticals and Contrast Media Market