
 Diagnostic Enzymes Market | 2026-2036
Diagnostic Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Diagnostic Enzymes Market Intelligence
Point-of-care testing is hardening its position as the fastest-expanding end-use vertical within diagnostic enzymes. Thermo Fisher Scientific leverages its scale across immunoassay and molecular diagnostics platforms to sustain supply continuity for enzyme reagents. F. Hoffmann-La Roche Ltd. anchors its competitive stance through integrated clinical chemistry systems that bundle proprietary enzyme formulations. Merck KGaA specializes in high-purity enzyme manufacturing for mass spectrometry workflows, occupying a niche with stringent specification requirements.
Diagnostic enzymes comprise purified biocatalysts—primarily hydrolases, transferases, and oxidoreductases—engineered for quantitative substrate detection in biological specimens, typically operating within narrow pH and temperature ranges to ensure assay reproducibility. These reagents serve as signal-generating components in clinical analyzers, enabling the measurement of metabolites, cardiac markers, and therapeutic drug concentrations with precision. Lipase and alkaline phosphatase product lines command stable margin pools in mature clinical chemistry segments, while creatine kinase formats are gaining traction in cardiac biomarker panels due to acute myocardial infarction protocol standardization. Molecular diagnostics technology is expanding fastest among enzyme-linked detection methods, driven by polymerase and reverse transcriptase demand in nucleic acid amplification workflows.
FDA enforces quality system regulation and in vitro diagnostic reagent classification that shapes enzyme stability validation requirements for U.S. market entry. EMA's In Vitro Diagnostic Regulation tightens performance evaluation and post-market surveillance standards across European member states, compelling manufacturers to rebuild technical documentation. Japan's PMDA maintains distinct master file procedures for diagnostic reagents that create incremental compliance layers for foreign suppliers. Stakeholders must monitor evolving harmonization between regional quality frameworks to optimize registration sequencing and avoid redundant clinical performance studies.
Market Dynamics
The diagnostic enzymes market is consolidating around point-of-care testing infrastructure, with decentralized clinical workflows demanding enzyme formulations that maintain stability outside controlled laboratory environments. This structural pull is compressing development cycles for ambient-tolerant biocatalysts while elevating cold-chain logistics from cost center to competitive differentiator.
Growth Catalysts
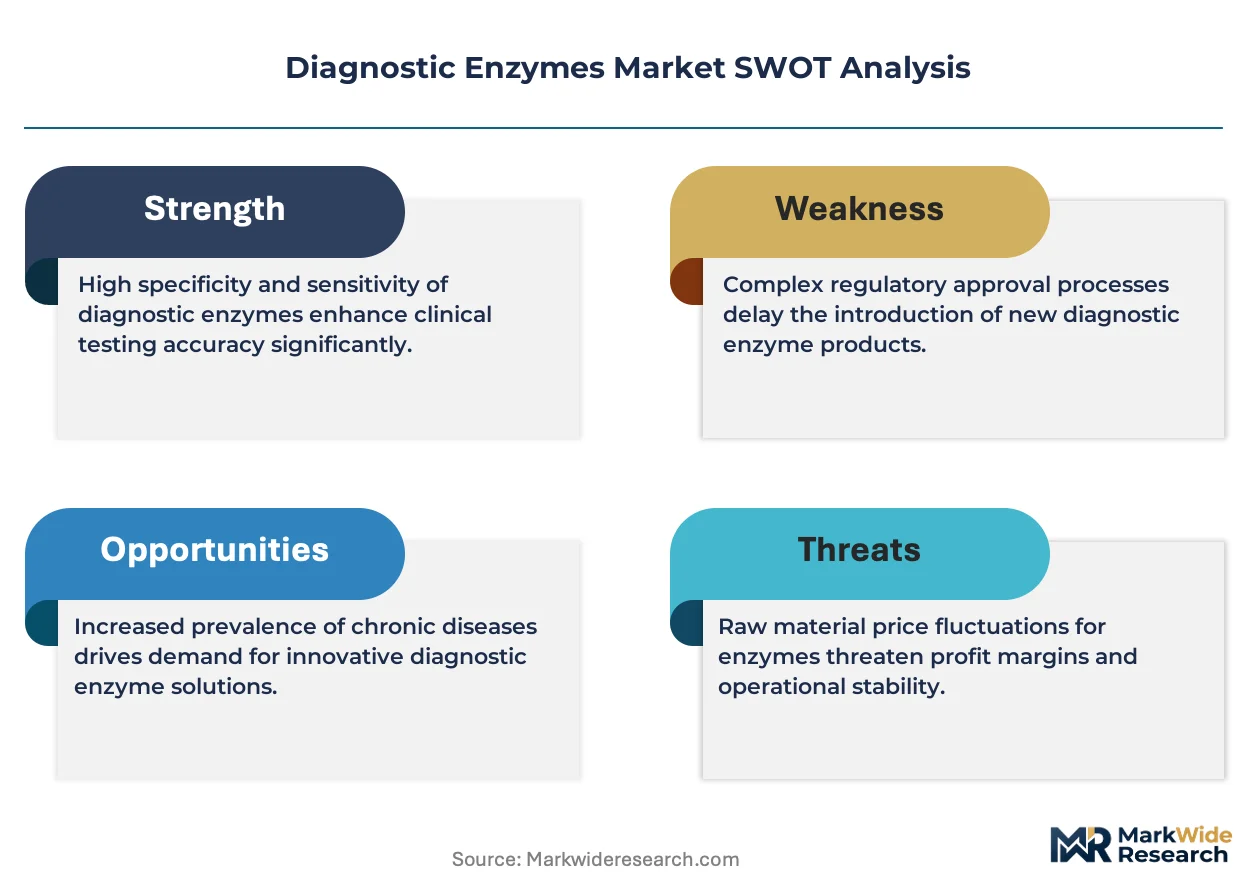
- IVDR Implementation:EMA's In Vitro Diagnostic Regulation mandates stricter performance documentation, accelerating replacement demand for legacy enzyme inventories that cannot meet enhanced stability validation protocols.
- Cardiac Biomarker Protocols:Standardized acute myocardial infarction diagnostic pathways in emergency medicine are embedding creatine kinase and troponin-linked enzyme assays into mandatory clinical workflows.
- Polymerase Engineering:Thermostable DNA polymerase variants are converging with isothermal amplification chemistries, opening nucleic acid testing to resource-limited settings previously excluded from molecular diagnostics access.
Market Restraints
- Raw Material Concentration:High-purity microbial fermentation feedstocks concentrate among suppliers in Germany and Japan, exposing enzyme manufacturers to input cost volatility when energy or agricultural commodity markets fluctuate.
- Recombinant Production Bottlenecks:Mammalian cell culture capacity for complex glycoprotein enzymes remains structurally constrained, limiting supply elasticity for mass spectrometry-grade reagents.
- Substitute Detection Modalities:Biosensor and electrochemical detection platforms are displacing enzyme-coupled colorimetric methods in glucose and lactate monitoring applications.
Strategic Opportunities
- Home-Based Monitoring:Self-administered enzyme-linked diagnostic kits for chronic disease management represent underpenetrated demand in United States and Japanese consumer health markets.
- CRISPR-Diagnostics Convergence:Cas enzyme integration with lateral flow readouts is creating programmable nucleic acid detection platforms that bypass thermal cycler infrastructure requirements.
- Green Chemistry Incentives:REACH-compliant solvent-free enzyme immobilization processes qualify for EU Green Deal innovation funding, reducing regulatory compliance costs for European manufacturing facilities.
Industry Challenges
- Specialized Bioprocess Engineering Talent:Scarcity of fermentation scientists capable of optimizing enzyme yield-to-purity ratios is extending process development timelines for novel biocatalyst introductions.
- Multi-Jurisdictional Registration Sequencing:Divergent master file procedures across FDA, EMA, and PMDA are forcing redundant stability studies that compress margin structures for mid-tier enzyme suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diagnostic Enzymes Market |
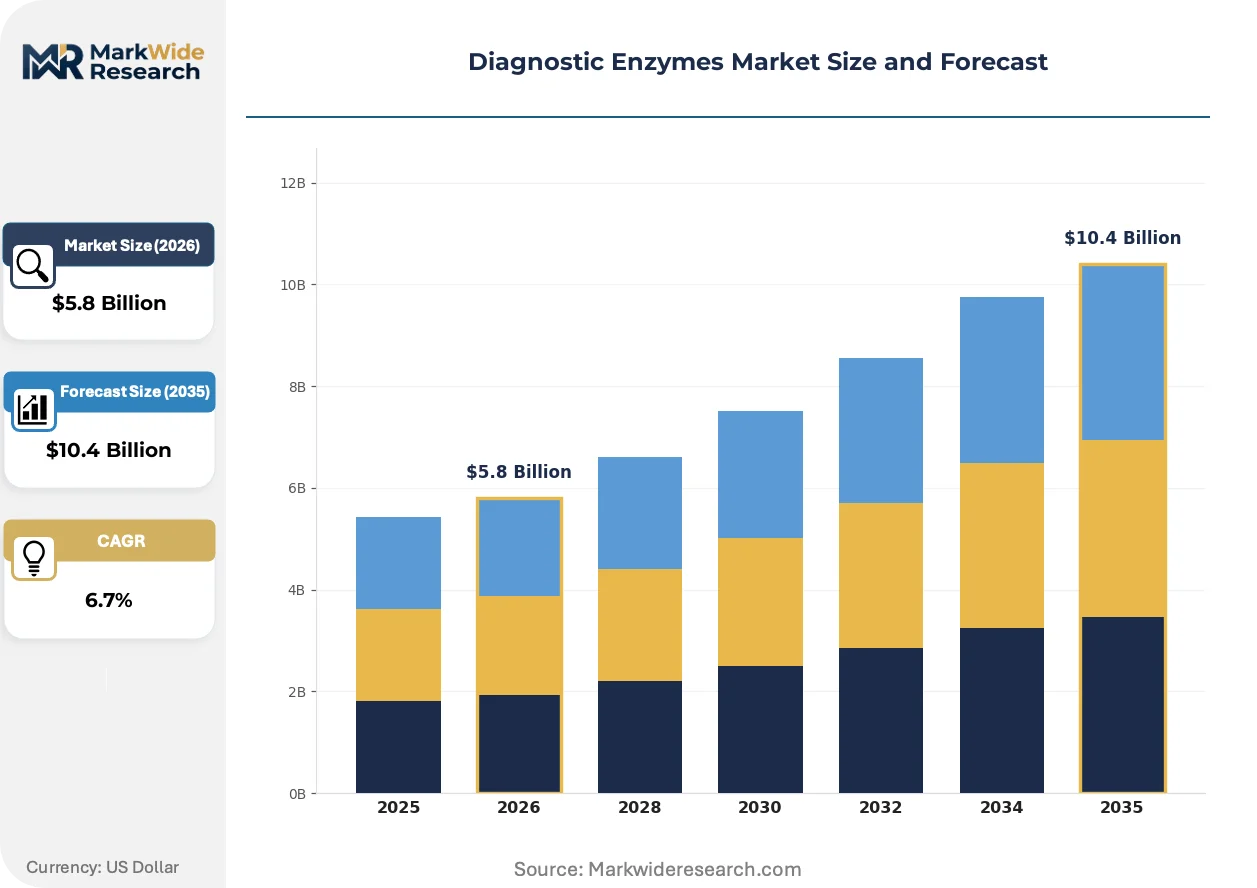
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.4 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Lipase, Alkaline Phosphatase, Creatine Kinase Application: Clinical Chemistry, Infectious Disease Testing, Cardiac Biomarkers, Drug Monitoring End User: Hospitals, Diagnostic Laboratories, Research Institutions, Home Care Settings Technology: Immunoassay, Mass Spectrometry, Molecular Diagnostics, Enzymatic Assays |
| Companies Covered | Thermo Fisher Scientific, Inc., F. Hoffmann-La Roche Ltd., Merck KGaA, Promega Corporation, Takara Bio, Inc., Codexis, Inc., Enzo Life Sciences, Inc., Amano Enzymes, Inc., Creative Enzyme, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diagnostic Enzymes Market Strategic Shifts & Innovations
Enzyme stabilization chemistry is advancing faster than assay platform integration, creating capability gaps between reagent performance and instrument readout sensitivity. Manufacturers are racing to align shelf-life extensions with the deployment timelines of next-generation clinical analyzers.
Lyophilized enzyme bead formats are converging with microfluidic cartridge architectures, enabling ambient-temperature distribution for previously cold-chain-dependent cardiac marker assays. Emergency department networks in United States health systems are adopting these formats to reduce pre-analytical variability. This convergence is compressing the addressable market for traditional liquid reagent configurations that require refrigerated logistics infrastructure.
EMA's In Vitro Diagnostic Regulation is forcing reconstruction of technical documentation for enzyme reagents marketed before 2022. Manufacturers must regenerate clinical performance data under stricter post-market surveillance requirements. European clinical chemistry segments are responding by consolidating supplier relationships toward vendors with established IVDR-compliant quality management systems.
Hospital procurement departments are unbundling enzyme reagent contracts from analyzer equipment leases, reversing decades of bundled pricing structures. This disintermediation exposes standalone reagent suppliers to direct price competition while creating opportunities for third-party enzyme manufacturers to penetrate previously captive accounts. The shift is most visible in German and Japanese hospital networks where diagnostic service outsourcing has eroded manufacturer lock-in effects.
Diagnostic Enzymes Market Segmentation
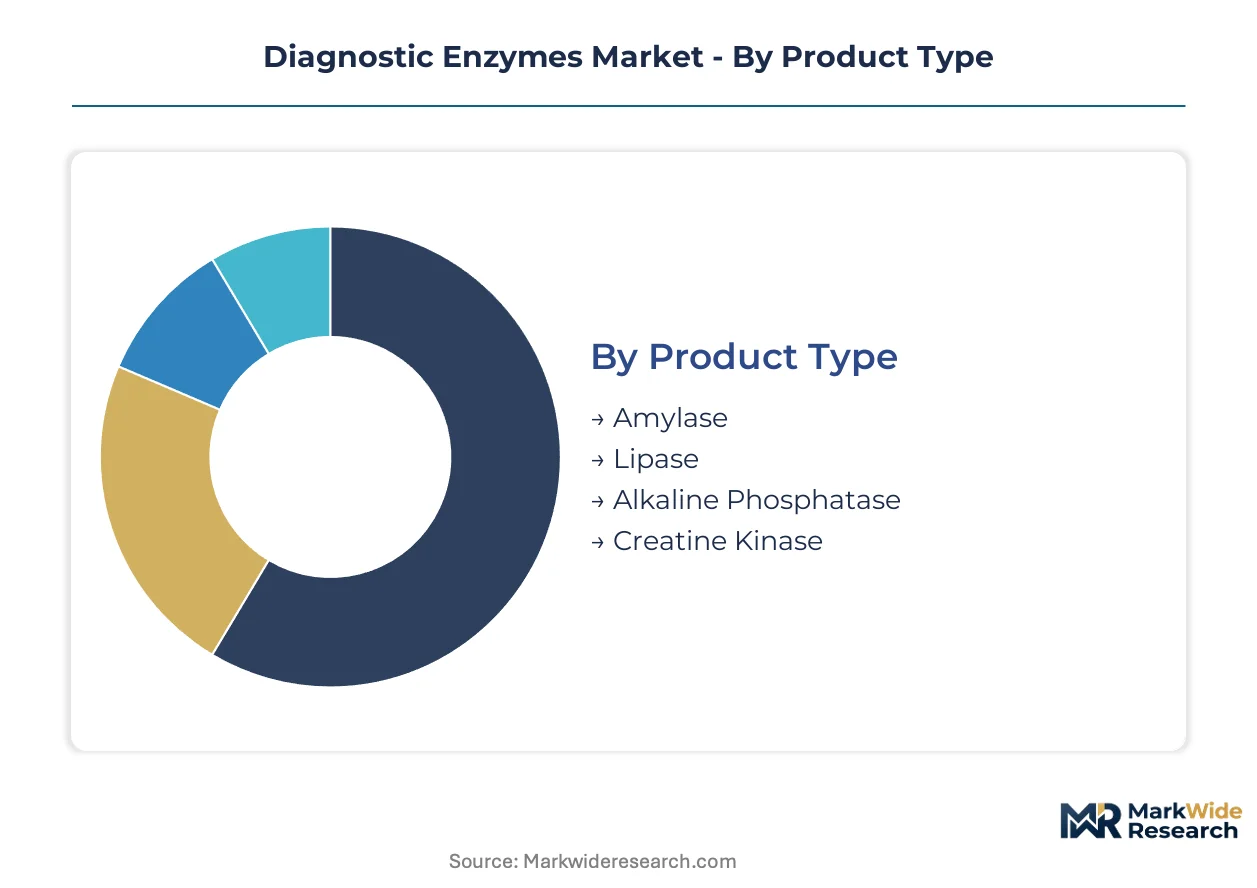
Diagnostic enzymes fragment across four analytical dimensions that shape procurement decisions. Product type determines manufacturing complexity and purity thresholds. Application and technology choices dictate regulatory pathway requirements and reimbursement positioning.
Product Type:
Standardization dominates amylase and alkaline phosphatase formats, while lipase and creatine kinase command premium specifications for cardiac and pancreatic diagnostic protocols.
- Amylase:Pancreatic and salivary isoforms hydrolyze starch substrates in serum and urine matrices. Demand clusters in emergency department triage protocols across United States health systems, where acute pancreatitis diagnosis requires rapid turnaround.
- Lipase:Triacylglycerol hydrolase with superior specificity for pancreatic pathology compared to amylase. German clinical chemistry laboratories specify this enzyme for standardized acute abdomen workups, driving volume concentration in centralized reference labs.
- Alkaline Phosphatase:Membrane-bound hydrolase detecting liver and bone disorders through p-nitrophenyl phosphate substrates. Japanese diagnostic manufacturers source this enzyme for automated analyzer compatibility.
- Creatine Kinase:Dimeric phosphotransferase catalyzing creatine-phosphocreatine interconversion. Cardiac biomarker panel standardization in emergency medicine protocols elevates CK-MB isoform demand.
Leading the category by volume: alkaline phosphatase. Growing fastest: creatine kinase.
Application:
Volume scale separates mature clinical chemistry segments from emerging molecular diagnostics workflows.
- Clinical Chemistry:High-throughput automated analyzers process metabolic panels using enzyme-coupled detection. United States hospital networks consolidate purchasing around integrated chemistry-immunoassay platforms.
- Infectious Disease Testing:Enzyme-linked immunosorbent assays and nucleic acid amplification detect pathogens. Polymerase and reverse transcriptase demand surges in point-of-care respiratory panel deployments.
- Cardiac Biomarkers:Troponin-linked enzyme assays and creatine kinase protocols for acute myocardial infarction rule-out. Emergency department networks in Japan adopt lyophilized formats for ambient stability.
- Drug Monitoring:Therapeutic drug concentration measurement via enzymatic competitive inhibition. German transplant centers specify high-precision formulations for immunosuppressant quantification.
Clinical chemistry commands installed base dominance. Molecular diagnostics applications are expanding most quickly.
End User:
Centralized laboratory infrastructure contrasts with decentralized point-of-care deployment models.
- Hospitals:Integrated health systems operate high-volume clinical chemistry and emergency cardiac marker testing. Procurement departments in United States networks unbundle reagent contracts from analyzer leases.
- Diagnostic Laboratories:Reference labs consolidate esoteric testing including mass spectrometry-grade enzyme applications. German laboratory networks outsource specialized biocatalyst production to contract manufacturers.
- Research Institutions:Academic medical centers source recombinant enzymes for assay development and biomarker discovery. Japanese national universities drive demand for CRISPR-associated nucleases.
- Home Care Settings:Self-administered enzyme-linked diagnostic kits for chronic disease monitoring. Underpenetrated demand in United States and Japanese consumer health markets creates white-space opportunity.
Hospital laboratories anchor volume procurement. Home care settings show steepest expansion trajectory.
Technology:
Detection sensitivity requirements stratify platform selection across clinical workflow settings.
- Immunoassay:Enzyme-linked signal generation for antibody-antigen binding detection. Roche and Abbott integrated systems embed proprietary alkaline phosphatase and horseradish peroxidase conjugates.
- Mass Spectrometry:High-purity proteolytic enzymes for bottom-up protein identification. Merck KGaA supplies immobilized trypsin formats meeting German pharmaceutical quality benchmarks.
- Molecular Diagnostics:Thermostable DNA polymerases and reverse transcriptases for nucleic acid amplification. Isothermal chemistry convergence opens resource-limited settings previously excluded from molecular testing access.
- Enzymatic Assays:Colorimetric and fluorometric substrate detection in clinical chemistry analyzers. Mature segment facing displacement pressure from biosensor platforms in glucose and lactate monitoring.
Enzymatic assays maintain installed base leadership. Molecular diagnostics technology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Singapore and biotech clusters in Massachusetts concentrate diagnostic enzyme manufacturing capacity through tax-advantaged R&D incentives and streamlined customs processing for high-value reagent exports.
United States
Emergency department networks in Texas and Florida deploy lyophilized cardiac marker assays for ambient-temperature distribution. FDA quality system regulations enforce enzyme stability validation for IVD reagent market entry. The Boston-Cambridge biotech corridor anchors recombinant enzyme development for CRISPR-diagnostic convergence.
Germany
Centralized reference laboratories in Bavaria specify high-purity lipase for standardized acute abdomen workups. EMA's In Vitro Diagnostic Regulation mandates reconstructed technical documentation for legacy enzyme inventories. The Rhine-Ruhr industrial cluster houses fermentation capacity for mass spectrometry-grade proteolytic enzymes.
Japan
PMDA master file procedures create compliance layers for foreign enzyme suppliers seeking market access. National university hospitals in Tokyo and Osaka drive demand for thermostable polymerases in point-of-care respiratory panels. The Kansai region concentrates automated clinical chemistry analyzer manufacturing with bundled proprietary enzyme formulations.
China
Domestic fermentation capacity expansion targets import substitution for diagnostic-grade hydrolases and transferases. NMPA in vitro diagnostic reagent classification shapes registration pathways for foreign manufacturers. The Yangtze River Delta biotech parks attract contract manufacturing investment for isothermal amplification enzymes.
India
CDSCO streamlined approval pathways for IVD reagents accelerate market entry for imported enzyme formulations. Diagnostic laboratory chains in Maharashtra and Karnataka consolidate procurement for enzyme-linked immunoassay reagents. The Hyderabad-Genome Valley cluster specializes in recombinant enzyme production for molecular diagnostics export.
Diagnostic Enzymes Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated life science conglomerates commanding bundled analyzer-reagent positions while independent enzyme suppliers penetrate disintermediated procurement channels. The vendor base concentrates around three strategic archetypes: diversified platform providers with captive enzyme production, pure-play biocatalyst specialists serving third-party assay developers, and fermentation-focused contract manufacturers supplying mass spectrometry-grade formulations. Competitive moves center on backward integration into microbial strain development and geographic expansion through distributor partnerships in Asia-Pacific growth markets.
Within the diversified platform tier, Thermo Fisher Scientific Inc. and F. Hoffmann-La Roche Ltd. exemplify integrated system providers that bundle proprietary enzyme formulations with analyzer hardware. Merck KGaA occupies a position among specialty chemical conglomerates with dedicated high-purity enzyme manufacturing capabilities. These three entities represent distinct competitive positioning archetypes: scale-driven supply continuity, clinical chemistry system integration, and precision-grade reagent specialization respectively.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Merck KGaA |
| Promega Corporation |
| Takara Bio, Inc. |
| Codexis, Inc. |
| Enzo Life Sciences, Inc. |
| Amano Enzymes, Inc. |
| Creative Enzyme |
| Others |
Cost & Logistics Intelligence
Backward integration into microbial strain development anchors supply security and pricing power for diagnostic enzyme manufacturers, with captive fermentation capacity in Germany and Japan insulating premium-tier suppliers from agricultural commodity volatility while forcing mid-tier competitors into spot-market feedstock exposure.
Pricing Analysis
Short lead-time premiums command 15-25% markups over contract-scheduled deliveries in clinical chemistry reagent procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by purity grade and IVDR certification status, with mass spectrometry-grade formulations capturing the top tier. Cost compression in standard-grade hydrolases is intensifying because hospital procurement departments unbundle reagent contracts from analyzer leases. Diagnostic laboratories exhibit highest price sensitivity due to volume consolidation pressures, while emergency department networks prioritize ambient-stability specifications over unit cost.
Supply Chain Analysis
Fermentation scientist scarcity in Bavaria and Kansai industrial clusters constrains capacity expansion timelines for high-purity enzyme manufacturing. Supply concentrates in Germany, Japan, and the United States, with microbial fermentation feedstocks drawing from concentrated agricultural suppliers in the Rhine-Ruhr region. Single-source vulnerability permeates recombinant glycoprotein enzyme production where mammalian cell culture capacity remains structurally constrained. Distribution runs through cold-chain logistics networks for liquid reagent formats, while lyophilized bead architectures enable ambient-temperature direct-to-hospital fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diagnostic enzymes market functions as a vertical-integration race where microbial strain ownership and captive fermentation capacity determine margin sustainability against disintermediated procurement trends.
For Market Incumbents: Deploy proprietary enzyme-analyzer bundling to lock in reference laboratory contracts before IVDR compliance documentation requirements fully phase in. Biosensor and electrochemical detection platforms threaten enzyme-coupled colorimetric methods in metabolic monitoring applications, necessitating accelerated lyophilized format development for cardiac biomarker segments. Backward integration into thermostable polymerase engineering secures molecular diagnostics positioning against isothermal amplification disruptors. For New Entrants and Emerging Players: Direct-to-hospital digital procurement platforms offer the lowest-friction entry vector for third-party enzyme suppliers seeking to bypass traditional distributor markups. Home care settings in the United States and Japan present the most penetrable white-space, with self-administered enzyme-linked diagnostic kits for chronic disease management remaining underdeveloped. CRISPR-associated nuclease supply contracts with national university hospitals provide a credible beachhead for specialty biocatalyst positioning. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified life science conglomerates seeking to fill molecular diagnostics capability gaps. Long-term viability hinges on fermentation yield-to-purity optimization expertise that remains scarce across the talent pool. Watch for PMDA-EMA regulatory harmonization progress as the inflection signal determining redundant stability study burdens and mid-tier supplier margin compression severity.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captive microbial production in Germany insulates against feedstock cost volatility from energy market fluctuations. |
| Lyophilized Format Development | Ambient-stable cardiac marker assays reduce cold-chain dependency for emergency department networks in Texas and Florida. |
| IVDR Technical Documentation Reconstruction | EMA compliance investment opens continued European market access for legacy enzyme reagent portfolios. |
| CRISPR-Diagnostic Enzyme Partnerships | Cas nuclease supply agreements with Japanese national universities anchor programmable detection platform positioning. |
| Direct Hospital Procurement Channel | Bypassing distributor layers captures margin from unbundled reagent contracts in German and Japanese health networks. |
Research Approach
SEC 10-K filings, EMA IVDR submission databases, and PMDA master file records formed the secondary backbone, supplemented by FDA quality system regulation guidance documents and customs trade data for fermentation feedstock flows. Primary interviews with fermentation process engineers, clinical chemistry laboratory directors, hospital procurement managers, and diagnostic reagent regulatory affairs specialists validated supply chain concentration patterns and pricing dynamics. Bottom-up enzyme volume estimates by product type and application triangulated against top-down market sizing from installed base analysis of automated analyzer deployments.
Historical trendline analysis of clinical chemistry reagent consumption per analyzer unit established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type hydrolase specifications, application workflow integration depth, end-user centralization level, and technology detection platform sensitivity. CAGRs derived from regression analysis of enzyme unit demand against diagnostic test volume projections, with polymerase demand in molecular diagnostics calibrated separately from mature clinical chemistry enzyme categories.
The model holds under stable regulatory harmonization timelines and continuous cold-chain infrastructure investment; deviation in IVDR enforcement severity or ambient-stability technology breakthroughs would shift volume forecasts between liquid and lyophilized format categories. Forecasts embed assumptions regarding hospital procurement unbundling velocity and point-of-care test menu expansion that remain sensitive to reimbursement policy evolution. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Rubella Diagnostic Testing Market
Diagnostics
Creatinine Test Market
Diagnostics
Global Inflammatory Bowel Disease (IBD) Diagnostic Market
Diagnostics
Glaucoma Diagnostics Market
Diagnostics
Diagnostic Testing of Stds Market
Diagnostics
Asia-Pacific Womens Health Diagnostics Market
Diagnostics
RT-PCR Kits Market
Diagnostics
Fructosamine Reagents Market
Diagnostics
In-Vitro Diagnostics (IVD) Packaging Market
Diagnostics
Pancreatic Cyst Diagnostics Market
Diagnostics
Direct Fluorescent Antibody Test Kits Market
Diagnostics
Global Diagnostic Radiopharmaceuticals and Contrast Media Market
Diagnostics
Global Neurodiagnostics Market
Diagnostics
Brazil in Vitro Diagnostics Market
Diagnostics
Immunoassay Interference Blocker Market
Diagnostics
Neglected Tropical Diseases Diagnosis Market