
 Professional Diagnostics Market | 2026-2036
Professional Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Professional Diagnostics Market Analysis
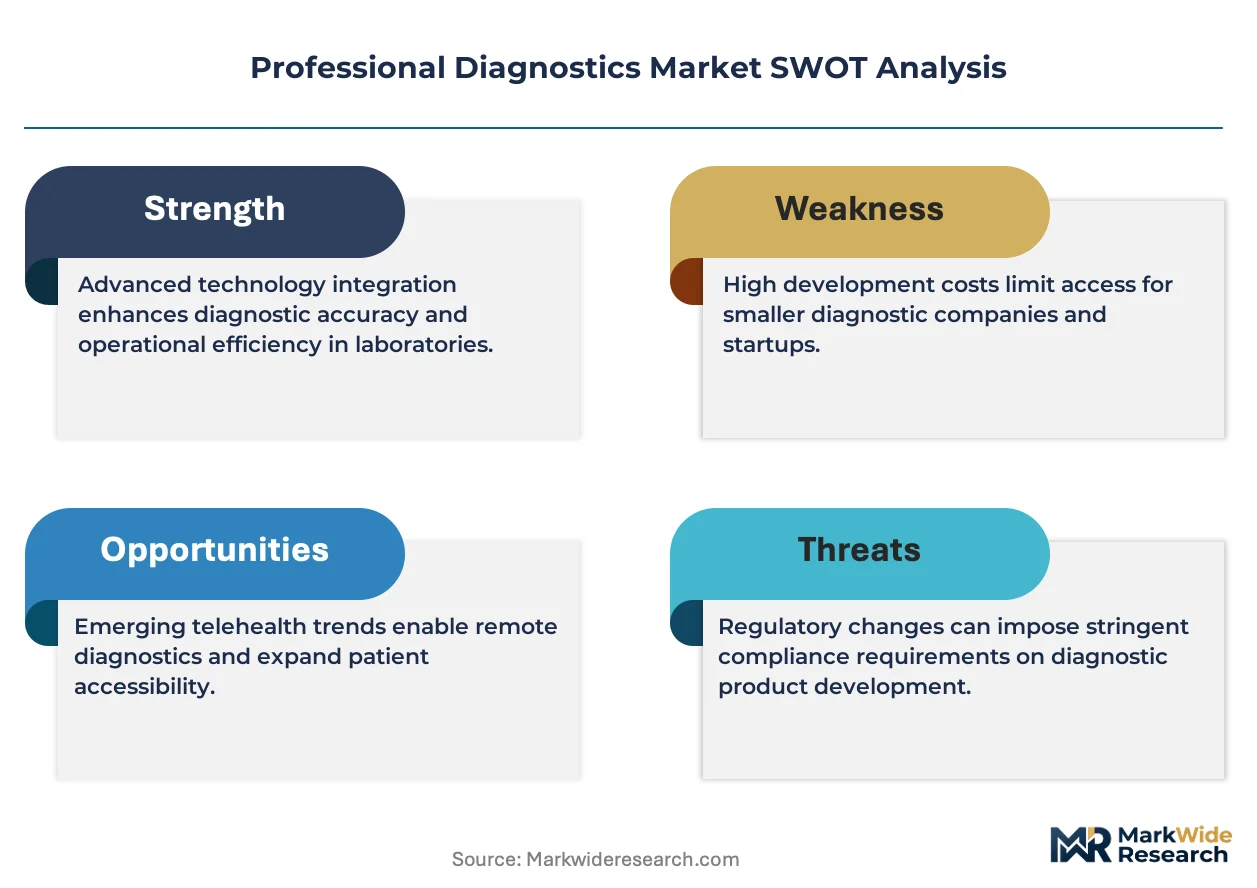
CLIA-waived testing standards is reorganizing how manufacturers allocate R&D budgets across instrument platforms. Abbott Laboratories leverages its point-of-care footprint to sustain channel density in urgent care settings. Siemens Healthineers anchors its position through magnetic resonance diagnostics integration with core lab automation.
Professional diagnostics comprises clinical-grade instruments, reagents, and software systems designed to detect disease biomarkers, pathogen signatures, and metabolic indicators with analytical sensitivity thresholds measured in picograms per milliliter. These systems serve tertiary care centers, reference laboratories, and decentralized clinics requiring traceable, reproducible results for treatment decisions. Molecular diagnostics represents the fastest-expanding product category as PCR and next-generation sequencing platforms displace slower culture-based methods in infectious disease and cancer diagnostics. Point-of-care testing technology commands premium pricing in emergency and homecare settings where turnaround time directly affects clinical workflow efficiency.
FDA premarket notification requirements and CLIA complexity classifications shape instrument design, software validation, and sales channel strategy for US market participants. The European Union's In Vitro Diagnostic Regulation enforces stricter clinical evidence standards and post-market surveillance obligations for CE-marked devices. Stakeholders must monitor evolving reimbursement codes for multiplexed molecular panels as payers recalibrate coverage policies for algorithm-driven diagnostic interpretations.
Market Dynamics
Automated testing line expansion in hospital laboratories is compressing turnaround times and forcing reagent manufacturers to reformulate for continuous-flow analyzers rather than batch-processing workflows.
Growth Catalysts
- CLIA-waived testing expansion:Urgent care clinics and retail health settings now process waived chemistry panels without laboratory personnel, opening instrument placement opportunities outside traditional hospital networks.
- Companion diagnostic premarket pathways:FDA streamlined review processes accelerate co-development timelines with oncology therapeutics, embedding diagnostic requirements into drug approval conditions.
- Integrated delivery network consolidation:United States health systems aggregate purchasing power across multi-site laboratory operations, favoring vendors with enterprise-scale automation portfolios.
Market Restraints
- Reagent supply concentration:Polymerase chain reaction chemistry production clusters in specialized contract manufacturers, creating single-source vulnerability for molecular diagnostic workflows.
- IVDR clinical evidence requirements:European Union post-market surveillance obligations extend validation timelines and documentation burdens for CE-marked instrument launches.
- Fluorescent dye input volatility:Rare earth element pricing swings for optical detection reagents compress margin predictability for immunoassay manufacturers.
Strategic Opportunities
- Decentralized oncology monitoring:Liquid biopsy platforms enable circulating tumor DNA surveillance in community oncology practices previously limited to centralized reference laboratory access.
- AI-assisted pathology integration:Algorithm-driven histopathology screening converges with digital slide scanners to augment specialist workforce capacity in underserved regions.
- Home-based chronic disease management:Connected glucose and coagulation monitors create recurring revenue streams through subscription reagent models outside acute care settings.
Industry Challenges
- Cross-trained laboratory technologist shortages:Molecular diagnostics and mass spectrometry operations require hybrid skill sets combining biochemistry with informatics competencies that training pipelines have not scaled.
- Laboratory information system interoperability:Middleware integration between proprietary analyzer software and hospital electronic health records demands customized validation protocols that extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Professional Diagnostics Market |
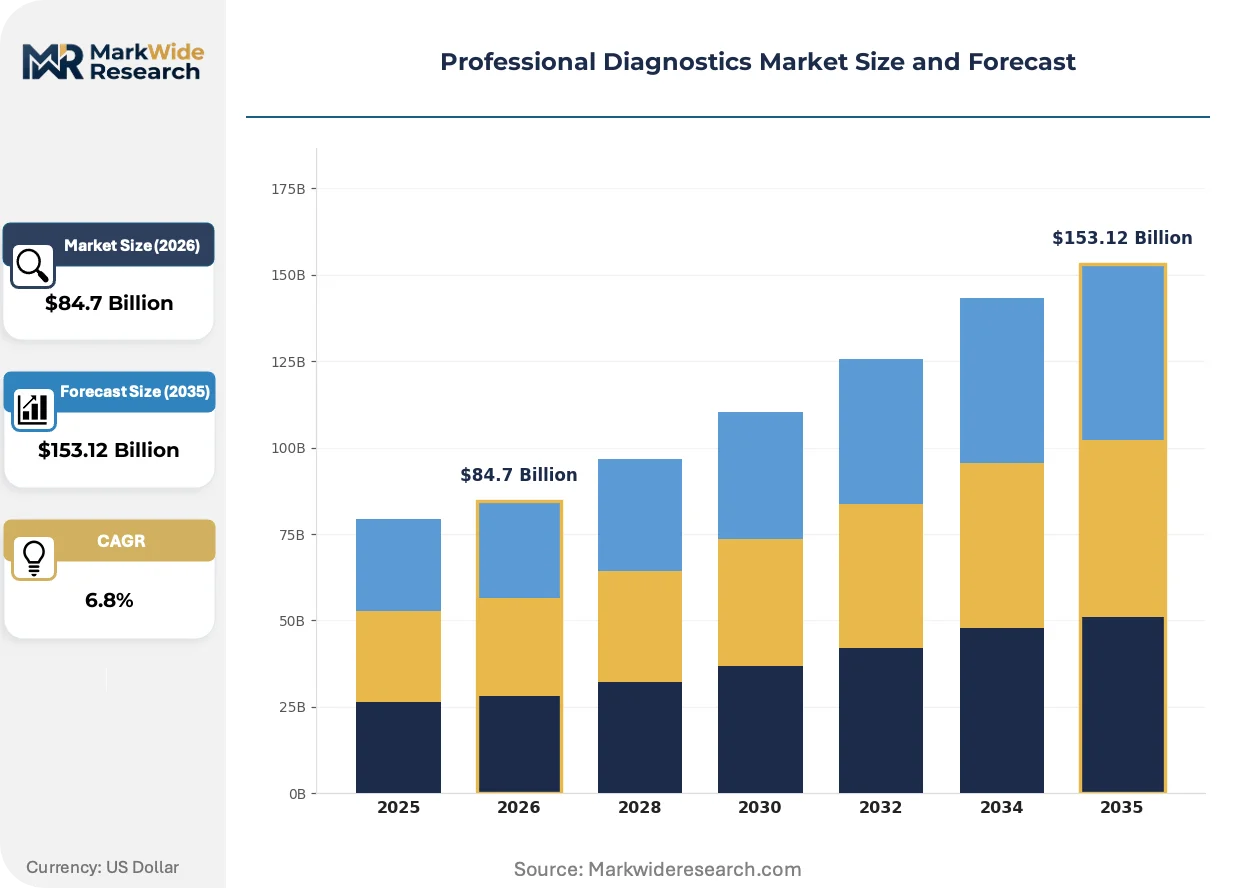
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $153.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassays, Molecular Diagnostics, Hematology Analyzers, Clinical Chemistry Analyzers End User: Hospitals, Laboratories, Clinics, Homecare Technology: Point-of-Care Testing, PCR, ELISA, Next-Generation Sequencing Application: Infectious Disease, Cancer Diagnostics, Cardiac Markers, Metabolic Disorders |
| Companies Covered | F. Hoffmann-La Roche Ltd, Abbott Laboratories, Danaher Corporation, Thermo Fisher Scientific Inc., Siemens Healthineers AG, Becton, Dickinson and Company, Bio-Rad Laboratories Inc., bioMérieux, QuidelOrtho Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Professional Diagnostics Market Emerging Trajectories
Next-generation sequencing throughput gains and artificial intelligence classification tools are restructuring competitive advantage around data processing speed rather than analytical sensitivity alone.
Multiplexed molecular panels is bifurcating infectious disease diagnostics into high-complexity reference laboratory workflows and simplified syndromic screening platforms. Hospital laboratories with existing PCR infrastructure upgrade to expanded respiratory panels, while point-of-care settings adopt cartridge-based systems with pre-validated pathogen menus. This technology is bifurcating vendor strategies between capital-intensive automation suites and disposable-consumable business models.
European Union In Vitro Diagnostic Regulation enforces Unique Device Identification traceability and periodic safety update reporting for all CE-marked devices. Manufacturers restructure quality management systems to accommodate post-market clinical follow-up obligations that extend beyond traditional vigilance requirements. Smaller reagent suppliers without established European notified body relationships face market exit pressures as certification costs escalate.
Health system procurement committees now bundle analyzer placement with multi-year reagent supply commitments and uptime service guarantees. Original equipment manufacturers displace independent service organizations through captive maintenance contracts that lock in consumable volumes. United States integrated delivery networks lead this contracting evolution, with similar structures emerging in German hospital alliances and Japanese clinical laboratory chains.
Professional Diagnostics Market Segmentation
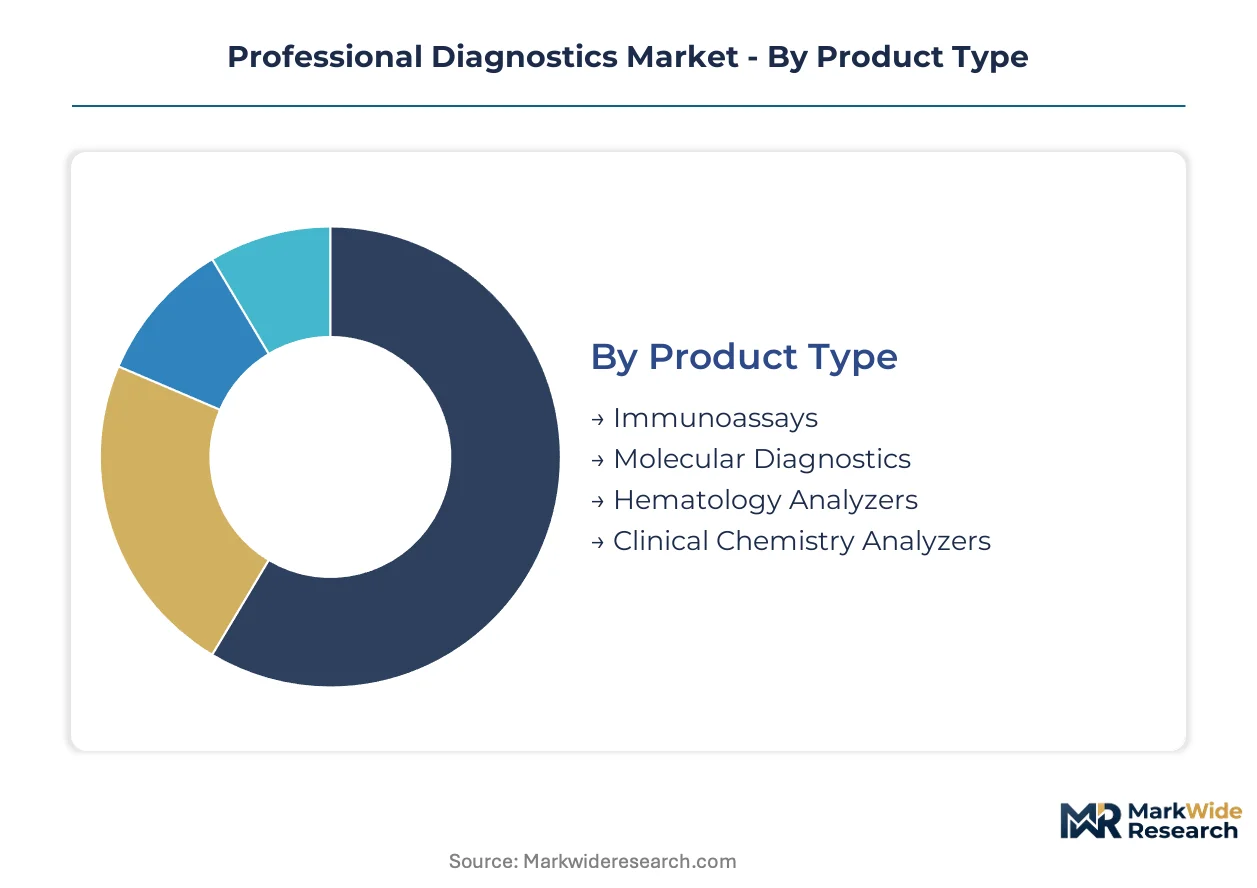
Professional diagnostics vendors configure product portfolios around four intersecting dimensions that determine pricing power, service attach rates, and regulatory pathway selection. Each segmentation axis carries distinct margin structures and capital intensity requirements that shape competitive positioning.
Product Type:
Margin pools concentrate in molecular diagnostics and immunoassays, where reagent annuity streams offset instrument placement costs.
- Molecular Diagnostics:PCR and next-generation sequencing platforms detect nucleic acid signatures with analytical sensitivity reaching single-copy detection. Demand clusters in United States oncology networks and infectious disease reference laboratories as companion diagnostic requirements expand. This segment is climbing the fastest as culture-based methods face displacement.
- Immunoassays:Antibody-antigen binding reactions measured through chemiluminescence or fluorescence dominate high-volume metabolic and cardiac marker testing. Hospital laboratories in Germany and Japan anchor purchasing concentration for automated immunoassay lines.
- Hematology Analyzers:Cell counting and differential platforms process complete blood count panels with throughput exceeding 100 samples hourly.
- Clinical Chemistry Analyzers:Spectrophotometric and ion-selective electrode systems quantify electrolytes, enzymes, and metabolites in serum and plasma matrices.
Molecular diagnostics holds installed capacity. Immunoassays is rotating up the share rankings.
End User:
Customer type determines contract structure, with integrated delivery networks commanding enterprise pricing distinct from spot purchases.
- Hospitals:Tertiary care centers deploy high-throughput automation suites with middleware integration to electronic health records. United States health systems consolidate multi-site laboratory operations under single vendor relationships.
- Laboratories:Independent and hospital-affiliated reference labs specialize in esoteric testing beyond routine panel capabilities. European Union IVDR compliance costs are forcing consolidation among smaller independent operators.
- Clinics:Urgent care and physician office settings favor CLIA-waived instruments with minimal operator training requirements.
- Homecare:Patient-operated devices for glucose monitoring and coagulation testing generate recurring reagent subscription revenue.
Hospitals command the capital deployment. Clinics is expanding most quickly.
Technology:
Technology selection dictates regulatory complexity and time-to-market, with point-of-care pathways offering accelerated clearance timelines.
- Point-of-Care Testing:Cartridge-based and handheld devices deliver results within minutes at the site of patient care. Emergency departments and retail health clinics in the United States drive placement volume for waived chemistry and immunoassay platforms.
- PCR:Thermal cycling amplification remains the gold standard for infectious disease and genetic testing with established reimbursement codes.
- ELISA:Enzyme-linked immunosorbent assays provide cost-effective batch processing for research and lower-complexity clinical applications.
- Next-Generation Sequencing:Massively parallel sequencing platforms enable comprehensive genomic profiling for oncology and rare disease diagnostics.
PCR holds the installed base. Point-of-Care Testing is gaining share fastest.
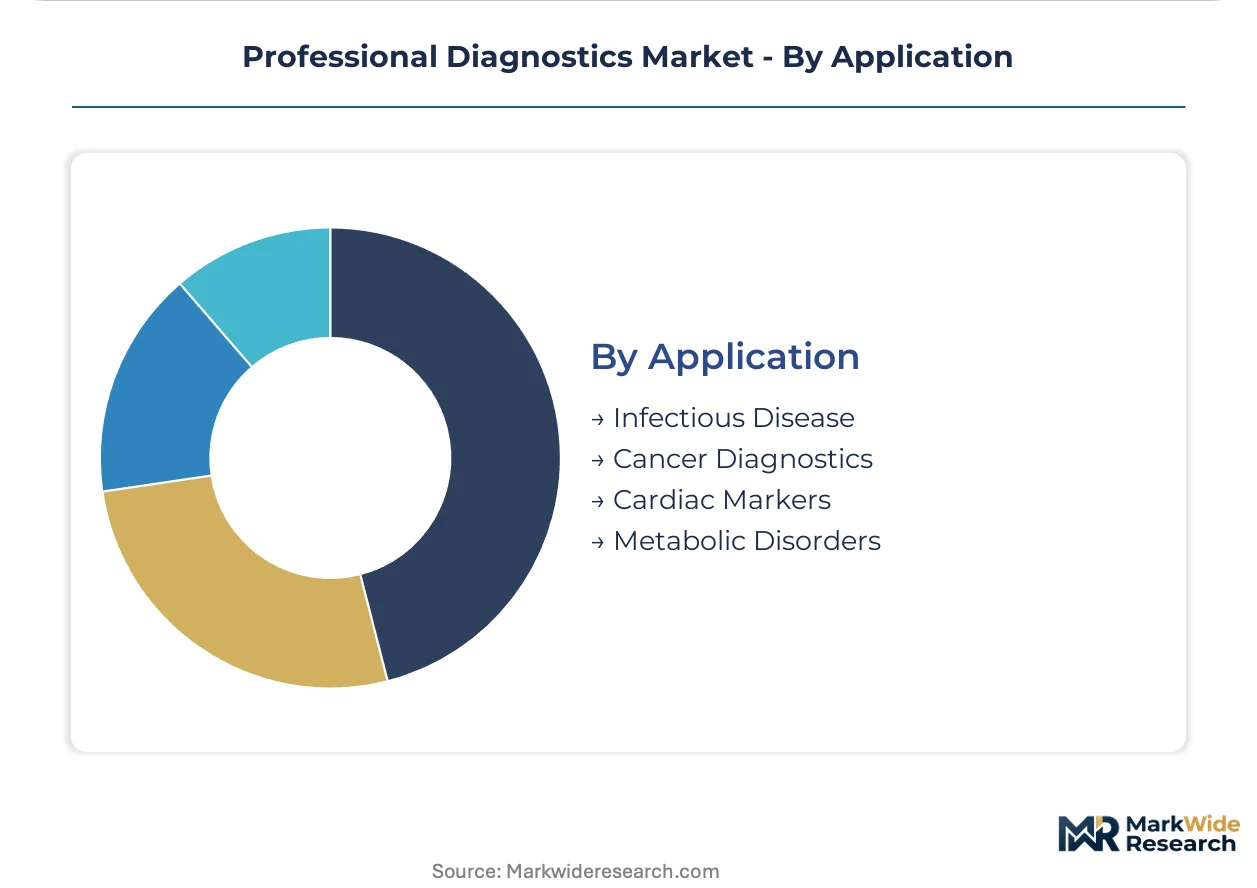
Application:
Disease area focus determines competitive intensity, with oncology commanding premium pricing and infectious disease driving volume scale.
- Infectious Disease:Syndromic respiratory panels and bloodstream pathogen detection command high test frequency in hospital settings. Multiplexed molecular assays for sepsis and antimicrobial resistance surveillance are expanding in United States and German critical care units.
- Cancer Diagnostics:Tissue-based biomarker testing and liquid biopsy platforms guide therapeutic selection and monitoring. Companion diagnostic co-development with pharmaceutical sponsors anchors revenue stability.
- Cardiac Markers:Troponin and natriuretic peptide testing supports emergency department triage and heart failure management protocols.
- Metabolic Disorders:Diabetes, lipid, and thyroid function panels constitute the highest test volume category with commoditized pricing dynamics.
Infectious Disease holds throughput leadership. Cancer Diagnostics is ascending the growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems exhibit the lowest price elasticity for high-throughput automation suites, while clinics in emerging markets prioritize waived-test platforms with minimal capital commitment. German hospital procurement demonstrates intermediate sensitivity, bundling analyzer placement with long-term service contracts. Japanese clinical laboratory chains anchor premium pricing for quality-accredited systems.
United States
Integrated delivery networks consolidate multi-site laboratory purchasing under enterprise contracts exceeding 500 million dollars annually. FDA companion diagnostic premarket pathways accelerate co-development timelines with oncology therapeutics. The Boston-Cambridge corridor concentrates liquid biopsy platform developers serving academic medical centers.
Germany
Hospital alliances aggregate demand for automated immunoassay lines across regional laboratory networks. EU In Vitro Diagnostic Regulation enforces stricter clinical evidence standards and post-market surveillance obligations for CE-marked devices. The Rhine-Ruhr metropolitan region hosts reference laboratories specializing in esoteric molecular testing.
Japan
Clinical laboratory chains drive placement of high-throughput hematology and chemistry analyzers with middleware integration requirements. PMDA quality management system inspections extend validation timelines for novel platform launches. The Kansai region around Osaka anchors domestic reagent manufacturing for export markets.
China
Provincial hospital networks expand PCR infrastructure for infectious disease surveillance and cancer biomarker detection. NMPA streamlined review pathways for innovative diagnostics accelerate market entry for domestic manufacturers. The Yangtze River Delta clusters contract reagent producers supplying both domestic and export markets.
India
Corporate hospital chains and diagnostic networks deploy point-of-care platforms in tier-2 and tier-3 cities lacking centralized laboratory access. CDSCO medical device rules mandate local clinical trials for novel platform categories. Maharashtra and Karnataka states concentrate diagnostic instrument distributors serving South Asian markets.
Professional Diagnostics Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Multinational conglomerates with diversified life science portfolios anchor the premium automation segment, while specialized molecular diagnostic firms occupy high-growth niches. Regional champions compete on reagent cost and local service density. Dominant competitive moves include captive maintenance contracts that lock in consumable volumes, and strategic partnerships with pharmaceutical sponsors for companion diagnostic co-development.
Among Swiss-based conglomerates, F. Hoffmann-La Roche Ltd exemplifies the integrated diagnostics-to-pharmaceuticals archetype with deep companion diagnostic pipelines. Abbott Laboratories represents the point-of-care expansion strategy, leveraging waived-test platform density in decentralized settings. Siemens Healthineers AG anchors the hospital automation tier through magnetic resonance diagnostics integration with core laboratory systems.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| Siemens Healthineers AG |
| Becton, Dickinson and Company |
| Bio-Rad Laboratories Inc. |
| bioMérieux |
| QuidelOrtho Corporation |
| Others |
Supply Flow & Price Mechanics
High-throughput analyzer utilization rates above 80% anchor unit economics for hospital laboratory automation, concentrating manufacturing scale among vendors with multi-thousand installed bases and compressing price floors for mid-tier entrants lacking comparable service network density.
Pricing Analysis
CLIA complexity classification dictates the pricing tier structure across instrument platforms, separating high-complexity molecular systems from waived point-of-care devices. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance pathway investment, with companion diagnostic platforms commanding royalty-linked models. Cost compression in standard-tier immunoassays is intensifying because integrated delivery networks bundle multi-year reagent commitments with uptime guarantees. Clinics and urgent care settings exhibit highest price sensitivity, while United States academic medical centers show lowest elasticity for automated lines with middleware integration.
Supply Chain Analysis
China and the United States anchor reagent manufacturing for polymerase chain reaction chemistries and fluorescent dye synthesis respectively. Germany and Japan feed precision optical components and ion-selective electrodes into analyzer assembly. Rare earth element sourcing for optical detection reagents rests on concentrated mining operations, creating single-source vulnerability for immunoassay manufacturers. Distribution runs through captive service organizations that lock in consumable volumes through multi-year maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, where FDA premarket notification history and established CLIA-waived product lines create switching costs that delay competitive displacement.
For Market Incumbents: Compound installed base advantages by embedding AI-assisted interpretation modules into existing middleware architectures, deepening reagent annuity streams. Extend captive maintenance contracts to independent reference laboratories facing IVDR compliance cost pressures. Prioritize backward integration into fluorescent dye production to offset rare earth pricing volatility.
For New Entrants and Emerging Players: Lead with liquid biopsy platforms targeting community oncology practices previously dependent on centralized reference laboratory access. Focus initial deployment on tier-2 Indian cities where corporate hospital chains expand point-of-care infrastructure without legacy analyzer commitments. Pursue CDSCO regulatory pathways that mandate local clinical trials as competitive barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized molecular diagnostic firms with companion diagnostic pipelines anchored to pharmaceutical co-development agreements. Five-to-ten year viability hinges on algorithm-driven diagnostic interpretation capabilities that augment pathologist workforce constraints. Monitor FDA premarket review pathway expansion for AI-assisted histopathology as inflection indicator for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA streamlined review pathways embed diagnostic requirements into oncology therapeutic approvals. |
| CLIA-Waived Platform Expansion | Urgent care and retail health settings process chemistry panels without laboratory personnel certification. |
| AI-Assisted Pathology Integration | Algorithm-driven screening augments specialist workforce capacity in underserved United States regions. |
| Middleware-EHR Integration | Proprietary analyzer software connections to hospital electronic health records extend deployment timelines. |
| Reagent Supply Concentration | Contract manufacturers for PCR chemistry create single-source vulnerability for molecular diagnostic workflows. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across hospital laboratory directors, reference laboratory technical directors, CLIA-waived clinic operators, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU IVDR notified body guidance documents. Bottom-up instrument placement and reagent volume estimates triangulated against top-down health system capital expenditure patterns.
Across the analysis window, projections incorporate product type segmentation by molecular diagnostics, immunoassays, hematology, and clinical chemistry alongside technology tier by point-of-care, PCR, and next-generation sequencing platforms. CAGRs were derived from installed base expansion rates, reagent consumption per analyzer, and pricing trajectory assumptions for waived versus high-complexity testing. Forecast inputs include companion diagnostic co-development pipeline density and IVDR compliance cost escalation for European market entry.
Forecasts assume regulatory continuity in FDA premarket notification pathways and EU IVDR post-market surveillance obligations; material policy shifts would require re-modeling. Specific risks include fluorescent dye supply disruption, cross-trained technologist shortage acceleration, and payer coverage restriction for algorithm-driven diagnostic interpretations. Recalibration cycles align with material shifts in companion diagnostic approval velocity and health system consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Phytopathological Disease Diagnostics Market
Diagnostics
Global Tissue Diagnostics Market
Diagnostics
Europe Blood Screening Market
Diagnostics
Helicobacter Pylori (H. Pylori) Diagnostics Market
Diagnostics
Immunoassay Interference Blocker Market
Diagnostics
Elisa Tests Market
Diagnostics
Asia-Pacific Radioimmunoassay Market
Diagnostics
Antimicrobial Resistance Diagnostics Market
Diagnostics
Semen Analysis Systems Market
Diagnostics
Global Women's Health Diagnostics Market
Diagnostics
Global Chlamydia Infection Diagnostics Market
Diagnostics
Digital Companion Diagnostics Market
Diagnostics
Europe Kidney Cancer Diagnostics Market
Diagnostics
Global Diagnostic Radiopharmaceuticals and Contrast Media Market
Diagnostics
Tissue Transglutaminase Test Market
Diagnostics
Asia Pacific in Vitro Diagnostics Market