
 Cervical Cancer Diagnostic Tests Market | 2026-2036
Cervical Cancer Diagnostic Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Cervical Cancer Diagnostic Tests Market Analysis
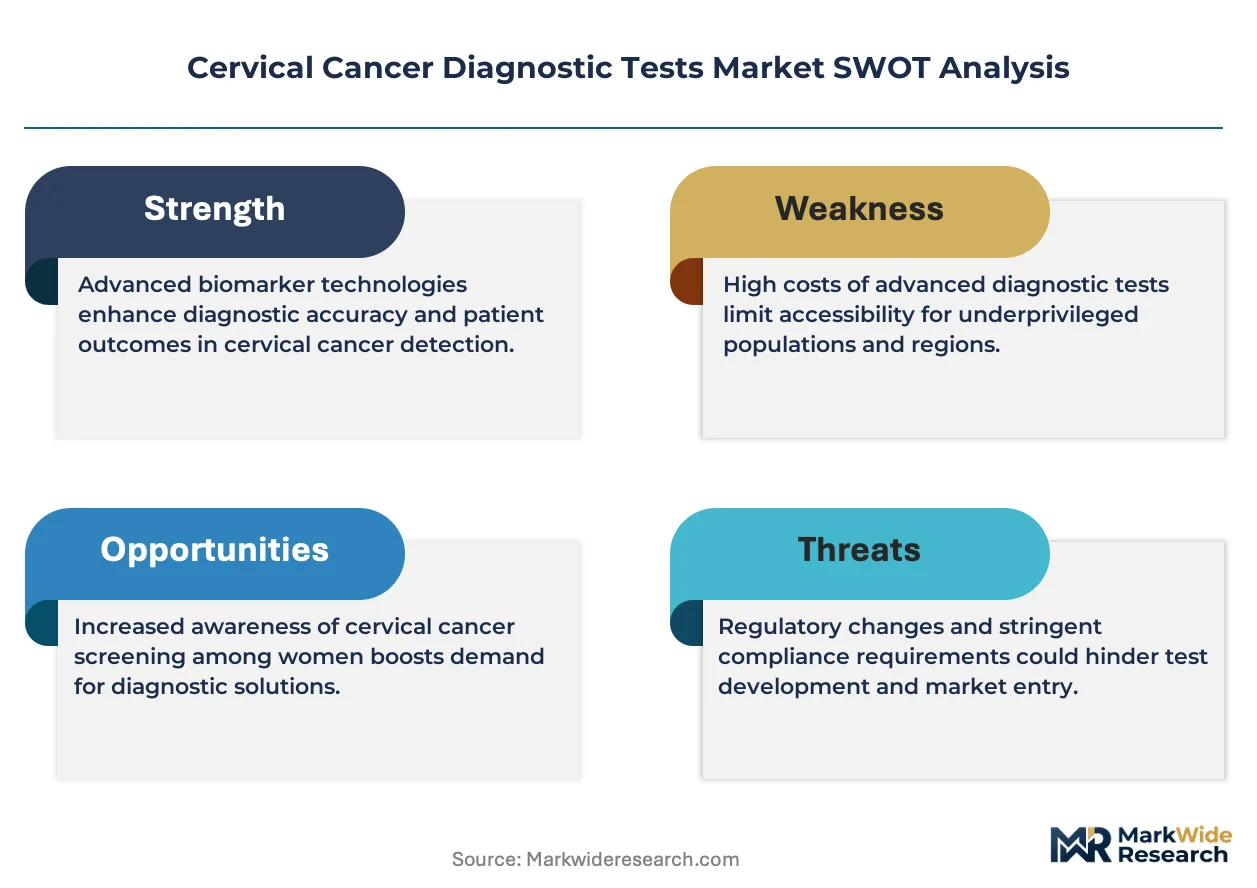
A capital-intensity divergence between integrated platform developers and point-of-care specialists is reorganizing competitive tiers in cervical cancer diagnostics. Abbott Laboratories leverages its broad molecular diagnostics infrastructure to sustain high-throughput HPV screening contracts with centralized laboratories. Hologic, Inc. anchors its position through proprietary liquid-based cytology systems that dominate North American screening workflows.
Cervical cancer diagnostic tests encompass cytological, molecular, and imaging-based methods designed to detect precancerous lesions or invasive carcinoma in the cervix uteri. HPV DNA assays utilizing PCR amplification achieve analytical sensitivity below one picogram of viral DNA, enabling detection of high-risk oncogenic subtypes before morphological changes appear. DNA Probes and PCR technologies command the largest share of the technology segment due to established clinical validation and automated platform integration. Point-of-Care Testing within the delivery mode dimension represents the fastest-expanding structural pocket, driven by decentralized screening initiatives in resource-limited settings where laboratory infrastructure remains sparse.
FDA premarket approval requirements and EMA in vitro diagnostic regulations shape assay development timelines and clinical evidence standards for market entry. WHO prequalification programs for HPV tests influence procurement decisions by ministries of health in low- and middle-income countries. Stakeholders must monitor evolving reimbursement thresholds for primary HPV screening versus cytology co-testing as health technology assessment bodies recalibrate cost-effectiveness benchmarks.
Market Dynamics
Primary HPV screening protocols are compressing cytology volumes while expanding molecular assay throughput requirements across laboratory networks. This transition is redistributing capital allocation between centralized high-throughput platforms and decentralized point-of-care systems.
Growth Catalysts
- WHO prequalification pathways:Ministries of health in low- and middle-income countries now procure validated HPV assays through consolidated tender mechanisms, accelerating test penetration where laboratory infrastructure previously constrained access.
- United States reimbursement alignment:Commercial payers and Medicare Advantage plans increasingly cover primary HPV screening without cytology co-testing, removing utilization barriers for molecular-first protocols.
- PCR platform automation:Integrated sample-to-result systems reduce hands-on time and technician skill requirements, enabling screening program expansion in nurse-led clinical settings.
Market Restraints
- Reagent supply concentration:Polymerase enzymes and fluorescent probe chemistries depend on a limited set of specialized biochemical suppliers, creating vulnerability to batch variability or geographic disruption.
- FDA premarket approval timelines:Clinical validation requirements for novel HPV genotyping assays extend development cycles, compressing commercialization windows before patent expiration.
- Cytology infrastructure sunk costs:Health systems with substantial investments in liquid-based cytology processors and trained cytopathologists face asset stranding risks during protocol transitions.
Strategic Opportunities
- Self-sampling regulatory expansion:FDA and Health Canada pathways for vaginal self-collection devices open direct-to-patient channels, bypassing clinic-based pelvic examination barriers.
- Artificial intelligence cytology:Deep learning algorithms applied to digital whole-slide imaging enable automated primary screening, addressing pathologist workforce shortages in Germany and Japan.
- Community health worker deployment:Portable thermal cycler and isothermal amplification platforms permit screening in rural India and sub-Saharan African settings lacking cold chain logistics.
Industry Challenges
- Cytopathologist training pipeline gaps:Morphologic interpretation expertise is contracting as medical residents prioritize molecular pathology fellowships, creating quality assurance vulnerabilities during hybrid screening periods.
- Laboratory information system integration:HPV genotyping results require structured data exchange with cancer registries and patient notification systems, imposing interoperability costs on smaller hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cervical Cancer Diagnostic Tests Market |
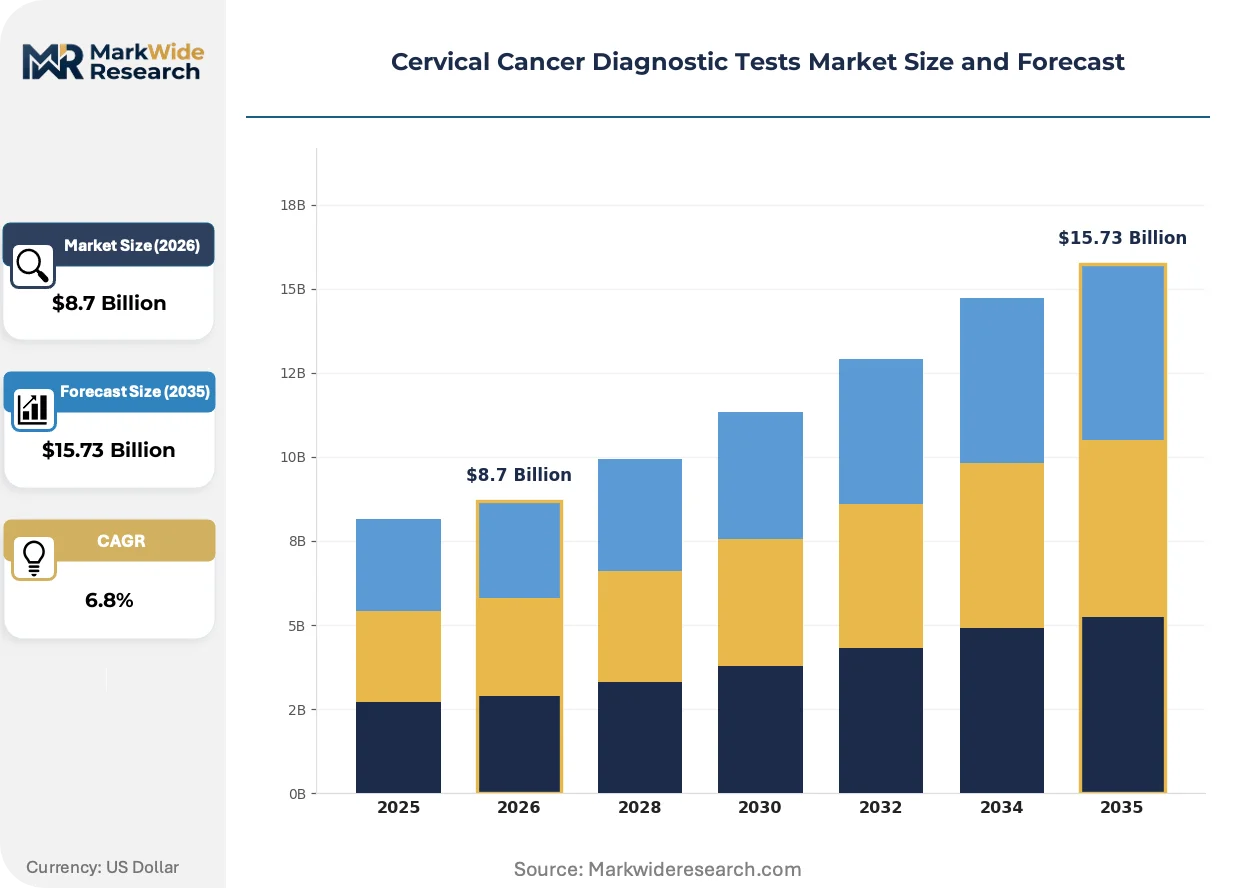
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Papanicolaou Test, HPV Test, Liquid-Based Cytology, Colposcopy Technology: DNA Probes, PCR, Microarray, Immunohistochemistry End User: Hospitals, Diagnostic Laboratories, Cancer Clinics, Research Institutions Delivery Mode: Laboratory Testing, Point-of-Care Testing, Home Testing, Telemedicine |
| Companies Covered | Abbott Laboratories, Becton, Dickinson and Company, Hologic, Inc., F. Hoffmann-La Roche Ltd., QIAGEN, CooperSurgical, Inc., DYSIS Medical, Inc., Seegene, Inc., Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cervical Cancer Diagnostic Tests Market Emerging Trajectories
Next-generation sequencing and isothermal amplification chemistries are fragmenting the technology base that has been dominated by real-time PCR for two decades. These platforms promise simplified workflow and expanded genotyping resolution.
mRNA-based HPV oncogene expression assays are supplanting DNA detection methods in tertiary care settings where risk stratification demands higher specificity. Oncology departments in the United States and Germany are adopting these platforms to reduce colposcopy referral rates among transient infections. The shift is compressing demand for repeat cytology in HPV-positive patients while elevating molecular pathology service line importance.
EMA In Vitro Diagnostic Regulation implementation is elevating clinical evidence requirements for HPV assay CE marking, particularly for self-sampling claims and home-use devices. Manufacturers must now submit prospective clinical studies rather than analytical bridging data alone. This regulatory elevation is favoring established assay developers with existing clinical trial infrastructure while raising capital barriers for emerging competitors.
Direct contracting between national screening programs and diagnostic manufacturers is displacing distributor-mediated procurement in high-volume markets. Brazil's national cancer institute and England's NHS Screening Programme now negotiate multi-year supply agreements with price-volume mechanisms. This channel consolidation is compressing margin structures for regional distributors while securing volume commitments for platform developers.
Cervical Cancer Diagnostic Tests Market Segmentation
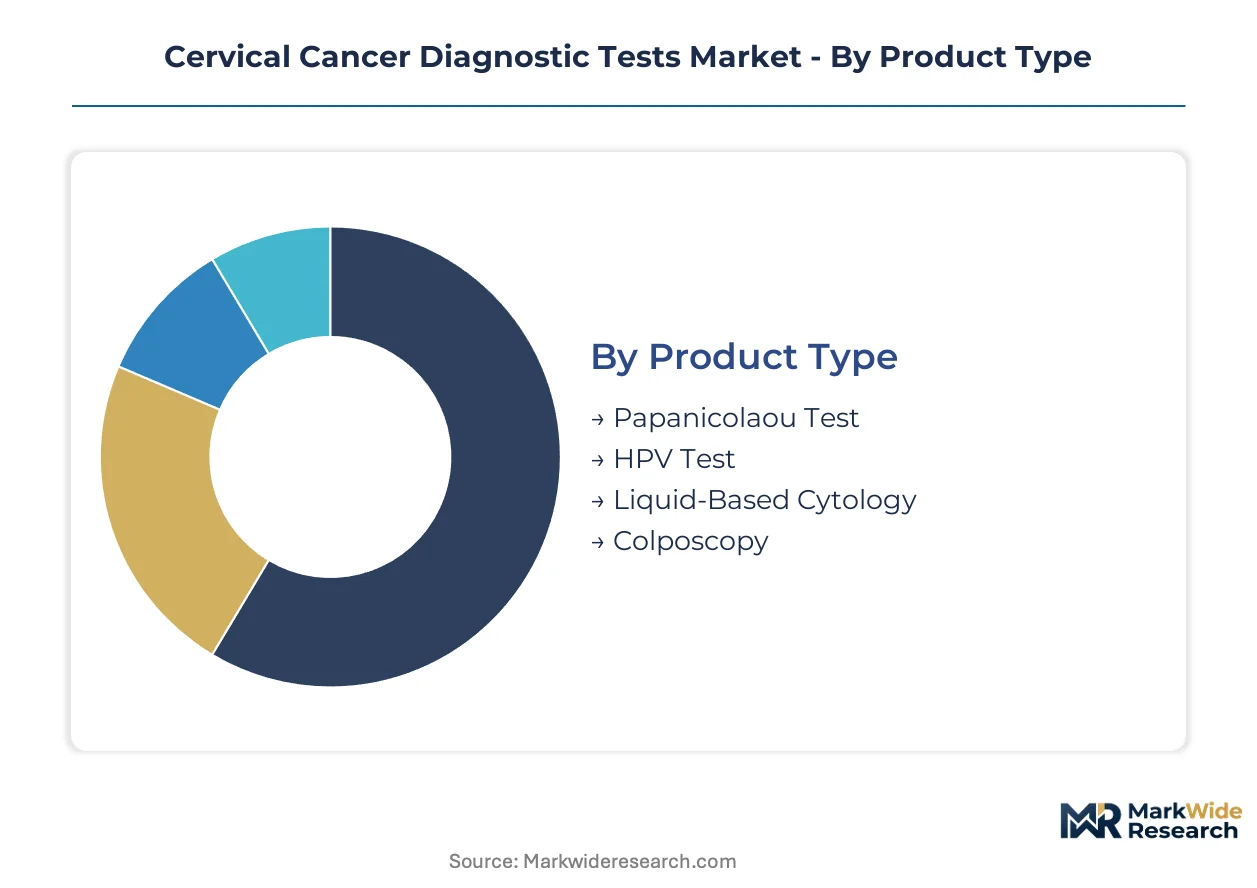
Diagnostic workflows for cervical cancer screening fragment across multiple technical and operational dimensions, each commanding distinct procurement channels and reimbursement pathways. Understanding these segment boundaries clarifies where platform developers concentrate R&D resources versus where point-of-care specialists capture decentralized volume.
Product Type:
Hospital procurement committees and national screening programs allocate capital across these modalities based on infrastructure maturity and protocol transition timelines, with centralized laboratories favoring high-throughput systems while community clinics prioritize accessible formats.
- HPV Test:Molecular assays detecting high-risk oncogenic DNA sequences through nucleic acid amplification. Demand concentrates in the United States and Germany where primary HPV screening protocols now reimburse molecular-first algorithms without cytology co-testing, compressing turnaround times for negative results.
- Papanicolaou Test:Conventional smear cytology requiring morphologic interpretation by trained cytopathologists. Volume remains substantial in Japan and developing health systems where liquid-based cytology infrastructure investments create asset stranding concerns during protocol transitions.
- Liquid-Based Cytology:Automated cell preservation and monolayer preparation systems that reduce sampling error rates versus conventional smears. Laboratories in North American hospital networks maintain installed bases of these processors.
- Colposcopy:Visual examination with magnification following abnormal screening results, performed in gynecologic oncology departments and specialized clinics. Referral volumes fluctuate with screening test specificity improvements.
By volume, Papanicolaou testing retains residual share in legacy systems. By growth pace, HPV testing is expanding most quickly as national programs convert to molecular-primary protocols.
Technology:
Assay developers select technical platforms based on sensitivity requirements, automation compatibility, and intellectual property positioning, with cost tiers separating research-grade instrumentation from screening-scale deployment.
- PCR:Real-time amplification achieving analytical sensitivity below one picogram of viral DNA with automated sample-to-result integration. Centralized laboratories in the United States and Germany deploy these platforms for high-throughput screening contracts.
- DNA Probes:Hybridization-based detection of specific HPV genotypes without amplification, offering simplified workflow at moderate sensitivity. Community health programs in resource-limited settings favor these for reduced cold chain dependency.
- Microarray:High-plex genotyping panels enabling simultaneous detection of multiple oncogenic subtypes. Tertiary care centers utilize these for risk stratification and research applications.
- Immunohistochemistry:Antibody-based protein detection applied to tissue biopsies for definitive cancer diagnosis. Pathology departments employ these for confirmatory testing following positive screening results.
PCR platforms command the largest installed base. Microarray adoption is climbing the fastest as genotyping resolution becomes clinically actionable.
End User:
Customer type determines purchasing authority, with integrated delivery networks negotiating enterprise contracts while independent laboratories respond to reference testing demand from physician practices.
- Diagnostic Laboratories:High-throughput processing centers serving multiple healthcare providers under capitated or fee-for-service arrangements. These facilities in the United States and Japan drive automation requirements for HPV assay platforms.
- Hospitals:Integrated health systems combining screening, diagnosis, and treatment within single organizations. Academic medical centers in Germany maintain cytopathology training programs that sustain morphologic interpretation expertise.
- Cancer Clinics:Specialized gynecologic oncology practices managing abnormal screening referrals and treatment planning. These settings in urban United States markets adopt mRNA-based oncogene expression assays for risk stratification.
- Research Institutions:Universities and government laboratories validating novel biomarkers and screening algorithms. WHO prequalification programs influence procurement by these entities for low- and middle-income country implementation studies.
Diagnostic laboratories process the highest test volumes. Cancer clinics are gaining share fastest as risk-stratified protocols concentrate complex cases in specialized settings.
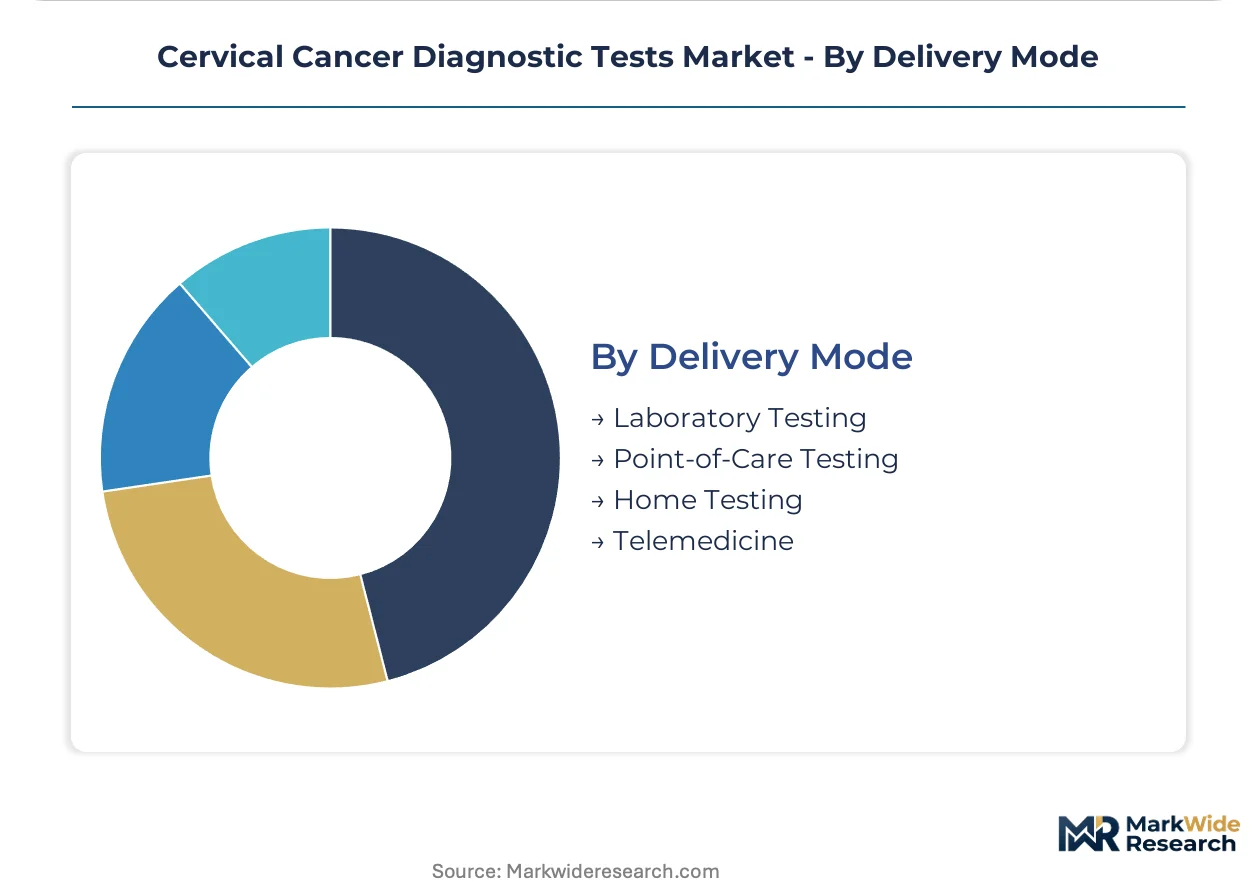
Delivery Mode:
Distribution configuration shapes regulatory requirements, with laboratory-developed tests facing different validation standards than commercial kits, and home collection devices triggering distinct FDA and EMA pathways.
- Laboratory Testing:Centralized specimen processing with standardized quality control and result reporting to electronic health records. This channel dominates reimbursement in the United States, Germany, and Japan.
- Point-of-Care Testing:Decentralized rapid assays performed in clinical settings without permanent laboratory infrastructure. India's community health worker programs and sub-Saharan African screening initiatives are deploying portable thermal cycler platforms.
- Home Testing:Self-collection devices with mail-in laboratory processing or direct-to-consumer result reporting. FDA and Health Canada regulatory expansions for vaginal self-sampling are opening direct-to-patient channels.
- Telemedicine:Remote consultation and result delivery platforms integrating with digital health infrastructure. These services in the United States address geographic access barriers for follow-up colposcopy scheduling.
Laboratory testing maintains volume leadership. Home testing is expanding most steeply as regulatory barriers to self-sampling devices erode.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where primary HPV screening reimbursement compresses cost-per-test floors, while India and Brazil operate on tender-driven procurement that fragments margin structures.
United States
FDA premarket approval pathways and Medicare Advantage reimbursement alignment drive molecular assay adoption in centralized laboratories. Commercial payers now cover primary HPV screening without cytology co-testing, removing utilization barriers. Academic medical centers in Boston and the Research Triangle anchor clinical validation studies for next-generation sequencing platforms.
Germany
EMA In Vitro Diagnostic Regulation implementation elevates clinical evidence requirements for HPV assay CE marking, favoring established developers with trial infrastructure. Health technology assessment bodies recalibrate cost-effectiveness benchmarks for molecular-first protocols. Cytopathology training programs in Bavaria and North Rhine-Westphalia sustain morphologic interpretation expertise during hybrid screening transitions.
Japan
PMDA regulatory frameworks shape assay development timelines for HPV genotyping platforms. National reimbursement covers routine cytology and HPV co-testing, sustaining dual-modality workflows. Tokyo and Osaka metropolitan clusters concentrate high-throughput diagnostic laboratory capacity serving aging screening populations.
India
Community health worker deployment of portable thermal cycler platforms addresses rural screening gaps where cold chain logistics remain sparse. WHO prequalification programs influence ministry of health procurement through consolidated tender mechanisms. Maharashtra and Karnataka states pilot decentralized point-of-care testing initiatives in nurse-led clinical settings.
Brazil
ANVISA regulatory pathways govern HPV assay registration for national cancer institute supply agreements. Direct contracting between screening programs and manufacturers displaces distributor-mediated procurement, compressing margin structures. São Paulo and Rio de Janeiro concentrate gynecologic oncology referral capacity for abnormal screening follow-up.
Cervical Cancer Diagnostic Tests Market Vendor Landscape
Concentration sits with integrated molecular diagnostics conglomerates that sustain high-throughput screening contracts through automated platform infrastructure. The vendor base stratifies across three tiers: multinational conglomerates with broad assay portfolios, specialized cytology system developers, and emerging point-of-care specialists. Dominant competitive moves include strategic partnerships for self-sampling regulatory expansion and technology licensing for isothermal amplification chemistries.
Within the integrated platform tier, Abbott Laboratories and F. Hoffmann-La Roche Ltd. exemplify multinational conglomerates with established FDA and EMA approval pathways. Hologic, Inc. occupies a specialized position in liquid-based cytology systems. These three entities anchor distinct strategic archetypes: broad molecular infrastructure, proprietary sample preparation automation, and imaging-integrated diagnostic workflows respectively.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Becton, Dickinson and Company |
| Hologic, Inc. |
| F. Hoffmann-La Roche Ltd. |
| QIAGEN |
| CooperSurgical, Inc. |
| DYSIS Medical, Inc. |
| Seegene, Inc. |
| Thermo Fisher Scientific Inc. |
| Others |
Supply Flow & Price Mechanics
FDA premarket approval and EMA In Vitro Diagnostic Regulation certification tiers simultaneously gate supplier qualification and stratify price realization across HPV assay developers. Laboratories purchasing validated kits face premium pricing for FDA-cleared platforms versus moderate tiers for CE-marked alternatives, with procurement committees weighing reimbursement alignment against total cost of ownership.
Pricing Analysis
Configured-to-order pricing for integrated sample-to-result systems commands substantial premiums over standard reagent rental arrangements. Three-tier pricing structure across premium, standard, and economy levels separates automated high-throughput platforms from benchtop analyzers and manual DNA probe kits. Cost compression in the economy tier intensifies as WHO prequalification programs consolidate tender volumes for low- and middle-income country procurement. National screening programs exhibit lowest price sensitivity due to multi-year volume commitments, while independent diagnostic laboratories face acute margin pressure from capitated reimbursement.
Supply Chain Analysis
United States and Germany anchor automated platform manufacturing and reagent formulation for molecular diagnostics. China and India feed critical polymerase enzyme and fluorescent probe chemistries into upstream biochemical supply tiers. Single-source vulnerability concentrates in specialized nucleic acid amplification reagents, with geographic disruption risks elevated by limited qualified suppliers. Distribution runs through direct contracting between manufacturers and national screening programs, displacing regional distributor intermediaries in high-volume markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring revenue from assay reagent contracts and service agreements expands faster than capital equipment sales, positioning consumable attach rates as the critical profitability lever for platform developers.
For Market Incumbents: Fortify installed base defenses through backward integration into critical reagent chemistries and exclusive multi-year supply agreements with national screening programs. Isothermal amplification platforms from emerging competitors threaten PCR-dominant positions in point-of-care segments. Capacity addition in India and sub-Saharan African distribution hubs secures first-mover positioning in WHO prequalification procurement channels. For New Entrants and Emerging Players: Differentiate on self-sampling regulatory positioning and portable thermal cycler deployment for nurse-led clinical settings. Community health worker programs in rural India and sub-Saharan Africa represent the most penetrable white-space opportunity. Go-to-market execution should prioritize ANVISA and CDSCO registration pathways to capture ministry of health consolidated tenders. For Investors and Strategic Acquirers: EMA In Vitro Diagnostic Regulation implementation reshapes the acquisition landscape toward developers with existing clinical trial infrastructure and prospective validation data. Long-term viability centers on molecular assay portfolios with sustainable reagent pull-through economics. Acquisition target archetypes include point-of-care specialists with Health Canada self-sampling approvals. Signal to watch: FDA pathway expansions for home-collection devices as direct-to-patient channel inflection.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Ministries of health in low- and middle-income countries consolidate HPV assay procurement through validated tender mechanisms. |
| Self-Sampling Regulatory Expansion | FDA and Health Canada approvals for vaginal self-collection devices open direct-to-patient channels bypassing clinic barriers. |
| Artificial Intelligence Cytology Integration | Deep learning algorithms applied to digital whole-slide imaging address pathologist workforce shortages in Germany and Japan. |
| Isothermal Amplification Platform Development | Simplified workflow chemistries enable community health worker deployment in cold chain-constrained settings. |
| mRNA Oncogene Expression Assay Adoption | Tertiary care centers in the United States and Germany reduce colposcopy referral rates through higher-specificity risk stratification. |
Methodological Framework
Operator-level perspectives from clinical laboratory directors, hospital procurement committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA CE marking databases, WHO prequalification listings, and hospital procurement records. Bottom-up test volume modeling and top-down market sizing triangulated across technology, delivery mode, and end-user segmentation dimensions.
Sensitivity analysis framing examined variable assumptions across the projection horizon without specifying discrete year markers. Segmentation dimensions modeled include product type, technology platform, end-user category, and delivery mode, with geographic regulatory clusters as an additional cross-cutting layer. CAGRs derived from fitted growth curves applied to base-year estimates, incorporating HPV screening protocol transition timelines and reimbursement policy shifts as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained primary HPV screening adoption rates, stable reagent supply availability, and continued regulatory pathway convergence would require recalibration. Forecasts reflect documented assumptions regarding WHO prequalification program expansion and Medicare Advantage reimbursement alignment. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global STD Diagnostics Market
Diagnostics
Global Chemiluminescence Immunoassay (CLIA) Market
Diagnostics
At-Home Cancer Testing Market
Diagnostics
Creatine Kinase Reagent Market
Diagnostics
Global Chromoendoscopy Agents Market
Diagnostics
In Vitro Diagnostic (IVD) Reagent Market
Diagnostics
Global Saliva Collection and Diagnosis Market
Diagnostics
Elisa Tests Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
Rapid RNA Testing Kits Market
Diagnostics
China in Vitro Diagnostics Market
Diagnostics
Hypopituitarism Diagnostics Market
Diagnostics
Global HIV Diagnosis Market
Diagnostics
Latent Tuberculosis Infection Detection Market
Diagnostics
Antigen Skin Test Market
Diagnostics
Clostridium Diagnostics Market