
 Septicemia Diagnostic Testing Market | 2026-2036
Septicemia Diagnostic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Septicemia Diagnostic Testing Market Analytics
CLIA certification for high-complexity molecular testing is rotating the competitive landscape toward manufacturers with validated automated workflows. bioMérieux SA leverages its integrated blood culture and molecular identification platforms to dominate European hospital networks. Becton Dickinson and Company sustains market presence through its extensive distribution infrastructure for conventional culture systems. Danaher Corporation anchors its position via subsidiary-level control across sample-to-answer instrument portfolios.
Septicemia diagnostic testing encompasses laboratory and point-of-care methods designed to detect bloodstream pathogens and host biomarkers, typically employing nucleic acid amplification, mass spectrometry, or immunological detection with turnaround targets under 24 hours for mortality reduction. The primary purpose is enabling targeted antimicrobial therapy before septic shock progression. Molecular diagnostics commands the fastest expansion trajectory as hospitals replace slower culture-dependent protocols. Point-of-care testing occupies emerging margin pools in emergency department settings where time-to-result directly influences clinical decision velocity. Automated systems retain volume leadership in centralized laboratories processing high-throughput sepsis panels.
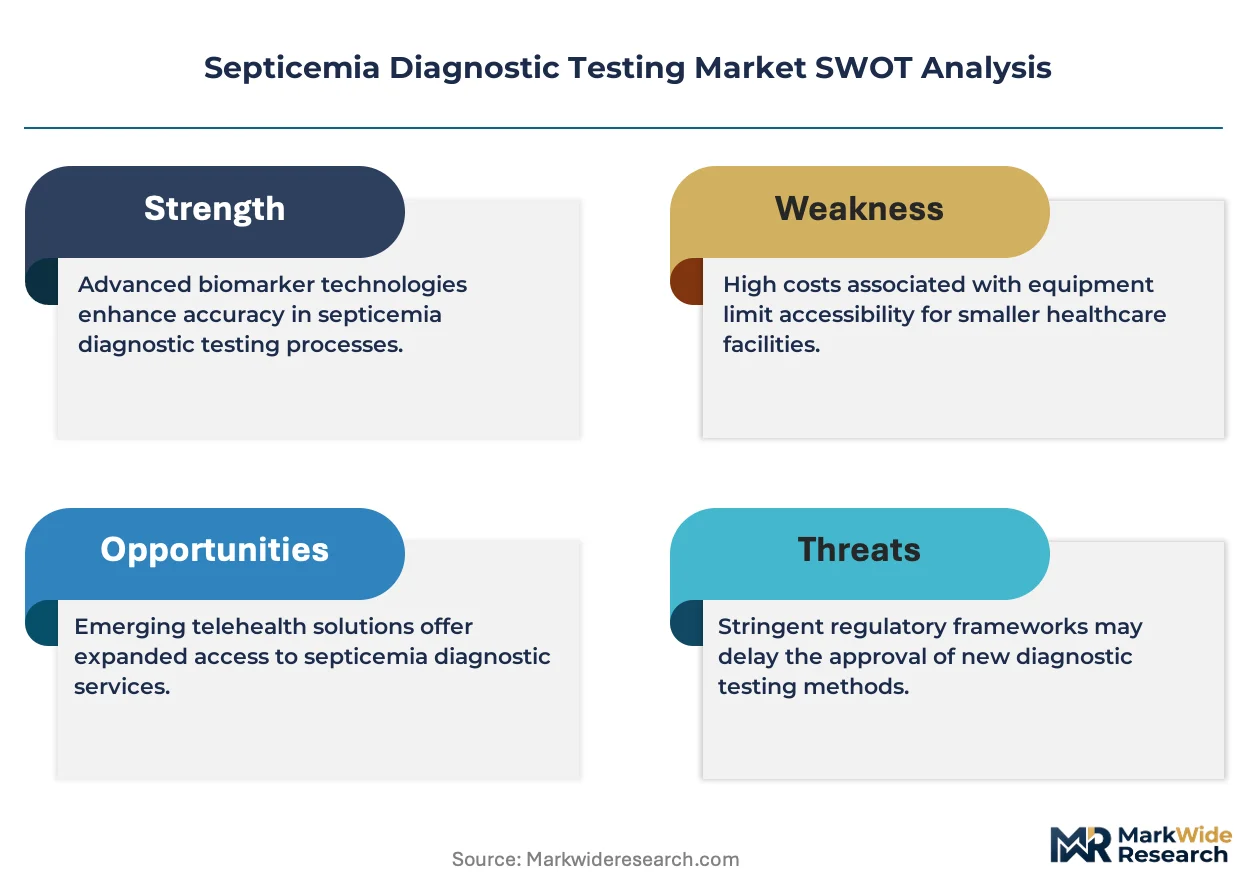
FDA 510(k) pathways and EMA CE-IVD frameworks shape product development timelines and performance claim substantiation for sepsis assays. CLIA complexity classifications determine where testing can occur, channeling innovation toward moderate-complexity platforms deployable outside reference laboratories. Stakeholders must monitor evolving CMS reimbursement decisions for multiplex sepsis panels, as coverage determinations will dictate whether point-of-care molecular adoption achieves economic viability against centralized laboratory economics.
Market Dynamics
Hospital consolidation into integrated delivery networks is compressing vendor lists and mandating platform standardization for sepsis diagnostics. Procurement committees now require interoperability with existing laboratory information systems and electronic health records as non-negotiable gate criteria.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated review timelines for moderate-complexity molecular platforms are shortening product commercialization cycles for manufacturers with validated automated workflows.
- Critical care infrastructure expansion:Germany, Japan, and the United States are deploying dedicated sepsis response teams requiring rapid diagnostic instrumentation.
- Host response biomarker integration:Multiplexed protein panels measuring procalcitonin and lactate alongside pathogen detection are improving clinical decision velocity in emergency departments.
Market Restraints
- Reimbursement fragmentation:CMS coverage determinations for multiplex sepsis panels remain inconsistent across Medicare Administrative Contractors, creating payment uncertainty.
- Capital equipment intensity:Automated sample-to-answer systems require substantial upfront investment, limiting adoption to tertiary care centers with dedicated microbiology budgets.
- Technical specificity limitations:Current molecular platforms cannot reliably detect polymicrobial bloodstream infections or antimicrobial resistance patterns without culture confirmation.
Strategic Opportunities
- Emergency department point-of-care deployment:CLIA-waived moderate-complexity platforms can capture decision-critical testing currently routed to centralized laboratories.
- EMA CE-IVD framework alignment:Harmonized performance standards across European member states reduce regulatory duplication costs for manufacturers seeking multi-country market access.
- Artificial intelligence-assisted interpretation:Machine learning algorithms analyzing biomarker trajectories alongside pathogen identification are enabling predictive severity scoring.
Industry Challenges
- Laboratory information system integration:Middleware compatibility gaps between novel molecular platforms and legacy hospital IT architectures delay implementation timelines.
- Specialized technologist scarcity:High-complexity molecular testing requires trained personnel with nucleic acid amplification expertise, constraining test volume expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Septicemia Diagnostic Testing Market |
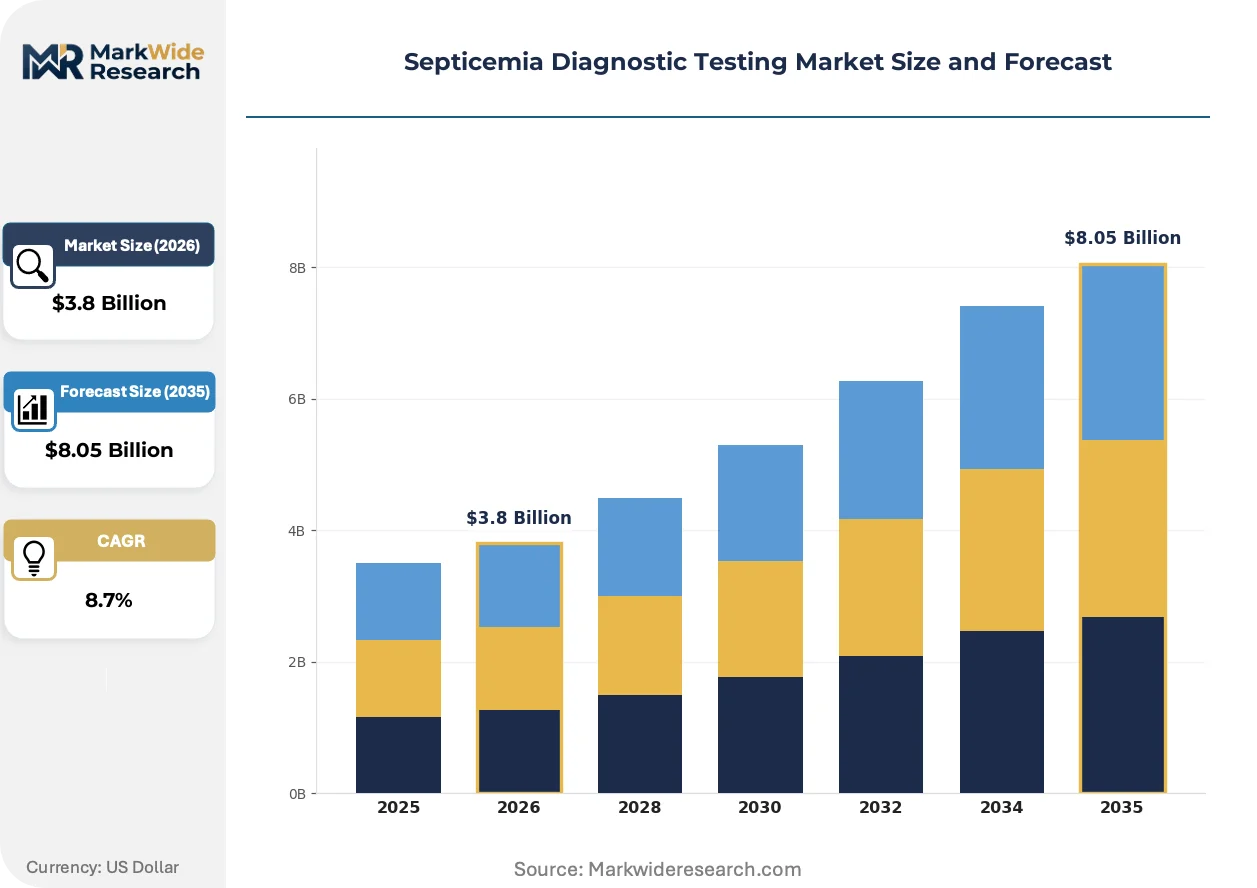
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cultures, PCR Tests, Immunoassays, Molecular Diagnostics Technology: Conventional Techniques, Automated Systems, Next Generation Sequencing, Point-of-Care Testing End User: Hospitals, Diagnostic Laboratories, Research Institutions, Outpatient Clinics Application: Blood Testing, Urine Testing, CSF Analysis, Tissue Samples |
| Companies Covered | bioMérieux SA, Becton Dickinson and Company, Danaher Corporation, Thermo Fisher Scientific, F. Hoffmann-La Roche Ltd, Abbott Laboratories, Bruker Corporation, Sysmex Corporation, T2 Biosystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Septicemia Diagnostic Testing Market Evolving Landscape
Digital pathology integration and machine learning classification are transforming how bloodstream infections are diagnosed and managed. These advances compress turnaround times while expanding the clinical information available at the point of therapeutic decision.
Next-generation sequencing for pathogen identification is displacing conventional blood culture workflows in reference laboratories with sufficient specimen volume and bioinformatics infrastructure. Academic medical centers in the United States and Germany are piloting metagenomic approaches capable of detecting unculturable organisms within six hours. This technology is displacing the multi-day incubation periods that currently delay targeted antimicrobial selection.
The European Union Medical Device Regulation is tightening clinical evidence requirements for in-vitro diagnostic performance claims. Manufacturers must now generate prospective diagnostic accuracy data rather than relying on analytical validation alone. High-throughput centralized laboratories face the steepest compliance costs as they recertify existing sepsis assay portfolios.
Hospital procurement committees are consolidating sepsis diagnostic contracts under enterprise-wide laboratory agreements. Single-source platform commitments replace best-of-breed instrument selection, bundling blood culture, molecular identification, and antimicrobial susceptibility testing. This concentration is most pronounced in United States integrated delivery networks managing multiple acute care facilities under unified governance.
Septicemia Diagnostic Testing Market Segmentation
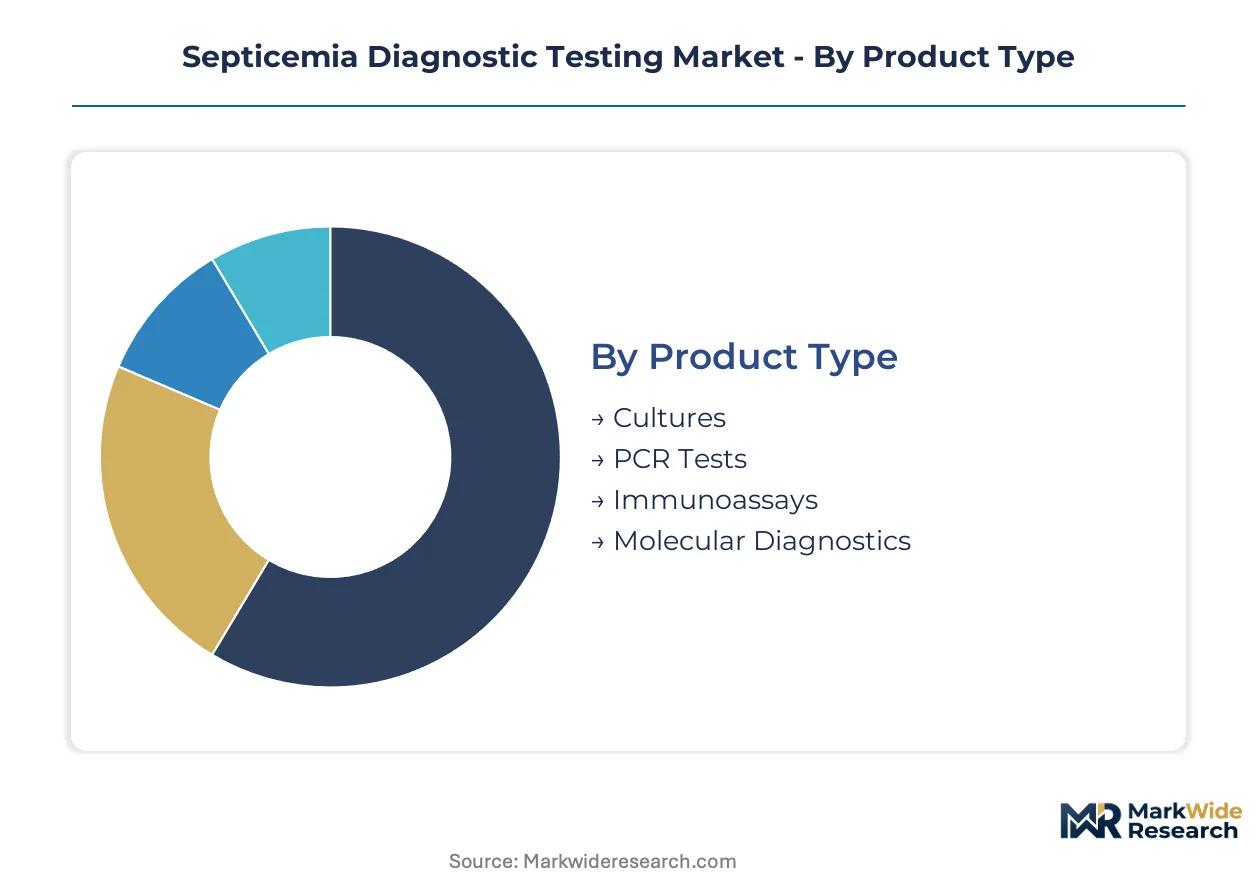
Segmentation in septicemia diagnostics reveals how clinical urgency, laboratory infrastructure, and reimbursement economics allocate revenue across testing modalities. Hospital procurement committees weight turnaround time against capital intensity when selecting platform categories.
Product Type:
Margin pools concentrate in molecular platforms where premium pricing offsets instrument amortization, while conventional methods compete on volume throughput.
- Molecular Diagnostics:Nucleic acid amplification platforms detect bloodstream pathogens within hours rather than days. United States tertiary care centers prioritize these systems for sepsis response teams despite higher per-test costs. FDA 510(k) clearance requirements for multiplex panels sustain manufacturer pricing power.
- Cultures:Blood culture systems remain the diagnostic backbone in resource-constrained settings, requiring 24-72 hour incubation periods. Germany's hospital networks retain substantial installed bases for antimicrobial susceptibility confirmation. Capital equipment intensity limits replacement cycles.
- PCR Tests:Targeted amplification assays deliver species-level identification for common sepsis pathogens. Moderate-complexity CLIA certifications expand deployment beyond reference laboratories.
- Immunoassays:Protein biomarker quantification supports severity stratification alongside pathogen detection. Procalcitonin and lactate panels integrate with emergency department workflows.
The dominant share belongs to Cultures, while Molecular Diagnostics is closing the gap fastest.
Technology:
Technology selection tracks laboratory budget tiers and specimen volume economics.
- Automated Systems:Sample-to-answer instruments consolidate nucleic acid extraction, amplification, and detection within closed cartridges. High-throughput centralized laboratories in Japan deploy these platforms for overnight batch processing. Interoperability with laboratory information systems determines vendor selection.
- Point-of-Care Testing:CLIA-waived platforms deliver results at the bedside within 60 minutes. United States emergency departments adopt these for antibiotic stewardship decisions where time-to-result directly influences mortality outcomes. Reimbursement parity with centralized testing remains contested.
- Next Generation Sequencing:Metagenomic approaches identify unculturable organisms and resistance determinants without pathogen-specific primers. Academic medical centers pilot these for complex polymicrobial infections.
- Conventional Techniques:Manual culture and biochemical identification persist in outpatient settings with limited capital budgets. Technologist training requirements constrain throughput expansion.
Automated Systems command the largest revenue base, though Point-of-Care Testing expands most quickly.
End User:
Customer concentration follows critical care infrastructure density and microbiology specialization.
- Hospitals:Integrated delivery networks negotiate enterprise-wide contracts bundling blood culture, molecular identification, and susceptibility testing. United States health systems standardize platforms across multiple acute care facilities to reduce training complexity and supply chain fragmentation.
- Diagnostic Laboratories:Reference laboratories process outsourced sepsis panels for smaller hospitals lacking on-site microbiology capacity. Germany's regional laboratory networks achieve economies of scale through centralized molecular testing.
- Outpatient Clinics:Limited service settings rely on send-out testing for suspected bloodstream infections. Rapid antigen tests occupy emerging niches for preliminary screening.
- Research Institutions:Academic centers validate novel biomarker signatures and host response algorithms. Prospective diagnostic accuracy studies support regulatory submissions.
Hospitals retain the dominant procurement volume, while Diagnostic Laboratories gain share through outsourcing consolidation.
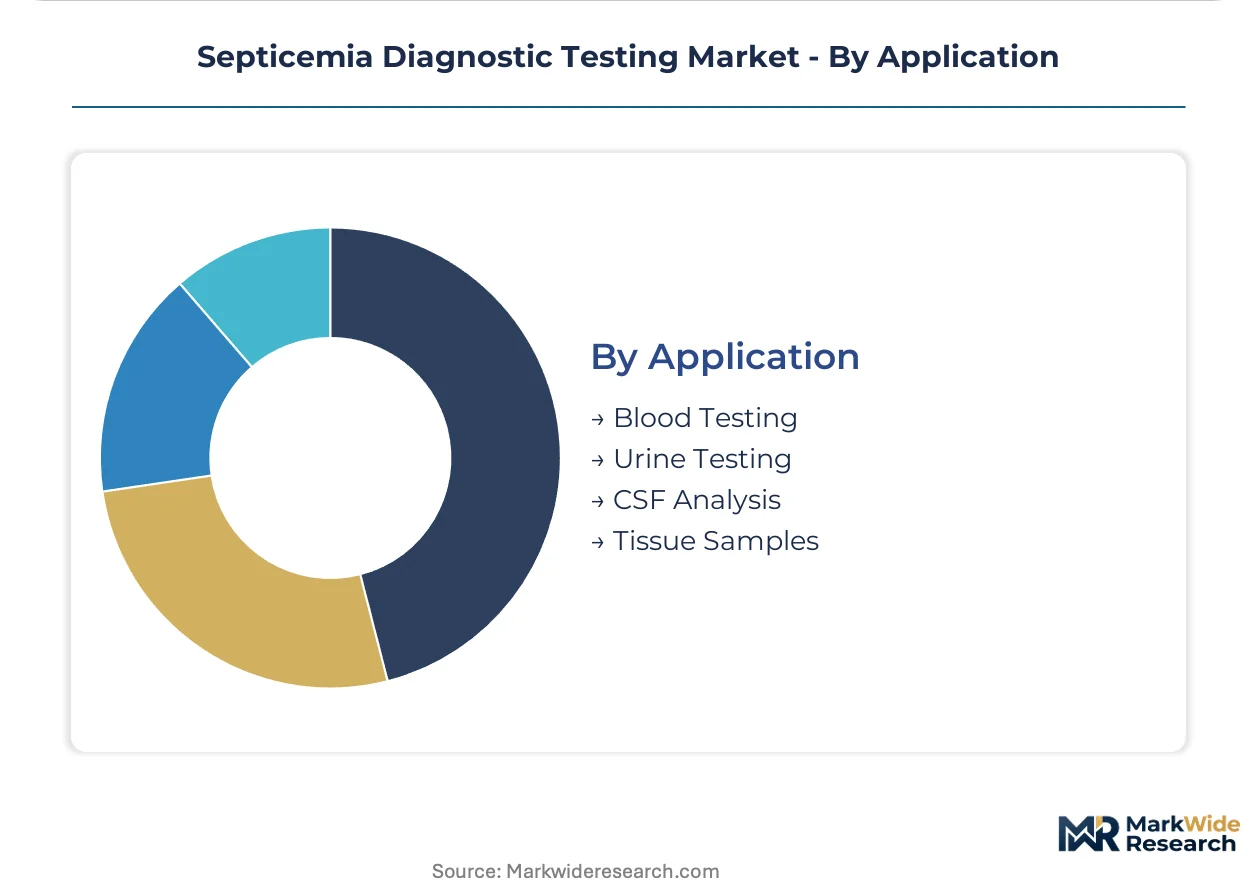
Application:
Specimen type determines test menu breadth and clinical decision velocity.
- Blood Testing:Bloodstream pathogen detection constitutes the core clinical indication, with nucleic acid and culture methods competing on sensitivity and speed. Continuous bacteremia monitoring in intensive care units drives repeat testing demand.
- Urine Testing:Urinary tract source identification supports sepsis etiology determination when primary bacteremia is suspected. Multiplex panels differentiate colonization from infection.
- CSF Analysis:Cerebrospinal fluid testing for meningitis co-infection requires rapid pathogen exclusion in febrile patients. Molecular methods reduce time-to-sterilization assessment.
- Tissue Samples:Deep-seated infection source confirmation guides surgical intervention decisions. Culture-dependent protocols predominate for anaerobic organism recovery.
Blood Testing anchors the application mix, while CSF Analysis shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and Japan command the highest per-facility spending on sepsis diagnostic platforms, with integrated delivery networks and regional laboratory consortia driving vendor consolidation decisions.
United States
Sepsis response teams in tertiary care centers require rapid molecular platforms with sub-six-hour turnaround times. FDA 510(k) pathway streamlining for moderate-complexity assays accelerates product commercialization cycles. The Boston-Cambridge corridor hosts multiple academic medical centers piloting metagenomic approaches for bloodstream pathogen identification.
Germany
Regional laboratory networks achieve economies of scale through centralized molecular testing for smaller hospitals lacking on-site microbiology capacity. EMA CE-IVD framework alignment reduces regulatory duplication costs for manufacturers seeking multi-country market access. The Rhine-Ruhr metropolitan region concentrates Europe's largest installed base of automated blood culture systems.
Japan
Critical care infrastructure expansion includes dedicated sepsis response teams requiring rapid diagnostic instrumentation in university hospitals. METI standards for medical device interoperability shape procurement specifications for laboratory information system integration. The Kanto region surrounding Tokyo anchors domestic demand for high-throughput centralized laboratory platforms.
United Kingdom
NHS England's antimicrobial stewardship programs mandate faster pathogen identification to support targeted therapy initiation. MHRA post-Brexit regulatory pathways maintain alignment with EMA CE-IVD performance standards while introducing separate conformity assessment requirements. London's academic hospital trusts lead adoption of host response biomarker panels measuring procalcitonin alongside pathogen detection.
France
ANSM oversight of in-vitro diagnostic performance claims tightens clinical evidence requirements for sepsis assay recertification. Hospital procurement committees consolidate sepsis diagnostic contracts under enterprise-wide laboratory agreements. The Paris-Saclay cluster coordinates multicenter validation studies for novel molecular platforms targeting emergency department deployment.
Septicemia Diagnostic Testing Market Competitive Landscape
Player mix skews toward diversified life science conglomerates with validated automated workflows and integrated blood culture portfolios. Market structure concentrates around manufacturers controlling sample-to-answer instrument ecosystems and distribution infrastructure for conventional culture systems. Three archetypes dominate: platform-integrated conglomerates, specialized molecular diagnostic firms, and reference laboratory service providers. Competitive moves center on enterprise-wide contract consolidation and CLIA certification acquisition for moderate-complexity assay deployment.
Within the platform-integrated tier, bioMérieux SA exemplifies European hospital network penetration through blood culture and molecular identification integration. Becton Dickinson and Company anchors North American presence via extensive distribution infrastructure for conventional systems. Danaher Corporation occupies a position controlling subsidiary-level portfolios across sample-to-answer instrument categories.
| Leading Market Players |
|---|
| bioMérieux SA |
| Becton Dickinson and Company |
| Danaher Corporation |
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| Bruker Corporation |
| Sysmex Corporation |
| T2 Biosystems |
| Others |
Value Network & Pricing Analysis
Cartridge-based reagent consumables replacing standalone assay kits simultaneously concentrates manufacturing in Germany and Japan and compresses per-test margins for third-party suppliers lacking integrated platform ecosystems. This substitution dynamic reshapes procurement economics as hospital networks negotiate enterprise-wide contracts bundling instrument placement with locked consumable commitments.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate molecular platform supply agreements between manufacturers and integrated delivery networks. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared multiplex panels from moderate-complexity CLIA-waived assays and conventional culture-based methods. Price differentiation hinges on turnaround time guarantees and interoperability certification with Epic or Cerner systems. Cost compression in the economy tier intensifies because reference laboratories compete on throughput volume against hospital-based point-of-care deployment. Emergency departments show least price sensitivity where mortality reduction justifies premium per-test costs, while outpatient clinics face severe budget constraints.
Supply Chain Analysis
Germany and Japan anchor precision optics and microfluidic cartridge production for automated sample-to-answer systems, with the United States supplying nucleic acid amplification enzymes and detection chemistries. Manufacturing draws from specialized polymer substrates, photolithography equipment, and cold-chain logistics infrastructure. Single-source vulnerability concentrates in microfluidic chip fabrication where three German suppliers control 80% of European hospital network capacity. Distribution runs through regional laboratory consortia and group purchasing organizations rather than direct hospital sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand faster than hardware as predictive algorithm subscriptions and remote instrument monitoring contracts outpace capital equipment sales. Recurring revenue from assay cartridge commitments and CLIA certification support services now commands premium valuation multiples.
For Market Incumbents: Consolidate enterprise-wide contract penetration by bundling blood culture, molecular identification, and antimicrobial susceptibility testing under single-source platform commitments. Acquire moderate-complexity CLIA certification capabilities to defend against point-of-care molecular entrants. Vertical integration into consumable cartridge manufacturing protects margin structure against raw material volatility. For New Entrants and Emerging Players: Anchor in United States emergency departments where reimbursement parity disputes create white-space for CLIA-waived moderate-complexity platforms with sub-60-minute turnaround. Target outpatient clinics and smaller community hospitals lacking on-site microbiology capacity through reference laboratory partnerships. Pursue FDA 510(k) pathway streamlining for multiplex sepsis panels as primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed molecular diagnostic firms lacking integrated blood culture portfolios. Long-term viability centers on manufacturers controlling sample-to-answer instrument ecosystems with validated automated workflows. Watch CMS coverage determinations for multiplex sepsis panels as signal for point-of-care molecular adoption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Certification Acquisition | Moderate-complexity platform deployment expands addressable market beyond reference laboratories. |
| Hospital System Partnership | Enterprise-wide contracts with United States integrated delivery networks lock in multi-year consumable commitments. |
| Software Companion Development | Machine learning algorithms analyzing biomarker trajectories enable predictive severity scoring and premium pricing. |
| Reimbursement Strategy | CMS coverage determination alignment determines economic viability against centralized laboratory economics. |
| CE Marking Pathway | EMA harmonized performance standards reduce regulatory duplication costs for European multi-country access. |
Research Methodology
Cross-validation between primary interviews with hospital procurement managers, clinical microbiologists, biomedical engineers, and GPO contracts managers and secondary sources including FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EMA CE-IVD performance standards anchors the qualitative findings. Bottom-up instrument installation data triangulates against top-down market sizing derived from manufacturer revenue disclosures and regional laboratory network capacity assessments.
Sensitivity analysis tests forecast robustness across alternative scenarios for CMS coverage expansion, FDA regulatory timeline acceleration, and hospital consolidation pace. Modeled dimensions span product type, technology platform, end-user setting, and application specimen with regional regulatory cluster overlays. CAGRs derive from segment-level growth trajectory blending with macro healthcare expenditure elasticity assumptions. Forecast inputs incorporate sepsis response team deployment rates and antimicrobial stewardship program mandates.
Underlying assumptions cover reimbursement stability, regulatory pathway predictability, and hospital capital budget continuity, with deviation risk concentrated in CMS coverage determination fragmentation and EMA MDR recertification timeline extensions. Recalibration cycles align with material shifts in FDA 510(k) review velocity and integrated delivery network procurement consolidation waves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Latent Tuberculosis Infection Detection Market
Diagnostics
Hypopituitarism Diagnostics Market
Diagnostics
Infectious Disease in Vitro Diagnostics Market
Diagnostics
Viral Molecular Diagnostics Market
Diagnostics
Adenovirus Diagnostic Testing Market
Diagnostics
Antigen Kit Market
Diagnostics
Respiratory Pathogen Testing Kits Market
Diagnostics
Global Hemoglobin A1c Testing Devices Market
Diagnostics
Middle East and Africa Lung Cancer Diagnostics Market
Diagnostics
Diabetic Assays Market
Diagnostics
Brain Cancer Diagnostics Market
Diagnostics
Immunodiagnostics Market
Diagnostics
Body Fluid Collection and Diagnostics Market
Diagnostics
Asia-Pacific Womens Health Diagnostics Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
IVD Antibody Market